
 Asia-Pacific Courier Market | 2026-2036
Asia-Pacific Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Courier Market Outlook
Same-day delivery tier is collapsing the traditional 48-72 hour standard across metropolitan corridors. SF Express leverages its integrated air-ground network to dominate high-value express corridors between Shenzhen, Shanghai, and Beijing. ZTO Express anchors volume economics through automated sorting hubs that process millions of parcels nightly. CJ Logistics differentiates via cold-chain specialization for pharmaceuticals and fresh produce across South Korea and Vietnam.
A courier service constitutes a time-definite logistics operation involving parcel collection, sortation, line-haul transport, and last-mile distribution, typically executed through hub-and-spoke networks with tracking visibility at each node. Express delivery commands premium pricing for urgent B2B documents and medical supplies, while drone delivery emerges as the fastest-growing delivery mode for island archipelagos and mountainous terrain where ground infrastructure remains sparse. E-commerce companies represent the deepest customer type for volume, though refrigerated goods within package type segments extract superior margins from healthcare and foodservice clients.
Japan's METI enforces labor standards that cap driver hours and mandate electric vehicle transition timelines for urban delivery fleets. China's SAMR and MIIT jointly regulate cross-border data flows from logistics platforms and certify autonomous delivery vehicle testing zones. India's CEA and state-level transport authorities coordinate interstate e-way billing that digitizes tax compliance for courier networks. Stakeholders must monitor how divergent national labor and emissions frameworks fragment operational standardization across the region.
Market Dynamics
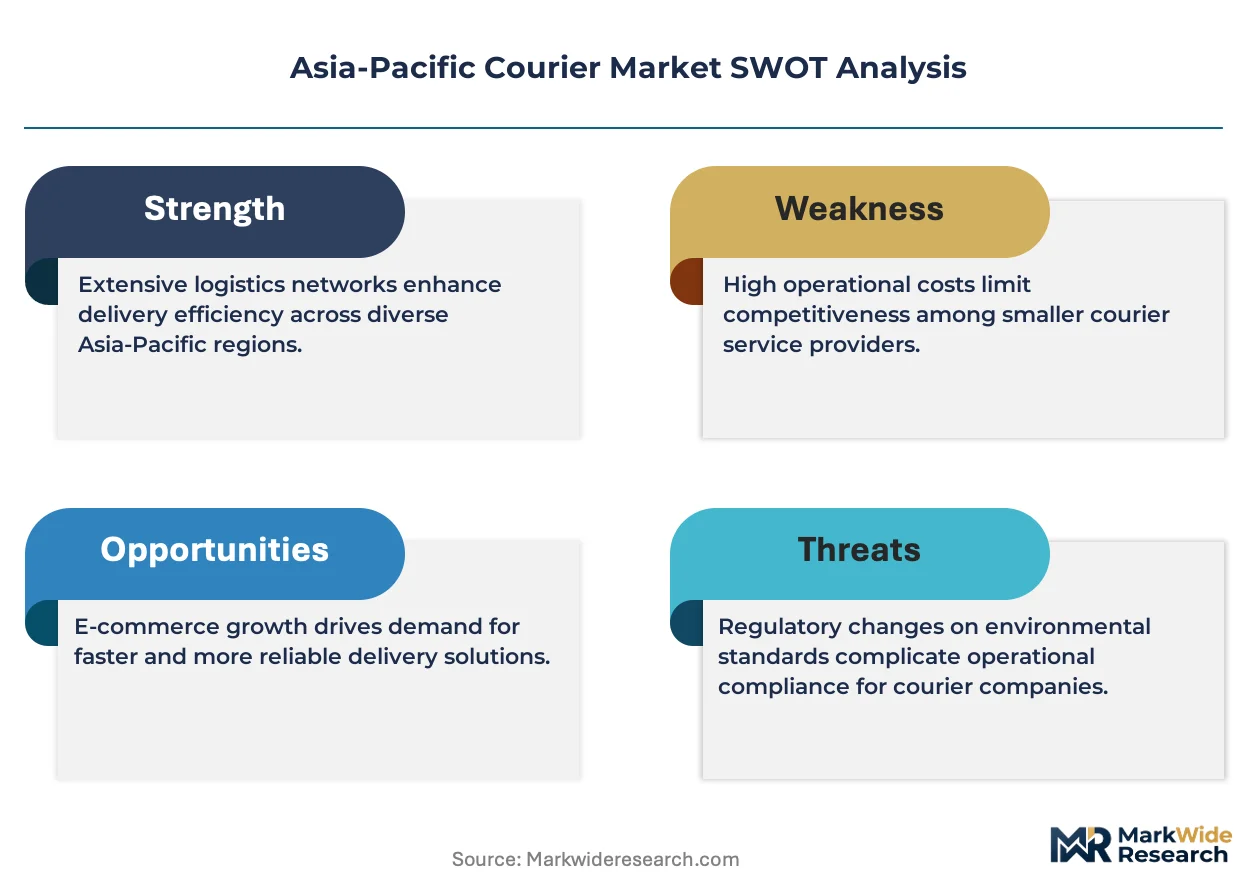
E-commerce parcel volumes are compressing delivery windows across Asia-Pacific metropolitan corridors. China's GB standards for autonomous vehicles and cross-border data flows are forcing network reconfiguration. Labor hour caps in Japan and India's digitized e-way billing are fragmenting operational standardization.
Growth Catalysts
- Cross-border e-commerce protocols:China's SAMR and MIIT joint frameworks for data localization and autonomous vehicle certification are accelerating compliant network expansion into Southeast Asian corridors.
- Drone delivery infrastructure:Island archipelagos and mountainous terrain across Indonesia and the Philippines are creating regulatory sandboxes for beyond-visual-line-of-sight operations where ground infrastructure remains sparse.
- Digital payment penetration:India's tier-two and tier-three urban clusters are unlocking last-mile density as UPI and wallet adoption reduce cash-on-delivery friction.
Market Restraints
- Diesel price volatility:Line-haul fleet operators face margin compression as fuel constitutes 25-35% of per-parcel costs across intercity corridors.
- Sorting hub concentration:Automated facilities cluster in China and South Korea, leaving Southeast Asian networks dependent on manual processing with lower throughput ceilings.
- Driver hour regulations:Japan's METI enforcement of strict caps limits fleet utilization rates during peak e-commerce windows.
Strategic Opportunities
- Cold-chain pharmaceuticals:Temperature-controlled last-mile networks for biologics and vaccines remain underdeveloped across Vietnam, Thailand, and Indonesia.
- Electric vehicle mandates:China's dual carbon goals and urban fleet electrification timelines are creating captive demand for charging infrastructure partnerships.
- Blockchain-IoT convergence:Real-time custody verification for high-value express parcels is opening premium pricing tiers in B2B document and medical supply segments.
Industry Challenges
- Autonomous vehicle certification timelines:China's MIIT testing zone approvals and Japan's safety validation protocols are extending deployment schedules for unmanned ground delivery.
- Legacy warehouse management integration:Mid-tier courier networks struggle to retrofit automated sortation APIs into existing ERP systems without operational disruption.
- Cross-border customs harmonization:Divergent documentation requirements between ASEAN member states create clearance friction for consolidated parcel flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Courier Market |
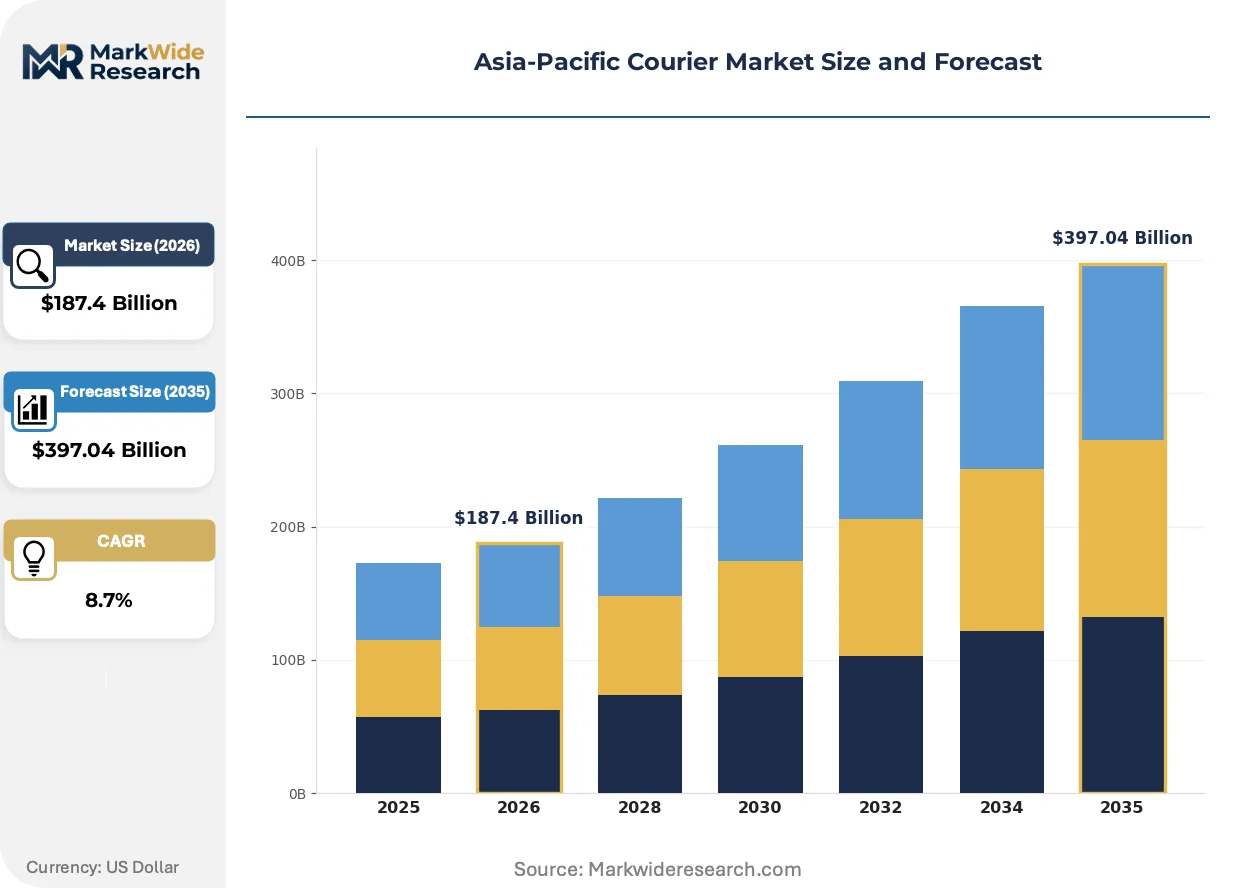
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Same-Day Delivery, Scheduled Delivery, International Shipping Customer Type: Retailers, E-commerce Companies, Corporations, Individual Customers Delivery Mode: Ground Transport, Air Freight, Sea Freight, Drone Delivery Package Type: Documents, Parcels, Pallets, Refrigerated Goods |
| Companies Covered | Japan Post Group, Yunda Holding Co., Ltd., SF Express, Singapore Post Limited, Sagawa Express Co., Ltd., China Post, ZTO Express, CJ Logistics, Yamato Holdings Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Courier Market Strategic Shifts
Autonomous delivery technologies and real-time visibility platforms are compressing the traditional hub-and-spoke model. Regulatory frameworks are hardening around data sovereignty and emissions compliance. Procurement patterns are shifting from volume-based contracts toward outcome-defined service level agreements.
Electric last-mile fleets are supplanting diesel vans in China's tier-one cities. E-commerce platforms and express operators in Shenzhen and Shanghai are deploying battery-swapping networks to eliminate charging downtime. This transition is compressing total cost of ownership calculations and locking in multi-year fleet procurement cycles.
China's GB standards for autonomous delivery vehicles and cross-border data flows are mandating localized server architecture. Logistics platforms must store tracking data within national borders, increasing capex for cloud infrastructure. Express operators are responding by establishing domestic data centers in Beijing and Hangzhou to maintain compliance.
Buyer procurement is consolidating around guaranteed delivery windows rather than per-parcel rates. Major e-commerce platforms in India and Southeast Asia are demanding same-day or four-hour commitments for premium SKUs. This shift is most visible in metropolitan India, where Flipkart and Amazon are penalizing carriers for window breaches.
Asia-Pacific Courier Market Segmentation
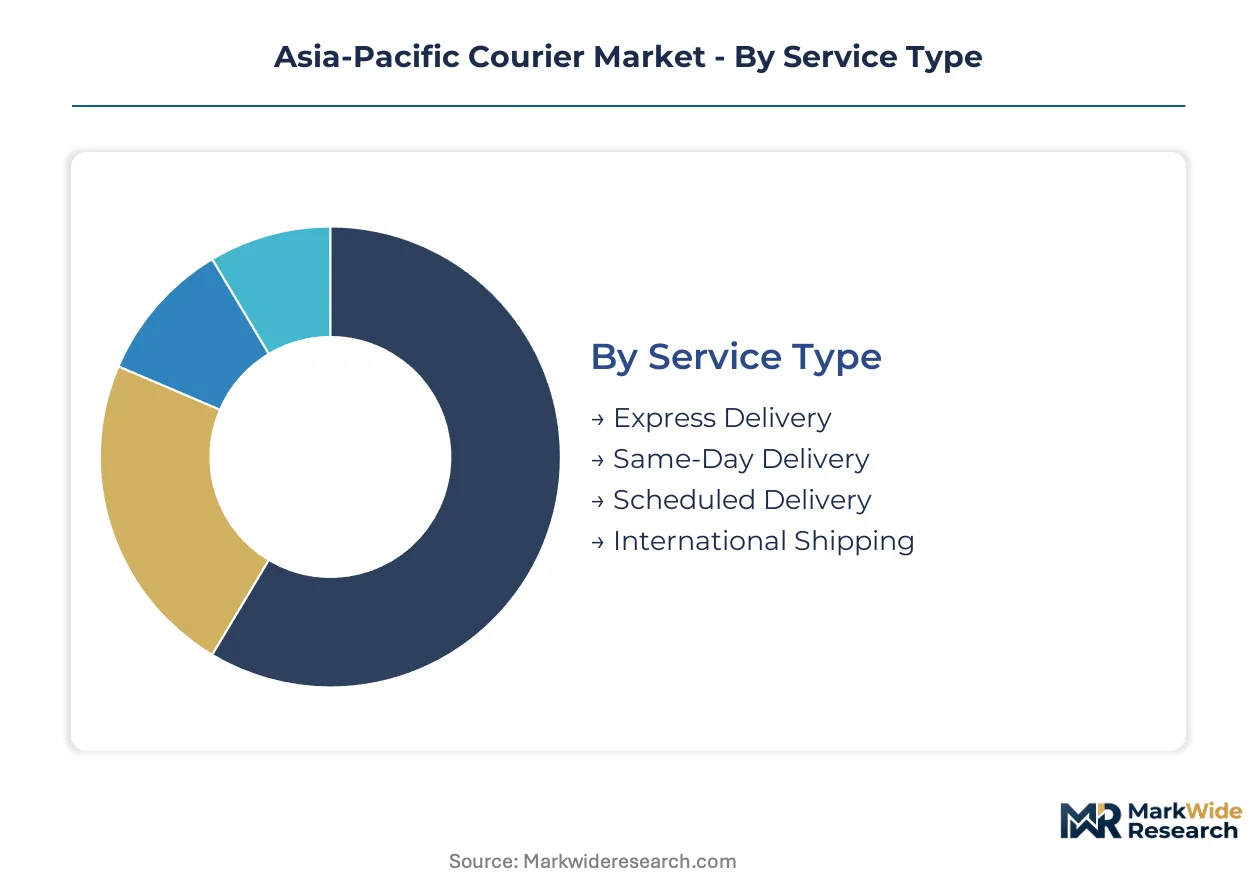
Segmentation in Asia-Pacific courier markets reveals how service tiers align with infrastructure investment and regulatory maturity. Each dimension exposes divergent margin structures and operational constraints across the region's fragmented national frameworks.
Service Type:
Express corridors concentrate in high-density metropolitan clusters where air-ground integration justifies premium positioning, while scheduled networks serve cost-sensitive bulk flows through deferred lane optimization.
- Express Delivery:Time-definite service leveraging integrated air-ground networks for urgent B2B documents and medical supplies. Demand concentrates in China's tier-one manufacturing corridors and India's pharmaceutical export zones where MIIT and CDSCO compliance requirements elevate reliability premiums.
- Same-Day Delivery:Ultra-rapid fulfillment compressing collection-to-delivery windows below eight hours through micro-fulfillment nodes. Metro India and Southeast Asian capitals are driving expansion as UPI penetration reduces cash-handling delays.
- Scheduled Delivery:Deferred lane consolidation for non-urgent B2B flows with predictable pickup windows.
- International Shipping:Cross-border parcel flows navigating divergent ASEAN customs documentation and China's SAMR data localization mandates.
By volume, Express Delivery leads. By growth pace, Same-Day Delivery is expanding most quickly.
Customer Type:
Volume concentration and margin extraction diverge sharply across customer categories, with platform economics dictating procurement power and service-level negotiation leverage.
- E-commerce Companies:Deep-volume anchor accounts driving network density through predictable daily parcel injections. Flipkart, Amazon India, and Southeast Asian platforms are compressing delivery windows to four-hour commitments for premium SKUs, forcing carriers to absorb infrastructure capex.
- Corporations:B2B contract logistics with stringent SLA penalties for window breaches and documentation errors. Japan's METI labor hour caps constrain fleet utilization during quarterly close peaks when document volumes surge.
- Retailers:Omnichannel fulfillment bridging storefront inventory with online order capture.
- Individual Customers:Fragmented C2C flows with highest last-mile cost per parcel and lowest price elasticity.
E-commerce Companies dominate parcel volume. Corporations command the steepest pricing premiums.
Delivery Mode:
Modal selection tracks geography and infrastructure maturity, with autonomous and aerial platforms penetrating terrain where ground networks face topological or regulatory barriers.
- Drone Delivery:Beyond-visual-line-of-sight operations for island archipelagos and mountainous terrain across Indonesia and the Philippines. Regulatory sandboxes in Southeast Asian corridors are accelerating certification timelines where ground infrastructure remains sparse.
- Air Freight:Long-haul express backbone connecting China's manufacturing zones with consumption clusters. SF Express dominates Shenzhen-Shanghai-Beijing triangles through captive freighter capacity and slot control at secondary airports.
- Ground Transport:Diesel-dependent line-haul and last-mile van networks facing margin pressure from fuel volatility.
- Sea Freight:Deferred international parcel consolidation for non-urgent cross-border e-commerce.
Ground Transport handles the largest parcel volumes. Drone Delivery is climbing the fastest as regulatory frameworks mature.
Package Type:
Physical characteristics and handling requirements determine network specialization, with temperature-controlled flows extracting superior margins through capital-intensive infrastructure.
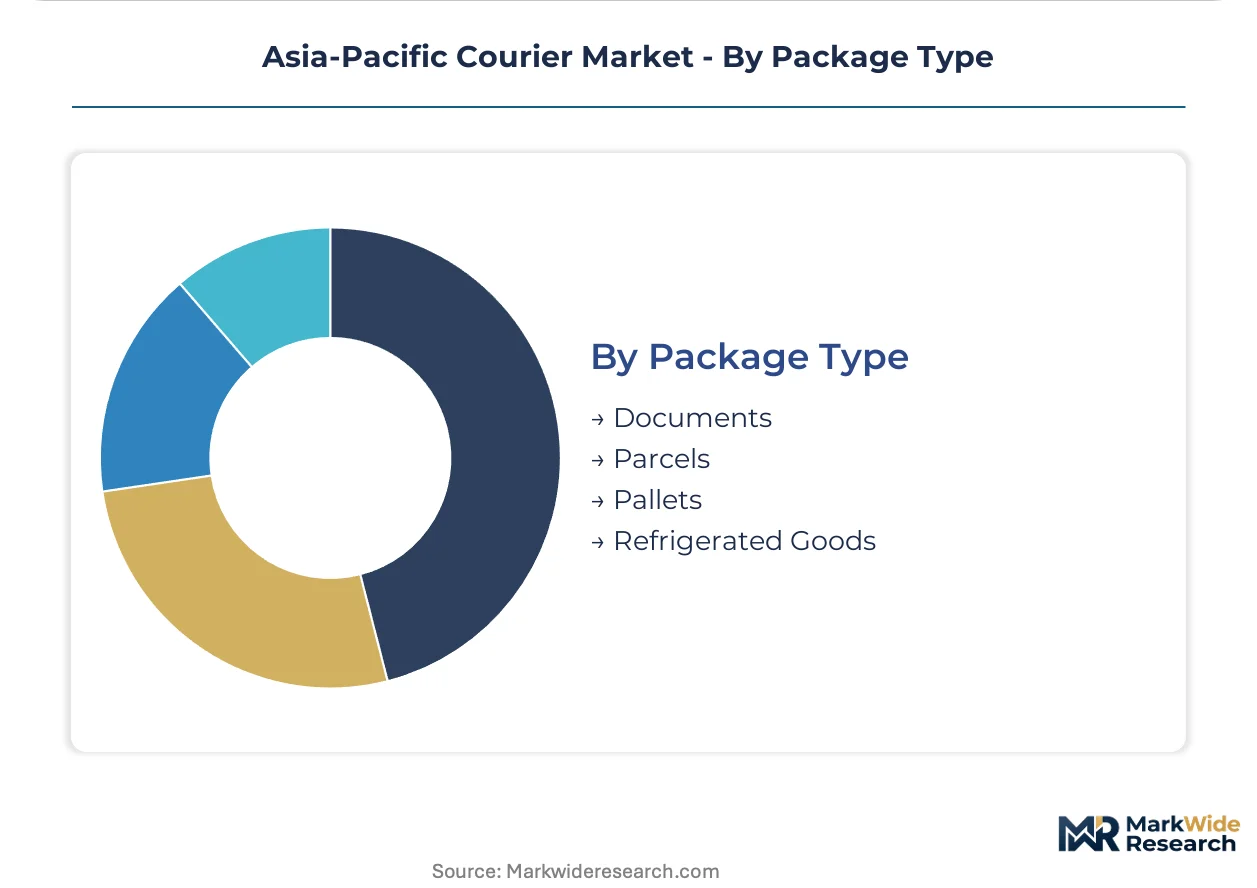
- Refrigerated Goods:Temperature-controlled end-to-end custody for biologics, vaccines, and fresh produce. CJ Logistics anchors cold-chain specialization across South Korea and Vietnam where pharmaceutical manufacturing clusters and foodservice platforms demand validated thermal integrity.
- Parcels:Standardized e-commerce units driving automated sortation investment and throughput economics. ZTO Express processes millions nightly through Chinese hub automation, while Southeast Asian networks remain constrained by manual processing ceilings.
- Documents:Lightweight B2B express with premium pricing for legal and financial instrument delivery.
- Pallets:B2B freight forwarding integrated with courier networks for enterprise supply chain consolidation.
Parcels dominate shipment counts. Refrigerated Goods capture the widest margin spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import-dependent Southeast Asian economies generate outbound parcel flows that outstrip domestic consumption, while China's manufacturing clusters feed cross-border e-commerce corridors. The region's courier networks align with trade imbalances, positioning sorting infrastructure near export zones and consumption hubs.
China
E-commerce manufacturing clusters in Shenzhen and Guangzhou inject massive parcel volumes into express networks serving domestic consumption and cross-border exports. MIIT and SAMR jointly enforce GB standards for autonomous vehicle certification and data localization, compelling logistics platforms to establish domestic server architecture. ZTO Express anchors automated sorting capacity in Hangzhou and Shanghai, processing millions of parcels nightly through hub-and-spoke configurations.
India
Tier-two urban clusters in Maharashtra and Karnataka are unlocking last-mile density as UPI penetration eliminates cash-on-delivery friction. CEA coordinates with state transport authorities on digitized e-way billing that streamlines interstate tax compliance for courier networks. Mumbai-Pune and Bangalore-Chennai corridors concentrate express infrastructure where pharmaceutical exporters demand time-definite B2B service.
Japan
Metropolitan Tokyo and Osaka corridors sustain premium express demand for B2B documents and medical supplies with stringent reliability requirements. METI enforces labor hour caps that constrain driver utilization during quarterly close peaks when financial instrument volumes surge. Yamato Holdings and Sagawa Express anchor last-mile density in Kanto and Kansai regions through integrated collection networks.
South Korea
Pharmaceutical manufacturing in Songdo and foodservice platforms in Seoul generate cold-chain demand that extracts superior margins from temperature-controlled networks. MFDS validates thermal integrity standards for biologics and vaccine distribution, elevating compliance requirements for last-mile operators. CJ Logistics specializes in refrigerated custody across the Seoul-Busan corridor and into Vietnam export zones.
Vietnam
Manufacturing relocation from China has concentrated export-oriented production in northern provinces bordering Guangxi, creating cross-border parcel flows through Lang Son and Mong Cai corridors. The country's transport ministry coordinates with Chinese counterparts on customs harmonization for e-commerce consolidation. Ho Chi Minh City anchors domestic consumption demand as digital wallet adoption accelerates last-mile delivery penetration.
Asia-Pacific Courier Market Competitive Environment
Concentration sits with integrated express operators that control captive air-ground networks and automated sorting infrastructure. Tiered competition separates premium service providers with reliability guarantees from volume-driven operators competing on per-parcel economics. Two archetypes dominate: integrated network operators with freighter capacity and slot control, and specialized cold-chain providers with validated temperature custody. Competitive moves center on fleet electrification partnerships and micro-fulfillment node deployment in dense metropolitan corridors.
Among integrated Chinese operators, SF Express and ZTO Express exemplify divergent strategic positioning within the same regulatory environment. SF Express occupies the premium express tier through captive freighter capacity on Shenzhen-Shanghai-Beijing triangles. ZTO Express anchors volume economics through automated hub processing at scale. Japan Post Group and Yamato Holdings represent the mature-market archetype where labor regulations constrain operational flexibility but sustain pricing power through reliability premiums.
| Leading Market Players |
|---|
| Japan Post Group |
| Yunda Holding Co., Ltd. |
| SF Express |
| Singapore Post Limited |
| Sagawa Express Co., Ltd. |
| China Post |
| ZTO Express |
| CJ Logistics |
| Yamato Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with e-commerce platforms lock in both hub utilization and price visibility across Asia-Pacific express networks. These agreements bind carriers to guaranteed volume floors while insulating per-parcel economics from spot-market volatility in diesel and labor inputs.
Pricing Analysis
E-commerce companies anchor contract-based pricing through multi-year offtake agreements that exchange volume commitments for fixed per-parcel rates. Pricing stratifies across same-day, express, and deferred tiers based on service level guarantees and network priority access. Cost compression in deferred lanes is intensifying because automated hub operators in China extract throughput advantages that manual Southeast Asian networks cannot match. Individual customers exhibit highest price sensitivity while pharmaceutical B2B buyers absorb premium reliability markups with minimal elasticity.
Supply Chain Analysis
Inventory positioning and lead-time compression favor automated sorting hub concentration in China and South Korea over manual Southeast Asian facilities. Supply rests on diesel-dependent line-haul fleets, lithium-ion battery cells for electric van conversion, and specialized cold-chain refrigerants. Single-source vulnerability concentrates in Chinese automation equipment vendors that dominate sortation system installation. Distribution feeds from manufacturing clusters in Guangdong and Zhejiang through hub-and-spoke configurations into metro consumption zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific courier fragmentation creates entry niches as divergent national regulations splinter operational standardization and specialized service tiers multiply.
For Market Incumbents: Shield automated hub economics through exclusive equipment supplier relationships that block Southeast Asian rivals from matching throughput scale. Deepen cold-chain certification investment against MFDS and CDSCO standards to capture pharmaceutical margin premiums before regional specialists consolidate. METI labor hour caps in Japan threaten fleet utilization during peak windows; counter through micro-fulfillment node deployment that reduces driver-dependent last-mile exposure. For New Entrants and Emerging Players: Differentiate on drone delivery certification for Indonesian archipelago and Philippine mountain corridors where ground infrastructure gaps persist. Target tier-two Indian cities where UPI penetration has unlocked density but national carriers maintain thin coverage. Pursue hospital system partnerships as the go-to-market angle for temperature-controlled biologics distribution in Vietnam and Thailand. For Investors and Strategic Acquirers: Capital is best deployed toward cold-chain specialists with validated pharmaceutical custody credentials and established Southeast Asian lane networks. Long-term viability hinges on regulatory compliance architecture that adapts to divergent national data localization and emissions mandates. Watch autonomous vehicle certification timelines from China's MIIT as the inflection signal for unmanned ground delivery scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Hub Expansion | ZTO Express-style throughput economics in Southeast Asia would collapse manual processing cost structures. |
| Electric Fleet Conversion Partnership | Battery-swapping networks in Shenzhen and Shanghai eliminate charging downtime and lock in multi-year procurement cycles. |
| Cold-Chain Certification Investment | MFDS-validated thermal integrity opens biologics and vaccine distribution premiums across Seoul-Busan corridors. |
| Drone Delivery Regulatory Sandbox Entry | Beyond-visual-line-of-sight approvals in Indonesia and Philippines exploit terrain where ground networks fail. |
| Micro-Fulfillment Node Deployment | Metro India density gains from four-hour delivery commitments reduce cash-handling friction through UPI integration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, carrier financial disclosures, and national transport ministry filings across the Asia-Pacific region. Interviews with express network operations directors, e-commerce logistics procurement managers, cold-chain compliance officers, and autonomous vehicle testing regulators informed demand and supply-side validation. Bottom-up parcel volume modeling triangulates against top-down market sizing from trade association aggregates.
Segmentation dimensions modeled include service type, customer category, delivery mode, and package characteristics across the projection horizon. CAGRs derive from trend extrapolation of e-commerce penetration curves, regulatory implementation schedules, and infrastructure investment pipelines. Forecast inputs incorporate diesel price volatility scenarios and electric vehicle adoption timelines from China's dual carbon policy framework.
Material uncertainties — regulatory harmonization failures, autonomous certification delays, and fuel cost spikes — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption rates and cross-border protocol convergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market