
 ASEAN Chemical Logistics Market | 2026-2036
ASEAN Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Chemical Logistics Market Insights
Vietnam's northern industrial corridor is reshaping regional chemical logistics capacity as foreign manufacturers relocate production from China. Mitsubishi Chemical Logistics leverages its integrated port-to-plant network across Ho Chi Minh City and Hai Phong to dominate specialty chemical distribution. Leschaco (Malaysia) Sdn Bhd anchors cross-border road freight between Peninsular Malaysia and Thailand with dedicated hazardous materials fleets. Den Hartogh Logistics sustains competitive positioning through its captive tank container pool serving Indonesian oleochemical exporters.
Chemical logistics encompasses the specialized transportation, warehousing, and handling of hazardous and non-hazardous chemical products under controlled temperature, pressure, and containment conditions, typically requiring ISO tank containers, drum facilities, or bulk liquid terminals with secondary containment systems and fire suppression infrastructure. The primary purpose is ensuring supply chain continuity for petrochemical, agrochemical, and specialty chemical producers while maintaining product integrity and regulatory compliance across multimodal networks. Sea freight leads value contribution due to inter-island ASEAN trade lanes and import dependency for base chemicals, while road transport captures the fastest expansion from just-in-time delivery requirements by Vietnamese and Thai manufacturers. Warehousing services concentrate margin pools in bonded facilities near deepwater ports, particularly for liquid chemicals requiring nitrogen blanketing and automated inventory systems.
Thailand's Department of Industrial Works enforces Hazardous Substance Act licensing for chemical storage facilities, while Indonesia's Ministry of Environment mandates spill response protocols that elevate compliance costs for new market entrants. Singapore's National Environment Agency integrates chemical logistics permits with its port clearance systems, creating regulatory friction for non-integrated operators. Stakeholders must monitor evolving ASEAN harmonized dangerous goods classification standards and prioritize cold chain certification investments before regulatory deadlines tighten across member states.
Market Dynamics
Thailand's Board of Investment petrochemical zone incentives are redrawing bonded warehouse demand patterns across Southeast Asia, compressing lead times for specialty chemical manufacturers relocating procurement from China.
Growth Catalysts
- Thailand's Hazardous Substance Act licensing:The Department of Industrial Works streamlined facility approvals for deepwater port zones, accelerating bonded storage construction near Laem Chabang.
- Temperature-controlled liquid storage:Vietnam's northern industrial corridor concentrates foreign chemical manufacturers requiring nitrogen blanketing infrastructure for agrochemical intermediates.
- Cross-border hazardous materials fleets:Dedicated road freight corridors between Peninsular Malaysia and Thailand enable just-in-time delivery for Thai petrochemical plants sourcing specialty additives.
Market Restraints
- Indonesian spill response mandates:The Ministry of Environment mandates containment infrastructure that elevates new entrant compliance costs by requiring dual-wall tank systems and 24-hour response teams.
- Singapore's integrated permit friction:The National Environment Agency links chemical logistics licenses to port clearance systems, disadvantaging non-integrated warehouse operators without captive container yards.
- ASEAN dangerous goods classification divergence:Harmonization delays between member state chemical registries force duplicate labeling and documentation for cross-border shipments.
Strategic Opportunities
- Indonesian oleochemical export cold chain:Captive ISO tank container pools serving palm derivative exporters remain underdeveloped outside Java, creating white space for temperature-controlled bulk liquid networks.
- Vietnamese northern corridor expansion:Hai Phong port hinterland lacks sufficient automated drum facilities for specialty chemical distributors serving relocated electronics manufacturers.
- ASEAN harmonized dangerous goods standards:Upcoming regulatory deadlines for unified classification create first-mover advantage for logistics operators pre-investing in dual-certified handling equipment.
Industry Challenges
- Hazmat certification pipeline gaps:Vietnam and Indonesia face acute shortages of certified tank container inspectors and dangerous goods safety advisors, extending onboarding timelines for new facilities.
- Legacy warehouse automation retrofit costs:Existing drum storage facilities across Thailand and Malaysia require nitrogen blanketing system upgrades to meet specialty chemical customer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Chemical Logistics Market |
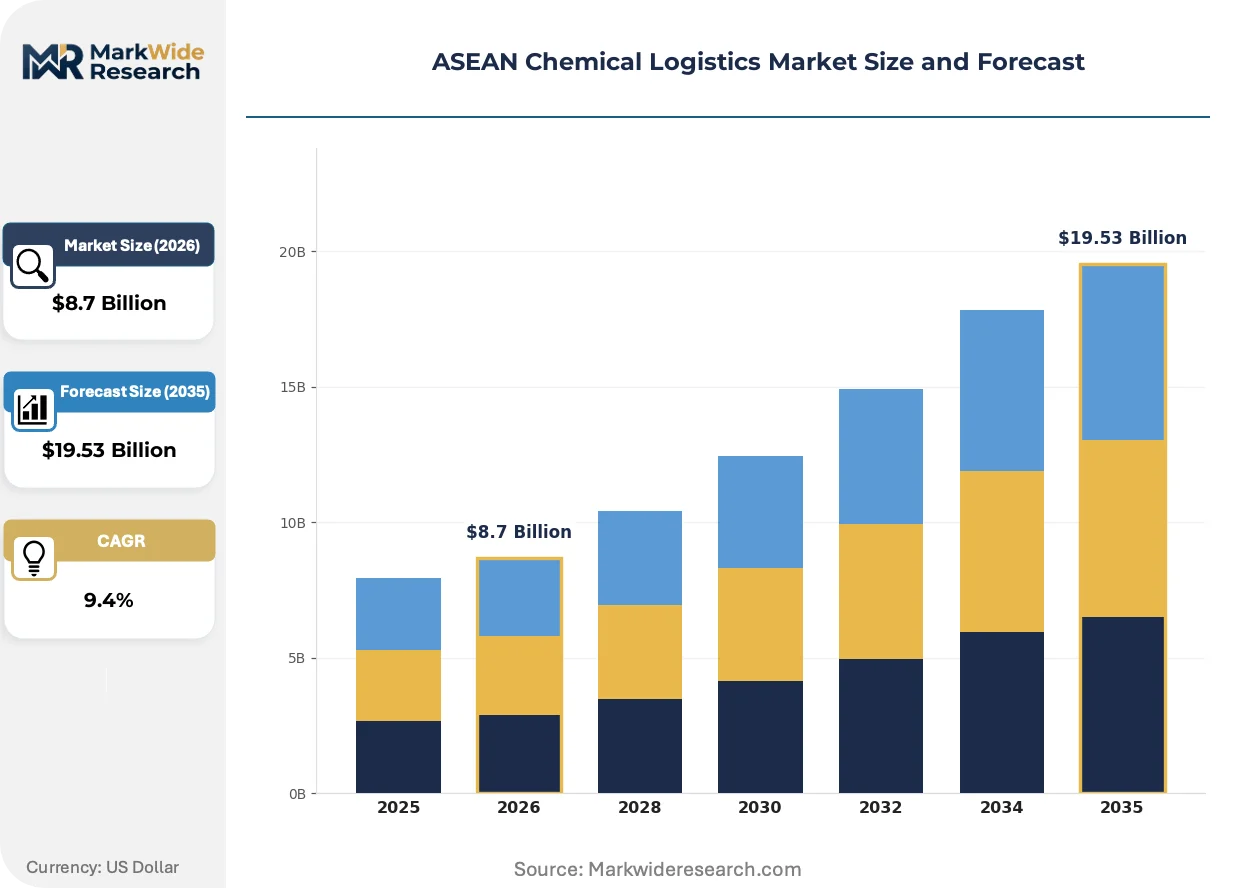
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transportation Mode: Road, Rail, Sea, Air Service Type: Warehousing, Freight Forwarding, Customs Clearance, Management End User: Manufacturers, Distributors, Retailers, Traders Product Type: Liquid Chemicals, Gaseous Chemicals, Solid Chemicals, Specialty Chemicals |
| Companies Covered | Mitsubishi Chemical Logistics, Leschaco (Malaysia) Sdn Bhd, Den Hartogh Logistics, Mitsui O.S.K. Lines, MOL Chemical Tankers, SCG Chemicals Public Company Limited, Dachser, Royal Den Hartogh Logistics, Noatum Logistics, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Chemical Logistics Market Trends and Innovations
Digital twin technology is virtualizing chemical logistics operations across ASEAN port zones, compressing inventory planning cycles while regulatory pressure on emissions tracking accelerates sensor deployment.
Blockchain-enabled documentation platforms are virtualizing customs clearance workflows for hazardous materials shipments. Thai petrochemical exporters and Vietnamese electronics chemical buyers are adopting distributed ledger systems at the fastest pace. This technology is virtualizing audit trails that previously required physical document couriers, reducing port dwell times for bonded warehouse releases.
Singapore's National Environment Agency integration of chemical logistics permits with port clearance systems is tightening compliance windows for non-integrated operators. The policy forces warehouse developers to co-locate with container terminals or absorb permit processing delays. Liquid chemical storage specialists with captive deepwater access capture disproportionate margin pools under this framework.
Specialty chemical buyers are consolidating vendor relationships around integrated port-to-plant service contracts. Vietnamese electronics manufacturers and Thai agrochemical formulators now demand single-source accountability for temperature-controlled delivery. This concentration is most visible in Ho Chi Minh City and Hai Phong, where Mitsubishi Chemical Logistics leverages multimodal networks to disperse fragmented trucking arrangements.
ASEAN Chemical Logistics Market Segmentation
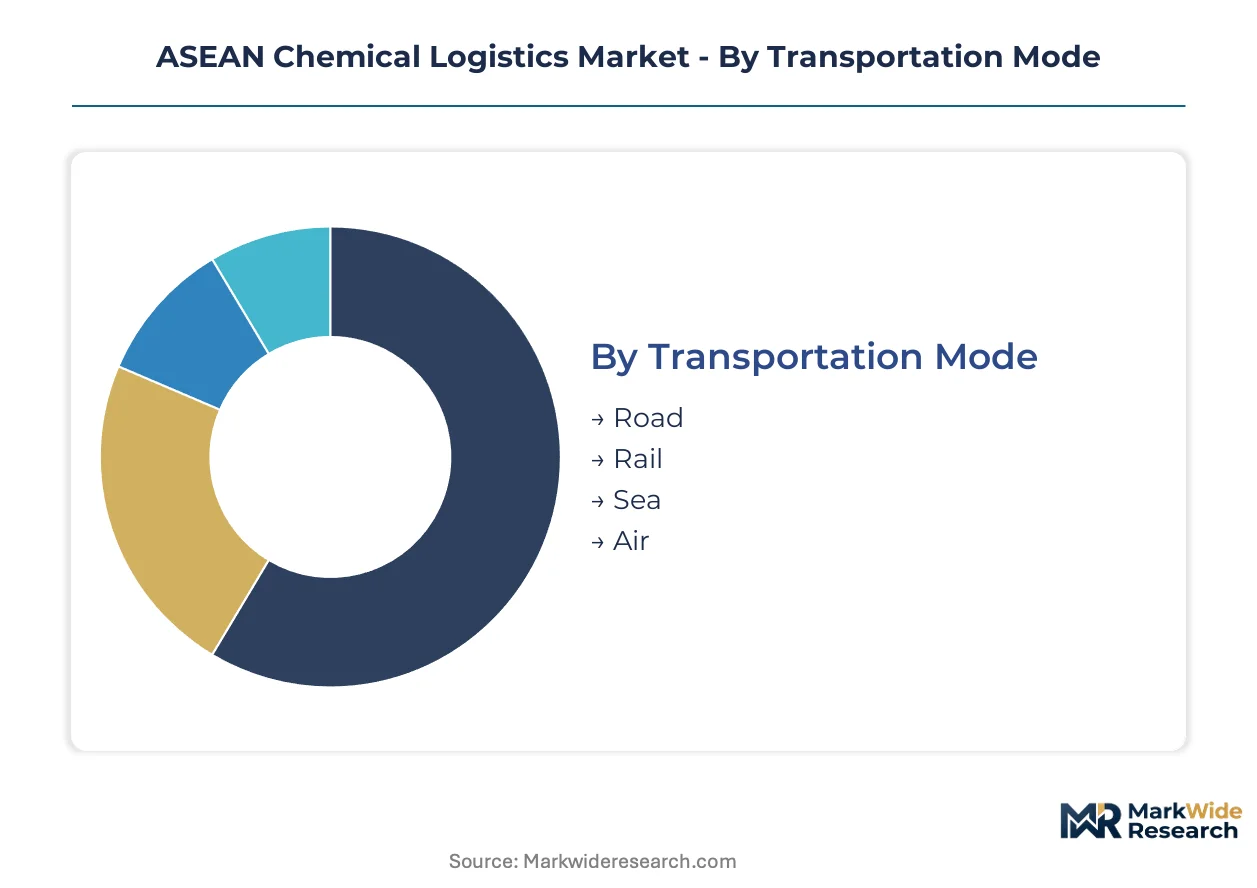
Chemical logistics segmentation reveals divergent capital intensity and contract duration across operational modes. Cycle times vary dramatically between bulk sea freight and just-in-time road delivery, dictating working capital requirements and facility investment priorities.
Transportation Mode:
Road freight turns inventory fastest while sea freight locks capital longest, creating distinct margin profiles and equipment specialization requirements across ASEAN corridors.
- Road:Dedicated hazardous materials fleets enable just-in-time delivery for Thai petrochemical plants and Vietnamese electronics manufacturers. Cross-border corridors between Peninsular Malaysia and Thailand concentrate demand for temperature-controlled tank trucks with ADR-certified drivers. This segment captures the steepest expansion trajectory from manufacturing relocation into Vietnam's northern industrial corridor.
- Sea:ISO tank containers and bulk liquid carriers dominate inter-island ASEAN trade lanes and base chemical imports. Deepwater port access at Laem Chabang and Hai Phong creates captive demand for bonded warehouse integration. Nitrogen blanketing and vapor recovery systems elevate handling specifications for oleochemical and solvent shipments.
- Rail:Limited network coverage across archipelago geographies restricts deployment primarily to Thailand's eastern seaboard corridor connecting Rayong industrial zones to Laem Chabang port.
- Air:Restricted to high-value specialty chemicals and emergency shipments due to IATA dangerous goods limitations and cost structures prohibiting bulk movement.
Road dominates transaction velocity. Sea commands installed capacity tonnage.
Service Type:
Service bundling intensity increases with customer sophistication, shifting margin capture from commoditized freight forwarding to integrated management contracts.
- Warehousing:Bonded liquid chemical terminals with secondary containment and automated nitrogen blanketing systems concentrate near deepwater ports. Thailand's Board of Investment incentives accelerate construction in Laem Chabang and Map Ta Phut zones. Spill response infrastructure mandated by Indonesia's Ministry of Environment elevates compliance costs for new entrants.
- Freight Forwarding:Cross-border hazardous documentation and multimodal coordination face friction from non-harmonized ASEAN dangerous goods classification standards. Blockchain-enabled customs platforms are compressing clearance cycles for Thai-Vietnamese chemical trade lanes.
- Customs Clearance:Singapore's National Environment Agency integration with port systems creates regulatory friction for non-integrated warehouse operators lacking captive container yards.
- Management:End-to-end accountability contracts covering port-to-plant temperature-controlled delivery are consolidating vendor relationships among Vietnamese electronics manufacturers and Thai agrochemical formulators.
Warehousing anchors fixed asset deployment. Management contracts represent the fastest-climbing margin pool.
End User:
End-user sophistication determines service tier requirements, with manufacturers demanding integrated solutions while traders prioritize cost-minimized spot arrangements.
- Manufacturers:Petrochemical and electronics chemical producers require captive ISO tank container pools and guaranteed temperature integrity. Relocated production from China into Vietnam's northern corridor is intensifying demand for automated drum facilities and nitrogen blanketing infrastructure.
- Distributors:Specialty chemical distributors face consolidation pressure as buyers demand single-source accountability for multimodal delivery across fragmented ASEAN trucking networks.
- Retailers:Agrochemical retail networks in Thailand and Indonesia require last-mile hazardous materials handling with certified safety advisors.
- Traders:Commodity chemical traders prioritize bonded warehouse access and rapid customs clearance over integrated service bundles.
Manufacturers drive premium service tier adoption. Traders concentrate spot market liquidity.
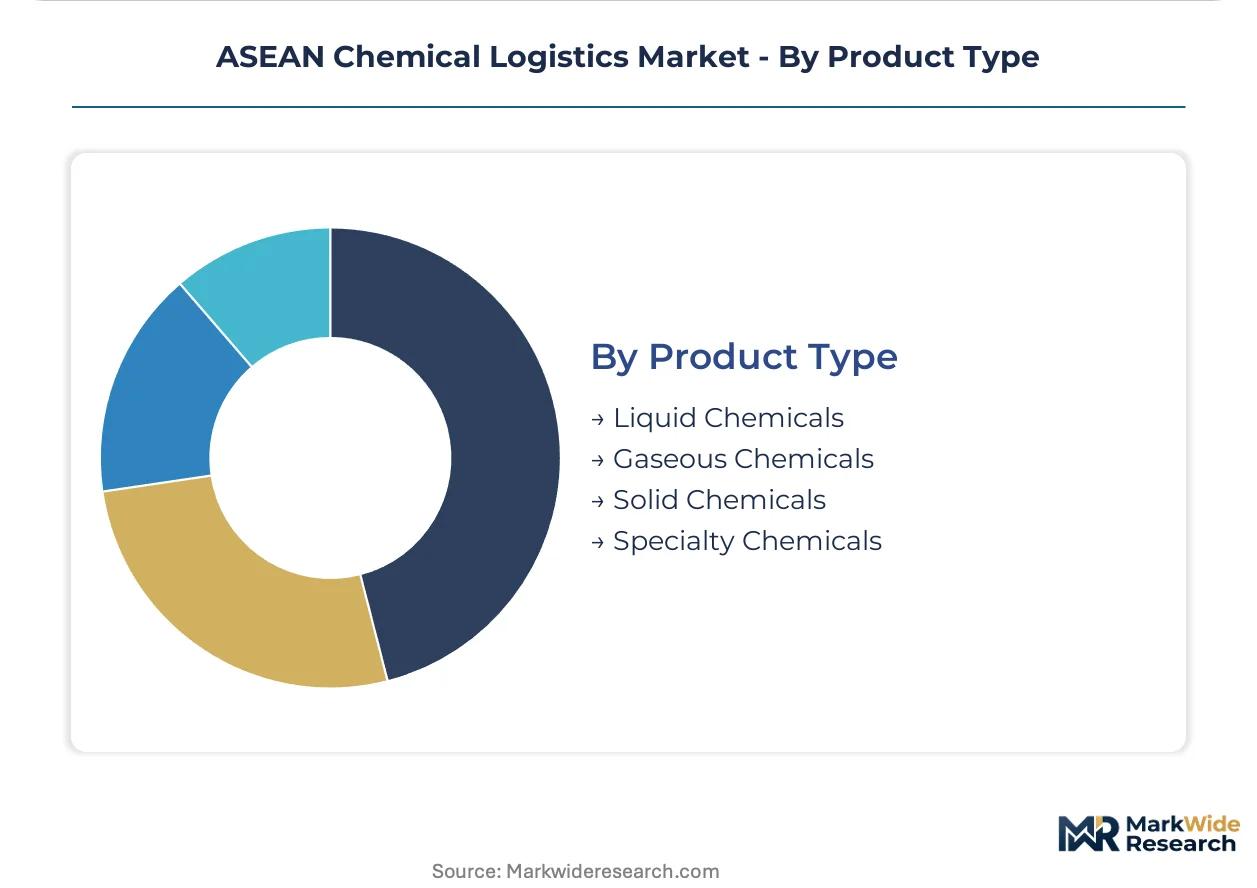
Product Type:
Physical state and hazard classification dictate containment infrastructure, with liquid chemicals requiring the most specialized handling systems across ASEAN port zones.
- Liquid Chemicals:Bulk liquid terminals with dual-wall tank systems and 24-hour spill response teams dominate capital allocation. Temperature-controlled storage for agrochemical intermediates concentrates in Vietnam's northern industrial corridor. Indonesian palm derivative exporters drive demand for captive ISO tank container pools outside Java.
- Specialty Chemicals:Electronics-grade solvents and agrochemical formulations require nitrogen blanketing and automated inventory tracking. Mitsubishi Chemical Logistics leverages integrated port-to-plant networks to capture consolidated procurement from relocated manufacturers.
- Solid Chemicals:Drum and bag handling facilities face retrofit pressure for automation upgrades to meet specialty chemical customer specifications.
- Gaseous Chemicals:Pressurized container requirements restrict handling to specialized terminals with fire suppression infrastructure and pressure relief systems.
Liquid chemicals dominate facility investment. Specialty chemicals concentrate value-added service margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's National Environment Agency anchors ASEAN chemical logistics regulation through its integrated port clearance framework, creating compliance benchmarks that neighboring jurisdictions reference. Thailand, Vietnam, Indonesia, and Malaysia each concentrate distinct demand drivers across bonded warehousing, temperature-controlled storage, and cross-border hazardous transport.
Thailand
Petrochemical zone incentives from Thailand's Board of Investment are compressing lead times for specialty chemical manufacturers relocating procurement from China. The Department of Industrial Works streamlined facility approvals under the Hazardous Substance Act for deepwater port zones, accelerating bonded storage construction. Laem Chabang and Map Ta Phut industrial zones anchor liquid chemical terminal expansion serving agrochemical formulators.
Vietnam
Foreign manufacturers relocating electronics and specialty chemical production from China are intensifying demand for nitrogen blanketing infrastructure. The northern industrial corridor around Hai Phong lacks sufficient automated drum facilities for specialty chemical distributors. Ho Chi Minh City and Hai Phong port hinterlands concentrate multimodal logistics networks serving just-in-time delivery requirements.
Indonesia
Palm derivative exporters outside Java drive demand for captive ISO tank container pools and temperature-controlled bulk liquid networks. The Ministry of Environment mandates spill response protocols requiring dual-wall tank systems and 24-hour response teams, elevating compliance costs for new entrants. Javanese industrial zones remain the primary concentration for oleochemical logistics infrastructure.
Malaysia
Cross-border road freight corridors between Peninsular Malaysia and Thailand concentrate dedicated hazardous materials fleets with ADR-certified drivers. Port Klang and Pasir Gudang industrial zones serve as transshipment nodes for specialty chemical distribution across ASEAN archipelago trade lanes. Bonded warehouse capacity near deepwater terminals captures margin pools from petrochemical re-exports.
Singapore
The National Environment Agency's integration of chemical logistics permits with port clearance systems creates regulatory friction for non-integrated warehouse operators lacking captive container yards. Jurong Island petrochemical cluster demands specialized liquid bulk terminals with vapor recovery systems. The city-state's regulatory framework functions as the regional template for dangerous goods handling certification.
ASEAN Chemical Logistics Market Competitive Landscape
Capability concentration sits with integrated port-to-plant operators; scale advantage sits with diversified maritime logistics conglomerates. The market structures around three tiers: captive chemical company logistics divisions, independent hazardous materials specialists, and diversified freight forwarders with chemical certification. Dominant competitive moves include strategic partnerships for cross-border fleet sharing and technology licensing for warehouse automation systems.
Within the integrated logistics tier, Mitsubishi Chemical Logistics exemplifies the port-to-plant network archetype across Vietnamese industrial corridors. Leschaco (Malaysia) Sdn Bhd and Den Hartogh Logistics occupy positions as hazardous materials specialists anchoring cross-border road freight and captive tank container pool operations respectively. These three represent distinct strategic postures: multimodal integration, regional corridor dominance, and equipment-heavy specialization serving export-oriented chemical segments.
| Leading Market Players |
|---|
| Mitsubishi Chemical Logistics |
| Leschaco (Malaysia) Sdn Bhd |
| Den Hartogh Logistics |
| Mitsui O.S.K. Lines |
| MOL Chemical Tankers |
| SCG Chemicals Public Company Limited |
| Dachser |
| Royal Den Hartogh Logistics |
| Noatum Logistics |
| Others |
Pricing and Supply Chain Analysis
Indonesian spill response mandates from the Ministry of Environment determine both the steep compliance cost spreads between premium and economy service tiers and the geographic clustering of bonded warehouse capacity around Java's established industrial zones. Buyers absorbing dual-wall tank infrastructure costs face pricing premiums of 40-60% above standard liquid chemical storage, while traders prioritizing spot clearance accept nitrogen blanketing service gaps in exchange for lower handling fees.
Pricing Analysis
Cross-border hazardous materials freight between Peninsular Malaysia and Thailand commands 25-35% premiums over domestic road rates due to ADR certification requirements and fleet scarcity. Pricing stratifies across integrated port-to-plant contracts, spot brokerage arrangements, and captive chemical company logistics divisions, with certification grade and volume scale as primary differentiation drivers. Cost compression in spot brokerage tiers is intensifying because Vietnamese electronics manufacturers are consolidating vendor relationships around single-source accountability. Distributors serving relocated Chinese manufacturers exhibit highest price sensitivity, while petrochemical formulators with captive ISO tank container pools demonstrate lowest sensitivity due to in-house depreciation schedules.
Supply Chain Analysis
Extended payment terms from Thai petrochemical buyers to logistics providers have compressed working capital cycles, forcing equipment-heavy operators to secure supply-chain finance facilities against tank container pools. Geographic supply concentration centers on Thailand's Eastern Seaboard, Vietnam's northern industrial corridor, and Singapore's Jurong Island petrochemical cluster. Raw material flows draw from Middle Eastern base chemical imports, Chinese specialty chemical additives, and Indonesian palm derivative feedstocks. Single-source vulnerability runs through Singapore's integrated permit system, where non-integrated warehouse operators face clearance delays without captive container yards. Distribution runs through bonded deepwater terminals with multimodal connectivity to electronics manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a post-relocation cyclical recovery driven by manufacturing migration from China into Vietnam's northern corridor, with demand for nitrogen blanketing infrastructure and automated drum facilities lagging supply by 18-24 months.
For Market Incumbents: Entrench competitive positioning through backward integration into captive ISO tank container manufacturing and exclusive port terminal leases at Hai Phong and Laem Chabang. Threats from digital-native logistics platforms with blockchain-enabled customs clearance require preemptive technology licensing investments. Certification pre-investment in ASEAN harmonized dangerous goods standards represents the critical defensive lever before regulatory deadlines tighten. For New Entrants and Emerging Players: Establish a beachhead in Indonesian oleochemical export cold chain networks outside Java, where temperature-controlled bulk liquid infrastructure remains underdeveloped relative to palm derivative production growth. The Vietnamese northern corridor's automated drum facility shortage offers the most penetrable white space for specialty chemical distributors. A go-to-market angle anchored to electronics manufacturer relocation clusters—offering guaranteed temperature integrity with single-source accountability—bypasses fragmented incumbent trucking arrangements. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors equipment-heavy specialists with captive tank container pools over asset-light freight forwarders. Long-term viability over a 5-10 year window hinges on regulatory compliance infrastructure rather than pure scale, making dual-certified handling equipment and spill response capabilities the durable moat. Acquisition target archetype: mid-cap hazardous materials specialists with established ADR-certified driver networks and deepwater port access. The signal to watch as inflection indicator is Thai Board of Investment incentive renewal timelines, which dictate bonded warehouse construction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tank Container Manufacturing | Captive equipment pools reduce dependency on Chinese ISO tank lessors and compress capital deployment cycles. |
| Joint Venture for Cross-Border Fleet Sharing | Malaysian-Thai corridor partnerships optimize ADR-certified driver utilization across fragmented trucking networks. |
| Green Certification Program for Nitrogen Blanketing | Singapore's National Environment Agency permits favor vapor recovery systems in Jurong Island terminal expansions. |
| Long-term Supply Agreement with Electronics Manufacturers | Vietnamese relocated production clusters demand guaranteed temperature integrity for agrochemical intermediates. |
| Capacity Expansion in Hai Phong Bonded Zone | Northern industrial corridor automation gaps create first-mover advantage for drum facility construction. |
Research Methodology
Desk research of customs trade databases, ASEAN regulatory filings, and petrochemical industry association reports preceded structured interviews with plant managers at Thai agrochemical formulators, procurement leads at Vietnamese electronics manufacturers, distribution channel partners across Malaysia-Thailand corridors, and technical R&D directors at specialty chemical producers. Bottom-up capacity assessments of bonded warehouse construction and ISO tank container fleet deployments were triangulated against top-down trade flow analysis across the analysis window.
Assumptions held fixed included prevailing Thai Board of Investment incentive structures, Indonesian Ministry of Environment spill response mandates, and Singapore's integrated permit framework; variables stress-tested included cross-border harmonization timelines, electronics manufacturing relocation velocity, and oleochemical export growth trajectories. Segmentation dimensions modeled encompassed transportation mode, service type bundling intensity, end-user sophistication tier, and product hazard classification grade. CAGRs were derived from equipment deployment trajectories and contract duration patterns across multimodal networks.
Stress conditions across regulatory harmonization delays, manufacturing relocation acceleration, and palm derivative export volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about incentive continuity and compliance cost trajectories. Macroeconomic contraction, abrupt regulatory restriction, or technological disruption in blockchain-enabled documentation platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market