
 Aircraft Amenities and Auxiliaries Market | 2026-2036
Aircraft Amenities and Auxiliaries Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Amenities and Auxiliaries Market Analysis
Market Context
European seat assembly capacity is decoupling from North American OEM schedules as Airbus ramps A320 family output in Toulouse and Hamburg. Stelia Aerospace leverages vertical integration across composite seat shells and thermoplastic manufacturing. Adient Aerospace anchors its position through Detroit-based R&D intensity in lightweight frame architectures. Recaro Aircraft Seating dominates long-haul business class configurations with specialized kinematic mechanisms.
Technical Definition and Segment Structure
Aircraft amenities and auxiliaries encompass all non-structural interior systems and passenger-facing equipment installed after airframe assembly, including fire-resistant textile assemblies meeting 16 CFR Part 25.853 burn-through criteria, injection-molded polycarbonate cabin components, and networked LED mood lighting with DALI protocol control. Seating solutions generate the deepest margin pools as airlines prioritize differentiated cabin experiences across premium economy and lie-flat segments. In-flight entertainment retains structural importance despite streaming displacement, since retrofit cycles for embedded hardware extend across decade-long fleet amortization periods. Smart lighting and energy management within the technology dimension are capturing disproportionate capital allocation as carriers target fuel burn reduction through LED conversion and intelligent load management.
Regulatory Framework and Outlook
FAA airworthiness directives and EASA CS-25 certification requirements govern flammability, smoke toxicity, and seat crashworthiness standards that dictate material selection and design validation protocols. EPA and REACH frameworks increasingly restrict halogenated flame retardants in textile and polymer formulations, forcing reformulation across supplier tiers. Stakeholders must monitor how CSRD disclosure mandates reshape procurement transparency requirements for tier-two component vendors supplying into final assembly.
Market Dynamics
Retrofit demand from Asia-Pacific full-service carriers is compressing seat assembly lead times and forcing European suppliers to decouple from Boeing-Airbus OEM synchronization. FAA burn-through testing protocols and EASA CS-25 amendments are simultaneously tightening material specifications while COMAC production ramps in Shanghai.
Growth Catalysts
- REACH flame-retardant restrictions:European chemical regulations are forcing reformulation of halogenated textiles, opening substitution contracts for phosphorus-based alternatives in cabin panels and seat assemblies.
- China domestic fleet expansion:COMAC C919 deliveries and narrow-body orders from Hainan Airlines and China Eastern are generating concentrated demand for premium economy seating configurations.
- LED conversion mandates:Carrier fuel-burn reduction targets are accelerating DALI-protocol lighting retrofits across aging A320 and 737 fleets, displacing fluorescent ballast systems.
Market Restraints
- Thermoplastic resin cost volatility:PA12 and PEEK feedstock prices fluctuate with oil-indexed contracts, compressing margin on composite seat shell programs.
- Single-source certification risk:FAA designated engineering representatives concentrate in Wichita and Seattle, creating bottleneck delays for novel kinematic mechanism approvals.
- Streaming substitution:Passenger device proliferation reduces perceived value of embedded IFE hardware, extending payback periods for retrofit investments.
Strategic Opportunities
- India narrow-body penetration:IndiGo and Air India Express fleet expansion creates white space for lightweight frame architectures in high-density configurations.
- CSRD procurement transparency:EU disclosure mandates are reshaping tier-two vendor qualification, favoring suppliers with documented carbon accounting.
- Biometric-IFE convergence:Facial recognition boarding and personalized content delivery are merging, enabling monetization of passenger data streams.
Industry Challenges
- Composite technician scarcity:Thermoplastic welding and automated fiber placement skills concentrate in Toulouse and Hamburg, creating recruitment friction for North American MRO expansion.
- 16 CFR Part 25.853 recertification:Burn-through test protocol updates require destructive sampling of installed seat assemblies, disrupting fleet availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Amenities and Auxiliaries Market |
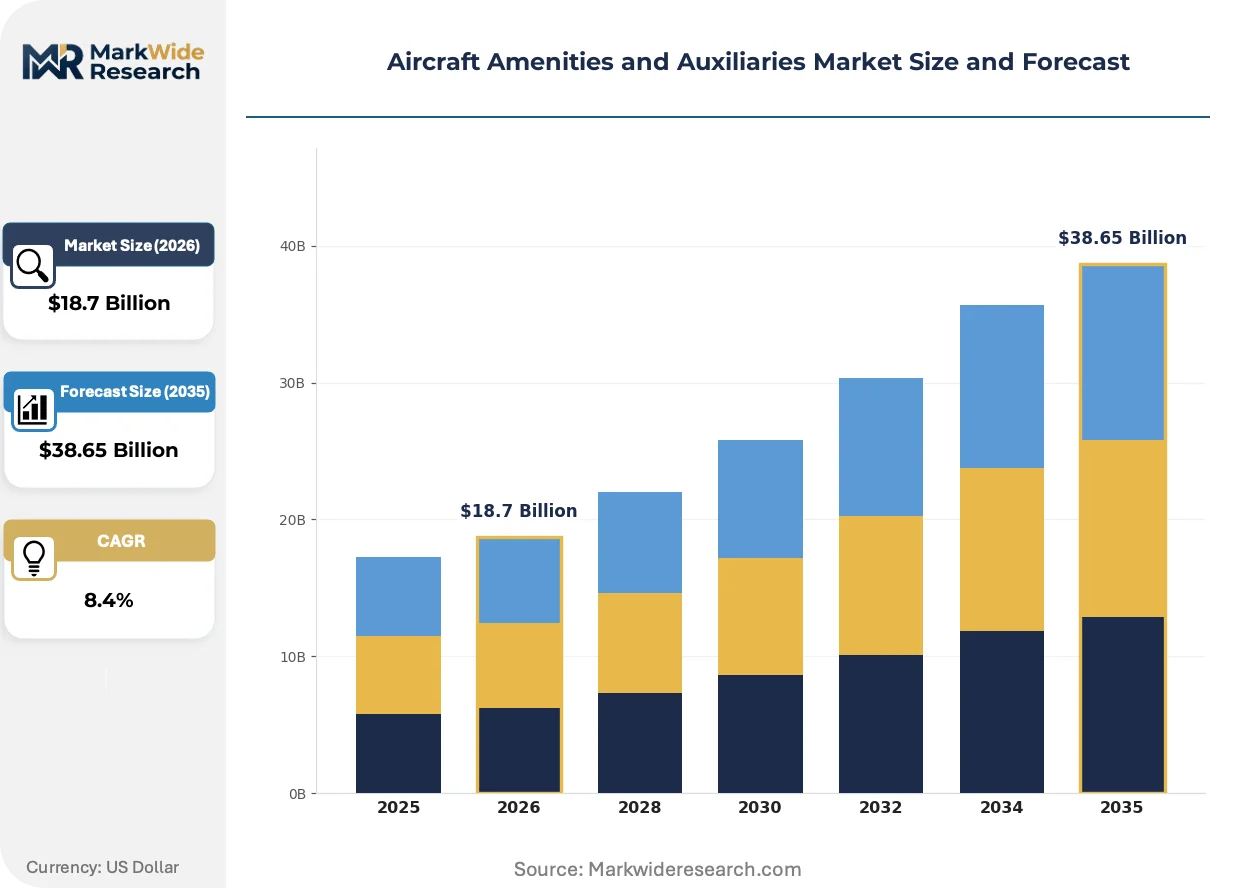
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Flight Entertainment, Cabin Lighting, Lavatory Supplies, Seating Solutions Material: Textiles, Composites, Metals, Plastics End User: Commercial Airlines, Private Jets, Cargo Airlines, Military Aircraft Technology: Wi-Fi Systems, Bluetooth Connectivity, Smart Lighting, Energy Management |
| Companies Covered | Stelia Aerospace, Adient Aerospace, Safran Seats, Haeco, Expliseat, Collins Aerospace, Jamco Corporation, Zodiac Seats, Recaro Aircraft Seating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Amenities and Auxiliaries Market Emerging Trajectories
Digital thread integration across seat design, manufacturing, and aftermarket service is collapsing traditional handoff points between OEMs and airlines. Real-time kinematic monitoring and predictive maintenance algorithms are shifting value capture from hardware sale to performance contracts.
Thermoplastic composite seat shells are expanding into long-haul business class configurations previously reserved for metallic frames. Singapore Airlines and Qatar Airways are specifying continuous fiber-reinforced PA12 for weight reduction targets. This material transition is expanding into crashworthiness-critical zones as Stelia Aerospace and Recaro validate impact performance against dynamic 16g test requirements.
EASA CS-25 Amendment 25-146 introduced stricter smoke toxicity thresholds for cabin interior materials, effective across all new type certificates. European seat assemblers are reformulating polyurethane foams and film adhesives to meet HCN and HCl emission limits. Asian carriers operating into EU airspace are now demanding pre-certified component supply to avoid retrofit liability exposure.
Airline technical procurement teams are consolidating vendor panels and demanding lifecycle cost guarantees rather than unit price discounts. Lufthansa Technik and ST Engineering are unbundling installation labor from hardware supply, capturing margin previously held by seat OEMs. This purchasing transformation is most visible in Southeast Asia, where low-cost carriers negotiate power-by-the-hour arrangements for IFE and lighting systems.
Aircraft Amenities and Auxiliaries Market Segmentation
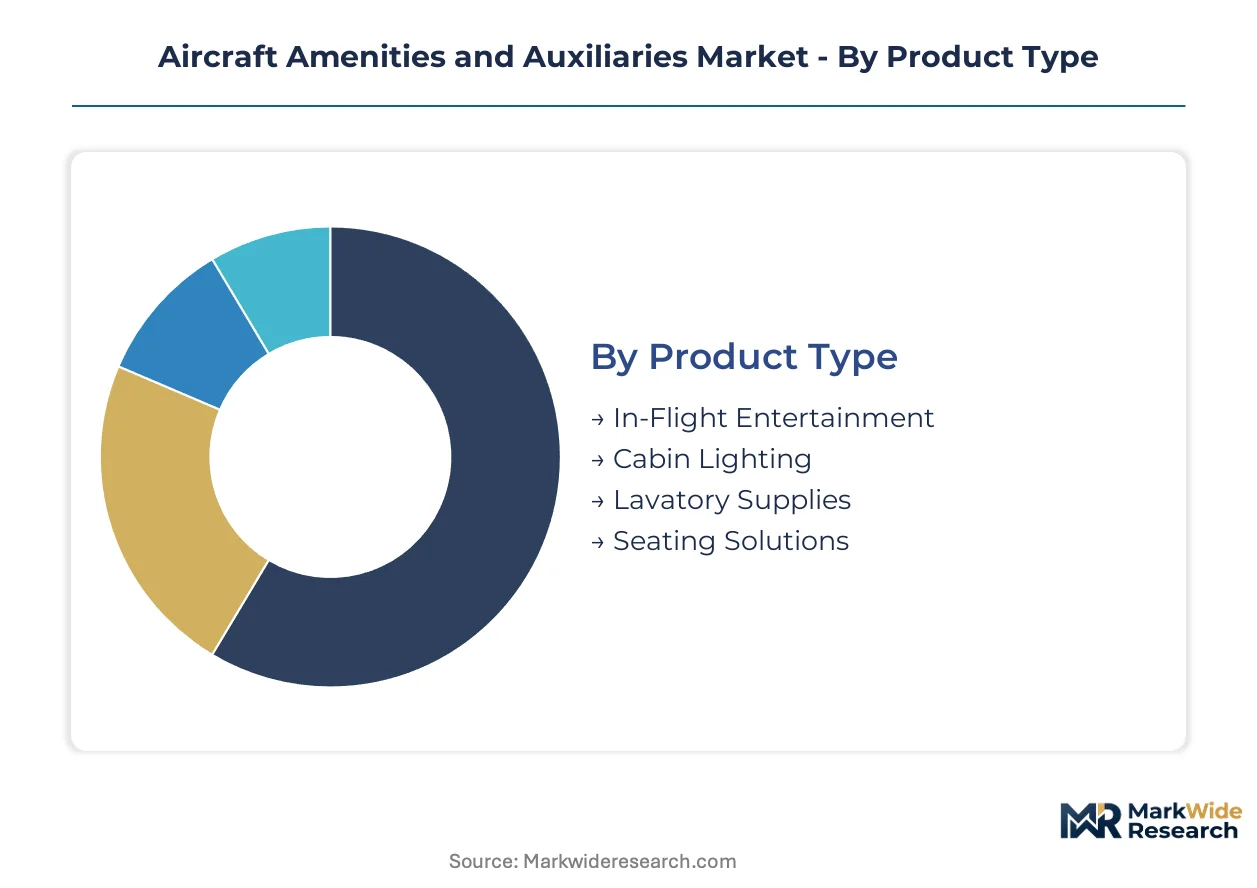
Aircraft amenities and auxiliaries fragment across four distinct taxonomies that reflect divergent buyer priorities: fleet managers optimize total cost of ownership through material selection, while passenger experience teams prioritize connectivity integration and cabin ambiance. Procurement contracts increasingly bundle hardware with lifecycle service commitments, collapsing traditional boundaries between product categories.
Product Type:
Airline technical procurement teams weight retrofit complexity against passenger-facing differentiation when allocating capital across interior systems.
- Seating Solutions:Kinematic mechanisms and fire-resistant upholstery assemblies dominate program value, with lie-flat business class configurations commanding extended lead times. Demand concentrates in Asia-Pacific full-service carrier retrofits as Airbus A350 and Boeing 787 fleets expand premium cabin footprints.
- In-Flight Entertainment:Embedded seatback screens with 4K resolution and integrated power delivery retain structural importance despite streaming displacement, since retrofit cycles amortize across decade-long fleet ownership periods. Narrow-body operators in India and Southeast Asia are delaying hardware refresh in favor of wireless streaming infrastructure.
- Cabin Lighting:DALI-protocol LED systems displace fluorescent ballasts for fuel burn reduction.
- Lavatory Supplies:Touchless fixtures and antimicrobial surfaces address hygiene protocols post-pandemic.
Seating Solutions leads on scale; Cabin Lighting leads on momentum.
Material:
Flammability certification requirements under FAA 16 CFR Part 25.853 and EASA CS-25 govern material substitution economics and supplier qualification timelines.
- Composites:Continuous fiber-reinforced thermoplastics—specifically PA12 and PEEK formulations—are penetrating crashworthiness-critical zones previously reserved for metallic frames. Stelia Aerospace and Recaro validate impact performance against dynamic 16g test requirements for Singapore Airlines and Qatar Airways specifications.
- Textiles:Fire-resistant wool-nylon blends and inherently flame-retardant polyester assemblies face REACH-driven reformulation as halogenated retardants phase out. European seat assemblers are qualifying phosphorus-based alternatives to meet HCN and HCl emission limits under EASA CS-25 Amendment 25-146.
- Metals:Aluminum frame architectures persist in high-density economy configurations where weight savings yield to unit cost constraints.
- Plastics:Injection-molded polycarbonate cabin components balance impact resistance with thermoformability for rapid part replacement.
Metals dominates installed base; Composites climbs the fastest on new program wins.
End User:
Operating cost structures and amortization horizons diverge sharply between scheduled passenger service and specialized mission profiles.
- Commercial Airlines:Full-service carriers monetize cabin differentiation through premium economy and lie-flat segments, while low-cost operators prioritize seat density and turnaround speed. COMAC C919 deliveries to Hainan Airlines and China Eastern are generating concentrated demand for domestic narrow-body configurations.
- Private Jets:Custom interior completion cycles reflect owner preferences for bespoke materials and artisan craftsmanship, with lead times extending 18-24 months for green airframe outfitting.
- Cargo Airlines:Quick-change combi configurations require modular seating that deploys for passenger service and stows for freight operations.
- Military Aircraft:Crashworthiness and electromagnetic hardening specifications exceed civilian requirements, limiting supplier pools to defense-qualified vendors.
Commercial Airlines anchors volume; Private Jets captures the steepest margin expansion.
Technology:
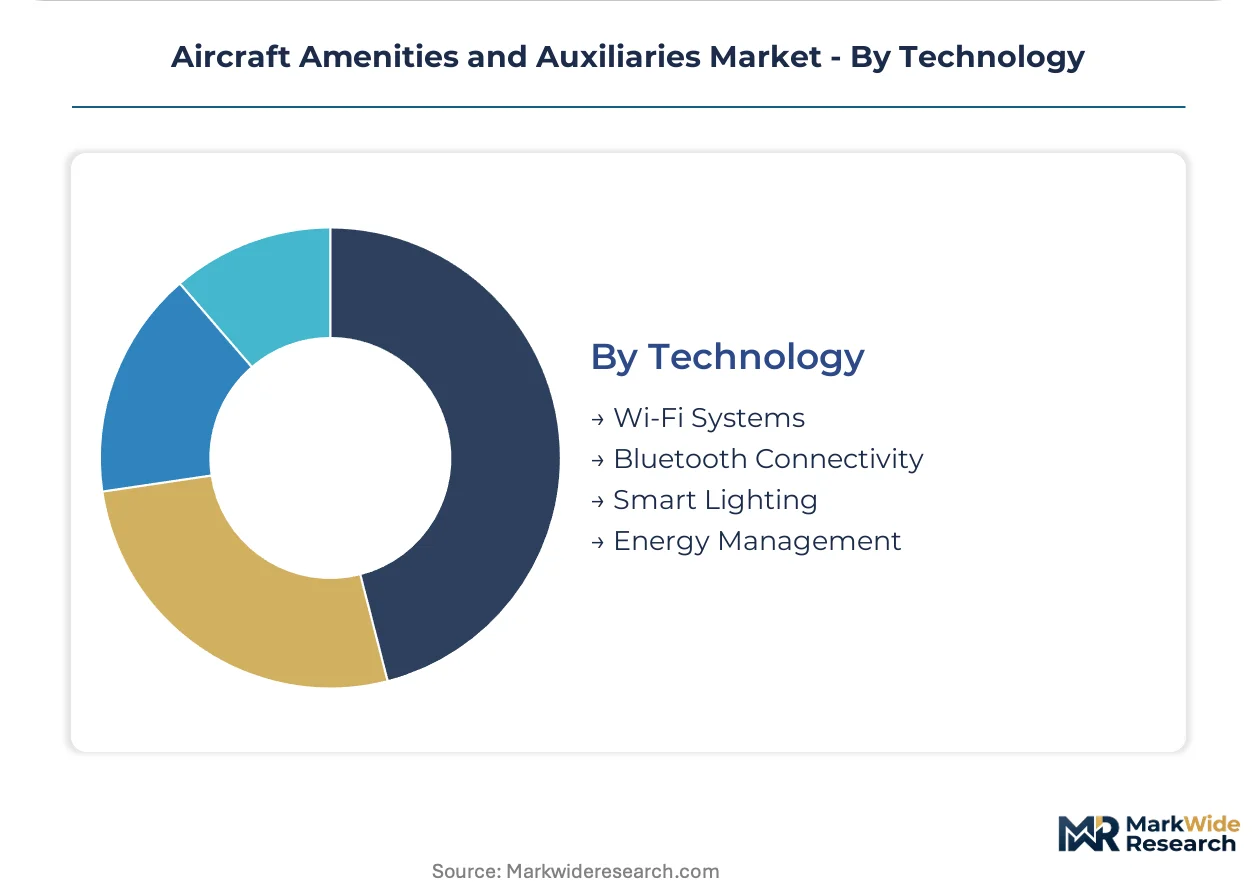
Connectivity infrastructure and intelligent load management are capturing disproportionate capital allocation as carriers target operational efficiency and ancillary revenue streams.
- Smart Lighting:DALI-protocol networked controls enable circadian rhythm programming and predictive maintenance through real-time diode performance monitoring. Lufthansa Technik and ST Engineering unbundle installation labor from hardware supply, capturing margin previously held by seat OEMs.
- Wi-Fi Systems:Ka-band and L-band satellite connectivity hardware faces passenger willingness-to-pay constraints despite installation cost recovery pressures. Low-cost carriers in Southeast Asia negotiate power-by-the-hour arrangements to align capital outlay with usage-based revenue.
- Energy Management:Intelligent load shedding and battery monitoring systems reduce generator sizing requirements.
- Bluetooth Connectivity:Personal device pairing for audio streaming displaces embedded headphone jacks in retrofit programs.
Wi-Fi Systems leads on installed base investment; Smart Lighting gains share fastest on retrofit conversion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as EASA REACH compliance costs in Europe push thermoplastic composite sourcing toward Asian manufacturing clusters with lower reformulation burdens.
United States
FAA burn-through testing under 16 CFR Part 25.853 drives seat assembly recertification cycles for aging narrow-body fleets. The agency's designated engineering representative concentration in Wichita and Seattle creates approval bottlenecks for novel kinematic mechanisms. Dallas-Fort Worth anchors MRO capacity expansion as American Airlines and Southwest accelerate LED retrofit programs.
China
COMAC C919 deliveries to Hainan Airlines and China Eastern generate concentrated demand for premium economy seating configurations. The country's MIIT standards for cabin interior materials are converging toward EASA smoke toxicity thresholds to facilitate export certification. Shanghai's Pudong district hosts expanding thermoplastic welding capacity serving both domestic carriers and foreign OEM supply chains.
Germany
REACH flame-retardant restrictions force halogenated textile phase-out across seat upholstery and cabin panel supply chains. The country's KBA maintains alignment with EASA CS-25 Amendment 25-146 for HCN and HCl emission limits. Hamburg's Airbus final assembly lines drive synchronized seat delivery schedules from adjacent Stelia Aerospace and Recaro production facilities.
France
Full-service carrier retrofit demand from Air France-KLM compresses lead times for lie-flat business class configurations on A350 and 787 fleets. The ANSM enforces CSRD disclosure mandates that reshape tier-two vendor qualification for carbon accounting transparency. Toulouse anchors Stelia Aerospace's vertical integration across composite seat shells and thermoplastic manufacturing.
Singapore
Singapore Airlines and Qatar Airways specify continuous fiber-reinforced PA12 for long-haul business class weight reduction targets. The country's civil aviation authority maintains bilateral recognition with EASA for CS-25 certification reciprocity. Seletar Aerospace Park concentrates thermoplastic composite technician skills serving Asia-Pacific MRO expansion.
Aircraft Amenities and Auxiliaries Market Vendor Landscape
European producers anchor the premium-tier segment through EASA-aligned certification depth; Asian specialists hold cost-competitive positions in high-volume narrow-body configurations. The vendor base stratifies across three tiers: full-service integrators with captive composite manufacturing, seat assembly specialists outsourcing shell production, and component suppliers focused on kinematic mechanisms or textile assemblies. Dominant competitive moves include backward integration into thermoplastic resin formulation and strategic partnerships with COMAC for China domestic fleet qualification.
Within the full-service integrator tier, Stelia Aerospace exemplifies vertical control from composite shell production through final assembly, while Recaro Aircraft Seating occupies a position defined by long-haul business class kinematic specialization. Adient Aerospace anchors the Detroit-based R&D intensity archetype for lightweight frame architectures. These three entities represent distinct competitive positioning vectors: European certification-integrated manufacturing, German kinematic mechanism expertise, and North American automotive-derived lightweighting.
| Leading Market Players |
|---|
| Stelia Aerospace |
| Adient Aerospace |
| Safran Seats |
| Haeco |
| Expliseat |
| Collins Aerospace |
| Jamco Corporation |
| Zodiac Seats |
| Recaro Aircraft Seating |
| Others |
Supply Flow & Price Mechanics
Thermoplastic composite welding specialists concentrate in Toulouse, Hamburg, and Shanghai, creating labor-cost differentials that widen pricing-tier spreads between premium kinematic seat assemblies and high-density economy configurations.
Pricing Analysis
Distributor margins on replacement textile assemblies and lighting components compress final-equipment pricing by 12-18 points before airline technical procurement. Three-tier pricing structure across premium lie-flat, standard recliner, and high-density economy levels reflects certification-grade differentiation and after-sales bundling intensity. Pricing pressure stems from COMAC C919 volume procurement contracts as Chinese carriers negotiate lifecycle cost guarantees. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while full-service carriers in Singapore and Qatar prioritize weight-reduction performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Hamburg, Shanghai, and Dallas-Fort Worth anchor hub-and-spoke patterns for seat assembly components and retrofit hardware kits. Manufacturing concentrates in France, Germany, and China, with raw material dependencies on Saudi-sourced PA12 resin, Korean-sourced PEEK feedstock, and Belgian-sourced phosphorus-based flame retardants. Single-source vulnerability around FAA-designated engineering representative certification creates approval bottlenecks for novel kinematic mechanisms. Distribution runs through OEM-integrated direct fulfillment for new aircraft and MRO-channel stocking for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Asia-Pacific full-service carriers shift retrofit demand toward premium cabin specifications with extended amortization horizons.
For Market Incumbents: Anticipate margin compression from COMAC supply chain localization mandates by deepening backward integration into thermoplastic resin formulation and captive composite shell production. EASA CS-25 Amendment 25-146 recertification requirements for HCN emission limits threaten installed base revenue streams; prioritize qualification of pre-certified component architectures for Asian carrier fleets. For New Entrants and Emerging Players: Enter via India's narrow-body expansion as IndiGo and Air India Express fleet growth outpaces incumbent seat assembly capacity. White space exists in lightweight frame architectures for high-density configurations where automotive-derived manufacturing scale can displace aerospace-incumbent cost structures. Go-to-market angle: power-by-the-hour service bundling with unbundled installation labor capture. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two kinematic mechanism specialists lacking EASA certification depth but holding FAA approval pathways. Long-term viability centers on CSRD procurement transparency mandates reshaping vendor qualification toward carbon-accounting documentation. Signal to watch: COMAC C919 export certification reciprocity agreements with EASA jurisdictions as inflection indicator for China-domestic supplier re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastic Resin | Captures margin from PA12 price volatility while securing REACH-compliant formulation control. |
| CSRD-Aligned Carbon Accounting Certification | Qualifies tier-two vendors for Lufthansa Technik and Air France-KLM procurement panels. |
| COMAC C919 Supply Chain Qualification | Locks in decade-long narrow-body delivery schedules from Hainan Airlines and China Eastern. |
| DALI-Protocol Lighting Retrofit Platform | Captures fuel-burn reduction mandates across aging A320 and 737 fleets at American Airlines. |
| Predictive Maintenance Service Contracts | Shifts value capture from hardware sale to performance-based arrangements with ST Engineering. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with airline technical procurement directors, seat OEM program managers, MRO operations heads, and thermoplastic composite manufacturing engineers with secondary validation. Secondary sources include FAA airworthiness directive filings, EASA CS-25 certification databases, COMAC delivery schedules, and REACH regulatory guidance documents. Bottom-up segment sizing triangulates against top-down fleet projection models.
Rate-of-change decomposition isolates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user operating model, and technology integration level. CAGRs derive from fitted growth curves against historical retrofit cycle data and announced fleet expansion programs. Industry-specific inputs include 16 CFR Part 25.853 burn-through test protocol updates and MIIT-EASA convergence timelines for cabin interior material standards.
Inputs from airline procurement directors and seat OEM engineering leads were available through the study window; gaps in COMAC C919 long-term delivery commitments and REACH alternative flame-retardant qualification timelines introduce uncertainty bands around China domestic fleet projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aircraft Seating Market