
 Aerospace Lavatory System Market | 2026-2036
Aerospace Lavatory System Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Lavatory System Market Outlook
Narrow-body commercial aviation is repositioning lavatory system procurement toward weight-optimized, space-efficient configurations. Safran leverages its integrated cabin systems portfolio to anchor European airline retrofit cycles. Diehl Stiftung & Co. KG sustains competitive positioning through specialized lavatory module manufacturing for Airbus platforms. JAMCO Corporation dominates supply to Japanese and Southeast Asian carriers with compact vacuum system designs.
An aerospace lavatory system comprises vacuum waste containment, potable water supply, odor control, and structural enclosure assemblies engineered to FAR 25.853 flammability standards, with primary purpose to sanitize and store human waste during flight operations while minimizing weight and water consumption. Vacuum systems lead product type demand due to regulatory mandates eliminating older chemical toilet installations across commercial fleets. Smart toilet technology represents the fastest-growing segment as touchless interfaces and sensor-based maintenance alerts reduce crew workload and improve hygiene protocols. Modular installation approaches concentrate margin pools by enabling line-fit customization and faster MRO turnaround.
FAA airworthiness directives and EASA CS-25 certification frameworks govern flammability, structural integrity, and electromagnetic compatibility of lavatory assemblies, compelling manufacturers to maintain dual-approval testing regimes. EPA effluent standards and OSHA workplace exposure limits further constrain chemical toilet residual handling, redirecting procurement toward closed-loop vacuum architectures. Stakeholders must monitor evolving CSRD sustainability disclosure requirements and airline ESG commitments that will increasingly embed lifecycle carbon metrics into lavatory system selection criteria.
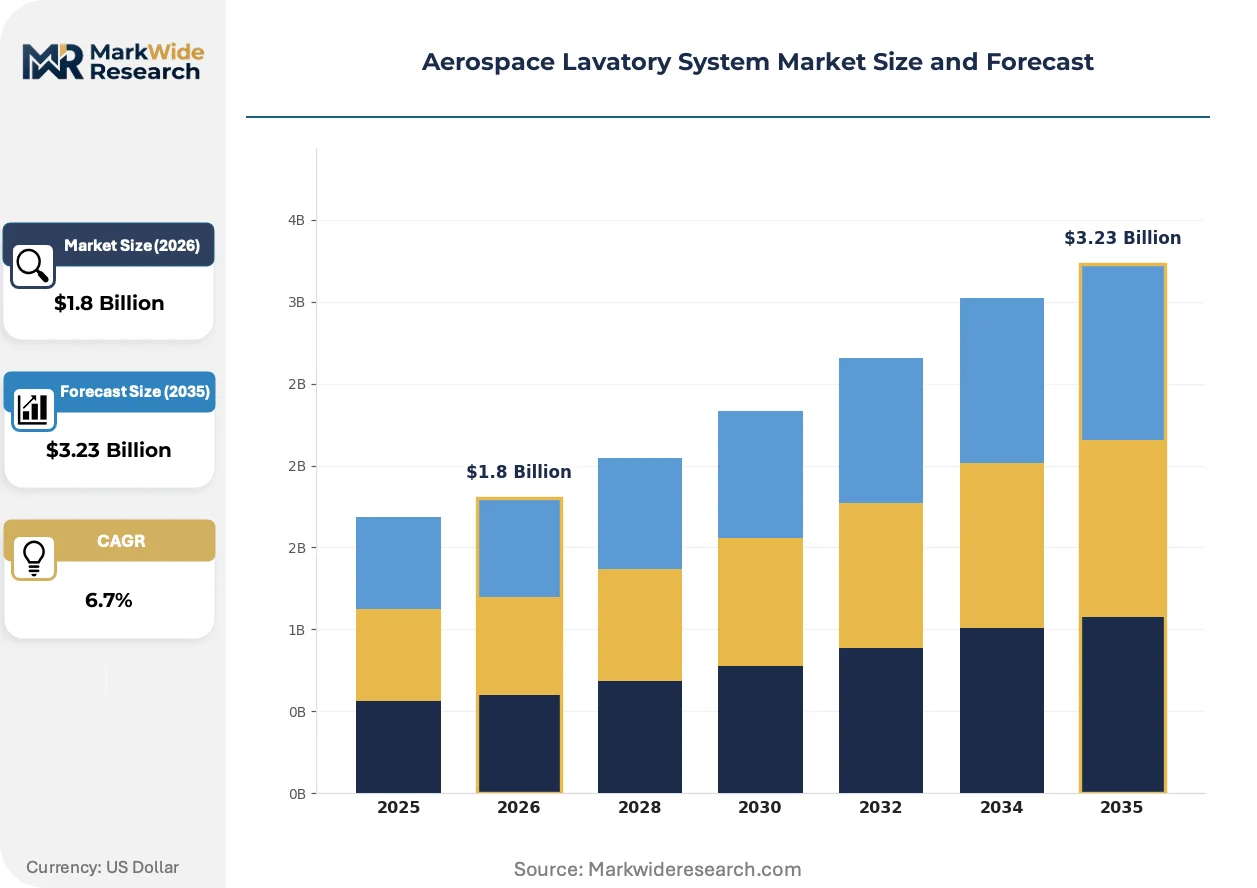
Market Dynamics
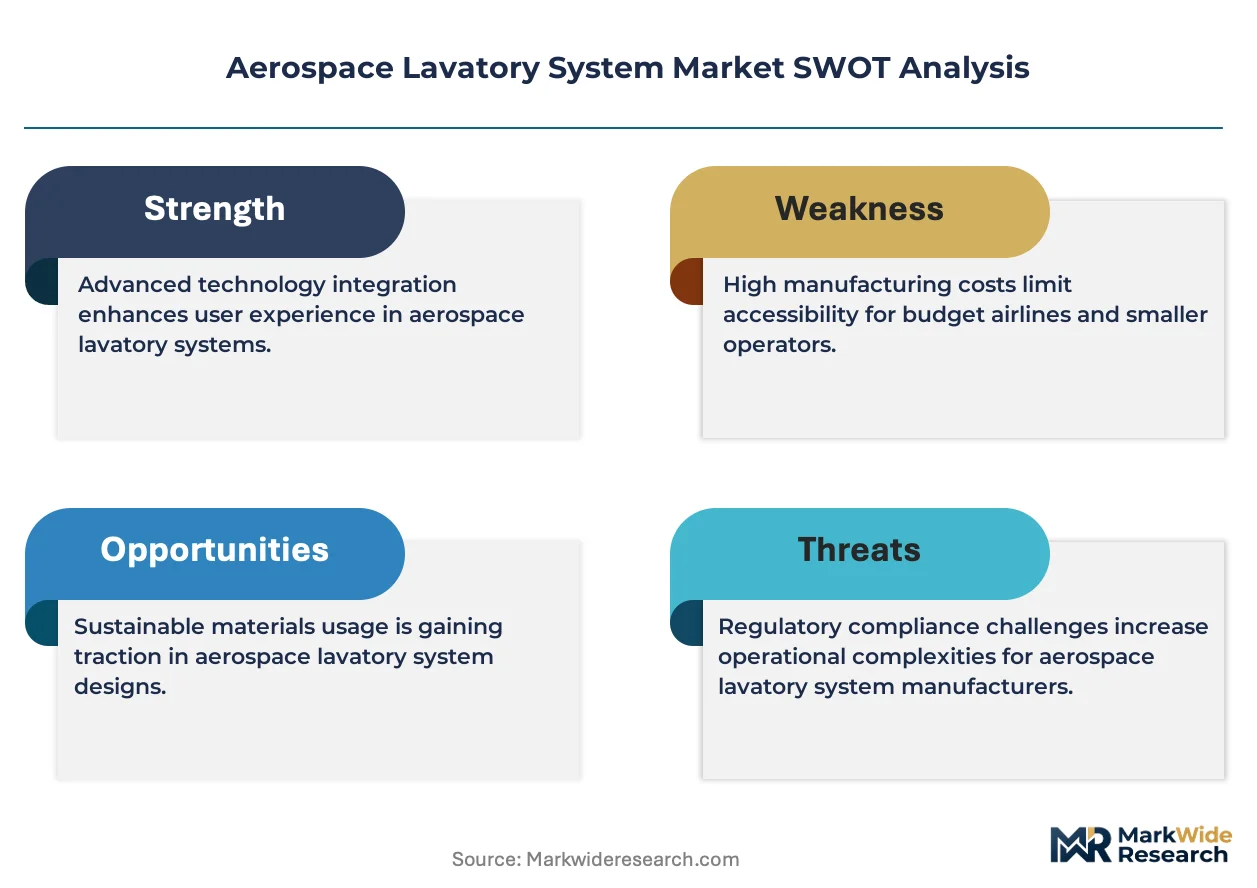
Fleet modernization cycles across narrow-body aviation are compressing procurement timelines for lavatory system suppliers, as carriers prioritize weight reduction and water conservation to offset rising fuel costs and meet tightening environmental mandates.
Growth Catalysts
- FAA Airworthiness Directives:Mandates phasing out chemical toilet systems are forcing commercial operators toward vacuum waste architectures, creating replacement demand across aging narrow-body fleets.
- India:Low-cost carriers expanding domestic and regional routes are driving line-fit procurement of compact, lightweight lavatory modules optimized for high-utilization cycles.
- Sensor Integration:Touchless interfaces and predictive maintenance algorithms are reducing crew workload and unscheduled ground time, accelerating airline technology refresh investments.
Market Restraints
- Titanium and Composite Input Costs:Volatility in aerospace-grade material pricing compresses margins for enclosure and structural component manufacturers locked into long-term supply agreements.
- Supplier Concentration in Japan:Vacuum system pump and valve assembly production clusters around a limited supplier base, exposing procurement chains to geographic disruption risk.
- EASA CS-25 Certification Burden:Dual-approval testing requirements for flammability and electromagnetic compatibility extend product development cycles and raise entry barriers for new entrants.
Strategic Opportunities
- Vietnam:Emerging low-cost carrier capacity expansion presents untapped demand for retrofit-ready lavatory systems compatible with leased narrow-body configurations.
- CSRD Sustainability Disclosure:European airline ESG commitments are embedding lifecycle carbon metrics into supplier selection criteria, favoring manufacturers with verified environmental product declarations.
- Modular-Additive Convergence:3D-printed polymer brackets combined with standardized vacuum interfaces enable rapid customization and reduced spare parts inventory for MRO networks.
Industry Challenges
- Aerospace Systems Integration Expertise:Shortages of engineers fluent in both cabin interior certification and fluid dynamics are constraining R&D throughput for smart toilet development programs.
- Legacy Fleet Interoperability:Retrofit installations must reconcile modern vacuum system dimensions with original equipment mounting points and plumbing runs, complicating field engineering and documentation.
- Extended Certification Timelines:FAA and EASA harmonization gaps on updated flammability testing protocols are delaying product approvals and freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Lavatory System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Systems, Gravity Systems, Chemical Toilets, Portable Toilets End User: Commercial Aircraft, Military Aircraft, Business Jets, Helicopters Technology: Electric Flush, Manual Flush, Hybrid Systems, Smart Toilets Installation Type: Bulkhead Installation, Floor Installation, Overhead Installation, Modular Installation |
| Companies Covered | JAMCO Corporation, Safran, Collins Aerospace, Diehl Stiftung & Co. KG, RTX, Geven, THE YOKOHAMA RUBBER CO., LTD., CIRCOR Aerospace, FACC AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Lavatory System Market Strategic Shifts
Digital hygiene interfaces and closed-loop waste processing are redefining lavatory system value propositions, shifting competitive advantage from mechanical reliability toward data-enabled operational efficiency and passenger experience differentiation.
Smart toilet technology is decentralizing maintenance scheduling across airline fleets. Sensor arrays monitoring flush cycles, valve wear, and odor filter saturation transmit real-time alerts to ground operations teams. Southeast Asian carriers with high aircraft utilization rates are deploying these systems most aggressively, compressing unscheduled removal events and redirecting labor toward predictive interventions.
EASA CS-25 amendments addressing electromagnetic interference from passenger electronic devices are tightening shielding requirements for lavatory control modules. Manufacturers must redesign circuit architectures to withstand higher-frequency emissions. European retrofit programs face the steepest compliance costs, with suppliers absorbing testing overhead to maintain platform approvals.
Airline procurement departments are consolidating vendor relationships around integrated cabin system providers capable of delivering lavatory, galley, and seating configurations as unified packages. This bundling displaces standalone component sourcing for narrow-body programs. Indian low-cost carriers are pioneering this approach, leveraging volume commitments to extract customization concessions and single-point accountability for interior delivery timelines.
Aerospace Lavatory System Market Segmentation
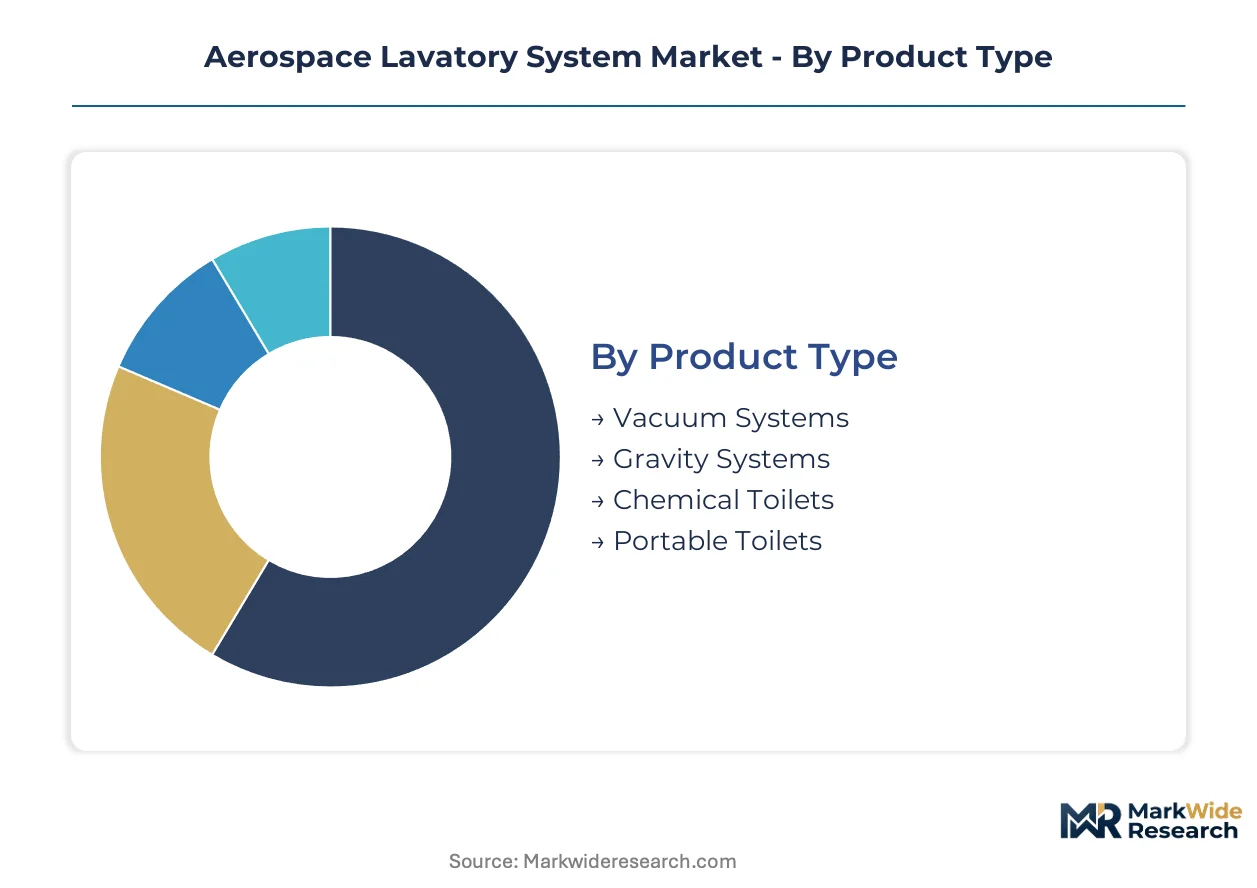
Segmentation in aerospace lavatory systems reveals distinct engineering requirements across platform types and operational profiles. Procurement patterns diverge sharply between line-fit OEM specifications and aftermarket retrofit configurations, with regulatory mandates and weight optimization driving technology selection.
Product Type:
Vacuum systems operate as standalone waste management architectures, while gravity and chemical configurations increasingly embed into integrated cabin modules for cost-sensitive applications.
- Vacuum Systems:These assemblies employ differential pressure to transport waste to containment tanks, eliminating water-intensive flushing. Demand clusters in India and Vietnam as low-cost carriers retrofit narrow-body fleets to meet FAA airworthiness directives phasing out chemical alternatives.
- Gravity Systems:Passive drainage designs using minimal moving parts serve regional turboprops and older aircraft where electrical load constraints persist. Southeast Asian operators with mixed-generation fleets maintain procurement for interoperability with existing plumbing infrastructure.
- Chemical Toilets:Recirculating blue-fluid systems persist in military transport and cargo conversions where vacuum infrastructure retrofit costs prove prohibitive.
- Portable Toilets:Self-contained units address helicopter and light aircraft applications lacking fixed waste plumbing, with demand tied to emergency medical services and offshore energy transport.
Volume placements concentrate in vacuum systems; the faster expansion belongs to smart toilet integrations within vacuum architectures.
End User:
Commercial aviation dominates procurement scale, yet military and business aviation segments command premium pricing through specialized certification requirements and lower production volumes.
- Commercial Aircraft:Narrow-body programs generate the highest unit volumes, with lavatory modules specified for weight targets below 35 kilograms per unit. Indian low-cost carriers compress procurement cycles through bundled cabin interior packages.
- Military Aircraft:Tactical transport platforms require ruggedized enclosures meeting MIL-STD-810 shock and vibration standards. Demand concentrates in crewed reconnaissance and tanker configurations where mission duration exceeds bladder capacity limits.
- Business Jets:Custom interior programs prioritize aesthetic integration and noise suppression over standardization. Completion centers in the United States and Switzerland specify bespoke vacuum systems with enhanced odor control.
- Helicopters:Severe weight and space constraints favor portable or compact gravity systems. Offshore oil and gas transport operators in the North Sea and Gulf of Mexico drive replacement demand for corrosion-resistant enclosures.
Commercial aircraft absorb the greatest unit volumes; business jets generate the steepest expansion trajectory through super-midsize platform introductions.
Technology:
Flush mechanism selection reflects trade-offs between electrical load, maintenance complexity, and passenger experience expectations across fleet types.
- Electric Flush:Solenoid-actuated valves deliver consistent performance across altitude variations, with sensor integration enabling usage monitoring. Southeast Asian carriers deploy these systems most aggressively for predictive maintenance programs.
- Manual Flush:Mechanical linkages eliminate electrical failure modes, persisting in military and cargo applications where system simplicity outweighs convenience.
- Hybrid Systems:Battery-backed electric operation with manual override addresses regulatory redundancy requirements for extended over-water operations.
- Smart Toilets:Touchless interfaces with IoT connectivity transmit maintenance alerts and usage analytics to ground operations teams.
Electric flush dominates current placements; smart toilet technology climbs the fastest as EASA electromagnetic compatibility amendments drive control module redesigns.
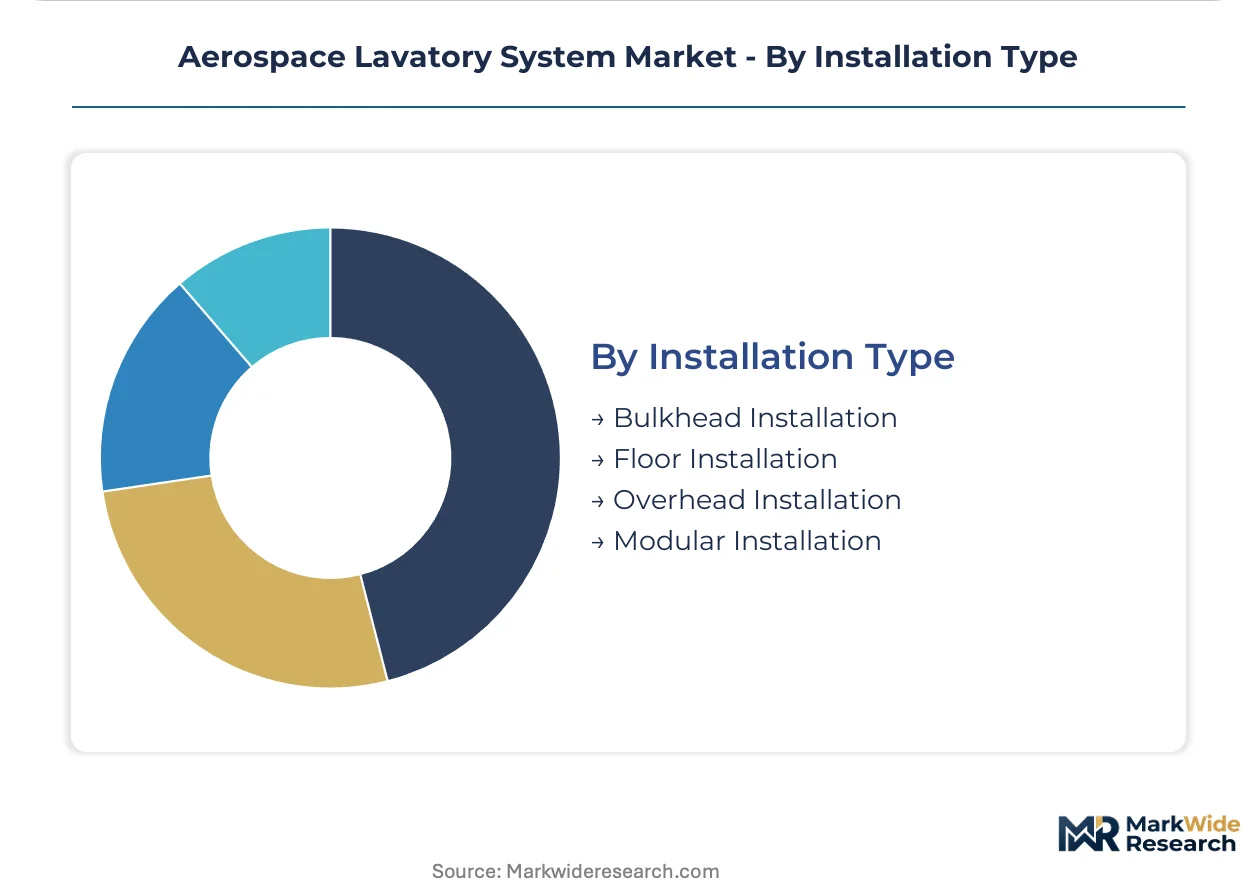
Installation Type:
Mounting configuration determines structural load paths and accessibility for maintenance, with modular approaches gaining share through MRO network efficiency.
- Bulkhead Installation:Wall-mounted assemblies transfer structural loads to airframe frames, common in narrow-body forward and aft lavatory positions. Retrofit programs in Vietnam face dimensional reconciliation challenges with original mounting points.
- Floor Installation:Pedestal-mounted systems distribute weight through cabin floor beams, preferred for wheelchair-accessible configurations requiring reinforced support.
- Overhead Installation:Ceiling-suspended waste tanks and supply modules free floor space in compact helicopter and business jet cabins.
- Modular Installation:Pre-integrated lavatory units with standardized utility connections enable rapid line-fit and replacement. Indian carriers extract customization concessions through volume commitments to integrated cabin system providers.
Modular installation gains share fastest; bulkhead mounting retains the greatest installed base across existing narrow-body fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asia and India's aerospace manufacturing corridors are concentrating lavatory system procurement and MRO capacity. Vietnam's Chu Lai and India's Bangalore Aerospace SEZ anchor regional supply chain investments. Regulatory harmonization pressures across FAA and EASA jurisdictions are reshaping where certification testing occurs.
United States
FAA airworthiness directives phasing out chemical toilet systems are forcing narrow-body retrofit programs at major carriers. The FAA's updated flammability testing protocols under FAR 25.853 are extending product approval timelines. Wichita, Kansas and Seattle-Tacoma aerospace clusters host vacuum system integration facilities serving Boeing production lines and aftermarket retrofit networks.
India
Low-cost carriers expanding domestic and regional narrow-body fleets are driving line-fit procurement of compact, sub-35 kilogram lavatory modules. The country's Production Linked Incentive scheme for aerospace components is attracting foreign system integrators to establish local assembly. Bangalore's aerospace SEZ and Hyderabad's aviation manufacturing cluster are emerging as procurement hubs for bundled cabin interior packages.
Vietnam
Emerging low-cost carrier capacity expansion is generating untapped demand for retrofit-ready lavatory systems compatible with leased narrow-body configurations. The country's national aviation regulator is aligning certification requirements with EASA CS-25 frameworks to accelerate fleet modernization. Chu Lai Open Economic Zone is concentrating MRO infrastructure investments serving Southeast Asian carrier networks.
Japan
JAMCO Corporation's domestic manufacturing base anchors vacuum system pump and valve assembly production for regional carrier supply. METI's aerospace industry competitiveness programs are supporting lightweight materials R&D for next-generation cabin systems. Nagoya's aerospace manufacturing corridor concentrates precision component fabrication for integrated lavatory module exports.
Germany
Diehl Stiftung's specialized lavatory module manufacturing for Airbus platforms sustains European supply chain positioning. EASA CS-25 amendments on electromagnetic compatibility are compelling control module redesigns for European retrofit programs. Hamburg's aircraft completion centers and Bavaria's aerospace supplier networks are embedding lifecycle carbon metrics into procurement specifications under CSRD disclosure requirements.
Aerospace Lavatory System Market Competitive Environment
Top-tier vendors anchor integrated cabin system portfolios, while mid-tier specialists concentrate on modular component manufacturing. The vendor base stratifies between full-system integrators and niche subsystem suppliers. Three archetypes dominate: European aerospace conglomerates with platform-specific approvals, Japanese precision manufacturers with regional carrier relationships, and diversified industrial groups leveraging cross-divisional aerospace expertise. Competitive moves center on strategic partnerships for bundled cabin packages and vertical integration into vacuum pump and valve assembly production.
Within the integrated systems tier, Safran and Diehl Stiftung & Co. KG exemplify European platform-anchored positioning, while JAMCO Corporation represents the Japanese precision manufacturing archetype with concentrated regional carrier supply relationships. These three entities occupy positions spanning full lavatory module integration, specialized vacuum system design, and OEM-aligned certification maintenance. Their collective presence illustrates how geographic proximity to final assembly lines and regulatory approval maintenance shape sustainable competitive positioning in aerospace cabin systems procurement.
| Leading Market Players |
|---|
| JAMCO Corporation |
| Safran |
| Collins Aerospace |
| Diehl Stiftung & Co. KG |
| RTX |
| Geven |
| THE YOKOHAMA RUBBER CO., LTD. |
| CIRCOR Aerospace |
| FACC AG |
| Others |
Value Chain & Pricing Dynamics
EASA CS-25 flammability amendments and CSRD sustainability disclosure mandates gate both qualified supply and premium-tier pricing access, as manufacturers must absorb dual-approval testing overhead and verified environmental product declaration costs to serve European airline procurement committees. Vacuum system suppliers with pre-certified module architectures command pricing premiums against spot-market component vendors lacking platform approvals.
Pricing Analysis
Lead-time-driven pricing stratification rewards suppliers with FAA-EASA dual certification and penalizes spot-market entrants facing extended approval timelines. Three-tier pricing structure across premium-certified, standard-compliant, and economy-modular levels separates OEM line-fit contracts from MRO retrofit bundles and leased-aircraft quick-turn installations. Cost compression in standard-grade vacuum pump assemblies is intensifying because titanium and composite input volatility has compressed margins for long-term supply agreement holders. Low-cost carriers in India and Vietnam exhibit the highest price sensitivity, while business jet completion centers in Switzerland and the United States demonstrate minimal elasticity for bespoke odor-control and aesthetic integration packages.
Supply Chain Analysis
Titanium billet and aerospace-grade polymer feedstock supply rests on Japanese specialty metal producers and German chemical compounders serving cabin interior certification requirements. Vacuum pump and valve assembly production concentrates in Japan, precision-machined structural enclosures originate from German and Italian aerospace clusters, and final module integration occurs at Airbus-adjacent facilities in France and Germany. Single-source vulnerability around Japanese pump suppliers exposes procurement chains to geographic disruption risk from seismic or logistics events. Distribution runs through OEM line-fit contracts for narrow-body production, MRO network stocking agreements for retrofit cycles, and airline direct procurement for emergency replacement scenarios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace lavatory system sector sits in a technology-transition phase as smart toilet architectures with sensor-based predictive maintenance displace legacy vacuum systems lacking IoT connectivity and crew workload reduction features.
For Market Incumbents: Extend platform-specific certification maintenance to lock out emerging competitors lacking dual FAA-EASA approval histories, while deepening backward integration into vacuum pump production to offset Japanese supplier concentration risk. Sensor-integrated smart toilet R&D represents the critical defensive lever against modular-additive specialists threatening MRO aftermarket share. For New Entrants and Emerging Players: MRO network partnerships with Southeast Asian carriers operating high-utilization narrow-body fleets offer the most penetrable channel for retrofit-ready lavatory modules compatible with leased aircraft configurations. Vietnam's emerging low-cost carrier expansion and India's Production Linked Incentive scheme for aerospace components present dual white-space targets, with volume-based customization concessions as the primary go-to-market angle. For Investors and Strategic Acquirers: EASA electromagnetic compatibility amendment implementation delays are the leading indicator that certification backlog will concentrate margin pools among incumbent dual-approval holders. The five-to-ten-year viability window favors acquisition of mid-tier modular specialists with existing vacuum system integration expertise and established airline relationships, with FAA-EASA harmonization gap closure as the specific signal to monitor for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FAA-EASA parallel approval maintenance locks platform access against emerging competitors lacking testing infrastructure. |
| Sensor Integration Partnership | IoT connectivity alliances with airline ground operations software vendors accelerate predictive maintenance deployment. |
| Modular-Additive Manufacturing Scale-Up | 3D-printed polymer bracket production reduces spare parts inventory carrying costs for MRO networks. |
| Sustainability Disclosure Alignment | Verified environmental product declarations capture European airline procurement under CSRD mandate implementation. |
| Regional Assembly Localization | India PLI scheme and Vietnam SEZ investments position suppliers for tariff-advantaged narrow-body line-fit contracts. |
Study Parameters
SEC 10-K filings, EASA certification databases, and airline fleet modernization disclosures formed the secondary backbone, cross-referenced against primary interviews with cabin systems procurement directors, MRO operations managers, and aerospace materials engineers. Bottom-up triangulation aggregated unit placement data across narrow-body, wide-body, and regional jet platforms, while top-down validation referenced OEM production schedules and carrier retrofit announcement timelines.
Historical trendline analysis of vacuum system retrofit cycles and line-fit penetration rates established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, installation configuration, technology tier, and regional regulatory cluster. CAGRs derived from slope-adjusted curve fitting incorporated fleet age profiles, airworthiness directive phase-out schedules, and low-cost carrier capacity expansion announcements as industry-specific forecast inputs.
Caveats apply where FAA-EASA harmonization delays, titanium price volatility, or geopolitical disruption of Japanese pump supply could materially shift the outlook. Forecasts reflect documented assumptions regarding certification timeline normalization and airline ESG commitment durability. A small set of named triggers—electromagnetic compatibility amendment implementation, CSRD disclosure mandate enforcement, and Indian PLI scheme expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Curtains Market