
 Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market | 2026-2036
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market Outlook
OEM-direct procurement channels for line-fit IFE hardware is narrowing as Chinese airframers and Southeast Asian low-cost carriers consolidate vendor lists around fewer certified integrators. Panasonic Avionics Corporation anchors wide-body programs across Japan and Australia with embedded seatback architectures. Thales Group competes aggressively on wireless streaming retrofit contracts for Airbus A320 and Boeing 737 fleets operated by Indian and Vietnamese carriers. Burrana leverages its lightweight portable media player line to capture budget airline business where minimal downtime installation matters.
Asia-Pacific commercial aircraft in-flight entertainment systems encompass seatback displays, overhead monitors, audio distribution networks, wireless access points, and passenger control units that deliver video, audio, gaming, and connectivity services during flight. These systems typically operate on aircraft-specific ARINC 429 or Ethernet-based avionics buses, with seatback units weighing between 1.2 kg and 2.5 kg depending on display size and processing integration. Wireless IFE architectures are displacing heavy embedded systems across short-haul fleets, creating margin compression in hardware while software and content licensing pools expand. Embedded Systems still dominate premium long-haul configurations where revenue differentiation through first and business class cabins drives specification. Content Delivery Network components face supply fragmentation as airlines source server hardware separately from software platforms.
Japan's METI enforces electrical safety and electromagnetic compatibility standards that shape IFE hardware certification timelines for suppliers targeting Japanese carriers. China's CAAC and India's DGCA both mandate passenger safety briefing integration that influences system architecture, requiring IFE platforms to interrupt entertainment for regulatory announcements. Australia's CASA maintains stringent continued airworthiness requirements that extend aftermarket service obligations. Stakeholders must monitor how CAAC's evolving airworthiness directives for indigenous COMAC platforms redirect certification resources and alter competitive access for foreign IFE integrators.
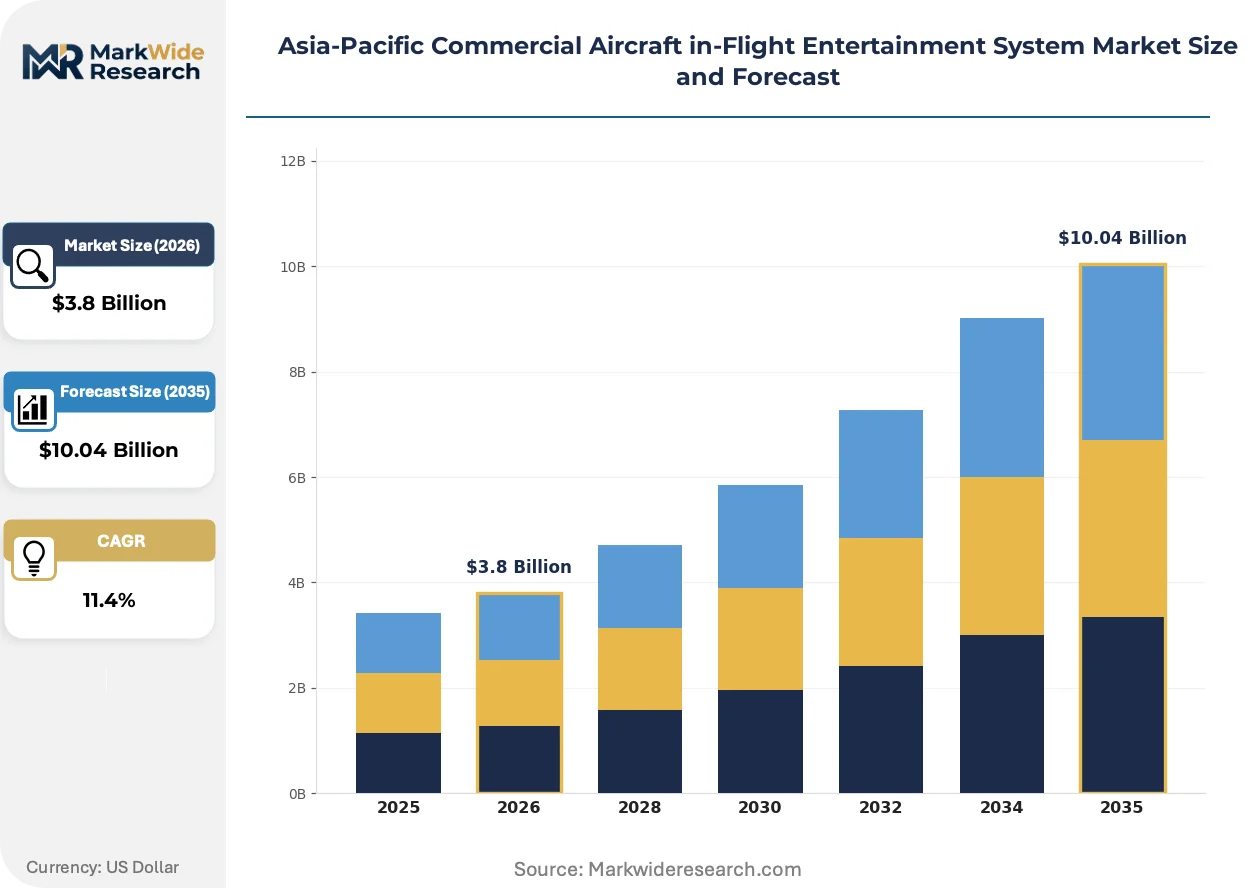
Market Dynamics
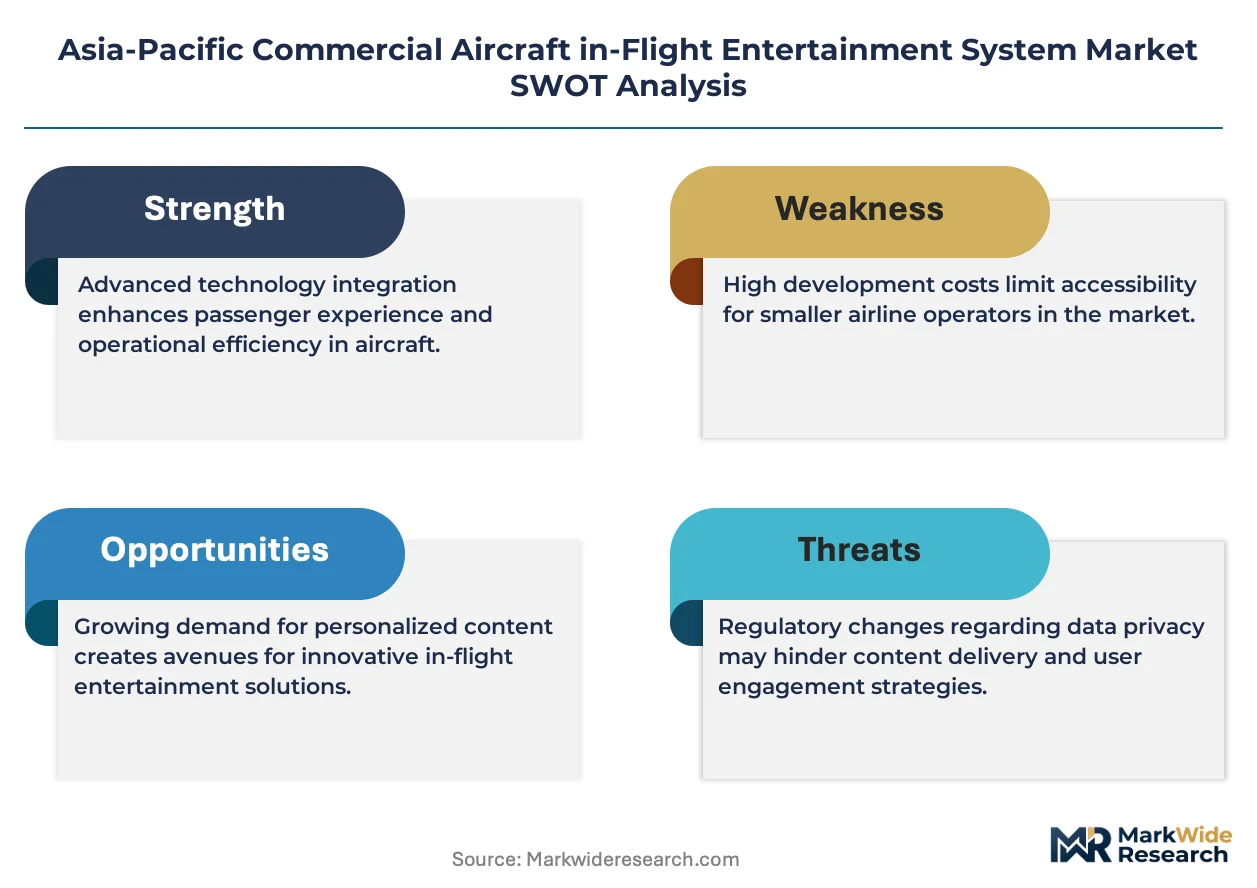
Wireless streaming architectures are compressing hardware margins while forcing embedded IFE suppliers to pivot toward software and content licensing revenue streams across Asia-Pacific airline procurement cycles.
Growth Catalysts
- India's DGCA safety mandate:Regulatory requirements for integrated passenger briefings are pulling airlines toward unified IFE platforms that bundle entertainment with mandatory communications.
- COMAC C919 fleet expansion:Indigenous narrow-body deliveries within China are creating captive retrofit demand for both embedded seatback and wireless streaming system installations.
- Fuel burn optimization:Southeast Asian full-service carriers are stripping heavy seatback hardware from narrow-body fleets to reduce unit weight and operating costs.
Market Restraints
- ARINC 429 legacy integration:Technical friction from 1970s-era avionics bus standards limits data throughput for high-definition streaming applications on older aircraft.
- Shanghai hardware concentration:Server assembly and display panel sourcing clusters within China create geographic supply vulnerability for foreign IFE integrators.
- Content licensing fragmentation:Studio rights negotiations across multiple Asia-Pacific jurisdictions inflate operating costs for wireless streaming platform operators.
Strategic Opportunities
- Vietnamese LCC retrofit wave:Budget carriers operating Airbus A320 and Boeing 737 fleets present untapped demand for lightweight portable media player rollouts with minimal downtime installation.
- Australia CASA airworthiness pathways:Stringent continued certification requirements are extending aftermarket service contracts and creating recurring revenue anchors for established suppliers.
- 5G-ATG convergence:Ground-to-air connectivity technology integration with existing wireless IFE infrastructure opens hybrid entertainment-connectivity bundling for domestic Chinese routes.
Industry Challenges
- EMC certification bottlenecks:Japan's METI electromagnetic compatibility testing timelines delay hardware approval for suppliers targeting Japanese carrier procurement windows.
- Seatback-to-server integration complexity:Airlines mixing embedded displays with bring-your-own-device streaming face cabin network architecture conflicts during phased fleet upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Embedded Systems, Portable Media Players, Streaming Services, Wireless IFE Component: Displays, Content Delivery Network, Audio Systems, Control Units End User: Commercial Airlines, Charter Services, Cargo Airlines, Private Jets Distribution Channel: OEM, Aftermarket, Direct Sales, Distributors |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Burrana, Latecoere, IMAGIK International Corp, Donica Aviation Engineering Co Ltd, Collins Aerospace, Gogo, Viasat, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market Strategic Shifts
Active reshaping of this market centers on hardware commoditization, regulatory-driven system architecture changes, and the unbundling of content delivery from proprietary hardware stacks.
Lightweight wireless access point technology operating on 802.11ac and 802.11ax standards is rendering obsolete traditional Ethernet-cabled seatback architectures across short-haul fleets. Southeast Asian low-cost carriers are adopting these platforms within 18-month retrofit cycles. The shift compresses capital expenditure per seat while expanding software and content licensing revenue pools for surviving hardware vendors.
China's CAAC airworthiness directives for indigenous COMAC platforms are redirecting certification resources toward domestic integration standards. Foreign IFE suppliers face extended approval timelines and altered competitive access for line-fit opportunities on C919 deliveries. System architects must now design dual-certification pathways for CAAC and traditional FAA-EASA frameworks.
Airlines are unbundling server hardware procurement from software platform licensing, fragmenting vendor relationships that previously ran through single-source integrators. Indian and Vietnamese carriers now source media servers separately from content delivery software, compressing margins for full-stack suppliers. This disintermediation is most visible in retrofit contracts for narrow-body fleets where installation speed outweighs brand loyalty.
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market Segmentation
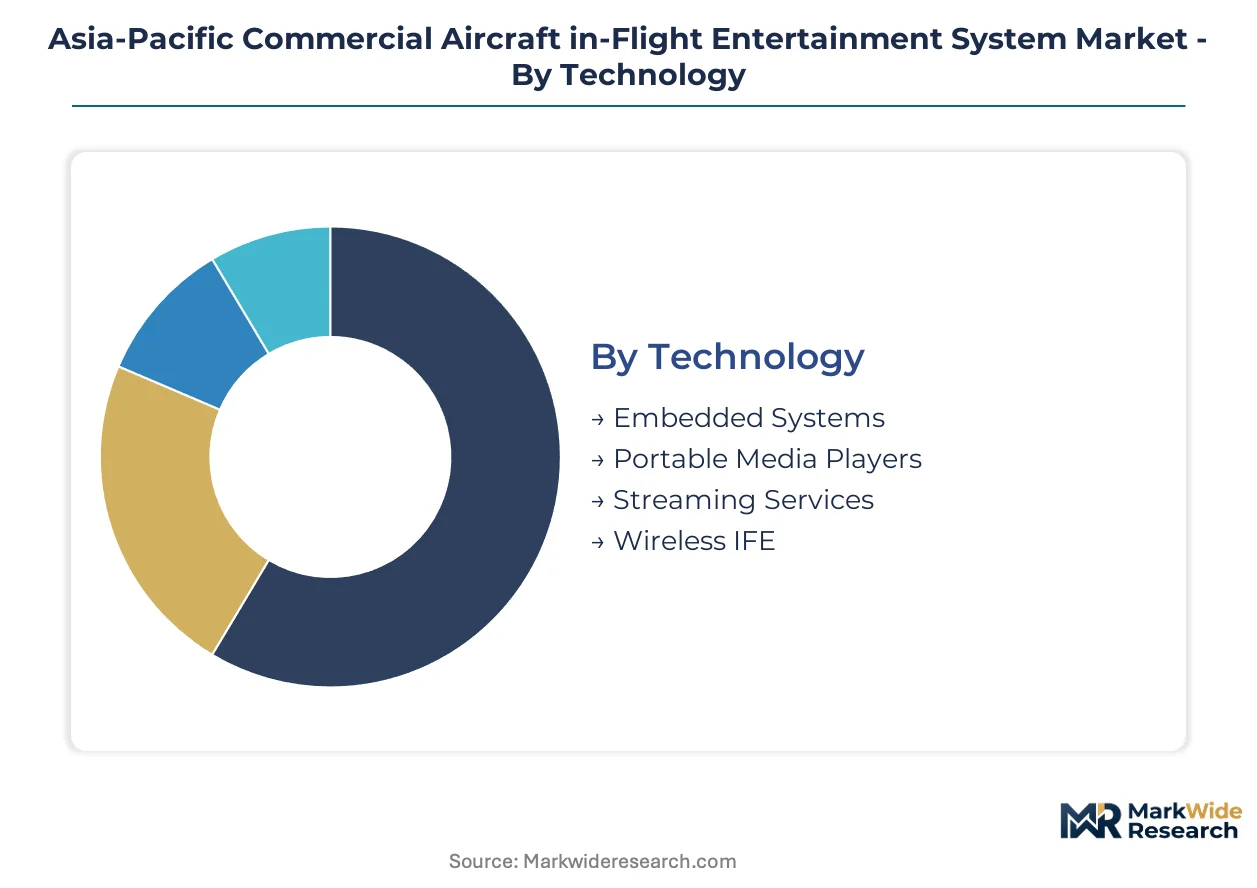
IFE procurement patterns across Asia-Pacific diverge sharply by fleet type and operational model. Wireless architectures dominate narrow-body retrofits while embedded systems retain lock-in on wide-body premium cabins. Understanding these segment boundaries clarifies where hardware margins compress versus where software and content licensing pools expand.
Technology:
Use-case spectrum spans heavy seatback installations through zero-hardware streaming platforms, with weight and installation downtime driving airline selection.
- Embedded Systems:Seatback displays with integrated processing units operate on ARINC 429 or Ethernet avionics buses, weighing 1.2 kg to 2.5 kg per unit. Demand concentrates in Japan and Australia wide-body fleets where first-class revenue differentiation mandates premium hardware. CAAC certification timelines for COMAC C919 line-fit opportunities are redirecting foreign supplier resources toward dual-approval pathways.
- Wireless IFE:802.11ac and 802.11ax access point architectures eliminate seatback hardware entirely. Southeast Asian low-cost carriers in Vietnam and Indonesia are adopting these platforms within compressed 18-month retrofit cycles to strip weight and fuel burn from Airbus A320 and Boeing 737 fleets.
- Portable Media Players:Lightweight battery-powered units with preloaded content serve budget airlines where minimal downtime installation matters.
- Streaming Services:Software-only platforms delivering content to passenger devices without dedicated cabin hardware.
Established volume favors Embedded Systems; emerging adoption favors Wireless IFE.
Component:
Cost tier separation runs from commoditized display panels through proprietary content delivery software stacks.
- Displays:LCD and OLED seatback panels range from 9-inch economy units to 32-inch first-class configurations. Sourcing clusters in Shanghai create geographic concentration risk for foreign integrators serving Chinese carrier retrofit programs.
- Content Delivery Network:Server hardware and software platforms that manage media storage, compression, and distribution to passenger endpoints. Indian and Vietnamese carriers are unbundling this procurement from full-stack integrator contracts, fragmenting vendor relationships and compressing margins for incumbent suppliers.
- Audio Systems:Seatback jack networks and wireless headphone pairing infrastructure.
- Control Units:Passenger interface devices for content navigation and cabin service requests.
Hardware procurement concentrates in Displays; margin expansion concentrates in Content Delivery Network licensing.
End User:
Customer type determines installation urgency, with scheduled retrofits competing against opportunistic maintenance windows.
- Commercial Airlines:Full-service and low-cost carriers operating scheduled passenger services across domestic and international routes. China's expanding COMAC C919 fleet and India's DGCA safety briefing mandates are pulling these operators toward integrated IFE platforms that bundle entertainment with mandatory passenger communications.
- Charter Services:On-demand operators requiring rapid reconfiguration capabilities for varying passenger profiles.
- Cargo Airlines:Freighter operators with minimal passenger IFE requirements beyond supernumerary seating.
- Private Jets:Business aviation operators prioritizing customization and premium content curation.
Volume scale favors Commercial Airlines; customization premiums favor Private Jets.
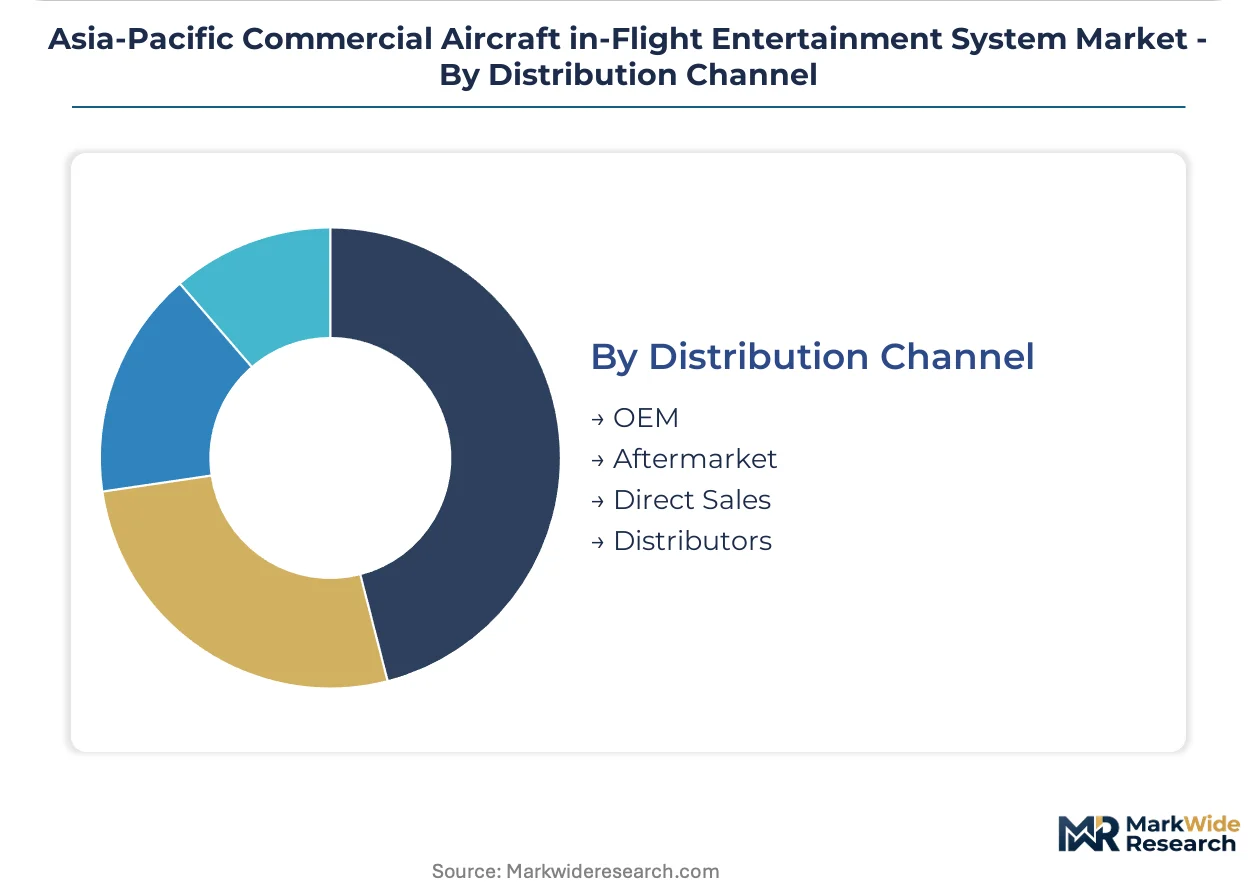
Distribution Channel:
Supply concentration shapes access patterns, with OEM line-fit narrowing toward certified integrators while aftermarket fragments across multiple procurement paths.
- OEM:Line-fit installations during airframe assembly. Chinese airframers and Southeast Asian low-cost carriers are consolidating vendor lists around fewer certified integrators, compressing competitive access for second-tier suppliers.
- Aftermarket:Retrofit and replacement installations during scheduled maintenance events. Australia's CASA stringent continued airworthiness requirements are extending service contract durations and creating recurring revenue anchors for established suppliers.
- Direct Sales:Airline procurement teams sourcing components without intermediary distributors.
- Distributors:Third-party logistics and integration service providers bridging hardware manufacturers with carrier maintenance operations.
Contract duration favors Aftermarket; margin capture favors Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japan and Australia runs substantially ahead of Southeast Asian markets, where procurement compression and rapid fleet turnover erode supplier margins. Carrier consolidation across the region is redirecting contract flows toward integrators with dual-certification capacity for both Western and Chinese airworthiness frameworks.
China
COMAC C919 deliveries are generating captive line-fit demand for embedded and wireless architectures across domestic narrow-body fleets. CAAC airworthiness directives for indigenous platforms are extending certification timelines for foreign suppliers while privileging integrators with established domestic approval pathways. Shanghai's display panel and server assembly clusters concentrate hardware sourcing, creating geographic lock-in for retrofit programs serving Chinese carriers.
Japan
Japan Airlines and ANA wide-body procurement sustains premium embedded seatback specifications for first and business class cabins. METI electromagnetic compatibility standards enforce extended hardware testing protocols that delay vendor qualification for new market entrants. Tokyo-Osaka industrial corridors host avionics integration facilities serving both domestic carriers and regional export programs.
India
DGCA mandates for integrated passenger safety briefings are pulling IndiGo, Air India, and Vistara toward unified IFE platforms that bundle regulatory communications with entertainment. Low-cost carrier dominance creates procurement pressure favoring lightweight wireless retrofits with compressed installation windows. Bengaluru and Hyderabad maintenance hubs are emerging as regional centers for narrow-body IFE overhaul cycles.
Australia
Qantas and Virgin Australia long-haul fleets sustain embedded system demand for premium cabin differentiation on transpacific routes. CASA continued airworthiness requirements extend aftermarket service obligations and anchor recurring revenue streams for established maintenance providers. Sydney and Melbourne technical bases concentrate heavy maintenance capacity that shapes retrofit scheduling for Asia-Pacific operator networks.
Vietnam
VietJet and Bamboo Airways rapid fleet expansion is driving 18-month wireless retrofit cycles across Airbus A320 and Boeing 737 narrow-body operations. Budget carrier procurement prioritizes minimal-downtime portable media player installations over heavy seatback architectures. Ho Chi Minh City and Hanoi maintenance infrastructure is scaling to accommodate compressed turnaround requirements for high-utilization low-cost operations.
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in displays, servers, and connectivity modules. The vendor structure concentrates around three to four full-stack suppliers with airworthiness certification across multiple regulatory domains, while second-tier hardware fabricators compete on price for discrete subassembly contracts. Strategic archetypes separate legacy avionics conglomerates, connectivity-focused technology entrants, and lightweight hardware specialists serving budget carrier retrofit cycles. Competitive moves center on dual-certification investments for Chinese market access and aftermarket service contract extensions to offset hardware margin compression.
Among the integrated platform tier, Panasonic Avionics Corporation and Thales Group exemplify full-stack suppliers with established certification breadth across FAA-EASA-CAAC frameworks. Burrana occupies a position within the lightweight hardware specialist archetype, representing vendors targeting rapid-install retrofit opportunities in Southeast Asian low-cost carrier procurement cycles. These three entities anchor the competitive structure, with their respective strategic postures reflecting divergent bets on embedded versus wireless architecture dominance across regional fleet renewal programs.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Burrana |
| Latecoere |
| IMAGIK International Corp |
| Donica Aviation Engineering Co Ltd |
| Collins Aerospace |
| Gogo |
| Viasat |
| Others |
Value Chain & Pricing Dynamics
Shanghai hardware concentration creates single-source vulnerability that compresses margin spreads between premium embedded seatback systems and commoditized wireless streaming platforms while simultaneously tethering foreign integrators to Chinese display panel and server assembly clusters. This geographic lock-in forces pricing stratification across CAAC-certified domestic suppliers versus FAA-EASA pathway vendors, with retrofit procurement further fragmenting as Indian and Vietnamese carriers unbundle server hardware from software licensing.
Pricing Analysis
Configured-to-order pricing for first-class embedded architectures commands substantial premiums over standard wireless streaming deployments across Asia-Pacific narrow-body retrofits. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CAAC dual-approval pathways adding cost layers for foreign suppliers. Pricing pressure stems from hardware commoditization as 802.11ax access points displace heavy seatback units, compressing capital expenditure per seat. Low-cost carriers in Vietnam and Indonesia exhibit highest price sensitivity, while Japan's full-service carriers maintain lowest sensitivity due to METI compliance premiums and cabin revenue differentiation mandates.
Supply Chain Analysis
Export-control regimes limiting avionics-grade processor and encryption technology flows constrain foreign IFE integrator access to Chinese COMAC line-fit opportunities. Hardware sourcing draws from China for LCD and OLED display panels, Japan for avionics-grade processing units, and Taiwan for wireless chipset fabrication. Raw material dependencies include rare-earth elements for display phosphors, copper for Ethernet cabling infrastructure, and lithium for portable media player batteries. Single-source vulnerability concentrates in Shanghai server assembly clusters, creating tariff exposure and logistics chokepoints for retrofit programs. Distribution runs through OEM line-fit channels narrowing toward certified integrators, alongside fragmented aftermarket procurement via airline direct sales and third-party maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IFE market fragmentation creates white-space opportunities as regulatory-driven system unbundling splinters previously integrated procurement relationships across Asia-Pacific carrier archetypes. Wireless streaming adoption, COMAC certification divergence, and content licensing disintermediation together generate niche entry points for specialized vendors.
For Market Incumbents: Harden aftermarket service contract positions through CASA airworthiness pathway investments in Australia, extending recurring revenue anchors as hardware margins compress. Pursue backward integration into Shanghai display panel sourcing to mitigate geographic concentration risk. Deepen CAAC certification resources to defend line-fit access on indigenous Chinese narrow-body deliveries against domestic integrator competition. For New Entrants and Emerging Players: Pursue Vietnamese low-cost carrier retrofit cycles where 18-month installation windows and minimal-downtime requirements favor lightweight portable media player specialists. Target India's DGCA-mandated safety briefing integration as a penetrable entry point where unified platform demand outstrips incumbent capacity. Position through Bengaluru and Hyderabad maintenance hub partnerships as a rapid-deployment go-to-market angle. For Investors and Strategic Acquirers: CAAC's evolving airworthiness directives for COMAC platforms reshapes the acquisition landscape by privileging integrators with established dual-certification capacity across FAA-EASA and Chinese frameworks. Long-term viability centers on software and content licensing revenue pools expanding as hardware commoditizes. Acquisition target archetype: lightweight hardware specialists with Southeast Asian low-cost carrier relationships and rapid-install IP. Signal to watch: CAAC approval timeline acceleration for foreign suppliers as C919 fleet expansion outpaces domestic integration capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | CAAC-FAA-EASA pathway expansion unlocks COMAC C919 line-fit opportunities for foreign integrators. |
| Wireless Platform Migration | 802.11ax retrofit rollouts capture Southeast Asian low-cost carrier demand for weight-stripped narrow-body fleets. |
| Aftermarket Service Extension | CASA airworthiness contract anchoring generates recurring revenue streams offsetting hardware margin compression. |
| Content Licensing Unbundling | Separate software platform procurement from server hardware fragments vendor relationships and creates SaaS revenue pools. |
| Maintenance Hub Partnership | Bengaluru and Hyderabad technical base alliances accelerate Indian narrow-body retrofit deployment cycles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline procurement directors, IFE platform engineering leads, avionics certification specialists, and maintenance hub operations managers. Secondary validation drew from CAAC airworthiness directive filings, DGCA safety mandate documentation, CASA continued airworthiness requirements, customs trade data for avionics components, and OEM delivery schedules. Bottom-up fleet retrofit demand modeling and top-down market sizing triangulation anchored volume and value estimates.
Calibration against historical installation cycles and announced fleet renewal programs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, component tier, end-user operational model, and distribution channel concentration, with additional weighting for regulatory compliance pathway requirements. CAGRs derived from fitted growth curves applied to disclosed retrofit timelines and line-fit delivery schedules, incorporating fuel burn optimization sensitivity and wireless adoption rate assumptions as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in aviation fuel costs, air travel demand recovery trajectories, or cross-border technology transfer restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding CAAC certification timeline evolution and COMAC production ramp schedules. Material shifts in export-control regime stringency or indigenous Chinese IFE supplier capability maturation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market