
 Asia-Pacific Breakfast Cereals Market | 2026-2036
Asia-Pacific Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Breakfast Cereals Market Outlook
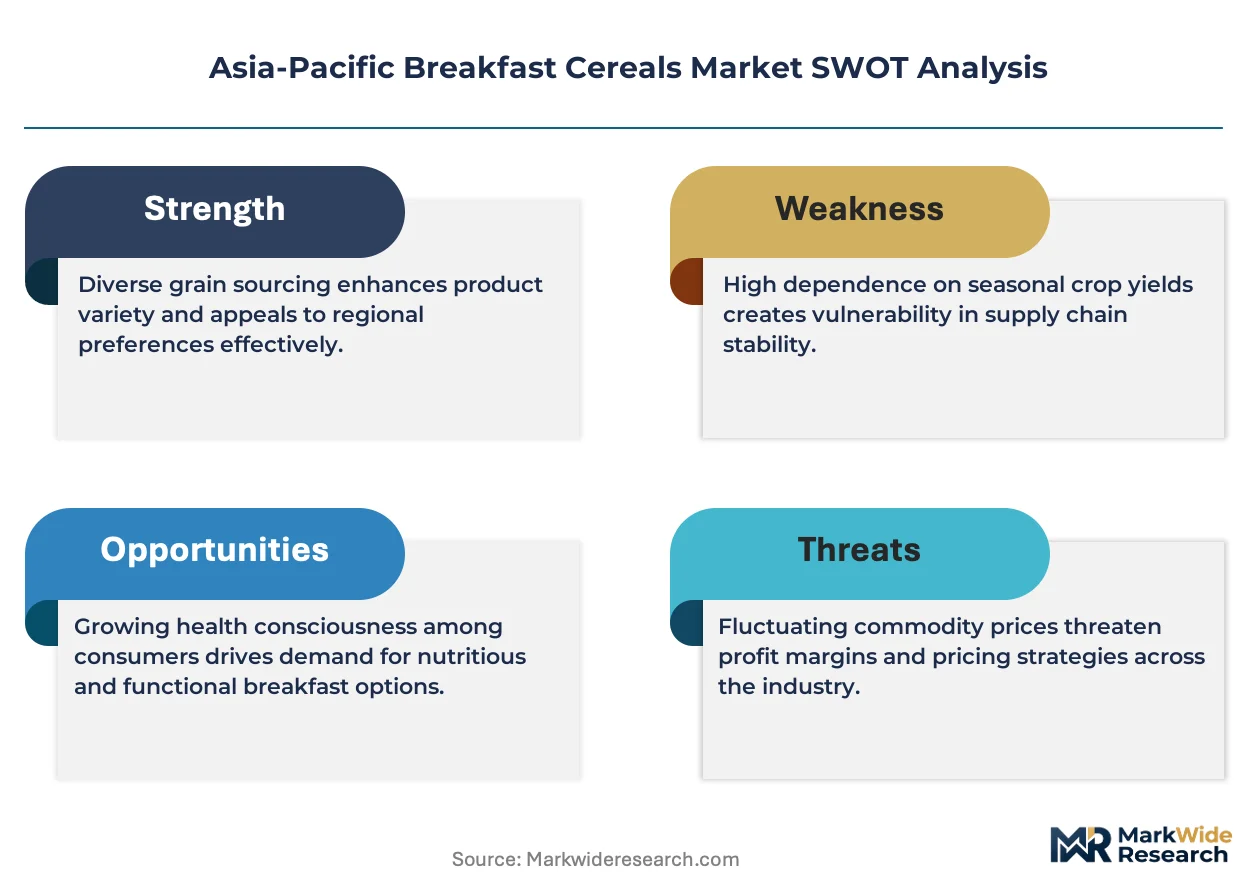
Multi-source grain procurement is recalibrating how Asia-Pacific cereal manufacturers secure wheat, rice, and oat supplies. Nestlé S.A. leverages its regional milling partnerships to secure consistent raw material flows across Southeast Asian plants. The Kellogg Company anchors its competitive stance through dedicated R&D facilities in India that tailor flavor profiles to local palates. Marico Limited differentiates via backward integration into indigenous grain sourcing networks that reduce import dependency.
Asia-Pacific breakfast cereals comprise processed grain formulations—typically extruded, flaked, or puffed—delivering between 100 and 150 kilocalories per standardized serving, designed for convenient morning consumption with milk or yogurt. Cold cereals dominate volume throughput in Australia and Japan due to established refrigeration infrastructure and dairy pairing traditions, while hot cereals capture expanding share in northern China and South Korea where warm breakfast customs persist. Single-serve packaging formats are attracting margin concentration as convenience stores and online retail channels expand across Indonesian and Vietnamese urban corridors.
FSSAI fortification standards in India, Australia's Health Star Rating scheme, and Japan's Ministry of Health labelling requirements collectively elevate reformulation costs while creating compliance barriers for new entrants. These frameworks push manufacturers toward cleaner-label claims and micronutrient-enhanced portfolios that align with pediatric and geriatric nutritional targets. Stakeholders must track evolving front-of-pack regulations across ASEAN member states where harmonization remains fragmented and enforcement timelines vary by jurisdiction.
Market Dynamics
Urbanization in Mumbai, Seoul, and Sydney is compressing morning preparation time and redirecting household food budgets toward shelf-stable, ready-to-eat formats that require minimal cooking infrastructure.
Growth Catalysts
- FSSAI Fortification Mandates:India's mandatory micronutrient enrichment standards for packaged foods are expanding addressable demand among pediatric and maternal health segments.
- Modern Retail Infrastructure:Organized supermarket and e-commerce penetration across Indonesian and Vietnamese urban corridors is pulling packaged breakfast categories into previously fragmented traditional trade territories.
- Extrusion Technology Advancement:Continuous extrusion process improvements are reducing energy input per kilogram of finished cereal while enabling texture diversification for regional palate adaptation.
Market Restraints
- Wheat Import Dependency:Southeast Asian manufacturing clusters rely on Australian and Black Sea wheat supplies, exposing margin structures to freight rate volatility and currency fluctuation.
- Cold Chain Limitations:Inadequate refrigerated distribution infrastructure across tier-two Indian cities and rural Philippines restricts cold cereal penetration and forces formulation toward ambient-stable alternatives.
- Japan's Ministry of Health Labelling:Nutrient content claim restrictions and front-of-pack disclosure requirements elevate compliance costs for new market entrants without established regulatory affairs capabilities.
Strategic Opportunities
- Northern China Hot Cereal Expansion:Warm breakfast customs in Beijing and Harbin present white space for instant oatmeal and congee-adjacent formulations with localized flavor profiles.
- Australia's Health Star Rating:Voluntary participation incentives are creating competitive differentiation for manufacturers that reformulate toward higher-scoring recipes before mandatory adoption timelines.
- Single-Serve Convenience Channel:Grab-and-go 30-gram sachets distributed through convenience stores and quick-commerce platforms are capturing premium pricing from time-constrained urban professionals.
Industry Challenges
- Grain Procurement Expertise Gap:Indigenous rice and millet sourcing networks require specialized agricultural extension capabilities that multinational manufacturers lack without local partnership structures.
- Dual Certification Timelines:Simultaneous FSSAI registration and state-level food safety licenses in India extend product launch cycles by four to six months versus comparable packaged food categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Breakfast Cereals Market |
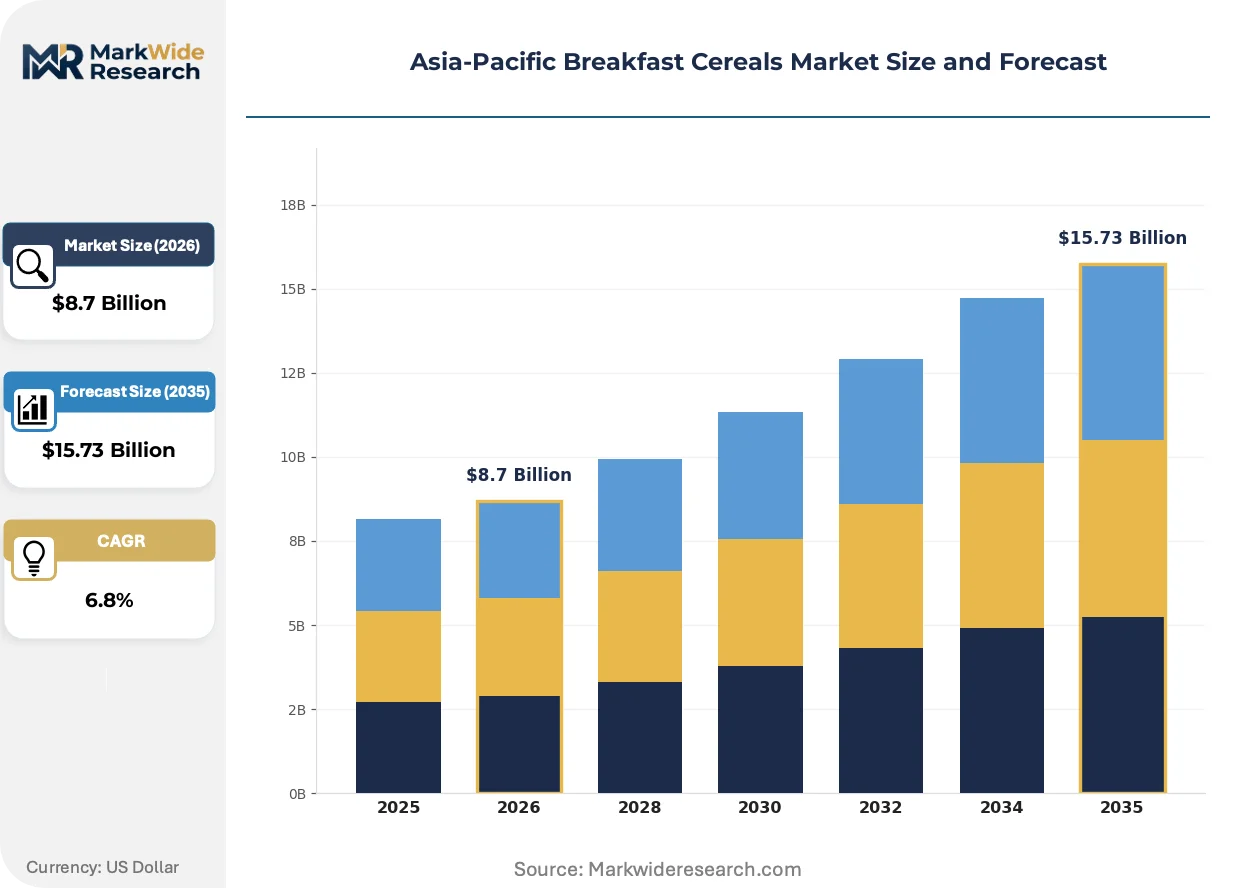
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cereals, Cold Cereals, Granola, Muesli Consumer Type: Adults, Children, Health-Conscious Consumers, Busy Professionals Packaging Type: Box, Bag, Bulk, Single Serve Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | General Mills, Inc., Nestlé S.A., The Kellogg Company, PepsiCo, Inc., Post Holdings, Inc., Marico Limited, Bagrry's India Limited, Tata Group, MTR Foods, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Breakfast Cereals Market Strategic Shifts
Reformulation priorities are converging around clean-label positioning, micronutrient density, and packaging formats that accommodate both refrigeration-dependent and ambient distribution channels.
Extrusion equipment with interchangeable die configurations is modularizing production lines across Thailand and Malaysia, allowing contract manufacturers to switch between puffed rice, flaked wheat, and bran-fortified extrudates within single shift cycles. Food processing cooperatives in Vietnam are adopting these systems to serve multiple brand clients without dedicated capital expenditure per product line. This flexibility is compressing minimum viable batch sizes and enabling regional brands to test localized flavors without volume commitments.
Australia's Health Star Rating scheme is mandating algorithmic nutrient profiling that penalizes added sugars and sodium while rewarding protein and fiber content, forcing reformulation of legacy recipes that relied on honey glazing and salt enhancement for palatability. Breakfast cereal portfolios in Sydney and Melbourne are restructuring toward whole-grain bases with fruit inclusions to optimize scoring. Manufacturers without in-house nutrition science capabilities are outsourcing reformulation to specialized food technology consultancies.
Convenience stores and quick-commerce platforms in Jakarta and Ho Chi Minh City are displacing traditional grocery channels for initial brand trial and repurchase among nuclear households without cold storage capacity at point of consumption. Single-serve sachets and cup formats with shelf-stable UHT milk companions are capturing this demand rotation. Urban Vietnamese consumers under thirty-five are driving the behavioral shift, prioritizing immediate availability over bulk purchasing economics.
Asia-Pacific Breakfast Cereals Market Segmentation
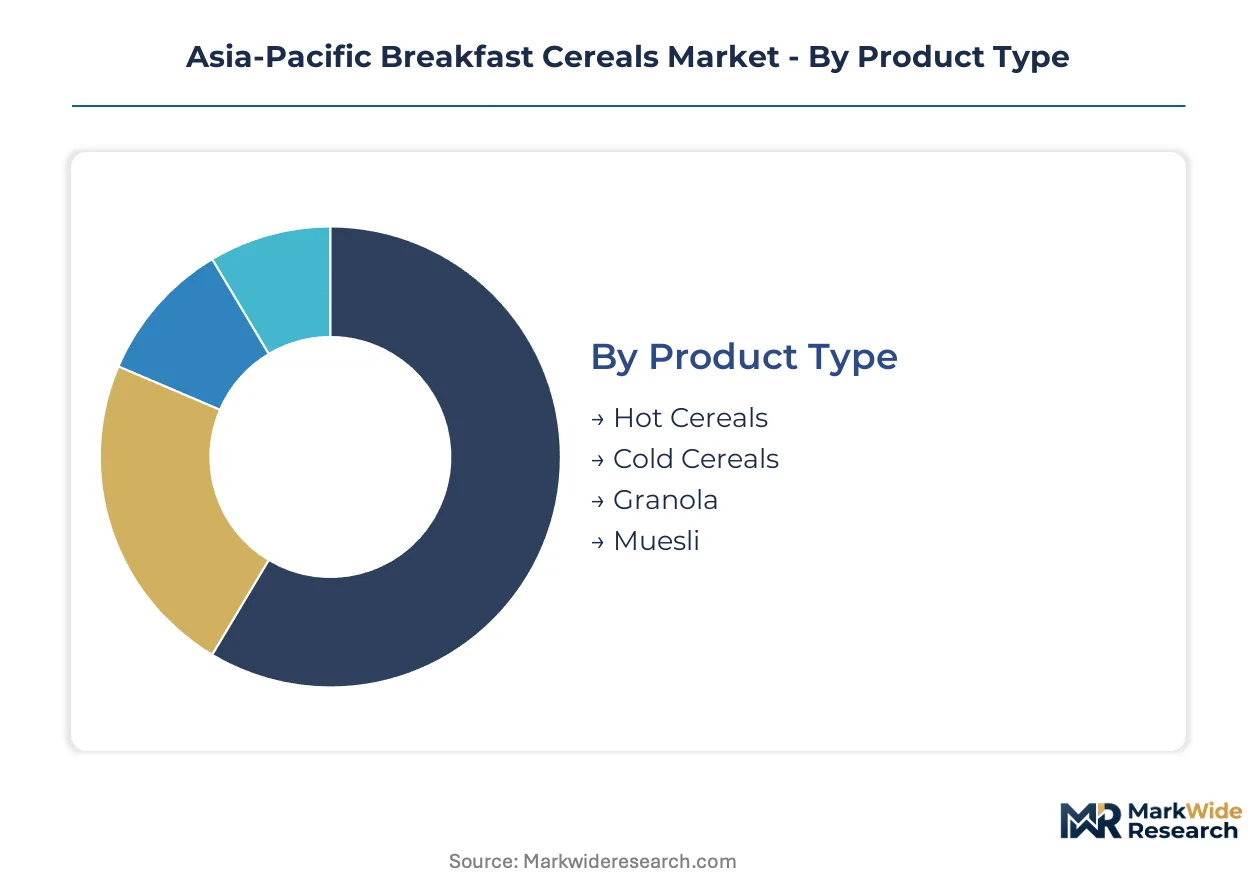
Segmentation in Asia-Pacific breakfast cereals reveals how formulation technology, consumption context, and retail infrastructure intersect to create distinct competitive arenas. Manufacturers must align product architecture with specific thermal processing requirements, household storage constraints, and channel-specific packaging formats to capture volume across this heterogeneous region.
Product Type:
Extrusion and flaking technologies define the manufacturing cost structure and distribution feasibility for each cereal format.
- Hot Cereals:Rolled or steel-cut grains requiring hot water or milk preparation, typically oatmeal and porridge bases. Demand concentrates in northern China and South Korea where warm breakfast customs persist, with instant formats capturing share among Seoul apartment dwellers lacking full cooking facilities.
- Cold Cereals:Extruded, flaked, or puffed grains designed for immediate consumption with cold dairy. Australian and Japanese households anchor volume due to established refrigeration infrastructure and dairy pairing traditions, though penetration faces constraints in tier-two Indian cities with unreliable cold chains.
- Granola:Baked clusters combining oats, sweeteners, and nuts or seeds for yogurt topping or standalone snacking. Premium positioning targets health-conscious urban professionals in Sydney and Melbourne.
- Muesli:Unbaked mixtures of rolled grains, dried fruits, and nuts requiring no processing at point of consumption. Swiss-origin heritage appeals to expatriate communities and wellness-focused consumers across Singapore and Hong Kong.
Cold cereals lead on scale through Australian and Japanese volume concentration; hot cereals lead on momentum through northern Chinese market development.
Consumer Type:
Demographic targeting determines micronutrient fortification levels, portion sizing, and flavor intensity calibration.
- Adults:Standardized serving formulations with moderate sweetness and fiber-forward positioning. Workplace breakfast consumption in Mumbai and Jakarta drives demand for portable, mess-resistant formats.
- Children:Fortified recipes with elevated iron, zinc, and B-vitamin content per FSSAI mandates in India. Cartoon licensing and high-sugar palatability requirements dominate purchase criteria among parental decision-makers.
- Health-Conscious Consumers:Low-glycemic index formulations, ancient grain inclusions, and minimal processing claims. Australia's Health Star Rating system guides reformulation priorities for this segment.
- Busy Professionals:Single-serve packaging with sub-60-second preparation requirements. Convenience store penetration in Ho Chi Minh City and Jakarta targets this cohort with grab-and-go placement.
Children's cereals lead on scale through mandatory fortification volume commitments; health-conscious formulations lead on momentum through clean-label premiumization.
Packaging Type:
Material selection and unit sizing directly determine shelf-life extension, logistics economics, and retail channel compatibility.
- Box:Paperboard primary packaging with inner liner bags for moisture protection. Dominates supermarket shelf presence across Australian and Japanese retail environments where brand visibility drives trial.
- Bag:Flexible film pouches reducing material cost and shipping cube versus rigid formats. Bulk value positioning targets multi-person households in price-sensitive Indian and Indonesian markets.
- Bulk:Institutional-scale containers for foodservice, hospitality, and commercial catering procurement. Hotel breakfast buffets in Bangkok and Kuala Lumpur represent core demand concentration.
- Single Serve:Pre-portioned sachets, cups, or bowls with ambient stability for immediate consumption. Quick-commerce platforms and convenience stores in Vietnamese urban corridors are expanding this format fastest.
Box formats lead on scale through established retail infrastructure; single-serve leads on momentum through channel shift toward immediate consumption occasions.
Distribution Channel:
Channel selection dictates pricing architecture, promotional mechanics, and cold chain requirements.
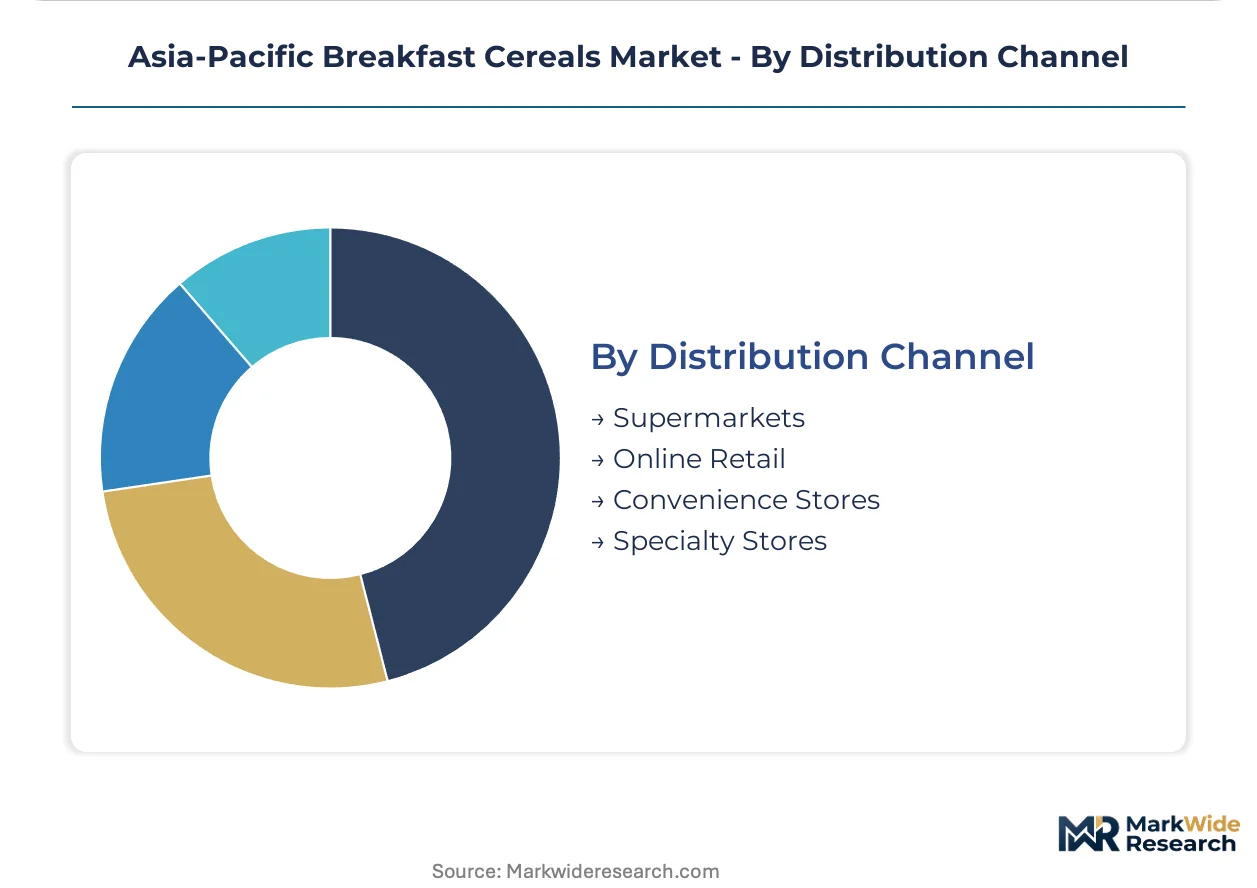
- Supermarkets:Full-category assortment with refrigerated dairy adjacency and promotional stacking. Modern retail penetration in Indonesian and Vietnamese urban corridors is pulling packaged breakfast categories from traditional trade.
- Online Retail:E-commerce platforms and quick-commerce apps offering subscription replenishment and bulk discounting. Mumbai and Seoul consumers utilize this channel for heavy, repetitive purchases avoiding transport burden.
- Convenience Stores:High-frequency, small-basket transactions with extended operating hours. Single-serve and cup formats dominate this channel in Jakarta and Ho Chi Minh City.
- Specialty Stores:Health food retailers, organic boutiques, and import-focused grocers. Premium granola and muesli variants with clean-label positioning concentrate here in Sydney and Melbourne.
Supermarkets lead on scale through category development investment; convenience stores lead on momentum through urban time-compression trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints across Asia-Pacific as manufacturers relocate extrusion and packaging operations toward jurisdictions with streamlined food safety registration timelines. FSSAI compliance costs in India and Australia's Health Star Rating implementation are creating divergent cost structures that favor multi-country manufacturing networks.
India
Nuclear family expansion and modern retail penetration in Mumbai and Delhi are accelerating organized breakfast adoption. FSSAI fortification mandates for iron, zinc, and B-vitamins are reformulating pediatric cereal portfolios. Manufacturing clusters in Maharashtra and Gujarat are scaling extrusion capacity to serve domestic demand and neighboring export markets.
China
Warm breakfast customs in Beijing and Harbin are pulling investment toward instant oatmeal and congee-adjacent hot cereal formats. SAMR labeling requirements for nutrient content claims are elevating compliance costs for imported brands. Yangtze River Delta production bases are retrofitting lines for dual hot-cold cereal flexibility.
Australia
Health Star Rating participation incentives are compressing reformulation cycles in Sydney and Melbourne manufacturing facilities. Cold cereal volume concentration reflects established refrigeration infrastructure and dairy pairing traditions. Victoria-based R&D facilities are developing whole-grain bases with optimized algorithmic scoring.
South Korea
Seoul apartment dwellers lacking full cooking facilities are driving instant hot cereal demand alongside persistent warm breakfast customs. MFDS front-of-pack disclosure requirements are accelerating clean-label portfolio restructuring. Busan-Ulsan logistics corridors are expanding ambient-stable distribution capacity for convenience store channels.
Vietnam
Ho Chi Minh City convenience stores and quick-commerce platforms are displacing traditional grocery for single-serve trial and repurchase. Food processing cooperatives adopting modular extrusion systems are serving multiple brand clients without dedicated capital expenditure. Urban consumers under thirty-five are prioritizing immediate availability over bulk purchasing economics.
Asia-Pacific Breakfast Cereals Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue indigenous grain sourcing and regional flavor localization. Market structure reflects moderate consolidation with multinational food conglomerates anchoring volume alongside domestic specialists capturing price-sensitive segments. Three archetypes dominate: backward-integrated grain processors, R&D-intensive flavor adaptors, and convenience-format specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure milling relationships and extrusion technology licensing.
Within the multinational tier, Nestlé S.A. and The Kellogg Company exemplify divergent strategic positioning. Nestlé leverages regional milling partnerships across Southeast Asian plants to secure consistent raw material flows. Kellogg anchors competitive stance through India-based R&D facilities that tailor flavor profiles to local palates. Among domestic specialists, Marico Limited occupies a position emphasizing backward integration into indigenous grain sourcing networks.
| Leading Market Players |
|---|
| General Mills, Inc. |
| Nestlé S.A. |
| The Kellogg Company |
| PepsiCo, Inc. |
| Post Holdings, Inc. |
| Marico Limited |
| Bagrry's India Limited |
| Tata Group |
| MTR Foods |
| Others |
Value Chain & Pricing Dynamics
Modular extrusion technology adoption across Thai and Malaysian contract manufacturers is compressing production batch economics while fragmenting supply concentration among mid-scale processing cooperatives. This dual effect simultaneously reduces per-unit manufacturing costs and disperses sourcing leverage across multiple regional grain milling networks.
Pricing Analysis
Distributor margin layers in Indonesian and Vietnamese convenience channels absorb 18-25 points of final shelf price, compressing manufacturer netbacks against ambient-stable formulation investments. Three-tier pricing structure across premium, standard, and economy levels separates Health Star Rating-optimized recipes from fortified economy lines and private-label alternatives. Pricing pressure stems from Black Sea wheat freight volatility exposing margin structures in Southeast Asian manufacturing clusters. Price-sensitive volume concentrates in Indian bag-format bulk purchases, while Australian single-serve premiums show lowest elasticity.
Supply Chain Analysis
Freight cost volatility from Australian and Black Sea wheat corridors is amplifying working capital requirements for Southeast Asian extrusion plants dependent on imported grain bases. Supply concentrates in India, Australia, and Thailand, with raw material flows drawing from Black Sea wheat, Australian milling oats, and indigenous Indian rice-millet networks. Single-source vulnerability sits with Australian wheat shipments through Singapore transshipment hubs. Distribution runs through modern retail chains in Mumbai and Jakarta, quick-commerce platforms in Ho Chi Minh City, and traditional trade in tier-two Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FSSAI compliance costs in India run 40% below equivalent Health Star Rating reformulation investments in Australia, creating divergent margin structures across the region.
For Market Incumbents: Deepen backward integration into Maharashtra and Gujarat grain milling networks to defend against Marico Limited's indigenous sourcing advantage. Anchor capacity expansion in Vietnam's food processing cooperatives to capture single-serve format momentum before modular extrusion systems saturate contract manufacturing availability.
For New Entrants and Emerging Players: Begin with northern China's instant hot cereal white space where warm breakfast customs meet underdeveloped branded oatmeal penetration. Target Jakarta and Ho Chi Minh City convenience channels with 30-gram sachet formats paired with UHT milk companions to bypass cold chain infrastructure gaps.
For Investors and Strategic Acquirers: Valuations sit cheapest among Vietnamese food processing cooperatives adopting modular extrusion technology without dedicated brand equity. Long-term viability hinges on regulatory arbitrage sustainability as ASEAN harmonization timelines converge. Watch FSSAI fortification mandate expansion into adjacent packaged food categories as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indigenous Grain Networks | Reduces Australian wheat import dependency for Indian manufacturers facing currency volatility. |
| Modular Extrusion Technology Licensing | Enables Thai and Malaysian contract manufacturers to serve multiple brand clients within single shifts. |
| Health Star Rating Pre-Compliance Reformulation | Positions Australian portfolios ahead of mandatory adoption timelines with algorithmic nutrient optimization. |
| Single-Serve Format Channel Expansion | Captures Jakarta and Ho Chi Minh City convenience store traffic from time-compressed urban professionals. |
| Dual Hot-Cold Cereal Production Flexibility | Allows Yangtze River Delta facilities to pivot between northern Chinese oatmeal demand and cold cereal export. |
Study Parameters
Coverage spans India, China, Australia, South Korea, Vietnam, Indonesia, and Thailand, with primary inputs from each market cluster. The research combines executive interviews with cereal brand managers, extrusion equipment suppliers, retail category buyers, and FSSAI regulatory consultants with secondary validation from customs trade records, Nielsen retail audit data, food safety registration databases, and SEC filings of listed parent companies. Bottom-up volume modeling triangulates against top-down category spend estimates.
Granularity extends to product type, consumer demographic, packaging format, and distribution channel dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories calibrated against urbanization rates, modern retail penetration curves, and regulatory implementation timelines. Forecast inputs incorporate extrusion capacity expansion announcements, Health Star Rating participation rates, and quick-commerce platform growth metrics.
Several conditions sit outside the modeled scope, including potential ASEAN regulatory harmonization acceleration, Black Sea wheat supply disruptions, and Indian cold chain infrastructure investment trajectories. Forecasts reflect documented assumptions about urban household formation patterns and nuclear family breakfast behavior shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Club Store Packs Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Hummus Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Canned Food Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Global Food Spread Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Global Aseptic Packaging in Food Market