
 GCC Biofertilizer Market | 2026-2036
GCC Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Biofertilizer Market Intelligence
Saudi Arabia's biofertilizer production capacity is reconfiguring supply dynamics across the Gulf. Emirates Bio Fertilizer Factory leverages its Abu Dhabi manufacturing base to anchor distribution networks across the Emirates. ADFERT sustains R&D intensity in specialized liquid formulations for arid-zone crops. Dhofar Organics LLC dominates Oman's southern agricultural corridor through backward integration into compost feedstock sourcing.
Biofertilizers comprise living microbial inoculants—primarily nitrogen-fixing bacteria, phosphate-solubilizing fungi, and plant growth-promoting rhizobacteria—formulated in liquid suspensions, granular carriers, or powdered peat bases with colony counts typically exceeding 10^8 CFU per gram. These preparations colonize root zones to enhance nutrient availability in saline-alkaline soils prevalent across Gulf states. Liquid biofertilizers lead current revenue pools due to ease of drip-irrigation integration in greenhouse operations, while granular formats are gaining fastest among open-field cereal producers seeking single-application efficiency. Agricultural supply stores remain the dominant distribution channel, though online sales are fragmenting procurement patterns among smaller organic farmers.
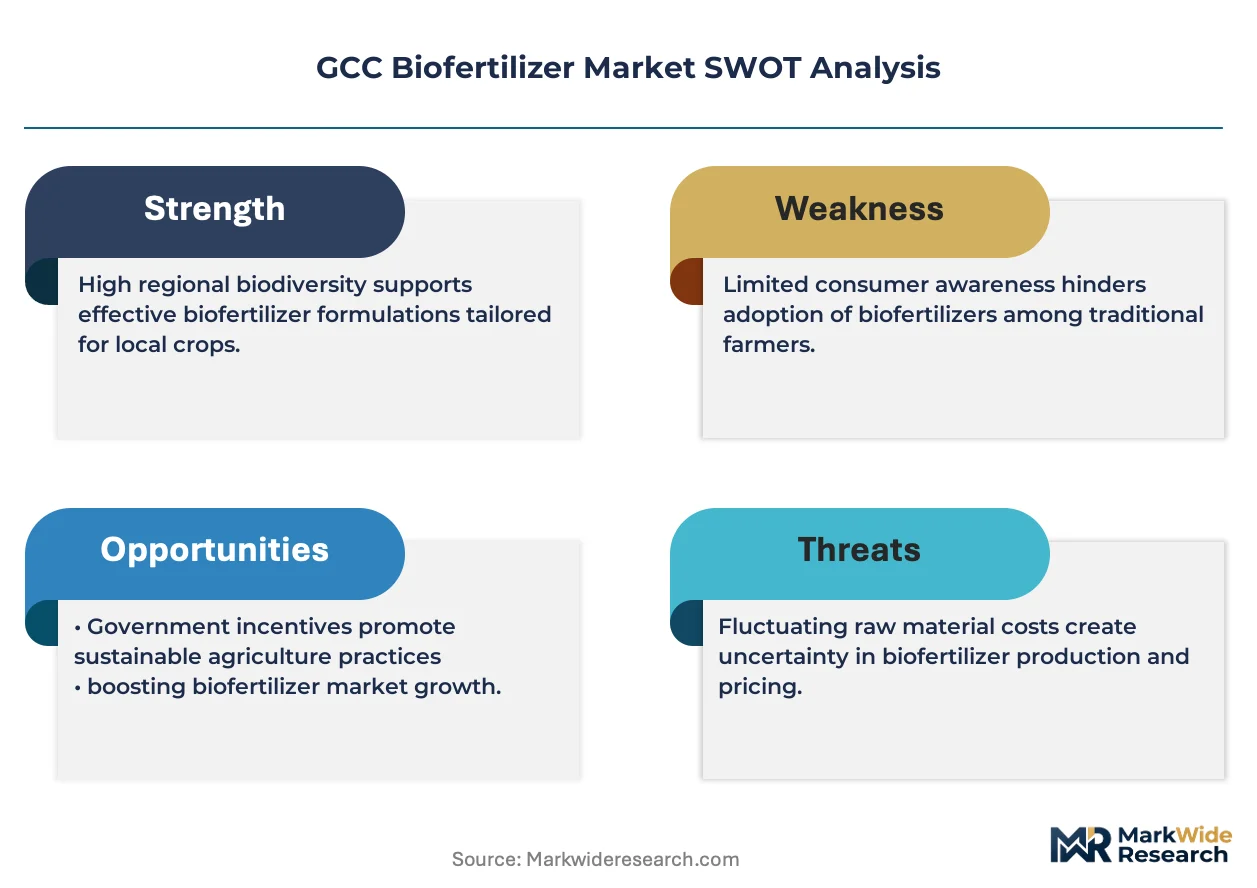
The Saudi Food and Drug Authority and UAE's Ministry of Climate Change and Environment enforce registration requirements for microbial agricultural inputs, while Oman's Ministry of Agriculture and Fisheries mandates efficacy trials before commercial approval. These frameworks elevate compliance costs for new entrants but protect established suppliers with validated strain libraries. Stakeholders must monitor strain patent expirations and evolving organic certification standards to anticipate competitive repositioning.
Market Dynamics
Saudi Arabia's sustainable agriculture mandates are redirecting procurement flows across the Gulf, as date palm growers in Al-Qassim abandon synthetic nitrogen for microbial inoculants and greenhouse operators demand liquid formulations compatible with drip-irrigation infrastructure.
Growth Catalysts
- SFDA Registration Pathways:The Saudi Food and Drug Authority's streamlined microbial input approvals are accelerating commercialization timelines for rhizobium-based products targeting arid-zone cereals.
- Greenhouse Expansion:Protected cultivation area across the Emirates is multiplying demand for phosphate-solubilizing fungi compatible with hydroponic and soilless systems.
- Water Conservation Mandates:UAE Ministry of Climate Change and Environment policies are penalizing synthetic fertilizer runoff while subsidizing microbial alternatives that reduce irrigation frequency.
Market Restraints
- Strain Viability Costs:Maintaining 10^8 CFU per gram potency through Gulf summer temperatures requires cold-chain infrastructure that elevates landed costs for granular formulations.
- Feedstock Concentration:Peat-based carrier supply depends on Baltic and North American sources, exposing formulators to shipping rate volatility and customs delays at Jebel Ali.
- Technical Shelf-Life Limitation:Liquid biofertilizers lose efficacy within 6-12 months in ambient storage, constraining inventory management for agricultural supply stores in remote Omani governorates.
Strategic Opportunities
- Underpenetrated Oman Interior:Dhofar Organics LLC's southern dominance leaves the Batinah coast and Al Dakhiliyah regions underserved for cereal-specific nitrogen-fixing inoculants.
- Organic Certification Premium:EU-equivalent organic standards adoption by UAE retailers is creating price premiums for biofertilizer-treated produce exported to European markets.
- Direct-to-Farmer Platforms:Mobile-based ordering and drone delivery networks are bypassing traditional agricultural supply store intermediaries for smaller organic operations.
Industry Challenges
- Microbiologist Talent Scarcity:Strain isolation and quality control functions require PhD-level expertise that Gulf universities currently underproduce relative to commercial demand.
- Multi-Jurisdiction Registration Burden:Separate efficacy trials mandated by Oman's Ministry of Agriculture and Fisheries, SFDA, and UAE's MOCCAE force redundant testing expenditures for regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Biofertilizer Market |
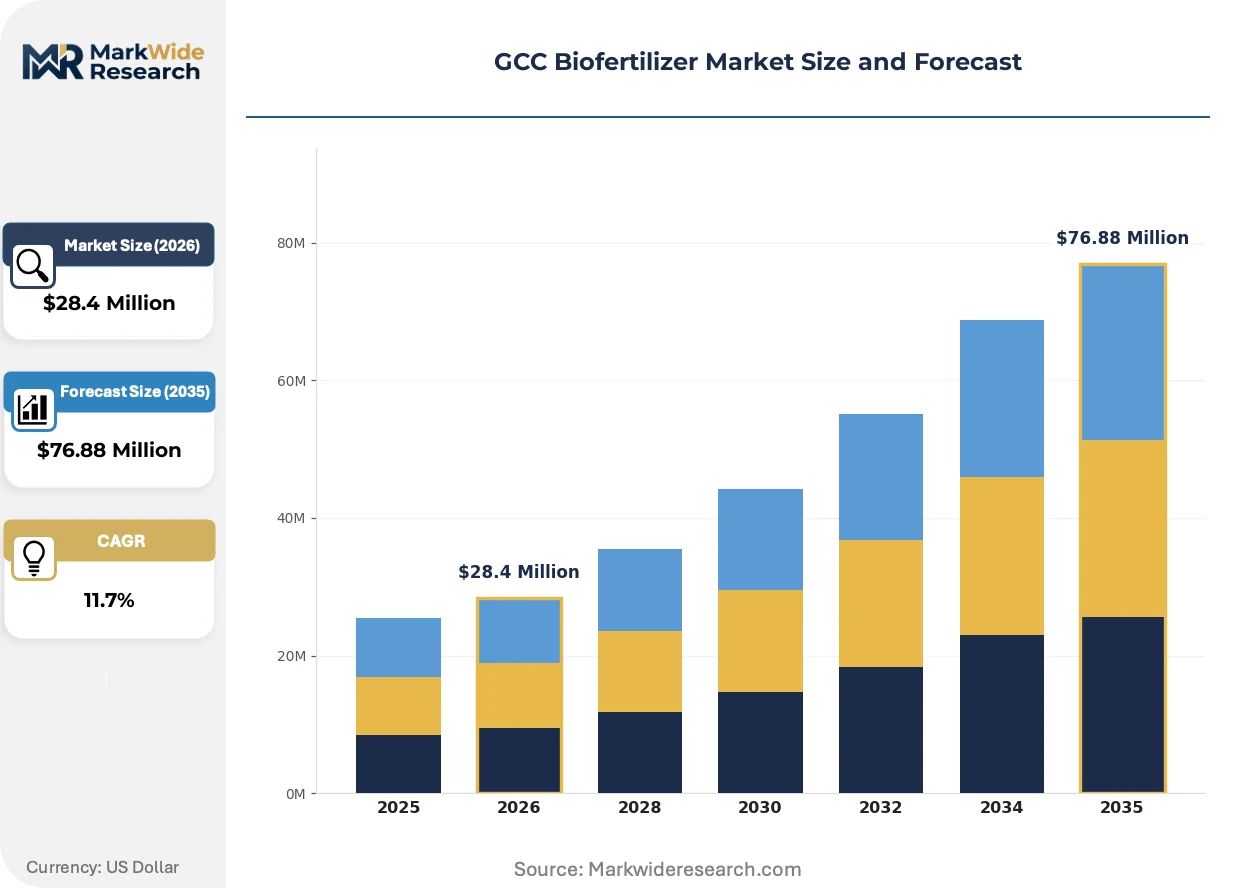
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $76.88 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Granular Biofertilizers, Powders, Composts End User: Agricultural Producers, Organic Farmers, Greenhouses, Retail Nurseries Application: Crops, Vegetables, Fruits, Ornamental Plants Distribution Channel: Online Sales, Retail Stores, Agricultural Supply Stores, Wholesale Distributors |
| Companies Covered | Al-Akhawain Holding, Union Chemicals Co. LLC, Emirates Bio Fertilizer Factory (EBFF), Desert Oasis Fertilizers Packaging LLC, uTerra Middle East Agro Industries, RNZ Agrotech Industries Ltd., Dhofar Organics LLC, Oman Agri-Fertilizer Co. LLC, Abu Dhabi Fertilizer Industries Co. (ADFERT), Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Biofertilizer Market Strategic Shifts & Innovations
Microbial formulation science and digital agriculture platforms are converging to transform how Gulf producers select, apply, and monitor biofertilizer performance across saline-alkaline production environments.
Sensor-enabled application equipment is digitizing field-level decision-making. Variable-rate inoculation systems using soil microbiome mapping allow date palm estates in Al-Qassim to target rhizobium placement to root zones with specific pH profiles. Major greenhouse operators in the Emirates are piloting these systems, compressing the feedback loop between application and yield response from seasons to weeks.
SFDA and UAE's MOCCAE are tightening microbial strain traceability requirements. New registration frameworks mandate whole-genome sequencing documentation for commercial inoculants, elevating compliance costs but filtering out uncharacterized consortia. Liquid formulation specialists with validated strain libraries are consolidating market position as smaller blenders face sequencing cost barriers.
Certification-driven purchasing is fragmenting traditional supply relationships. Organic farmers in Saudi Arabia's Riyadh region now demand third-party efficacy documentation and strain-specific performance data before procurement, displacing relationship-based ordering with specification-driven tenders. Agricultural cooperatives are aggregating this demand to negotiate volume pricing directly with Abu Dhabi manufacturers.
GCC Biofertilizer Market Segmentation
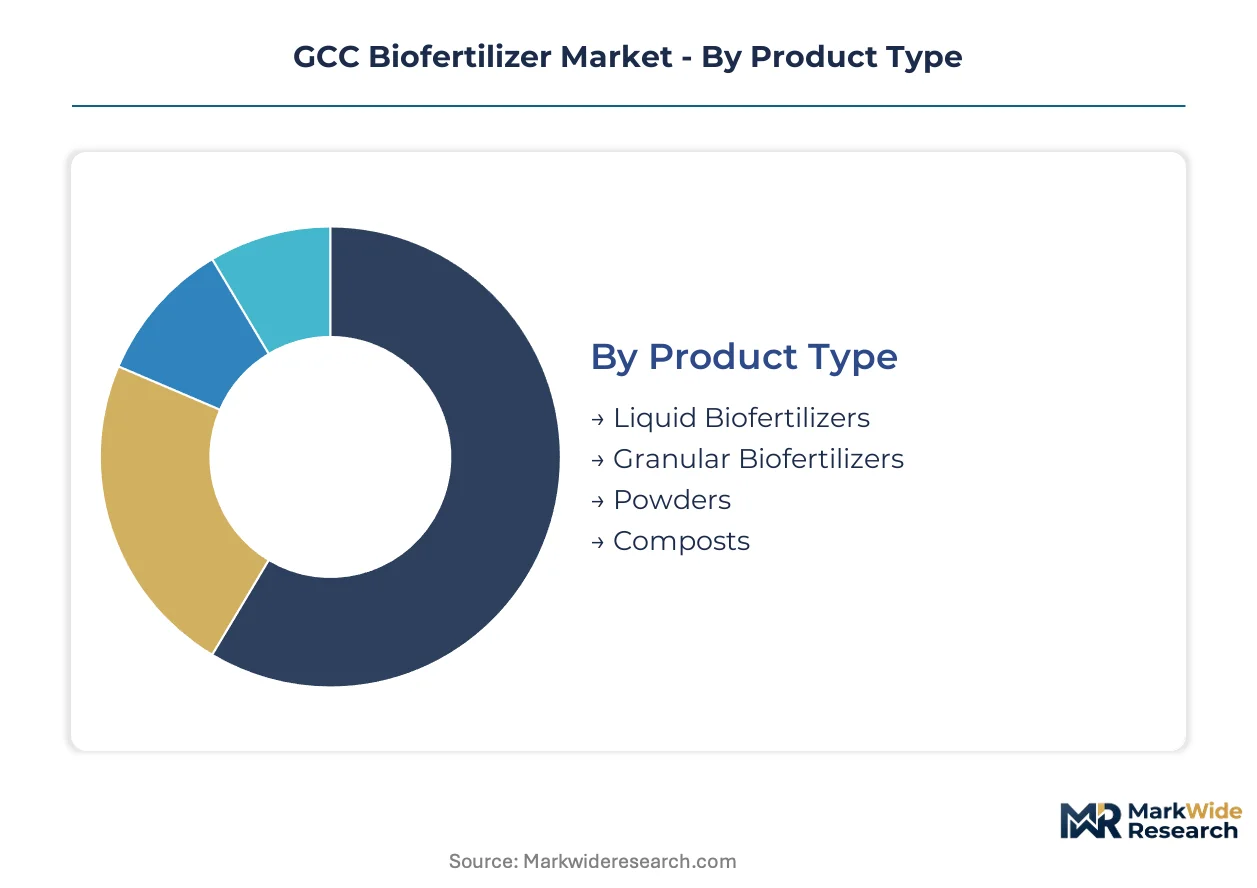
Product format dictates compatibility with Gulf irrigation infrastructure and shelf-life economics. End-user concentration in protected cultivation and date palm estates shapes demand specifications. Distribution channel fragmentation reflects the divergence between bulk procurement by agricultural cooperatives and direct ordering by smaller organic operations.
Product Type:
Cost tier differentiation separates premium cold-chain-dependent formats from ambient-stable alternatives suited to remote Gulf governorates.
- Liquid Biofertilizers:Microbial suspensions with 10^8 CFU per gram potency, formulated for direct injection into drip-irrigation systems. Greenhouse operators across the Emirates prefer these for hydroponic compatibility and rapid root-zone colonization, though six-month ambient shelf-life constrains inventory planning for agricultural supply stores in Oman's interior regions.
- Granular Biofertilizers:Peat or compost-based carriers embedding nitrogen-fixing bacteria or phosphate-solubilizing fungi for single-application broadcasting. Open-field cereal producers in Saudi Arabia's Al-Qassim region favor these for labor efficiency, but Baltic peat feedstock dependence exposes formulators to shipping volatility through Jebel Ali port congestion.
- Powders:Lyophilized microbial preparations with extended stability requiring reconstitution before application. Retail nurseries stock these for small-volume sales to home gardeners.
- Composts:Organic matter inoculated with microbial consortia during controlled decomposition. Dhofar Organics LLC leverages backward integration into compost feedstock sourcing for Oman's southern agricultural corridor.
Liquid biofertilizers command the established base. The steepest expansion runs through granular formats as open-field adoption accelerates.
End User:
Application volume and technical sophistication diverge sharply across customer types, from precision greenhouse operators to commodity cereal growers.
- Agricultural Producers:Large-scale date palm estates and cereal farms driving bulk procurement of rhizobium-based nitrogen fixers. SFDA registration requirements for microbial inputs elevate supplier qualification thresholds, concentrating procurement among established Abu Dhabi manufacturers with validated strain libraries.
- Organic Farmers:Certification-driven purchasers demanding third-party efficacy documentation and strain-specific performance data. Riyadh-region cooperatives aggregate this demand to negotiate direct volume pricing, displacing traditional agricultural supply store relationships.
- Greenhouses:Protected cultivation operators requiring phosphate-solubilizing fungi compatible with soilless systems. Emirates-based facilities pilot sensor-enabled variable-rate inoculation using soil microbiome mapping.
- Retail Nurseries:Small-volume outlets serving home gardeners and landscape contractors with powder formulations and consumer-packaged composts.
Agricultural producers anchor volume demand. Organic farmers are gaining share fastest through certification-premium produce channels.
Application:
Crop-specific nutrient requirements and soil salinity tolerance determine microbial strain selection across Gulf production environments.
- Crops:Wheat and barley cultivation in saline-alkaline soils requires salt-tolerant nitrogen-fixing bacteria. Al-Qassim region growers replace synthetic inputs with microbial alternatives under Saudi sustainable agriculture mandates.
- Vegetables:Greenhouse tomato and cucumber production demands phosphate-solubilizing fungi for hydroponic nutrient efficiency. UAE water conservation policies subsidize these inputs to reduce irrigation frequency.
- Fruits:Date palm root zones in Saudi Arabia receive targeted rhizobium placement based on pH-profile mapping. Sensor-enabled application equipment compresses feedback loops from seasons to weeks.
- Ornamental Plants:Landscaping and export floriculture in the Emirates utilize plant growth-promoting rhizobacteria for stress tolerance in controlled-environment production.
Date palm and cereal applications command the established base. Vegetable greenhouse applications are climbing the fastest.
Distribution Channel:
Procurement pattern fragmentation reflects scale divergence between bulk cooperative purchasing and fragmented small-farmer demand.
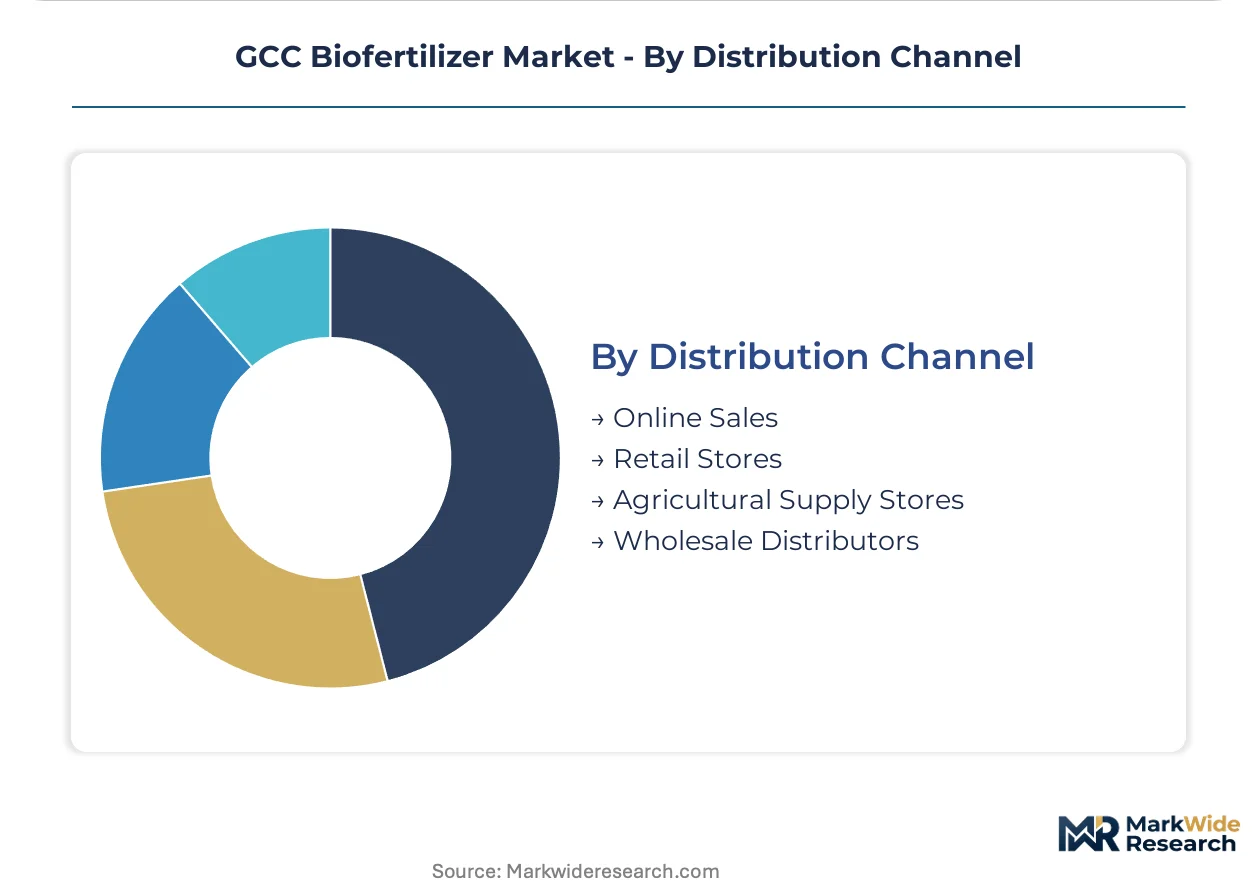
- Agricultural Supply Stores:Traditional intermediaries stocking liquid and granular formats for immediate pickup. Remote Omani governorates face inventory challenges due to liquid biofertilizer shelf-life limitations.
- Wholesale Distributors:Bulk logistics operators consolidating shipments from Abu Dhabi manufacturing bases to Saudi agricultural cooperatives. Cold-chain infrastructure investments elevate landed costs for temperature-sensitive formulations.
- Online Sales:Mobile-based ordering platforms bypassing intermediaries for smaller organic operations. Drone delivery networks pilot last-mile distribution to isolated farms.
- Retail Stores:General agricultural retailers serving hobbyist gardeners with powder and compost formats.
Agricultural supply stores retain the volume base. Online platforms are expanding most quickly among tech-adopting smaller producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration pathways anchor Saudi Arabia's dominance in Gulf biofertilizer demand. The kingdom's sustainable agriculture mandates redirect procurement flows across the region as date palm estates and greenhouse operators abandon synthetic inputs.
Saudi Arabia
Al-Qassim region date palm growers drive rhizobium-based nitrogen fixer procurement under Vision 2030 agricultural transformation programs. SFDA streamlined microbial input approvals accelerate commercialization timelines for arid-zone cereal formulations. Riyadh-region agricultural cooperatives aggregate organic farmer demand to negotiate direct volume pricing with manufacturers.
United Arab Emirates
Greenhouse operators across the Emirates multiply demand for phosphate-solubilizing fungi compatible with hydroponic systems. MOCCAE water conservation policies penalize synthetic fertilizer runoff while subsidizing microbial alternatives that reduce irrigation frequency. Abu Dhabi manufacturing bases anchor distribution networks serving protected cultivation expansion in Dubai and Sharjah.
Oman
Dhofar Organics LLC dominates the southern agricultural corridor through backward integration into compost feedstock sourcing. The Ministry of Agriculture and Fisheries mandates efficacy trials before commercial approval, elevating compliance costs for new entrants. Batinah coast and Al Dakhiliyah regions remain underserved for cereal-specific nitrogen-fixing inoculants.
Qatar
Food security initiatives drive protected cultivation investment requiring microbial inputs compatible with soilless production systems. The Ministry of Municipality and Environment enforces organic certification standards for agricultural exports. Al Khor and Al Thakira greenhouse clusters generate concentrated demand for liquid biofertilizer formulations.
Kuwait
Wafra agricultural area farmers adopt biofertilizers under national sustainable farming directives targeting reduced chemical dependency. The Public Authority for Agriculture Affairs and Fish Resources regulates microbial input quality standards. Greenhouse expansion in Jahra Governorate creates demand for drip-irrigation-compatible liquid suspensions.
GCC Biofertilizer Market Key Industry Players
Capability concentration sits with strain library specialists; scale advantage sits with integrated manufacturers with captive distribution. The vendor base separates into three tiers: Abu Dhabi-based integrated producers with regional logistics networks, Riyadh-region formulators serving domestic cooperatives, and Omani compost-integrated operators controlling southern feedstock supply. M&A activity concentrates on strain patent acquisitions and cold-chain infrastructure investments.
Within the integrated manufacturing tier, Emirates Bio Fertilizer Factory and Abu Dhabi Fertilizer Industries Co. occupy positions anchored by Emirates-based production and distribution infrastructure. Dhofar Organics LLC exemplifies the compost-integrated archetype through Omani feedstock control. These three entities represent distinct competitive positioning vectors: manufacturing scale, liquid formulation specialization, and backward supply integration.
| Leading Market Players |
|---|
| Al-Akhawain Holding |
| Union Chemicals Co. LLC |
| Emirates Bio Fertilizer Factory (EBFF) |
| Desert Oasis Fertilizers Packaging LLC |
| uTerra Middle East Agro Industries |
| RNZ Agrotech Industries Ltd. |
| Dhofar Organics LLC |
| Oman Agri-Fertilizer Co. LLC |
| Abu Dhabi Fertilizer Industries Co. (ADFERT) |
| Others |
Cost & Logistics Intelligence
Baltic peat feedstock dependency exposes GCC formulators to shipping rate volatility through Jebel Ali port congestion, compressing margin structures for granular carriers while elevating landed cost spreads between liquid and solid formats. This single-source vulnerability for carrier materials concentrates pricing power with importers holding cold-chain infrastructure, forcing regional manufacturers to absorb freight fluctuations or pass through to greenhouse operators.
Pricing Analysis
Abu Dhabi-manufactured liquid suspensions command premiums over Saudi-imported granular alternatives due to cold-chain logistics costs. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-registered formulations from unregistered consortia and generic peat-based powders. Cost compression in the granular tier is intensifying because Baltic shipping congestion and Jebel Ali customs delays compound feedstock expenses. Agricultural cooperatives in Al-Qassim exhibit lowest price sensitivity due to volume aggregation, while remote Omani greenhouse operators face highest sensitivity given per-unit delivery premiums.
Supply Chain Analysis
Extended payment terms from Emirates Bio Fertilizer Factory and ADFERT to Saudi agricultural cooperatives stabilize working capital for bulk procurement seasons. Manufacturing concentrates in the UAE, Saudi Arabia, and Estonia for peat feedstock. Production draws from nitrogen-fixing bacterial strains, phosphate-solubilizing fungal cultures, and Baltic peat carriers. Single-source vulnerability for carrier materials threatens formulation continuity during Baltic shipping disruptions. Distribution runs through wholesale distributors consolidating Abu Dhabi output to Saudi cooperatives, with agricultural supply stores serving fragmented Omani demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PhD-level microbiologist scarcity across Gulf universities constrains strain isolation capacity, elevating acquisition premiums for validated strain libraries and sequencing-compliant operations.
For Market Incumbents: Harden cold-chain infrastructure investments to defend granular formulation margins against summer viability losses. Consolidate position through backward integration into compost feedstock sourcing, mirroring Dhofar Organics LLC's Omani model. Prioritize SFDA and MOCCAE registration maintenance to filter out sequencing-cost-burdened challengers. For New Entrants and Emerging Players: Oman's Batinah coast and Al Dakhiliyah regions offer immediate white-space access for cereal-specific nitrogen-fixing inoculants underserved by southern compost operators. Target mobile-based direct-to-farmer platforms bypassing agricultural supply store intermediaries. Launch through drone delivery pilots to isolated farms, leveraging technical shelf-life limitations of incumbents as service differentiation. For Investors and Strategic Acquirers: SFDA's whole-genome sequencing mandate reshapes the acquisition landscape toward liquid formulation specialists with documented strain libraries. Long-term viability centers on regulatory compliance infrastructure rather than production scale alone. Target acquisition candidates with validated consortia and sequencing documentation. Monitor strain patent expiration schedules as inflection signals for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compost Feedstock | Dhofar Organics LLC demonstrates how Omani feedstock control secures southern corridor dominance against importers. |
| Cold-Chain Infrastructure Investment | Emirates-based manufacturers protect granular viability through Gulf summer temperatures, preserving premium positioning. |
| SFDA Registration Acceleration | Streamlined microbial input approvals compress commercialization timelines for arid-zone cereal formulations in Al-Qassim. |
| Direct-to-Farmer Platform Launch | Mobile ordering with drone delivery bypasses agricultural supply stores, capturing organic farmer demand in Riyadh region. |
| Whole-Genome Sequencing Compliance | Sequencing documentation mandates filter uncharacterized consortia, consolidating market position for validated strain holders. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SFDA registration databases, UAE Ministry of Climate Change and Environment policy filings, and GCC customs trade records. Primary interviews engaged biofertilizer formulation scientists, agricultural cooperative procurement managers, greenhouse operations directors, and cold-chain logistics providers across Saudi Arabia, the UAE, and Oman. Secondary validation drew from organic certification registries, strain patent documentation, and port authority shipping manifests. Bottom-up demand modeling from end-user consumption patterns triangulates against top-down supply capacity assessments from manufacturing facility outputs.
Forecast inputs incorporate product format adoption curves, irrigation infrastructure penetration rates, and regulatory approval velocity across the projection horizon. Segmentation dimensions modeled include microbial strain type, formulation format, end-user scale tier, and application crop category. CAGRs derive from compounding annual demand growth assumptions calibrated to sustainable agriculture mandate implementation timelines. Industry-specific inputs include SFDA registration pathway efficiency and greenhouse expansion permits issued by MOCCAE.
Practitioners should monitor Baltic shipping rate volatility, strain patent expiration clusters, and sequencing compliance cost trajectories for early signals of competitive repositioning. Forecasts assume sustained regulatory enforcement intensity and cold-chain infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market