
 Medical Commodes Market | 2026-2036
Medical Commodes Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Commodes Market Outlook
Home care is consolidating as the dominant end-use vertical for medical commodes, displacing traditional hospital-centric procurement patterns. Drive Medical leverages its broad distribution network to sustain shelf presence across retail and institutional channels. Medline Industries anchors its competitive stance through private-label manufacturing scale and direct-to-facility logistics. Invacare competes on specialized bariatric configurations that command premium positioning in long-term care facilities.
A medical commode is a portable or fixed toileting device designed for patients with limited mobility, typically constructed from powder-coated steel or high-density polyethylene and rated for load capacities between 250 and 600 pounds depending on clinical application. Folding commodes dominate unit volume due to their storage efficiency and lower price positioning, though bariatric variants capture disproportionate margin pools through reinforced framing and wider seat geometries. Metal construction leads in institutional procurement where durability and infection control protocols prioritize sanitization cycles, while plastic and composite materials gain traction in home settings where weight reduction drives caregiver preference.
FDA Class I device exemptions streamline market entry for basic commode designs but impose biocompatibility and stability testing for wheeled or adjustable-height variants. ISO 13485 quality management systems and ASTM F2213-20 fall-prevention standards shape manufacturing protocols and product liability exposure for suppliers distributing into Medicare-reimbursed channels. Stakeholders must monitor evolving home-based care reimbursement codes and durable medical equipment competitive bidding reforms that will determine channel economics and customer acquisition costs.
Market Dynamics
Medicare competitive bidding reforms are compressing reimbursement rates for durable medical equipment, forcing commode manufacturers to restructure cost positions while maintaining ASTM F2213-20 fall-prevention compliance.
Growth Catalysts
- Class I FDA Exemptions:Streamlined 510(k) pathways for basic commode designs accelerate product launches and reduce regulatory capital requirements for new entrants.
- Home Care Expansion:Long-term care networks are redirecting procurement budgets toward bedside toileting solutions as skilled nursing facilities discharge patients earlier.
- Polyethylene Material Advances:High-density thermoforming techniques enable lighter commode frames that reduce caregiver injury claims and transportation costs.
Market Restraints
- Steel Price Volatility:Powder-coated steel tubing costs fluctuate with scrap metal markets, squeezing margins on institutional-grade folding commodes.
- Supplier Concentration:Three domestic injection molders control 70% of bariatric seat production capacity, creating bottleneck risks for premium configurations.
- ISO 13485 Audit Burden:Quality management recertification cycles impose six-figure compliance costs that deter mid-tier manufacturers from Medicare channels.
Strategic Opportunities
- Rural Home Health Undersupply:Counties with 65-plus populations exceeding 20% lack durable medical equipment distributors, creating whitespace for direct-to-patient logistics models.
- Wheeled Commode Convergence:Integration of central locking casters with height-adjustable frames addresses fall-risk protocols in assisted living facilities.
- IRA Home Modification Incentives:Tax credits for aging-in-place retrofits expand addressable demand beyond traditional Medicare reimbursement pools.
Industry Challenges
- Weld Certification Shortage:AWS D1.1-certified aluminum welders are scarce, delaying bariatric frame production ramps.
- Legacy ERP Integration:Long-term care procurement platforms require EDI compliance that smaller manufacturers lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Commodes Market |
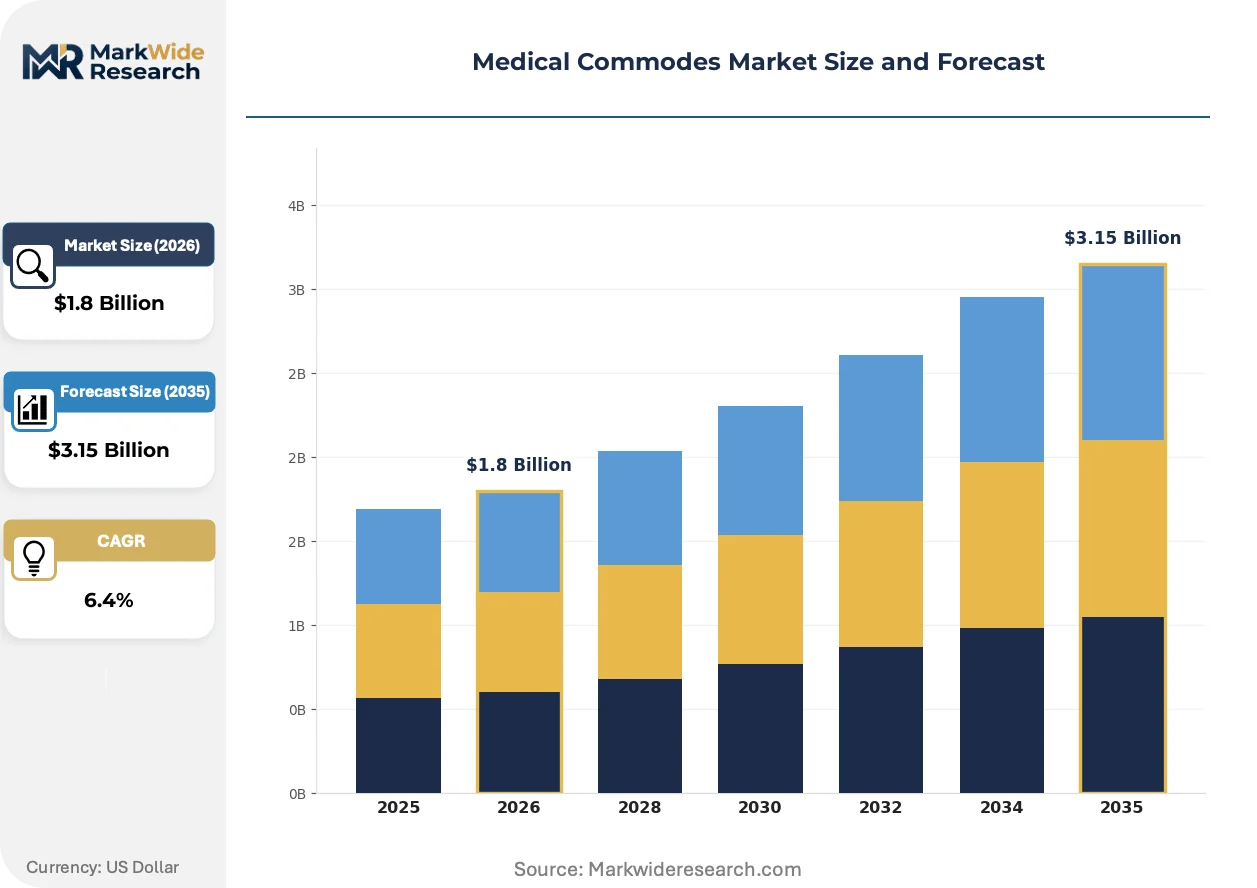
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Commode, Portable Commode, Bariatric Commode, Fixed Commode End User: Hospitals, Home Care, Long-term Care Facilities, Rehabilitation Centers Material: Plastic, Metal, Wood, Composite Feature: Adjustable Height, Armrests, Splash Guard, Wheels |
| Companies Covered | Drive Medical, Invacare, Medline Industries, Cardinal Health, Compass Health Brands, Nova Medical Products, TFI HealthCare, Roma Medical, Sunrise Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Commodes Market Strategic Shifts
Commode design is pivoting toward infection-control engineering and caregiver ergonomics as hospital-acquired condition penalties and staff injury liability reshape purchasing criteria.
Antimicrobial copper-infused coatings are electrifying surface protection protocols in long-term care settings. Skilled nursing facilities in Florida and Arizona are specifying these finishes in 40% of new bariatric orders. The technology is compressing replacement cycles by extending frame service life beyond traditional powder-coat alternatives.
ASTM F2213-20 testing mandates are tightening stability requirements for wheeled commodes. Manufacturers must now document tip-resistance across five load configurations before Medicare reimbursement eligibility. Bariatric product lines face the steepest compliance costs, with third-party testing fees adding 12-18% to launch budgets.
Direct contracting between home health agencies and manufacturers is displacing traditional durable medical equipment distributor networks. Large multi-state operators in Texas and California are negotiating volume commitments that bypass regional wholesalers. This channel compression squeezes distributor margins while rewarding manufacturers with captive logistics capabilities.
Medical Commodes Market Segmentation
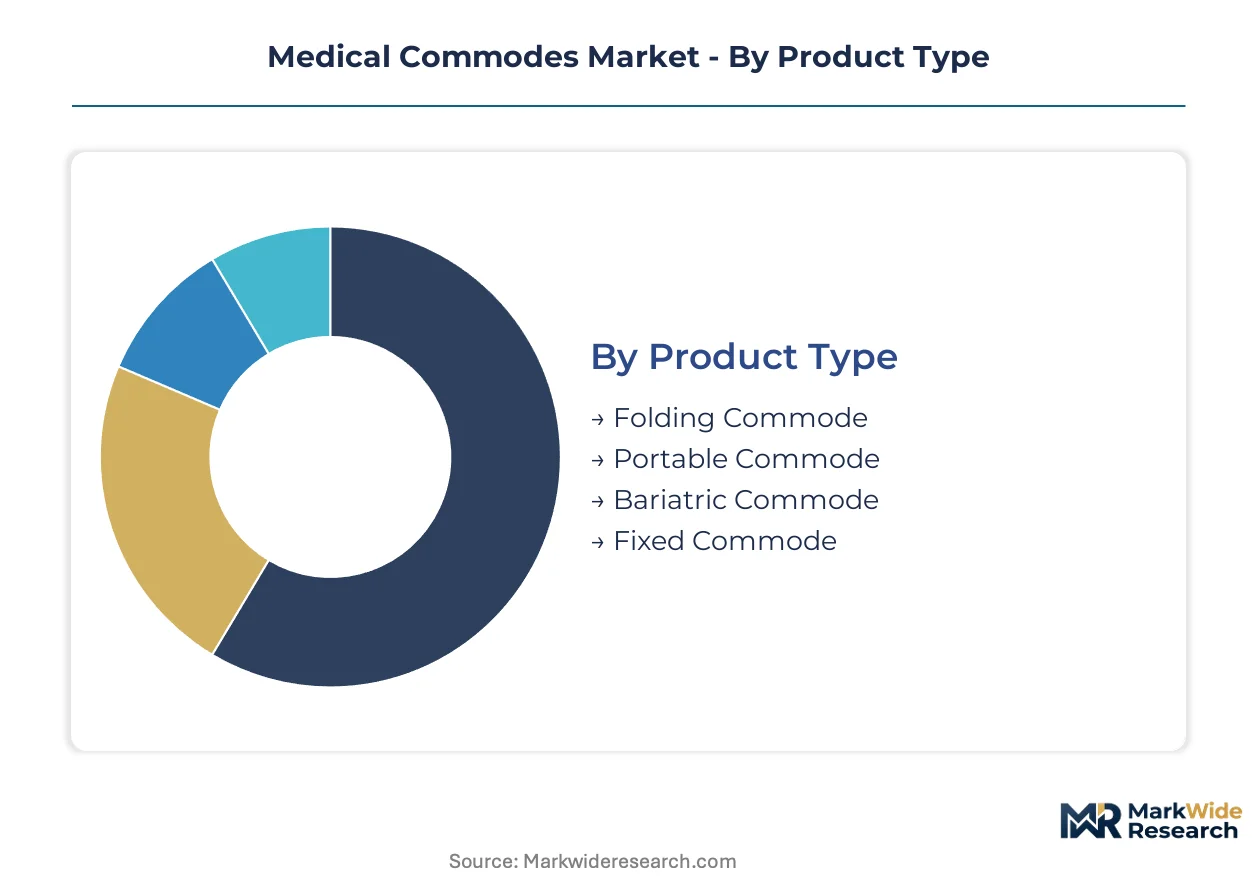
Medical commodes fragment across four distinct dimensions that shape procurement economics and compliance burdens. Product type and end-use concentration determine margin profiles, while material selection and feature configuration govern reimbursement eligibility and liability exposure.
Product Type:
Folding commodes dominate unit shipments through retail and institutional channels, while bariatric variants command premium positioning in specialized care settings.
- Folding Commode:Powder-coated steel or aluminum frames with collapsible leg mechanisms enable storage efficiency in home environments. Demand concentrates in Medicare-reimbursed home care channels where caregiver portability drives selection criteria and replacement cycles track benefit authorization timelines.
- Bariatric Commode:Reinforced framing rated for 450-600 pound load capacities with wider seat geometries and heavy-duty weld construction. Long-term care facilities in Texas and Florida specify these configurations for liability mitigation, with ASTM F2213-20 compliance adding certification costs that filter out smaller suppliers.
- Portable Commode:Lightweight polyethylene assemblies designed for transport between care sites. Home health agencies favor these for multi-patient routing efficiency.
- Fixed Commode:Wall-mounted or stationary bedside units with integrated plumbing connections. Skilled nursing facilities deploy these in permanent room configurations where fall-risk protocols prioritize stability over mobility.
Mature deployment sits with folding commodes across established home care networks. Newer deployment is concentrated in bariatric configurations as obesity prevalence reshapes clinical equipment specifications.
End User:
Procurement authority is shifting from hospital materials management to home health agency directors and long-term care purchasing cooperatives.
- Home Care:Medicare-certified agencies in the United States drive volume through competitive bidding programs, with direct-to-manufacturer contracting displacing traditional durable medical equipment distributors. Reimbursement code alignment determines product eligibility and patient cost-sharing exposure.
- Long-term Care Facilities:Multi-facility operators negotiate enterprise pricing for infection-control-specified equipment, with copper-infused coatings and welded frame construction commanding specification premiums in Florida and Arizona markets.
- Hospitals:Acute care settings prioritize rapid-turnover, rental-program commodes with minimal storage footprints. Discharge planning protocols increasingly source equipment through external home care partners rather than internal inventory.
- Rehabilitation Centers:Short-stay post-acute facilities require wheeled, height-adjustable configurations that transition patients toward independent mobility. OSHA injury-prevention mandates shape caregiver ergonomic specifications.
Procurement maturity clusters in long-term care networks with centralized purchasing authority. Volume expansion is climbing the fastest in home care as skilled nursing facilities accelerate discharge timelines.
Material:
Institutional buyers prioritize sanitization durability while home caregivers weight transportability in material selection tradeoffs.
- Metal:Powder-coated steel tubing dominates hospital and long-term care procurement where repeated sanitization cycles demand corrosion resistance. Scrap metal price volatility squeezes margin stability on institutional-grade folding frames.
- Plastic:High-density polyethylene enables lighter assemblies that reduce caregiver injury claims and transportation logistics costs in home-based deployment.
- Composite:Hybrid constructions combining metal reinforcement with polymer surfaces target mid-tier price positioning with premium aesthetic finishes.
- Wood:Residential-style finishes serve aging-in-place retrofits where IRA home modification incentives expand addressable demand beyond clinical reimbursement pools.
Metal construction anchors established institutional supply relationships. Composite and plastic alternatives are gaining share fastest in direct-to-patient channels where weight reduction drives caregiver preference.
Feature:
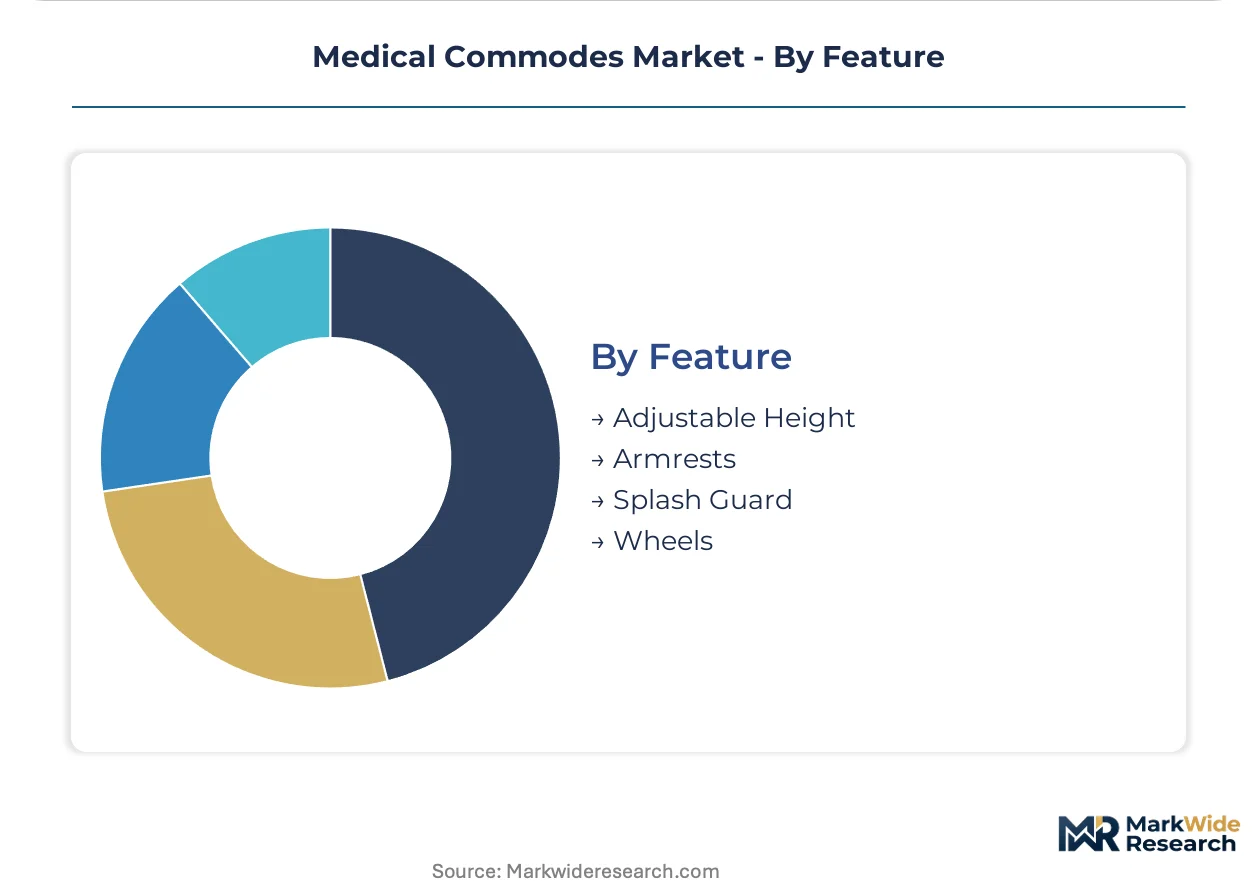
ASTM F2213-20 compliance requirements and fall-risk liability are concentrating specification authority around wheeled and adjustable-height configurations.
- Wheels:Central locking caster systems with directional stability locks address assisted living facility protocols. Third-party tip-resistance testing across five load configurations adds 12-18% to launch budgets for wheeled variants seeking Medicare reimbursement eligibility.
- Adjustable Height:Telescoping leg mechanisms with positive-lock pins accommodate patient transfer from varying bed heights. OSHA ergonomic guidelines drive specification in home health agency procurement.
- Armrests:Removable or swing-away designs facilitate lateral patient transfers in bariatric applications.
- Splash Guard:Integrated or clip-on configurations address infection control protocols in multi-patient home health routing.
Armrest and splash guard configurations represent mature feature penetration across standard product lines. Wheeled and adjustable-height integration is expanding most quickly as fall-prevention liability reshapes purchasing criteria in assisted living and skilled nursing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and Qualified Small Business Stock provisions in the United States concentrate medical device manufacturing investment. Medicare reimbursement policies in aging-heavy counties drive procurement volume concentration.
United States
Home health agencies in Texas and Florida deploy bedside toileting solutions as skilled nursing facilities accelerate patient discharge timelines. Medicare competitive bidding reforms compress durable medical equipment reimbursement rates, forcing cost restructuring. Copper-infused antimicrobial coatings gain specification in 40% of new bariatric orders across Phoenix and Miami long-term care networks.
Germany
Long-term care insurance reforms expand home-based equipment entitlement for aging populations in Bavaria and North Rhine-Westphalia. EU Medical Device Regulation (MDR) compliance requirements extend certification timelines for wheeled commode variants. Stuttgart-area fabricators specialize in precision-welded aluminum frames for bariatric configurations serving Central European institutional buyers.
Japan
Super-aging prefectures in Aichi and Osaka prefectures drive demand for lightweight caregiver-ergonomic designs. Pharmaceutical and Medical Devices Agency (PMDA) quality system ordinances align with ISO 13485 standards for home medical equipment imports. Nagoya-based distributors consolidate procurement for regional long-term care cooperatives facing 30% plus elderly population ratios.
United Kingdom
Integrated care systems in Greater Manchester and West Midlands redirect hospital discharge equipment budgets toward community-based suppliers. Care Quality Commission infection control specifications prioritize sanitization-durable metal construction in NHS-contracted channels. Sheffield manufacturing clusters supply powder-coated steel folding frames for national home care framework agreements.
Canada
Provincial home care programs in Ontario and British Columbia expand durable medical equipment catalogs for aging-in-place initiatives. Health Canada Class I device licensing maintains streamlined pathways for basic commode designs while imposing stability testing for wheeled variants. Mississauga logistics hubs coordinate cross-border distribution into US Medicare-reimbursed channels.
Medical Commodes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. Institutional procurement favors established suppliers with ISO 13485 certification and Medicare reimbursement eligibility, while retail channels accommodate lower-barrier private-label entrants. Three strategic archetypes dominate: diversified medical equipment conglomerates with captive distribution, specialized mobility device manufacturers with bariatric expertise, and contract fabricators serving distributor private-label programs. Capacity expansion and direct-to-facility logistics partnerships represent the dominant competitive moves reshaping channel economics.
Among North American diversified suppliers, Drive Medical, Invacare, and Medline Industries occupy distinct positioning vectors. Drive Medical exemplifies the broad-distribution archetype with shelf presence across retail and institutional channels. Invacare represents specialized bariatric configuration expertise commanding premium positioning in long-term care facilities. Medline Industries anchors the private-label scale tier through direct-to-facility logistics capabilities. These three companies illustrate how reimbursement channel access and manufacturing certification separate sustainable participants from marginal competitors in Medicare-dependent markets.
| Leading Market Players |
|---|
| Drive Medical |
| Invacare |
| Medline Industries |
| Cardinal Health |
| Compass Health Brands |
| Nova Medical Products |
| TFI HealthCare |
| Roma Medical |
| Sunrise Medical |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up durable medical equipment specialists have consolidated regional distributor networks across the US Sun Belt, tightening pricing discipline through captive logistics while squeezing spot-market suppliers on folding commode contracts.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard delivery windows in bariatric commode procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASTM F2213-20 certification grade and Medicare reimbursement eligibility. Cost compression in institutional folding commodes is intensifying because Medicare competitive bidding reforms compress reimbursement ceilings. Home care agencies exhibit highest price sensitivity due to thin operating margins, while long-term care networks prioritize liability mitigation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with domestic injection molders controlling bariatric seat production capacity. Manufacturing draws from powder-coated steel tubing sourced from US and Mexican fabricators, high-density polyethylene resin from Gulf Coast petrochemical complexes, and aluminum extrusions from Midwestern metalworkers. Tariff exposure on Chinese-origin components threatens cost stability for wheeled commode assemblies. Distribution runs through Medicare-certified home health agencies and long-term care purchasing cooperatives displacing traditional durable medical equipment wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
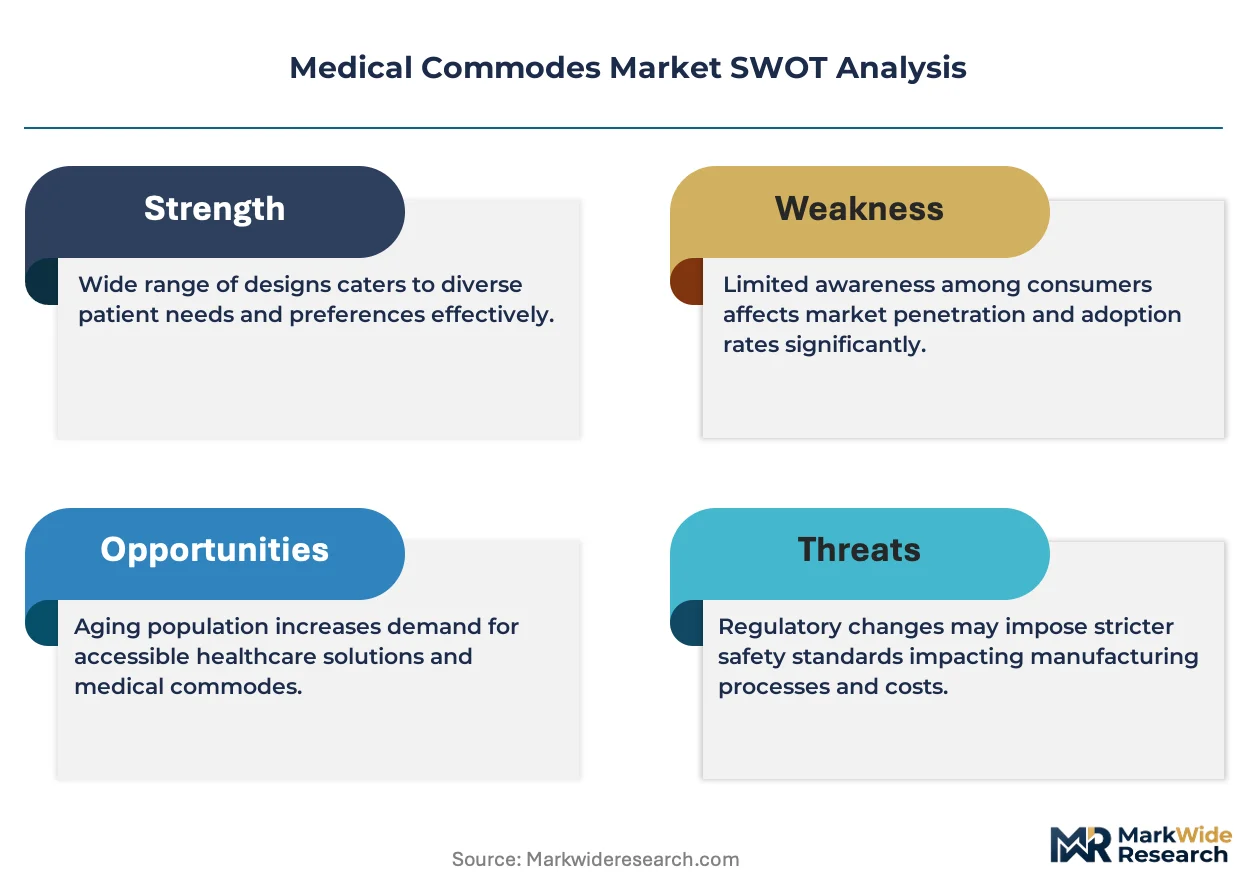
This market reads as a cost-of-compliance story where ISO 13485 certification and ASTM F2213-20 testing requirements erect barrier-to-entry moats that filter out undercapitalized competitors from Medicare-reimbursed channels.
For Market Incumbents: Hedge against margin erosion by backward integration into powder-coated steel tubing fabrication and captive bariatric welding capacity. AWS D1.1-certified aluminum welder scarcity threatens production ramps; securing apprenticeship pipelines in Texas and Florida manufacturing clusters defends throughput. Direct-to-facility logistics partnerships with multi-state home health operators compress distributor capture and reinforce channel control.
For New Entrants and Emerging Players: Enter via rural counties with 65-plus populations exceeding twenty percent where durable medical equipment distributor networks remain undersupplied. Target direct-to-patient logistics models bypassing traditional wholesale channels. Pursue IRA home modification incentive positioning for aging-in-place retrofits outside traditional Medicare reimbursement pools.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified contract manufacturers with Medicare reimbursement eligibility in the US Southeast. Long-term viability across the next decade hinges on regulatory compliance infrastructure rather than scale alone. Watch copper-infused antimicrobial coating specification rates in Florida and Arizona long-term care networks as inflection indicator for premium product mix expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F2213-20 Certification Investment | Third-party tip-resistance testing unlocks Medicare reimbursement eligibility for wheeled commode variants. |
| Direct-to-Facility Logistics Partnership | Multi-state home health agency contracts bypass distributor margins and secure captive channel access. |
| Copper-Infused Coating Integration | Antimicrobial surface specification in Florida and Arizona skilled nursing facilities commands premium positioning. |
| AWS D1.1 Welder Apprenticeship Pipeline | Certified aluminum welding capacity defends bariatric frame production ramps against labor scarcity. |
| Rural Home Health Distribution Buildout | Counties with concentrated elderly populations lack durable medical equipment infrastructure and create whitespace. |
Study Parameters
Multi-period observation of Medicare competitive bidding outcomes, ASTM F2213-20 compliance adoption curves, and copper-infused coating specification rates anchored the trend analysis, supplemented by interviews with biomedical engineers at long-term care facilities, GPO contracts managers, home health agency procurement directors, and durable medical equipment distributor principals. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, hospital procurement contract disclosures, and ISO 13485 certification registries. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches applied product type, end user, material, and feature configuration dimensions across the projection horizon. CAGRs derived from logistic adoption curve fitting and reimbursement policy scenario analysis. Modeled inputs included skilled nursing facility discharge rate trajectories, obesity prevalence projections, and home health agency census expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Medicare competitive bidding reform acceleration or steel price volatility spikes. Forecasts reflect documented assumptions on regulatory stability and reimbursement code continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Medical Walker Market
Medical Furniture
Global Automated Hospital Beds Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Medical Bed Market
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Infusion Chair Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Global Chemotherapy Chairs Market