
 GCC Calcium Chloride Market | 2026-2036
GCC Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Calcium Chloride Market Intelligence
Advanced purification and drying technology is fragmenting traditional calcium chloride supply chains into specialty-grade and commodity-grade tiers. Occidental Chemical Corporation leverages its integrated chlor-alkali operations to sustain cost leadership across the Gulf. TETRA Technologies, Inc. anchors its regional position through oilfield service bundling, while Solvay differentiates via high-purity flake production for food preservation and pharmaceutical applications.
Calcium chloride is an inorganic salt with the chemical formula CaCl₂, typically produced via the Solvay process or as a byproduct of synthetic soda ash manufacturing, and exists in anhydrous and dihydrate forms with hygroscopic properties that drive its industrial utility. Its primary commercial purpose centers on moisture absorption, freeze-point depression, and density modification for drilling fluids. Flake and liquid formats dominate Gulf procurement for road treatment and dust control, where granular commands premium positioning in oilfield applications due to controlled dissolution rates. Direct sales channels capture the largest volume share, though wholesalers retain relevance for construction sector spot purchasing across smaller Emirates and Bahrain.
SASO, the UAE's Ministry of Climate Change and Environment, and Kuwait's Public Authority for Industry collectively enforce product purity, packaging, and environmental discharge standards that shape market access for imported calcium chloride. These frameworks elevate compliance costs for non-GCC suppliers while creating preferential conditions for producers with regional blending and certification capabilities. Stakeholders must monitor evolving desalination brine management regulations, as circular calcium chloride recovery from seawater plants presents both competitive threat and partnership opportunity for incumbent suppliers.
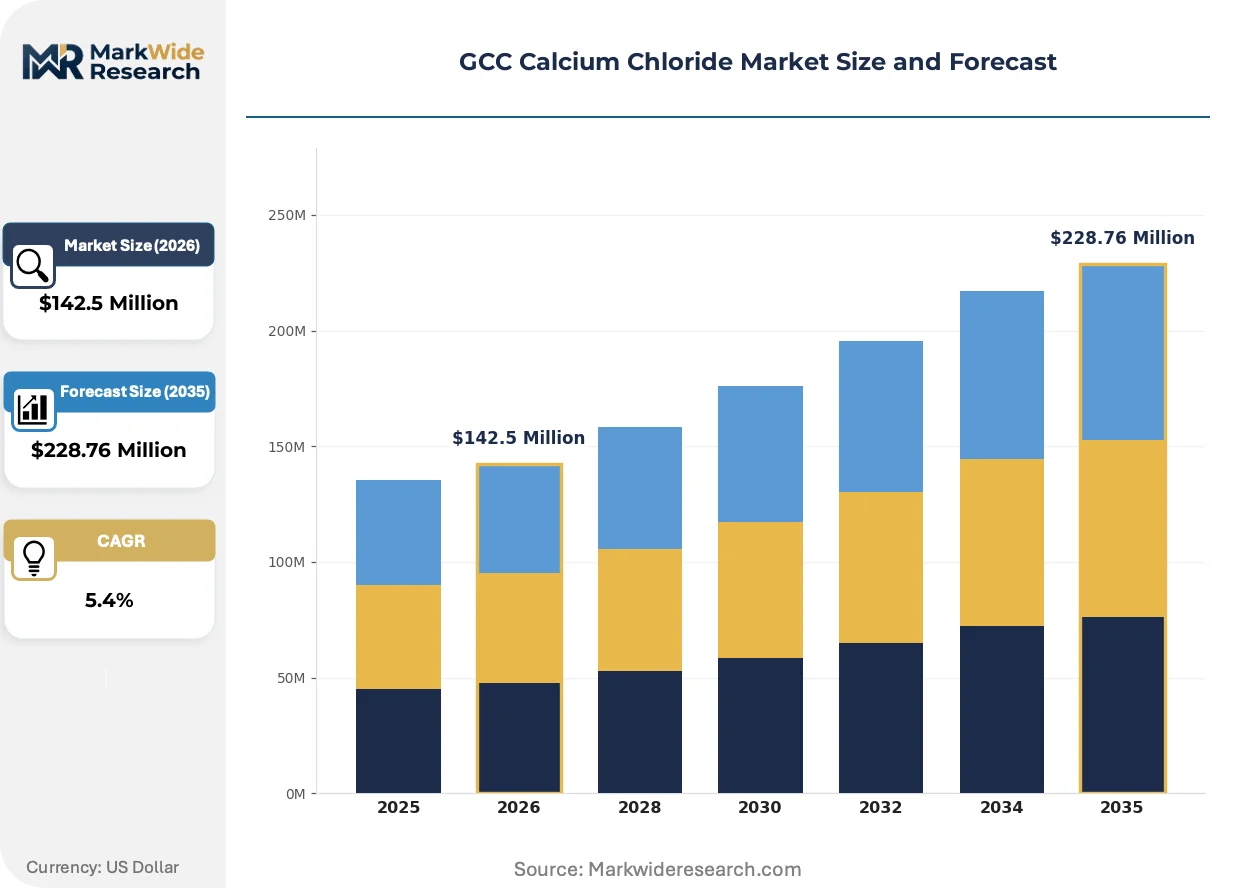
Market Dynamics
SASO's tightened industrial chemical specifications are fragmenting the GCC calcium chloride landscape into compliance-driven specialty tiers and price-sensitive commodity streams, forcing suppliers to choose between purification investment or volume-focused positioning.
Growth Catalysts
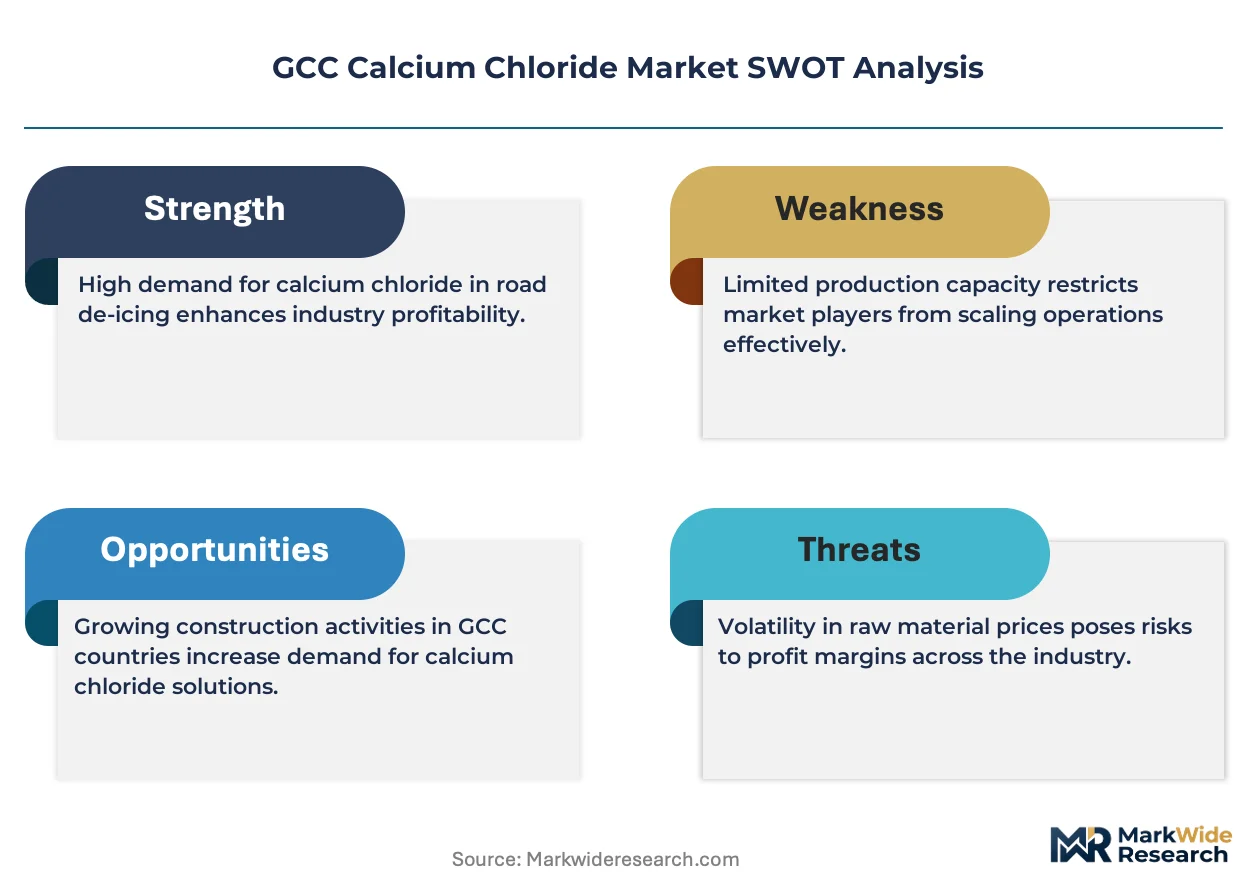
- Oilfield completion fluid demand:Drilling operations across Saudi Arabia's Eastern Province and Kuwait's Burgan field sustain bulk consumption of high-density calcium chloride brines for wellbore stability.
- REACH-aligned purity standards:ECHA chemical safety frameworks are penetrating Gulf procurement specifications, creating pull for pharmaceutical-grade flake production in UAE free zones.
- Desalination brine valorization:Circular recovery processes at Saudi Arabia's Jubail and Ras Al-Khair plants are positioning waste chloride streams as feedstock alternatives.
Market Restraints
- Limestone and hydrochloric acid cost volatility:Chlor-alkali input prices swing with European energy markets, compressing margins for Solvay-process producers without captive chlorine supply.
- Import concentration risk:Non-GCC suppliers face elevated compliance costs from SASO, MOHAP, and Kuwait's Public Authority for Industry certification requirements, narrowing the viable supplier base.
- Magnesium chloride substitution:Lower-cost de-icing salts are capturing municipal road treatment contracts in Bahrain and smaller Emirates during price-sensitive procurement cycles.
Strategic Opportunities
- Food preservation certification gap:High-purity calcium chloride for cheese making and beverage processing remains underpenetrated in UAE and Qatar, where FSSAI-aligned import standards create entry barriers for uncertified suppliers.
- Pharmaceutical-grade flake production:Dubai's Jebel Ali pharmaceutical cluster offers offtake potential for USP-grade material currently sourced from European toll manufacturers.
- Direct-to-refinery digital channels:Saudi Aramco's vendor portal integration is disintermediating traditional oilfield service distributors for completion fluid procurement.
Industry Challenges
- Process safety engineering scarcity:Chlor-alkali plant operators across the Gulf face recruitment gaps for hazmat-certified technicians capable of managing anhydrous calcium chloride production.
- SASO certification timeline compression:Laboratory testing and documentation requirements for industrial chemical registration now stretch 14-18 weeks, delaying market entry for new product grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Calcium Chloride Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Flake, Granular, Powder End User: Construction, De-icing, Dust Control, Agriculture Application: Road Treatment, Food Preservation, Hygroscopic Agent, Chemical Intermediate Distribution Channel: Direct Sales, Wholesalers, Online, Retail |
| Companies Covered | Tiger Calcium Services Inc., Zirax Limited, Occidental Chemical Corporation, Quzhou Menjie Chemicals Co., Ltd., Weifang Haibin Chemical Co., Ltd., TETRA Technologies, Inc., Ward Chemical Ltd., BJ Services Company, Solvay, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Calcium Chloride Market Strategic Shifts & Innovations
Membrane-based purification and digital supply chain orchestration are compressing traditional calcium chloride value chains, eliminating intermediaries while elevating product-grade specificity as the primary competitive differentiator.
Spray-drying technology with integrated fluidized bed classification is rendering obsolete conventional rotary kiln production for high-purity flake grades. Saudi Arabia's Jubail petrochemical cluster has adopted this process for pharmaceutical-grade output. The technology is compressing moisture content variability from 3-5% to sub-1%, eliminating downstream reprocessing costs for food and drug manufacturers.
SASO's Technical Regulation for Industrial Chemicals mirrors EU REACH substance registration requirements, mandating safety data sheet harmonization and hazard classification alignment. Importers must now maintain Gulf-based technical file repositories. The regulation most affects construction-grade liquid calcium chloride suppliers, who are consolidating certification documentation through Dubai-based third-party laboratories.
Refinery procurement teams are unbundling completion fluid service contracts from integrated drilling packages, creating spot-market purchasing for calcium chloride brines. Saudi Aramco and Kuwait Oil Company now issue standalone chemical tenders with 90-day pricing windows. This behavior is most visible in Saudi Arabia's Eastern Province, where direct supplier relationships are displacing oilfield service company intermediaries for bulk liquid delivery.
GCC Calcium Chloride Market Segmentation
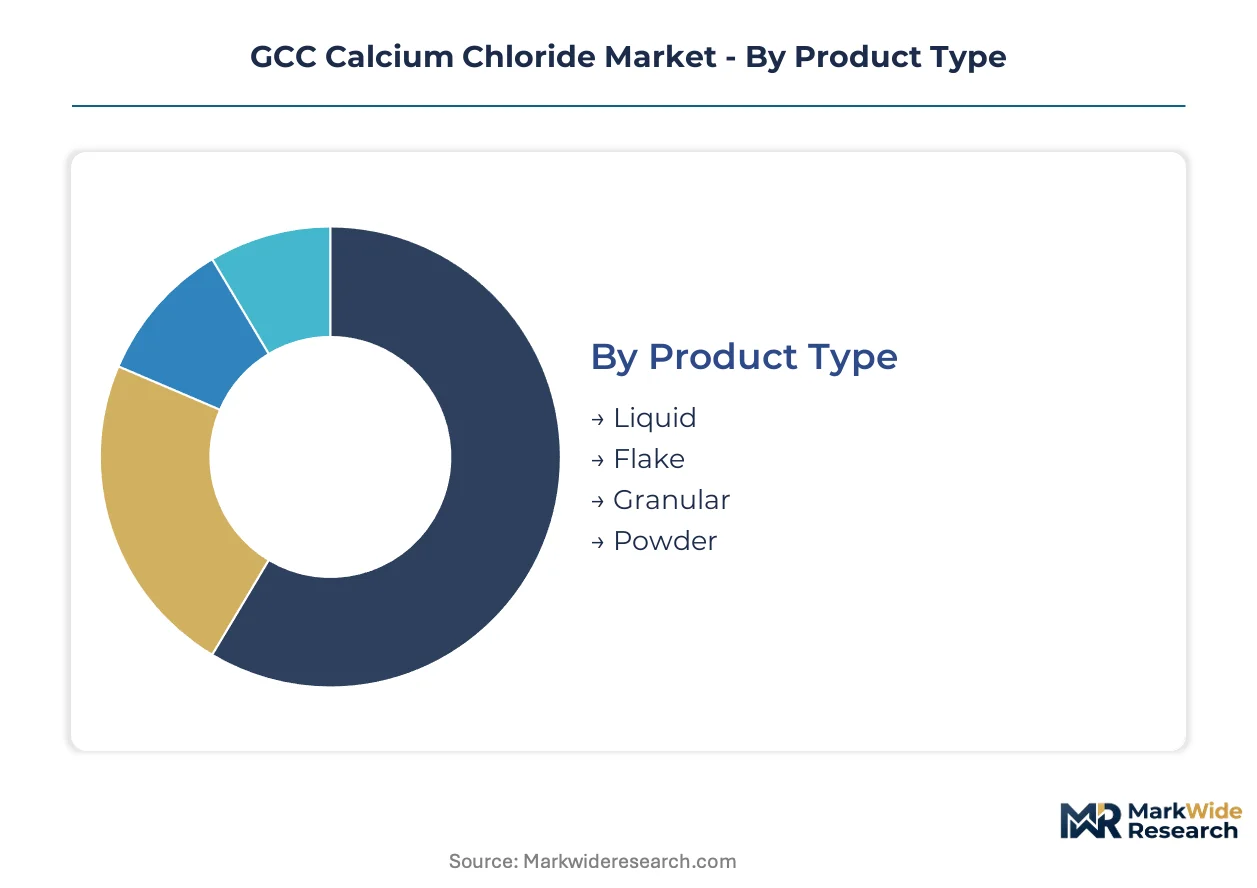
Calcium chloride procurement patterns across the Gulf diverge sharply by physical form and delivery mechanism. Oilfield operators, municipal authorities, and food processors each impose distinct purity and packaging specifications that reshape supplier economics.
Product Type:
Use-case spectrum spans controlled dissolution for downhole applications to rapid moisture absorption for surface treatments.
- Liquid:Pre-diluted brine solutions at 32-40% concentration eliminate on-site mixing for Saudi Aramco completion fluid contracts. Eastern Province drilling clusters account for concentrated offtake where bulk tanker delivery minimizes handling costs.
- Flake:Hygroscopic solid with 77-80% calcium chloride content serves food preservation and pharmaceutical feedstock applications. UAE free zone processors favor this format for REACH-aligned import documentation and moisture-controlled warehousing.
- Granular:Uniform particle sizing between 2-5mm enables metered dissolution rates for dust control on Kuwaiti unpaved roads.
- Powder:Fine-ground anhydrous grade commands niche positioning for chemical synthesis and desiccant manufacturing in Jubail's petrochemical corridor.
The dominant share belongs to Liquid, while Flake is closing the gap fastest.
End User:
Cost tier separation distinguishes bulk commodity purchasers from specification-driven specialty buyers.
- Construction:Concrete acceleration and soil stabilization drive volume procurement across Qatar's infrastructure buildout, with contractors prioritizing price-per-ton over purity certification.
- De-icing:Municipal road authorities in Bahrain and smaller Emirates favor magnesium chloride substitution during budget-constrained procurement cycles, compressing calcium chloride share.
- Dust Control:Unpaved haul roads at Saudi mining and quarry operations sustain granular flake consumption where surface binding durability outweighs unit cost sensitivity.
- Agriculture:Foliar calcium supplementation and post-harvest washing for date palm cultivation in Al-Ahsa oasis creates seasonal demand spikes tied to harvest calendars.
Construction holds the dominant share, though Agriculture shows the steepest expansion trajectory as food security investments intensify.
Application:
Volume concentration tracks infrastructure spending cycles and regulatory enforcement intensity.
- Road Treatment:Freeze-point depression and pre-wetting applications dominate Kuwaiti and northern Saudi municipal procurement, with delivery schedules tied to winter weather forecasts.
- Food Preservation:Cheese brining and beverage processing applications in Dubai and Abu Dhabi require FSSAI-aligned purity certification that filters out uncertified import sources.
- Hygroscopic Agent:Industrial desiccant and moisture control applications span pharmaceutical packaging and electronics manufacturing in UAE industrial zones.
- Chemical Intermediate:Calcium chloride serves as feedstock for calcium salts and drilling fluid additives within Saudi Arabia's integrated petrochemical complexes.
Road Treatment maintains dominant positioning, while Food Preservation gains share fastest on certification-driven import substitution.
Distribution Channel:
Customer type and procurement scale determine channel selection across spot purchasing and contracted supply.
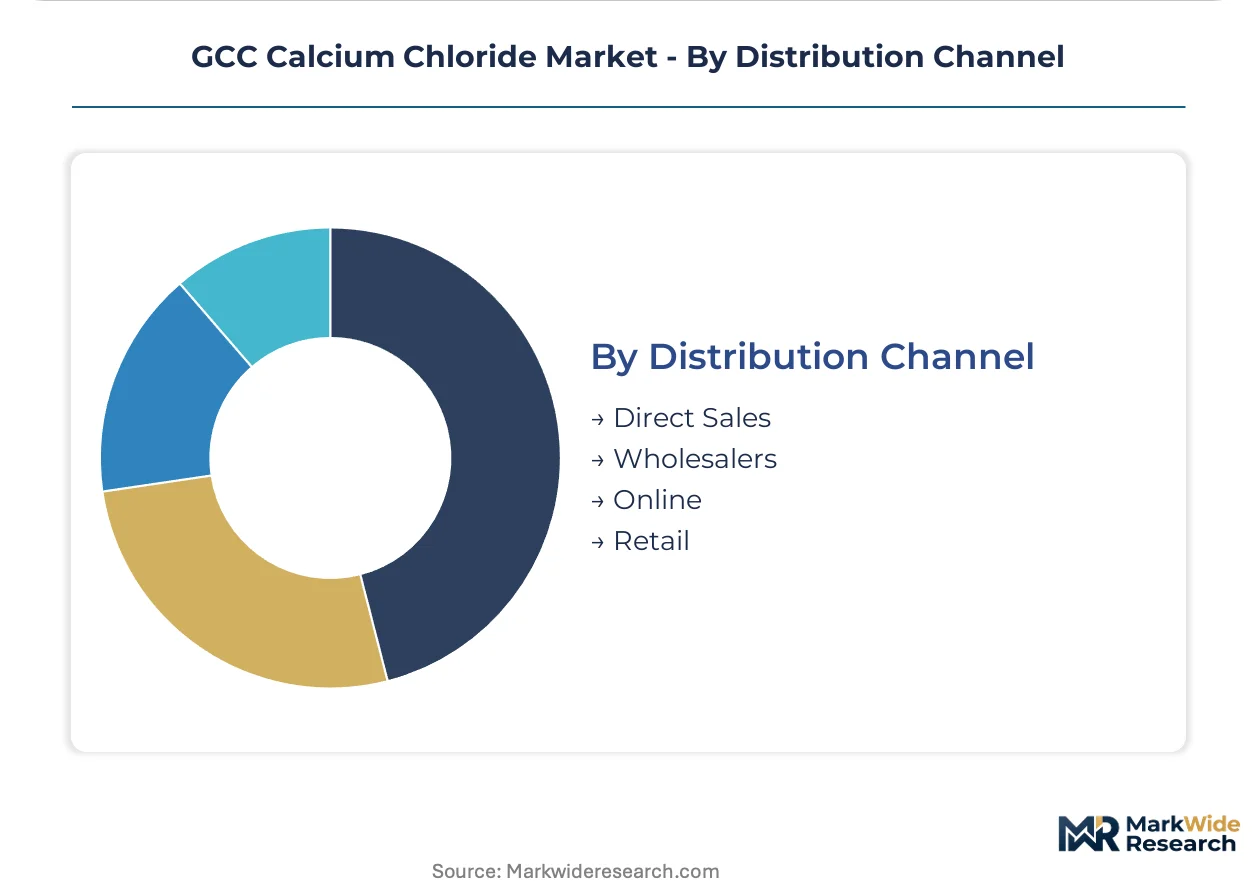
- Direct Sales:Long-term supply agreements with Saudi Aramco, Kuwait Oil Company, and major desalination operators eliminate intermediary margins for bulk liquid and granular formats.
- Wholesalers:Construction sector spot purchasing across Bahrain and smaller Emirates relies on Dubai-based distributors for flexible delivery quantities and credit terms.
- Online:E-procurement platforms capture emerging share from mid-sized contractors and agricultural cooperatives seeking price transparency and rapid order fulfillment.
- Retail:Bagged flake and pellet formats for residential de-icing and small-scale agricultural use move through hardware and agricultural supply stores in urban Saudi and UAE markets.
Direct Sales commands the dominant share, while Online channels are expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports bulk liquid calcium chloride to Kuwait's Burgan field operations and UAE's offshore drilling clusters, establishing a regional trade corridor anchored by Eastern Province production capacity. This cross-border flow shapes procurement patterns across the Gulf Cooperation Council.
Saudi Arabia
Oilfield completion fluid contracts from Saudi Aramco and desalination brine valorization at Jubail sustain concentrated demand. SASO's Technical Regulation for Industrial Chemicals mandates REACH-aligned safety documentation for all imports. The Eastern Province petrochemical corridor hosts spray-drying facilities producing pharmaceutical-grade flake for Dubai's pharmaceutical free zone.
United Arab Emirates
Dubai's Jebel Ali pharmaceutical cluster and Abu Dhabi's food processing sector drive high-purity flake procurement. MOHAP enforces FSSAI-aligned import standards that filter uncertified suppliers from food preservation applications. Ras Al-Khair desalination facilities are piloting circular chloride recovery as alternative feedstock for regional chemical producers.
Kuwait
Burgan field drilling operations and municipal road de-icing programs generate dual-demand streams for liquid and granular formats. The Public Authority for Industry administers industrial chemical registration with 14-18 week certification timelines. Ahmadi Governorate warehouses serve as distribution nodes for spot purchasing by smaller contractors.
Qatar
North Field expansion infrastructure and food security investments are accelerating calcium chloride consumption for concrete acceleration and agricultural foliar supplementation. The Ministry of Municipality and Environment regulates dust control chemical discharge from mining haul roads. Doha-based distributors consolidate construction sector procurement through credit-extended supply agreements.
Bahrain
Municipal road authorities favor magnesium chloride substitution during budget-constrained procurement cycles, compressing calcium chloride market share. The Ministry of Works maintains seasonal tender schedules tied to winter weather forecasts. Manama's construction sector relies on Dubai-based wholesalers for flexible spot purchasing of bagged flake formats.
GCC Calcium Chloride Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that fragments into compliance-driven specialty tiers and price-sensitive commodity streams. Occidental Chemical Corporation leverages integrated chlor-alkali operations for cost leadership, while TETRA Technologies bundles oilfield services to anchor regional positioning. Solvay differentiates through high-purity flake production. Strategic moves concentrate on purification technology licensing and direct-to-refinery digital channel development.
Within the integrated chemical conglomerate tier, Occidental Chemical Corporation and Solvay exemplify divergent positioning—one emphasizing captive chlorine supply economics, the other pharmaceutical-grade specialization. Among oilfield service bundlers, TETRA Technologies, Inc. occupies a position tied to completion fluid contract integration. Chinese manufacturers Quzhou Menjie Chemicals Co., Ltd. and Weifang Haibin Chemical Co., Ltd. represent commodity-grade supply archetypes serving construction and de-icing price sensitivity. Canadian specialists Tiger Calcium Services Inc. and Ward Chemical Ltd. sit within regional road treatment expertise segments. Russian supplier Zirax Limited and UAE-based BJ Services Company exemplify geographic proximity plays for Gulf procurement.
| Leading Market Players |
|---|
| Tiger Calcium Services Inc. |
| Zirax Limited |
| Occidental Chemical Corporation |
| Quzhou Menjie Chemicals Co., Ltd. |
| Weifang Haibin Chemical Co., Ltd. |
| TETRA Technologies, Inc. |
| Ward Chemical Ltd. |
| BJ Services Company |
| Solvay |
| Others |
Cost & Logistics Intelligence
European chlor-alkali input concentration ties Gulf calcium chloride margin pools to Amsterdam-Rotterdam-Antwerp energy arbitrage, forcing regional producers to absorb hydrochloric acid and limestone cost volatility or surrender share to integrated operators with captive chlorine.
Pricing Analysis
Spray-drying technology-generation pricing gaps separate pharmaceutical-grade flake premiums from rotary kiln commodity output, with sub-1% moisture specification commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on SASO certification tier and volume scale, with bulk liquid contracts for Saudi Aramco showing lowest sensitivity. Cost compression in construction-grade liquid intensifies because magnesium chloride substitution erodes municipal road treatment budgets.
Supply Chain Analysis
Contract-manufacturing concentration sits with Jubail petrochemical cluster toll processors and Dubai-based third-party laboratories handling SASO documentation. Geographic supply concentration centers on Saudi Arabia, the UAE, and Chinese commodity exporters. Raw material dependencies draw from European chlor-alkali byproduct streams, Saudi limestone deposits, and hydrochloric acid spot markets. Single-source vulnerability runs through Eastern Province production for oilfield completion fluid grade. Distribution runs through direct tanker delivery to Aramco terminals and Dubai wholesaler networks for construction spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital procurement platform integration at Saudi Aramco and Kuwait Oil Company signals platform-economics inflection, where vendor portal interoperability disintermediates traditional oilfield service bundlers and rewards direct supplier relationships.
For Market Incumbents: Pre-empt magnesium chloride substitution in Bahrain and smaller Emirates by securing multi-year municipal road treatment contracts before budget cycles favor lower-cost alternatives. Backward integration into captive chlor-alkali capacity at Jubail insulates margin position from European energy volatility. Reinforce SASO certification capabilities to compress 14-18 week registration timelines for new entrants.
For New Entrants and Emerging Players: Qatar's North Field expansion infrastructure and food security investments represent underpenetrated white-space for concrete acceleration and agricultural foliar supplementation. Pharmaceutical-grade flake production for Dubai's Jebel Ali cluster offers certification-barrier entry with REACH-aligned documentation. Partner with UAE free zone processors for toll manufacturing to bypass direct SASO registration requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional oilfield service bundlers facing disintermediation from direct-to-refinery digital channels. Long-term viability favors operators with integrated chlor-alkali economics or pharmaceutical-grade purification technology. Monitor Saudi Aramco vendor portal onboarding velocity as inflection indicator for distributor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive chlorine supply at Jubail insulates Occidental Chemical from European energy volatility. |
| Pharmaceutical-Grade Certification | USP-grade flake production unlocks Dubai Jebel Ali pharmaceutical cluster offtake. |
| Direct-to-Refinery Digital Channel | Aramco vendor portal integration disintermediates TETRA Technologies' service bundling. |
| Desalination Brine Valorization | Circular chloride recovery at Ras Al-Khair threatens traditional Solvay-process feedstock economics. |
| SASO Certification Consolidation | Dubai-based third-party laboratory partnerships compress 14-18 week registration barriers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and SASO regulatory bulletins. Interviews with chlor-alkali plant managers, Saudi Aramco procurement leads, Dubai-based distribution channel partners, and technical R&D directors at desalination operators informed demand-side validation. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments across the analysis window.
Forecast inputs span grade tier segmentation, end-use industry absorption rates, packaging format economics, and regional production hub capacity utilization. CAGRs derive from regression against oilfield drilling intensity, infrastructure spending cycles, and regulatory enforcement trajectory. Industry-specific variables include desalination brine valorization pilot scale-up and REACH-aligned purity standard adoption velocity.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese commodity exporters or accelerated circular recovery deployment at Saudi desalination plants would shift outcomes. Quarterly review of Aramco vendor portal supplier onboarding rates and SASO certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market