
 Recurring Payments Market | 2026-2036
Recurring Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Recurring Payments Market Analytics
Enterprise buyer concentration is hardening as mid-market SaaS vendors and fitness chains consolidate onto unified billing platforms rather than fragmented point solutions. Stripe Inc. leverages developer-first APIs to anchor subscription onboarding workflows for high-growth software companies. PayPal Holdings Inc. sustains consumer trust networks that reduce churn in installment and membership models. Adyen N.V. competes on unified commerce rails that bridge online recurring billing with in-person payment acceptance.
Recurring payments are automated, scheduled fund transfers executed at fixed intervals through tokenized credentials stored by a merchant or payment service provider, typically governed by pre-authorized debit agreements or card-on-file protocols that reduce friction and improve collection predictability. The subscription payment model dominates value generation due to its entrenched position in software and media verticals, while the digital wallet payment method represents the fastest structural expansion as tokenized mobile credentials displace card-not-present friction. Monthly billing frequency occupies the largest transaction volume pool, though annual prepay structures command superior margin profiles through reduced processing cost ratios.
PCI DSS standards enforced by the card networks mandate encrypted credential vaulting and breach liability frameworks that elevate infrastructure costs for non-compliant entrants. The EU's PSD2 and open banking APIs administered by national regulators in Germany, France, and the Netherlands are displacing traditional card-on-file dominance with account-to-account alternatives. Stakeholders must monitor regulatory divergence between card-network compliance regimes and emerging real-time payment mandates to preserve cross-border billing architecture flexibility.
Market Dynamics
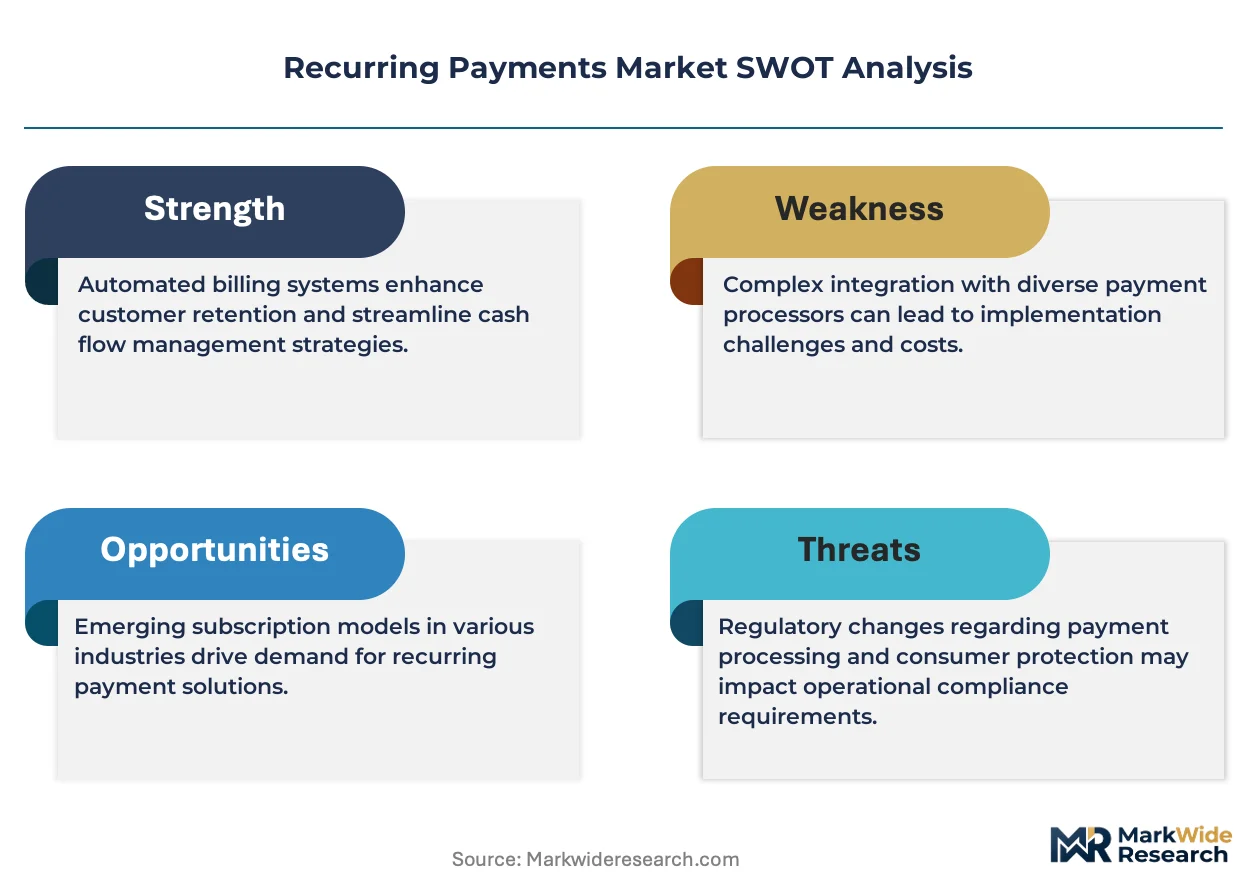
Tokenized credential vaulting and real-time account-to-account settlement rails are compressing payment friction to near-zero, forcing infrastructure providers to rebuild core architectures around open banking APIs rather than legacy card-network dependencies.
Growth Catalysts
- PSD2 Mandates:The European Union's open banking framework compels financial institutions to expose payment initiation APIs, accelerating merchant adoption of direct debit alternatives that bypass interchange fees entirely.
- SaaS Subscription Density:Vertical software providers in property management, fitness, and professional services are hardwiring automated billing into customer onboarding flows, creating embedded payment demand that locks in recurring revenue streams.
- Mobile Wallet Tokenization:Apple Pay and Google Pay credential storage is electrifying consumer willingness to authorize recurring charges, reducing checkout abandonment for subscription sign-ups.
Market Restraints
- PCI DSS Compliance Burden:Card network encryption standards mandate annual audits and breach liability frameworks that consume 15-25% of infrastructure operating budgets for non-specialist entrants.
- Banking Rail Fragmentation:Real-time payment schemes remain nationally siloed—FedNow in the United States, SEPA Instant in the Eurozone, Faster Payments in the United Kingdom—preventing seamless cross-border recurring settlement without correspondent banking layers.
- Chargeback Exposure:Card-not-present recurring transactions carry elevated dispute ratios that trigger reserve holds and processing rate penalties, compressing net margins for high-churn verticals.
Strategic Opportunities
- Brazilian Open Finance:PIX instant payment infrastructure and Central Bank of Brazil API mandates are creating a greenfield market for account-to-account recurring billing without card-network intermediation.
- Healthcare Subscription Models:Direct-to-consumer telehealth and medication delivery services are piloting recurring payment structures for chronic condition management, expanding beyond traditional insurance billing.
- AI-Powered Dunning:Machine learning models predicting payment failure before charge attempts are enabling intelligent retry scheduling that reduces involuntary churn without human intervention.
Industry Challenges
- Credential Lifecycle Management:Expired card updates and bank account closures require continuous data synchronization across merchant vaults, payment processors, and issuer systems, creating operational complexity at scale.
- Cross-Jurisdictional Tax Compliance:Subscription merchants selling across United States, United Kingdom, and German markets face divergent VAT and sales tax calculation rules that demand real-time localization engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recurring Payments Market |
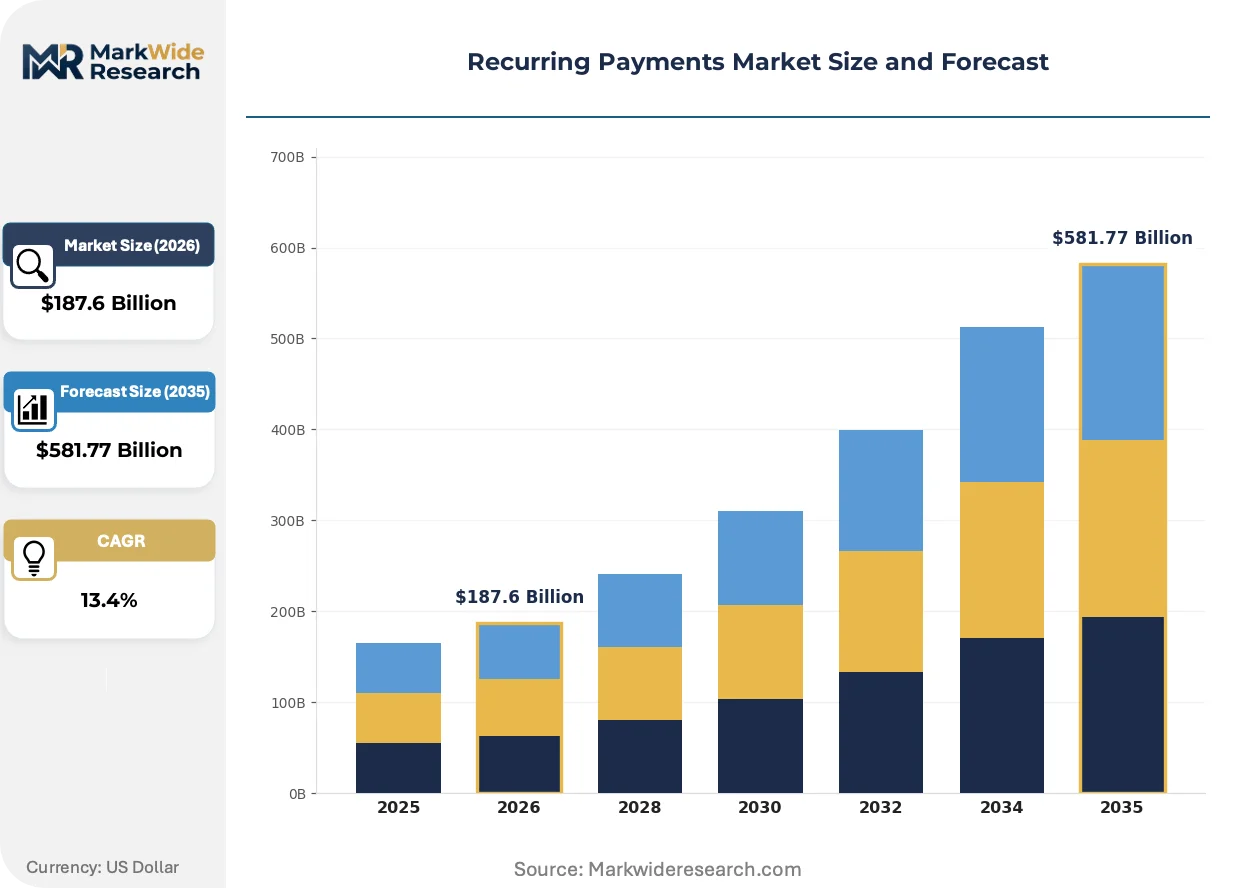
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $581.77 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Model: Subscription, Installment, Membership, Lease Industry Vertical: Media & Entertainment, E-commerce, SaaS, Fitness Billing Frequency: Monthly, Quarterly, Annually, Weekly Payment Method: Credit Card, Direct Debit, Digital Wallet, Bank Transfer |
| Companies Covered | Stripe Inc., PayPal Holdings Inc., American Express Company, Adyen N.V., Square Inc., Zuora Inc., Recurly Inc., Chargebee Inc., Klarna Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recurring Payments Market Evolving Landscape
Real-time payment infrastructure and machine learning orchestration layers are displacing batch-processed card billing as the default architecture, compressing settlement timelines from days to seconds while raising the technical bar for market entry.
Network tokenization is electrifying credential security by replacing primary account numbers with device-bound cryptograms that render intercepted data useless to fraudsters. Mid-market SaaS vendors are adopting this standard fastest, pressured by liability shift deadlines from major card networks. The structural consequence is collapsing merchant fraud losses while elevating infrastructure costs for providers lacking direct issuer integrations.
The EU's Digital Operational Resilience Act (DORA) mandates critical ICT risk management standards for payment service providers, effective January 2025. Financial entities must map third-party dependencies and maintain 24-hour recovery capabilities. European neobanks and payment facilitators are reconfiguring vendor contracts and redundancy architectures to meet these binding requirements.
Usage-based billing models are displacing flat-rate subscriptions in developer tools and cloud infrastructure verticals. Procurement committees now demand consumption-aligned pricing that ties payments to measurable value delivery. This shift is most pronounced in United States enterprise software, where finance teams are rejecting prepaid annual contracts in favor of monthly metered arrangements with transparent usage dashboards.
Recurring Payments Market Segmentation
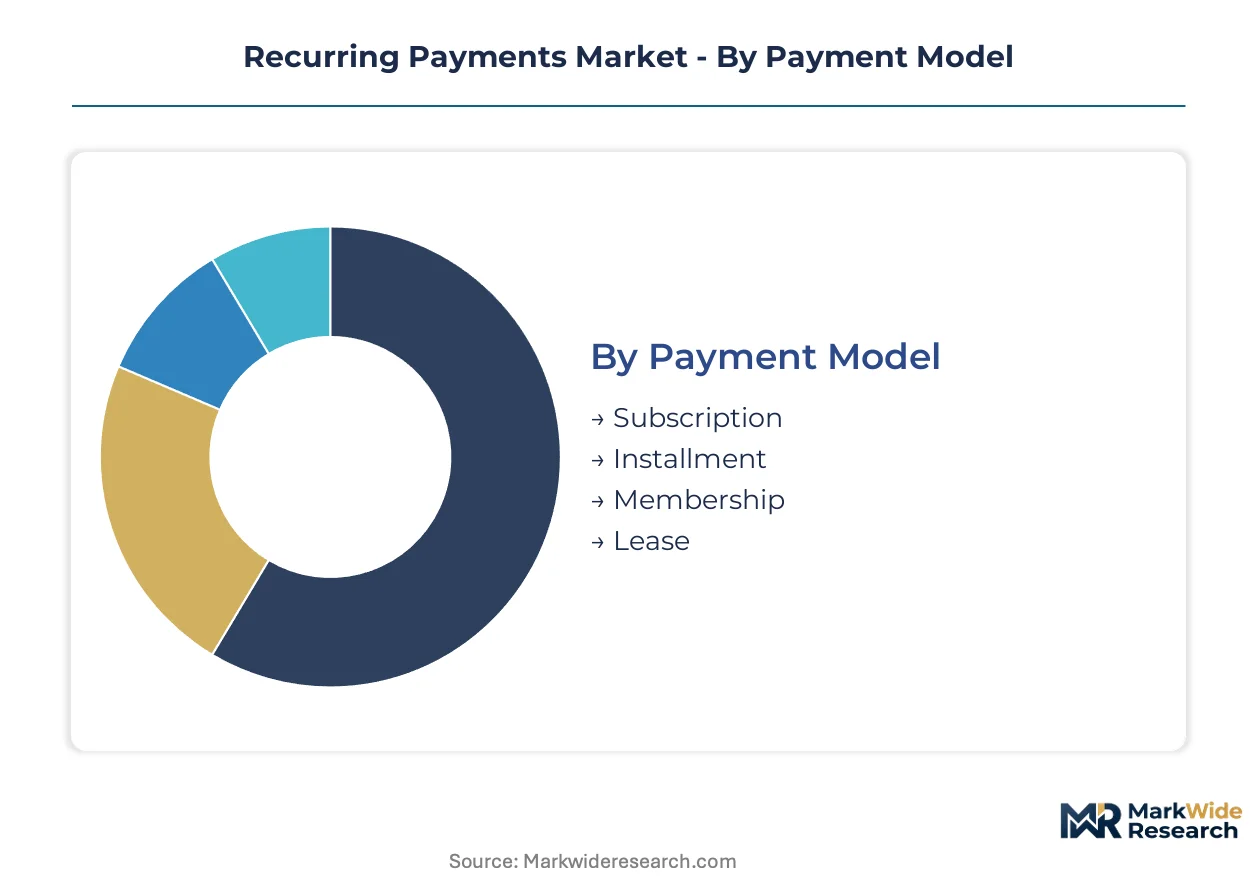
Recurring payments infrastructure varies dramatically across billing architectures, with each segment demanding distinct compliance protocols and technical integrations. Merchants optimize for different cost structures and customer retention profiles depending on which segmentation dimension they prioritize.
Payment Model:
Upgrade cycles from legacy invoicing to automated recurring architectures reshape competitive positioning across merchant tiers.
- Subscription:Pre-authorized periodic charges for continuous service access dominate software and media verticals. SaaS vendors in the United States embed these flows into onboarding to lock annual contract values. Subscription sits at the top of the volume ranking, with Installment climbing the fastest.
- Installment:Split-payment structures for single purchases spread cost burden across pay periods. Buy-now-pay-later providers in Germany leverage PSD2 account-to-account rails to bypass card interchange entirely.
- Membership:Access-based recurring fees for clubs, associations, and loyalty programs. Fitness chains in the United Kingdom consolidate fragmented point solutions onto unified platforms.
- Lease:Equipment and vehicle financing with automated end-of-term renewal workflows. Commercial lessors demand PCI DSS vaulting for high-value asset portfolios.
Subscription commands the largest transaction pool, while Installment gains share fastest among high-ticket retail verticals.
Industry Vertical:
Cost tier differentiation separates premium integrated stacks from basic gateway implementations.
- Media & Entertainment:Streaming platforms and publishing subscriptions require global tax calculation engines for multi-jurisdictional billing. Netflix-scale operators in the United States build proprietary dunning systems.
- E-commerce:Replenishment and membership box models demand flexible pause-skip-cancel logic. Direct-to-consumer brands in Germany face strict GDPR consent requirements for stored credentials.
- SaaS:Usage-based billing integration with product analytics drives developer tool pricing. Enterprise procurement committees in the United States reject prepaid annual contracts for metered alternatives.
- Fitness:Hybrid in-person and digital membership billing bridges POS and online channels. Boutique studios in the United Kingdom adopt Apple Pay tokenization to reduce checkout abandonment.
SaaS generates the highest revenue per transaction, with Fitness expanding most quickly as post-pandemic hybrid models stabilize.
Billing Frequency:
Customer type separates enterprise procurement teams from individual consumer authorization patterns.
- Monthly:Standard SaaS and subscription box cadence optimizes cash flow predictability for mid-market merchants. Property management platforms in the United States automate rent collection on this rhythm.
- Quarterly:B2B software and professional services align billing with customer budget cycles. Consulting firms in Germany structure retainers around fiscal quarters.
- Annually:Prepay structures reduce processing cost ratios and improve net margins. High-growth startups in the United Kingdom offer discounts to lock annual commitments.
- Weekly:Gig economy and on-demand service platforms match payment cycles to earnings patterns. Delivery apps in the United States settle driver payouts on compressed timelines.
Monthly occupies the dominant volume position, with Annually delivering superior margin profiles through reduced per-transaction overhead.
Payment Method:
Maturity curves separate established card networks from emerging open banking alternatives.
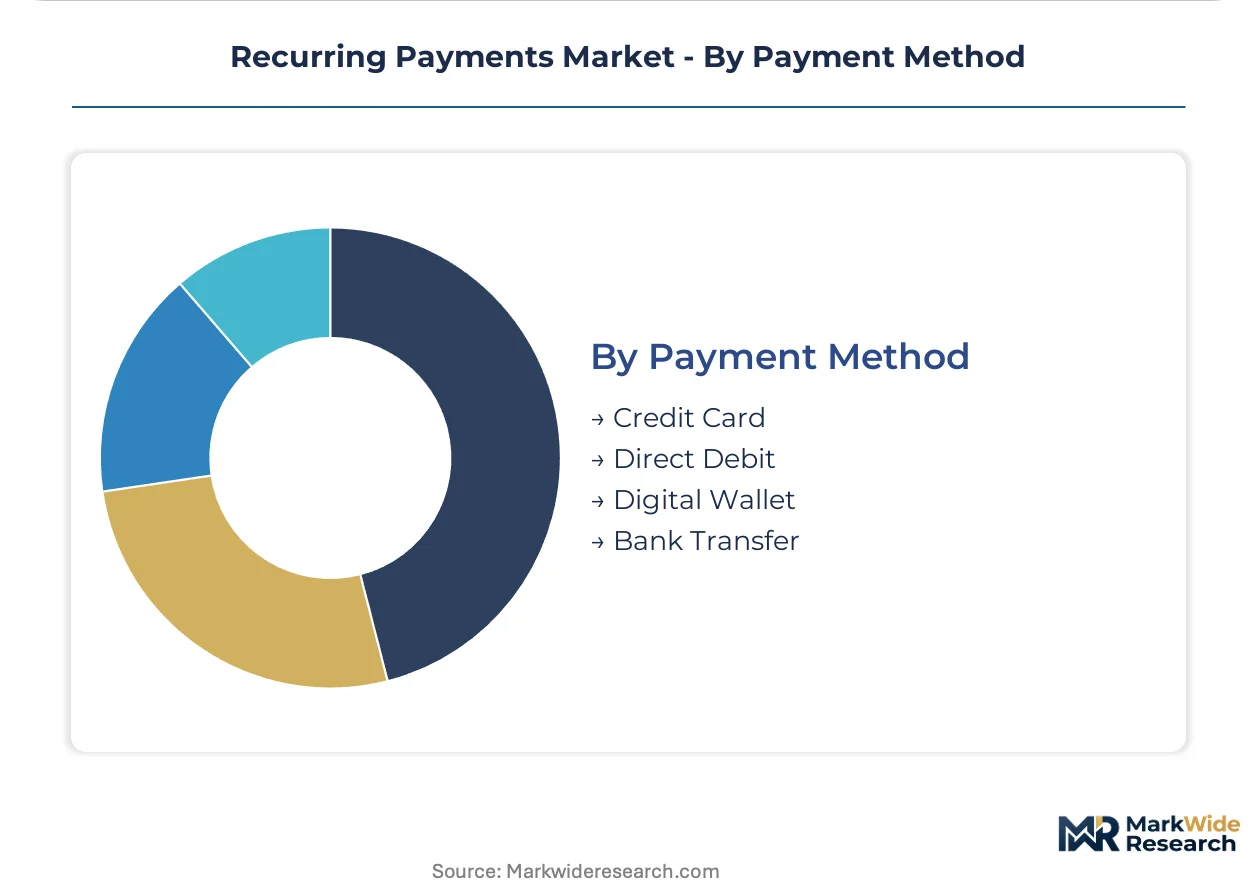
- Credit Card:Card-on-file protocols with network tokenization remain default for cross-border commerce. PCI DSS compliance costs consume significant infrastructure budgets for non-specialist entrants.
- Direct Debit:Pre-authorized bank account pulls dominate utility and telecom verticals with predictable billing. SEPA mandates in Germany and the Netherlands accelerate account-to-account adoption.
- Digital Wallet:Apple Pay and Google Pay credential storage electrifies mobile subscription sign-ups. Tokenized mobile credentials displace card-not-present friction fastest in the United States and United Kingdom.
- Bank Transfer:Real-time settlement via FedNow and PIX instant rails compresses timelines from days to seconds. Brazilian Central Bank API mandates create greenfield recurring infrastructure without card intermediation.
Credit Card retains volume leadership, with Digital Wallet gaining share fastest as mobile-first checkout becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher recurring payment transaction volumes than Germany, though both markets are converging on open banking API standards that bypass traditional card-network rails entirely.
United States
SaaS vendors and streaming platforms drive automated billing adoption across the country. FedNow instant payment infrastructure from the Federal Reserve compresses settlement timelines for account-to-account transfers. Silicon Valley and New York City host dense clusters of fintech infrastructure providers building tokenized credential vaults for subscription merchants.
Germany
SEPA Direct Debit dominates utility and telecom billing, with merchants leveraging PSD2-mandated APIs for lower-cost alternatives to card processing. BaFin supervision enforces strict authentication protocols for recurring payment authorizations. Berlin and Frankfurt concentrate neobank and payment facilitator operations reconfiguring systems for DORA resilience requirements effective January 2025.
United Kingdom
Fitness chains and boutique studios consolidate fragmented billing onto unified platforms with hybrid POS-online capabilities. Faster Payments infrastructure supports real-time settlement for account-to-account recurring transfers. London anchors the highest density of subscription billing technology vendors serving European and Commonwealth markets.
Brazil
PIX instant payment rails from the Central Bank of Brazil enable greenfield recurring billing infrastructure without card-network intermediation. Open Finance API mandates accelerate merchant migration to direct account-to-account models. São Paulo hosts the dominant concentration of fintech infrastructure builders targeting Latin American recurring payment automation.
Netherlands
SEPA Instant adoption runs highest among EU member states, with merchants leveraging real-time settlement for subscription and installment billing. Dutch Banking Association standards govern credential vaulting security for automated payment agreements. Amsterdam concentrates payment service providers building cross-border billing architectures for Benelux and German markets.
Recurring Payments Market Competitive Landscape
United States-based technology platforms anchor the developer-centric tier; European specialists hold the regulated infrastructure tier with deeper open banking integrations. Market structure splits between consolidated gateway providers serving enterprise merchants and fragmented vertical-specific billing platforms targeting mid-market SaaS vendors. Three archetypes dominate: API-first infrastructure builders, unified commerce rails bridging online and in-person channels, and subscription management specialists with dunning optimization. Competitive moves center on M&A to acquire tokenization capabilities and strategic partnerships to embed billing into vertical software workflows.
Within the API-first infrastructure tier, Stripe Inc. and Square Inc. exemplify developer-centric positioning that anchors subscription onboarding for high-growth software companies. PayPal Holdings Inc. occupies consumer trust network architecture that reduces churn in installment and membership models. Adyen N.V. represents unified commerce rails that bridge online recurring billing with in-person payment acceptance across European and North American markets.
| Leading Market Players |
|---|
| Stripe Inc. |
| PayPal Holdings Inc. |
| American Express Company |
| Adyen N.V. |
| Square Inc. |
| Zuora Inc. |
| Recurly Inc. |
| Chargebee Inc. |
| Klarna Inc. |
| Others |
Value Network & Pricing Analysis
Interchange fee compression in the European Union flows through to merchant-facing pricing tiers, with PSD2-mandated account-to-account rails undercutting card-network cost structures by eliminating scheme fees entirely. Infrastructure providers pass these savings to SaaS vendors and subscription platforms while absorbing PCI DSS compliance overhead through tiered service packaging.
Pricing Analysis
Capacity additions in Brazil and the Netherlands are reshaping price floors for real-time recurring settlement infrastructure. Three-tier pricing structure across premium, standard, and economy levels segments merchants by transaction volume and vaulting complexity. Price differentiation hinges on tokenization certification grade and cross-border settlement capability. Pricing pressure stems from open banking API commoditization in SEPA and PIX markets. Mid-market SaaS vendors exhibit highest price sensitivity, while enterprise streaming platforms prioritize reliability over per-transaction cost.
Supply Chain Analysis
Cross-border data center latency and subsea cable routing costs influence infrastructure provider site selection for credential vaulting operations. Supply concentrates in the United States, Germany, and the United Kingdom for core payment processor operations, with Brazil and the Netherlands emerging for real-time rail integration. Raw material dependencies include cryptographic hardware security modules, cloud compute capacity, and fiber network capacity. Single-source vulnerability runs through SWIFT correspondent banking layers for cross-currency settlement. Distribution runs through API-first platform integrations and direct merchant sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between PCI DSS audit jurisdictions and open banking API standardization costs creates geographic positioning advantages for infrastructure providers. Merchants in Germany face BaFin supervision expenses that United States counterparts avoid, while Brazilian PIX mandates offer greenfield cost structures.
For Market Incumbents: Acquire tokenization technology specialists to anchor credential vaulting capabilities against emerging account-to-account challengers. Consolidate fragmented dunning optimization vendors to lock subscription management workflows. Vertical integration into real-time settlement infrastructure in Brazil and the Netherlands defends margin position as card-network interchange erodes.
For New Entrants and Emerging Players: AI-powered payment failure prediction offers a technology-first wedge into involuntary churn reduction for mid-market SaaS vendors. White-space targets include healthcare subscription billing for chronic condition management and usage-based developer tool pricing. The most penetrable segment spans United Kingdom fitness chains consolidating fragmented point solutions. Go-to-market through embedded billing partnerships with vertical software platforms accelerates customer acquisition.
For Investors and Strategic Acquirers: Consolidation pressure builds where DORA resilience requirements and PCI DSS compliance burdens simultaneously elevate fixed costs for sub-scale payment facilitators. Long-term viability favors infrastructure providers with direct issuer integrations and multi-rail architecture spanning card, open banking, and real-time settlement. Target acquisition archetype: European neobanks with PSD2 API infrastructure and BaFin licensing. Signal to watch: reserve hold tightening by card networks on high-churn verticals indicating underwriting discipline shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding billing workflows into property management and fitness software locks recurring revenue streams. |
| Acquisition of Specialist Firm | Tokenization vendors with direct issuer relationships collapse fraud liability for subscription merchants. |
| Strategic Partnership | FedNow and SEPA Instant rail access compresses settlement timelines from days to seconds. |
| Geographic Expansion | Brazilian PIX infrastructure offers greenfield recurring billing without card-network intermediation. |
| Product Launch | AI-powered dunning optimization reduces involuntary churn through intelligent retry scheduling. |
Research Methodology
Bottom-up merchant vertical modeling reconciled against top-down infrastructure provider tracking forms the analytical core of this study. Primary interviews with payment operations executives, SaaS CFOs, platform engineers, and regulatory compliance officers combined with secondary validation against SEC filings, central bank API documentation, and card network scheme rules. Data synthesis draws from BaFin supervision reports, Brazilian Central Bank Open Finance disclosures, and European Banking Authority PSD2 implementation assessments. Top-down and bottom-up estimates triangulate through cross-referencing transaction volume disclosures with credential vaulting capacity announcements.
Input-output matrices map payment method adoption curves against regulatory mandate timelines across the projection horizon. Segmentation dimensions modeled include payment model architecture, billing frequency cadence, industry vertical compliance requirements, and geographic rail availability. CAGRs derive from curve-fitting historical adoption patterns against infrastructure deployment schedules. Forecast inputs incorporate FedNow rollout velocity, DORA implementation compliance costs, and PIX merchant onboarding rates.
The model holds under stable regulatory enforcement intensity; deviation in card-network liability shift deadlines or open banking API standardization fragmentation would shift merchant migration timelines. Forecasts reflect documented assumptions about interchange fee trajectories and real-time rail interoperability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Medical Payment Fraud Detection Market
Payments
South Africa Real Time Payments Market
Payments
India Gift Card and Incentive Card Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Middle East and Africa Payments Market
Payments
Voice-Based Payments Market
Payments
Europe POS Terminal Market
Payments
China Forex Cards Market
Payments
United States Payment Gateways Market
Payments
B2B Payments Platform Market
Payments
Latin America Mobile Payment Market
Payments
Romania POS Terminals Market
Payments
Singapore Remittance Market
Payments
United Kingdom Payment Gateway Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Buy Now Pay Later Platform Market