
 Sweden Mobile Payments Market | 2026-2036
Sweden Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Mobile Payments Market Analytics
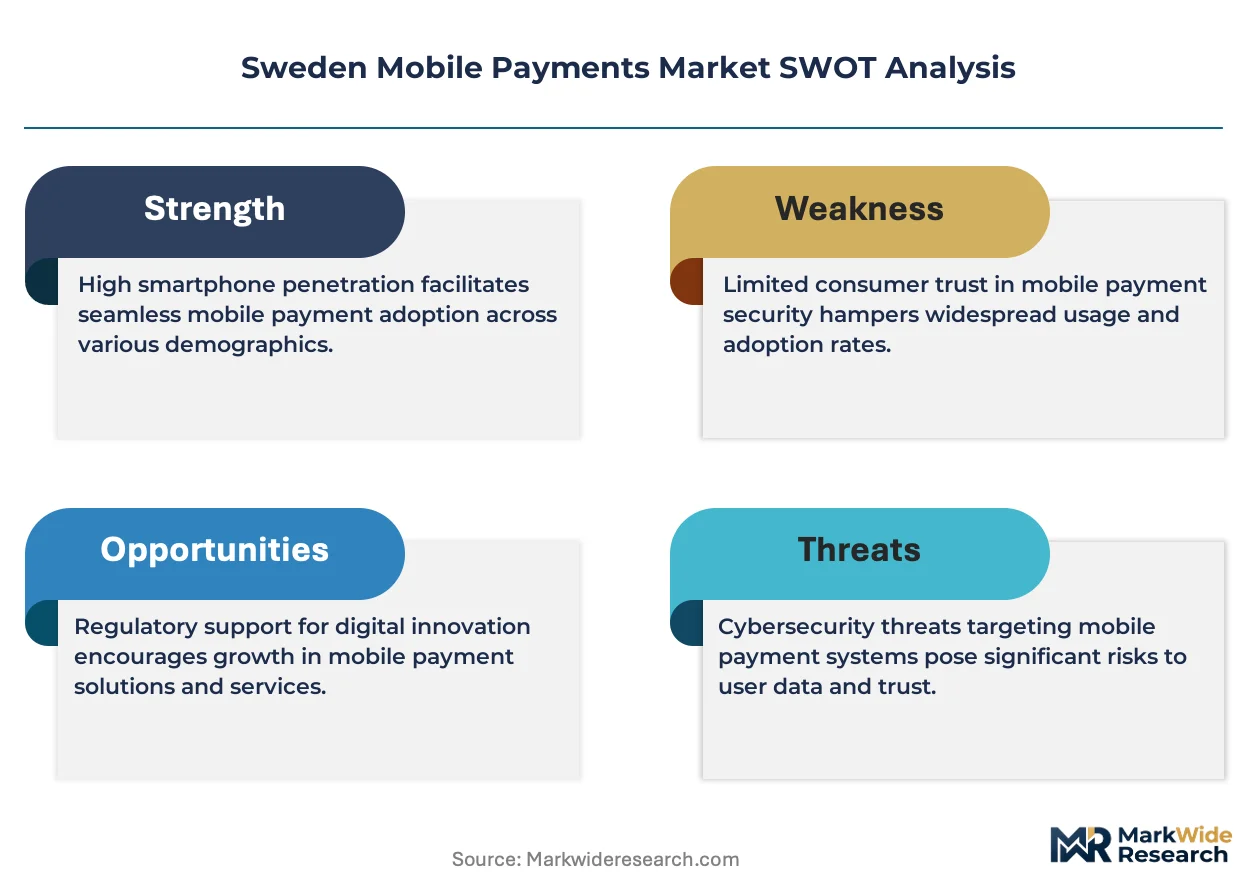
PCI DSS Level 1 certification is reorganizing competitive access among Sweden's mobile payment providers. Swish leverages its bank-backed consortium structure to dominate domestic P2P transfers. Klarna anchors its position through buy-now-pay-later integration embedded directly at merchant checkouts. Trustly Group competes via account-to-account payment rails that bypass card networks entirely.
Sweden mobile payments encompass digital fund transfers executed through smartphone applications, relying on NFC protocols, tokenized credential vaulting, and real-time bank integration to replace physical card-present transactions. These systems serve commercial purpose by collapsing checkout friction while reducing merchant interchange exposure. Mobile wallet deployments lead transaction volume growth as consumers consolidate credentials into single-application interfaces. Bank transfer mechanisms capture expanding share among subscription billing use cases where merchants seek lower processing costs. Biometric login features now differentiate premium platform tiers as security expectations harden across user demographics.
The Swedish Financial Supervisory Authority enforces PSD2 compliance on all payment service providers, while Finansinspektionen mandates operational resilience standards for critical infrastructure operators. GDPR and Sweden's national data protection framework constrain how transaction behavioral data circulates between merchants and platform operators. Stakeholders must monitor how open banking API standardization alters the economics of payment routing decisions.
Market Dynamics
PSD2-mandated open banking API standardization is dismantling Sweden's legacy payment infrastructure, forcing real-time account-to-account rails to displace card-network dependency across merchant acceptance stacks.
Growth Catalysts
- EU Open Banking Framework:PSD2 compliance requirements compel Swedish banks to expose standardized payment initiation APIs, enabling third-party fintechs to embed account-to-account transfers at merchant checkouts.
- Small Business Merchant Adoption:Sweden's retail corridor micro-merchants now anchor volume expansion as low-cost mobile POS solutions replace traditional terminal infrastructure.
- NFC Protocol Maturation:Contactless tokenized credential vaulting achieves sub-500 millisecond transaction speeds, collapsing checkout friction in Stockholm's high-throughput urban retail environments.
Market Restraints
- Interchange Rate Compression:Account-to-account payment rails eliminate card network fees entirely, squeezing revenue pools available to platform operators for reinvestment.
- Bank Consortium Concentration:Sweden's mobile payment infrastructure remains captive to the bank-backed Swish consortium, creating single-point-of-failure risk for domestic P2P liquidity.
- GDPR Data Circulation Constraints:Sweden's national data protection framework restricts behavioral transaction data sharing between merchants and platform operators, limiting personalization revenue streams.
Strategic Opportunities
- Subscription Billing Vertical:Bank transfer mechanisms capture expanding share among Swedish SaaS and media merchants seeking lower processing costs for recurring revenue models.
- Biometric Authentication Tiering:Fingerprint and facial recognition features now differentiate premium platform tiers as security expectations harden across Swedish user demographics.
- Gothenburg-Malmö Corridor Expansion:Demand concentration beyond Stockholm's fintech cluster offers white-space penetration in Sweden's second-tier urban retail corridors.
Industry Challenges
- Legacy Core Banking Integration:Real-time settlement requirements force Swedish banks to rearchitect decades-old batch-processing infrastructure, stretching IT modernization timelines.
- Operational Resilience Certification:Finansinspektionen mandates stringent uptime and failover standards for critical payment infrastructure, elevating compliance costs for platform operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Mobile Payments Market |
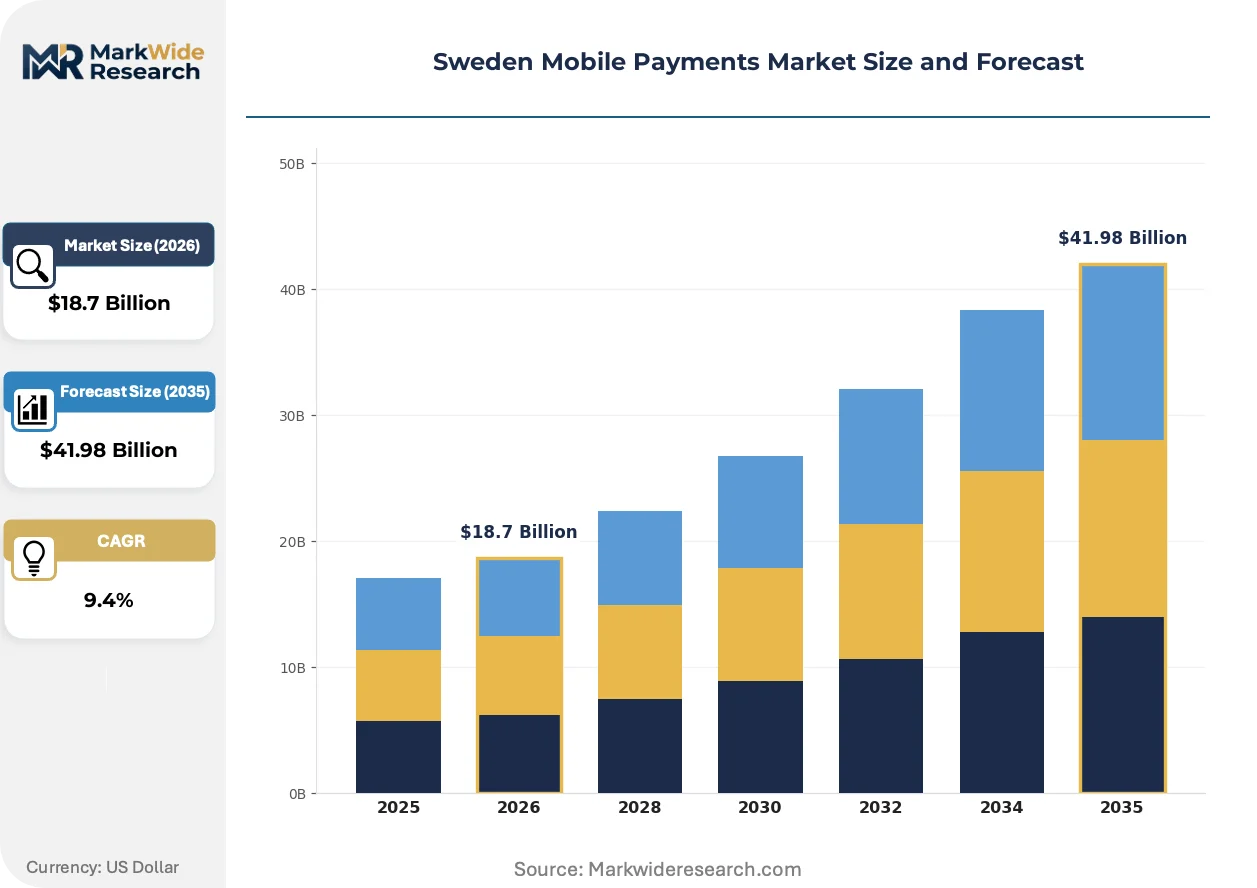
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer User Demographic: Students, Young Professionals, Small Businesses, Seniors Transaction Type: In-Store Payments, Online Purchases, P2P Transfers, Subscriptions Security Feature: Two-Factor Authentication, Biometric Login, Encryption, Tokenization |
| Companies Covered | Google Pay, PayPal, Swish, Bambora, Trustly Group, Klarna, Samsung Pay, Zimpler, Apple Pay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Mobile Payments Market Evolving Landscape
Tokenized credential vaulting architectures are actively dismantling Sweden's card-present transaction dominance, compressing merchant interchange exposure while enabling smartphone-native checkout experiences.
Decentralized identity verification is fragmenting Sweden's authentication stack. Biometric liveness detection and device-bound cryptographic keys now replace static passwords across premium mobile wallet tiers. Swedish fintechs deploy these rails to bypass traditional KYC document workflows. The structural consequence is compressing onboarding friction for neobank challengers while elevating compliance automation spend.
Finansinspektionen's operational resilience mandates are hardening infrastructure redundancy requirements. Swedish payment service providers must maintain 99.99% availability with sub-4-hour failover recovery windows. Critical infrastructure operators respond by diversifying cloud hosting across domestic and Nordic data center zones, elevating capex intensity for platform scaling.
Merchant procurement of payment acceptance is pivoting from terminal hardware ownership toward software-embedded checkout. Swedish retailers now demand single-application interfaces consolidating credentials, loyalty, and financing at point-of-sale. This pattern concentrates in Stockholm's fashion and electronics verticals where checkout speed directly correlates with cart abandonment rates.
Sweden Mobile Payments Market Segmentation
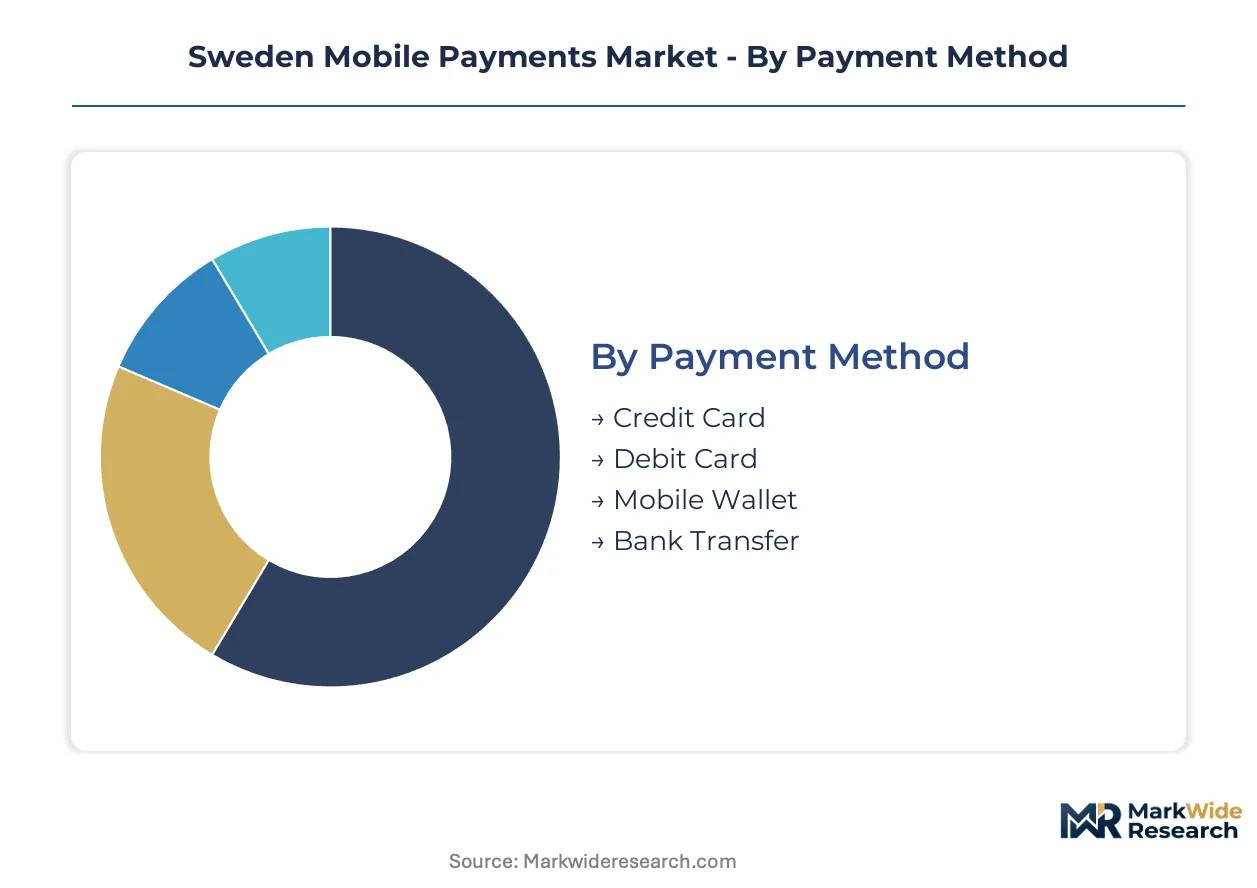
Sweden's mobile payment infrastructure fragments across four distinct segmentation axes, each governing how capital flows through Stockholm's fintech corridors versus retail micro-merchant networks. Payment method and transaction type segmentation determines routing economics between card networks and PSD2-enabled account-to-account rails.
Payment Method:
Channel mix across Sweden's payment infrastructure splits between legacy card-present rails and emerging open-banking alternatives, with merchant checkout integration determining which methods achieve transaction density.
- Credit Card:Revolving credit instruments maintain dominance in Stockholm's premium retail verticals where consumer financing drives basket size expansion. High interchange exposure concentrates demand among merchants with margin absorption capacity.
- Debit Card:Direct bank account debiting captures volume across Sweden's grocery and transit corridors where transaction velocity outweighs financing needs. SEB and Swedbank issuers anchor domestic debit credential distribution.
- Mobile Wallet:Smartphone-native credential vaulting consolidates multiple payment instruments into single-application interfaces. NFC-enabled tap-to-pay functionality drives adoption in urban retail environments.
- Bank Transfer:PSD2-initiated account-to-account rails bypass card networks entirely, capturing subscription billing volume among SaaS merchants seeking processing cost reduction.
By volume, Debit Card leads. By growth pace, Bank Transfer is ahead.
User Demographic:
Customer-type segmentation across Sweden mirrors generational digital-native penetration, with fintech adoption curves steepening among cohorts with neobank exposure.
- Students:University-affiliated populations drive peer-to-peer transfer volume through low-friction onboarding requirements. Campus-adjacent retail corridors in Uppsala and Lund concentrate merchant acceptance infrastructure.
- Young Professionals:Stockholm's tech sector workforce exhibits highest mobile wallet credential consolidation rates. Salary account integration with Klarna and Swish accelerates checkout habit formation.
- Small Businesses:Micro-merchants across Sweden's retail corridors anchor mobile POS adoption growth. Low-cost terminal replacement drives account-to-account payment acceptance.
- Seniors:Late-adopter demographic concentrates in rural counties where branch banking persists. Trustly's simplified interface design targets this cohort for digital migration.
Small Businesses generate highest transaction frequency per capita. Young Professionals show steepest expansion trajectory for emerging payment modalities.
Transaction Type:
Application-based segmentation determines infrastructure requirements, with real-time settlement demands varying sharply between physical presentment and digital origination.
- In-Store Payments:NFC-enabled smartphone tap-to-pay dominates Stockholm's high-throughput retail environments. Sub-500 millisecond transaction speed requirements compress checkout friction.
- Online Purchases:E-commerce checkout integration drives embedded finance adoption, with buy-now-pay-later options anchoring merchant conversion optimization.
- P2P Transfers:Person-to-person liquidity flows concentrate through bank-consortium infrastructure. Mobile phone number-based routing replaces traditional account detail entry.
- Subscriptions:Recurring billing use cases favor bank transfer rails where merchants prioritize processing cost reduction over authorization speed.
In-Store Payments maintain volume leadership. Subscriptions are gaining share fastest among merchant verticals.
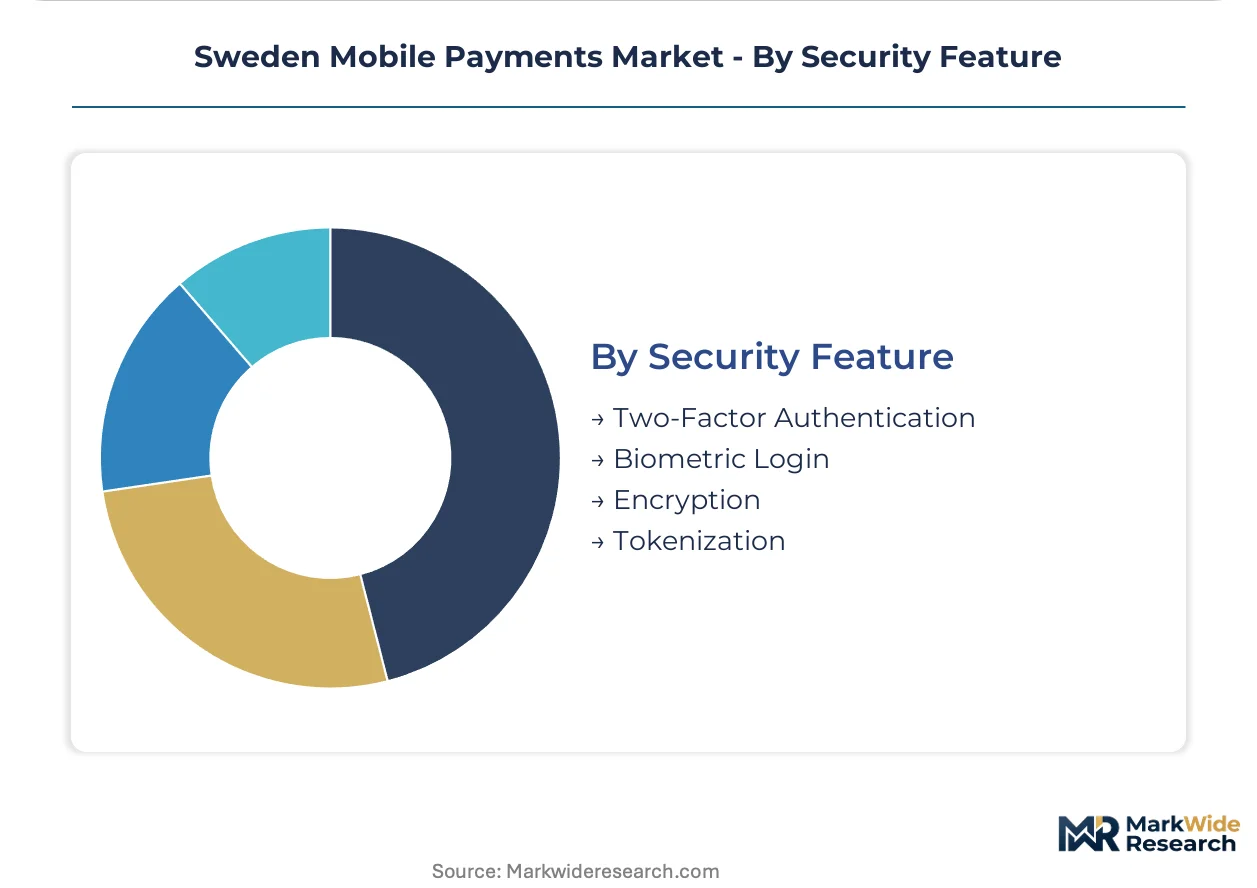
Security Feature:
Maturity-tiered segmentation governs platform premium positioning, with authentication sophistication separating baseline from differentiated service tiers.
- Two-Factor Authentication:SMS and email verification codes constitute baseline security across Swedish payment platforms. PSD2 strong customer authentication mandates elevate this to minimum viable standard.
- Biometric Login:Fingerprint and facial recognition features differentiate premium platform tiers. Device-bound cryptographic keys replace static password workflows.
- Encryption:Transport and data-at-rest encryption protocols secure credential transmission between merchant terminals and acquiring banks.
- Tokenization:Dynamic credential substitution replaces static card numbers, reducing breach exposure across merchant acceptance stacks.
Encryption underpins all transaction volume. Biometric Login is climbing the fastest among security-tier differentiators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norrsken fiber-optic backbone and Stockholm's data center interconnects anchor Sweden's mobile payment infrastructure across Nordic digital corridors.
Stockholm
SEB and Swedbank headquarters drive open banking API adoption among fintech challengers. Finansinspektionen mandates operational resilience standards for payment service providers operating critical infrastructure. The Kista Science City cluster concentrates neobank development and mobile wallet credential vaulting engineering.
Gothenburg
Port logistics and automotive supply chains generate B2B payment automation demand. GDPR compliance requirements constrain cross-border transaction data flows between merchant networks and platform operators. The Lindholmen Science Park hosts Trustly Group's account-to-account rail development operations.
Malmö
Øresund Bridge connectivity integrates Danish-Swedish payment corridors for cross-border P2P liquidity. The Swedish Financial Supervisory Authority enforces PSD2 strong customer authentication on all payment initiation services. The Möllan district retail corridor anchors mobile POS adoption among micro-merchants.
Uppsala
University-affiliated populations concentrate peer-to-peer transfer volume through low-friction onboarding protocols. Sweden's national data protection framework restricts behavioral transaction data circulation between campus-adjacent merchants and platform operators. The Fyrisån corridor hosts student-focused fintech pilot programs.
Linköping
Defense and aerospace supply chains drive secure payment authentication procurement. Finansinspektionen mandates sub-4-hour failover recovery windows for critical payment infrastructure operators. The Mjärdevi Science Park concentrates biometric liveness detection research for mobile wallet tiering.
Sweden Mobile Payments Market Competitive Landscape
Listed leaders compete with private specialists across bank-consortium and independent fintech dimensions. The market structure fragments between bank-backed infrastructure operators and venture-scaled challengers, with PCI DSS Level 1 certification creating tiered access barriers. Three archetypes dominate: domestic P2P consortium platforms, buy-now-pay-later embedded finance providers, and account-to-account rail specialists. Competitive moves concentrate on merchant checkout integration partnerships and biometric authentication tier differentiation.
Within the bank-consortium archetype, Swish anchors domestic P2P liquidity flows through its six-bank ownership structure. Klarna and Trustly Group occupy positions across the independent fintech tier, with Klarna exemplifying embedded checkout finance integration and Trustly Group representing account-to-account payment rail specialization. Google Pay and Apple Pay sit within the global platform vector, leveraging device-native credential vaulting to compress merchant onboarding friction.
| Leading Market Players |
|---|
| Google Pay |
| PayPal |
| Swish |
| Bambora |
| Trustly Group |
| Klarna |
| Samsung Pay |
| Zimpler |
| Apple Pay |
| Others |
Value Network & Pricing Analysis
Sub-48-hour settlement latency requirements compress merchant pricing power while simultaneously forcing cloud infrastructure providers to maintain strategic stockpiles of compute capacity across Nordic data center zones. This interdependency between real-time payment rail performance and distributed hardware provisioning shapes how Swedish platform operators negotiate interchange rate exposure against capital expenditure commitments.
Pricing Analysis
Volume-discount tiering structures dominate merchant acquiring contracts, with transaction velocity thresholds separating micro-merchant rates from enterprise-scale pricing bands. PSD2 compliance certification levels differentiate premium API access tiers from basic payment initiation services. Pricing pressure stems from account-to-account rails eliminating card network fees entirely, compressing revenue pools available for platform reinvestment. Small business merchants exhibit highest price sensitivity, while Stockholm's premium retail verticals absorb interchange exposure through margin absorption capacity.
Supply Chain Analysis
Just-in-time infrastructure deployment preferences dominate Swedish payment service provider procurement, though Finansinspektionen's operational resilience mandates force strategic stockpiling of failover capacity across domestic and Norwegian data center zones. Hardware supply concentrates in Taiwan, South Korea, and Germany for NFC terminal components and server infrastructure. Cloud compute dependencies, cryptographic security modules, and biometric sensor arrays anchor procurement portfolios. Single-source vulnerability runs through Taiwan's semiconductor foundry concentration for tokenization chipsets. Distribution runs through Nordic systems integrators and direct hyperscaler partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's mobile payments market sits in early-cycle recovery as PSD2-mandated infrastructure modernization forces replacement demand across legacy banking stacks. The cyclical driver is regulatory compliance spend compounding with merchant terminal refresh cycles.
For Market Incumbents: Shield core P2P liquidity flows by deepening bank consortium integration against Trustly Group's account-to-account rail expansion. Prioritize PCI DSS Level 1 certification investment to maintain tiered market access. Defensive consolidation through merchant checkout API exclusivity agreements locks in Stockholm retail corridor density before biometric authentication tiering commoditizes.
For New Entrants and Emerging Players: Finansinspektionen operational resilience certification fast-tracks market entry for infrastructure operators targeting Gothenburg-Malmö corridor white-space. Campus-adjacent retail in Uppsala and Lund offers lowest competitive density for peer-to-peer onboarding innovation. Go-to-market angle: subscription billing vertical specialization for SaaS merchants seeking processing cost reduction.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because open banking API standardization collapses differentiation toward operational scale and regulatory compliance automation. Acquisition target archetype: account-to-account rail specialists with embedded merchant checkout integrations. Signal to watch is biometric authentication patent filing velocity crossing threshold into enforcement litigation.
| Strategic Initiative | Industry Significance |
|---|---|
| PSD2 API Certification Investment | Finansinspektionen mandates operational resilience standards that gate market access for payment service providers. |
| Merchant Checkout Integration Partnership | Single-application interfaces consolidating credentials and loyalty reduce cart abandonment in Stockholm fashion verticals. |
| Biometric Authentication Tier Development | Fingerprint and facial recognition features differentiate premium platform tiers as security expectations harden. |
| Gothenburg-Malmö Corridor Expansion | White-space penetration in second-tier urban retail corridors captures volume beyond Stockholm fintech cluster concentration. |
| Bank Transfer Rail Specialization | Account-to-account payment rails bypass card networks entirely, capturing subscription billing volume among SaaS merchants. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with payment platform executives, merchant acquiring specialists, bank consortium strategists, and regulatory compliance officers; and secondary validation through Finansinspektionen enforcement disclosures, Swedish Financial Supervisory Authority PSD2 implementation reports, EU open banking API standardization documentation, and Nordic fintech venture financing databases. Bottom-up merchant adoption modeling triangulated against top-down transaction volume projections.
Across the analysis window, the forecasting framework modeled payment method segmentation, user demographic cohorts, transaction type applications, and security feature tiers. CAGRs derived from historical velocity patterns adjusted for regulatory compliance acceleration effects. Industry-specific inputs included open banking API adoption curves, terminal infrastructure replacement cycles, and biometric authentication penetration rates.
Decision-makers should treat outputs as directional under sustained PSD2 enforcement and merchant terminal refresh assumptions; material deviation would warrant model refresh. Forecasts reflect base-case infrastructure investment continuity. Revision becomes warranted when GDPR data circulation constraint enforcement crosses thresholds that materially alter personalization revenue economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Australia Mobile Payment Market
Payments
Payment Orchestration Platform Market
Payments
North America Real Time Payment Market
Payments
Blockchain Payments Software Market
Payments
Canada Mobile Payments Market
Payments
In-Vehicle Payment Services Market
Payments
Subscription Billing Management Market
Payments
South Korea Mobile Payment Market
Payments
Mobile Payment Security Market
Payments
In Vehicles Payment Market
Payments
Spain POS Terminals Market
Payments
NFC Payments Market
Payments
India Forex Cards Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Payment Instruments Market
Payments
Germany Payments Market