
 Smart Handwriting Machine Market | 2026-2036
Smart Handwriting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Handwriting Machine Market Insights
Direct sales channels serving enterprise accounts is narrowing as online retail platforms capture growing share of individual and small-business buyers. Wacom Co. Ltd. anchors premium creative professional segments with specialized pen systems. Samsung Electronics competes through integrated ecosystem bundling with tablets and displays. Huawei Technologies Co. Ltd. dominates domestic procurement channels in China through education-sector partnerships.
A smart handwriting machine captures, digitizes, and reproduces handwritten strokes through electromechanical or sensor-based systems, typically operating at 200-400 DPI resolution with pressure levels from 2048 to 8192 for professional-grade units. These devices serve commercial purposes spanning digital documentation, remote instruction, automated form completion, and artistic reproduction. Pen systems lead product type segments due to lower unit cost and compatibility with existing tablets, while interactive displays represent the fastest-growing category as hybrid classrooms and corporate collaboration rooms expand. Optical recognition technology sustains mature revenue pools in document scanning applications, though Bluetooth connectivity segments attract margin concentration through subscription-linked cloud services.
FCC certification requirements in the United States govern radio-frequency emissions for Bluetooth-enabled units, while CE marking under EU RoHS and REACH frameworks restricts hazardous substances in stylus manufacturing and mandates interoperability disclosures. China's MIIT enforces GB standards for wireless transmission protocols affecting import eligibility and domestic production licensing. Stakeholders must monitor evolving electromagnetic compatibility rules across multiple jurisdictions and assess whether to pursue modular hardware architectures that simplify regional compliance recertification.
Market Dynamics
Pressure-sensitive digitization hardware is compressing replacement cycles across education and creative sectors, while government procurement mandates in China accelerate standardization around domestic GB wireless protocols.
Growth Catalysts
- Smart classroom mandates:China's Ministry of Education directives require interactive handwriting systems in tier-one urban districts, creating baseline demand for capacitive touch displays and stylus bundles.
- REACH substance restrictions:EU RoHS and ECHA frameworks phase out cadmium and lead in stylus manufacturing, pushing OEMs toward indium tin oxide alternatives that improve pressure sensitivity.
- Remote instruction infrastructure:Universities in South Korea and Japan deploy lecture-capture systems integrating real-time stroke digitization for hybrid course delivery.
Market Restraints
- Indium supply concentration:Refining capacity for transparent conductive oxide coatings clusters in Chinese smelters, exposing downstream manufacturers to input volatility.
- Bluetooth certification friction:FCC Part 15 testing timelines for 2.4 GHz modules extend 8-14 weeks, delaying product launches for North American distribution.
- Optical character recognition substitution:Cloud-based OCR apps on commodity smartphones erode addressable market for dedicated handwriting capture hardware among casual document digitization users.
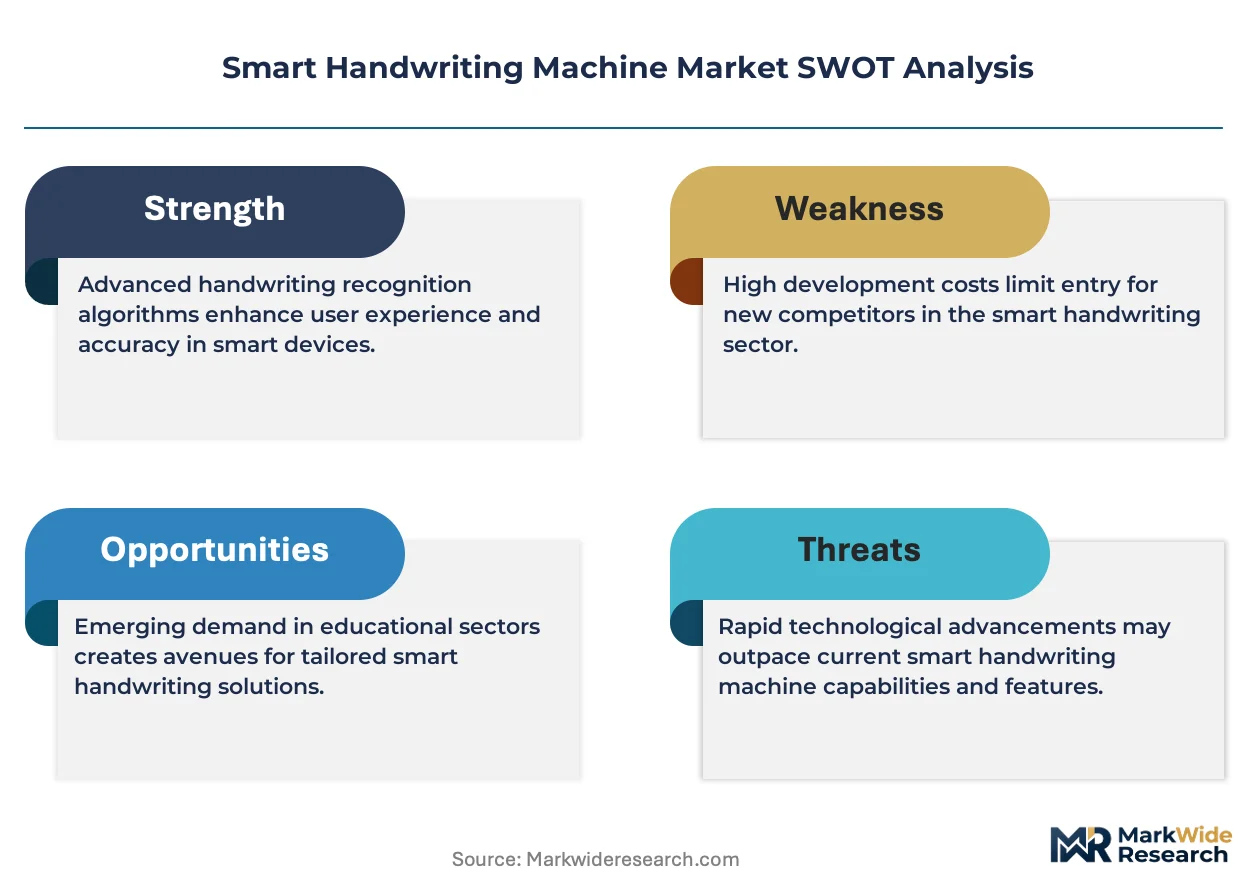
Strategic Opportunities
- Tier-two Chinese districts:Provincial education bureaus in Sichuan and Hubei lag Beijing and Shanghai in interactive display penetration, creating whitespace for mid-tier OEMs.
- Healthcare clinical documentation:Physician preference for handwritten notes during patient encounters drives pilot deployments of HIPAA-compliant stylus systems in US hospital networks.
- AI-assisted stroke analysis:Convergence of pressure-sensor arrays with on-device neural processing enables real-time handwriting assessment for occupational therapy applications.
Industry Challenges
- Firmware integration complexity:Enterprise IT departments struggle to synchronize handwriting data pipelines with legacy document management systems from established software vendors.
- Electromagnetic compatibility testing:Multi-jurisdiction certification requirements for stylus-to-tablet wireless protocols fragment engineering resources and compress margin on sub-$200 units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Handwriting Machine Market |
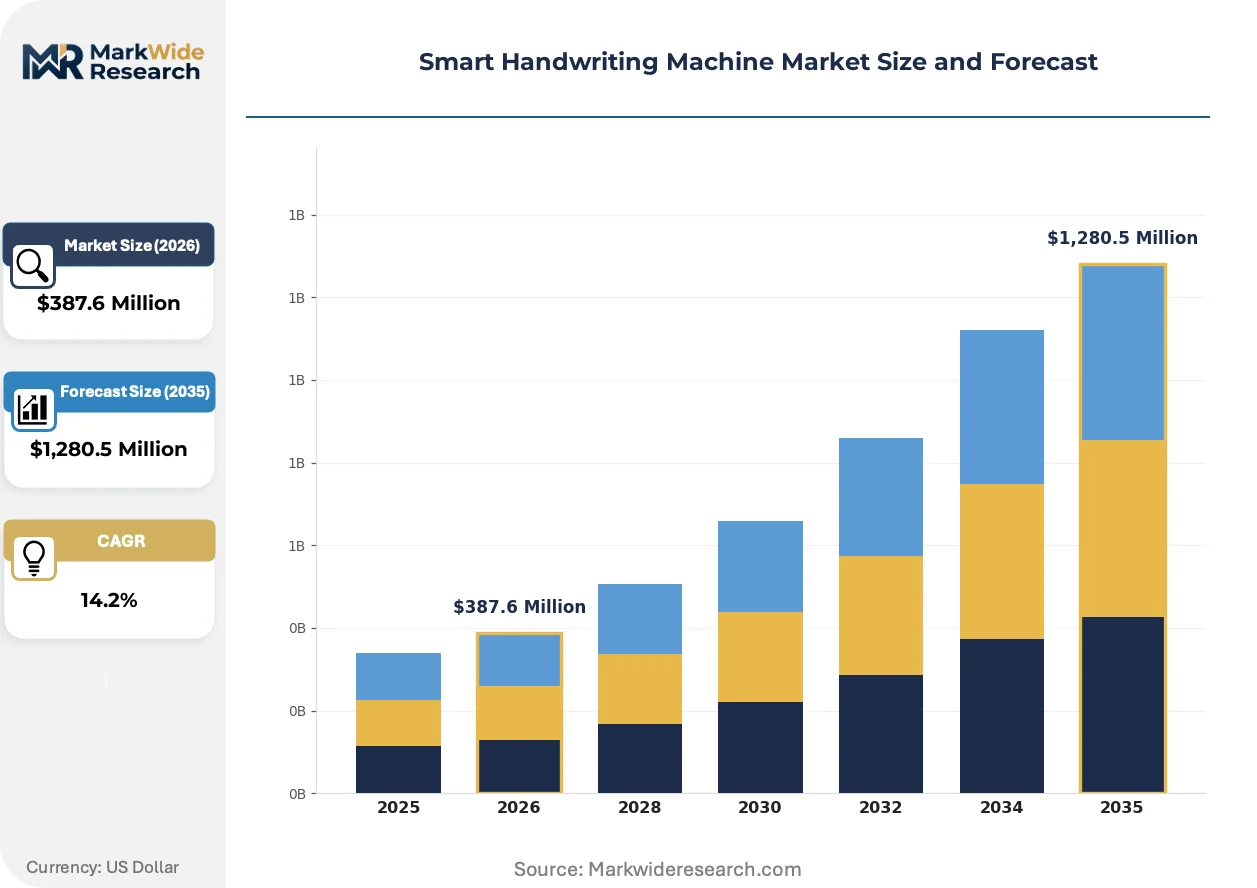
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Machines, Pen Systems, Digital Pads, Interactive Displays Technology: Optical Recognition, Pressure Sensors, Capacitive Touch, Bluetooth Connectivity End User: Educational Institutions, Corporates, Creative Professionals, Home Users Distribution Channel: Online Retail, Offline Stores, Direct Sales, Third-party Distributors |
| Companies Covered | Wacom Co. Ltd., Samsung Electronics, Apple Inc., Microsoft Corporation, Livescribe Inc., HP Inc., Huawei Technologies Co. Ltd., AxiDraw, UUNA TEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Handwriting Machine Market Trends and Innovations
Active stylus architectures are displacing passive capacitive alternatives as pressure-level specifications become a procurement differentiator in professional creative and education segments.
Electromagnetic resonance digitizers are digitizing handwritten input at 8192 pressure levels with sub-millimeter positional accuracy. Animation studios and industrial design firms in Germany and California adopt these systems for concept-to-production workflows. The technology is digitizing previously paper-bound creative processes while compressing revision cycles.
China's MIIT GB/T 9254 electromagnetic compatibility standards now mandate conducted emission testing for all wireless stylus devices sold through government procurement channels. Domestic OEMs retool testing protocols to satisfy both GB certification and CE marking requirements for export markets. Education-sector suppliers face the steepest compliance burden as dual-certification becomes table stakes for municipal tenders.
Enterprise buyers increasingly unbundle hardware purchases from cloud storage subscriptions, treating stroke data as sovereign IT assets rather than SaaS inputs. Large Japanese manufacturers and South Korean conglomerates lead this shift, negotiating direct API access to handwriting recognition engines while self-hosting archival infrastructure. The behavior is most pronounced in financial services and legal sectors where data residency requirements override convenience preferences.
Smart Handwriting Machine Market Segmentation
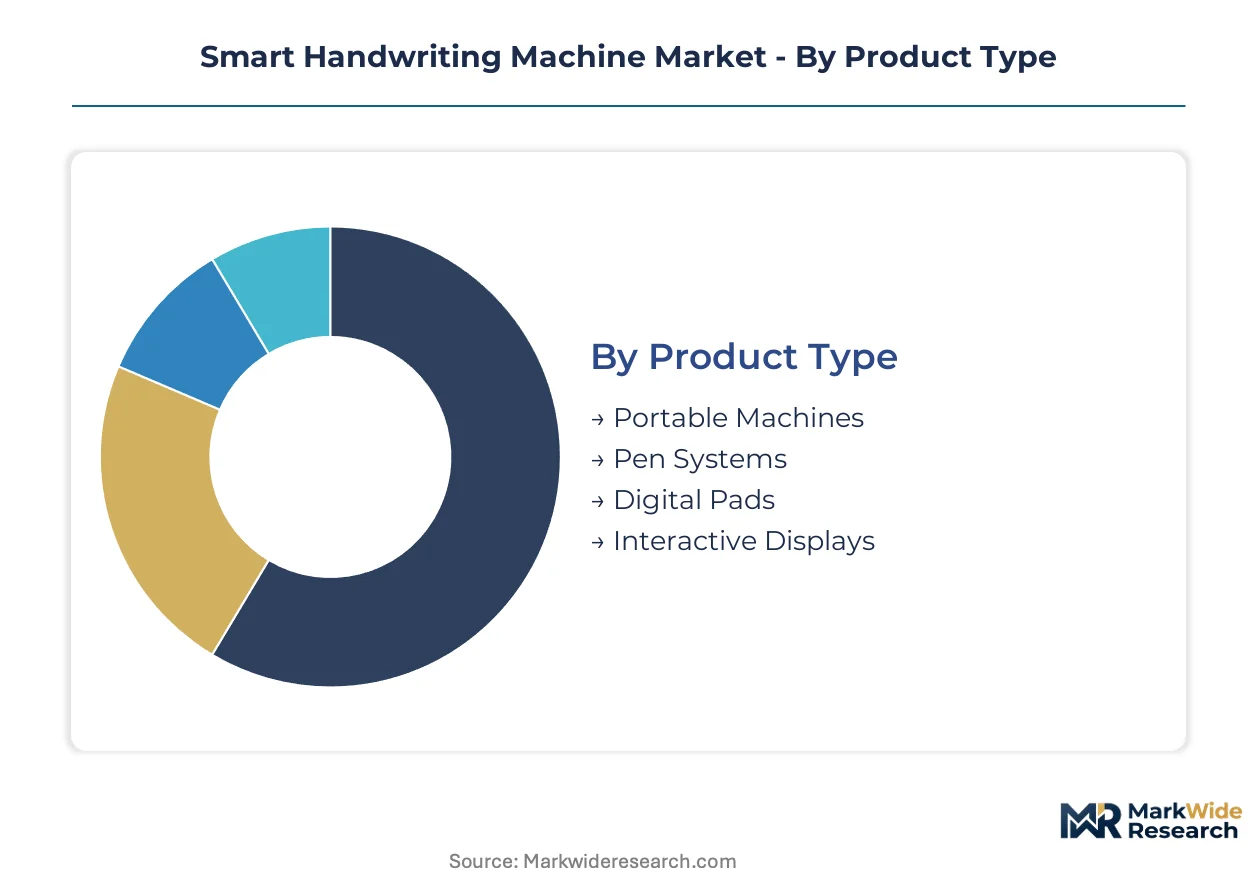
Segmentation in the smart handwriting machine market reveals distinct service requirements and margin profiles across hardware categories. After-sales intensity varies sharply between enterprise deployments requiring firmware integration support and consumer purchases with minimal technical assistance.
Product Type:
After-sales service intensity runs highest for interactive displays requiring on-site calibration and enterprise IT integration, while pen systems demand minimal post-purchase support beyond warranty replacement.
- Pen Systems:Electromagnetic or capacitive stylus devices operating at 2048-8192 pressure levels with sub-millimeter tracking accuracy. Demand concentrates among creative professionals in California and Germany where pressure sensitivity specifications drive procurement decisions for animation and industrial design workflows. These units carry the lowest service burden due to plug-and-play compatibility with existing tablets.
- Interactive Displays:Large-format touch surfaces with integrated digitizers supporting multi-user collaboration. Chinese tier-one urban districts under Ministry of Education smart classroom mandates anchor procurement volume, with municipal tenders requiring multi-year maintenance contracts and firmware update commitments.
- Portable Machines:Self-contained electromechanical devices for document digitization and automated form completion.
- Digital Pads:Dedicated graphics tablets without integrated displays, serving budget-conscious creative users and remote instruction applications.
Pen Systems holds the largest share; momentum sits with Interactive Displays.
Technology:
Cost tier stratification separates premium pressure-sensor arrays from commodity optical recognition, with Bluetooth modules commanding subscription-linked recurring revenue premiums.
- Pressure Sensors:Piezoelectric or strain-gauge arrays capturing 8192 distinct pressure levels with electromagnetic resonance positioning. Animation studios in Japan and Germany specify these systems for concept-to-production pipelines where stroke nuance affects final output quality. Indium tin oxide electrode layers dominate transparent conductive coatings, though supply concentrates in Chinese refining operations.
- Bluetooth Connectivity:Wireless transmission protocols enabling cloud synchronization and cross-device pairing. Enterprise buyers in South Korean conglomerates and Japanese manufacturers increasingly demand API access to handwriting recognition engines while self-hosting stroke data, unbundling hardware from SaaS subscriptions.
- Optical Recognition:Camera-based digitization for document scanning and OCR preprocessing applications.
- Capacitive Touch:Passive or active stylus interaction with consumer tablet displays, prevalent in education sector bulk purchases.
Pressure Sensors holds the largest share; Bluetooth Connectivity is gaining share fastest.
End User:
Application-specific requirements differentiate procurement patterns, with educational institutions prioritizing durability certifications and creative professionals demanding pressure-level granularity.
- Educational Institutions:K-12 and university deployments spanning lecture-capture systems and interactive whiteboards. China's Ministry of Education directives for tier-one urban districts create baseline demand, while provincial bureaus in Sichuan and Hubei represent whitespace for mid-tier OEMs. GB/T 9254 electromagnetic compatibility certification is mandatory for government procurement eligibility.
- Creative Professionals:Animation studios, industrial design firms, and architectural practices requiring 8192-pressure-level precision. German and California-based studios lead adoption of electromagnetic resonance digitizers for revision-cycle compression.
- Corporates:Enterprise meeting rooms and collaboration spaces deploying hybrid work infrastructure.
- Home Users:Individual consumers purchasing through online retail platforms for personal productivity and hobbyist applications.
Educational Institutions holds the largest share; momentum sits with Creative Professionals.
Distribution Channel:
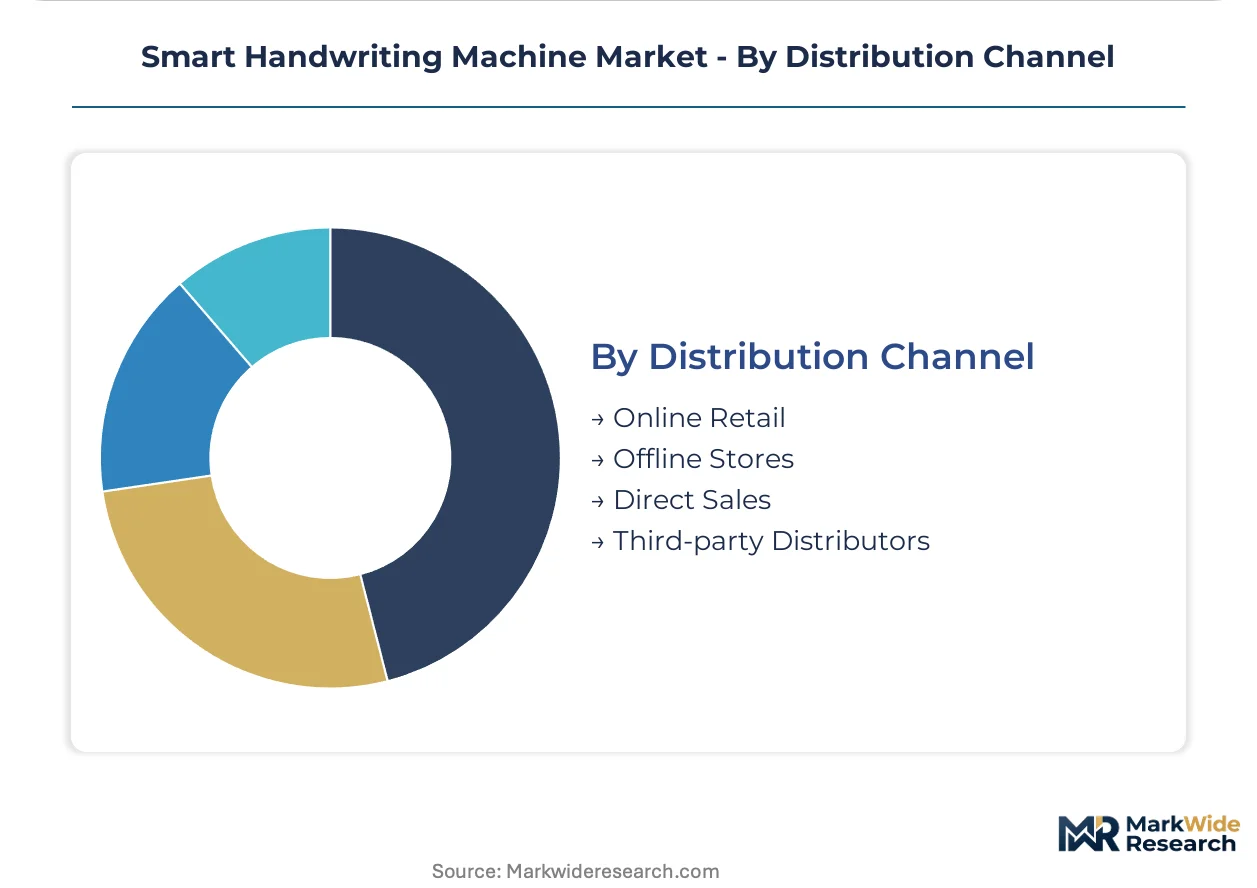
Volume concentration shifts toward online retail for individual and small-business buyers, while direct sales retain importance for enterprise accounts requiring integration services.
- Online Retail:E-commerce platforms capturing individual consumers and small creative practices. Wacom Co. Ltd. anchors premium positioning through specialized pen system listings, while domestic Chinese OEMs compete on price for capacitive touch bundles. FCC Part 15 certification delays of 8-14 weeks create inventory planning complexity for North American fulfillment.
- Direct Sales:Enterprise account teams serving municipal education bureaus and corporate IT departments. Huawei Technologies Co. Ltd. dominates this channel in China through education-sector partnerships and government procurement relationships.
- Offline Stores:Consumer electronics retail and specialty art supply channels.
- Third-party Distributors:Value-added resellers providing regional logistics and technical support.
Direct Sales holds the largest share; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in smart handwriting machine procurement, moving indium tin oxide electrodes and finished stylus assemblies across Pacific supply chains. Shenzhen's electronics corridor anchors manufacturing for capacitive touch modules serving education-sector tenders.
China
Ministry of Education smart classroom mandates in Beijing and Shanghai drive baseline demand for interactive displays. MIIT enforces GB/T 9254 electromagnetic compatibility standards for all government procurement channels. Shenzhen's OEM ecosystem retools testing protocols to satisfy dual-certification requirements for municipal tenders.
United States
HIPAA-compliant stylus pilots in hospital networks and animation studio demand in California concentrate procurement. FCC Part 15 certification timelines of 8-14 weeks for 2.4 GHz modules delay product launches. Los Angeles-based creative professionals specify 8192-pressure-level electromagnetic resonance digitizers for concept-to-production workflows.
Germany
Industrial design firms and animation studios in Bavaria and Baden-Württemberg anchor European demand for precision pressure-sensor systems. ECHA REACH frameworks phase out cadmium and lead in stylus manufacturing, pushing OEMs toward indium tin oxide alternatives. Berlin's creative technology cluster adopts real-time stroke digitization for hybrid collaboration spaces.
Japan
Universities in Tokyo and Osaka deploy lecture-capture systems integrating real-time handwriting digitization. METI standards govern wireless transmission protocols affecting enterprise procurement. Nagoya's electronics manufacturing base supplies pressure-sensor arrays to domestic animation studios.
South Korea
Conglomerate enterprise buyers in Seoul negotiate direct API access to handwriting recognition engines while self-hosting stroke data. MFDS frameworks influence medical-grade stylus specifications for clinical documentation pilots. Busan's industrial corridor supplies Bluetooth modules for education-sector exports.
Smart Handwriting Machine Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: premium creative specialists, ecosystem-integrated electronics conglomerates, and domestic OEMs serving government procurement channels. Tier-one players anchor professional segments through pressure-level differentiation, while mid-tier fabricators compete on price for education bulk purchases. Dominant competitive moves include vertical integration into indium tin oxide electrode supply and strategic partnerships with cloud storage providers for subscription-linked recurring revenue.
Within the premium creative tier, Wacom Co. Ltd. and Livescribe Inc. exemplify specialized pen system architectures, while Samsung Electronics occupies a position among ecosystem-integrated conglomerates bundling stylus hardware with tablet and display portfolios. Huawei Technologies Co. Ltd. anchors the domestic OEM archetype in China through education-sector partnerships and municipal procurement relationships.
| Leading Market Players |
|---|
| Wacom Co. Ltd. |
| Samsung Electronics |
| Apple Inc. |
| Microsoft Corporation |
| Livescribe Inc. |
| HP Inc. |
| Huawei Technologies Co. Ltd. |
| AxiDraw |
| UUNA TEK |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Ningbo port complex moves indium tin oxide electrodes and finished stylus assemblies across Pacific supply chains, with freight cost volatility transmitting directly into tiered price differentiation between education-sector bulk tenders and premium creative professional channels.
Pricing Analysis
Volume-discount tiering separates municipal education procurement in Chinese tier-one districts from individual creative professional purchases. Three-tier pricing structure across premium, standard, and economy levels reflects pressure-sensor specification grades and after-sales service bundling. Price differentiation hinges on electromagnetic compatibility certification tier and geographic delivery infrastructure. Cost compression in mid-tier capacitive touch bundles is intensifying because domestic OEMs compete for provincial bureau tenders in Sichuan and Hubei. Education buyers exhibit highest price sensitivity; animation studios in Germany and California demonstrate lowest sensitivity due to workflow-critical pressure-level requirements.
Supply Chain Analysis
Extended payment terms from Shenzhen OEMs to indium tin oxide refiners anchor working capital structures across the assembly tier. Manufacturing concentrates in China, South Korea, and Japan, with upstream indium refining anchored in Chinese smelters. Component sourcing draws from transparent conductive oxide coatings, electromagnetic resonance digitizer arrays, and Bluetooth transmission modules. Single-source vulnerability in indium supply exposes downstream manufacturers to input volatility. Distribution runs through direct sales teams for enterprise education accounts and online retail platforms for individual consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Chinese municipal education bureaus consolidating vendor lists under Ministry of Education smart classroom mandates, fragmenting pricing leverage for mid-tier OEMs competing on volume.
For Market Incumbents: Harden certification moats by pursuing dual GB/T 9254 and CE marking compliance ahead of provincial tender requirements. Deepen captive supply of indium tin oxide electrode layers to offset raw material volatility. Defensive positioning against cloud-based OCR substitution demands API-accessible handwriting recognition engines that enterprise buyers can self-host. For New Entrants and Emerging Players: Build out healthcare clinical documentation pilots in US hospital networks where HIPAA-compliant stylus systems face limited incumbent penetration. White-space opportunity concentrates in tier-two Chinese districts lagging Beijing and Shanghai in interactive display adoption. Go-to-market leverage rests on occupational therapy applications using AI-assisted stroke analysis for real-time handwriting assessment. For Investors and Strategic Acquirers: Carve-out targets emerge from electronics conglomerates with dormant stylus hardware divisions lacking cloud-service integration. Long-term viability across the projection horizon favors specialists with pressure-sensor array IP and education-sector procurement relationships. Watch for inflection in electromagnetic resonance digitizer adoption rates among German industrial design firms as signal of premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | GB/T 9254 and CE marking compliance unlocks Chinese municipal and European education tenders simultaneously. |
| Backward Integration into Electrode Supply | Captive indium tin oxide production mitigates raw material volatility from Chinese smelter concentration. |
| API-First Platform Development | Enterprise buyers in South Korean conglomerates demand direct handwriting recognition engine access for self-hosted data. |
| Healthcare Partnership Pilots | HIPAA-compliant stylus deployments in US hospital networks address physician preference for handwritten clinical notes. |
| Occupational Therapy Application Launch | AI-assisted stroke analysis converges pressure-sensor arrays with on-device neural processing for rehabilitation markets. |
Research Methodology
Desk research of customs trade records, MIIT certification filings, and education procurement databases preceded structured interviews with OEM product managers, municipal tender officers, and electromagnetic compatibility testing engineers. Primary fieldwork with supply chain managers at indium refiners and stylus assembly facilities validated secondary volume estimates. Bottom-up unit shipment analysis triangulated against top-down procurement budget disclosures from Chinese provincial bureaus.
Assumptions held fixed include MIIT smart classroom mandate continuity and REACH substance restriction phase-out timelines; variables stress-tested encompass indium price volatility bands and FCC certification timeline extensions. The analytical framework modeled product type, technology tier, end-user vertical, and distribution channel across the analysis window. CAGRs derived from logistic diffusion curves fitted to education-sector penetration data and creative professional replacement cycle compression. Forecast inputs incorporated Bluetooth module cost trajectories and pressure-sensor yield rates from electromagnetic resonance digitizer production.
Stress conditions across indium supply disruption severity, electromagnetic compatibility testing backlog duration, and cloud-based OCR substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procurement mandate continuity and wireless protocol standardization. Macroeconomic contraction, regulatory timeline acceleration, or neural processing cost breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Operational Technology Market
Industrial Automation
Sortation Systems Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Europe ICS Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
UV Curing System Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Global Automated Truck Loading System Market