
 Edtech Market | 2026-2036
Edtech Market Size, Share, and Industry Trends Forecast 2026-2036
Edtech Market Intelligence
Subscription-based enterprise licensing and revenue-sharing partnerships with universities is narrowing the competitive field for mid-sized content providers. Coursera leverages its university consortium relationships to sustain premium positioning in professional certificate programs. Yuanfudao anchors its model on live-streamed K-12 tutoring infrastructure across China's provincial markets. Duolingo differentiates through gamified freemium mechanics that lower customer acquisition costs in individual learner segments.
Edtech encompasses digitally delivered educational content, assessment tools, and administrative platforms that operate through cloud-hosted learning management systems, adaptive algorithms, and real-time video streaming protocols to enable remote skill acquisition and credential verification. The technology serves institutional cost reduction, workforce reskilling mandates, and personalized learning pathways across formal and informal education contexts. Learning Management Systems dominate institutional procurement cycles due to integration complexity and switching costs that lock in multi-year contracts. Mobile Learning captures the fastest expansion as smartphone-first delivery reduces infrastructure barriers in emerging markets. Corporate end users represent the most concentrated margin pool where training budgets convert to recurring SaaS commitments with measurable ROI requirements.
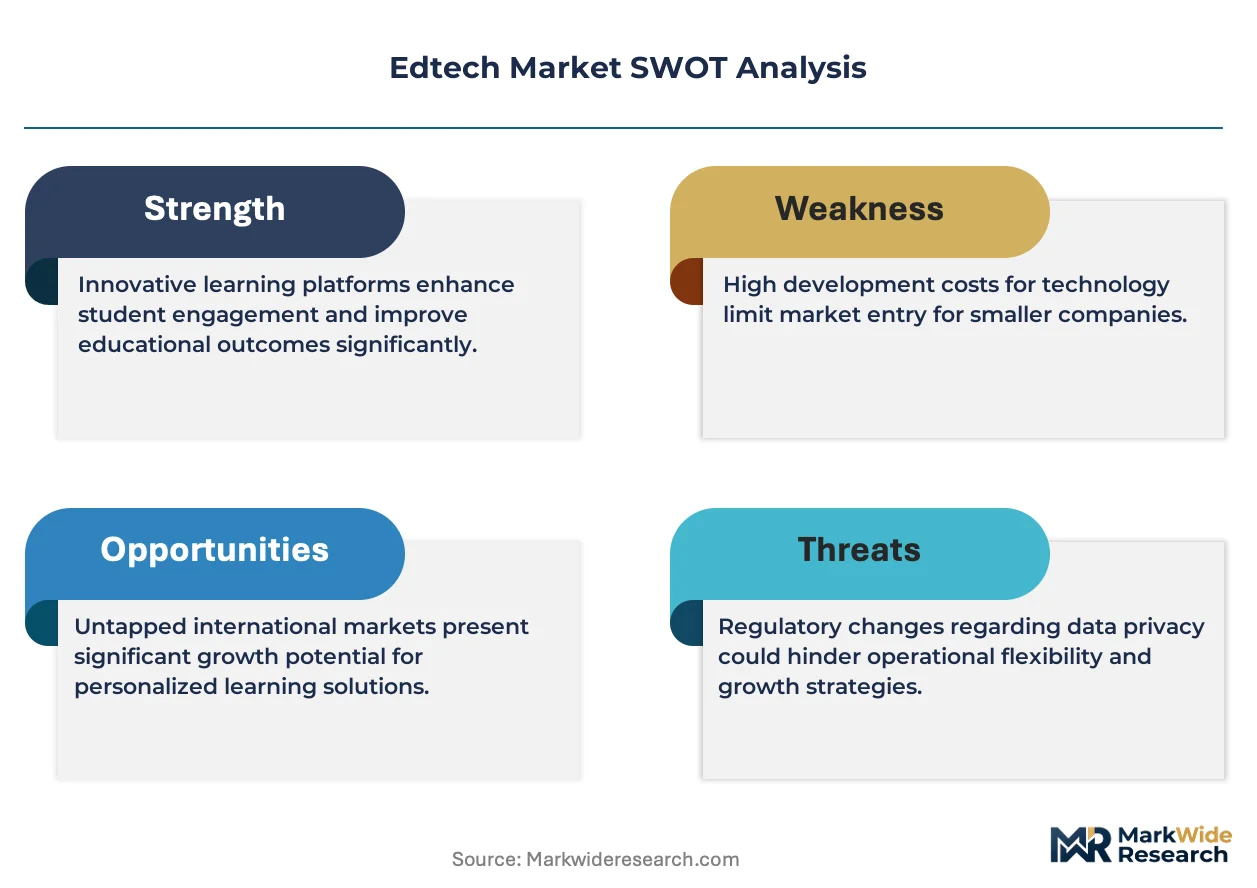
The US Department of Education enforces FERPA compliance for student data privacy while the FDA oversees software-based medical education simulations as regulated devices. China's MIIT and SAMR jointly govern content licensing, data residency, and anti-monopoly provisions that constrain platform expansion. India's BIS mandates interoperability standards for digital educational content under national accreditation frameworks. Stakeholders must monitor evolving cross-border data governance as jurisdictional fragmentation threatens platform scalability and content portability across operating regions.
Market Dynamics
Corporate learning budgets are consolidating around measurable skill outcomes, compressing procurement cycles for multi-year Learning Management System contracts and marginalizing content providers lacking direct workforce placement pathways.
Growth Catalysts
- FERPA-aligned data governance:US educational institutions prioritize platforms with certified student privacy architectures, accelerating vendor consolidation toward compliant enterprise suites.
- India's tier-two broadband penetration:Competitive examination pressure in cities like Lucknow and Indore generates concentrated demand for live-streamed test preparation infrastructure.
- Adaptive assessment algorithms:Real-time competency mapping reduces time-to-credential for professional certification programs, expanding addressable learner pools in workforce reskilling segments.
Market Restraints
- MIIT data localization mandates:China's Ministry of Industry and Information Technology requires server infrastructure within provincial borders, raising capital intensity for foreign platform operators serving K-12 segments.
- Cloud hosting concentration:Three hyperscale providers dominate educational data center capacity, creating single-point vulnerability for institutional continuity planning.
- Legacy SCORM interoperability:Decades-old content packaging standards constrain granular analytics extraction, limiting ROI demonstration for procurement committees.
Strategic Opportunities
- Micro-credential stacking frameworks:European Qualifications Framework alignment enables portable digital badges across member state labor markets, reducing employer verification friction.
- AI-driven language tutoring:Large language model integration with speech recognition compresses personalized feedback loops in spoken fluency acquisition.
- Brazilian vocational reskilling mandates:Federal workforce development allocations under SENAI expansion create procurement windows for simulation-based technical training platforms.
Industry Challenges
- Instructional design talent scarcity:Platforms compete for professionals capable of translating subject expertise into scaffolded digital learning sequences with valid assessment rubrics.
- Multi-jurisdictional compliance layering:Simultaneous FERPA, GDPR, and BIS adherence requirements extend legal review timelines for content launches across operating regions.
- LMS integration complexity:Custom API development for student information system connectivity consumes engineering resources and delays enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edtech Market |
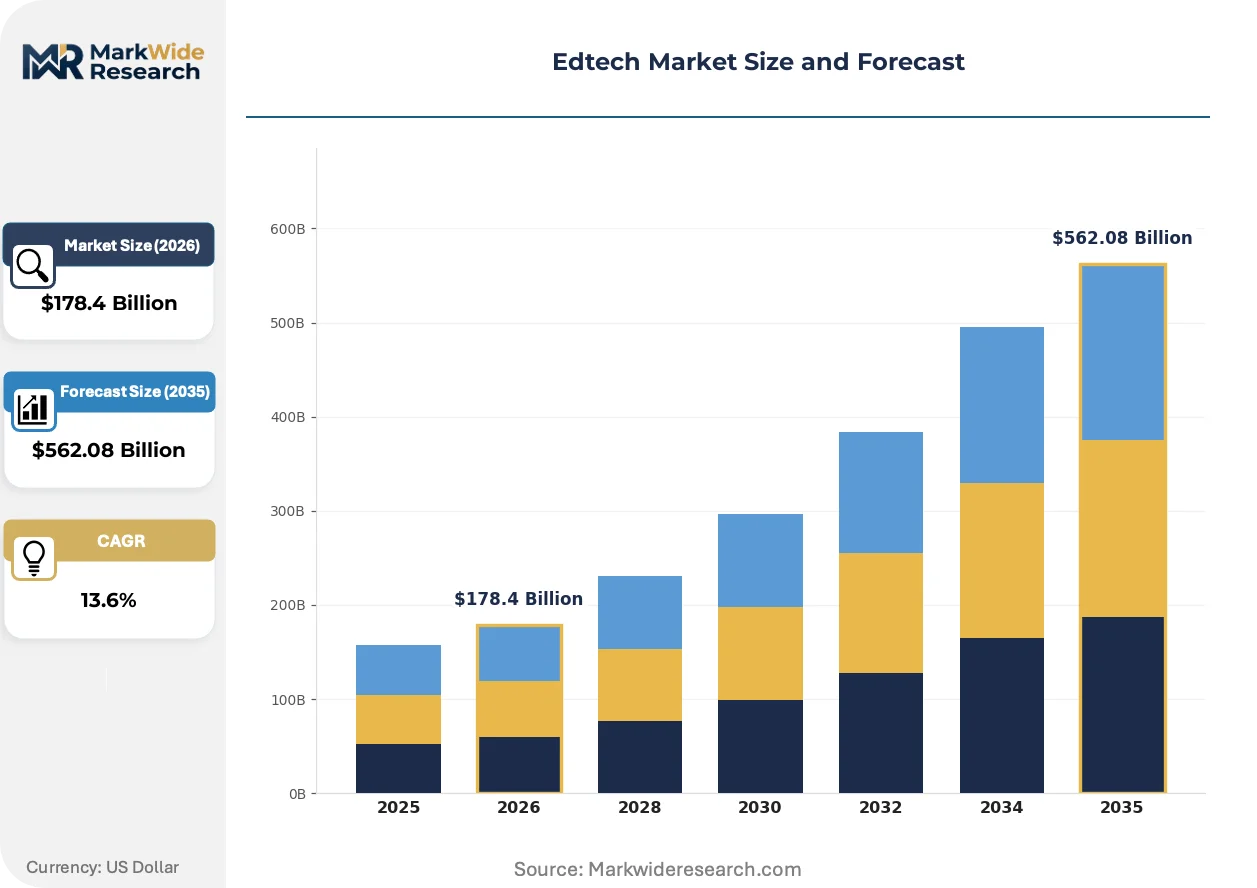
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $562.08 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Online Courses, Learning Management Systems, Virtual Classrooms, Tutoring Platforms End User: K-12 Schools, Higher Education, Corporates, Individual Learners Delivery Mode: Synchronous Learning, Asynchronous Learning, Blended Learning, Mobile Learning Content Type: Video Lectures, Interactive Quizzes, E-books, Simulations |
| Companies Covered | Udemy, Duolingo, Byju's, edX, Coursera, Yuanfudao, 360Learning, Pluralsight, Skillsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edtech Market Strategic Shifts & Innovations
Generative AI architectures are compressing content production economics while regulatory fragmentation around learner data residency forces platform operators toward modular infrastructure designs.
Immersive simulation environments built on WebGL and cloud rendering is collapsing the cost differential between physical laboratory access and virtual experimentation for STEM curricula. Community colleges and vocational institutes in the US Midwest adopt these platforms at accelerating pace. The technology is collapsing geographic barriers to hands-on technical training that previously required capital-intensive facility investment.
China's MIIT and SAMR joint enforcement of anti-monopoly provisions in educational software licensing is constraining exclusive content distribution agreements. Platform operators must restructure university partnership terms to permit multi-provider access. K-12 tutoring segments in provincial markets face the most acute contract renegotiation pressure as authorities prioritize consumer choice over platform exclusivity.
Employer-sponsored tuition benefit programs are consolidating purchasing authority through dedicated education-as-a-benefit platforms. Human resource departments disaggregate traditional degree reimbursement into skill-specific micro-credential subscriptions. This concentration is most visible in US technology and financial services sectors where measurable competency verification outweighs credential prestige in promotion decisions.
Edtech Market Segmentation
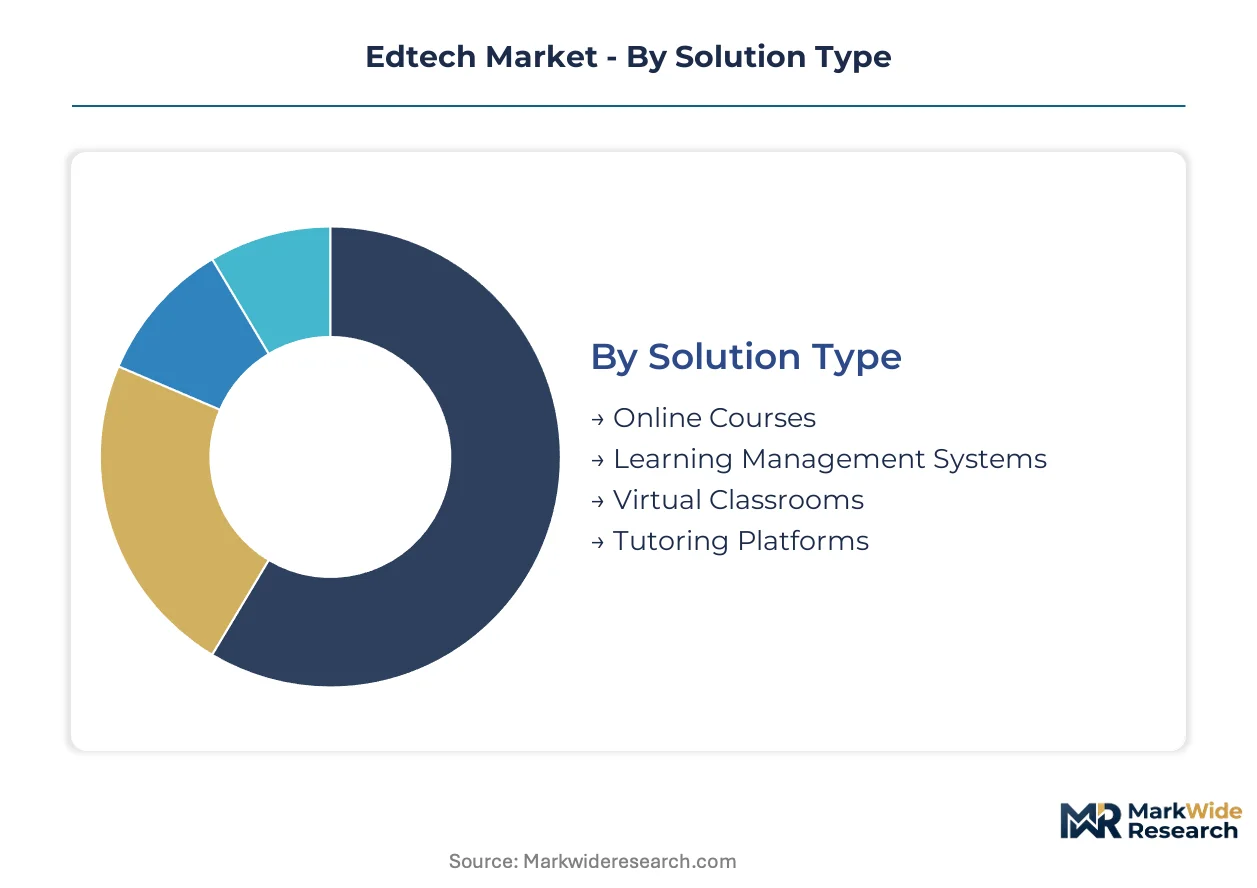
Edtech procurement varies sharply by institutional buyer sophistication and learner autonomy levels. Solution architecture, delivery infrastructure, and content format choices each create distinct margin profiles and renewal dynamics across customer segments.
Solution Type:
Post-deployment service intensity distinguishes enterprise platforms from self-serve content libraries, with integration complexity driving multi-year support commitments.
- Online Courses:Pre-recorded instructional modules packaged for individual progression tracking. Corporate L&D departments in US technology and financial services sectors prioritize these for standardized compliance training with completion verification.
- Learning Management Systems:Cloud-hosted administrative platforms managing enrollment, assessment, and credential issuance through API-connected student information systems. Higher education institutions in India and Brazil lock into these systems due to switching costs and accreditation reporting requirements.
- Virtual Classrooms:Real-time video conferencing infrastructure with breakout room and whiteboard functionality.
- Tutoring Platforms:On-demand or scheduled live instruction matching learners with subject specialists.
By volume, Online Courses leads. By growth pace, Learning Management Systems is expanding most quickly.
End User:
Customer lifetime value concentrates in institutional contracts where procurement committees evaluate multi-year total cost of ownership against measurable outcome metrics.
- K-12 Schools:District-level purchasing of curriculum-aligned platforms with parent communication portals and progress dashboards. China's provincial education bureaus mandate data localization for these deployments under MIIT guidelines, raising infrastructure requirements for foreign operators.
- Higher Education:University consortium procurement of degree-integrated platforms and professional certificate stacking programs. US institutions prioritize FERPA-certified architectures that limit third-party data access.
- Corporates:Enterprise SaaS licensing tied to workforce reskilling mandates and measurable skill outcome verification.
- Individual Learners:Direct-to-consumer subscription models with freemium acquisition funnels and micro-credential purchasing.
Corporates generate the highest contract values. Individual Learners show the steepest expansion trajectory in emerging market smartphone penetration.
Delivery Mode:
Bandwidth infrastructure and learner scheduling flexibility determine adoption patterns across synchronous and asynchronous formats.
- Synchronous Learning:Real-time scheduled sessions requiring stable low-latency connectivity. India's tier-two cities including Lucknow and Indore drive concentrated demand for live-streamed competitive exam preparation where instructor interaction is non-negotiable.
- Asynchronous Learning:Self-paced module completion with embedded assessment checkpoints. Corporate training programs in Germany and France adopt these for timezone-distributed workforce segments.
- Blended Learning:Scheduled in-person instruction supplemented by digital pre-work and reinforcement.
- Mobile Learning:Smartphone-optimized bite-sized content delivery with offline download capability.
Synchronous Learning dominates revenue concentration. Mobile Learning is gaining share fastest in markets with limited fixed broadband penetration.
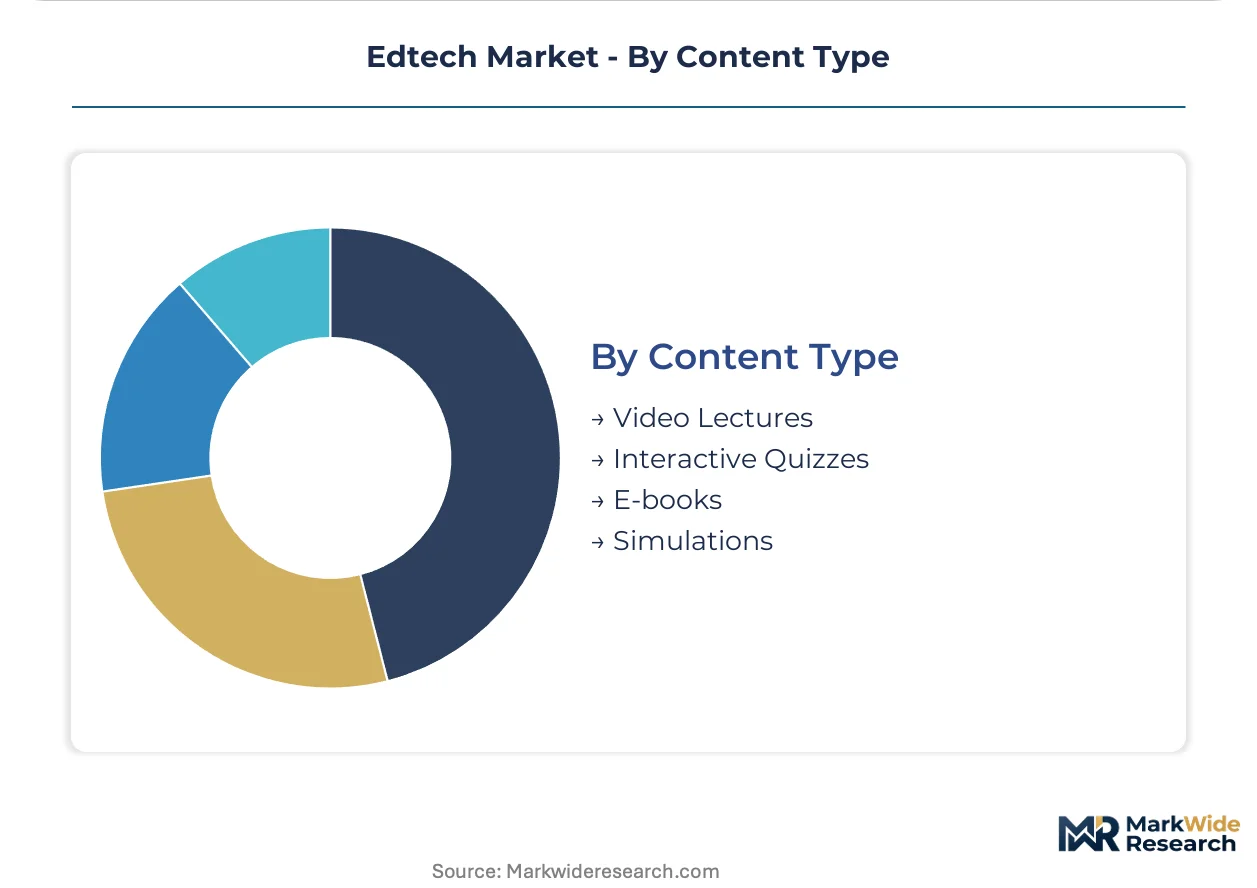
Content Type:
Production cost structures and update frequency requirements vary dramatically across format categories, with simulation development consuming disproportionate instructional design resources.
- Video Lectures:Produced instructor recordings with captioning and variable playback speed. Higher education institutions in the UK and Australia standardize on these for lecture capture and flipped classroom models.
- Simulations:Interactive virtual environments for procedural practice and consequence-free experimentation. US community colleges in the Midwest adopt WebGL-based STEM simulations to replace capital-intensive physical laboratory access.
- Interactive Quizzes:Adaptive assessment engines with immediate feedback loops and competency mapping.
- E-books:Digital text repositories with annotation, search, and citation export functionality.
Video Lectures lead by deployment volume. Simulations show the most rapid adoption acceleration in vocational and technical training segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where enterprise SaaS contracts command premium multiples, while Indian operators compete on volume in tier-two city markets with compressed unit economics.
United States
Corporate learning budgets and university consortium procurement drive platform consolidation. FERPA compliance requirements filter vendor eligibility toward certified enterprise architectures. Silicon Valley and Boston corridor clusters concentrate venture-backed adaptive learning startups targeting workforce credentialing.
China
Provincial K-12 markets sustain live-streamed tutoring demand despite regulatory contraction. MIIT data localization mandates force foreign operators into joint venture structures with domestic cloud providers. Beijing and Shanghai education bureaus pilot AI-driven assessment pilots under SAMR content licensing frameworks.
India
Broadband penetration in Lucknow and Indore intersects with competitive examination pressure to concentrate test preparation demand. BIS interoperability standards govern national accreditation frameworks for digital content portability. Bangalore and Hyderabad host engineering talent clusters building adaptive assessment infrastructure for export markets.
Germany
Corporate apprenticeship digitization and vocational reskilling mandates sustain simulation-based training procurement. GDPR learner data governance extends legal review timelines for platform launches. Munich and Stuttgart industrial clusters adopt WebGL-based technical training to replace physical laboratory access.
Brazil
Federal workforce allocations under SENAI expansion create procurement windows for simulation platforms. ANVISA oversight applies to software-based medical education modules as regulated devices. São Paulo state concentrates edtech venture formation targeting Portuguese-language corporate learning segments.
Edtech Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in content production and assessment engine licensing. The vendor base separates into three strata: enterprise LMS incumbents with multi-year institutional lock-in, freemium consumer apps with viral acquisition mechanics, and vertical specialists targeting regulated professional certification. Strategic moves concentrate on university partnership restructuring under anti-monopoly pressure and AI-driven content generation capacity expansion.
Within the enterprise platform tier, Coursera and Yuanfudao occupy positions reflecting divergent geographic anchoring—US-based degree-integrated credentialing versus China-focused live-streamed tutoring infrastructure. Duolingo exemplifies the freemium archetype through gamified mechanics that compress customer acquisition costs in individual learner segments. These three operators represent distinct competitive vectors: institutional consortium leverage, provincial market density, and viral consumer engagement.
| Leading Market Players |
|---|
| Udemy |
| Duolingo |
| Byju's |
| edX |
| Coursera |
| Yuanfudao |
| 360Learning |
| Pluralsight |
| Skillsoft |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud infrastructure concentration in the United States, China, and Ireland concentrates compute cost leverage among three providers, forcing edtech platforms to absorb margin compression or pass through storage and bandwidth escalators to enterprise buyers locked into multi-year LMS contracts.
Pricing Analysis
Configured-to-order enterprise SaaS licensing commands 3-4x premiums over standardized self-serve subscriptions. Pricing stratifies across premium, standard, and economy tiers based on API integration depth and FERPA certification status. Cost compression in the mid-market tier is intensifying because university consortiums consolidate procurement around outcome-verified platforms. Individual learners exhibit highest price sensitivity, while corporate L&D departments prioritize measurable ROI over per-seat economics.
Supply Chain Analysis
Export-control regimes restricting GPU and AI training hardware flows to Chinese data centers fragment infrastructure deployment strategies. Cloud compute supply concentrates in the United States, China, and Ireland, with content delivery networks drawing from edge server partnerships across India, Brazil, and Germany. Single-source vulnerability in NVIDIA chip provisioning threatens adaptive algorithm development timelines. Distribution runs through API-first platform integrations rather than direct institutional sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in edtech hinge on interoperable credentialing standards that erode switching costs, with the European Qualifications Framework's micro-credential portability forcing incumbent LMS providers to open API architectures or risk disintermediation by modular specialist stacks.
For Market Incumbents: Entrench multi-year institutional contracts through deeper student information system integration and exclusive content licensing with flagship university consortiums. Vertical integration into adaptive assessment engine development counters specialist algorithm providers. FERPA certification investment maintains procurement eligibility as privacy audits tighten. For New Entrants and Emerging Players: Build out simulation-based vocational training modules for Brazil's SENAI procurement windows and India's tier-two test preparation markets. Live-streamed tutoring infrastructure in Lucknow and Indore offers penetrable white-space before Yuanfudao's provincial density solidifies. Go-to-market through mobile-first freemium mechanics lowers customer acquisition costs against incumbent enterprise sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed LMS incumbents burdened by legacy SCORM technical debt and stalled AI roadmap execution. Long-term viability favors platforms with modular infrastructure capable of jurisdictional fragmentation compliance. Watch for MIIT data localization enforcement intensity as the signal for China market capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep LMS-student information system connectivity locks in multi-year renewal cycles at US universities. |
| AI-Driven Content Generation | Large language model deployment compresses instructional design costs for adaptive assessment engines. |
| Geographic Expansion | Provincial K-12 density in India and Brazil captures smartphone-first learner growth outside saturated markets. |
| Regulatory Certification Investment | FERPA, GDPR, and BIS alignment extends platform eligibility across fragmented data governance regimes. |
| Strategic Partnership | University consortium restructuring under China's SAMR anti-monopoly enforcement preserves content distribution access. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and national accreditation databases. Interviews with LMS procurement officers, instructional design directors, and cloud infrastructure architects informed demand-side validation. Regulatory review incorporated MIIT circulars, FERPA audit protocols, and BIS interoperability standards. Bottom-up platform revenue modeling triangulated against top-down education expenditure forecasts.
Forecast inputs span deployment model, institutional buyer tier, content format, and regional regulatory cluster across the analysis window. Segmentation dimensions include solution type, end-user category, delivery mode, and content format. CAGRs derive from enrollment trend extrapolation, corporate training budget elasticity, and mobile penetration curves. AI content generation adoption rates and micro-credential stacking velocity serve as industry-specific demand modifiers.
Sensitivities concentrate around MIIT enforcement intensity, FERPA audit expansion, and hyperscale cloud pricing resets. Forecasts reflect assumptions on broadband infrastructure buildout pacing and competitive examination pressure persistence. Material shifts in cross-border data governance or GPU export control scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
E Learning Virtual Reality Market