
 SETM Education Market | 2026-2036
SETM Education Market Size, Share, and Industry Trends Forecast 2026-2036
SETM Education Market Insights
The capability gap between cloud-native platform developers and legacy print publishers is redrawing competitive boundaries in SETM education. McGraw Hill leverages its institutional relationships and curriculum depth to sustain print-to-digital transitions. PASCO Scientific differentiates through proprietary sensor hardware integrated with its digital lab platforms. Discovery Education anchors its position with streaming media infrastructure that reaches millions of K-12 students.
SETM education encompasses science, engineering, technology, and mathematics instruction delivered through structured curricula, digital platforms, hands-on laboratory equipment, and assessment systems designed to build technical competency from primary through professional levels. eLearning platforms dominate product-level revenue as districts seek scalable delivery, while Learning Management Systems capture recurring subscription value through institutional lock-in. Among customer types, K-12 institutions represent the largest addressable base, though Corporate Training commands premium pricing per seat for specialized certification content in Application segments.
In the United States, the Department of Education's Title I funding rules and the Individuals with Disabilities Education Act shape procurement compliance requirements for federally subsidized digital tools. China's Ministry of Education mandates national curriculum standards that determine which laboratory equipment and digital content qualify for provincial procurement lists. Stakeholders must monitor how evolving AI governance frameworks in both jurisdictions alter product certification pathways and content moderation obligations.
Market Dynamics
The SETM Education Market is being fundamentally restructured by the collision between legacy curriculum publishers and cloud-native platform developers, each competing to capture institutional procurement budgets as districts accelerate digital transitions.
Growth Catalysts
- EU AI Act compliance pathways:Automated tutoring systems that meet the Act's risk classification requirements are gaining preferential market access across European procurement channels, creating certification premiums for compliant vendors.
- China's provincial lab modernization mandates:Local education bureaus in Jiangsu, Guangdong, and Zhejiang provinces are funding sensor-integrated science laboratories in public middle schools, driving equipment replacement cycles.
- Cloud-native LMS architectures:Microservices-based learning management platforms are capturing recurring subscription revenue through API-driven integrations with district student information systems.
Market Restraints
- Semiconductor sensor cost volatility:PASCO Scientific and similar hardware-integrated platform providers face margin pressure from MEMS component price swings in their proprietary laboratory sensor supply chains.
- Federal procurement compliance friction:US Department of Education Title I funding rules impose documentation burdens on digital tool vendors seeking subsidized district contracts, extending sales cycles.
- Substitute content abundance:Open Educational Resource repositories and teacher-generated content platforms are compressing willingness-to-pay for premium digital curriculum licenses in underfunded districts.
Strategic Opportunities
- Underpenetrated rural US districts:Broadband infrastructure investments under the Infrastructure Investment and Jobs Act are enabling synchronous remote lab experiences for schools previously excluded from hands-on science programs.
- Corporate certification convergence:AWS Educate and similar cloud credential programs are creating demand for standardized SETM curricula that bridge K-12 instruction with professional technical certification pathways.
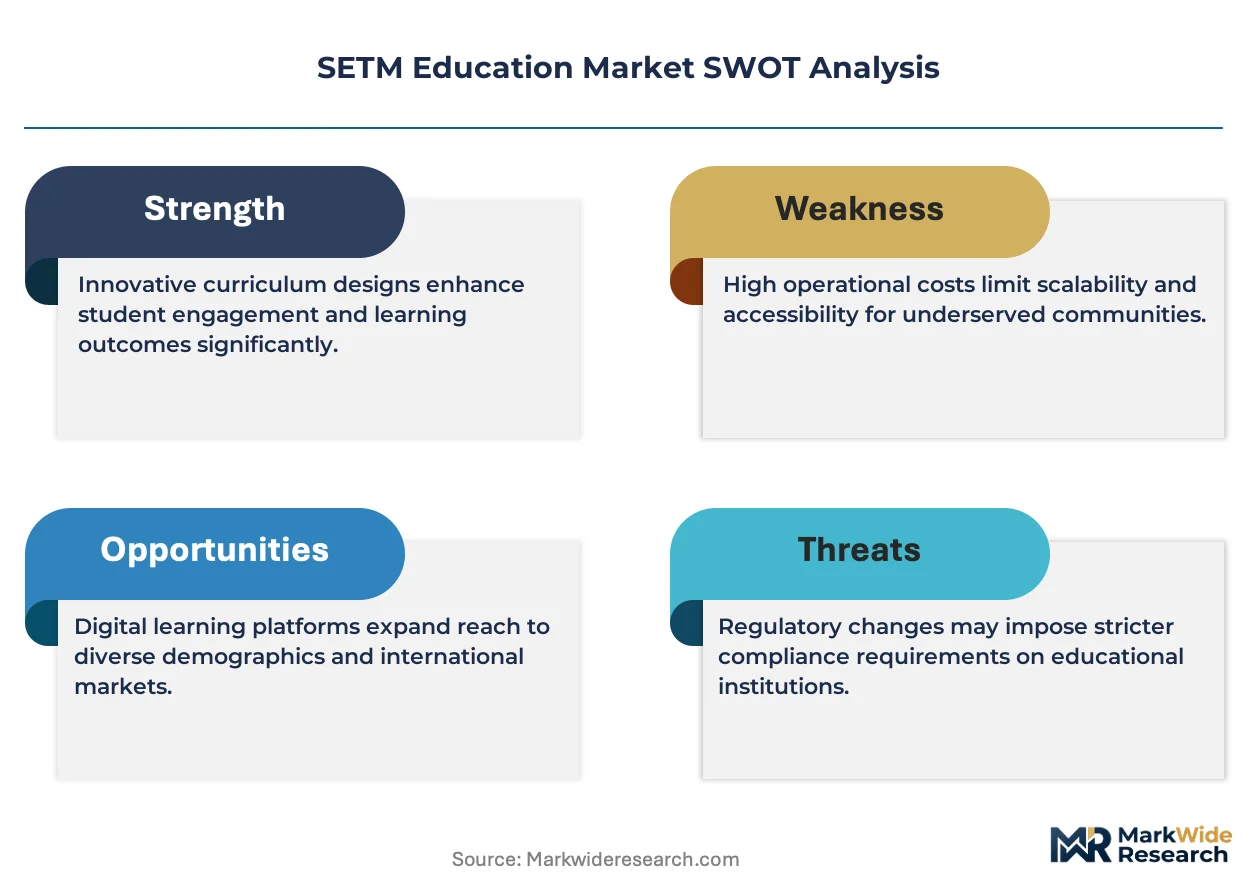
- AI governance advisory services:The EU AI Act's implementation timeline is generating consulting revenue for platform vendors who bundle compliance documentation with their automated assessment products.
Industry Challenges
- Instructional designer talent scarcity:Vendors struggle to hire professionals who combine subject-matter expertise in physics, chemistry, or engineering with user-experience design capabilities for digital platforms.
- Legacy SIS integration complexity:Districts running on-premises student information systems from the 2010s require costly custom API development to connect with modern cloud-native learning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SETM Education Market |
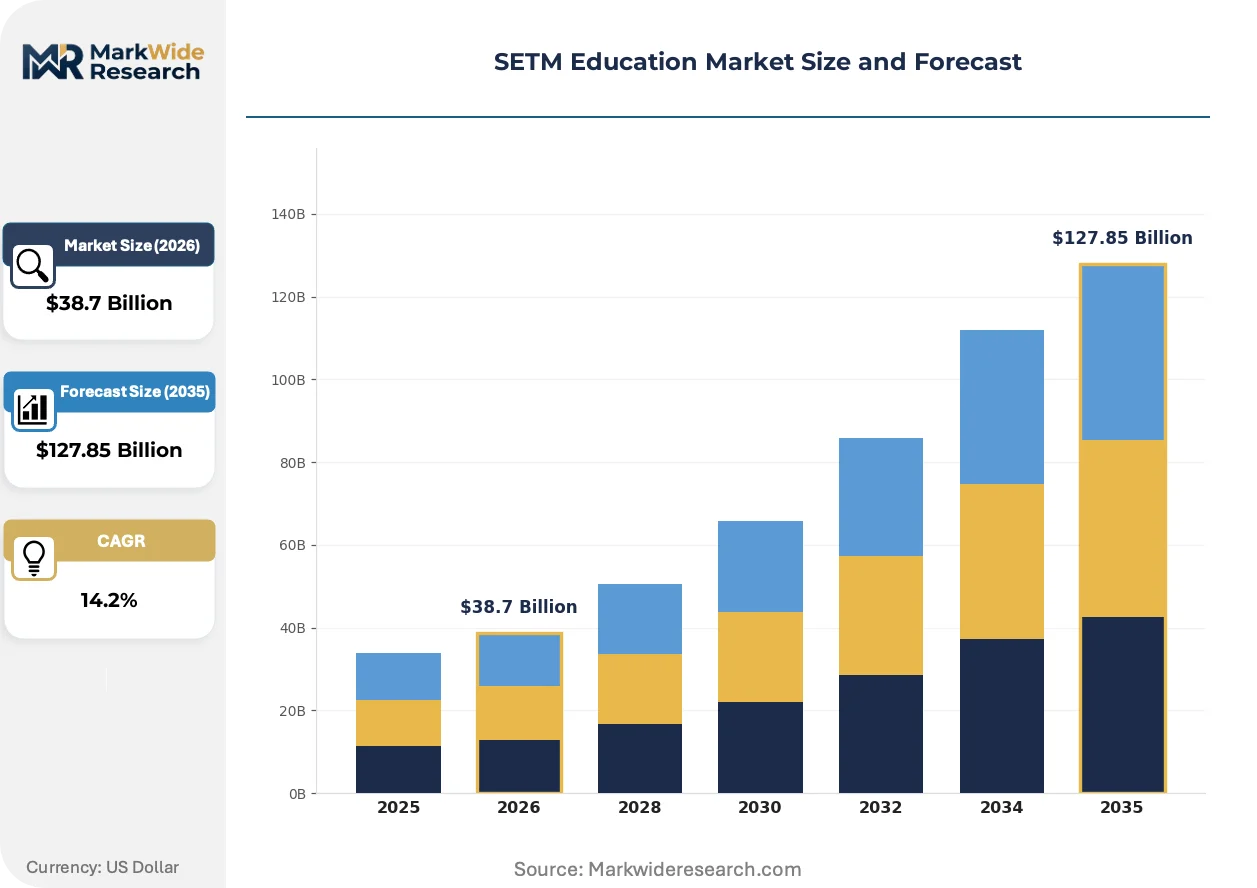
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: eLearning Platforms, Learning Management Systems, Virtual Classrooms, Assessment Tools Customer Type: K-12 Institutions, Higher Education, Corporate Training, Non-Profits Delivery Mode: Online, Blended, Hybrid, In-Person Application: Skill Development, Certification Programs, Academic Courses, Professional Development |
| Companies Covered | Amplify Education, Inc., Discovery Education, Houghton Mifflin Harcourt, McGraw Hill, Carolina Biological Supply Company, Cengage Learning, Kendall Hunt Publishing Company, PASCO Scientific, Lab-Aids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SETM Education Market Trends and Innovations
Generative AI capabilities are rewriting content production economics for curriculum developers while regulatory frameworks in Brussels and Beijing establish divergent compliance baselines for automated educational tools.
Virtual laboratory simulations built on browser-based WebGL rendering engines are supplanting physical equipment kits in introductory biology and chemistry courses. US suburban districts with constrained facilities budgets are adopting these platforms at accelerating rates. This technology is compressing the addressable market for entry-level sensor hardware while expanding total student lab access hours.
The EU AI Act's risk-based classification system for educational applications is forcing automated tutoring vendors to reengineer their recommendation algorithms for transparency and human oversight. Systems classified as high-risk must undergo third-party conformity assessment before CE marking. European K-12 procurement offices are now requiring AI Act compliance documentation in their RFP evaluation criteria, favoring vendors with established EU legal presence.
District-level buying committees are consolidating vendor relationships around integrated platform suites rather than point solutions for content, assessment, and lab management. This pattern is displacing standalone digital curriculum publishers who lack LMS or hardware integration capabilities. The consolidation is most visible in Texas and Florida, where state-level textbook adoption processes have shifted toward multi-year platform contracts with single primary vendors.
SETM Education Market Segmentation
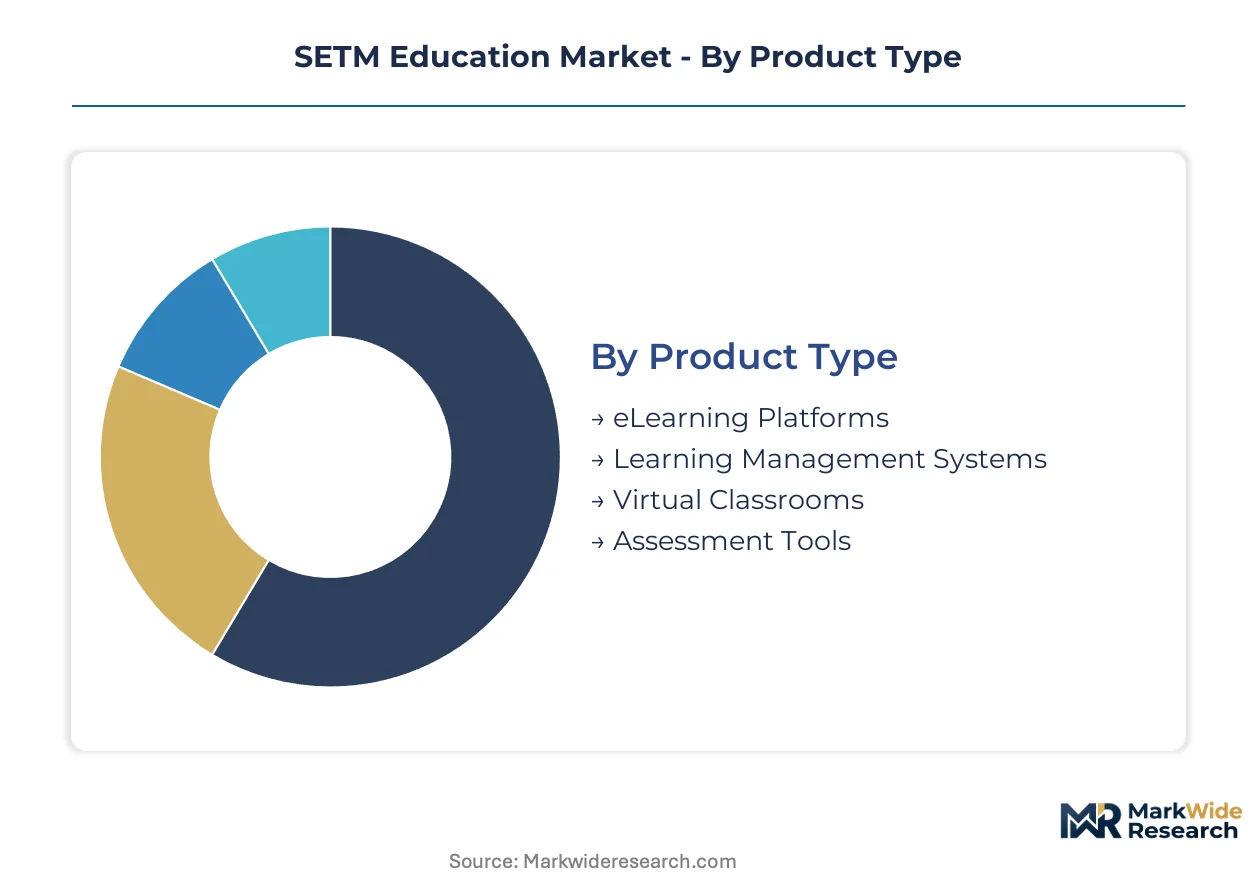
SETM education procurement patterns diverge sharply across institutional tiers, with K-12 districts favoring integrated platform suites while corporate buyers prioritize modular certification pathways. Understanding these segment boundaries clarifies where vendors must bundle versus specialize.
Product Type:
eLearning Platforms concentrate demand in China and India where provincial and state governments fund district-wide digital curriculum rollouts. Learning Management Systems anchor North American and European procurement through recurring institutional subscriptions.
- eLearning Platforms:Cloud-native content delivery systems hosting interactive science simulations, video lectures, and adaptive problem sets. Districts in Jiangsu and Guangdong provinces deploy these at scale for middle school physics and chemistry instruction, with provincial procurement lists favoring vendors offering Simplified Chinese localization and national curriculum alignment.
- Learning Management Systems:Microservices-based platforms managing enrollment, progress tracking, and assessment administration through API integrations with student information systems. US Title I-funded districts require FERPA-compliant data handling and Section 508 accessibility certification, extending vendor sales cycles but creating multi-year subscription lock-in once deployed.
- Virtual Classrooms:Synchronous video conferencing tools with breakout rooms, digital whiteboards, and real-time polling for remote lab instruction.
- Assessment Tools:Automated grading engines and competency-tracking dashboards for formative and summative evaluation.
Learning Management Systems command the established base. The steepest expansion runs through eLearning Platforms.
Customer Type:
Revenue per seat climbs from K-12 through corporate tiers, with certification content capturing 3-4x the unit economics of compulsory education materials. Non-profit deployment concentrates in development finance-backed rural connectivity programs.
- K-12 Institutions:Public and private primary and secondary schools procuring district-wide licenses for core science and mathematics instruction. Texas and Florida state adoption processes now favor multi-year platform contracts over discrete textbook purchases, consolidating vendor relationships around integrated suite providers.
- Higher Education:Universities and community colleges licensing discipline-specific content for undergraduate engineering and laboratory science courses. Research-intensive institutions in Germany and the Netherlands prioritize vendors with EU AI Act compliance documentation for automated tutoring components.
- Corporate Training:Enterprises purchasing technical certification curricula for cloud infrastructure, data analytics, and cybersecurity workforce development.
- Non-Profits:NGOs and foundation-funded programs delivering SETM access to underserved populations through grant-subsidized hardware and connectivity.
K-12 Institutions command the established base. The steepest expansion runs through Corporate Training.
Delivery Mode:
Cost structures stratify sharply between fully online and in-person modalities, with blended formats capturing premium pricing for flexibility while requiring higher instructional design investment.
- Online:Fully asynchronous or synchronous digital delivery without physical facility requirements. Rural US districts under the Infrastructure Investment and Jobs Act now access synchronous remote lab experiences previously unavailable, expanding addressable market for browser-based simulation providers.
- Blended:Scheduled alternation between digital content consumption and face-to-face laboratory or discussion sessions. Suburban US districts with constrained capital budgets adopt this format to maximize existing facilities while expanding course catalog breadth.
- Hybrid:Simultaneous in-person and remote participation enabling real-time inclusion of geographically dispersed students.
- In-Person:Traditional facility-based instruction with physical laboratory equipment and direct instructor contact.
In-Person delivery commands the established base. The steepest expansion runs through Blended formats.
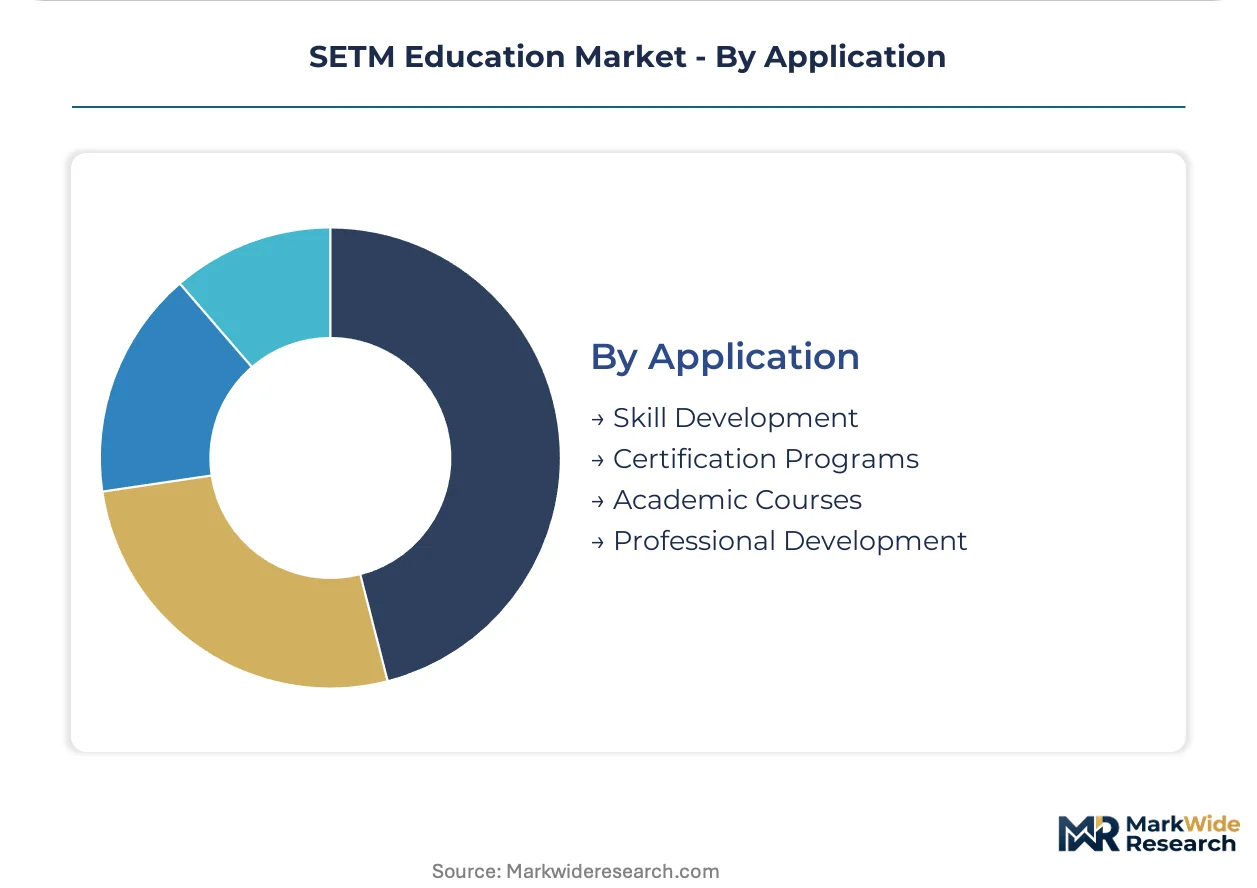
Application:
Skill Development and Certification Programs overlap increasingly as AWS Educate and similar cloud credential programs create standardized pathways bridging K-12 instruction with professional technical qualifications.
- Skill Development:Foundational competency building in coding, data literacy, and scientific methodology without formal credentialing. China's Ministry of Education mandates national curriculum standards determining which digital content qualifies for provincial procurement, favoring vendors with established local partnerships.
- Certification Programs:Structured preparation for vendor-specific or industry-standard technical credentials with examination alignment. Corporate buyers in the United States pay premium per-seat rates for content mapped to AWS, Microsoft Azure, and Google Cloud certification pathways.
- Academic Courses:For-credit instruction within formal degree or diploma programs at accredited institutions.
- Professional Development:Continuing education for practicing educators and technical professionals maintaining licensure or advancing specialization.
Academic Courses command the established base. The steepest expansion runs through Certification Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in educational technology tilt toward content and platform licensing flows from North American and European developers into Asian procurement markets, with hardware component trade running in reverse from East Asian manufacturing clusters.
United States
Title I funding rules and IDEA compliance requirements shape district procurement of federally subsidized digital tools. The Department of Education's documentation burdens extend vendor sales cycles. Texas and Florida state adoption processes favor multi-year platform contracts, consolidating vendor relationships in Austin and Tallahassee corridors.
China
Provincial governments in Jiangsu, Guangdong, and Zhejiang fund sensor-integrated science laboratories in public middle schools. The Ministry of Education mandates national curriculum standards determining equipment and digital content eligibility for procurement lists. Beijing-based content developers align with these standards to secure provincial placement.
Germany
Research-intensive universities prioritize vendors with EU AI Act compliance documentation for automated tutoring components. The Act's risk-based classification system requires third-party conformity assessment for high-risk educational applications. Berlin and Munich procurement offices now embed AI Act documentation requirements into RFP evaluation criteria.
United Kingdom
FERPA-equivalent data protection standards govern institutional subscription contracts for learning management systems. The Department for Education's digital strategy accelerates cloud-native platform adoption across academy trusts. London-based edtech clusters supply these platforms to Commonwealth markets.
India
State government digital education missions in Maharashtra, Karnataka, and Telangana drive district-wide eLearning platform deployments. The National Education Policy framework emphasizes experiential learning infrastructure in tier-2 cities. Hyderabad and Bangalore host developer ecosystems serving these procurement programs.
SETM Education Market Competitive Landscape
Concentration sits with legacy curriculum publishers transitioning print-to-digital against cloud-native platform developers capturing institutional subscription revenue. The competitive field splits between integrated suite providers bundling content, assessment, and lab management, and specialized hardware-integrated platform vendors defending sensor-based differentiation. Dominant competitive moves include API-driven LMS integrations with district student information systems and strategic partnerships bridging K-12 instruction with cloud certification pathways.
Within the legacy publisher tier, McGraw Hill and Houghton Mifflin Harcourt occupy positions sustained by institutional relationship depth and curriculum breadth. Discovery Education anchors the streaming media infrastructure segment with reach across millions of K-12 students. PASCO Scientific exemplifies the hardware-integrated specialist archetype, differentiating through proprietary laboratory sensor ecosystems paired with digital platforms.
| Leading Market Players |
|---|
| Amplify Education, Inc. |
| Discovery Education |
| Houghton Mifflin Harcourt |
| McGraw Hill |
| Carolina Biological Supply Company |
| Cengage Learning |
| Kendall Hunt Publishing Company |
| PASCO Scientific |
| Lab-Aids |
| Others |
Pricing and Supply Chain Analysis
EU AI Act conformity assessment requirements gate both vendor qualification and price differentiation simultaneously, forcing automated tutoring providers to absorb certification costs that translate into premium positioning for compliant systems while excluding non-compliant competitors from procurement shortlists.
Pricing Analysis
Configured-to-order pricing for custom curriculum integrations commands spreads of 40-60% above standard SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by FERPA compliance depth and API integration complexity. Cost compression in the standard tier is intensifying because open educational resource repositories expand substitute availability. Underfunded rural districts exhibit highest price sensitivity, while corporate training buyers show lowest elasticity for certification-aligned content.
Supply Chain Analysis
Just-in-time component sourcing for MEMS laboratory sensors clashes with strategic stockpile preferences for semiconductor inventory among hardware-integrated platform vendors. Manufacturing concentrates in China, South Korea, and Taiwan for sensor components and digital infrastructure. Proprietary hardware platforms draw from MEMS foundries, cloud server capacity, and specialized instructional design labor pools. Single-source vulnerability in MEMS sensor supply chains poses structural risk. Distribution runs through direct institutional sales teams and provincial procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open educational resource platforms and teacher-generated content tools threaten premium curriculum licensing, forcing incumbents to demonstrate measurable learning outcome differentiation against free substitutes.
For Market Incumbents: Shield core institutional relationships by embedding proprietary assessment algorithms into district student information systems, creating switching costs that neutralize open-resource substitution. Deepen backward integration into sensor hardware production to defend margin position against MEMS cost volatility. Prioritize EU AI Act compliance documentation as a competitive moat in European procurement.
For New Entrants and Emerging Players: AI governance advisory services represent the most penetrable service-layer gap, as established vendors under-serve districts navigating EU AI Act implementation. Target rural US districts gaining broadband access under Infrastructure Investment and Jobs Act funding, where synchronous remote lab experiences remain underserved. Lead with bundled compliance consulting to differentiate from content-only competitors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed curriculum publishers completing print-to-digital transitions. Long-term viability hinges on API integration density with district student information systems. Watch for inflection signals in provincial China procurement list placements, where Ministry of Education curriculum alignment determines multi-year contract access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with district SIS systems locks in recurring subscription revenue across Texas and Florida procurement corridors. |
| Certification Alignment | AWS Educate and Azure curriculum mapping captures premium corporate training pricing per seat. |
| Compliance Documentation | EU AI Act conformity assessment bundles create consulting revenue alongside automated tutoring sales. |
| Hardware-Platform Bundling | Proprietary sensor ecosystems paired with digital labs defend against browser-based simulation substitution. |
| Provincial Partnership | Jiangsu and Guangdong education bureau relationships secure placement on national curriculum procurement lists. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, Department of Education procurement databases, EU AI Act implementation guidance, and provincial China education bureau announcements. Interviews with curriculum directors, instructional technology officers, LMS procurement leads, and laboratory equipment specialists informed demand-side validation. Bottom-up district-level deployment estimates triangulate against top-down market sizing from platform vendor revenue disclosures.
Segmentation dimensions modeled include product type, customer tier, delivery mode, and application across the analysis window. CAGRs derive from enrollment trend projections, digital curriculum adoption curves, and equipment replacement cycle analysis. Inputs incorporate Title I funding allocation patterns, China provincial modernization mandates, and corporate certification program expansion trajectories.
Underlying assumptions cover sustained federal education funding levels, China provincial budget continuity, and EU AI Act enforcement timelines, with deviation risk concentrated in semiconductor supply chain disruptions and open educational resource quality improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market
Educational Technology (EdTech)
Education Technology Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Global AI in Education Market