
 US Anesthesiology Service Market | 2026-2036
US Anesthesiology Service Market Size, Share, and Industry Trends Forecast 2026-2036
US Anesthesiology Service Market Analytics
Certified registered nurse anesthetist supply is bifurcating the US Anesthesiology Service Market into staffing-intensive and technology-augmented delivery models. Envision Healthcare leverages its national hospital-based contracts to sustain geographic coverage across fragmented metropolitan markets. TeamHealth Holdings Inc. competes through employed-physician structures that anchor perioperative service lines in academic and community hospitals alike.
Anesthesiology service encompasses the preoperative evaluation, intraoperative management, and postoperative pain control delivered by physicians or supervised advanced practice providers, utilizing volatile agents, intravenous hypnotics, neuromuscular blockade, and multimodal analgesia to achieve reversible loss of consciousness or targeted neural blockade. General anesthesia maintains dominant revenue share within service type segmentation due to its necessity in major inpatient procedures, while monitored anesthesia care expands fastest as colonoscopy and endoscopy volumes shift to ambulatory settings. Orthopedic surgery application segments command substantial anesthesia hours given joint replacement frequency, though cardiovascular surgery retains premium reimbursement complexity.
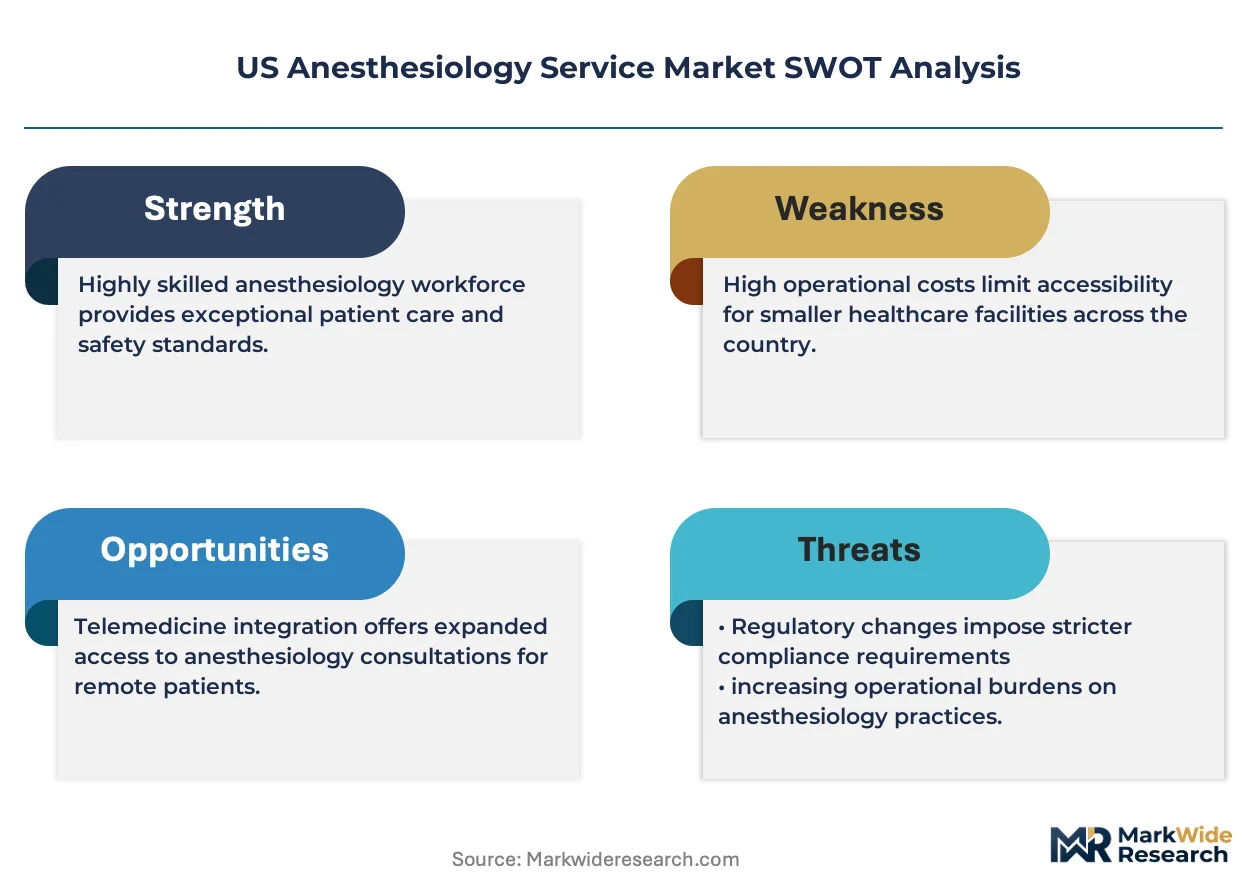
FDA oversight of anesthesia machines and advanced monitoring systems establishes device safety baselines, while CMS reimbursement rules directly shape hospital and ambulatory surgery center purchasing decisions for anesthesia staffing models. State medical boards and the Centers for Medicare & Medicaid Services jointly determine whether nurse anesthetists require physician supervision, creating regulatory patchwork that operators must navigate across multi-state footprints. Stakeholders should track evolving scope-of-practice legislation and CMS site-neutral payment proposals as these will determine whether independent anesthesia groups or health system employment models capture future margin pools.
Market Dynamics
CMS site-neutral payment proposals are compressing margins for hospital-based anesthesia groups while simultaneously accelerating ambulatory surgery center expansion, forcing operators to reconfigure staffing models and geographic footprints.
Growth Catalysts
- Ambulatory procedural migration:Colonoscopy and endoscopy volumes are shifting to freestanding surgical facilities, expanding monitored anesthesia care utilization beyond traditional hospital settings.
- Texas-Florida-California demand concentration:Large health systems in these states are consolidating anesthesia coverage through exclusive contracting arrangements that favor scaled operators.
- CRNA scope expansion:State-level supervision waivers under CMS conditions of participation are enabling workforce deployment models that reduce physician dependency ratios.
Market Restraints
- Physician supply concentration:Anesthesiologist training pipeline bottlenecks at ACGME-accredited programs limit specialty workforce expansion regardless of demand signals.
- Reimbursement compression:Medicare conversion factor updates lag inflation in practice costs, squeezing operating margins for independent group practices.
- Malpractice cost volatility:Premium spikes in high-litigation states like Florida and Illinois directly constrain market entry for new anesthesia service providers.
Strategic Opportunities
- Tele-anesthesia preoperative screening:Remote patient assessment platforms are opening rural and critical access hospital markets previously unreachable due to specialist scarcity.
- Regional anesthesia protocols:Enhanced recovery after surgery mandates from major payers are driving demand for nerve block and catheter-based analgesia services.
- ASC joint ventures:Equity participation in ambulatory surgery center development allows anesthesia groups to capture facility fee revenue streams alongside professional fees.
Industry Challenges
- CRNA-physician collaboration protocols:Navigating supervision requirements that vary by state medical board creates operational friction for multi-state anesthesia groups.
- Legacy EHR integration:Anesthesia information management systems require costly interface development with hospital-wide electronic health records.
- Quality reporting burden:MIPS and QPP participation demands data infrastructure investments that disproportionately strain smaller practice entities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Anesthesiology Service Market |
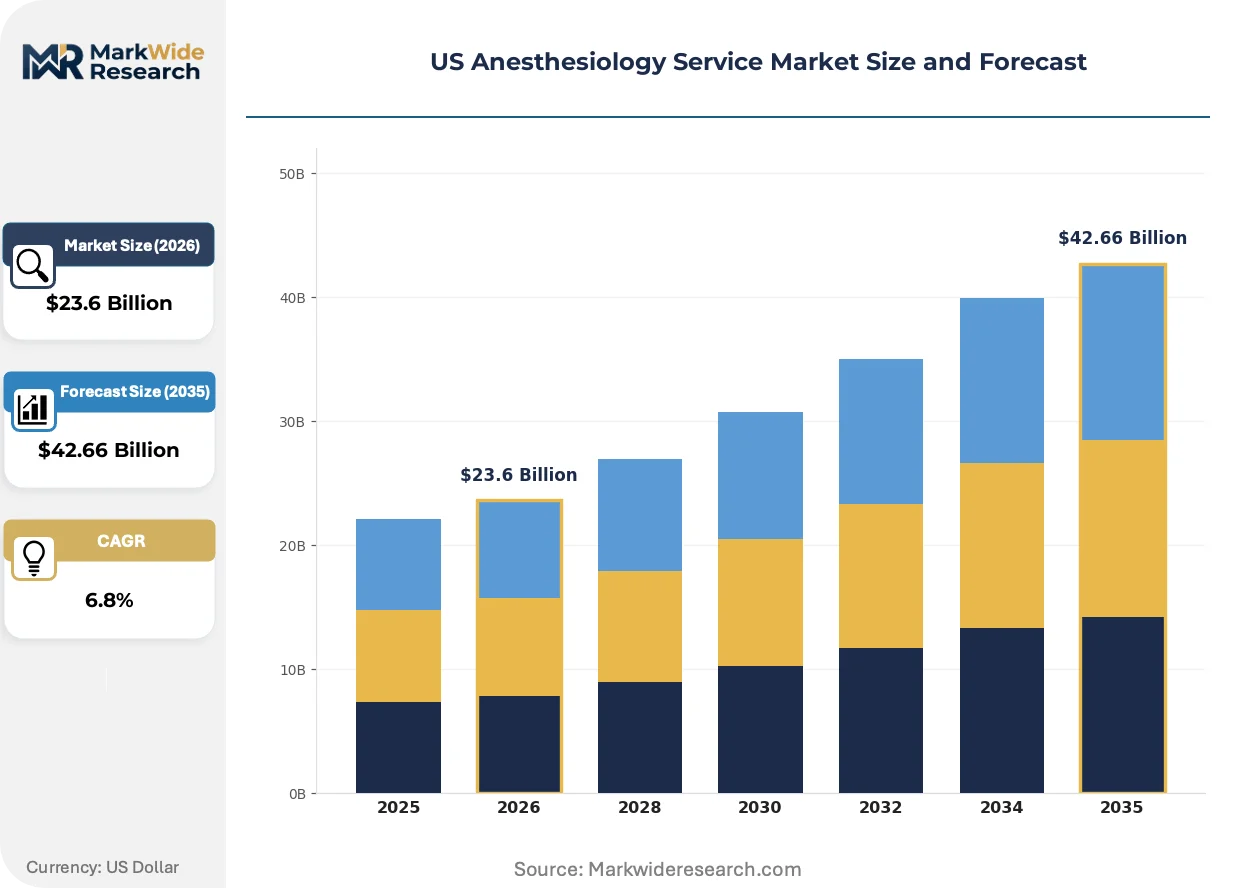
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Anesthesia, Regional Anesthesia, Sedation, Monitored Anesthesia Care End User: Hospitals, Ambulatory Surgery Centers, Clinics, Pain Management Facilities Technology: Advanced Monitoring Systems, Anesthesia Machines, Delivery Systems, Software Solutions Application: Orthopedic Surgery, Cardiovascular Surgery, Neurological Procedures, Obstetric Surgery |
| Companies Covered | Envision Healthcare, TeamHealth Holdings Inc., North American Partners in Anesthesia, US Anesthesia Partners, Mednax Services, American Anesthesiology, Somnia Anesthesia, Anesthesia Consultants of America, Sheridan Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Anesthesiology Service Market Evolving Landscape
Artificial intelligence applications and workflow automation are penetrating perioperative care, altering how anesthesia services are documented, billed, and clinically delivered across US health systems.
Closed-loop anesthesia delivery systems utilizing bispectral index monitoring and automated propofol titration are fragmenting traditional anesthesiologist oversight models. Academic medical centers in Massachusetts and California are piloting these platforms for routine cases, compressing the labor intensity of maintenance-phase anesthesia while redirecting physician attention to induction, emergence, and crisis management.
CMS conditions of participation for ambulatory surgery centers now mandate specific emergency preparedness protocols including difficult airway management capabilities. This regulatory tightening is forcing facility-level capital investment in video laryngoscopy and supraglottic airway devices, with California and New York ASCs leading compliance-driven procurement cycles.
Hospital systems are consolidating anesthesia purchasing through centralized procurement offices that negotiate system-wide professional service agreements. This buyer concentration is displacing traditional local group contracting in Texas and Florida, where HCA and Tenet facilities are standardizing vendor selection criteria across metropolitan clusters.
US Anesthesiology Service Market Segmentation
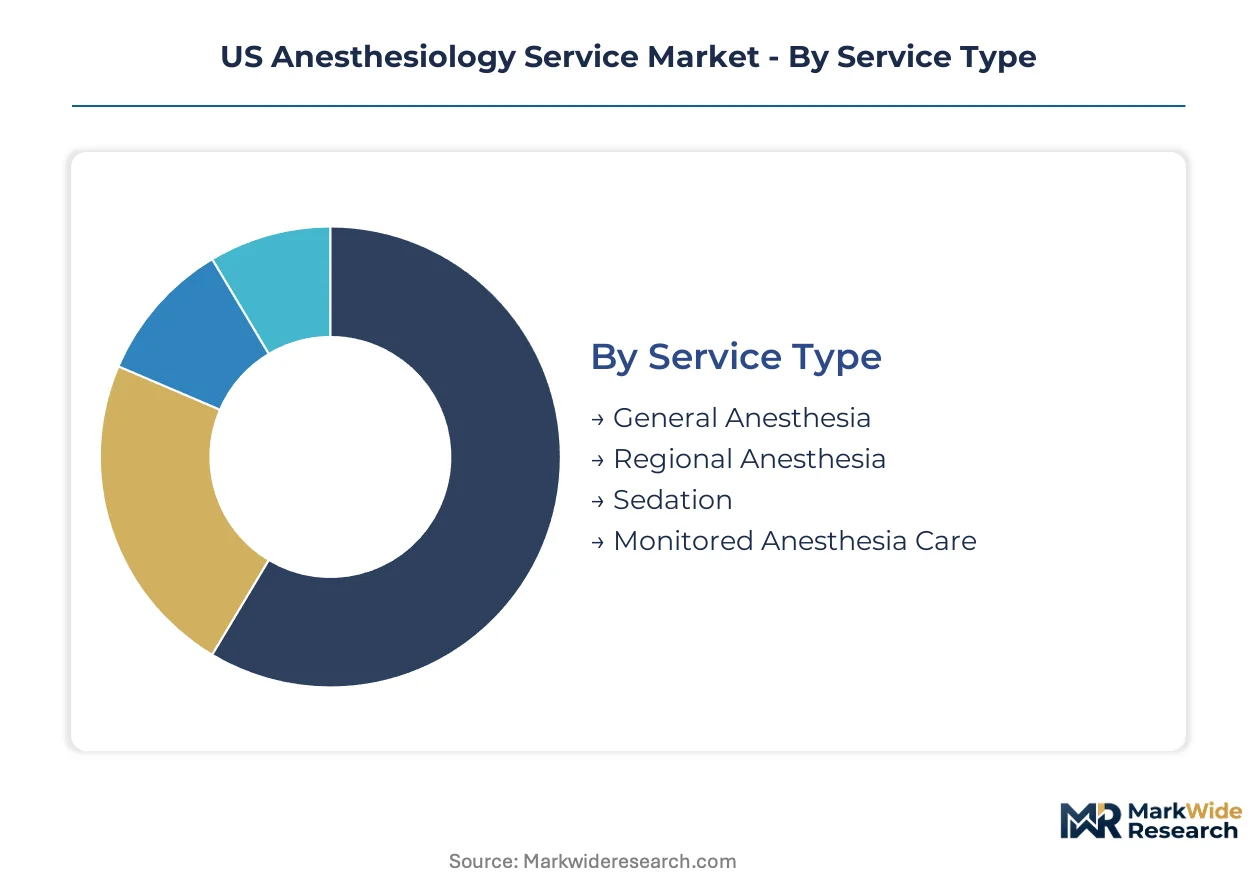
Segmentation reveals how anesthesia service revenue pools distribute across care settings and procedural types. Understanding these divisions exposes where workforce models, technology investments, and reimbursement strategies diverge.
Service Type:
Margin concentration tracks procedural complexity and staffing intensity, with high-acuity interventions commanding premium professional fees.
- General Anesthesia:Pharmacological induction of unconsciousness using volatile agents and intravenous hypnotics for major surgical procedures. Demand clusters in cardiovascular and neurological cases at academic medical centers in Texas and California, where physician supervision requirements sustain billing rates.
- Regional Anesthesia:Targeted neural blockade via epidural, spinal, or peripheral nerve techniques. Orthopedic surgery volumes in Florida and ambulatory joint replacement centers are accelerating catheter-based analgesia adoption for enhanced recovery protocols.
- Sedation:Conscious suppression of awareness for minor procedures without airway instrumentation. Dental and endoscopic applications in standalone clinics utilize this tier to minimize staffing overhead.
- Monitored Anesthesia Care:Physician or CRNA oversight of patient responsiveness during superficial procedures. Colonoscopy migration to freestanding ASCs in California and Texas is expanding utilization fastest.
The dominant share belongs to General Anesthesia, while Monitored Anesthesia Care is gaining share fastest.
End User:
Procurement authority and contracting sophistication vary sharply across facility types, shaping vendor selection criteria.
- Hospitals:Inpatient surgical towers and perioperative suites requiring 24/7 anesthesia coverage. Large health systems in Texas and Florida are consolidating purchasing through centralized procurement offices that negotiate system-wide professional service agreements.
- Ambulatory Surgery Centers:Freestanding facilities performing same-day procedures. CMS site-neutral payment proposals are accelerating ASC development in California, where HCA and Tenet facilities are standardizing anesthesia vendor selection across metropolitan clusters.
- Clinics:Office-based settings for minor procedures and preoperative evaluation. Rural critical access locations in Texas leverage tele-anesthesia screening to overcome specialist scarcity.
- Pain Management Facilities:Dedicated centers for chronic pain intervention and catheter placement. State-level scope-of-practice variations determine CRNA deployment feasibility.
Hospitals retain the largest revenue footprint, though Ambulatory Surgery Centers show the steepest expansion trajectory.
Technology:
Capital allocation priorities reflect regulatory mandates and labor substitution economics.
- Advanced Monitoring Systems:Bispectral index, cerebral oximetry, and hemodynamic tracking devices. FDA oversight establishes safety baselines that ASCs in New York and California must meet for emergency preparedness compliance.
- Anesthesia Machines:Integrated workstations for gas delivery, ventilation, and scavenging. Hospital replacement cycles concentrate in large Texas systems upgrading perioperative infrastructure.
- Delivery Systems:Syringe pumps, vaporizers, and regional anesthesia equipment. Academic centers in Massachusetts pilot closed-loop automated titration platforms.
- Software Solutions:Anesthesia information management systems for documentation and billing. Legacy EHR integration costs disproportionately strain smaller practice entities.
Advanced Monitoring Systems capture the dominant technology spend, while Software Solutions are climbing the fastest as quality reporting requirements intensify.
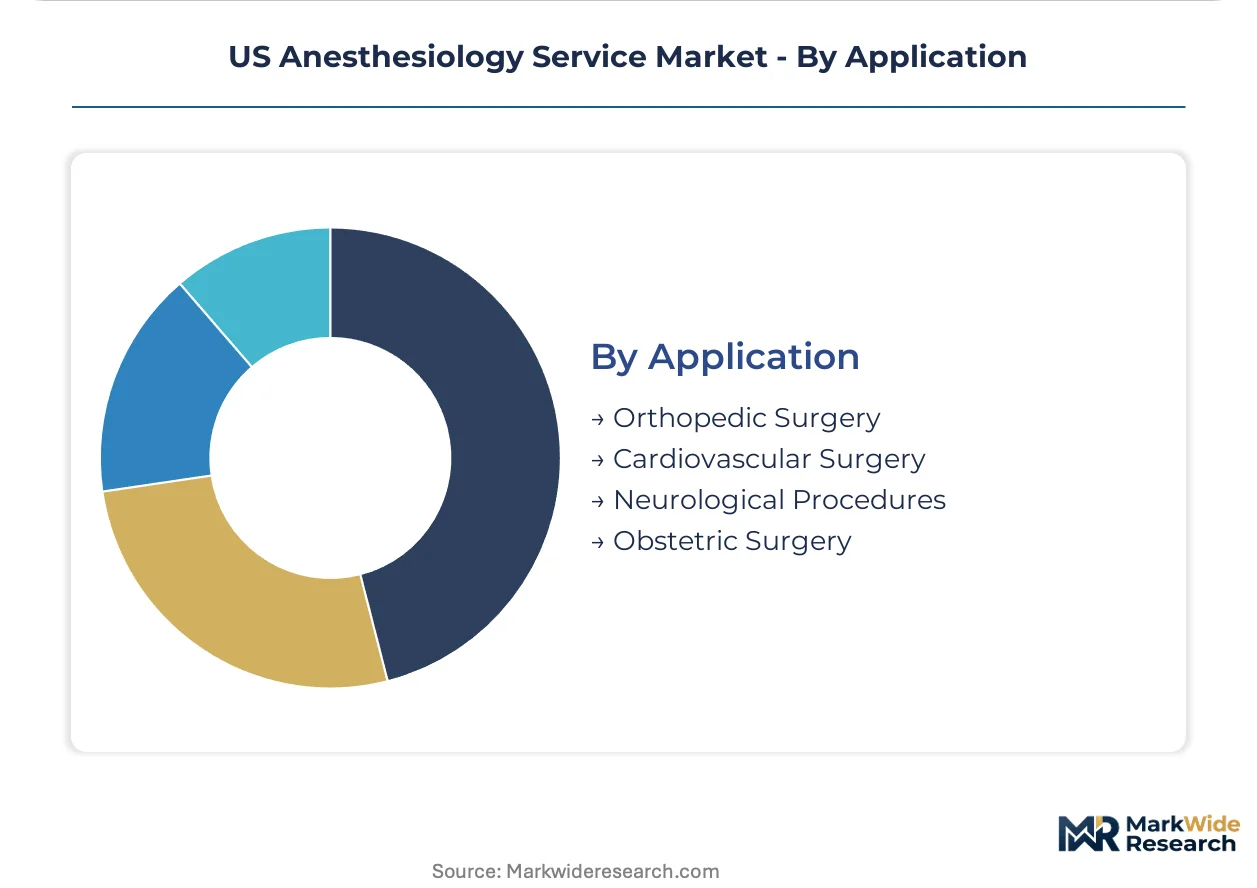
Application:
Procedural volume and reimbursement complexity determine anesthesia hour allocation across surgical specialties.
- Orthopedic Surgery:Joint replacement, arthroscopy, and fracture repair procedures. Aging demographics in Florida and Texas sustain high case volumes, with regional anesthesia protocols reducing opioid dependency.
- Cardiovascular Surgery:Coronary artery bypass, valve replacement, and aortic interventions. Premium reimbursement complexity retains anesthesiologist-intensive staffing despite workforce constraints.
- Neurological Procedures:Craniotomy, spine surgery, and interventional neuroradiology. Academic medical centers in California concentrate specialized expertise.
- Obstetric Surgery:Cesarean delivery and labor analgesia services. CRNA scope expansion in select states enables workforce deployment models that reduce physician dependency ratios.
Orthopedic Surgery commands the most anesthesia hours, while Cardiovascular Surgery maintains the highest revenue per case.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands premium anesthesia reimbursement rates that exceed Florida by 15-20 percent, while California's regulatory density compresses margins despite higher procedural volumes. This pricing-power asymmetry shapes where national groups deploy capital and talent.
Texas
HCA and Tenet health systems drive exclusive contracting consolidation across Dallas-Fort Worth and Houston metropolitan clusters. CMS conditions of participation for ambulatory surgery centers mandate specific emergency preparedness protocols that favor scaled operators with capital reserves. The Texas Medical Board maintains physician supervision requirements for nurse anesthetists, preserving anesthesiologist-intensive staffing models in academic medical centers.
Florida
Aging demographics sustain high orthopedic and cardiovascular procedural volumes in Tampa Bay and South Florida corridors. Malpractice premium volatility creates barriers to entry for independent groups, concentrating market share among established players with captive insurance structures. State-level scope-of-practice legislation permits CRNA practice without physician supervision in select settings, enabling workforce deployment flexibility.
California
Academic medical centers in Los Angeles and San Francisco pilot closed-loop anesthesia delivery systems for routine cases. FDA oversight of advanced monitoring devices intersects with state-level ASC licensing requirements to drive capital investment in video laryngoscopy and cerebral oximetry. Kaiser Permanente and Sutter Health consolidate anesthesia purchasing through centralized procurement offices.
Illinois
Chicago metropolitan health systems anchor perioperative service lines that extend into Wisconsin and Indiana border markets. Medicare conversion factor updates lag regional inflation in practice costs, squeezing operating margins for independent group practices. Northwestern Medicine and Advocate Aurora negotiate system-wide professional service agreements that displace local group contracting.
New York
Downstate hospital systems concentrate specialized neurological and cardiovascular anesthesia expertise in Manhattan and Long Island corridors. State medical board regulations require physician supervision for CRNA practice in most settings, sustaining billing rate premiums. Northwell Health and NYU Langone standardize anesthesia vendor selection across metropolitan clusters through centralized procurement.
US Anesthesiology Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. National staffing platforms with hospital-based contracts compete against regional employed-physician models anchored in academic and community hospitals. Two strategic archetypes dominate: scaled operators leveraging geographic coverage density, and specialty-focused groups capturing premium reimbursement through subspecialty certification. Consolidation through exclusive contracting arrangements and equity participation in ambulatory surgery center development represent the dominant competitive moves.
Within the national coverage tier, Envision Healthcare and TeamHealth Holdings Inc. exemplify divergent structural approaches to market presence. Envision Healthcare leverages national hospital-based contracts to sustain geographic coverage across fragmented metropolitan markets. TeamHealth Holdings Inc. competes through employed-physician structures that anchor perioperative service lines in academic and community hospitals alike. US Anesthesia Partners occupies a position representing consolidation of independent group practices into regional platforms.
| Leading Market Players |
|---|
| Envision Healthcare |
| TeamHealth Holdings Inc. |
| North American Partners in Anesthesia |
| US Anesthesia Partners |
| Mednax Services |
| American Anesthesiology |
| Somnia Anesthesia |
| Anesthesia Consultants of America |
| Sheridan Healthcare |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day staffing contract lead times in Texas and Florida anesthesia markets concentrate pricing power with national operators holding exclusive hospital agreements, while California's regulatory complexity extends procurement cycles and compresses margin capture. This temporal asymmetry across state-level supply configurations directly shapes where scaled groups deploy capital versus where regional players retain local negotiating leverage.
Pricing Analysis
Texas commands premium anesthesia reimbursement rates that exceed Florida by fifteen to twenty percent, reflecting HCA and Tenet purchasing concentration in metropolitan Dallas-Fort Worth and Houston clusters. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center contracts from community hospital arrangements and ambulatory surgery center bundled rates. Pricing pressure stems from CMS site-neutral payment proposals compressing hospital-based margins, with independent group practices in Illinois and New York exhibiting highest price sensitivity due to Medicare conversion factor lag against regional inflation.
Supply Chain Analysis
Ninety-day capital equipment procurement cycles for anesthesia machines and advanced monitoring systems tether facility-level investment decisions to FDA safety baseline compliance and state ASC licensing mandates. Manufacturing concentration for integrated workstations rests on domestic assembly operations in Texas and California, with specialized component sourcing from Massachusetts and Minnesota for closed-loop delivery platforms. Single-source vulnerability concentrates in volatile agent supply chains subject to pharmaceutical manufacturing disruption, while distribution runs through health system centralized procurement offices displacing traditional local group contracting in Florida and Texas metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anesthesia service markets present a compelling service-attach opportunity as monitored anesthesia care and postoperative pain management protocols expand faster than capital equipment replacement cycles, creating recurring revenue layers with superior margin profiles.
For Market Incumbents: Compound geographic coverage density through exclusive contracting consolidation in Texas, Florida, and California metropolitan clusters where HCA and Tenet facilities are standardizing vendor selection. Defend margin position by integrating tele-anesthesia preoperative screening capabilities to capture rural critical access hospital markets previously unreachable due to specialist scarcity, while navigating CRNA-physician collaboration protocol variations that create operational friction for multi-state footprints. For New Entrants and Emerging Players: Rural tele-anesthesia screening represents the most penetrable service-layer gap where national operators under-serve critical access hospitals in Texas border markets and Appalachian corridors. Target ASC joint venture equity participation in California and Florida where CMS site-neutral payment acceleration drives facility development, leveraging regional anesthesia protocol expertise as a differentiated go-to-market angle for orthopedic surgery centers adopting enhanced recovery mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across technology-augmented delivery models as closed-loop anesthesia systems reduce labor intensity, while physician-intensive staffing models retain higher fixed-cost structures. Acquisition targets should emphasize regional platforms with consolidated independent group practices and captive ASC equity positions, with the signal to watch being state-level scope-of-practice legislation expansion that enables CRNA deployment models reducing physician dependency ratios.| Strategic Initiative | Industry Significance |
|---|---|
| ASC Joint Venture Development | Captures facility fee revenue alongside professional fees in California and Texas expansion corridors. |
| Tele-Anesthesia Platform Deployment | Opens rural critical access markets previously unreachable due to anesthesiologist specialist scarcity. |
| Regional Anesthesia Protocol Integration | Aligns service offerings with major payer enhanced recovery mandates driving catheter-based analgesia demand. |
| CRNA Workforce Model Optimization | Exploits state supervision waivers under CMS conditions of participation to reduce physician dependency ratios. |
| Centralized Procurement Office Alignment | Secures system-wide professional service agreements with HCA, Tenet, and Kaiser Permanente purchasing clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with anesthesiology group administrators, hospital perioperative directors, ambulatory surgery center executives, and certified registered nurse anesthetist practice leaders. Secondary validation drew from CMS Medicare reimbursement databases, FDA medical device filings, state medical board scope-of-practice regulations, and GPO contract disclosure records. Bottom-up and top-down triangulation reconciled facility-level staffing deployment data with national health system expenditure aggregates.
Across the analysis window, forecasting incorporated service type segmentation by general anesthesia, regional anesthesia, sedation, and monitored anesthesia care, alongside end-user categories spanning hospitals, ambulatory surgery centers, clinics, and pain management facilities. CAGRs were derived from procedural volume trajectories, reimbursement rate assumptions, and workforce supply pipeline constraints specific to ACGME-accredited anesthesiologist training programs and CRNA graduation rates.
Forecasts assume regulatory continuity in CMS conditions of participation and state medical board supervision requirements; material policy shifts such as federal scope-of-practice preemption or site-neutral payment acceleration would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Global Anesthesia Gases Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Anesthetics Market
Anesthesiology
Delirium Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Sedation in ICU Setting Market