
 Artichokes Market | 2026-2036
Artichokes Market Size, Share, and Industry Trends Forecast 2026-2036
Artichokes Market Analysis
Asset-light leasing arrangements for controlled-atmosphere storage and processing equipment is narrowing the capital barrier for mid-scale growers seeking entry into value-added artichoke products. Ocean Mist Farms leverages its integrated California growing and packing operations to sustain year-round supply consistency for retail and foodservice clients. Caprichos del Paladar S.L.U. anchors its position through specialized Andalusian sourcing and artisanal processing methods that differentiate its preserved artichoke lines in European specialty channels. Bonduelle competes through global frozen and canned vegetable distribution networks that extend artichoke product reach into mass-market retail across multiple continents.
Artichokes comprise the edible flower buds of Cynara cardunculus var. scolymus, harvested before floral maturation when bract tightness and heart diameter meet commercial grading standards for fresh, processed, or extract applications. The primary commercial purpose centers on food consumption—whole bud preparation, heart extraction, and leaf-derived inulin or cynarin compound isolation for functional ingredients. Fresh artichokes dominate volume in Mediterranean procurement channels where perishability drives rapid turnover and premium pricing at origin. Canned artichokes capture the widest margin pool through extended shelf stability and foodservice portion control, while health supplements and nutraceuticals represent the fastest-expanding end-use as standardized extract formulations gain traction in digestive wellness positioning.
The USDA and FDA govern phytosanitary certification, pesticide tolerance thresholds, and processed food labeling standards that shape US import access and domestic product compliance requirements. REACH and EU Green Deal sustainability mandates from ECHA and European Commission frameworks are redirecting cultivation inputs and packaging specifications across Mediterranean supplier bases. Stakeholders must monitor evolving residue limit harmonization between EU and US standards while calibrating sourcing strategies against climate volatility in primary growing regions.
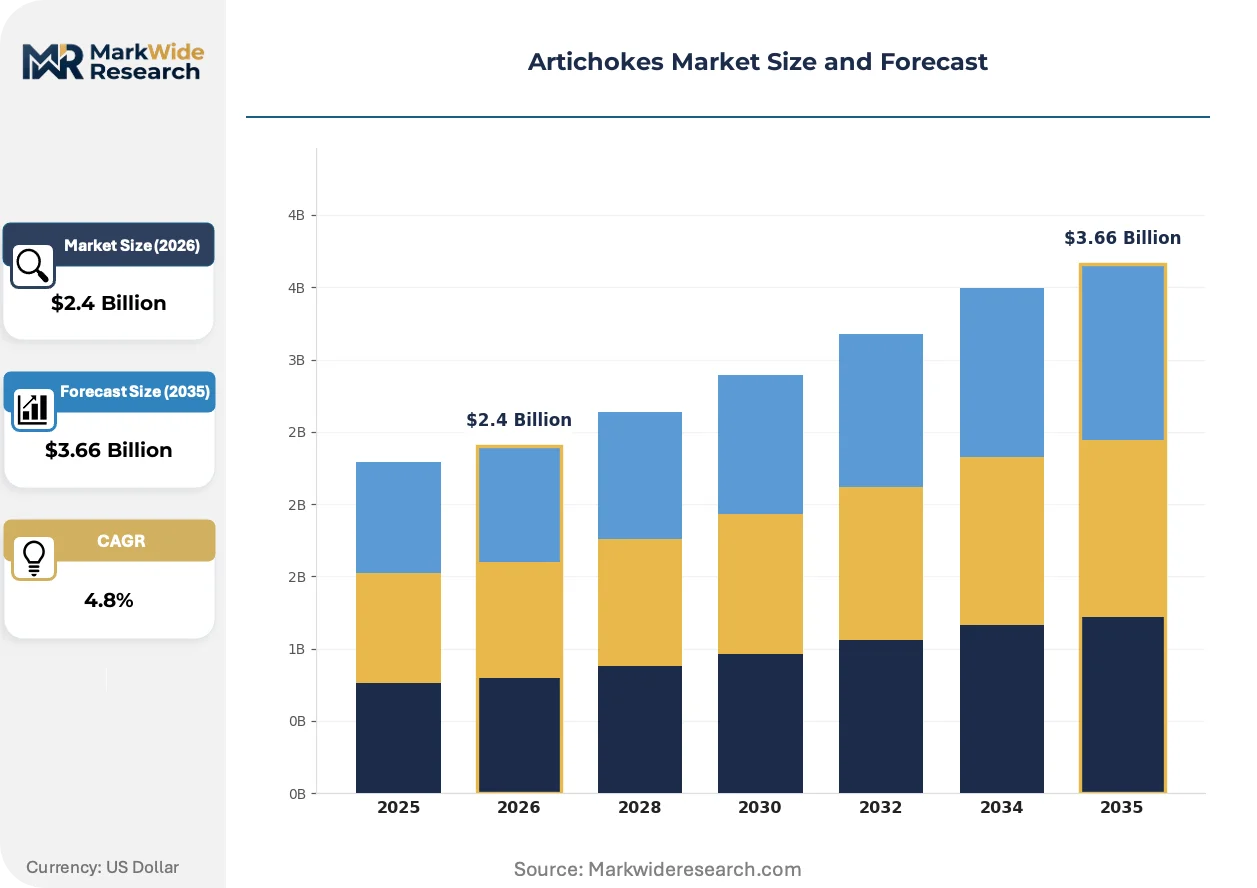
Market Dynamics
EU Green Deal pesticide residue limits and Farm to Fork Strategy mandates are compressing cultivation timelines and forcing Mediterranean growers toward integrated pest management systems that alter cost structures and sourcing geography.
Growth Catalysts
- REACH chemical compliance:Artichoke processors investing in residue testing infrastructure gain preferential access to EU retail channels that now require batch-level certification.
- Foodservice portion control demand:Mediterranean cuisine chains are standardizing artichoke heart specifications to reduce kitchen prep labor and waste.
- Andalusian cluster concentration:Spain's integrated growing and processing corridor offers year-round supply continuity that northern European buyers increasingly favor.
Market Restraints
- Input cost volatility:Nitrogen-based fertilizer prices fluctuate with natural gas benchmarks, squeezing margins for non-integrated growers.
- Single-region supply risk:Italy dominates canned artichoke processing capacity; climate shocks in Lazio or Campania disrupt global availability.
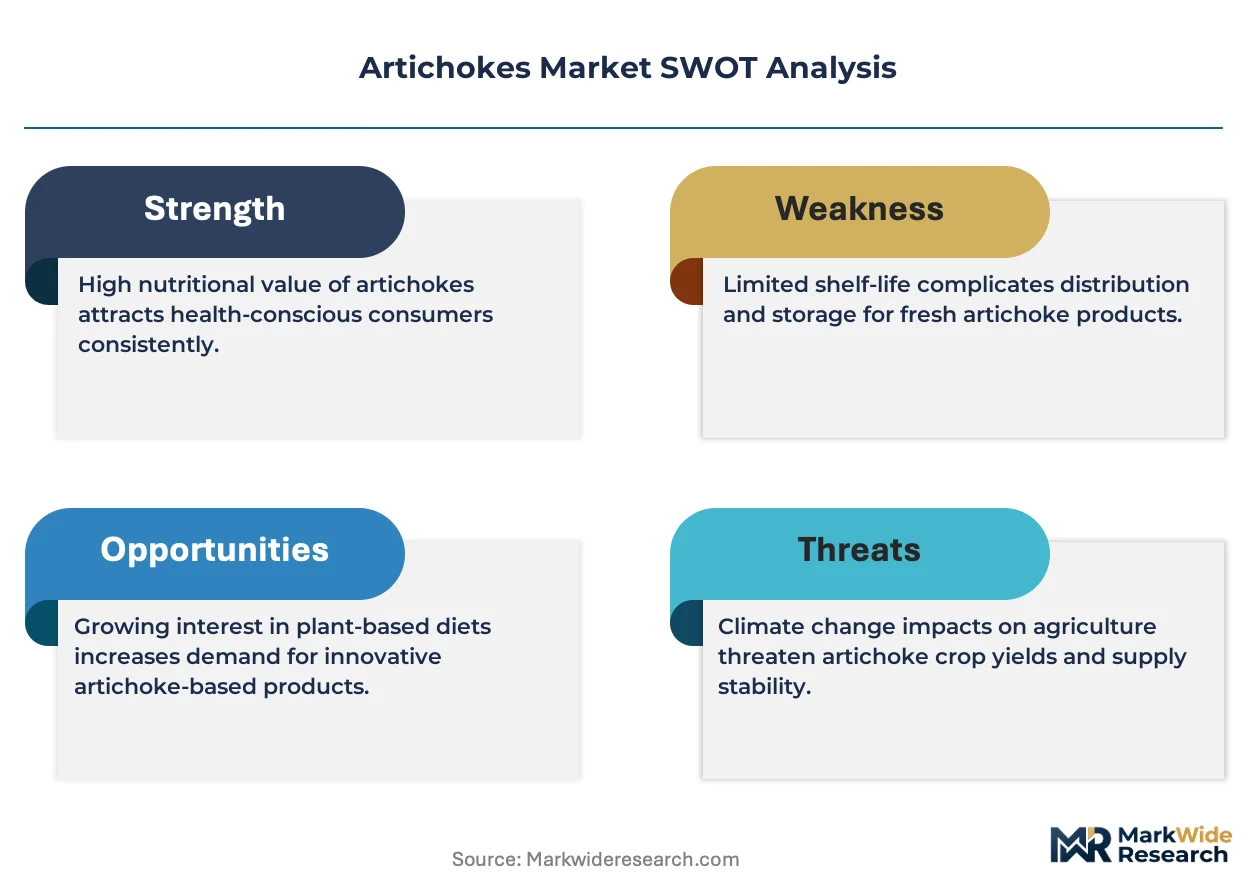
- Fresh perishability:Bract browning and moisture loss limit fresh artichoke distribution radius to 72-hour cold chains.
Strategic Opportunities
- Underpenetrated German retail:Discounter chains in Bavaria and Baden-Württemberg carry limited artichoke SKUs relative to Mediterranean markets.
- Nutraceutical extraction:Standardized cynarin formulations for digestive wellness supplements command price premiums over commodity canned goods.
- Controlled-atmosphere leasing:Third-party storage providers enable mid-scale growers to enter value-added processing without capital-intensive facility construction.
Industry Challenges
- Integrated pest management expertise:Growers lack technical capacity to substitute biological controls for synthetic pesticides under tightened EU residue limits.
- Dual certification timelines:Organic plus GlobalGAP accreditation requires 18-24 months, delaying market access for transitioning operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artichokes Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Artichokes, Canned Artichokes, Frozen Artichokes, Dried Artichokes End Use: Food Industry, Culinary Applications, Health Supplements, Nutraceuticals Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bulk Packaging, Retail Packaging, Vacuum-Sealed Packaging, Glass Jars |
| Companies Covered | Ocean Mist Farms, Caprichos del Paladar S.L.U., Anklam Extrakt GmbH, Agro T18 Italia Srl, Gaia Herbs Inc., Master Fruit Srl, Bonduelle, D'Arrigo Bros. Co., Herrawi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artichokes Market Emerging Trajectories
Processing technology and regulatory alignment are compressing traditional value chain steps, while buyer procurement models favor consolidated supply relationships over fragmented spot purchasing.
Modified atmosphere packaging with oxygen-scavenging films is collapsing the freshness gap between field-packed and centrally processed artichokes. Italian and Spanish processors are retrofitting packing lines with this technology to extend retail shelf life. The structural consequence is collapsing regional price premiums that previously justified local packing operations.
EU Green Deal sustainability mandates from the European Commission are redirecting cultivation inputs across Mediterranean supplier bases. REACH restrictions on active substances are eliminating several legacy pesticides from artichoke protection protocols. Processors in Campania and Andalusia are responding by vertically integrating into biological control propagation to secure compliant supply.
Consolidated procurement contracts are displacing spot-market purchasing among foodservice distributors. Large Mediterranean restaurant chains now demand multi-year supply agreements with residue guarantees and volume commitments. This shift is most visible in France, where procurement directors at major hospitality groups have centralized artichoke sourcing decisions previously made at regional level.
Artichokes Market Segmentation
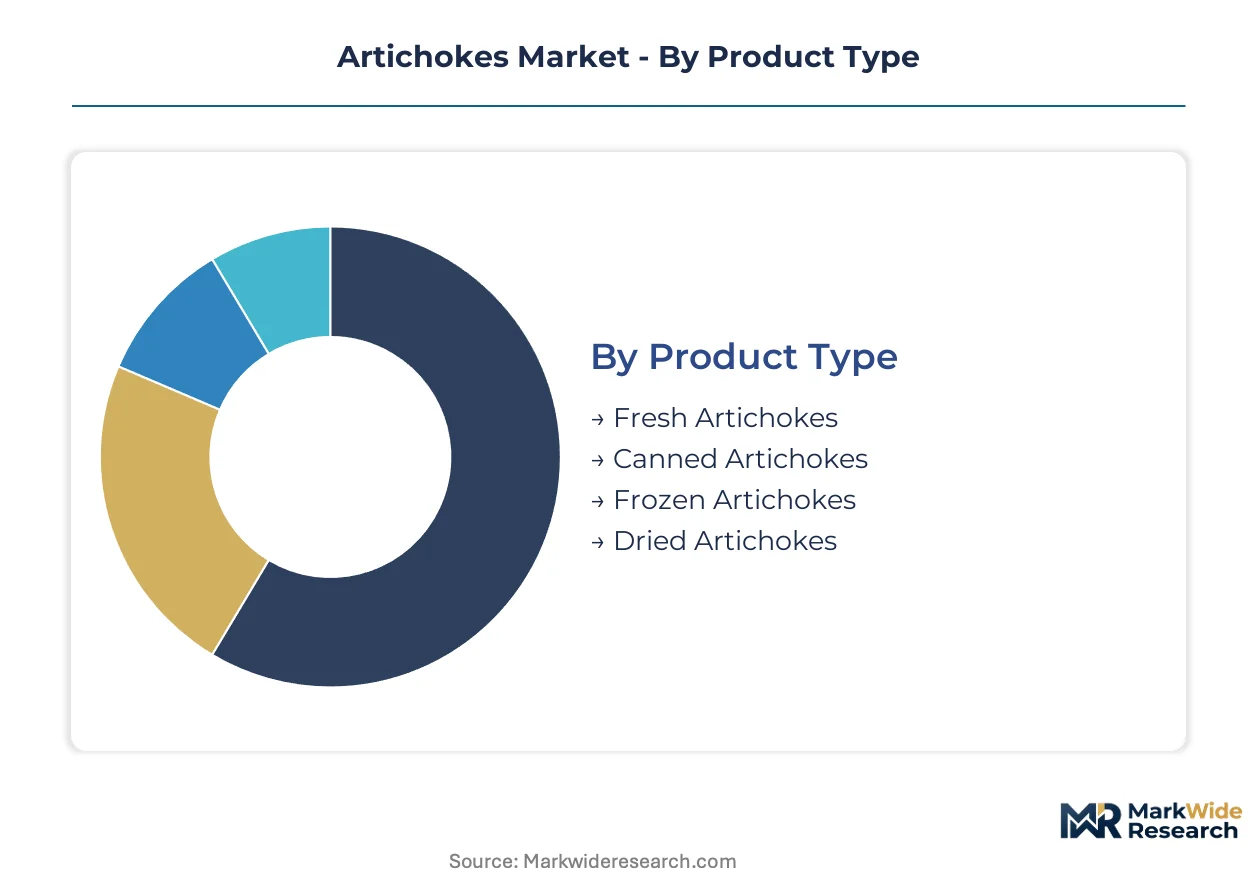
Artichoke procurement patterns diverge sharply across product formats, with perishability dictating channel economics and processing depth determining margin capture. End-use applications span commodity foodservice through high-value extract isolation, each segment carrying distinct certification and supply chain requirements.
Product Type:
Mature formats dominate current revenue pools while emerging preservation technologies unlock new distribution reach.
- Fresh Artichokes:Harvested at tight-bract maturity for immediate consumption, these buds require continuous cold chain maintenance below 4°C. Mediterranean restaurant chains in Italy and Spain specify 48-hour field-to-kitchen windows, with Campania growers capturing premium pricing through varietal differentiation.
- Canned Artichokes:Brine-packed hearts and quarters deliver 24-month shelf stability that foodservice distributors favor for inventory predictability. Lazio processors supply private-label programs for French and German retail chains under EU Green Deal residue protocols.
- Frozen Artichokes:IQF processing preserves cellular structure for industrial ready-meal formulations. Demand concentrates with European frozen vegetable packers seeking year-round raw material continuity.
- Dried Artichokes:Dehydrated leaves and hearts serve specialty ingredient channels and extract feedstock applications. Italian nutraceutical processors source these for cynarin concentration protocols.
Fresh artichokes retain volume leadership; health supplement-grade dried material holds the steepest expansion curve.
End Use:
Application tiers separate commodity food processing from premium wellness positioning, with regulatory intensity escalating across the value ladder.
- Food Industry:Industrial processors incorporate artichoke hearts into frozen pizzas, dips, and antipasti mixes. Bonduelle and similar operators specify calibrated heart diameters for automated production lines.
- Culinary Applications:Chefs in Mediterranean cuisine chains demand consistent brine acidity and tender heart texture for à la carte preparation. Spanish foodservice distributors consolidate procurement through Andalusian supply contracts.
- Health Supplements:Standardized cynarin extracts target digestive wellness positioning in German and Italian pharmacy channels. EFSA health claim scrutiny shapes formulation strategies.
- Nutraceuticals:Clinical-grade inulin and polyphenol isolates command pharmaceutical-tier pricing. REACH-compliant solvent extraction infrastructure limits viable suppliers to Campania and Sicily.
Culinary applications anchor current procurement volumes; nutraceutical extraction climbs fastest as pharmacy channel penetration deepens.
Distribution Channel:
Channel selection determines margin retention and brand control, with direct relationships displacing traditional wholesale intermediation.
- Supermarkets:Multinational retail groups in France and Germany negotiate private-label artichoke programs with residue certification requirements. Modified atmosphere packaging investments enable extended shelf-life claims.
- Online Retail:Direct-to-consumer platforms aggregate artisanal preserved artichoke producers for specialty food enthusiasts. Logistics constraints favor non-perishable formats.
- Specialty Stores:Italian and Spanish delicatessen channels stock DOP-branded artichoke products with provenance documentation. Margin structures support small-batch processing economics.
- Wholesale:Foodservice distributors in Paris and Madrid maintain inventory positions for restaurant chain accounts. Consolidated procurement contracts now specify multi-year volume commitments.
Supermarket channels retain volume leadership; specialty store distribution gains share fastest as provenance differentiation intensifies.
Packaging Type:
Packaging technology investments separate commodity handlers from premium positioning, with sustainability mandates reshaping material specifications.
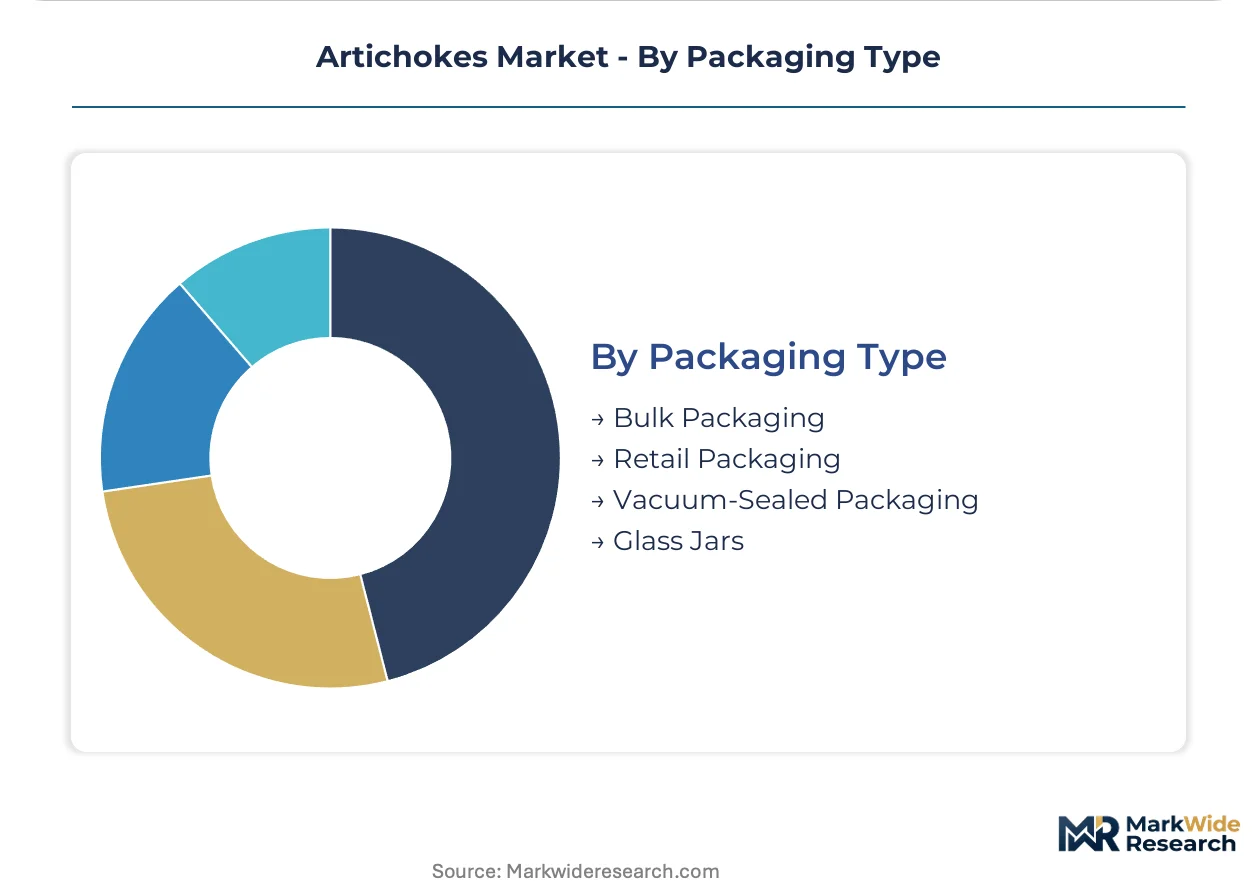
- Bulk Packaging:Food industry processors receive artichoke hearts in industrial totes for immediate formulation. Cost minimization drives format selection.
- Retail Packaging:Consumer-facing formats incorporate oxygen-scavenging films and resealable features. Italian packers retrofit lines to meet EU Green Deal plastic reduction targets.
- Vacuum-Sealed Packaging:Extended shelf-life applications for fresh artichokes and marinated products. Modified atmosphere technology narrows freshness gaps with field-packed alternatives.
- Glass Jars:Premium preserved artichoke presentations for specialty retail and gift channels. Andalusian processors favor this format for artisanal positioning.
Retail packaging retains volume leadership; vacuum-sealed formats expand most quickly as freshness technology costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances define regional artichoke economics, with Mediterranean processing clusters supplying deficit markets in Northern Europe and North America. Trade flows concentrate through Italian canning infrastructure and Spanish fresh corridors, while regulatory divergence between EU Green Deal standards and FDA import protocols shapes competitive access.
Italy
Domestic processing capacity for canned and marinated artichokes remains unmatched globally, with Campania and Lazio hosting the densest concentration of brine-packing facilities. EFSA residue protocols under EU Green Deal mandates now require batch-level certification for retail channel access. Naples-area processors are retrofitting lines with modified atmosphere technology to extend shelf-life claims for German supermarket private-label programs.
Spain
Andalusian growing corridors supply year-round fresh artichokes to French and British foodservice distributors seeking supply continuity. REACH chemical compliance investments by Seville-based processors have secured preferential EU retail placement as residue limits tighten. The Cádiz-Jerez cluster anchors artisanal preserved product positioning through glass-jar formats targeting specialty channels.
United States
California's Central Valley and Monterey County sustain integrated growing-packing operations serving domestic retail and foodservice accounts. USDA phytosanitary certification and FDA pesticide tolerance thresholds govern import access for Mediterranean suppliers seeking market entry. Ocean Mist Farms leverages captive California production to guarantee year-round supply consistency against seasonal import volatility.
Germany
Bavarian and Baden-Württemberg discounter chains carry limited artichoke SKU penetration relative to Mediterranean markets, creating expansion headroom for compliant suppliers. ECHA REACH restrictions on legacy active substances are eliminating several pesticides from protection protocols used by southern European growers. Frankfurt-based foodservice distributors are consolidating procurement through multi-year supply agreements with Spanish processors.
France
Paris and Lyon hospitality groups have centralized artichoke sourcing decisions previously managed at regional level, favoring consolidated supplier relationships. EU Green Deal sustainability mandates are redirecting cultivation input specifications across Italian and Spanish supplier bases. Provence-Alpes-Côte d'Azur retail channels stock DOP-branded provenance products with margin structures supporting small-batch processing economics.
Artichokes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and extract supply. The vendor base separates between vertically integrated growing-packing operations and specialized processors focused on single format dominance. Three archetypes prevail: Mediterranean heritage processors with DOP provenance positioning, North American integrated growers with year-round supply guarantees, and botanical extract specialists serving pharmacy and nutraceutical channels. Competitive moves concentrate on backward integration into biological control propagation and multi-year procurement contract consolidation.
Within the heritage processor tier, Caprichos del Paladar S.L.U. and Agro T18 Italia Srl exemplify Andalusian and Campanian provenance-based positioning respectively. Ocean Mist Farms anchors the integrated North American grower archetype through captive California production. Anklam Extrakt GmbH occupies the extract specialist position, representing German pharmaceutical-tier processing infrastructure for standardized compound isolation.
| Leading Market Players |
|---|
| Ocean Mist Farms |
| Caprichos del Paladar S.L.U. |
| Anklam Extrakt GmbH |
| Agro T18 Italia Srl |
| Gaia Herbs Inc. |
| Master Fruit Srl |
| Bonduelle |
| D'Arrigo Bros. Co. |
| Herrawi Group |
| Others |
Supply Flow & Price Mechanics
Barcelona-Marseille freight corridors carry fresh artichoke shipments where fuel surcharge volatility compresses margins for non-integrated Andalusian growers while enabling Campanian processors to command premium spreads on shelf-stable formats.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on residue certification grade and volume scale. Pricing pressure stems from nitrogen fertilizer cost compression that squeezes non-integrated Mediterranean growers. Foodservice distributors show least price sensitivity due to portion-control labor savings, while private-label retail buyers negotiate hardest on per-unit costs.
Supply Chain Analysis
Extended payment terms from Seville-based processors to Campanian canners illustrate working capital intensity across the value chain. Supply concentrates in Italy, Spain, and California, with raw material flows drawing from artichoke bud feedstock, brine formulations, and modified atmosphere packaging films. Single-region processing vulnerability in Lazio creates structural risk. Distribution runs through consolidated foodservice procurement contracts and supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as nutraceutical extraction penetration in German pharmacy channels accelerates adoption curves for standardized cynarin formulations.
For Market Incumbents: Harden biological control propagation capabilities to preempt EU Green Deal residue limit tightening that threatens synthetic pesticide-dependent supply bases. Deepen backward integration into captive Andalusian growing operations to defend margin structures against input cost volatility from natural gas-linked fertilizer benchmarks. For New Entrants and Emerging Players: Establish a beachhead in German discounter retail where artichoke SKU penetration lags Mediterranean benchmarks. Target Bavarian and Baden-Württemberg chains with REACH-compliant canned formats. Pursue controlled-atmosphere leasing partnerships to bypass capital-intensive facility construction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extract specialists with pharmaceutical-tier solvent infrastructure over commodity canners facing margin compression. Long-term viability rests on pharmacy channel penetration depth. Watch EFSA health claim authorization timelines as inflection signals for nutraceutical tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Control Propagation | EU Green Deal residue mandates eliminate legacy pesticides, forcing backward integration into compliant supply. |
| Controlled-Atmosphere Leasing | Third-party storage providers enable mid-scale growers to enter value-added processing without facility construction. |
| REACH Certification Investment | Batch-level residue testing infrastructure secures preferential placement in tightening EU retail channels. |
| Nutraceutical Extraction Scale-Up | Standardized cynarin formulations command pharmaceutical-tier pricing in German digestive wellness positioning. |
| Multi-Year Procurement Contracts | Consolidated agreements with French hospitality groups displace fragmented spot purchasing. |
Methodological Framework
Desk research of trade flow databases, EU regulatory filings, and foodservice procurement records preceded structured interviews with artichoke processors, agricultural input suppliers, retail category buyers, and nutraceutical formulators. Bottom-up volume estimates from growing region acreage and yield data were triangulated against top-down demand aggregation across end-use segments.
Assumptions around EU Green Deal implementation pace, fertilizer price normalization, and pharmacy channel adoption curves were held fixed across baseline scenarios while climate volatility and regulatory acceleration were stress-tested. Segmentation modeling spanned product format, end-use application, distribution channel, and packaging technology dimensions. CAGRs were derived from trend extrapolation of historical volume-price relationships calibrated against stakeholder interview inputs.
Stress conditions across nitrogen fertilizer benchmarks, EFSA residue protocol timelines, and German retail SKU expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dehydrated Vegetables Market
Vegetables
Qatar Greenhouse Market
Vegetables
Dried Vegetable Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Europe Christmas Tree Market
Vegetables
Canada Microgreens Market
Vegetables
Air Dried Vegetables Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Field Peas Market
Vegetables
Dry Onion Market
Vegetables
Vegetable Chutney Market
Vegetables
South America Peas Market
Vegetables
Global Mushroom Market
Vegetables
Vegetable Grader Market
Vegetables
Garlic Market
Vegetables
Asia-Pacific Peas Market