
 Aquaculture Products Market | 2026-2036
Aquaculture Products Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Products Market Analysis
Plant-based and insect-derived protein is shifting feed formulations across Atlantic salmon and shrimp operations. Mowi ASA leverages its integrated feed-to-fork model across Norwegian and Scottish waters. Thai Union Group PCL anchors its supply chain through Thai and Vietnamese processing facilities for value-added seafood exports. Bakkafrost P/F dominates Faroese production with stringent biological controls and limited site licensing.
Aquaculture products encompass live organisms, processed seafood, feeds, equipment, and health inputs raised or manufactured under controlled aquatic conditions, with protein content typically exceeding 15% in finfish and shellfish destined for human consumption. The primary purpose centers on supplying protein for human diets, restocking wild fisheries, and supporting ornamental trade. Feed formulations command the largest value pool within product type segmentation due to recurring volume intensity in grow-out operations. Shellfish farming represents the fastest-expanding application segment, driven by lower feed conversion ratios and carbon-negative filtering properties. Direct sales channels capture premium margin pools by eliminating intermediary markups for large-scale commercial farm contracts.
The EU's EFSA and REACH frameworks govern chemical residues and feed additive approvals, while Norway's national veterinary institute enforces strict pathogen monitoring for infectious salmon anemia. The US FDA and NOAA jointly oversee seafood safety under the Food Safety Modernization Act and Magnuson-Stevens Fishery Conservation Act, creating layered compliance obligations for cross-border suppliers. China's MEE and GB standards regulate wastewater discharge from intensive pond systems, particularly in Guangdong and Hainan production zones. Stakeholders must monitor evolving certification thresholds for Aquaculture Stewardship Council and Best Aquaculture Practices labels as retail procurement policies harden.
Market Dynamics
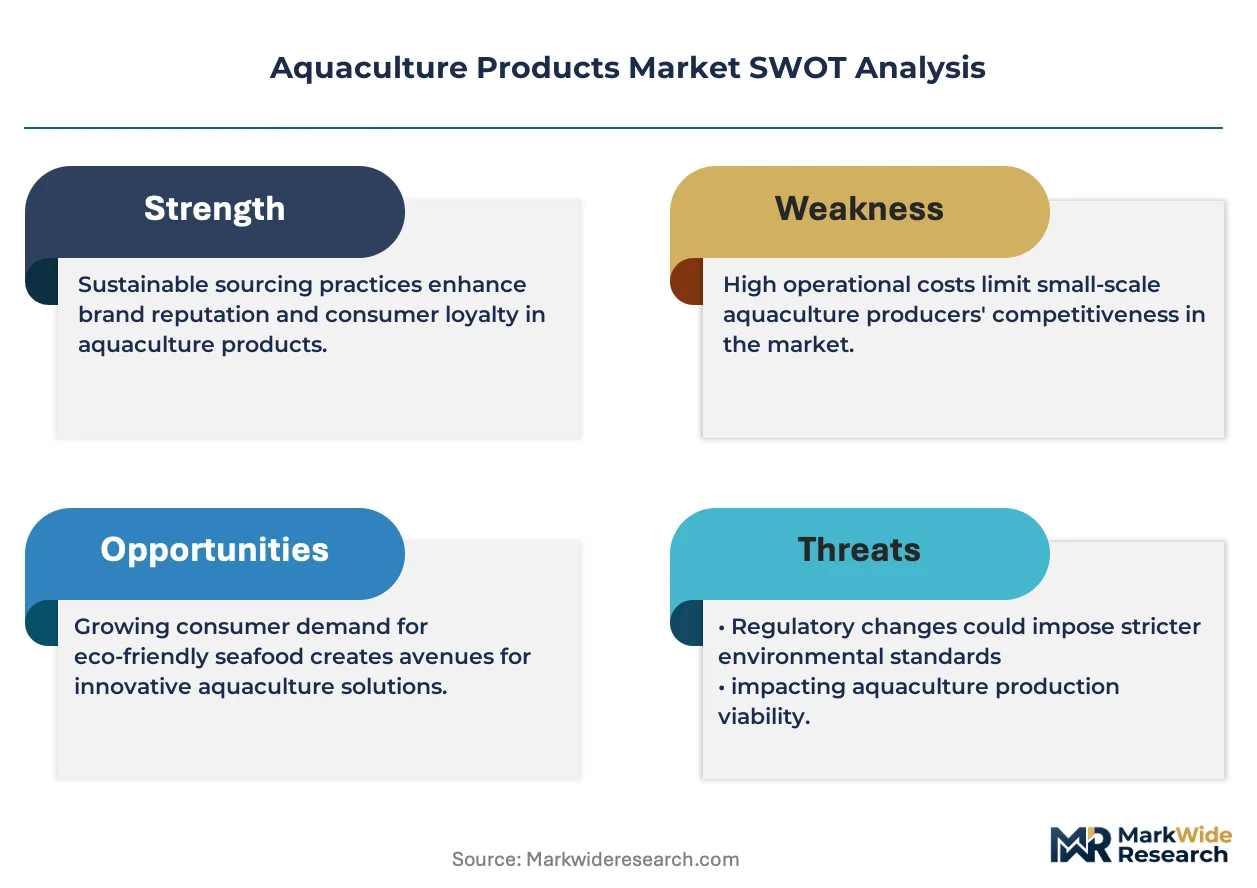
Feed cost volatility and pathogen pressure are compressing margins across Atlantic salmon and shrimp grow-out operations, forcing consolidation around vertically integrated producers with captive hatchery and formulation capabilities.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainability disclosure under the Green Deal is redirecting procurement toward ASC-certified suppliers, tightening import eligibility for non-compliant Asian processors.
- Recirculating Aquaculture Systems (RAS):Land-based closed-containment technology is de-risking production from algal blooms and thermal shifts, attracting institutional capital to smolt and full-cycle salmon operations.
- Southeast Asian foodservice expansion:Hotel and restaurant chains in Vietnam, Thailand, and Indonesia are formalizing direct contracts with Mekong Delta pangasius integrators, bypassing traditional auction markets.
Market Restraints
- Marine ingredient cost spikes:Peruvian anchovy quota volatility and competing demand from pet nutrition are squeezing fishmeal and fish oil input economics for premium feed formulations.
- Norwegian site licensing scarcity:The Norwegian Food Safety Authority's strict MAB (maximum allowable biomass) limits and fallowing mandates constrain expansion in the dominant Atlantic salmon production corridor.
- Pathogen amplification risk:Intensive monoculture practices in Guangdong and Hainan pond systems accelerate white spot syndrome virus and streptococcus outbreaks, requiring costly biosecurity retrofitting.
Strategic Opportunities
- Indonesian archipelago development:Underutilized brackish water areas in Sulawesi and Kalimantan offer expansion terrain for vannamei shrimp farming with lower land competition than Vietnam or Ecuador.
- Insect protein feed convergence:Black soldier larva meal combined with single-cell proteins from fermentation is creating novel formulation pathways that reduce marine dependency.
- Direct-to-retail channel bypass:E-commerce platforms and subscription seafood boxes are capturing margin pools previously absorbed by foodservice distributors and wholesale auctions.
Industry Challenges
- Genetic breeding talent scarcity:Selective breeding programs for disease resistance and growth rates require molecular biology and quantitative genetics expertise that outpaces university pipeline output in producing regions.
- Multi-certification compliance burden:Simultaneous ASC, BAP, and national organic audits create administrative overhead and timeline friction for exporters serving differentiated retail channels.
- RAS capex intensity:Full-cycle salmon recirculating systems demand 3-5x capital per ton of annual production versus net-pen alternatives, constraining deployment to well-capitalized operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Products Market |
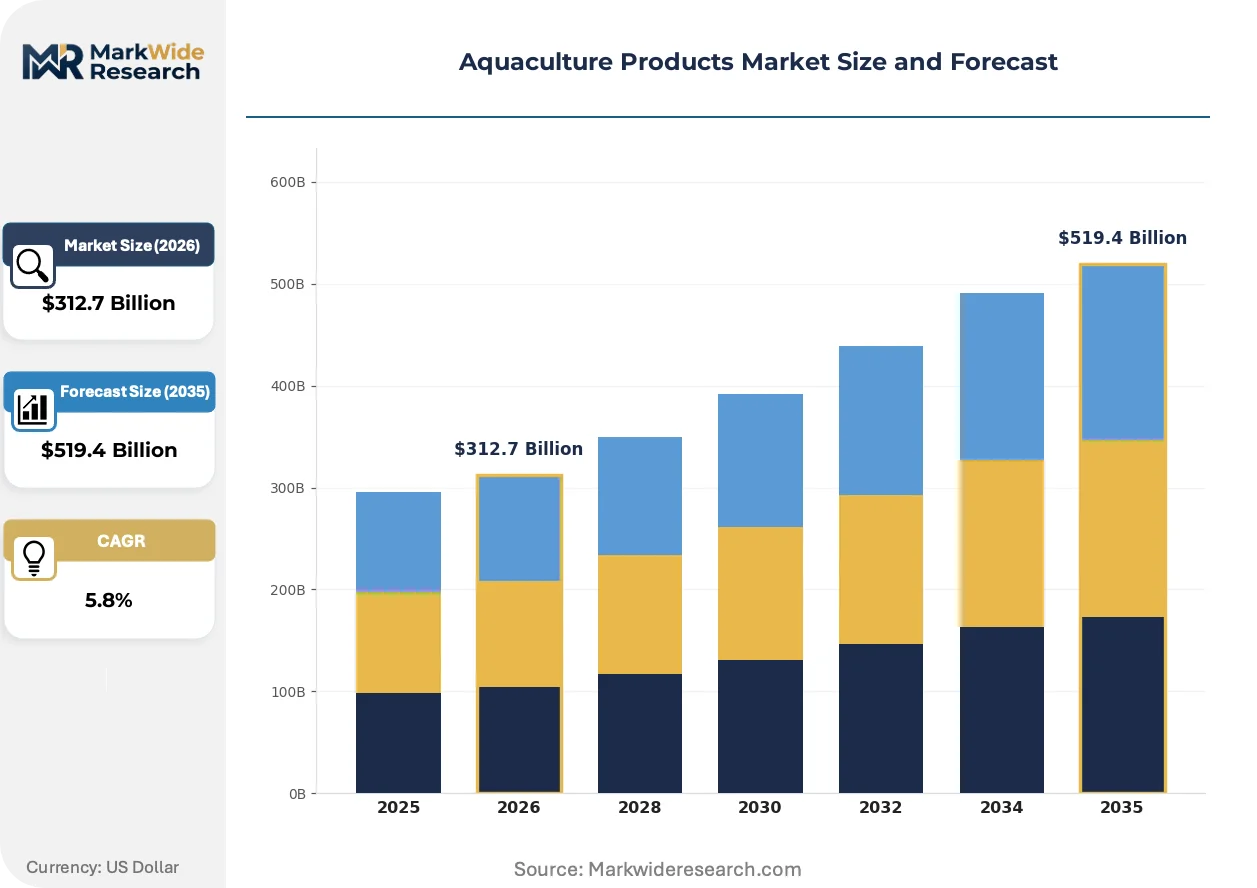
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $519.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed, Equipment, Medicinal Products, Water Treatment Solutions Application: Fish Farming, Shellfish Farming, Aquaponics, Hatcheries End User: Commercial Farms, Research Institutes, Retailers, Aquarists Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Mowi ASA, Cermaq Group AS, Thai Union Group PCL, SalMar ASA, Cooke Aquaculture Inc., Bakkafrost P/F, Maruha Nichiro Corporation, Lerøy Seafood Group ASA, Grieg Seafood ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Products Market Emerging Trajectories
Biological monitoring, alternative proteins, and supply chain digitization are converging to reshape cost structures and risk profiles across finfish and shellfish value chains.
Precision aquaculture sensor networks combining dissolved oxygen probes, hydroacoustic biomass estimation, and AI-driven feeding algorithms is rewriting operational economics for large-scale salmon and shrimp producers. Norwegian and Chilean operators deploying these integrated systems report feed conversion improvements and mortality reduction. The technology is compressing competitive advantage toward data-integrated incumbents with capital for telemetry infrastructure.
China's MEE wastewater discharge standards for intensive pond aquaculture are tightening effluent nitrogen and phosphorus limits in Guangdong and Hainan production zones. Enforcement through satellite monitoring and automated sampling is forcing facility upgrades or consolidation. Smallholder operations without treatment lagoon capacity are exiting or integrating into larger cooperative structures with shared infrastructure.
Foodservice buyers in Southeast Asia are consolidating supplier relationships around vertically integrated pangasius and shrimp processors with traceable batch records. Direct contracting with Mekong Delta facilities is displacing spot-market procurement through Ho Chi Minh City trading floors. This concentration is most visible in Vietnam, where supermarket chains and QSR networks now mandate farm-level QR code traceability as a condition of volume agreements.
Aquaculture Products Market Segmentation
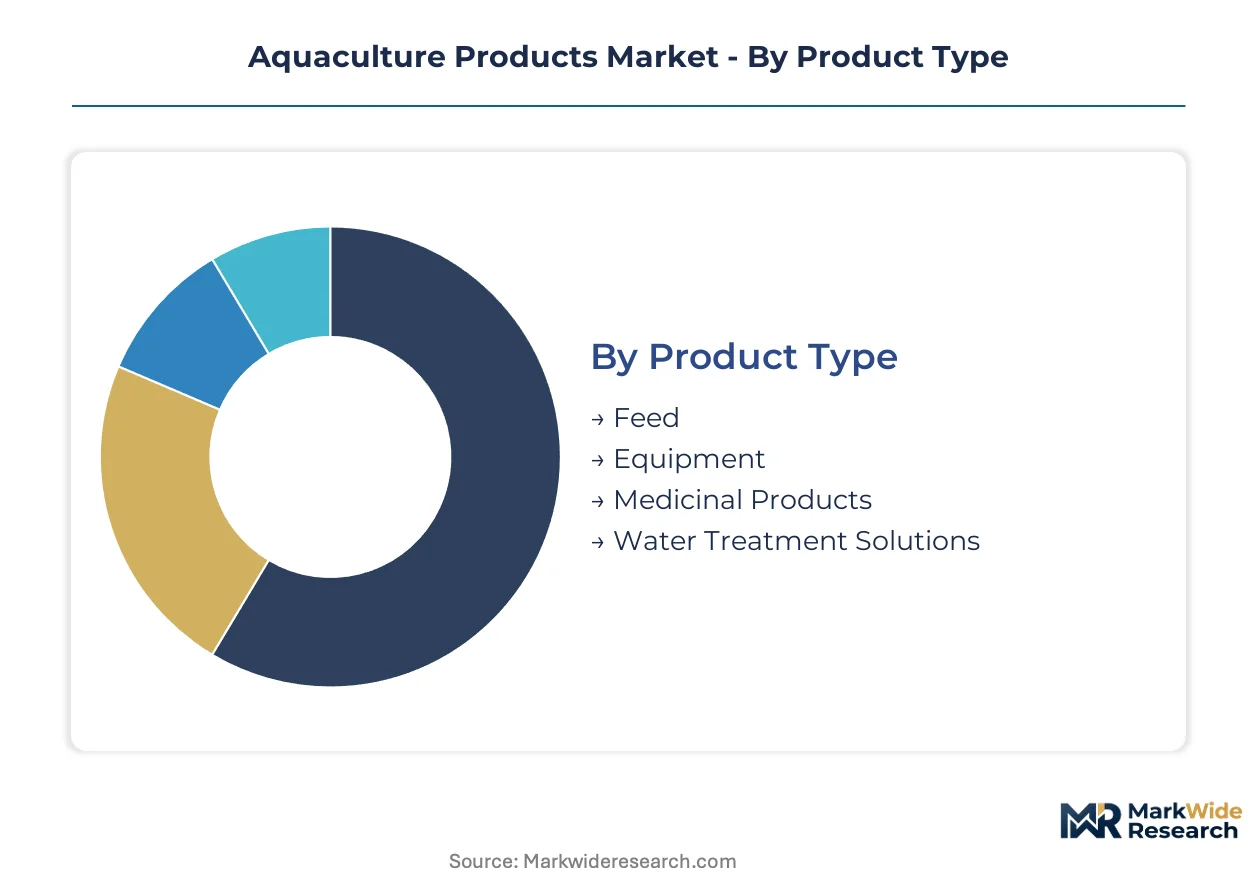
Segmentation in aquaculture products reflects divergent compliance burdens and margin structures across the value chain. Feed formulations face recurring ASC and BAP certification audits, while equipment and medicinal categories navigate FDA, EFSA, and national veterinary institute approvals.
Product Type:
Feed formulations carry the heaviest certification load with ASC, BAP, and EU Feed Hygiene Regulation overlapping requirements, while equipment and water treatment solutions face simpler CE marking and ISO compliance paths.
- Feed:Nutritional formulations combining fishmeal, plant proteins, and functional additives for grow-out operations. Demand concentrates in Norway's fjord-based salmon corridor and Vietnam's Mekong Delta pangasius hubs, driven by vertical integrators seeking captive supply security. EFSA and national veterinary institutes enforce strict residue limits and additive approvals.
- Equipment:Aerators, net pens, feeding systems, and monitoring infrastructure for intensive and extensive operations. Norwegian and Chilean salmon producers dominate procurement, prioritizing precision aquaculture sensor networks with AI-driven feeding algorithms. CE marking and ISO 9001 certification satisfy most regulatory thresholds.
- Medicinal Products:Vaccines, antibiotics, and probiotics for disease management in finfish and shellfish. China's MEE and national veterinary regulators enforce withdrawal periods and residue monitoring.
- Water Treatment Solutions:Filtration, ozonation, and biological treatment systems for RAS and pond operations. Guangdong and Hainan producers retrofit facilities to meet tightening MEE effluent standards.
Leading the category by volume: Feed. Growing fastest: Water Treatment Solutions.
Application:
Cost tier differentiation separates capital-intensive RAS operations from extensive pond systems, with shellfish farming offering the lowest feed input economics.
- Fish Farming:Atlantic salmon, pangasius, tilapia, and carp production in marine, brackish, and freshwater systems. Norwegian MAB licensing constraints and Vietnamese direct contracting trends reshape competitive dynamics. ASC certification dominates premium channel eligibility.
- Shellfish Farming:Oysters, mussels, and clams cultivated with minimal feed inputs and carbon-negative filtering properties. France, Ireland, and New Zealand producers lead output, with EU organic and national ecolabels driving retail differentiation. Lowest certification burden among major applications.
- Aquaponics:Integrated fish and hydroponic vegetable production in closed-loop systems. Urban and peri-urban installations in Singapore and the Netherlands attract sustainability-focused foodservice procurement.
- Hatcheries:Broodstock management, larval rearing, and smolt production supplying grow-out operations. Norwegian and Scottish facilities enforce strict pathogen monitoring for infectious salmon anemia under national veterinary protocols.
Lowest cost tier: Shellfish Farming. Steepest expansion trajectory: Aquaponics.
End User:
Customer type determines contract structure, with commercial farms negotiating multi-year supply agreements and research institutes driving experimental formulation demand.
- Commercial Farms:Large-scale salmon, shrimp, and pangasius producers with integrated processing capabilities. Thai Union and Mowi ASA anchor procurement through direct supplier relationships, bypassing traditional wholesale channels. Volume contracts mandate farm-level traceability systems.
- Research Institutes:Universities and government laboratories developing selective breeding programs and alternative protein feeds. Molecular biology and quantitative genetics expertise scarcity limits program expansion in producing regions.
- Retailers:Supermarket chains and e-commerce platforms procuring finished seafood and ornamental species. EU Green Deal sustainability disclosure requirements redirect procurement toward ASC-certified suppliers.
- Aquarists:Hobbyist and ornamental trade participants sourcing live organisms and specialized feeds. Niche certification through Ornamental Fish International standards applies.
Dominant contract value: Commercial Farms. Fastest-growing customer type: Retailers.
Distribution Channel:
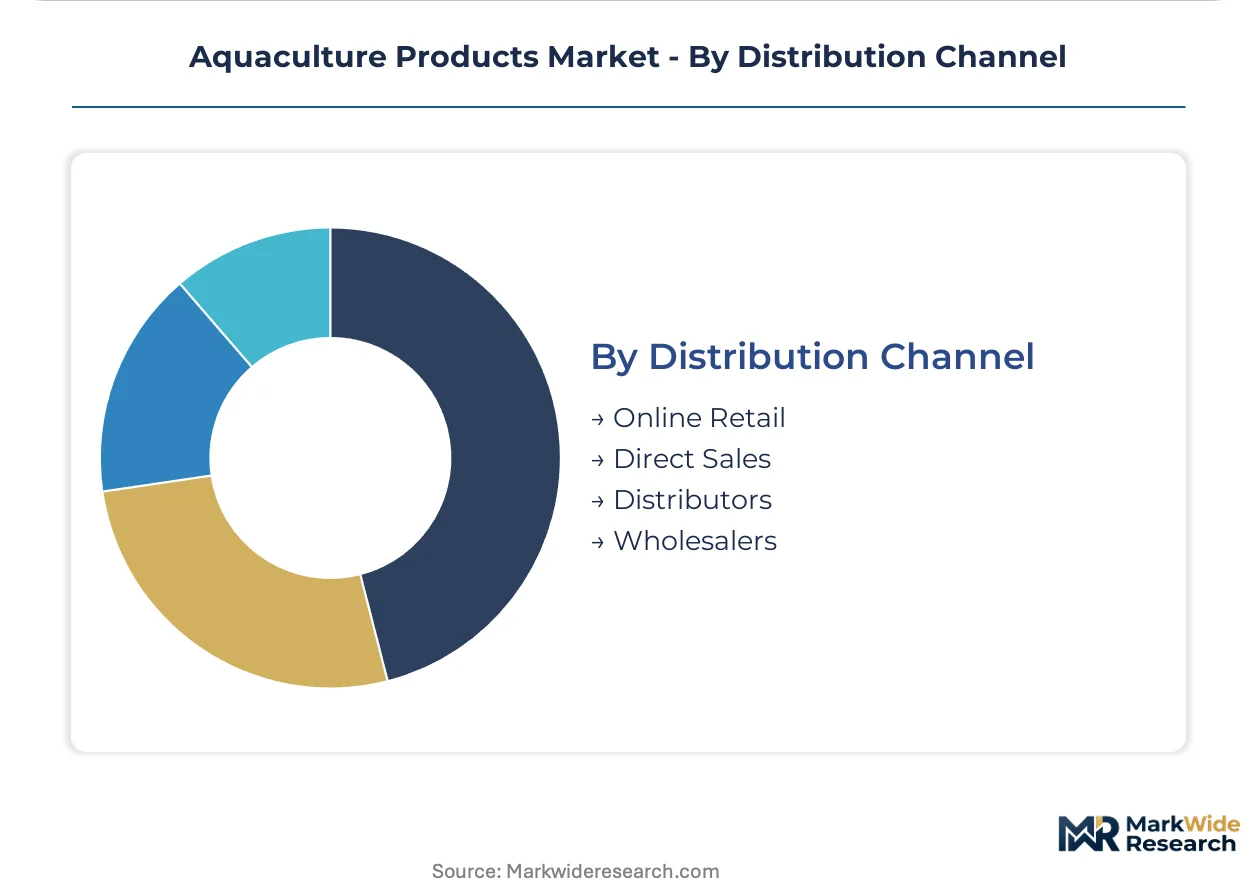
Margin retention varies sharply across channels, with direct sales capturing premium pools and distributor networks absorbing compliance overhead for fragmented buyers.
- Direct Sales:Producer-to-farm contracts eliminating intermediary markups for large-scale commercial operations. Norwegian salmon integrators and Vietnamese pangasius processors dominate this channel, supported by QR code traceability mandates from Southeast Asian foodservice buyers.
- Online Retail:E-commerce platforms and subscription seafood boxes capturing margin pools previously absorbed by foodservice distributors. Urban consumers in Vietnam, Thailand, and Indonesia drive platform expansion.
- Distributors:Regional wholesalers consolidating fragmented demand from smallholder farms and aquarists. Inventory carrying costs and multi-certification compliance burdens compress margins.
- Wholesalers:Traditional auction markets and trading floors in Ho Chi Minh City and Bangkok facing displacement from direct contracting trends. Spot-market liquidity remains for non-integrated processors.
Highest margin retention: Direct Sales. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway and Vietnam concentrate demand for Atlantic salmon and pangasius respectively, while regulatory divergence across major producing zones reshapes competitive access.
Norway
Atlantic salmon farming dominates output through fjord-based net-pen operations. The Norwegian Food Safety Authority enforces strict MAB limits and fallowing mandates that constrain biomass expansion. Bergen and Trøndelag host the densest concentration of vertically integrated producers deploying precision aquaculture sensor networks.
Vietnam
Mekong Delta pangasius processors supply expanding Southeast Asian foodservice chains with traceable fillet contracts. The Ministry of Agriculture and Rural Development implements antibiotic residue monitoring under national veterinary protocols. An Giang and Đồng Tháp provinces concentrate direct contracting relationships with supermarket and QSR networks.
China
Intensive shrimp and carp pond systems in Guangdong and Hainan face tightening effluent standards. The MEE enforces nitrogen and phosphorus discharge limits through satellite monitoring and automated sampling. Smallholder operations without treatment infrastructure are consolidating into cooperative structures with shared lagoon capacity.
Chile
Atlantic salmon production in Los Lagos and Aysén regions competes with Norwegian supply for premium export channels. SERNAPESCA mandates strict pathogen monitoring and zone-based fallowing for infectious salmon anemia containment. Puerto Montt anchors processing and smolt production infrastructure serving international markets.
United States
Domestic demand for farmed seafood concentrates in Pacific Northwest salmon operations and Gulf Coast shrimp hatcheries. The FDA and NOAA jointly oversee seafood safety under FSMA and Magnuson-Stevens provisions. Maine and Washington State host emerging recirculating aquaculture system deployments attracting institutional capital.
Aquaculture Products Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integrators commanding premium positions in Atlantic salmon while Asian processors dominate whitefish commoditization. Three archetypes define the field: Norwegian-Scottish salmon integrators with captive hatchery and feed assets, Southeast Asian pangasius-shrimp processors serving foodservice direct contracts, and Japanese trading house affiliates with diversified marine protein portfolios. Consolidation pressure favors M&A among mid-scale feed formulators and capacity expansion in Indonesian shrimp zones.
Within the Atlantic salmon integration tier, Mowi ASA and Bakkafrost P/F exemplify the feed-to-fork model with Norwegian and Faroese production concentration. Thai Union Group PCL anchors Southeast Asian processing through Thai and Vietnamese facility networks. These three represent divergent geographic and species specializations that structure competitive rivalry around certification access and direct retail channel penetration.
| Leading Market Players |
|---|
| Mowi ASA |
| Cermaq Group AS |
| Thai Union Group PCL |
| SalMar ASA |
| Cooke Aquaculture Inc. |
| Bakkafrost P/F |
| Maruha Nichiro Corporation |
| Lerøy Seafood Group ASA |
| Grieg Seafood ASA |
| Others |
Supply Flow & Price Mechanics
Captive feed production across Norwegian salmon integrators and Vietnamese pangasius processors anchors both supply security and margin retention against volatile marine ingredient costs. This backward integration into nutritional formulations insulates pricing power from Peruvian anchovy quota fluctuations while concentrating procurement leverage among Mowi ASA and Thai Union Group PCL.
Pricing Analysis
Volume contracts dominate the feed and equipment tiers while premium ASC-certified fillets command margin separation at the finished product level. Certification grade and vertical integration depth serve as the primary price differentiation drivers, with EU Green Deal disclosure requirements widening the spread between compliant and non-compliant suppliers. Cost compression in standard-grade pangasius intensifies as Mekong Delta processors consolidate around direct foodservice contracts. Commercial farms with captive hatchery capacity exhibit the lowest price sensitivity, whereas smallholder operations dependent on spot-market feed purchases face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from Southeast Asian foodservice chains mandate qualified supplier rosters spanning both Norwegian fjord-based salmon operations and Vietnamese Mekong Delta pangasius facilities. Raw material flows draw from Peruvian anchovy fisheries for fishmeal, Brazilian soy complexes for plant protein, and Chinese fermentation capacity for single-cell protein additives. Single-source vulnerability concentrates in marine ingredient inputs subject to El Niño-driven quota volatility. Distribution runs through direct producer-to-farm contracts for large integrators, with e-commerce platforms capturing emerging urban consumer channels in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating across feed formulation and processing tiers as pathogen management costs and multi-certification compliance burdens force sub-scale operators toward acquisition or exit. Norwegian MAB licensing constraints and Chinese MEE effluent enforcement are compressing viable operational footprints.
For Market Incumbents: Deploy precision aquaculture sensor networks as the defensive anchor, combining AI-driven feeding algorithms with hydroacoustic biomass estimation to compress feed conversion ratios below competitor benchmarks. Deepen captive hatchery capacity in Scotland and the Faroe Islands to isolate broodstock from infectious salmon anemia amplification risks. Secure ASC and BAP certification pre-approval for EU retail channel eligibility before Green Deal disclosure mandates harden procurement screens.
For New Entrants and Emerging Players: Urban aquaponics operators in Singapore and the Netherlands represent the most penetrable buyer archetype for modular closed-loop system providers, with sustainability-focused foodservice procurement creating immediate contract traction. Sulawesi and Kalimantan brackish water zones offer expansion terrain for vannamei shrimp operations with lower land competition than Vietnam or Ecuador. Lead with subscription seafood box partnerships targeting Indonesian and Thai urban consumers to bypass entrenched wholesale auction structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale feed formulators with captive marine protein substitution capabilities and established ASC certification relationships. Long-term viability centers on operators with demonstrated alternative protein formulation expertise and direct retail channel penetration. The signal to watch is acceleration in black soldier larva meal adoption rates among Norwegian salmon integrators, indicating inflection toward reduced marine dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Formulation | Mowi ASA's captive nutritional production insulates margin from Peruvian anchovy quota volatility. |
| Recirculating Aquaculture System Deployment | Maine and Washington RAS projects attract institutional capital by de-risking production from algal blooms. |
| Multi-Certification Pre-Approval Investment | Simultaneous ASC and BAP audit completion secures EU Green Deal procurement eligibility. |
| Direct-to-Retail Channel Development | E-commerce platforms in Vietnam capture margin pools previously absorbed by Ho Chi Minh City wholesalers. |
| Alternative Protein Feed Convergence | Black soldier larva meal combined with single-cell proteins reduces marine ingredient dependency. |
Methodological Framework
Trade flow databases, national veterinary institute pathogen surveillance reports, and ASC certification registries formed the secondary backbone, cross-referenced against EU Feed Hygiene Regulation filings and MEE effluent monitoring disclosures. Primary interviews with salmon farm operations managers, pangasius processing procurement leads, feed formulation R&D directors, and Southeast Asian foodservice chain category buyers validated volume and pricing assumptions. Bottom-up farm-level production estimates and top-down trade value aggregation were triangulated to anchor segmentation outputs.
Historical trendline analysis across Norwegian MAB licensing trajectories, Vietnamese direct contracting penetration rates, and Chinese smallholder consolidation patterns informed the projection framework. Segmentation dimensions modeled include product type tier, application intensity level, end-user contract structure, and distribution channel format. CAGRs were derived from fitted growth curves applied to validated baseline estimates, with RAS capital intensity and insect protein substitution rates serving as scenario sensitivity inputs.
Revisions become necessary when Norwegian Food Safety Authority licensing moratoria extend beyond current fallowing cycles, Peruvian anchovy quotas collapse under extreme El Niño conditions, or EU Green Deal enforcement timelines accelerate. Deviation in marine ingredient cost trajectories or ASC certification audit backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
North America Aqua Feed Market