
 Metaverse in E-Commerce Market | 2026-2036
Metaverse in E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Metaverse in E-Commerce Market Analytics
Platform bundling of virtual storefronts with payment rails and social discovery tools is realigning how retailers evaluate metaverse vendors. Meta Platforms Inc. anchors its commerce stack around Horizon Worlds creator monetization. Alibaba Group leverages its Alipay infrastructure to bridge physical inventory with virtual try-on experiences. Epic Games Inc. differentiates through Unreal Engine-powered photorealistic product rendering for brand activations.
The Metaverse in E-Commerce denotes persistent, interoperable virtual environments where buyers inspect, customize, and transact for goods through avatars or spatial computing interfaces, typically rendering at 90 frames per second for VR immersion and sub-20 millisecond latency for real-time co-shopping. Its commercial purpose centers on reducing return rates through virtual fit verification while capturing behavioral data impossible to gather in physical retail. Virtual Fashion commands premium margin pools as scarcity-driven digital collectibles resale sustains secondary royalty streams. Blockchain-based provenance tracking for In-Game Assets represents the fastest-growing product type as cross-platform interoperability standards mature. AI Integration within the technology stack increasingly determines which platforms deliver personalized merchandising at scale.
The EU AI Act and GDPR constrain how avatar behavioral data fuels recommendation algorithms, forcing platforms to implement explicit consent architectures before profiling virtual shoppers. The US FTC monitors deceptive native advertising in influencer-hosted metaverse environments, particularly undisclosed sponsorships within Roblox brand worlds. South Korea's MFDS coordinates with platform operators on age-gating standards for virtual cosmetics trials involving facial scanning. Stakeholders must weigh regulatory fragmentation against the technical cost of building jurisdictionally compliant identity and payment layers.
Market Dynamics
Platform interoperability mandates and avatar identity standardization are compressing vendor lock-in advantages while forcing commerce infrastructure rebuilds around decentralized identity protocols.
Growth Catalysts
- GDPR-compliant consent architectures:European retailers deploying explicit opt-in frameworks for biometric avatar data capture are unlocking personalized merchandising capabilities previously restricted by regulatory ambiguity.
- Spatial computing rendering pipelines:Unreal Engine 5's Nanite virtualized geometry enables photorealistic product inspection at 90 frames per second, reducing return rates through accurate virtual fit verification.
- Seoul Metropolitan Government metaverse economy initiative:South Korea's $177 million public investment in virtual commerce infrastructure accelerates merchant onboarding and consumer wallet adoption.
Market Restraints
- GPU compute cost volatility:Real-time ray-traced rendering for virtual showrooms requires NVIDIA H100-class hardware, exposing retailers to semiconductor supply concentration in Taiwan.
- EU AI Act automated decision-making restrictions:Recommendation engines profiling virtual shoppers face explainability mandates that increase algorithmic audit costs.
- Web2 platform substitution:Instagram Shop and TikTok Shop's embedded commerce layers siphon experimental budgets from immersive VR deployments.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic VR headset production incentives reduce import duties for retailers building captive virtual commerce hardware stacks.
- Blockchain-based digital collectible provenance:Cross-platform interoperability standards for virtual fashion items enable secondary royalty streams across Decentraland, Roblox, and Fortnite ecosystems.
- AI-driven spatial merchandising:Convergence of generative AI and real-time 3D engines allows dynamic storefront reconfiguration based on avatar behavioral cues.
Industry Challenges
- Immersive experience design talent scarcity:Retailers compete with gaming studios for Unity and Unreal Engine developers capable of building sub-20 millisecond latency co-shopping environments.
- Legacy ERP integration complexity:SAP and Oracle systems require custom middleware to synchronize physical inventory with virtual try-on availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaverse in E-Commerce Market |
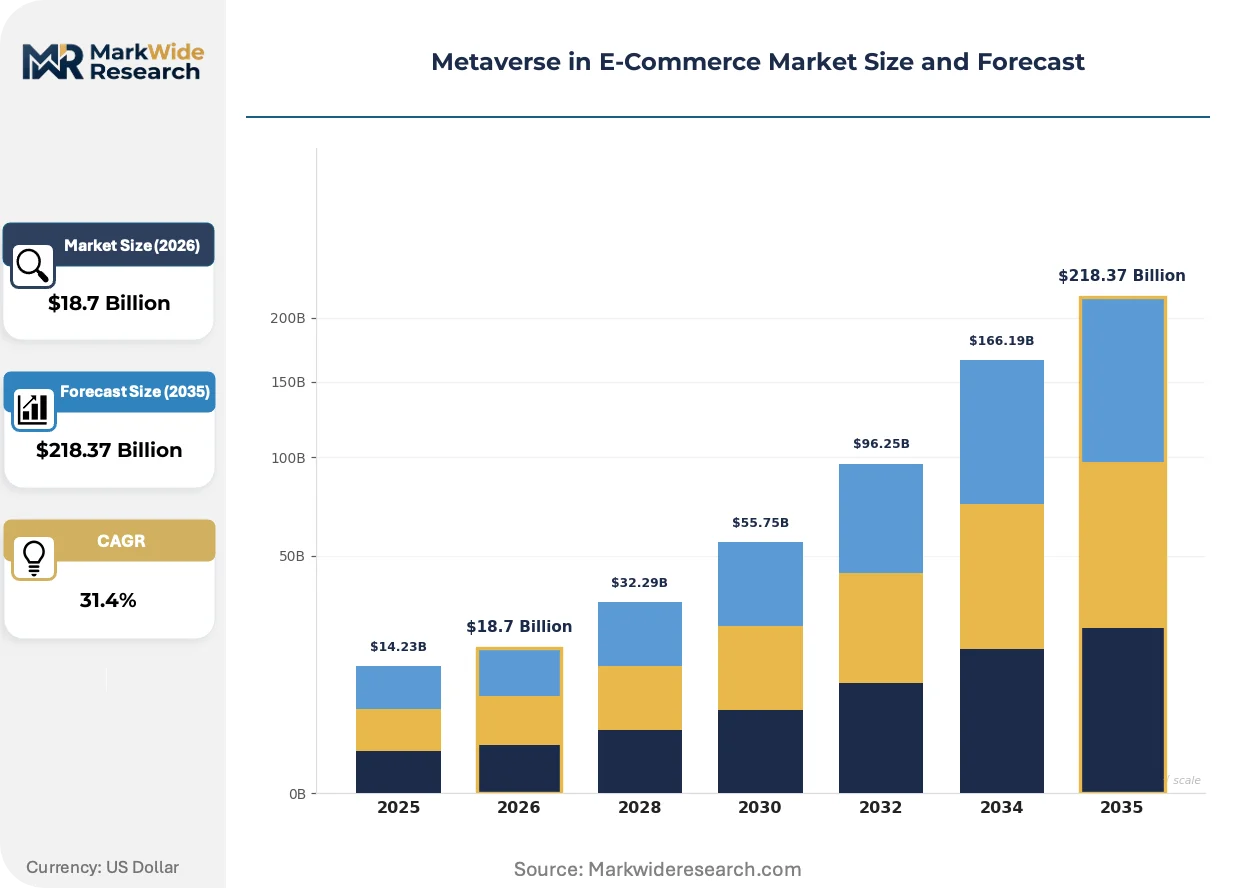
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $218.37 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Goods, Virtual Fashion, Augmented Reality Experiences, In-Game Assets End User: Brands, Retailers, Consumers, Influencers Technology: Blockchain, VR Platforms, AR Solutions, AI Integration Distribution Channel: Direct Sales, Marketplaces, Social Media, Third-Party Platforms |
| Companies Covered | Amazon.com Inc., Alibaba Group, Meta Platforms Inc., Tencent Holdings Ltd., Nvidia Corporation, Epic Games Inc., Roblox Corporation, Unity Technologies Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaverse in E-Commerce Market Evolving Landscape
Generative AI and spatial computing are collapsing the production timeline for virtual commerce environments from months to days, enabling rapid test-and-learn deployment cycles.
OpenUSD is unifying 3D asset pipelines across metaverse platforms, allowing brands to author product models once and deploy across Horizon Worlds, Zepeto, and Spatial without format conversion. Luxury fashion houses adopting this standard reduce creative production costs by eliminating redundant retopology work. The structural compression this enables is unifying creative operations that previously fragmented across platform-specific teams.
The EU AI Act's risk-based classification system for biometric identification in virtual cosmetics trials forces retailers to implement human-in-the-loop review for facial scanning data processing. Beauty brands operating in France must coordinate with CNIL on age-gating protocols for virtual makeup applications. Premium cosmetics retailers are responding by relocating facial analysis servers to EU sovereign cloud infrastructure.
Avatar-based co-shopping is displacing asynchronous e-commerce browsing among Gen Z consumers, who prioritize real-time social validation during purchase decisions. Virtual showroom traffic concentrates in evening hours across US and European time zones, requiring elastic cloud rendering capacity. Fashion resale platforms are embedding live auction mechanics where avatars bid on digital collectibles in synchronized virtual spaces.
Metaverse in E-Commerce Market Segmentation
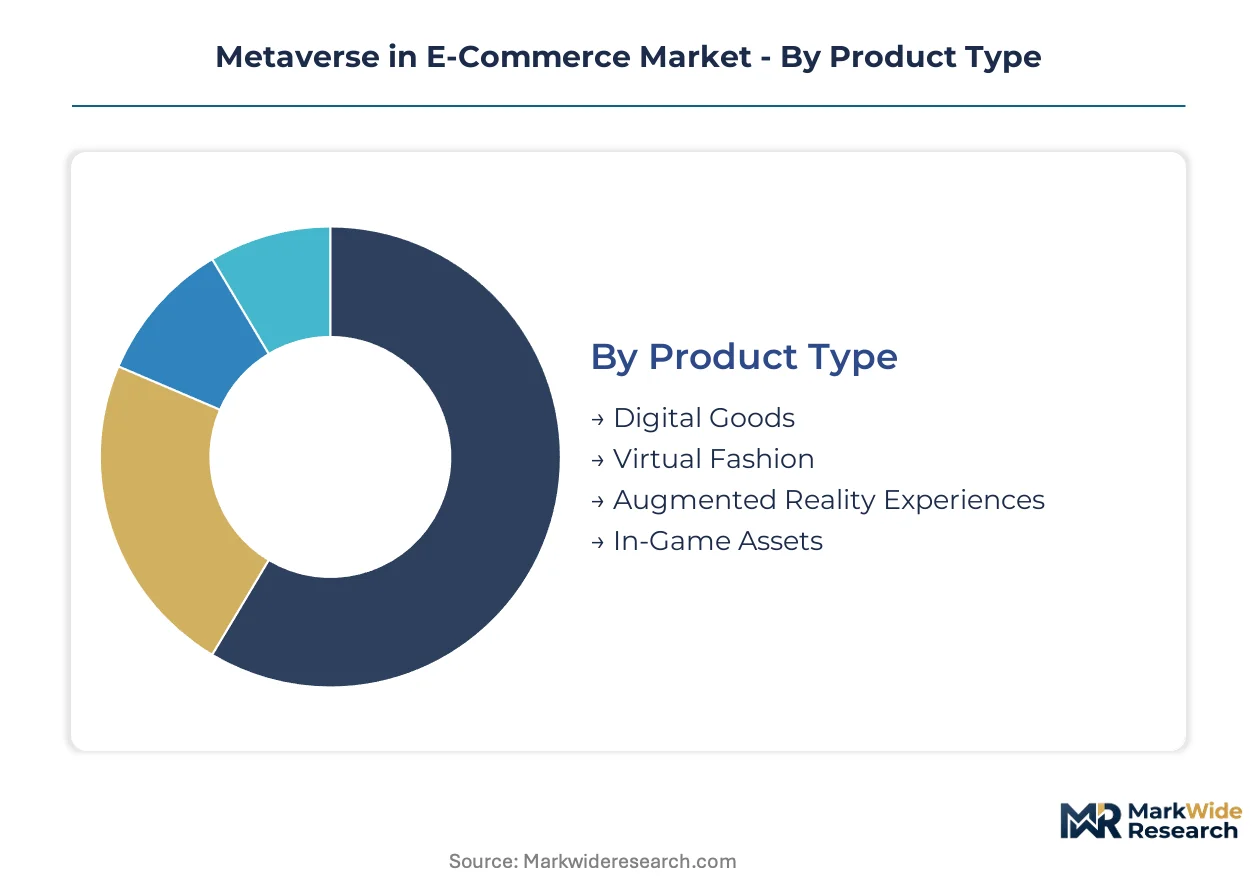
Segmentation in the Metaverse in E-Commerce Market reveals how value migrates across technology stacks and buyer archetypes. Distinct infrastructure requirements separate enterprise deployments from consumer-facing experiences. Each dimension carries unique regulatory exposure and margin architecture.
Product Type:
Upgrade cycles in metaverse commerce accelerate as rendering fidelity thresholds reset with each engine generation. Product categories diverge sharply in production cost and secondary market liquidity.
- Virtual Fashion:Photorealistic digital garments with physics-based cloth simulation enable avatar try-on at 90 frames per second. Luxury houses in France and South Korea drive demand for scarcity-driven drops with embedded smart contract royalties. Regulatory compliance with EU AI Act biometric processing rules constrains facial scanning deployment for virtual fit verification.
- In-Game Assets:Cross-platform interoperable items with blockchain-verified provenance support secondary trading across Decentraland, Roblox, and Fortnite ecosystems. South Korea's MFDS age-gating standards and Seoul's metaverse economy initiative accelerate merchant onboarding for virtual cosmetics and wearables.
- Digital Goods:Static or lightly interactive virtual items without persistent world integration.
- Augmented Reality Experiences:Spatial computing overlays bridging physical retail with virtual product visualization.
Volume placements concentrate in Virtual Fashion; the faster expansion belongs to In-Game Assets.
End User:
Cost tier stratification separates enterprise infrastructure investments from experimental consumer budgets. Each user type commands distinct platform access rights and data governance obligations.
- Brands:Enterprise licensees deploying persistent virtual showrooms with integrated payment rails and CRM synchronization. European luxury houses face GDPR-compliant consent architecture requirements for avatar behavioral data capture. Unreal Engine 5 Nanite pipelines reduce creative production cycles for photorealistic product rendering.
- Retailers:Mid-market merchants leveraging third-party platform APIs for virtual try-on without captive infrastructure. India's PLI scheme for electronics manufacturing reduces hardware import duties for VR headset deployment in captive virtual commerce stacks.
- Consumers:Individual purchasers of digital collectibles and virtual fashion items.
- Influencers:Content creators hosting sponsored experiences in metaverse environments subject to US FTC disclosure mandates.
Enterprise deployments dominate current volume; influencer-mediated commerce is gaining share fastest.
Technology:
Application maturity varies dramatically across the stack, with some layers commoditizing while others consolidate around proprietary advantage.
- AI Integration:Real-time personalization engines processing avatar behavioral cues for dynamic merchandising. EU AI Act explainability mandates increase algorithmic audit costs for automated decision-making in immersive retail. Convergence with generative AI enables spatial storefront reconfiguration based on live shopper signals.
- Blockchain:Distributed ledger infrastructure for digital collectible provenance and cross-platform interoperability. Open standards development enables secondary royalty streams across previously siloed virtual worlds.
- VR Platforms:Persistent immersive environments rendering at 90 frames per second with sub-20 millisecond latency requirements.
- AR Solutions:Spatial computing overlays requiring less specialized hardware than full VR immersion.
Blockchain infrastructure captures the steepest expansion trajectory; AI Integration commands premium pricing.
Distribution Channel:
Customer acquisition economics diverge sharply between owned channels and platform-mediated discovery. Margin retention and data sovereignty trade off against reach.
- Third-Party Platforms:Meta Horizon Worlds, Zepeto, and Spatial provide templated virtual storefronts with embedded social discovery. Platform bundling of payment rails and creator monetization tools reduces merchant technical burden. South Korea's public investment in virtual commerce infrastructure accelerates consumer wallet adoption across these environments.
- Marketplaces:Aggregated venues for digital collectible trading with standardized interoperability protocols.
- Direct Sales:Brand-controlled virtual experiences with full data ownership and custom identity layers.
- Social Media:Instagram Shop and TikTok Shop's embedded commerce layers competing for experimental metaverse budgets.
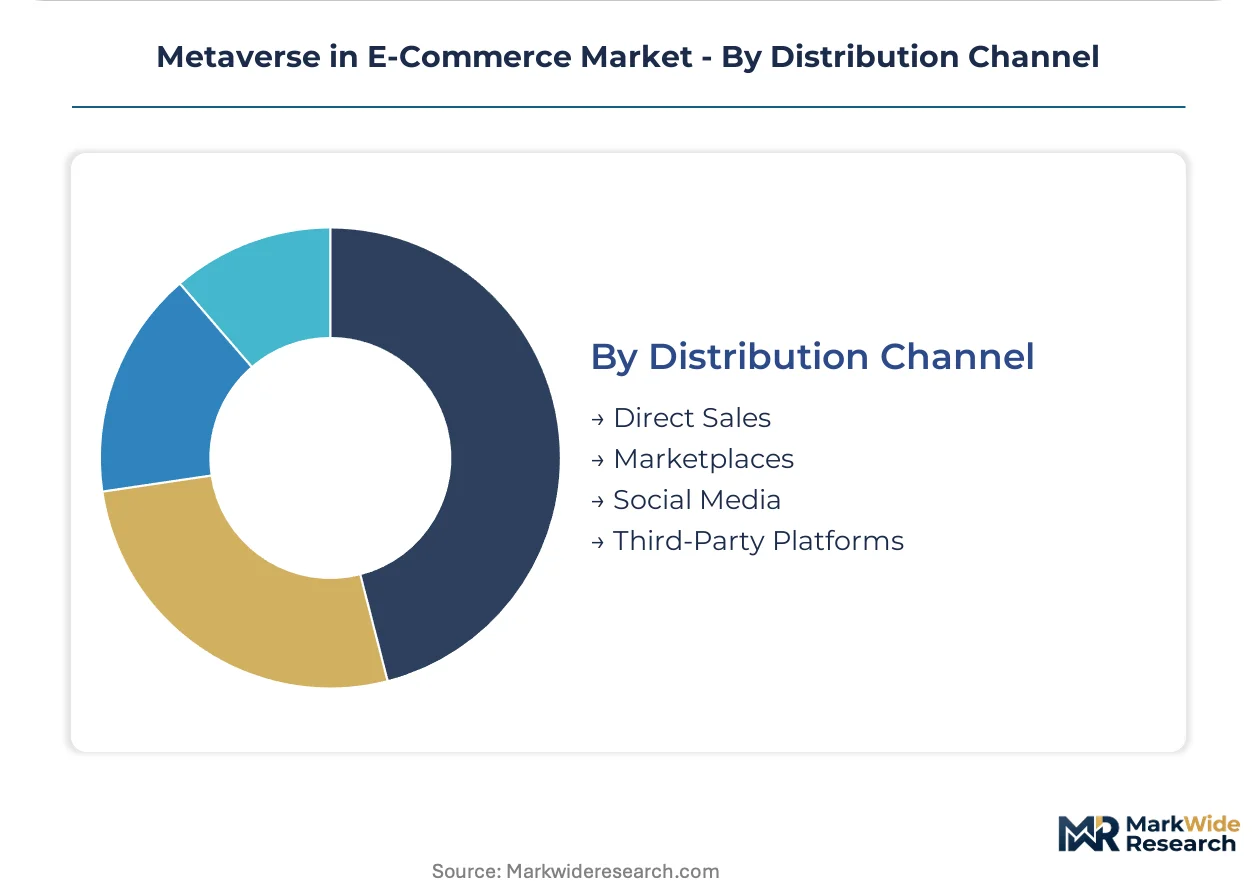
Third-Party Platforms aggregate the largest volume; Direct Sales is climbing the fastest as brands seek data sovereignty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of metaverse commerce infrastructure concentrates in the United States and China while consumption clusters in South Korea and Western Europe. This asymmetry shapes cross-border platform licensing and regulatory arbitrage strategies.
United States
Meta Platforms Inc. and Epic Games Inc. anchor cloud rendering capacity for virtual showrooms. The FTC monitors undisclosed sponsorships in influencer-hosted brand worlds on Roblox. San Francisco and Seattle house the engineering clusters building Horizon Worlds creator monetization tools.
South Korea
Seoul's $177 million metaverse economy initiative accelerates merchant onboarding and consumer wallet adoption. The MFDS coordinates age-gating standards for virtual cosmetics trials involving facial scanning. The Seoul Capital Area dominates virtual fashion drops and digital collectible trading volume.
China
Alibaba Group bridges Alipay infrastructure with virtual try-on experiences for domestic retailers. The MIIT governs cross-border data flows for avatar behavioral analytics in immersive commerce. Shenzhen and Hangzhou concentrate XR hardware manufacturing for export to Southeast Asian markets.
Germany
Luxury automotive brands deploy Unreal Engine-powered virtual showrooms for configurators. The KBA and GDPR compliance requirements constrain biometric data capture for avatar personalization. Munich and Stuttgart host the industrial design studios integrating virtual commerce into omnichannel retail.
France
LVMH and Kering deploy photorealistic digital garment trials with physics-based cloth simulation. The CNIL enforces EU AI Act explainability mandates for automated recommendation engines in virtual cosmetics applications. Paris anchors the luxury fashion cluster driving scarcity-driven digital collectible drops.
Metaverse in E-Commerce Market Competitive Landscape
The competitive structure tilts toward platform bundling of virtual storefronts with payment rails and social discovery tools. Horizon Worlds, Zepeto, and Spatial aggregate merchant volume through templated deployment. Three archetypes dominate: cloud infrastructure operators, game engine licensors, and social platform owners. Capacity expansion in GPU rendering clusters and strategic partnerships for cross-platform interoperability define current competitive moves.
Within the cloud infrastructure tier, Amazon.com Inc. and Microsoft Corporation occupy positions anchoring elastic compute for real-time spatial rendering. Meta Platforms Inc. sits within the social platform archetype, bundling creator monetization with immersive commerce layers. Epic Games Inc. represents the game engine licensor model, differentiating through Unreal Engine-powered photorealistic product rendering for brand activations.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Alibaba Group |
| Meta Platforms Inc. |
| Tencent Holdings Ltd. |
| Nvidia Corporation |
| Epic Games Inc. |
| Roblox Corporation |
| Unity Technologies Inc. |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Unreal Engine and Unity developer talent concentration in Seoul and San Francisco compresses labor-cost differentials into pricing-tier spreads across virtual commerce deployments. European retailers absorbing GDPR-compliant consent architecture costs pass through premiums for biometric-enabled avatar personalization, while Asia-Pacific merchants exploit domestic GPU cloud rendering clusters to undercut photorealistic showroom pricing.
Pricing Analysis
Cost-down pressure on mid-market virtual storefront deployments accelerates because Web2 platform substitution siphons experimental budgets toward Instagram Shop and TikTok Shop. Three-tier pricing structure across premium, standard, and economy levels separates enterprise licensees with captive Unreal Engine 5 pipelines from API-dependent retailers and templated third-party platform users. Certification level for EU AI Act biometric processing compliance and volume scale of concurrent avatar sessions drive price differentiation. Small and mid-size retailers exhibit highest price sensitivity; luxury fashion houses demonstrate lowest sensitivity given secondary royalty capture from digital collectible resale.
Supply Chain Analysis
CE marking and GDPR certification gating for facial scanning hardware constrain vendor qualification pools for European virtual cosmetics trials. GPU semiconductor supply concentrates in Taiwan, South Korea, and the United States, with NVIDIA H100-class hardware anchoring real-time ray-traced rendering capacity. Cloud rendering infrastructure draws from specialized data center buildouts in Northern Virginia, Frankfurt, and Singapore. Single-source vulnerability in TSMC advanced node production exposes retailers to supply disruption. Distribution runs through hyperscaler marketplaces and direct enterprise licensing agreements with Epic Games and Unity Technologies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spatial computing interfaces are displacing legacy 2D e-commerce browsing among Gen Z consumers, compressing the technology-transition window for platform migration. Retailers must reallocate infrastructure investment toward persistent virtual environments or surrender share to immersive-native competitors.
For Market Incumbents: Anticipate Web2 platform substitution by bundling payment rails with social discovery tools in owned virtual environments. Defensive consolidation through backward integration into GPU cloud rendering clusters in Seoul and Northern Virginia reduces exposure to Taiwan semiconductor concentration. Certification investment for EU AI Act biometric processing compliance preserves European market access against regulatory fragmentation. For New Entrants and Emerging Players: Third-party platform API routes offer lowest-friction entry for mid-market retailers seeking virtual try-on capabilities without captive infrastructure investment. White-space targets include India's domestic VR headset production under PLI scheme incentives and blockchain-based digital collectible provenance for cross-platform interoperability. Go-to-market angle emphasizes rapid deployment timelines enabled by generative AI and OpenUSD asset standardization. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cloud infrastructure operators given Seoul's $177 million metaverse economy initiative and accelerating consumer wallet adoption. Long-term viability over a 5-10 year horizon favors platforms controlling identity, payment, and rendering layers simultaneously. Acquisition target archetype: Unreal Engine specialist studios with luxury fashion house relationships. Signal to watch: elastic cloud rendering capacity pricing compression as GPU supply constraints ease.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenUSD standardization enables single-author deployment across Horizon Worlds, Zepeto, and Spatial without retopology. |
| Strategic Partnership | Alipay infrastructure bridges physical inventory synchronization with virtual try-on experiences for Chinese retailers. |
| Acquisition of Specialist Firm | Unreal Engine 5 Nanite pipelines reduce photorealistic product rendering cycles for luxury automotive configurators. |
| Geographic Expansion | Seoul Metropolitan Government investment accelerates merchant onboarding and consumer wallet adoption in South Korea. |
| Product Launch | AI-driven spatial merchandising enables dynamic storefront reconfiguration based on live avatar behavioral cues. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this metaverse commerce analysis. Primary interviews with virtual experience designers, platform engineering leads, luxury brand digital officers, and cloud infrastructure procurement managers combined with secondary validation from EU AI Act implementation guidance, Seoul Metropolitan Government investment disclosures, and FTC enforcement actions. SEC filings from Meta Platforms and Epic Games, alongside hyperscaler capex disclosures, supplied financial trajectory inputs. Bottom-up merchant onboarding estimates and top-down GPU cloud rendering capacity assessments underwent triangulation.
Granularity-level modeling distinguished virtual fashion, in-game assets, digital goods, and augmented reality experiences by technology stack maturity and regulatory exposure. End-user segmentation captured brands, retailers, consumers, and influencers with distinct platform access rights. CAGRs derived from cohort-based adoption curves incorporating Seoul's public investment acceleration and EU AI Act compliance cost absorption. Industry-specific inputs included Unreal Engine 5 rendering pipeline deployment timelines and blockchain interoperability standard development progress across the analysis window.
The model holds under sustained GPU cloud rendering capacity expansion and stable cross-border data flow governance; deviation in Taiwan semiconductor supply or EU AI Act enforcement intensity would shift trajectory. Forecasts reflect assumptions on avatar-based co-shopping adoption velocity and generative AI production timeline compression. A model refresh is warranted upon material change in Seoul metaverse economy initiative funding or OpenUSD standard ratification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market