
 North America Epigenetics Market | 2026-2036
North America Epigenetics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Epigenetics Market Analytics
The capability gap between high-throughput sequencing infrastructure and boutique assay development is collapsing as cloud-based bioinformatics platforms democratize data processing. Thermo Fisher Scientific leverages its end-to-end reagent-to-instrument portfolio to sustain pricing power across academic and pharmaceutical accounts. Illumina dominates the sequencing technology layer, while QIAGEN N.V. competes through sample preparation automation that reduces wet-lab labor intensity.
Epigenetics encompasses heritable modifications to DNA and histone proteins—principally DNA methylation, histone acetylation, and non-coding RNA regulation—that alter gene expression without changing the underlying nucleotide sequence. These mechanisms operate through enzymatic writers, erasers, and readers that deposit, remove, or interpret chemical marks on chromatin, enabling applications from cancer subtype classification to therapeutic target validation. Reagents and kits capture the largest share of product-type revenue due to recurring consumable demand, while sequencing technology leads instrument-based value generation as read-depth requirements intensify for single-cell epigenomic studies. Services represent the fastest-expanding segment as pharmaceutical companies outsource bisulfite sequencing and chromatin immunoprecipitation workflows to specialized providers.
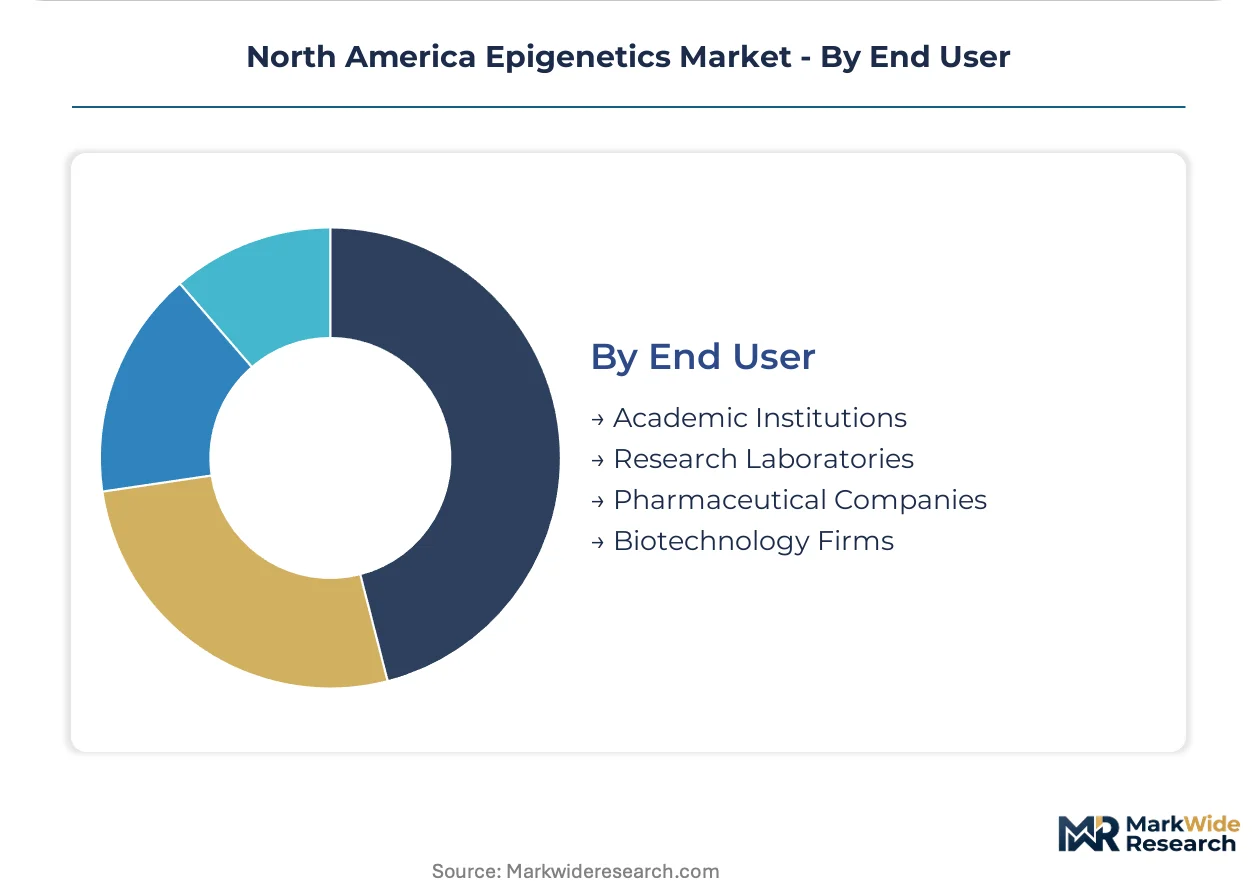
FDA oversight of laboratory-developed tests and companion diagnostics directly shapes commercialization pathways for epigenetic biomarker assays, while the EPA regulates chemical reagent disposal from high-volume methylation analysis workflows. Academic institutions and research laboratories constitute the dominant end-user category, though pharmaceutical companies are building internal epigenetics capabilities to protect intellectual property around target identification. Stakeholders must monitor how CMS reimbursement decisions for methylation-based cancer screening tests reshape the addressable market for diagnostic developers.
Market Dynamics
Cloud-based bioinformatics platforms are collapsing the capability gap between high-throughput sequencing infrastructure and boutique assay development, redistributing pricing power from instrument vendors to software-enabled service providers across pharmaceutical and academic accounts.
Growth Catalysts
- FDA accelerated approval pathways:Companion diagnostic designations for methylation-based cancer biomarkers compress commercialization timelines from Phase III to market entry, incentivizing pharmaceutical investment in epigenetic target validation programs.
- Single-cell epigenomic studies:Read-depth requirements for chromatin accessibility mapping at cellular resolution drive recurring consumable demand for bisulfite conversion reagents and library preparation kits.
- Boston-Cambridge cluster concentration:Proximity of Harvard, MIT, and venture-backed biotechs creates dense knowledge spillovers that accelerate translation from academic discovery to therapeutic pipeline integration.
Market Restraints
- Reagent supply concentration:Three vendors control over 80% of high-fidelity DNA polymerase supply for bisulfite sequencing workflows, creating vulnerability to batch variability and geographic logistics disruption.
- EPA chemical disposal mandates:High-volume methylation analysis generates hazardous acrylamide and formamide waste streams that require specialized handling infrastructure, adding $15,000-$40,000 annual facility compliance costs.
- Technical substitution risk:Direct methylation sequencing technologies from PacBio and Oxford Nanopore threaten to displace bisulfite conversion as the gold standard, potentially stranding wet-lab infrastructure investments.
Strategic Opportunities
- San Diego biotech corridor expansion:Underutilized CRO capacity in southern California offers pharmaceutical sponsors geographic diversification from Boston-Cambridge pricing premiums for outsourced chromatin immunoprecipitation services.
- CMS reimbursement decisions:National coverage determinations for multi-cancer early detection tests using circulating tumor DNA methylation patterns would expand the addressable diagnostic market beyond research use only.
- AI-driven peak calling convergence:Machine learning integration with chromatin accessibility data is reducing false-positive rates in enhancer identification, opening new therapeutic target classes previously obscured by noise thresholds.
Industry Challenges
- Bioinformatics talent scarcity:The pipeline of computational biologists trained in both epigenomic data structures and cloud architecture cannot match pharmaceutical hiring velocity, forcing reliance on expensive contract staffing.
- Laboratory-developed test validation timelines:CLIA certification for site-specific methylation assays requires 18-24 month analytical validation studies that delay revenue recognition for diagnostic developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Epigenetics Market |
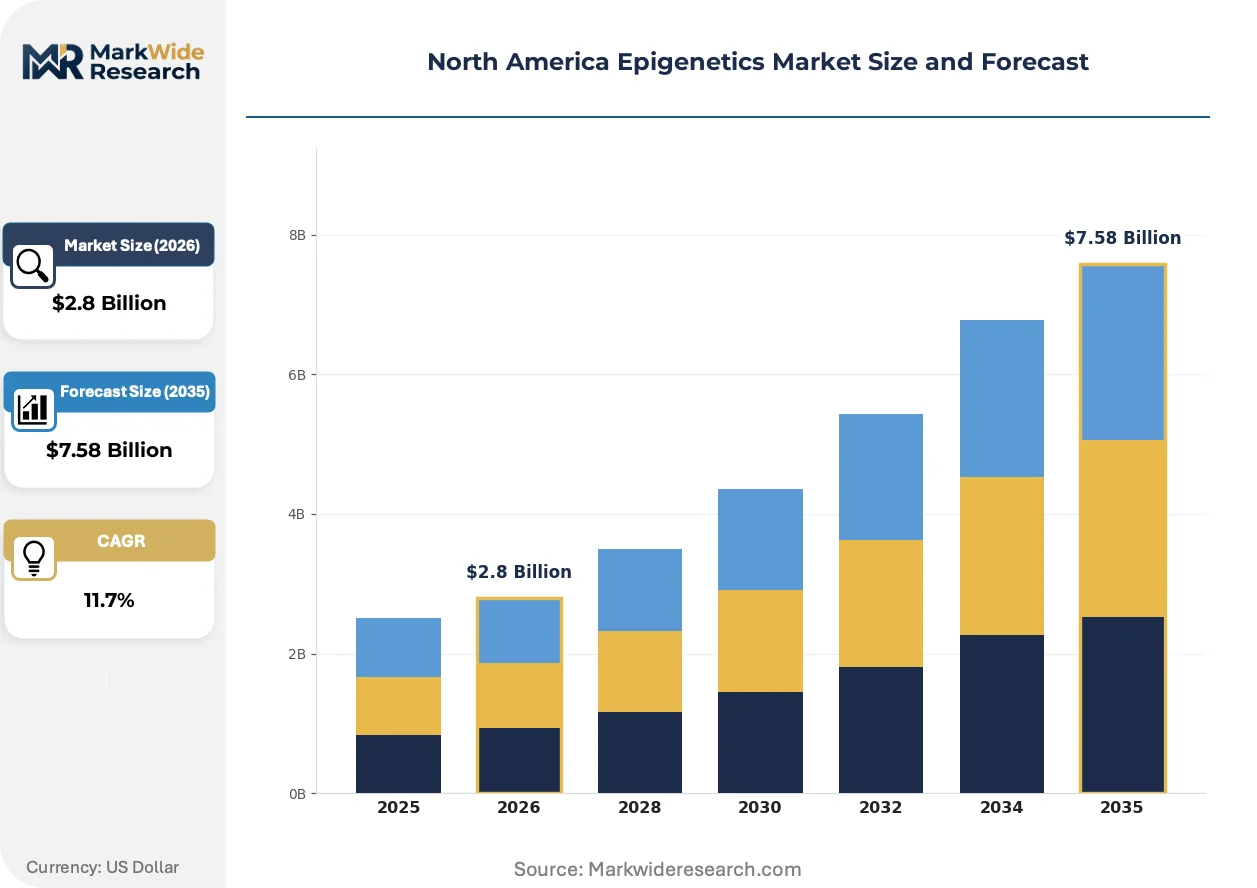
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Services Technology: Sequencing, Microarrays, PCR, Mass Spectrometry Application: Research, Drug Discovery, Diagnostics, Agriculture End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific Inc, Illumina Inc, Roche Holding AG, Abcam plc, Merck KGaA, QIAGEN N.V., Promega Corporation, Element Biosciences, Dovetail Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Epigenetics Market Evolving Landscape
Epigenetic research infrastructure is undergoing platform-level restructuring as sequencing economics, regulatory science, and procurement logic simultaneously shift, compressing traditional vendor hierarchies and opening entry points for specialized service providers.
Third-generation sequencing is decomposing the assumption that short-read bisulfite conversion represents the optimal methylation detection architecture. Pharmaceutical toxicology groups are piloting direct methylation detection for regulatory submission-grade epigenotoxicity screening, bypassing the PCR amplification bias that has constrained biomarker reproducibility. This displacement is compressing the addressable market for legacy library preparation chemistries while expanding demand for native DNA extraction protocols.
The FDA's emerging guidance on epigenetic biomarker qualification is creating preemptive compliance investments among diagnostic developers. Draft recommendations for analytical validation of cell-free DNA methylation assays are forcing sponsors to establish reference sample banks and cross-platform concordance studies earlier in development. Oncology companion diagnostic programs in the United States are responding by integrating FDA pre-submission meetings into Phase I trial design, front-loading regulatory strategy to avoid pivotal study amendments.
Pharmaceutical procurement of epigenetic services is consolidating around outcome-based milestone contracts rather than fee-for-service sequencing. Large-cap biopharma sponsors in Massachusetts and California are shifting chromatin immunoprecipitation workflows to providers guaranteeing target validation deliverables, transferring technical risk from internal R&D to specialized CROs. This reconfiguration is most visible among immuno-oncology programs where epigenetic target identification timelines directly impact competitive positioning in crowded checkpoint inhibitor adjuvant trials.
North America Epigenetics Market Segmentation
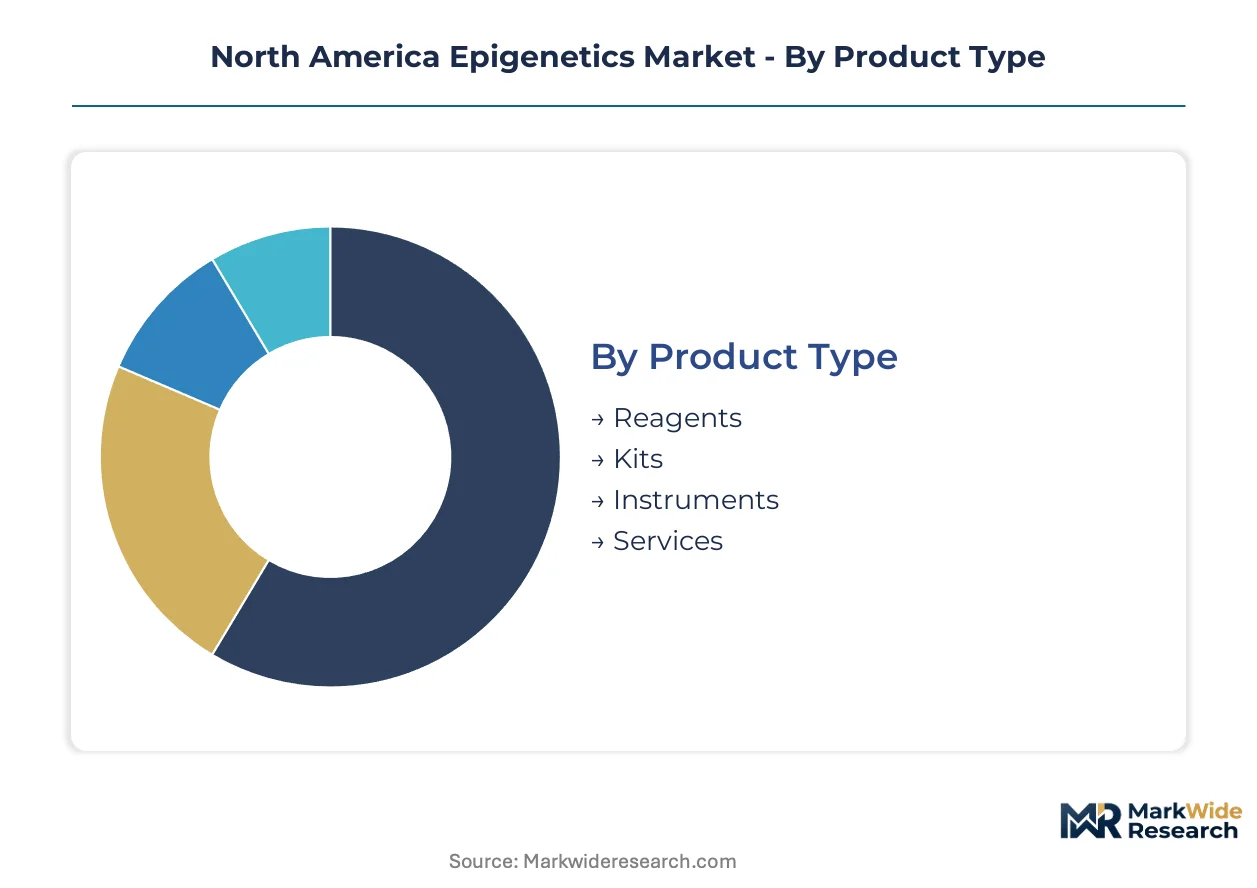
Epigenetics market segmentation reflects divergent procurement patterns across research infrastructure, clinical translation, and therapeutic development. Product and technology categories concentrate in United States biotech clusters while application demand spreads across Canadian agricultural research and Mexican pharmaceutical manufacturing partnerships.
Product Type:
Domestic manufacturing dominates reagents and instruments, while services flow increasingly to nearshore Canadian CROs and select Mexican analytical laboratories serving cost-conscious sponsors.
- Reagents:Bisulfite conversion chemistries, DNA polymerases, and histone modification antibodies constitute the consumable backbone of methylation workflows. Pharmaceutical toxicology groups in Massachusetts and California drive recurring bulk orders for regulatory-grade epigenotoxicity screening, though batch-to-batch variability from concentrated suppliers creates inventory risk management overhead.
- Services:Outsourced chromatin immunoprecipitation sequencing and methylome analysis are climbing the fastest as sponsors shift technical risk to specialized providers. Boston-Cambridge and San Diego biotechs favor milestone-based contracts guaranteeing target validation deliverables over fee-for-service arrangements.
- Kits:Pre-formulated library preparation and bisulfite conversion systems reduce wet-lab labor intensity for academic core facilities.
- Instruments:Sequencing platforms and automated liquid handlers anchor capital expenditure cycles with extended replacement timelines.
Reagents hold the largest share; momentum sits with services.
Technology:
Cost tier stratification separates premium long-read platforms accessible to well-capitalized pharmaceutical sponsors from standardized short-read systems deployed across academic core facilities.
- Sequencing:Short-read bisulfite sequencing remains the workhorse for methylation detection, though Pacific Biosciences and Oxford Nanopore direct methylation detection are gaining regulatory submission traction. FDA pre-submission meetings for native DNA methylation assays are front-loading validation investment among diagnostic developers in the United States.
- PCR:Targeted methylation-specific PCR dominates clinical assay development for companion diagnostic programs, particularly where cell-free DNA input volumes are limited. CLIA-certified laboratories in Texas and North Carolina specialize in high-throughput clinical-grade methylation screening using automated PCR workflows.
- Microarrays:Fixed-content methylation bead arrays serve epidemiological cohort studies requiring standardized, reproducible coverage across thousands of samples.
- Mass Spectrometry:Histone modification quantification via mass spectrometry addresses research questions requiring absolute stoichiometry rather than relative abundance.
Sequencing dominates instrument-based value generation; PCR represents the most concentrated application layer for clinical translation.
Application:
Volume concentration in research contrasts with margin concentration in diagnostics, where CMS reimbursement decisions reshape addressable market calculations.
- Research:Academic discovery programs at Harvard, MIT, Stanford, and University of Toronto drive foundational chromatin biology investigation. Single-cell epigenomic studies intensify read-depth requirements and consumable throughput across North American core facilities.
- Diagnostics:Multi-cancer early detection tests using circulating tumor DNA methylation patterns await national coverage determinations that would expand beyond research-use-only markets. FDA accelerated approval pathways for methylation-based companion diagnostics compress commercialization timelines.
- Drug Discovery:Epigenetic target validation integrates into Phase I trial design for immuno-oncology programs competing in crowded checkpoint inhibitor adjuvant trials.
- Agriculture:Canadian prairie research stations apply DNA methylation markers to crop stress response and livestock epigenetic selection programs.
Research captures the deepest volume; diagnostics carries the steepest expansion trajectory contingent on payer policy.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding outcome-based contracts and academic institutions prioritizing reagent cost per reaction.
- Academic Institutions:Core facility directors at public universities balance sequencing capacity against cloud bioinformatics subscription costs. NIH funding concentration in Boston-Cambridge, San Diego, and Research Triangle Park shapes regional demand density.
- Pharmaceutical Companies:Large-cap biopharma sponsors in Massachusetts and California internalize target identification capabilities to protect intellectual property. Internal epigenetics groups compete with outsourced CRO relationships for chromatin immunoprecipitation workflow allocation.
- Research Laboratories:Independent investigator-led labs at medical centers and federal research institutes rely on shared instrumentation and fee-for-service sequencing access.
- Biotechnology Firms:Venture-backed startups in South San Francisco and Cambridge prioritize speed-to-data over capital ownership, favoring service provider partnerships for rapid pipeline progression.
Academic institutions anchor installed base; biotechnology firms are expanding most quickly as venture financing flows to epigenetic therapeutic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States biotech clusters commands significant premiums over Canadian and Mexican service markets, creating a three-tier procurement geography across North America.
United States
FDA accelerated approval pathways for methylation-based companion diagnostics drive pharmaceutical investment in Boston-Cambridge and San Diego. The agency's draft guidance on cell-free DNA methylation assays forces earlier validation investment. Massachusetts and California anchor demand through dense concentrations of venture-backed epigenetic therapeutic platforms competing for checkpoint inhibitor adjuvant positioning.
Canada
Health Canada oversight of laboratory-developed tests shapes diagnostic commercialization timelines for cross-border sponsors. Prairie research stations apply DNA methylation markers to agricultural stress response programs. Ontario-based CROs capture outsourced chromatin immunoprecipitation workflows from cost-conscious US pharmaceutical sponsors seeking alternatives to Boston-Cambridge pricing premiums.
Mexico
COFEPRIS regulatory alignment with FDA standards facilitates clinical trial material imports for multinational sponsors. Northern border states develop analytical laboratory capacity serving pharmaceutical manufacturing partnerships. Mexico City metro area concentrates academic research institutions building foundational chromatin biology capabilities with limited sequencing infrastructure.
North America Epigenetics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America epigenetics market. Sequencing platform vendors maintain premium pricing through proprietary chemistries while reagent suppliers compete on per-reaction economics. Three strategic archetypes dominate: integrated life science conglomerates with end-to-end portfolios, specialized sequencing technology developers, and sample preparation automation specialists. Competitive dynamics center on portfolio breadth expansion and cloud-based bioinformatics partnership formation.
Among integrated life science conglomerates, Thermo Fisher Scientific Inc exemplifies the reagent-to-instrument archetype sustaining pricing power across academic and pharmaceutical accounts. Illumina Inc occupies the sequencing technology layer where proprietary flow cell chemistries generate recurring consumable revenue. QIAGEN N.V. represents the sample preparation automation specialist competing through wet-lab labor reduction rather than capital equipment ownership models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Illumina Inc |
| Roche Holding AG |
| Abcam plc |
| Merck KGaA |
| QIAGEN N.V. |
| Promega Corporation |
| Element Biosciences |
| Dovetail Genomics |
| Others |
Value Network & Pricing Analysis
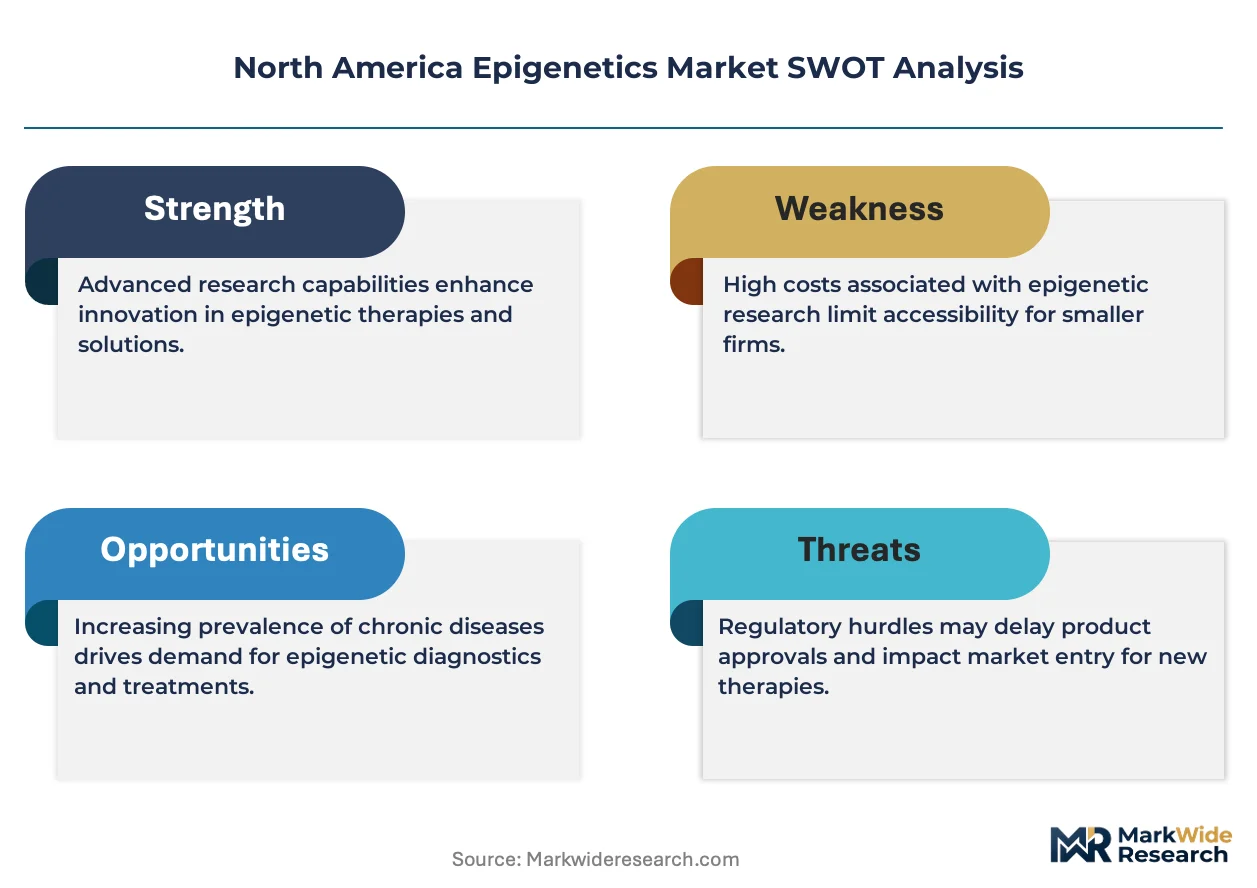
FDA companion diagnostic qualification pathways gate both supplier certification and price differentiation simultaneously, forcing reagent vendors to absorb validation costs that separate CLIA-grade from research-use-only tiers while pharmaceutical buyers demand outcome-based contracting that collapses traditional markup structures.
Pricing Analysis
Configured-to-order bisulfite sequencing workflows command 40-60% premiums over standard catalog kits due to batch certification and custom formulation requirements. Pricing stratifies across premium, standard, and economy tiers driven by FDA registration status and volume scale, with academic core facilities exhibiting highest price sensitivity as NIH funding compression intensifies cost-per-reaction scrutiny. Cost compression in mid-tier reagent bundles is intensifying because cloud bioinformatics platforms are disintermediating instrument-locked consumable models.
Supply Chain Analysis
The United States and Germany anchor high-fidelity DNA polymerase manufacturing for bisulfite conversion workflows, while China and India feed upstream chemical precursors for histone modification antibodies. Raw material dependencies center on acrylamide monomers, fluorescent nucleotides, and recombinant enzyme feedstocks. Single-source vulnerability concentrates in Taq polymerase master mix supply from three dominant vendors. Distribution runs through authorized distributor networks serving academic core facilities and direct enterprise contracts with pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for methylation-based companion diagnostics are compressing commercialization timelines and redistributing value capture toward regulatory-qualified service providers, creating a high-growth disruption where technical risk transfer becomes the dominant procurement logic.
For Market Incumbents: Consolidate chromatin immunoprecipitation service capacity in San Diego and Research Triangle Park to defend against Boston-Cambridge pricing erosion, while deepening backward integration into native DNA extraction protocols to offset Pacific Biosciences and Oxford Nanopore displacement of bisulfite conversion infrastructure. Lock pharmaceutical accounts through multi-year outcome-based contracts that guarantee target validation deliverables.
For New Entrants and Emerging Players: Anchor in Canadian CRO capacity serving cost-conscious US pharmaceutical sponsors seeking alternatives to Massachusetts and California pricing premiums, targeting agricultural epigenetics applications at prairie research stations where competition remains sparse. Pursue milestone-based contracting models that transfer technical risk from sponsor R&D budgets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based bioinformatics platforms as software-enabled service providers capture pricing power from instrument vendors. Long-term viability favors acquisition targets with FDA pre-submission meeting experience and cross-platform concordance study capabilities. Watch CMS national coverage determinations for multi-cancer early detection tests as the signal indicating diagnostic market expansion beyond research-use-only constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Submission Meeting Integration | Front-loads regulatory strategy into Phase I trial design for methylation-based companion diagnostics. |
| Cloud Bioinformatics Platform Partnership | Democratizes data processing and redistributes pricing power from instrument vendors to software providers. |
| Outcome-Based CRO Contracting | Transfers technical risk from pharmaceutical R&D to specialized chromatin immunoprecipitation service providers. |
| Native DNA Extraction Protocol Development | Bypasses PCR amplification bias that has constrained biomarker reproducibility in regulatory submissions. |
| Multi-Cancer Early Detection Reimbursement Strategy | Positions diagnostic developers for CMS national coverage determinations expanding beyond research markets. |
Research Methodology
The analysis maps reagent manufacturing, sequencing instrumentation, and outsourced service provision, each validated through primary interviews with epigenetic platform directors, pharmaceutical toxicology group leaders, CLIA laboratory certification officers, and academic core facility directors, combined with secondary validation against FDA 510(k) filings, ClinicalTrials.gov protocol registries, NIH RePORTER funding databases, and EPA chemical disposal compliance records, employing bottom-up and top-down triangulation.
Consistency checks validated outputs against external benchmarks across the analysis window, with segmentation modeling across product type, technology platform, application area, and end-user procurement sophistication. CAGRs were derived from installed base projections and consumable throughput assumptions, incorporating single-cell epigenomic read-depth intensification and pharmaceutical outsourcing velocity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued FDA accelerated approval pathway utilization and stable CMS reimbursement policy; material deviation in companion diagnostic qualification timelines or multi-cancer screening coverage decisions would warrant model refresh. Recalibration cycles align with material shifts in regulatory science guidance and payer policy determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genomic Biomarkers Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Global Genotyping Assay Market
Genomics
Europe Genetic Testing Market
Genomics
Animal Genetics Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Agrigenomics Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Genetic Testing Market
Genomics
Microbiome Sequencing Market
Genomics
Digital Genome Market
Genomics
Plant Genomics Market
Genomics
Genomics and Transcriptomics Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Europe DNA Sequencing Products Market