
 Asia Pacific Smart Card Market | 2026-2036
Asia Pacific Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smart Card Market Insights
Multi-application bundling of transit and payment credentials onto single credential platforms is recalibrating buyer choice across municipal procurement offices. NXP Semiconductors N.V. leverages its secure element portfolio to anchor contactless transit deployments in major Asian metros. IDEMIA SAS competes through biometric-integrated credential systems that extend government identity contracts. Samsung Electronics Co., Ltd. dominates embedded secure element manufacturing for mobile payment ecosystems.
Asia Pacific smart cards are pocket-sized plastic or polycarbonate devices embedding integrated circuits with ISO/IEC 7816 or 14443 compliant contact pads or radio-frequency antennas, manufactured through lamination, chip bonding, and personalization processes to store encrypted data for authentication and transaction authorization. Contactless smart cards lead volume deployment in transportation and retail point-of-sale terminals across the region's dense urban corridors. Hybrid smart cards sustain premium positioning in government identity programs requiring legacy contact compatibility alongside modern RF interfaces. Payment systems applications concentrate margin pools where financial services institutions demand EMVCo-certified dual interface credentials with advanced cryptographic coprocessors.
TRAI's machine-to-machine communication guidelines in India, China's GB/T standards for financial IC cards administered by SAMR, and Japan's JIS X 6319 specifications enforced by METI collectively shape product certification pathways and procurement eligibility across the region. EMA's data protection principles for healthcare credentials and Australia's eID framework under the Digital Transformation Agency further segment compliance requirements for cross-border credential issuers. Stakeholders must monitor evolving interoperability mandates between national digital identity schemes and private payment networks to anticipate procurement specification shifts.
Market Dynamics
Multi-application credential platforms are compressing procurement cycles across Asia Pacific municipal transit authorities, forcing secure element suppliers to re-architect product roadmaps around unified transit-payment-identity stacks rather than single-purpose card deployments.
Growth Catalysts
- UIDAI Digital Identity Mandates:India's Aadhaar-linked credential requirements are pulling EMVCo-certified dual-interface cards into financial inclusion programs at state and district levels.
- Contactless Transit Upgrades:Dense urban corridors in China and Southeast Asia are replacing magnetic stripe systems with ISO/IEC 14443-compliant platforms to reduce gate congestion.
- TRAI M2M Communication Guidelines:India's machine-to-machine framework is creating embedded secure element demand for connected vehicle and utility metering applications.
Market Restraints
- Silicon Supply Concentration:Secure element wafer fabrication concentrates among a handful of foundries, exposing credential manufacturers to allocation volatility.
- Polycarbonate Raw Material Costs:Durable card substrate prices fluctuate with petrochemical feedstock indices, squeezing margin on government identity contracts.
- Legacy Contact Infrastructure:Hybrid card requirements for backward compatibility inflate bill-of-materials costs versus pure contactless alternatives.
Strategic Opportunities
- Indonesia's Unbanked Population:Archipelago geography and low branch density create white space for mobile-credential ecosystems bridging feature phone and smartphone users.
- Biometric-Converged Credentials:Fingerprint-on-card technology is opening government identity and high-value payment segments previously resistant to standard smart card form factors.
- Australia's Digital Transformation Agency eID Framework:Federal procurement specifications favoring interoperable credentials are creating vendor qualification pathways for regional players.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:EMVCo and Common Criteria certification expertise concentrates among senior specialists, elongating product development timelines.
- Multi-Jurisdiction Compliance Overhead:Credential issuers must simultaneously satisfy China's SAMR GB/T standards, Japan's METI JIS specifications, and India's TRAI guidelines for cross-border contracts.
- Legacy System Integration Complexity:Transit authorities running decades-old fare collection infrastructure face protracted migration paths to open-loop payment acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smart Card Market |
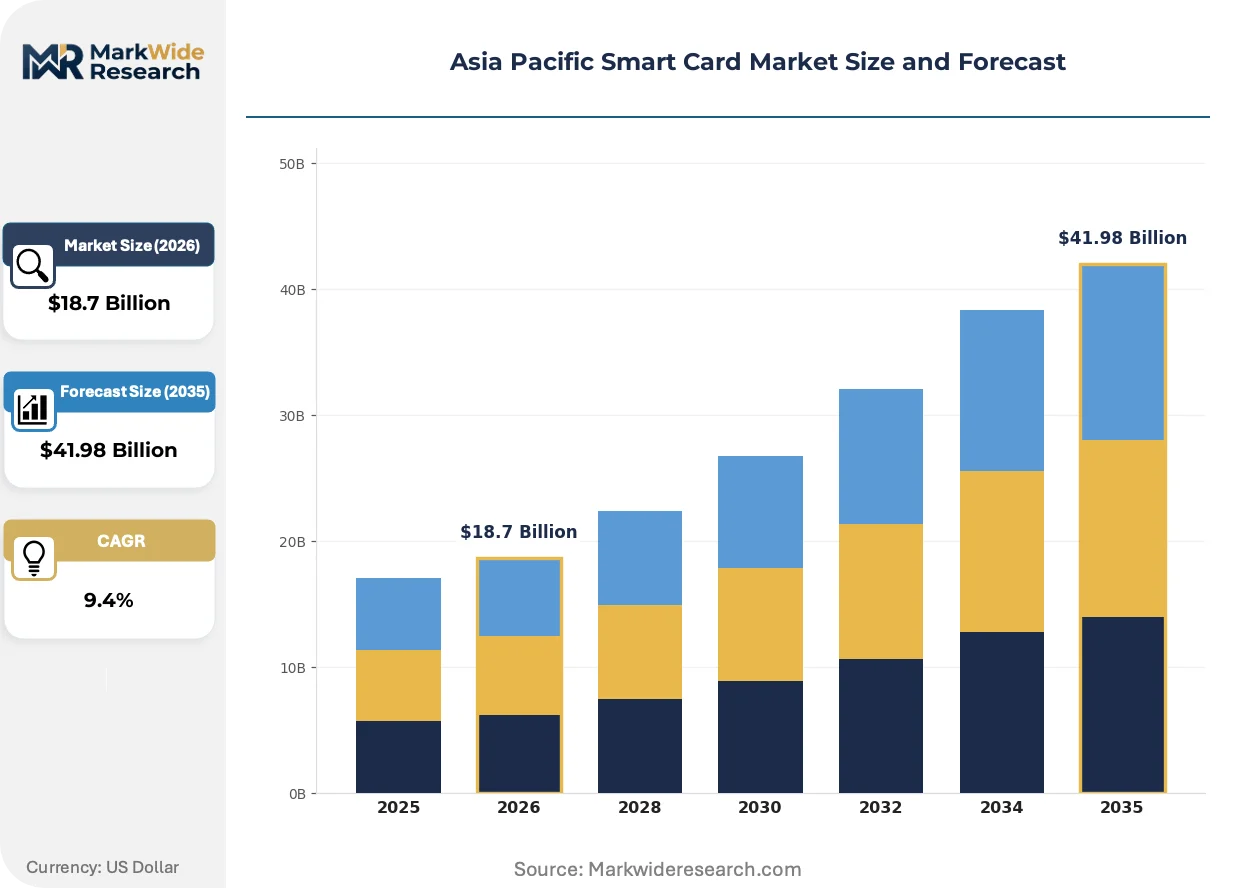
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Contactless Smart Cards, Contact-Based Smart Cards, Hybrid Smart Cards, Dual Interface Cards Application: Payment Systems, Identity Verification, Access Control, Transportation End User: Retail Sector, Government Agencies, Healthcare Institutions, Financial Services Material: Polycarbonate, PVC, PET, ABS |
| Companies Covered | NXP Semiconductors N.V., IDEMIA SAS, Giesecke & Devrient GmbH, Thales Group S.A., Samsung Electronics Co., Ltd., Infineon Technologies AG, Toshiba Corporation, Watchdata Co., Ltd., Eastcompeace Technology Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smart Card Market Trends and Innovations
Secure element architecture is fragmenting into discrete functional blocks that credential assemblers can recombine across transit, payment, and identity use cases without full silicon redesign cycles.
Embedded secure elements are modularizing into application-specific slices combining cryptographic cores, RF front-ends, and tamper-resistant memory in configurable footprints. Mobile wallet providers and wearable manufacturers are adopting these slices to compress certification timelines for new device categories. This modularization is collapsing the traditional boundary between card-based and device-native credential markets.
China's SAMR-administered GB/T financial IC card standards are tightening interoperability requirements between domestic payment networks and municipal transit systems. The regulation forces foreign secure element vendors to establish local testing partnerships for market access. Domestic credential assemblers are responding by deepening backward integration into chip packaging to capture margin pools previously flowing offshore.
Municipal procurement offices are consolidating vendor relationships around full-stack credential platform providers rather than component suppliers. This concentration displaces pure-play card manufacturers who lack secure element design capabilities or personalization bureau networks. The shift is most visible in China's tier-one metro systems and India's state transport undertakings issuing combined transit-benefit credentials.
Asia Pacific Smart Card Market Segmentation
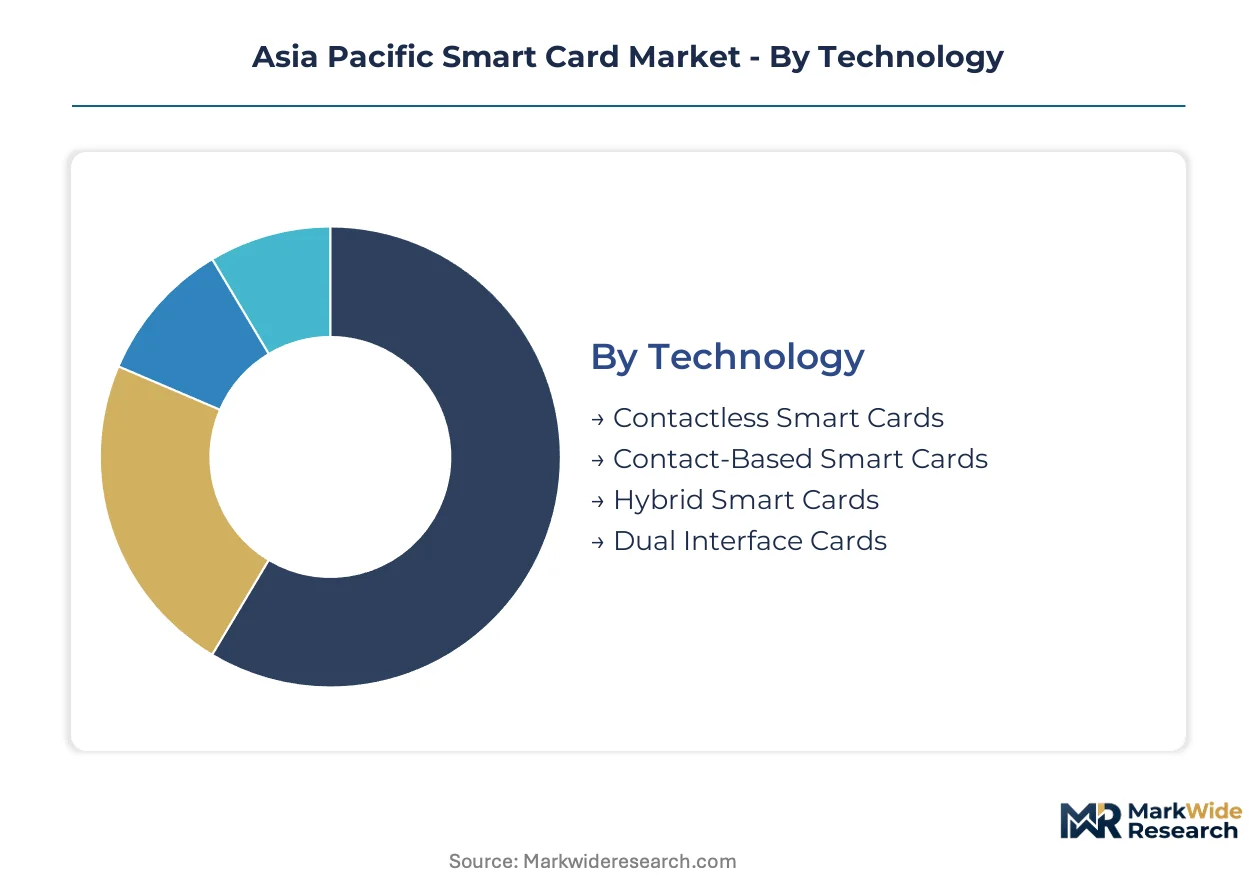
Technology choices in Asia Pacific smart card procurement are hardening around interoperability mandates from China's SAMR, India's TRAI, and Japan's METI. Application bundling across transit, payment, and identity is collapsing traditional segment boundaries. Material selection now tracks directly against durability specifications in government identity contracts.
Technology:
Buyers prioritize certification velocity against national standards over raw performance metrics.
- Contactless Smart Cards:ISO/IEC 14443-compliant platforms with RF antennas laminated into polycarbonate substrates. Dense urban transit corridors in China and Southeast Asia are replacing magnetic stripe gates with these credentials to reduce passenger processing time at fare barriers.
- Dual Interface Cards:EMVCo-certified credentials embedding both contact pads and RF front-ends with advanced cryptographic coprocessors. India's UIDAI-linked financial inclusion programs are pulling these into state-level procurement specifications for combined Aadhaar-payment credentials.
- Contact-Based Smart Cards:ISO/IEC 7816-compliant devices with embedded chips and metallic contact pads for physical insertion readers.
- Hybrid Smart Cards:Multi-protocol credentials supporting both legacy contact infrastructure and modern contactless terminals.
Contactless Smart Cards lead on scale; Dual Interface Cards lead on momentum.
Application:
Procurement offices are consolidating specifications around unified credential stacks rather than single-purpose deployments.
- Payment Systems:EMVCo-certified credentials with dual-interface capability and tamper-resistant secure elements. Financial services institutions across the region are demanding these for point-of-sale terminal compatibility and cross-border interoperability.
- Transportation:ISO/IEC 14443-compliant contactless platforms optimized for high-volume gate processing. China's tier-one metro systems and India's state transport undertakings are driving replacement cycles for combined transit-benefit credentials.
- Identity Verification:Polycarbonate-based credentials with embedded secure elements and optical security features for government issuance.
- Access Control:Corporate and facility credentials with encrypted RF protocols for physical security applications.
Payment Systems dominates revenue contribution; Transportation is expanding most quickly.
End User:
Budget cycles and compliance requirements vary sharply across institutional buyer categories.
- Government Agencies:National identity programs requiring polycarbonate durability standards and biometric integration capabilities. India's Aadhaar ecosystem and Australia's Digital Transformation Agency eID framework are reshaping procurement specifications.
- Financial Services:Retail banking and payment network operators demanding EMVCo certification and dual-interface compatibility. Southeast Asian markets are accelerating contactless adoption for financial inclusion objectives.
- Retail Sector:Merchant acquirers and loyalty program operators deploying credentials for customer engagement.
- Healthcare Institutions:Patient identification and insurance credential systems with data protection compliance requirements.
Government Agencies anchor volume commitment; Financial Services shows steepest expansion trajectory.
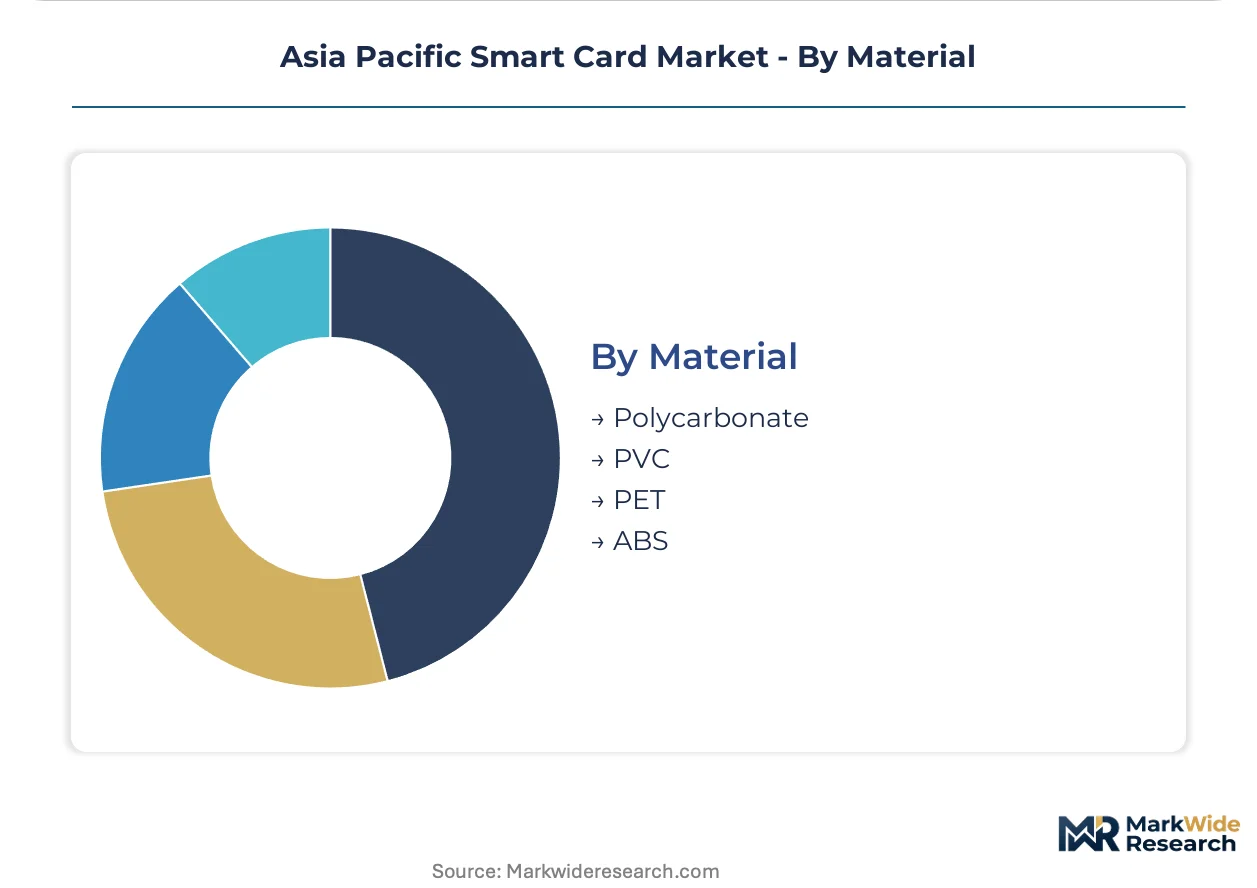
Material:
Substrate selection tracks durability specifications and petrochemical feedstock cost exposure.
- Polycarbonate:High-durability thermoplastic substrates with laser-engravable layers for ten-year document lifecycles. Government identity contracts specify these for tamper resistance and environmental stability.
- PVC:Standard card substrates with established personalization infrastructure for short-lifecycle payment credentials.
- PET:Polyester-based materials with reduced environmental footprint for sustainability-focused issuers.
- ABS:Acrylonitrile butadiene styrene compounds for cost-sensitive applications with moderate durability requirements.
Polycarbonate commands premium positioning; PET is gaining share fastest on sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific smart card manufacturing first achieved industrial scale in Japan during the 1980s, with Tokyo-based semiconductor houses pioneering secure element fabrication for domestic transit and banking applications. This technical foundation diffused across the region through licensing arrangements and joint ventures, establishing the production corridors that now serve municipal procurement offices from Seoul to Singapore.
China
Urban transit networks in Beijing, Shanghai, and Shenzhen are replacing legacy magnetic stripe infrastructure with ISO/IEC 14443-compliant contactless platforms to reduce gate congestion during peak hours. SAMR-administered GB/T standards for financial IC cards are tightening interoperability requirements between domestic payment networks and municipal transit systems, forcing foreign secure element vendors to establish local testing partnerships. The Yangtze River Delta corridor anchors credential manufacturing capacity, with Shanghai-based assemblers deepening backward integration into chip packaging to capture margin pools previously flowing offshore.
India
UIDAI-linked Aadhaar mandates are pulling EMVCo-certified dual-interface cards into financial inclusion programs at state and district levels, reshaping procurement patterns across rural banking cooperatives. TRAI's machine-to-machine communication guidelines are creating embedded secure element demand for connected vehicle and utility metering applications in Maharashtra and Gujarat. Karnataka's Bangalore-Tumkur industrial corridor hosts personalization bureaus serving combined transit-benefit credentials for state transport undertakings in southern India.
Japan
METI-enforced JIS X 6319 specifications govern product certification pathways for domestic transit and payment credential issuers, segmenting compliance requirements from regional competitors. The Kanto region surrounding Tokyo maintains concentrated demand from Suica and Pasmo network operators upgrading to next-generation secure element architectures. Osaka-based transit authorities in the Kansai region are piloting biometric-converged credential systems for high-value payment segments previously resistant to standard smart card form factors.
South Korea
Seoul Capital Area metro operators are consolidating vendor relationships around full-stack credential platform providers rather than component suppliers, displacing pure-play card manufacturers lacking secure element design capabilities. The country's financial regulator mandates EMVCo certification for dual-interface payment credentials deployed through retail banking channels. Busan-Ulsan industrial complexes host polycarbonate substrate fabrication for government identity contracts requiring ten-year document lifecycles.
Australia
The Digital Transformation Agency's eID framework under federal procurement specifications favors interoperable credentials, creating vendor qualification pathways for regional players seeking entry into government identity contracts. New South Wales and Victoria state transport authorities are evaluating combined transit-payment credential stacks following procurement consolidation trends visible in Asian tier-one metros. Sydney-based personalization bureaus are positioning for cross-border contracts requiring simultaneous satisfaction of Australia's eID framework and neighboring Asia Pacific regulatory regimes.
Asia Pacific Smart Card Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification velocity and secure element design capability, with municipal procurement offices now consolidating around full-stack platform providers rather than component suppliers. The vendor base organizes into three tiers: semiconductor houses controlling secure element silicon, credential assemblers with personalization bureau networks, and modular technology licensors supplying configurable functional blocks. Dominant competitive moves include strategic partnerships with municipal transit authorities for multi-application credential deployments and backward integration into chip packaging to capture margin pools from offshore foundries.
Within the semiconductor-architecture tier, NXP Semiconductors N.V. and Infineon Technologies AG represent European-origin secure element specialists whose product portfolios anchor contactless transit deployments across major Asian metros. Samsung Electronics Co., Ltd. occupies a distinct position as a Korea-based conglomerate with captive secure element manufacturing capacity serving mobile payment ecosystems. IDEMIA SAS exemplifies the integrated credential platform model, with its biometric-integrated systems extending government identity contracts in France and derivative markets. These three anchors illustrate how competitive positioning now depends on unified transit-payment-identity stack capabilities rather than single-purpose card manufacturing scale.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| IDEMIA SAS |
| Giesecke & Devrient GmbH |
| Thales Group S.A. |
| Samsung Electronics Co., Ltd. |
| Infineon Technologies AG |
| Toshiba Corporation |
| Watchdata Co., Ltd. |
| Eastcompeace Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Modular secure element architectures are collapsing traditional cost structures across Asia Pacific credential manufacturing, compressing certification timelines while simultaneously redistributing margin pools from offshore foundries toward domestic chip packaging facilities in China and South Korea.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement across government identity, financial services, and transit applications. Price differentiation centers on EMVCo certification grade and polycarbonate substrate durability specifications. Cost compression in economy-tier contactless cards is intensifying because domestic Chinese assemblers have achieved backward integration into secure element packaging. Government agencies exhibit lowest price sensitivity due to ten-year document lifecycle mandates, while municipal transit authorities face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from China's tier-one metro systems and India's state transport undertakings, while specialized distributors serve mid-tier personalization bureaus across Southeast Asia. Secure element wafer fabrication concentrates in Taiwan, South Korea, and Germany, drawing from polycarbonate substrate feedstocks tied to petrochemical indices. Single-source vulnerability in EMVCo-certified cryptographic core supply creates procurement risk for credential assemblers lacking multi-foundry relationships. Distribution runs through regional personalization bureau networks anchored in Shanghai, Bangalore, and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia Pacific smart cards rests on the shift toward biometric-converged premium credentials and the cost-down trajectory of modular secure element architectures displacing full-custom silicon redesigns.
For Market Incumbents: Deepen backward integration into chip packaging to capture margin pools previously flowing to Taiwan and South Korea foundries. Defend against modular technology licensors by accelerating EMVCo certification velocity for unified transit-payment-identity stacks. Prioritize captive secure element capacity in the Yangtze River Delta corridor to offset allocation volatility from concentrated wafer fabrication. For New Entrants and Emerging Players: Capture Indonesia's unbanked archipelago population through mobile-credential ecosystems bridging feature phone and smartphone users. Penetrate Australia's Digital Transformation Agency eID framework procurement specifications by establishing interoperability certification against federal standards. Lead with biometric-on-card technology partnerships to bypass entrenched incumbents in government identity contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among regional personalization bureau operators lacking secure element design capabilities but possessing municipal transit authority relationships. Five-to-ten year viability favors credential platform providers with unified transit-payment-identity stacks over pure-play card manufacturers. Monitor procurement consolidation announcements from China's tier-one metros and India's state transport undertakings as inflection signals for vendor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chip Packaging | Shanghai-based assemblers capture margin pools from offshore foundries under SAMR's GB/T standards. |
| Biometric-Converged Credential Development | Fingerprint-on-card technology opens government identity segments resistant to standard form factors. |
| Multi-Application Platform Certification | Unified transit-payment-identity stacks compress procurement cycles for India's UIDAI-linked programs. |
| Local Testing Partnership Establishment | Foreign secure element vendors secure China market access through SAMR-administered GB/T compliance. |
| Personalization Bureau Network Expansion | Regional bureaus in Bangalore and Sydney position for cross-border credential contracts. |
Research Methodology
Bottom-up transit authority and financial institution procurement modeling reconciled against top-down secure element foundry output tracking forms the analytical core. Primary interviews with municipal procurement officers, credential platform engineering directors, EMVCo certification specialists, and polycarbonate substrate procurement leads combined with secondary validation against SAMR GB/T filings, TRAI machine-to-machine guidelines, UIDAI procurement notices, and metro operator tender documents.
Input-output matrices map secure element wafer supply through chip packaging, card lamination, and personalization bureau stages across the projection horizon. Segmentation dimensions include technology tier, application bundle, end-user institutional category, and material substrate. CAGRs derive from installed base replacement cycles and new credential issuance trajectories, incorporating UIDAI mandate penetration rates and contactless transit gate upgrade timelines as industry-specific forecast inputs.
Regulatory specification shifts, polycarbonate feedstock price volatility, and cryptographic engineering talent scarcity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EMVCo certification velocity and municipal procurement consolidation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
US Transcription Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Global Freight Software Market