
 Digital Pen Market | 2026-2036
Digital Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pen Market Intelligence
Subscription-based hardware leasing and asset-light procurement models is rewriting competitive entry barriers for educational institutions and mid-sized enterprises. Wacom Co., Ltd. leverages decades of electromagnetic digitization expertise to anchor premium graphic tablet pen supply chains. Samsung Electronics Co., Ltd. competes through tight integration with its Galaxy device ecosystem, while Apple Inc. controls stylus distribution via proprietary capacitive protocols locked to iPad hardware.
A digital pen is an electronic input device capturing handwritten strokes through pressure-sensitive nibs, accelerometers, and wireless transmission modules, converting analog handwriting into machine-readable vector or raster data for display, storage, or cloud synchronization. The device typically employs electromagnetic resonance or active capacitive sensing to achieve sub-millimeter positional accuracy across glass or paper substrates. Stylus pen and smart pen categories dominate unit volume, with Bluetooth-enabled segments capturing expanding margin pools as enterprises prioritize wireless pairing reliability. Electromagnetic technology leads in professional art and design applications, while capacitive variants penetrate education budgets due to lower per-unit cost structures.
FCC certification governs radio frequency emissions for Bluetooth-equipped devices sold in the United States, while CE marking mandates electromagnetic compatibility and safety compliance across European distribution channels. Japan's METI enforces energy efficiency and radio law standards that constrain product design cycles for infrared and Bluetooth variants. Stakeholders must monitor evolving interoperability mandates from ISO and IEC working groups, as unified digitization standards will determine which technology architectures secure long-term platform integration contracts.
Market Dynamics
Enterprise procurement of stylus and smart pen devices is accelerating across healthcare documentation workflows, reshaping vendor qualification criteria toward electromagnetic digitization and Bluetooth interoperability standards.
Growth Catalysts
- Healthcare digitization mandates:Clinical annotation systems in the United States require pressure-sensitive input devices for electronic health record compliance, expanding institutional procurement volumes.
- ISO/IEC digitization standards:Unified interoperability mandates from international working groups are compressing fragmentation across electromagnetic and capacitive technology architectures.
- Education budget reallocations:Germany and Japan deploy large-scale digital learning infrastructure, concentrating demand for lower-cost capacitive stylus variants in K-12 and university procurement channels.
Market Restraints
- Input cost volatility:Rare earth magnet supply concentration in China creates pricing instability for electromagnetic resonance coil assemblies.
- Technical limitation:Sub-millimeter accuracy requirements on glass substrates exclude low-cost resistive technologies from professional art and design applications.
- Regulatory friction:Japan's METI radio law standards extend product design cycles for Bluetooth-equipped variants, delaying market entry timelines.
Strategic Opportunities
- Underpenetrated clinical workflows:Surgical documentation and pathology annotation in German hospital systems remain paper-dependent, creating whitespace for smart pen deployment.
- Technology convergence:Accelerometer-gyroscope fusion with machine learning stroke recognition is enabling predictive handwriting analysis for enterprise workflow optimization.
- Asset-light procurement models:Subscription-based hardware leasing is rewriting competitive entry barriers for educational institutions and mid-sized enterprises.
Industry Challenges
- Certification timeline compression:FCC radio frequency emissions testing and CE electromagnetic compatibility validation create sequential bottlenecks for multi-region product launches.
- Integration complexity:Legacy electronic health record systems in United States hospital networks require custom middleware development for stylus data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pen Market |
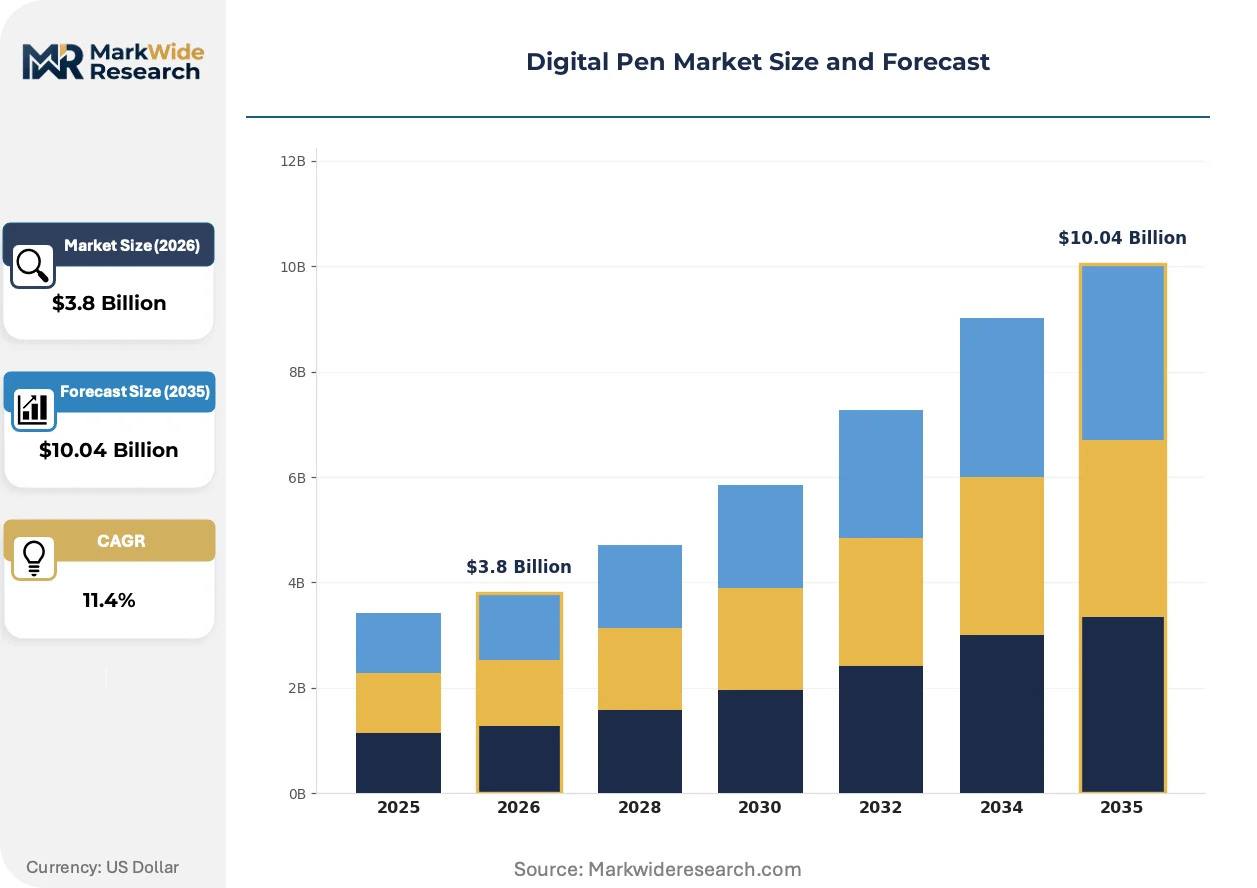
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pen, Stylus Pen, Graphic Tablet Pen, Digital Notepad Technology: Capacitive, Bluetooth, Infrared, Electromagnetic Application: Education, Art and Design, Business, Healthcare End User: Students, Professionals, Artists, Healthcare Providers |
| Companies Covered | Samsung Electronics Co., Ltd., Hanvon Technology Co., Ltd., Apple Inc., Sony Corporation, Canon Inc., Wacom Co., Ltd., Lenovo Group Limited, Hewlett-Packard Development Company, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pen Market Strategic Shifts & Innovations
Bluetooth and electromagnetic digitization standards are actively reshaping interoperability requirements, forcing cross-platform device architectures toward unified transmission protocols and cloud-native stroke synchronization.
Machine learning-enhanced stroke recognition is virtualizing handwriting analysis by converting analog pressure and tilt data into predictive intent models. Healthcare documentation teams in the United States are piloting these systems for real-time clinical coding assistance. This capability is virtualizing the traditional transcription services market by embedding semantic understanding directly into capture hardware.
CE marking mandates for electromagnetic compatibility are tightening safety compliance thresholds across European distribution channels. Medical device manufacturers must now demonstrate sub-millimeter positional accuracy under IEC testing protocols before hospital procurement approval. Professional art and design segments are absorbing these certification costs fastest, passing premiums through to institutional buyers.
Enterprise buyers now unbundle hardware acquisition from software licensing, forcing vendors to separate stylus device sales from proprietary cloud synchronization subscriptions. Educational institutions in Japan are driving this shift through bulk procurement frameworks that mandate API-accessible stroke data. Healthcare systems in Germany exhibit similar purchasing patterns, prioritizing vendor-neutral data portability over integrated ecosystem lock-in.
Digital Pen Market Segmentation
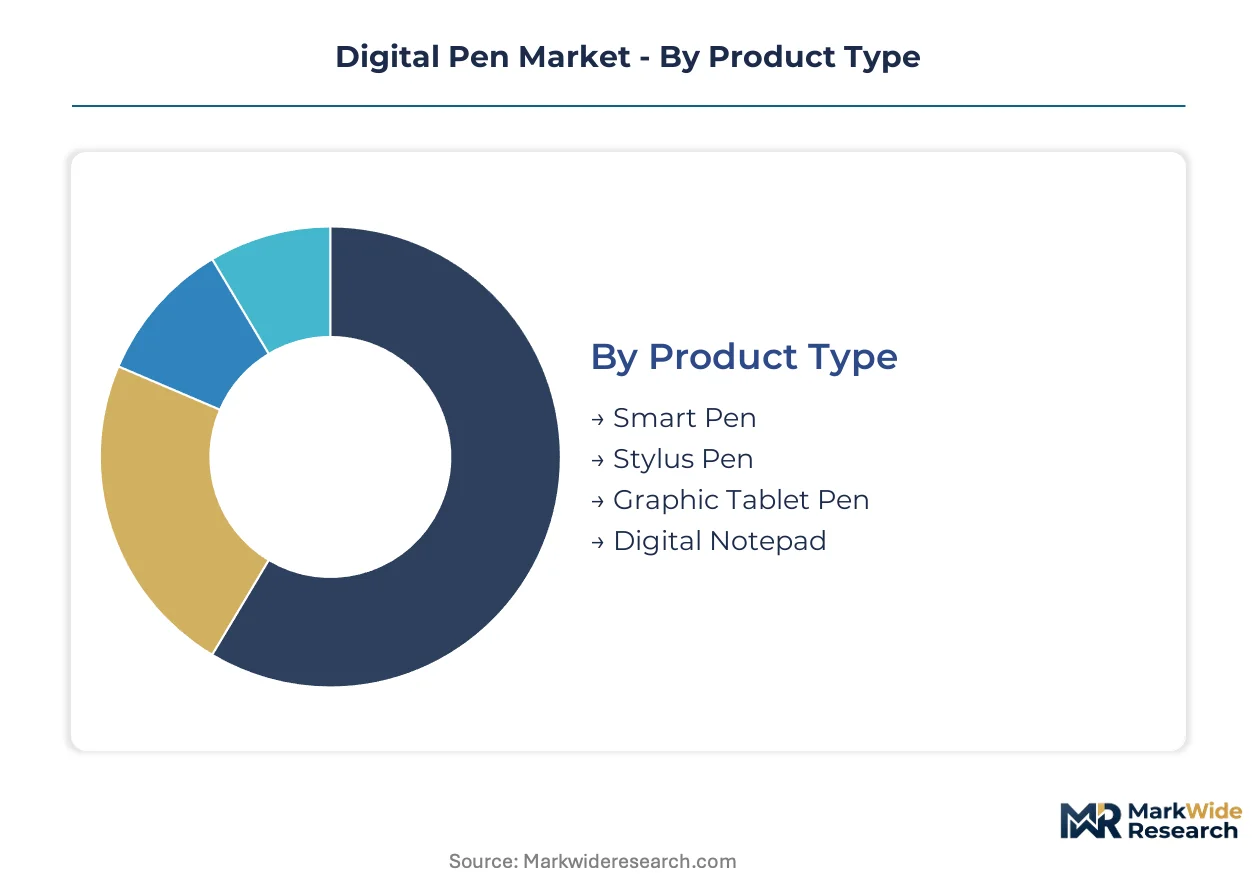
Segmentation in the digital pen market reveals how procurement priorities diverge across electromagnetic precision requirements, wireless protocol standards, and institutional budget tiers. Understanding these fault lines exposes where vendors can defend margin pools versus where price competition erodes profitability.
Product Type:
Mature stylus pen formats coexist with emerging smart pen architectures that embed local processing and cloud synchronization capabilities.
- Smart Pen:These devices integrate internal processors, onboard storage, and wireless transmission modules to capture handwriting without companion tablets. Healthcare documentation workflows in the United States concentrate procurement here, driven by HIPAA-compliant electronic health record mandates that require offline capture with encrypted synchronization.
- Stylus Pen:Passive or active capacitive implements rely on host device screens for positional detection and power. Germany's K-12 digital learning infrastructure absorbs volume at the economy tier, though electromagnetic variants penetrate university procurement channels demanding sub-millimeter accuracy.
- Graphic Tablet Pen:Electromagnetic resonance devices paired with dedicated digitizing tablets deliver pressure sensitivity up to levels for professional illustration and industrial design.
- Digital Notepad:Hybrid systems combining paper-physical writing surfaces with real-time digitization target business professionals requiring analog note retention alongside digital archives.
Stylus pen handles the majority of throughput; smart pen is climbing the fastest on share.
Technology:
Cost tier stratification separates premium electromagnetic implementations from mass-market capacitive alternatives, with Bluetooth connectivity commanding intermediate pricing.
- Capacitive:Passive styluses leveraging existing touch screen electrostatic fields dominate unit economics in education budgets. Japan's METI energy efficiency standards constrain active variants, favoring passive designs in bulk institutional procurement.
- Bluetooth:Active wireless protocols enabling cross-platform pairing and cloud-native stroke synchronization. Enterprise healthcare deployments in the United States prioritize FCC-certified variants for clinical annotation systems requiring reliable wireless handoff.
- Infrared:Optical tracking systems using patterned paper and infrared cameras capture handwriting position through external sensors rather than pen-integrated electronics.
- Electromagnetic:Resonance coil architectures delivering superior positional accuracy and pressure granularity. Professional art applications and medical device manufacturing specifications in Germany mandate IEC-tested electromagnetic variants for sub-millimeter precision compliance.
Capacitive handles the majority of throughput; Bluetooth is gaining share fastest.
Application:
Customer type differentiation separates institutional procurement with extended qualification cycles from individual purchasing with minimal vendor scrutiny.
- Education:Large-scale infrastructure deployments across K-12 and university systems. Germany and Japan concentrate demand through national digital learning initiatives that standardize on API-accessible stroke data formats.
- Art and Design:Professional creative workflows requiring pressure sensitivity, tilt recognition, and low latency. Electromagnetic graphic tablet pens anchor this segment with certification costs passed through to studio and institutional buyers.
- Business:Corporate documentation, signature capture, and meeting annotation. Subscription-based hardware leasing models are rewriting competitive entry barriers for mid-sized enterprises.
- Healthcare:Clinical documentation, surgical annotation, and pathology review. United States electronic health record compliance mandates accelerate procurement of pressure-sensitive input devices with middleware integration capabilities.
Education handles the majority of throughput; healthcare is expanding most quickly on share.
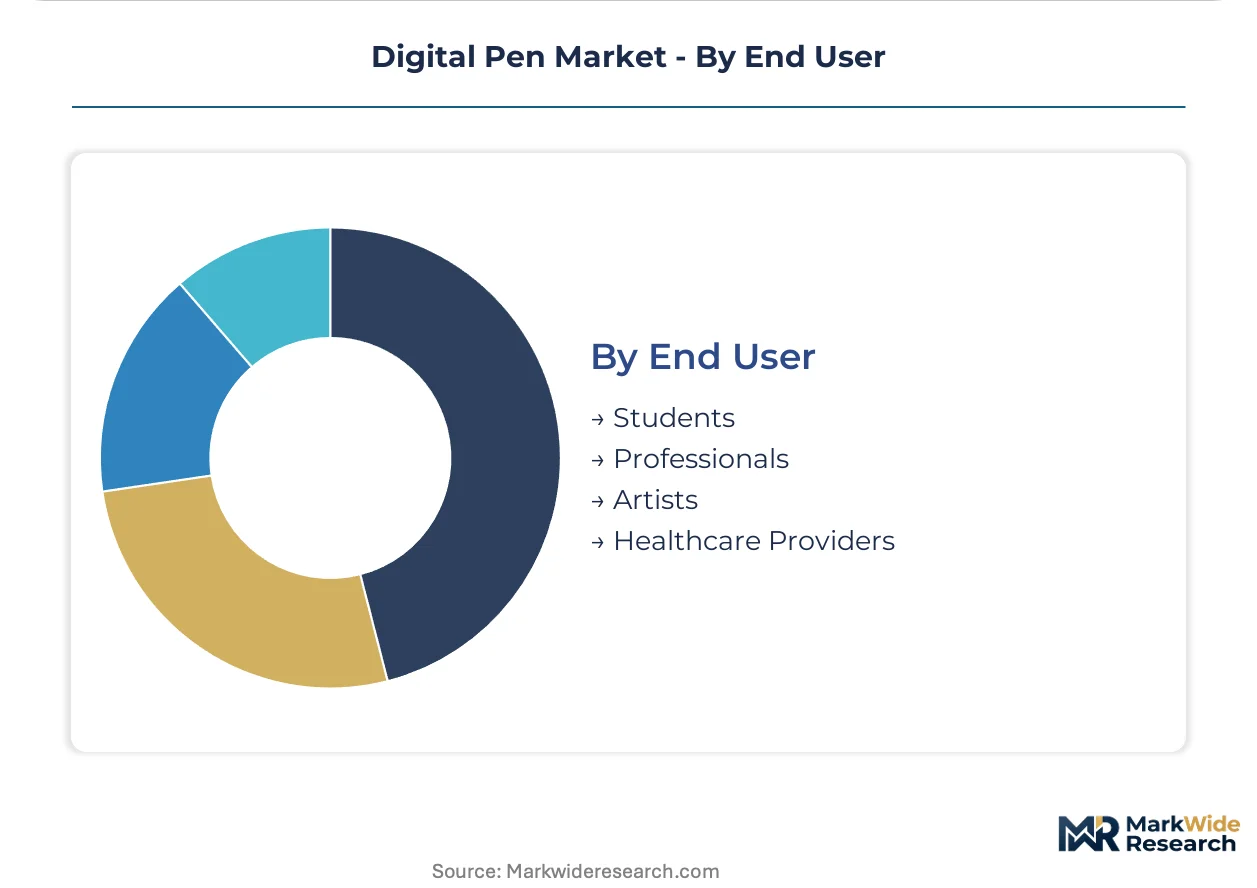
End User:
Volume concentration in student populations contrasts with margin concentration among professional segments where accuracy specifications justify premium pricing.
- Students:Price-sensitive bulk procurement through educational institutions. Capacitive stylus variants dominate this population with per-unit costs aligned to constrained K-12 technology budgets.
- Professionals:Business users prioritizing workflow integration and data portability. API-accessible stroke data requirements drive vendor-neutral purchasing patterns over ecosystem lock-in.
- Artists:Creative professionals demanding electromagnetic precision and pressure sensitivity tiers. Certification under IEC protocols validates sub-millimeter accuracy claims for studio equipment procurement.
- Healthcare Providers:Clinical staff requiring HIPAA-compliant capture with electronic health record integration. Middleware development for legacy hospital systems extends sales cycles but secures long-term platform contracts.
Students handle the majority of throughput; healthcare providers are the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in digital pen hardware tilt toward import-dependent education systems and export-oriented precision manufacturing clusters. The United States, Germany, and Japan concentrate procurement volumes, while assembly operations gravitate toward established electronics manufacturing corridors.
United States
Healthcare digitization and enterprise documentation drive institutional procurement. FCC radio frequency emissions certification governs Bluetooth-equipped device market entry. Boston and Austin metropolitan areas concentrate health-tech pilot programs for clinical annotation systems.
Germany
K-12 digital learning infrastructure and industrial design studios absorb distinct product tiers. CE marking mandates electromagnetic compatibility validation across European distribution. Bavaria anchors professional graphics tablet demand through Munich-based creative industry clusters.
Japan
National digital education initiatives and precision manufacturing specifications shape procurement patterns. METI radio law standards extend design cycles for wireless variants. Tokyo-Osaka corridor hosts specialized electromagnetic resonance component suppliers serving domestic OEMs.
South Korea
Display panel manufacturing integration creates captive demand for active stylus architectures. National energy efficiency regulations favor low-power capacitive implementations. Seoul metropolitan area concentrates R&D facilities for pressure-sensing digitization technologies.
China
Domestic education technology budgets and rare earth magnet supply concentration influence cost structures. GB standards govern electromagnetic product safety for local distribution. Shenzhen and Dongguan manufacturing clusters handle final assembly for export markets.
Digital Pen Market Key Industry Players
On the supply side, the industry is bifurcated between integrated device ecosystem vendors and specialized digitization technology providers. Tiered competitive positioning separates premium electromagnetic specialists from mass-market capacitive suppliers. Strategic archetypes include ecosystem-locked hardware vendors, component-focused precision manufacturers, and cross-platform interoperability specialists. Dominant competitive moves center on proprietary protocol licensing and backward integration into rare earth magnet supply chains.
Within the precision digitization tier, Wacom Co., Ltd. and Hanvon Technology Co., Ltd. exemplify specialized electromagnetic resonance expertise. Samsung Electronics Co., Ltd. occupies a position representing ecosystem-locked hardware distribution through tight device integration. These archetypes illustrate how vendor strategies diverge between open interoperability mandates and proprietary platform control.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Hanvon Technology Co., Ltd. |
| Apple Inc. |
| Sony Corporation |
| Canon Inc. |
| Wacom Co., Ltd. |
| Lenovo Group Limited |
| Hewlett-Packard Development Company |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Shenzhen and Dongguan assembly corridors compresses supplier margins while concentrating pricing power with electromagnetic component specialists. This utilization imbalance drives tiered procurement behavior: premium electromagnetic pens command certification-backed premiums, while capacitive variants compete on unit economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IEC certification grade and volume scale, with healthcare providers absorbing the highest premiums for HIPAA-compliant smart pen architectures. Cost compression in education-tier capacitive styluses is intensifying because Japan's METI energy efficiency standards favor passive designs. Students exhibit greatest price sensitivity, while clinical procurement committees prioritize interoperability over per-unit cost.
Supply Chain Analysis
Extended payment terms from Japanese OEMs and supply-chain finance facilities anchor working capital structures for component suppliers. Rare earth magnet processing draws from China, electromagnetic coil manufacturing centers on Japan, and final assembly feeds from South Korea. Single-source vulnerability concentrates in neodymium supply chains. Distribution runs through educational procurement frameworks, enterprise IT channels, and direct-to-professional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital pen market functions as a defensive-moat story where proprietary electromagnetic protocols create regulatory entrenchment. Switching costs for healthcare systems with embedded EHR middleware lock in incumbent positions.
For Market Incumbents: Harden electromagnetic resonance IP portfolios against capacitive substitution threats. Expand backward integration into rare earth magnet supply chains to offset input cost volatility. Deepen certification investments under IEC and FCC protocols to extend hospital procurement lock-in. For New Entrants and Emerging Players: Build out API-accessible stroke data platforms targeting Germany's underpenetrated surgical documentation workflows. The most penetrable whitespace sits in pathology annotation systems requiring offline capture with encrypted synchronization. Lead with subscription-based hardware leasing to bypass capital budget friction in mid-sized enterprises. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native stroke synchronization providers with healthcare middleware integration. Long-term viability favors vendors with proprietary electromagnetic architectures and institutional certification depth. Watch for inflection when ISO/IEC unified digitization standards force interoperability mandates that erode ecosystem lock-in advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Protocol Licensing | Proprietary resonance architectures secure long-term platform integration contracts from healthcare OEMs. |
| Backward Integration into Magnets | Captive neodymium supply chains insulate margin pools from Chinese export quota volatility. |
| HIPAA-Compliant Cloud Synchronization | Encrypted stroke data pipelines unlock institutional procurement in United States hospital networks. |
| API-Accessible Data Platforms | Vendor-neutral portability meets German and Japanese educational procurement mandates. |
| Accelerometer-Gyroscope Fusion R&D | Machine learning stroke recognition virtualizes transcription services for clinical coding assistance. |
Research Approach
Cross-validation between procurement director interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork encompassed hospital IT directors, educational technology procurement officers, electromagnetic component engineers, and GPO contracts managers. Secondary sources included FCC equipment authorization databases, METI radio law compliance listings, CE marking registries, and customs trade flow records. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Calibration against historical penetration curves in comparable input device categories informed the analytical framework. Segmentation dimensions spanned product architecture, wireless protocol standard, institutional budget tier, and regional regulatory cluster. CAGRs derived from fitted adoption curves across healthcare digitization and educational infrastructure deployment waves. Forecast inputs incorporated electromagnetic component cost trajectories and Bluetooth certification timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ecosystem-locked hardware vendors would shift outcomes. Macroeconomic contraction in institutional technology budgets, acceleration of capacitive substitution in professional segments, or unification of ISO/IEC digitization standards ahead of projected timelines would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Business Transcription Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Online Recruitment Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Data Integration Market
Digital Solutions
France ICT Market
Digital Solutions
Indonesia Enterprise Mobility Management Market
Digital Solutions
Demand Side Platform (DSP) Market