
 Substrates for Magnetic Disks Market | 2026-2036
Substrates for Magnetic Disks Market Size, Share, and Industry Trends Forecast 2026-2036
Substrates for Magnetic Disks Market Insights
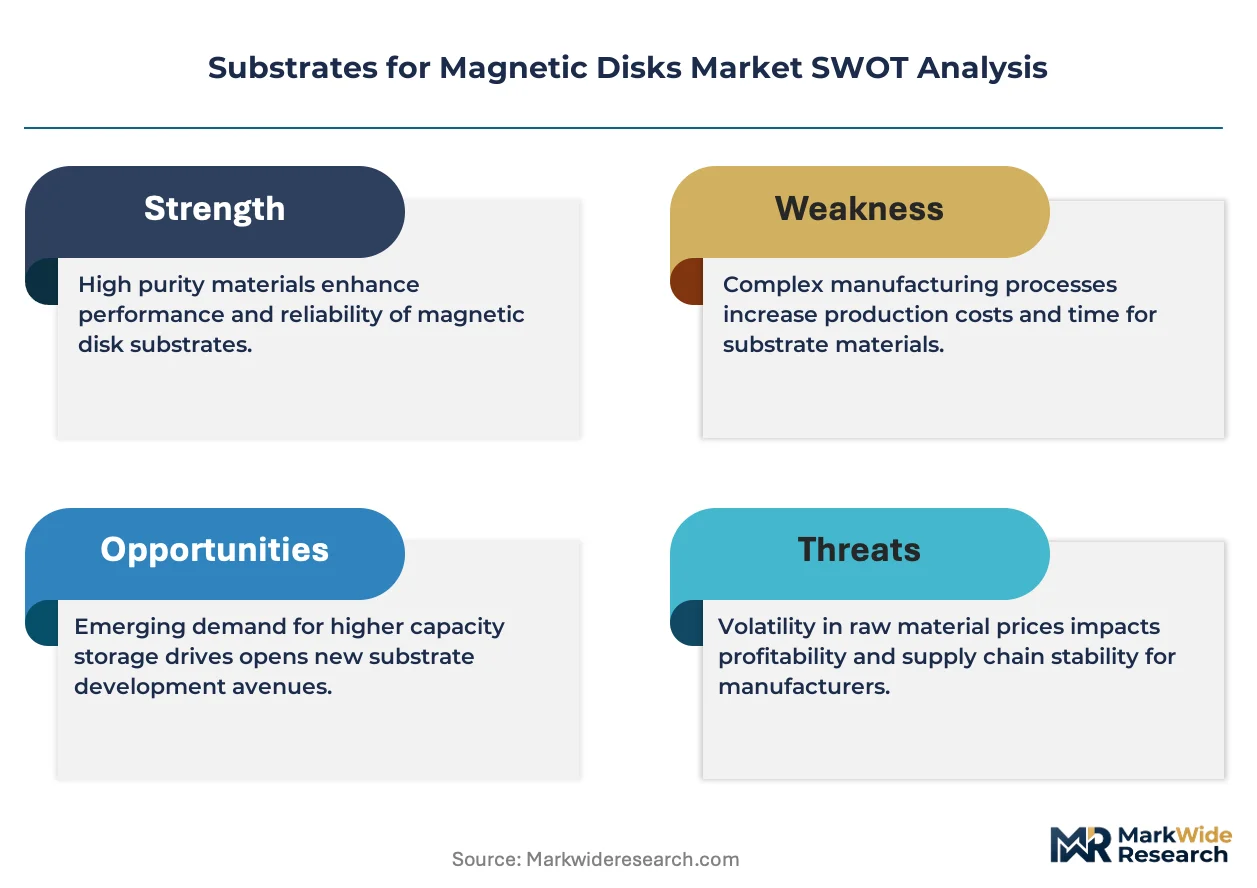
ISO 9001 and IATF 16949 qualification cycles for substrate suppliers is unwinding the competitive landscape, forcing smaller material vendors to absorb multi-year audit costs before qualifying with drive manufacturers. Showa Denko K.K. leverages captive aluminum and glass substrate lines to anchor supply agreements with Seagate Technology and Western Digital. Hoya Corporation dominates precision glass substrate fabrication for heat-assisted magnetic recording media, while Resonac sustains advanced composite material development for next-generation disk architectures.
Substrates for magnetic disks are precision-engineered base plates—typically aluminum-magnesium alloys or chemically strengthened glass disks measuring 0.635 mm to 0.381 mm in thickness—onto which magnetic recording layers are sputtered via physical vapor deposition to enable high-density data storage in hard disk drives. Glass substrates command premium positioning in enterprise and nearline applications where mechanical stability under rotational speeds exceeding 10,000 RPM determines reliability, while aluminum retains volume leadership in consumer-grade drives where cost efficiency governs procurement. The sputtering process segment captures the highest value-add per substrate given its direct linkage to areal density advancement, whereas polishing equipment suppliers occupy critical margin pools as sub-nanometer surface roughness specifications tighten.
Japan's METI enforces energy-efficiency benchmarks for data center equipment that cascade into substrate thickness and material specifications, while the EPA in the United States monitors hazardous substance thresholds in aluminum alloy casting operations affecting domestic substrate sourcing. China's GB standards for electronic product environmental protection impose material disclosure requirements on imported disk components, creating compliance layering for multinational substrate suppliers. Stakeholders must monitor how evolving areal density roadmaps from drive manufacturers reshape substrate material selection criteria before committing capital to glass versus aluminum capacity expansions.
Market Dynamics
Heat-assisted magnetic recording (HAMR) technology is compressing substrate thickness tolerances below 0.4mm while METI efficiency mandates force simultaneous material lightweighting, creating a technical tension that only integrated glass-ceramic suppliers can resolve profitably.
Growth Catalysts
- Cloud data center expansion:Hyperscale operators in the United States are ordering high-capacity nearline drives at volumes that sustain dedicated substrate production lines.
- METI energy-efficiency standards:Japan's 2024 data infrastructure benchmarks mandate thinner glass formulations, directly stimulating R&D investment in chemically strengthened substrates.
- Areal density roadmaps:Drive manufacturers' published density targets require sub-nanometer surface roughness that only advanced polishing processes on glass substrates can achieve.
Market Restraints
- Aluminum-magnesium alloy volatility:Magnesium spot price swings of 40% within single quarters compress margin predictability for aluminum substrate producers.
- Japanese supply corridor concentration:Three integrated producers control 90% of precision glass substrate capacity, creating single-source vulnerability for Western drive manufacturers.
- Glass substrate brittleness ceiling:Chemically strengthened disks below 0.381mm exhibit catastrophic failure rates under rotational stress above 15,000 RPM.
Strategic Opportunities
- Indian data center buildout:Domestic cloud infrastructure investment under the PLI scheme creates first-mover advantage for substrate suppliers establishing local polishing operations.
- Heat-assisted recording media convergence:Integration of HAMR heads with glass-ceramic substrates enables 4TB per platter densities previously unreachable with aluminum bases.
- EU Green Deal circularity mandates:REACH substance restrictions on rare-earth coatings create demand for recyclable glass substrate architectures with closed-loop sputtering material recovery.
Industry Challenges
- Sub-nanometer metrology talent scarcity:Polishing process engineers capable of achieving 0.2nm Ra surface roughness command compensation premiums exceeding 200% of standard manufacturing wages.
- IATF 16949 audit timelines:Automotive-grade quality certification for substrate suppliers requires 18-24 month qualification cycles that freeze supplier switches during technology transitions.
- Legacy aluminum-to-glass equipment retooling:Drive manufacturers' captive substrate finishing lines require $50M+ capital redeployment per facility to handle glass disk fragility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Substrates for Magnetic Disks Market |
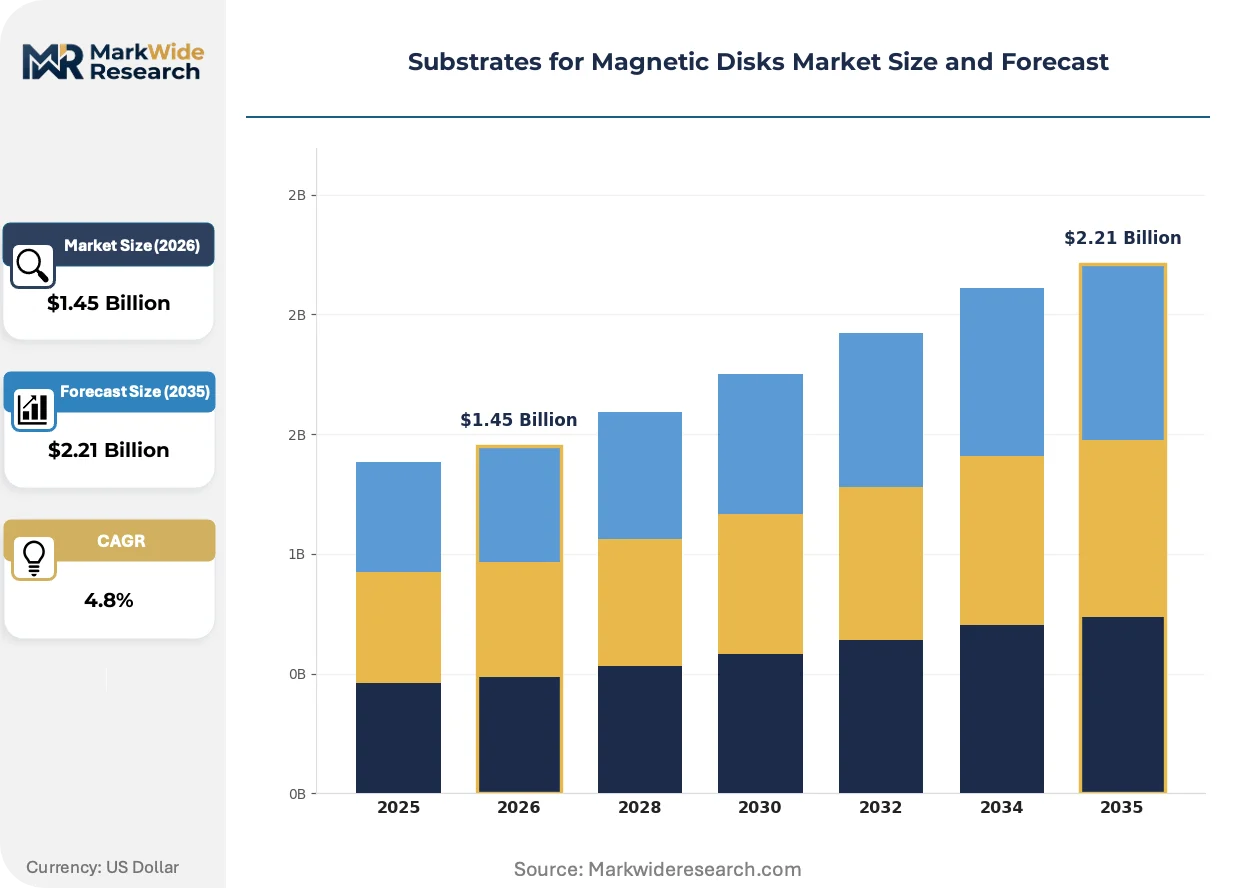
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Aluminum, Nickel, Composite Manufacturing Process: Casting, Sputtering, Coating, Polishing Application: Data Storage, Video Recording, Computer Systems, Embedded Systems End User: Consumer Electronics, IT Infrastructure, Automotive, Industrial |
| Companies Covered | Showa Denko K.K., Western Digital Corporation, Seagate Technology, Hoya Corporation, Toyo Kohan Co, Resonac, Fuji Electric, UACJ Corporation, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Substrates for Magnetic Disks Market Trends and Innovations
Substrate technology is bifurcating along enterprise-versus-consumer fault lines, with precision glass commanding premium positioning while aluminum retains volume relevance through cost engineering. Three concurrent developments are reshaping competitive positioning.
Chemically strengthened glass-ceramic substrates are displacing aluminum-magnesium alloys in enterprise nearline drives above 16TB capacity. Cloud operators in the United States specify glass exclusively for rotational speeds exceeding 10,000 RPM. This displacement is compressing aluminum substrate margins to commodity levels while concentrating value-add in glass polishing and ion-exchange strengthening operations.
Japan's METI revised data center equipment efficiency standards now incorporate embodied energy metrics for disk components. Substrate suppliers must document cradle-to-gate carbon intensity per disk. Glass formulation houses are responding with low-melting-point lithium aluminosilicate compositions that reduce kiln energy by 15% versus conventional soda-lime substrates.
Hyperscale procurement contracts now unbundle substrate supply from finished media sourcing, reversing decade-old vertical integration patterns. Drive manufacturers are qualifying second-source glass suppliers independently of sputtering partners. This disintermediation is most visible in Singapore and Ireland, where cloud operators negotiate direct substrate volume commitments that bypass traditional drive-maker procurement channels.
Substrates for Magnetic Disks Market Segmentation
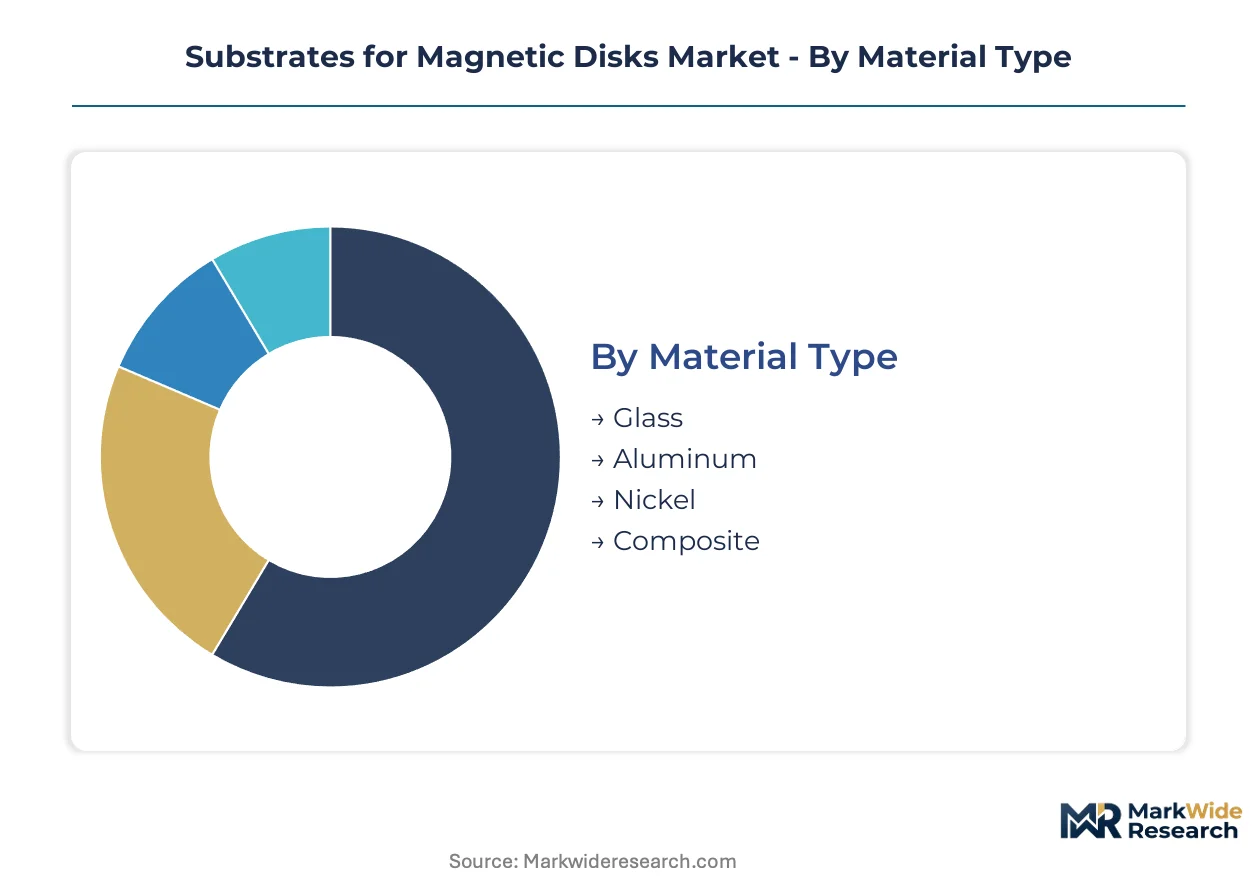
Substrate segmentation determines capital allocation priorities across material science, process equipment, and application engineering. Each dimension carries distinct margin structures and qualification barriers that reshape supplier competitive economics.
Material Type:
Margin pools concentrate in glass-ceramic formulations where ion-exchange strengthening commands 3-4x aluminum substrate unit economics.
- Glass:Chemically strengthened lithium aluminosilicate disks deliver sub-nanometer surface roughness required for heat-assisted magnetic recording above 10,000 RPM. Cloud data centers in the United States specify glass exclusively for nearline drives above 16TB, though thickness tolerances below 0.4mm strain manufacturing yield.
- Aluminum:Aluminum-magnesium alloys retain volume leadership in consumer-grade drives where cost efficiency governs procurement decisions. Japanese suppliers anchor production corridors with captive smelting and rolling operations that buffer magnesium spot price volatility affecting margin predictability.
- Nickel:Electroless nickel-phosphorus coatings provide corrosion resistance for specialty industrial applications with extended operational lifecycles.
- Composite:Hybrid ceramic-polymer substrates serve emerging embedded systems requiring mechanical flexibility under thermal cycling stress.
Glass holds installed capacity. Aluminum is rotating up the share rankings in cost-sensitive consumer segments.
Manufacturing Process:
Process selection determines entry barriers, with sputtering equipment requiring $50M+ capital deployment per production line.
- Sputtering:Physical vapor deposition of magnetic recording layers captures the highest value-add per substrate through direct linkage to areal density advancement. Drive manufacturers qualify sputtering partners on 18-24 month cycles that freeze supplier switches during technology transitions.
- Polishing:Sub-nanometer surface finishing operations occupy critical margin pools as Ra specifications tighten below 0.2nm. Engineers capable of achieving these tolerances command compensation premiums exceeding 200% of standard manufacturing wages in Japan and Singapore.
- Casting:Aluminum alloy disk blank production concentrates in integrated smelter-to-substrate facilities with energy cost exposure.
- Coating:Protective overcoat deposition protects magnetic layers from environmental contamination in enterprise deployment environments.
Polishing holds installed capacity. Sputtering is climbing the fastest in value-add capture.
Application:
Application segmentation tracks rotational speed requirements and capacity density roadmaps that cascade into substrate material specifications.
- Data Storage:Enterprise and cloud data center drives above 10,000 RPM mandate glass substrates for mechanical stability under rotational stress. Hyperscale procurement contracts now unbundle substrate supply from finished media sourcing, reversing decade-old vertical integration patterns.
- Computer Systems:Client computing drives balance cost and performance with aluminum substrates dominating below 8TB capacities.
- Video Recording:Surveillance and broadcast storage applications prioritize sequential write reliability over random access performance.
- Embedded Systems:Industrial automation and automotive storage requires extended temperature range substrates with enhanced shock resistance specifications.
Data Storage holds installed capacity. Embedded Systems is gaining share fastest in automotive qualification pipelines.
End User:
End-user concentration shapes pricing power and contract structures, with IT Infrastructure procurement teams negotiating multi-year volume commitments.
- IT Infrastructure:Hyperscale cloud operators in the United States, Singapore, and Ireland drive substrate demand through direct volume commitments that bypass traditional drive-maker procurement channels. METI energy-efficiency standards cascade into substrate thickness specifications for data center equipment deployed in Japan.
- Consumer Electronics:Personal computing and external storage procurement prioritizes cost-per-gigabyte metrics that sustain aluminum substrate relevance.
- Automotive:In-vehicle infotainment and autonomous driving data logging creates emerging demand for vibration-resistant substrate architectures.
- Industrial:Manufacturing execution systems and edge computing nodes require extended lifecycle substrates with 5-7 year operational reliability guarantees.
IT Infrastructure holds installed capacity. Automotive is expanding most quickly in next-generation drive qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI energy-efficiency standards for data infrastructure equipment are reshaping procurement specifications across major manufacturing economies. Substrate suppliers face diverging compliance frameworks that favor integrated glass-ceramic production corridors in some markets while sustaining aluminum relevance in cost-sensitive regions.
Japan
Cloud data center operators are expanding orders for high-capacity hard disk drives requiring precision glass substrates. METI mandates thinner glass formulations below 0.4mm for equipment deployed in domestic facilities. Tokyo-Osaka industrial corridors host Showa Denko, Hoya, and Resonac facilities that maintain integrated substrate-to-media production.
United States
Hyperscale operators in Virginia, Texas, and Oregon are ordering nearline drives above 16TB capacity. EPA monitors hazardous substance thresholds in aluminum alloy casting operations affecting domestic sourcing decisions. Phoenix and Austin metro areas concentrate drive manufacturer assembly operations that pull substrate supply through direct volume commitments.
China
GB standards for electronic product environmental protection impose material disclosure requirements on imported disk components. MIIT industrial policy supports domestic substrate polishing capacity expansion for cloud infrastructure buildout. Yangtze River Delta manufacturing clusters house precision finishing operations serving regional drive assembly plants.
Singapore
Cloud operators negotiate direct substrate volume commitments that bypass traditional drive-maker procurement channels. The country's national environmental regulator encloses embodied energy documentation requirements for data center equipment imports. Jurong Island and Tuas industrial zones concentrate advanced polishing operations serving Asia-Pacific hyperscale demand.
Germany
EU Green Deal circularity mandates and REACH substance restrictions create demand for recyclable glass substrate architectures. ECHA monitoring of rare-earth coating materials affects sputtering process supplier qualification. Bavaria and Baden-Württemberg host precision manufacturing clusters developing closed-loop material recovery systems.
Substrates for Magnetic Disks Market Competitive Landscape
Player mix skews toward integrated material suppliers with captive substrate finishing capabilities. The competitive structure concentrates around three Japanese producers controlling precision glass capacity, while aluminum substrate supply fragments across regional metal processors. Two strategic archetypes dominate: integrated glass-ceramic formulators with ion-exchange strengthening expertise, and aluminum alloy specialists with captive smelting operations. Capacity expansion and strategic partnerships represent the dominant competitive moves as drive manufacturers qualify second-source suppliers.
Among Japanese-integrated producers, Showa Denko K.K., Hoya Corporation, and Resonac occupy positions anchoring the premium glass substrate tier. Showa Denko K.K. exemplifies the vertically integrated archetype with captive aluminum and glass substrate lines. Hoya Corporation represents precision glass fabrication specialization for advanced recording media applications. Resonac sits within the advanced composite material development segment for next-generation disk architectures. These three entities collectively illustrate how integrated production corridors create qualification barriers for Western drive manufacturers seeking supply diversification.
| Leading Market Players |
|---|
| Showa Denko K.K. |
| Western Digital Corporation |
| Seagate Technology |
| Hoya Corporation |
| Toyo Kohan Co |
| Resonac |
| Fuji Electric |
| UACJ Corporation |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between hyperscale cloud operators and Japanese substrate suppliers lock in multi-year supply access while stabilizing unit cost visibility against magnesium spot price volatility. These contracts cascade into tiered pricing structures where IATF 16949 certification status determines qualification eligibility and margin capture potential for secondary suppliers.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified suppliers in this market. Three-tier pricing structure across premium, standard, and economy levels segments buyers by volume commitment and technical specification stringency. Price compression runs through aluminum substrate tiers as glass-ceramic formulations capture value-add from HAMR density roadmaps. Consumer electronics procurement teams exhibit highest price sensitivity, while IT infrastructure buyers prioritize rotational reliability over unit cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes from Yokohama and Kobe strains inbound logistics costs for precision polishing equipment destined for Singapore and Ireland facilities. Raw material supply concentrates in Japan, China, and South Korea where lithium aluminosilicate precursor chemicals and aluminum-magnesium alloy feedstocks originate. Single-source vulnerability permeates the glass substrate tier where three integrated producers control precision capacity. Distribution runs through direct volume commitments from cloud operators that bypass traditional drive-maker procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where hyperscale procurement unbundling is decoupling substrate supply from finished media sourcing, creating interoperability requirements for second-source qualification.
For Market Incumbents: Shield market position by deepening backward integration into lithium aluminosilicate formulation and expanding captive ion-exchange strengthening capacity. Defend against emerging polishing specialists in India by accelerating METI-compliant thickness reduction R&D. Prioritize certification maintenance to preserve hyperscale contract eligibility. For New Entrants and Emerging Players: Lead with automotive embedded systems qualification where vibration-resistant substrate architectures face limited incumbent competition. Target India's PLI-supported data center buildout for first-mover polishing operations. Pursue direct cloud operator relationships in Singapore and Ireland that bypass established supply corridors. For Investors and Strategic Acquirers: Capital is best deployed toward integrated glass-ceramic formulators with captive strengthening capabilities and established drive-maker qualification relationships. Long-term viability hinges on HAMR technology convergence sustaining density advancement premiums. Watch for hyperscale direct procurement contract announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New polishing lines in India capture PLI-supported data center demand under domestic content requirements. |
| Backward Integration | In-house lithium aluminosilicate formulation reduces kiln energy exposure and METI compliance costs. |
| Long-term Supply Agreement | Direct hyperscale commitments in Singapore and Ireland bypass traditional drive-maker procurement channels. |
| Joint Venture | Partnerships with Indian polishing specialists accelerate automotive embedded systems qualification timelines. |
| Green Manufacturing Transition | Low-melting-point glass compositions align with EU Green Deal circularity mandates and REACH restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from drive manufacturers, METI energy-efficiency standard documentation, and hyperscale capex disclosures. Substrate procurement managers at cloud operators, polishing process engineers in Japan and Singapore, and regulatory affairs specialists at glass formulation houses provided qualitative inputs. Trade data from Japanese customs authorities and aluminum alloy spot price indices anchored supply-side validation. Bottom-up unit economics triangulated against top-down market sizing across material type and application segments.
Segmentation dimensions modeled include substrate material chemistry, manufacturing process value-add tier, rotational speed application class, and end-user procurement archetype. Volume projections incorporate drive manufacturer areal density roadmaps, METI thickness mandate compliance timelines, and hyperscale storage deployment patterns across the analysis window. CAGRs derive from installed base replacement cycles and technology transition elasticity in enterprise versus consumer segments.
Forecasts assume regulatory continuity in Japan's METI efficiency regimes and EPA hazardous substance monitoring; material policy shifts would require re-modeling substrate thickness specifications and aluminum casting compliance costs. Technology transition risk from HAMR deployment delays or solid-state storage substitution could revise glass substrate demand elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Blu-Ray Drive Market
Data Storage
Ireland Data Center Storage Market
Data Storage
External Storage Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
Object-Based Storage Market
Data Storage
Japan Data Center Storage Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Flash Memory Market
Data Storage
Enterprise Flash Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Digital Recording System Market
Data Storage
NAND Flash Market