
 Hyperinsulinemia Hypoglycaemia Treatment Market | 2026-2036
Hyperinsulinemia Hypoglycaemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperinsulinemia Hypoglycaemia Treatment Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is decoupling procurement preferences from pure efficacy metrics toward lifecycle environmental impact. Novo Nordisk A/S leverages its integrated recombinant protein manufacturing to reduce carbon intensity across glucagon analog supply chains. Eli Lilly and Company anchors North American distribution through captive fill-finish capacity near Indianapolis. Sanofi competes on biosimilar cost structures while sustaining European regulatory dossier density.
Hyperinsulinemia hypoglycaemia treatment encompasses pharmacological and non-pharmacological interventions that suppress pathological insulin secretion or restore euglycemia in patients with congenital hyperinsulinism, insulinoma, or post-bariatric hypoglycaemia, typically involving diazoxide, octreotide, or glucagon formulations administered via continuous subcutaneous infusion. The primary purpose is preventing neuroglycopenic brain injury while enabling normal growth and cognitive development in pediatric populations. Pharmacological therapy dominates current revenue pools due to chronic dosing requirements, while surgical intervention commands premium pricing in tertiary referral centers. Injectable solutions lead formulation demand because endocrinologists prioritize rapid glycemic rescue, though tablet-based glucose precursors are gaining traction among home users seeking reduced caregiver burden.
The FDA, EMA, and WHO prequalification programme collectively shape trial design, pediatric investigational plan requirements, and post-market surveillance obligations for hypoglycaemia rescue therapies. These frameworks elevate manufacturing standards, compel real-world evidence generation, and restrict market entry to sponsors with dedicated rare disease regulatory capabilities. Stakeholders must monitor evolving pediatric exclusivity incentives and decentralized clinical trial guidance to optimize development timelines and reimbursement positioning.
Market Dynamics
The FDA's Breakthrough Therapy designation pathway is compressing development timelines for novel insulin secretion inhibitors while pediatric endocrinology clinics accelerate continuous glucose monitoring integration.
Growth Catalysts
- CGM-integrated therapy protocols:Pediatric endocrinology clinics in Boston and Philadelphia are embedding continuous glucose monitoring into standard congenital hyperinsulinism care pathways.
- Pediatric exclusivity incentives:The FDA's rare pediatric disease priority review voucher program rewards sponsors developing diazoxide alternatives for neonatal populations.
- Centers of excellence clustering:Tertiary referral networks around Boston Children's Hospital and Children's Hospital of Philadelphia concentrate diagnostic expertise and surgical volume.
Market Restraints
- Recombinant peptide input costs:Glucagon analog manufacturing depends on mammalian cell culture systems with volatile serum and media pricing.
- Single-source fill-finish capacity:North American aseptic injectable production concentrates near Indianapolis, creating geographic supply vulnerability.
- EMA pediatric investigation plan delays:The European Medicines Agency's stringent paediatric investigation plan requirements extend regulatory timelines for novel octreotide formulations.
Strategic Opportunities
- Home-based glucose precursor tablets:Oral glucose rescue formulations address caregiver burden reduction in domestic settings outside hospital networks.
- EU Green Deal pharmaceutical procurement:Lifecycle environmental impact criteria favor sponsors with integrated recombinant protein manufacturing and carbon-reduced supply chains.
- Real-world evidence generation:Decentralized clinical trial guidance from the FDA enables post-market surveillance data collection from congenital hyperinsulinism registries.
Industry Challenges
- Pediatric endocrinology workforce scarcity:Fellowship-trained specialists capable of managing diazoxide-refractory cases remain concentrated in coastal academic medical centers.
- CGM-EMR integration complexity:Continuous glucose monitoring data streams require health system IT infrastructure upgrades to interface with electronic medical records.
- Biosimilar regulatory dossier density:European reference product comparability studies demand extensive analytical and clinical bridging data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperinsulinemia Hypoglycaemia Treatment Market |
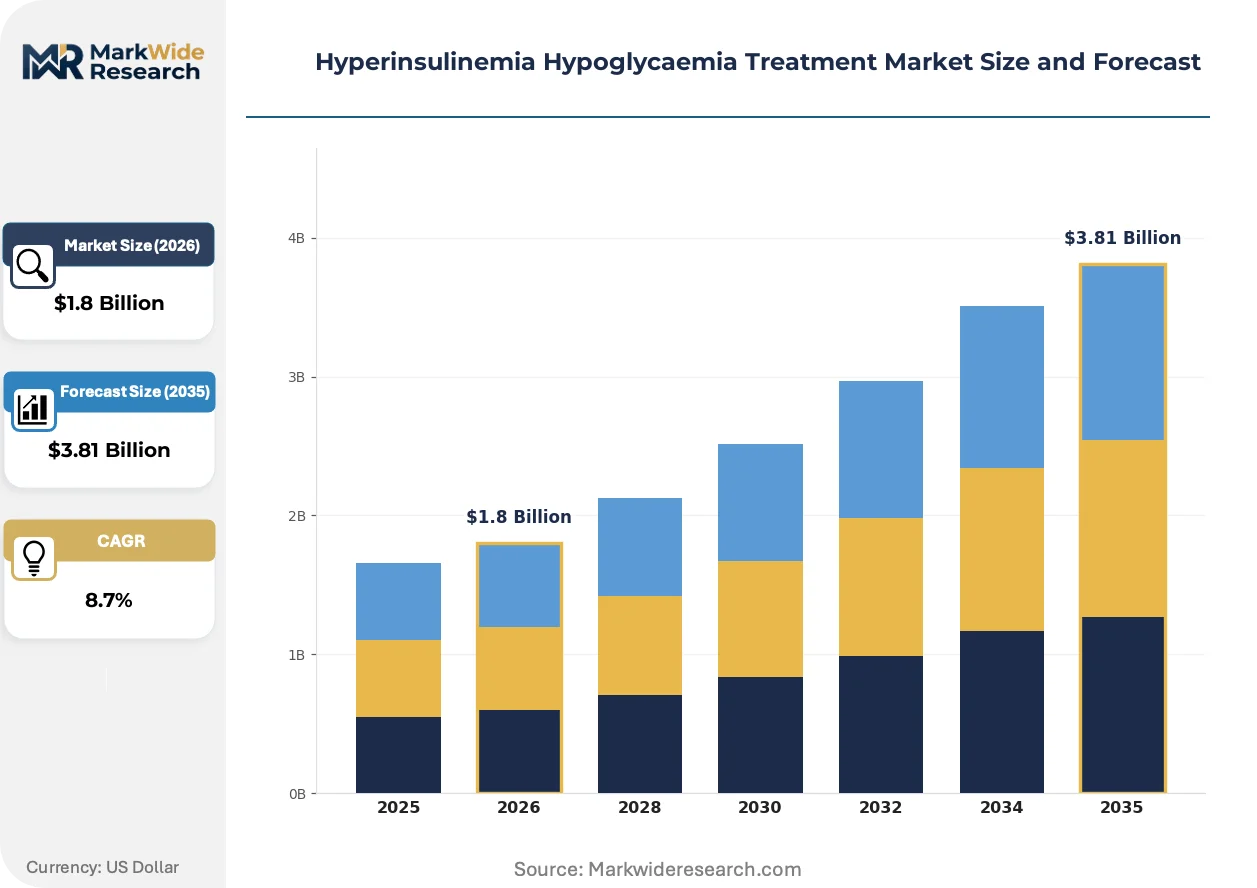
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Inhibitors, Glucose Precursors, Hormone Receptors, Dietary Supplements End User: Hospitals, Clinics, Research Institutes, Home Users Treatment Method: Pharmacological Therapy, Nutritional Management, Lifestyle Modification, Surgical Intervention Formulation: Tablets, Injectable Solutions, Infusion Solutions, Natural Extracts |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Novartis AG, AstraZeneca, Crinetics Pharmaceuticals, Zealand Pharma, Vertex Pharmaceuticals, Hanmi Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperinsulinemia Hypoglycaemia Treatment Market Shifts & Advancements
Device-drug convergence and regulatory pathway innovation are restructuring how congenital hyperinsulinism therapies reach pediatric patients.
Continuous subcutaneous glucagon infusion systems are electrifying rescue therapy delivery by automating hypoglycaemia prevention. Home caregivers and school nurses are adopting these devices faster than institutional procurement cycles anticipated. This automation is compressing emergency department utilization for neuroglycopenic events.
The EU Green Deal's pharmaceutical sustainability criteria is decoupling procurement preferences from pure efficacy metrics toward lifecycle environmental impact. Manufacturing sponsors with integrated recombinant protein production and reduced carbon intensity now capture tender advantages in European hospital systems. Biosimilar sponsors face heightened documentation burdens to demonstrate supply chain environmental credentials.
Buyer concentration among congenital hyperinsulinism centers of excellence is consolidating purchasing power around tertiary pediatric hospitals. Regional health systems are centralizing complex case referrals to Boston Children's Hospital and Children's Hospital of Philadelphia networks. This geographic demand rotation is reshaping distribution economics for chronic diazoxide and octreotide supplies.
Hyperinsulinemia Hypoglycaemia Treatment Market Segmentation
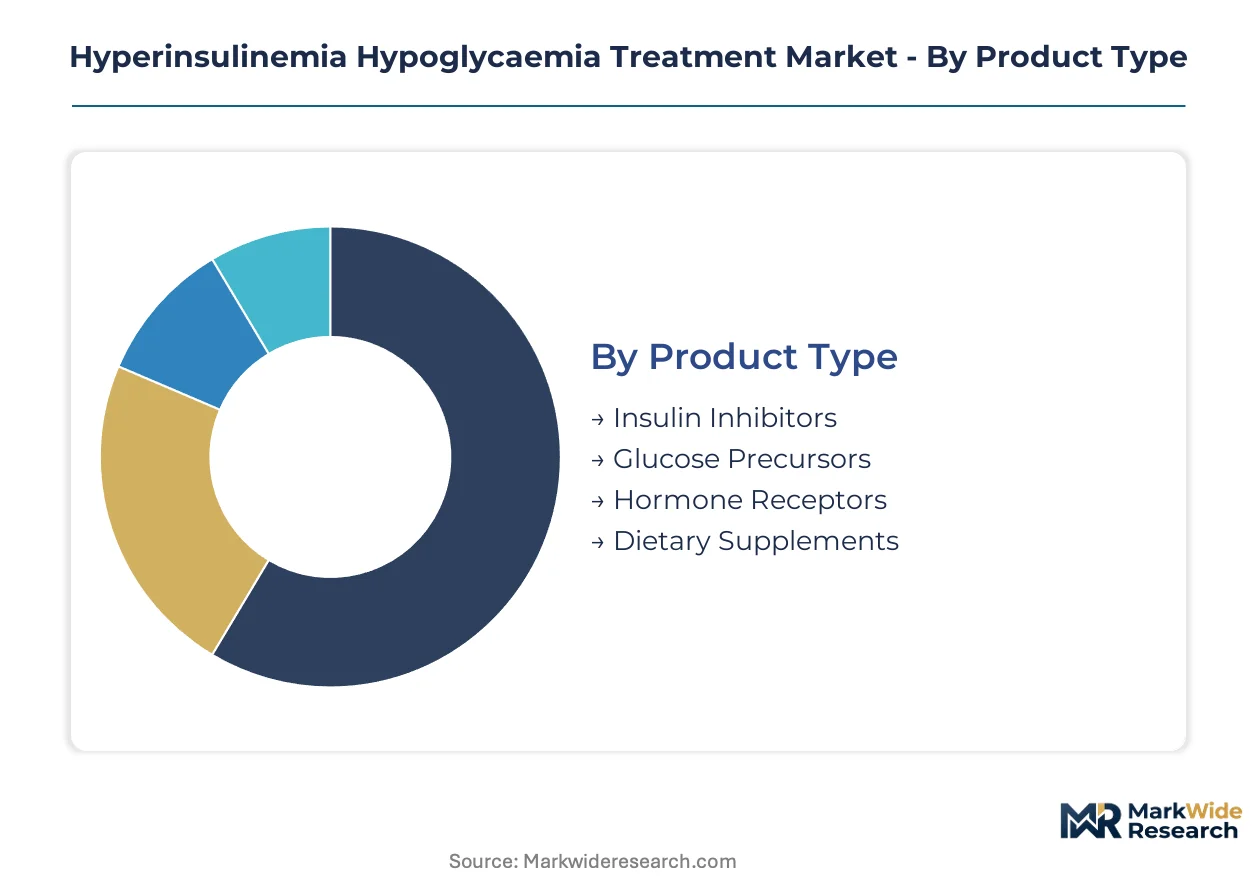
Hyperinsulinemia hypoglycaemia treatment markets fragment across therapeutic modality, care setting, and delivery format. Each segment carries distinct regulatory certification burdens and reimbursement pathways that shape commercial viability.
Product Type:
Certification requirements diverge sharply across this category. Insulin inhibitors and hormone receptors demand FDA Breakthrough Therapy or EMA orphan drug designation pathways, while glucose precursors and dietary supplements navigate food-drug interface regulations with lighter clinical trial obligations.
- Insulin Inhibitors:Small-molecule and biologic agents that suppress pathological insulin secretion through ATP-sensitive potassium channel modulation or glucagon-like peptide antagonism. Demand concentrates in tertiary pediatric centers managing diazoxide-refractory congenital hyperinsulinism, where FDA rare pediatric disease priority review vouchers accelerate sponsor timelines.
- Glucose Precursors:Rapidly absorbed carbohydrate formulations designed for acute hypoglycaemia rescue, including dextrose tablets and gel preparations. Home users in suburban Philadelphia and Boston metropolitan areas are driving procurement volume as caregivers seek alternatives to emergency department visits.
- Hormone Receptors:Somatostatin analogs and glucagon receptor agonists requiring refrigerated cold-chain distribution.
- Dietary Supplements:Cornstarch-based sustained-release carbohydrate preparations and micronutrient formulations with lighter regulatory dossier requirements.
Insulin inhibitors sit at the top of the volume ranking, with glucose precursors climbing the fastest.
End User:
Procurement authority and reimbursement rates vary dramatically by care setting, with hospitals commanding premium pricing through 340B drug pricing programs while home users face higher out-of-pocket exposure.
- Hospitals:Tertiary academic medical centers with congenital hyperinsulinism centers of excellence. These institutions aggregate surgical volume and complex case referrals, leveraging group purchasing organizations to negotiate formulary placement for chronic octreotide and diazoxide supplies.
- Clinics:Pediatric endocrinology practices embedded in regional health systems. Philadelphia-area clinic networks are embedding continuous glucose monitoring into standard care pathways faster than institutional procurement anticipated.
- Research Institutes:Academic centers conducting natural history studies and interventional trials under FDA pediatric investigational plan frameworks.
- Home Users:Family caregivers managing nocturnal hypoglycaemia prevention and school-day glucose rescue protocols.
Hospitals capture the largest revenue share, though home users are expanding most quickly as device-drug convergence enables decentralized care.
Treatment Method:
Margin structures invert across this category, with surgical intervention commanding single-case premium pricing while chronic pharmacological therapy generates recurring revenue pools.
- Pharmacological Therapy:Chronic dosing regimens with diazoxide, octreotide, or glucagon analogs. Boston Children's Hospital and Children's Hospital of Philadelphia anchor North American prescribing volume for novel insulin secretion inhibitors.
- Nutritional Management:Structured carbohydrate intake protocols and continuous feeding schedules. Dietitian-directed protocols concentrate demand in centers with dedicated pediatric endocrinology fellowship programs.
- Lifestyle Modification:Exercise regulation and meal timing interventions for post-bariatric hypoglycaemia populations.
- Surgical Intervention:Partial pancreatectomy and focal lesion enucleation performed at centers of excellence with intraoperative insulin monitoring capabilities.
Pharmacological therapy dominates current revenue pools, with surgical intervention showing the steepest expansion trajectory as referral networks centralize complex cases.
Formulation:
Supply concentration and fill-finish capacity constraints shape competitive dynamics, with aseptic injectable production clustering near Indianapolis while tablet manufacturing disperses across broader geographic footprints.
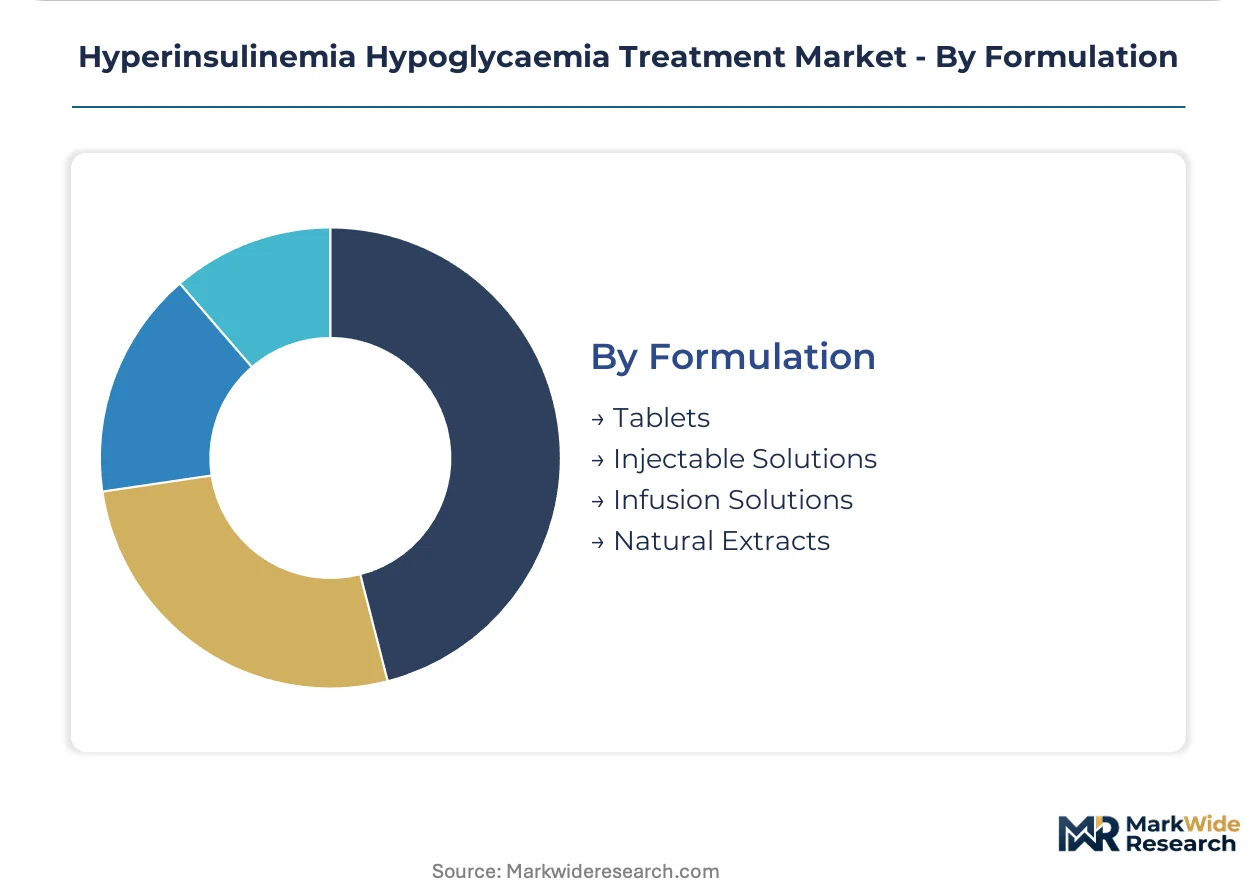
- Injectable Solutions:Glucagon rescue kits and octreotide vials requiring parenteral administration training. Endocrinologists prioritize rapid glycemic rescue capability, sustaining demand despite caregiver burden concerns.
- Tablets:Oral diazoxide formulations and glucose precursor tablets. Home users seeking reduced caregiver burden are accelerating adoption outside hospital networks.
- Infusion Solutions:Continuous subcutaneous glucagon delivery systems with automated hypoglycaemia prevention algorithms.
- Natural Extracts:Botanical preparations with limited clinical evidence bases and minimal regulatory scrutiny.
Injectable solutions maintain volume leadership, though infusion solutions are gaining share fastest as device-drug convergence automates rescue therapy delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric endocrinology fellowship programs concentrate in coastal academic medical centers across five countries, anchoring diagnostic expertise and therapeutic innovation for congenital hyperinsulinism management.
United States
Boston Children's Hospital and Children's Hospital of Philadelphia anchor North American demand for diazoxide-refractory case management. The FDA's rare pediatric disease priority review voucher program accelerates sponsor timelines for novel insulin secretion inhibitors. Indianapolis-based fill-finish capacity concentrates aseptic injectable production for glucagon analog supply chains.
Germany
University hospital networks in Munich and Heidelberg aggregate surgical volume for partial pancreatectomy procedures. The EMA's paediatric investigation plan requirements extend regulatory timelines for octreotide formulations while elevating manufacturing standards. Baden-Württemberg hosts specialized recombinant peptide production facilities serving European cold-chain distribution.
United Kingdom
London's Great Ormond Street Hospital centralizes complex congenital hyperinsulinism referrals from across the National Health Service. The MHRA's pediatric licensing pathway aligns with EMA frameworks while maintaining sovereign approval authority. Oxford and Cambridge academic medical centers generate real-world evidence through national disease registries.
Japan
PMDA orphan drug designation accelerates market access for somatostatin analog therapies in Tokyo and Osaka pediatric centers. The Ministry of Health, Labour and Welfare's premium pricing system rewards innovation in rare disease therapeutics. Nagoya hosts specialized diagnostic imaging capabilities for focal lesion identification.
Switzerland
Swissmedic's streamlined pediatric authorization process attracts sponsor headquarters to Basel and Zurich. The country's integrated recombinant protein manufacturing infrastructure reduces carbon intensity across glucagon supply chains. Geneva's academic hospitals participate in multinational congenital hyperinsulinism natural history studies.
Hyperinsulinemia Hypoglycaemia Treatment Market Competitive Landscape
Capital-heavy producers with integrated recombinant protein manufacturing compete with asset-light developers licensing formulation technology to contract manufacturers. The market structures around three tiers: multinational pharmaceutical conglomerates with rare disease divisions, mid-cap biotech specialists pursuing FDA Breakthrough Therapy designation, and regional generics manufacturers supplying diazoxide tablets. Consolidation concentrates purchasing power among congenital hyperinsulinism centers of excellence. Competitive moves center on captive fill-finish capacity expansion and strategic partnerships for continuous glucose monitoring integration.
Within the multinational tier, Novo Nordisk A/S and Eli Lilly and Company exemplify divergent supply chain strategies—Danish integrated manufacturing versus North American distribution anchoring. Sanofi occupies a position between originator and biosimilar economics. Among development-stage specialists, Crinetics Pharmaceuticals and Zealand Pharma represent the asset-light archetype pursuing novel hormone receptor modulation. Vertex Pharmaceuticals anchors the genomic medicine vector with potential curative approaches.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Novartis AG |
| AstraZeneca |
| Crinetics Pharmaceuticals |
| Zealand Pharma |
| Vertex Pharmaceuticals |
| Hanmi Pharmaceutical |
| Others |
Supply & Pricing Matrix
EU Green Deal pharmaceutical procurement preferences are forcing recombinant peptide manufacturers to decarbonize production or sacrifice European tender eligibility, compressing margins for sponsors lacking integrated biologics infrastructure. This demand-side environmental mandate reshapes supplier qualification criteria and elevates cost structures for glucagon analog producers dependent on carbon-intensive mammalian cell culture systems.
Pricing Analysis
Bundled device-drug combinations command premium positioning against unbundled vial-and-syringe alternatives in congenital hyperinsulinism centers of excellence. Three-tier pricing structure across premium, standard, and economy levels separates automated infusion systems from manual injectable kits from generic diazoxide tablets. Price differentiation rests on FDA Breakthrough Therapy designation status and cold-chain reliability certification. Pricing pressure stems from biosimilar octreotide entrants targeting European hospital procurement tenders. Home caregivers exhibit highest price sensitivity, while tertiary academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Refrigerated freight costs for cold-chain biologics concentrate distribution economics around Indianapolis fill-finish hubs and Baden-Württemberg recombinant peptide facilities. Active pharmaceutical ingredient production draws from Denmark, Switzerland, and the United States. Key inputs include mammalian cell culture media, pharmaceutical-grade serum, and aseptic vial components. Single-source fill-finish vulnerability near Indianapolis creates geographic supply risk for North American glucagon rescue kit availability. Distribution runs through specialized pharmaceutical wholesalers with temperature-controlled logistics capabilities serving pediatric endocrinology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA rare pediatric disease priority review voucher economics and EMA paediatric investigation plan timeline penalties, with sponsors capturing development cost advantages by anchoring clinical trials in the United States while maintaining European regulatory optionality through Swissmedic or MHRA pathways.
For Market Incumbents: Lock in captive fill-finish capacity expansion near Indianapolis to defend against single-source supply vulnerability threatening glucagon analog availability. Secure continuous glucose monitoring integration partnerships before device-drug convergence standardizes around dominant platform ecosystems. Threat of mid-cap biotech specialists securing FDA Breakthrough Therapy designation for novel insulin secretion inhibitors demands preemptive pipeline positioning in diazoxide-refractory indications. For New Entrants and Emerging Players: Launch via direct-to-home distribution models targeting suburban Philadelphia and Boston metropolitan area caregivers seeking glucose precursor tablet alternatives to emergency department utilization. White-space concentration exists in oral diazoxide formulations with reduced caregiver burden profiles and in automated hypoglycaemia prevention algorithms for school-day settings. Most penetrable segment comprises home users outside established congenital hyperinsulinism center of excellence referral networks. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light developers possessing FDA Breakthrough Therapy designation for novel hormone receptor modulation and licensing partnerships with established fill-finish operators. Long-term viability over the next decade hinges on successful navigation of pediatric exclusivity incentive structures and CGM-EMR integration standardization. Signal to watch is decentralized clinical trial guidance adoption rates enabling real-world evidence generation from congenital hyperinsulinism registries.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation Pursuit | Compresses development timelines for novel insulin secretion inhibitors targeting diazoxide-refractory pediatric populations. |
| Continuous Glucose Monitoring Integration Partnership | Positions sponsors for device-drug convergence standardizing automated hypoglycaemia prevention protocols. |
| Integrated Recombinant Protein Manufacturing Scale-Up | Captures EU Green Deal procurement advantages through carbon-reduced glucagon analog supply chains. |
| Home-Based Glucose Precursor Tablet Launch | Addresses caregiver burden reduction demand in suburban markets outside tertiary hospital networks. |
| Congenital Hyperinsulinism Registry Data Collaboration | Enables real-world evidence generation supporting post-market surveillance and reimbursement positioning. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, Japan, and Switzerland, with primary inputs from each market's congenital hyperinsulinism treatment ecosystem. Research combined structured interviews with pediatric endocrinologists, regulatory affairs specialists, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation anchored market sizing across therapeutic modality and care setting segments.
Rate-of-change decomposition separated volume expansion from price evolution across the projection horizon. Analytical framework modeled treatment method, formulation type, end-user setting, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from indication-specific prevalence trajectories, therapy penetration assumptions, and pricing elasticity parameters informed by formulary placement dynamics. Forecast inputs incorporated FDA rare pediatric disease priority review voucher award patterns and EMA paediatric investigation plan completion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pediatric endocrinology workforce scarcity intensification or CGM-EMR integration standardization delays. Forecasts reflect documented assumptions regarding referral network centralization rates and biosimilar octreotide European tender penetration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Thailand Diabetes Care Devices Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market