
 Asia-Pacific Biologics Market | 2026-2036
Asia-Pacific Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biologics Market Outlook
GMP-plus and biosimilar-grade specifications is reorganizing procurement priorities across the Asia-Pacific biologics landscape. Samsung Biologics anchors massive mammalian cell culture capacity in South Korea, serving global innovators seeking cost-efficient manufacturing alternatives. WuXi Biologics extends integrated discovery-to-commercial platforms across China, leveraging geographic proximity to domestic biotech startups. Roche Holding AG competes through specialized oncology biologics expertise, sustaining premium positioning in markets with evolving reimbursement frameworks.
Asia-Pacific biologics comprise therapeutic proteins, monoclonal antibodies, vaccines, and cellular therapies manufactured through recombinant DNA or cell culture processes, typically requiring cold-chain distribution and parenteral administration for targeted immune modulation or metabolic correction. Monoclonal antibodies command substantial margin pools given complex CMC requirements and patent-protected indications, while recombinant proteins represent a mature volume base with intensifying biosimilar competition. Contract manufacturing organizations constitute the fastest-growing end-user channel as virtual biotech firms outsource integrated development and commercial production.
China's NMPA and India's CDSCO enforce divergent biosimilar approval pathways, creating compliance complexity for sponsors pursuing multi-country launches across the region. Japan's PMDA maintains stringent comparability standards that limit biosimilar substitution, preserving originator revenue streams while constraining patient access expansion. South Korea's MFDS accelerates review timelines for locally manufactured biologics, reshaping regional investment flows. Stakeholders must monitor evolving data exclusivity terms and local content requirements as governments balance innovation incentives against healthcare affordability pressures.
Market Dynamics
Contract manufacturing organizations are consolidating biologics production across the Asia-Pacific region, with China's Yangtze River Delta and South Korea's Incheon Free Economic Zone anchoring mammalian cell culture capacity for global innovators seeking cost-efficient alternatives to Western manufacturing.
Growth Catalysts
- India's PLI scheme for biopharmaceuticals:The production-linked incentive framework subsidizes capital expenditure for greenfield biologics facilities, drawing contract manufacturers to Hyderabad and Bengaluru.
- Single-use bioreactor adoption:Disposable manufacturing systems reduce cross-contamination risk and facility turnaround time, accelerating multi-product campaign flexibility for CDMOs serving virtual biotech clients.
- Oncology biologics demand:China's National Reimbursement Drug List expansion for PD-1 inhibitors and CAR-T therapies is pulling volume through domestic manufacturing networks.
Market Restraints
- Plasma supply concentration:Blood-derived protein feedstocks depend on US and European collection networks, exposing Asia-Pacific fractionators to input cost volatility and geopolitical supply disruption.
- Biosimilar substitution limits:Japan's PMDA maintains stringent interchangeability standards that constrain pharmacist-level substitution, preserving originator pricing power while limiting patient access expansion.
- Cell line development bottlenecks:Proprietary CHO platform access remains concentrated among legacy biologics developers, forcing emerging sponsors into lengthy license negotiations or risky platform switches.
Strategic Opportunities
- Southeast Asia greenfield expansion:Singapore's Biopolis and Thailand's Eastern Economic Corridor offer tax-advantaged zones for cold-chain biologics manufacturing serving ASEAN markets with limited local production.
- Continuous processing convergence:Integration of perfusion bioreactors with continuous chromatography is compressing cost-of-goods for biosimilar manufacturers competing on price in China's tender-driven hospital procurement.
- MFDS accelerated review pathway:South Korea's streamlined approval for locally manufactured biologics is redirecting regional investment toward Songdo and Osong bioclusters.
Industry Challenges
- Process analytical technology implementation:Real-time release testing requires validated spectroscopic methods and statistical process control expertise scarce among mid-scale CDMOs.
- Multi-country dossier divergence:China's NMPA, India's CDSCO, and South Korea's MFDS enforce non-harmonized stability and comparability requirements, forcing sponsors to maintain parallel development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biologics Market |
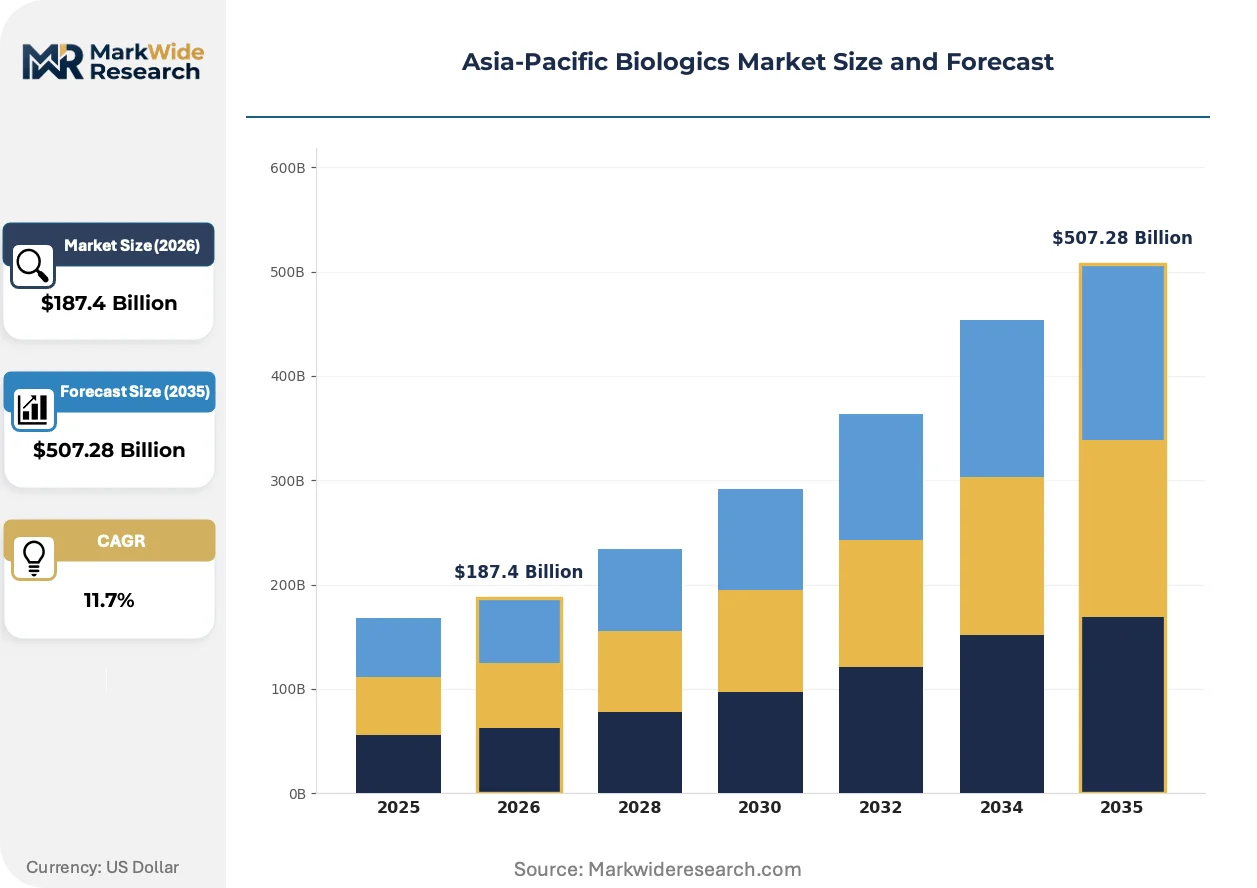
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Blood Products End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Application: Oncology, Infectious Diseases, Autoimmune Disorders, Rare Diseases Technology: Recombinant DNA Technology, Monoclonal Antibody Technology, Cell Culture Technology, Synthetic Biology |
| Companies Covered | Roche Holding AG, Pfizer Inc., Amgen Inc., Samsung Biologics, WuXi Biologics, AbbVie Inc., Johnson & Johnson, Catalent Inc., Novartis AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biologics Market Strategic Shifts
Bioprocessing technology and regulatory pathway evolution are compressing development timelines and reshaping competitive positioning across Asia-Pacific biologics manufacturing. Three forces dominate the current transformation.
Single-use downstream processing systems are supplanting stainless-steel chromatography skids in multi-product facilities throughout China and India. CDMOs serving virtual biotech sponsors are adopting disposable membrane chromatography and single-use tangential flow filtration to eliminate CIP/SIP validation burdens and accelerate campaign changeovers. This shift is compressing facility qualification timelines from eighteen months to under six months for standard monoclonal antibody platforms.
China's NMPA biosimilar guidance revision is tightening immunogenicity and clinical endpoint requirements for insulin and growth hormone products. The regulatory friction is diverting sponsor investment toward more complex monoclonal antibody biosimilars where clinical equivalence pathways remain clearer. Domestic biotech firms are responding by front-loading CMC investment and engaging NMPA pre-submission meetings earlier in development cycles.
Virtual biotech procurement patterns are fragmenting across specialized CDMOs rather than consolidating with full-service providers. Early-stage sponsors in Shanghai and Hangzhou are unbundling cell line development, drug substance manufacturing, and fill-finish across separate vendors to optimize technical fit and pricing leverage. This behavior is most visible in China's Yangtze River Delta cluster, where geographic proximity enables just-in-time logistics coordination between disaggregated supply chain nodes.
Asia-Pacific Biologics Market Segmentation
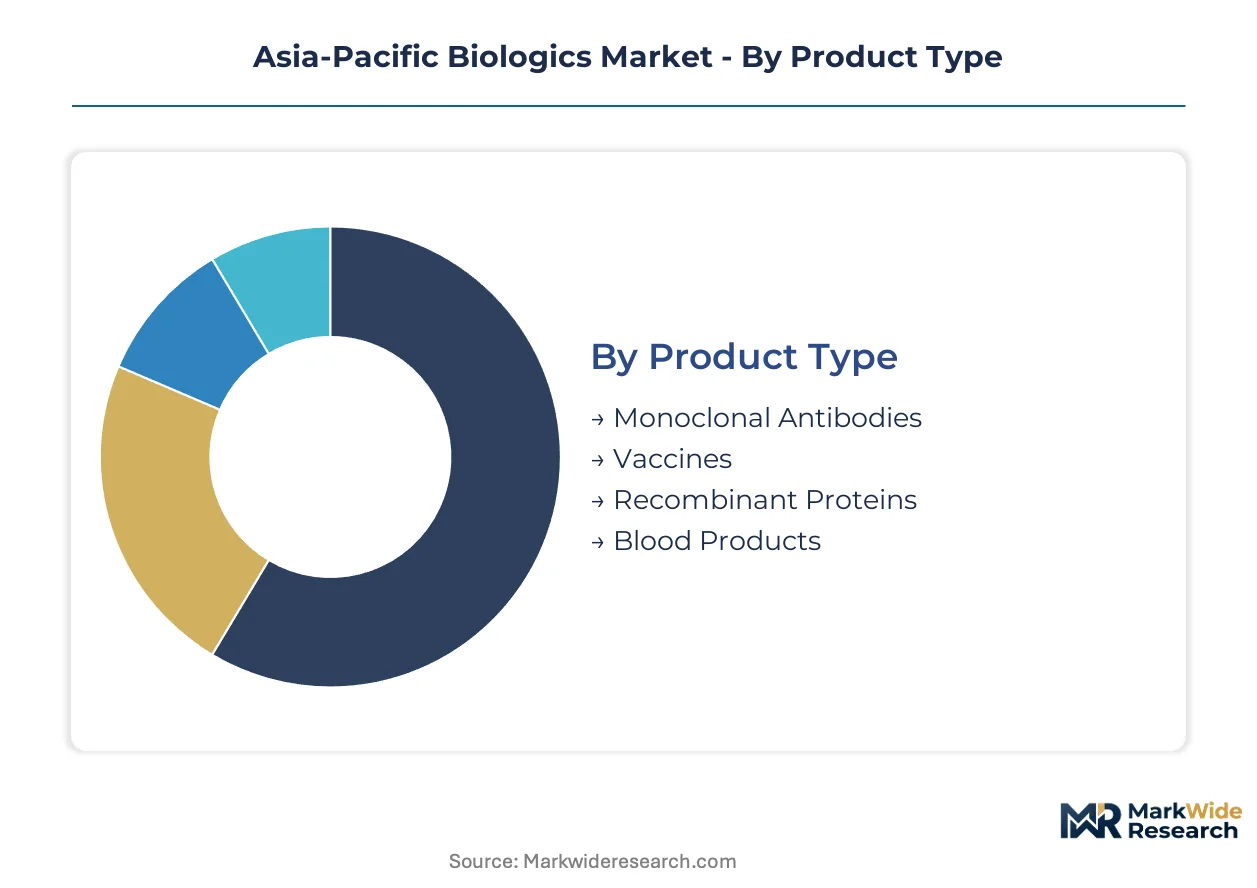
Margin distribution across Asia-Pacific biologics segments reflects divergent manufacturing complexity, regulatory burden, and reimbursement intensity. Sponsors and contract manufacturers allocate capital based on where CMC investment yields sustainable pricing power versus commoditization risk.
Product Type:
Monoclonal antibodies capture the deepest margin pools given cell line development complexity and patent-protected oncology positioning, while recombinant proteins face accelerating biosimilar compression.
- Monoclonal Antibodies:These therapeutic proteins bind specific antigens with high specificity, requiring sophisticated CHO cell line engineering and extensive immunogenicity profiling. China's Yangtze River Delta biotech cluster concentrates demand for PD-1 and HER2-targeted formats as domestic sponsors expand oncology pipelines. NMPA's tightened biosimilar guidance for complex antibodies preserves originator pricing power while extending development timelines for followers.
- Vaccines:Prophylactic and therapeutic immunization products span viral vector, mRNA, and recombinant subunit platforms with divergent cold-chain requirements. India's CDSCO and China's NMPA are expanding accelerated approval pathways for pandemic preparedness vaccines, pulling investment toward Hyderabad and Shenzhen manufacturing hubs. Government procurement tenders dominate volume allocation, compressing margins relative to specialty biologics.
- Recombinant Proteins:Insulin, growth hormone, and blood factors manufactured through microbial or mammalian fermentation face intense biosimilar competition across Asia-Pacific hospital procurement.
- Blood Products:Plasma-derived immunoglobulins and albumin depend on US and European plasma collection networks, exposing fractionators to feedstock cost volatility.
The dominant share belongs to monoclonal antibodies, while vaccines are closing the gap fastest through pandemic infrastructure investment and expanded national immunization programs.
End User:
Customer type determines procurement scale, technical specification intensity, and outsourcing depth across the value chain.
- Pharmaceutical Companies:Large-cap innovators with in-house mammalian cell culture capacity anchor demand for high-volume drug substance manufacturing. Japanese and Korean originators maintain captive production for premium oncology biologics, while expanding partnerships with Chinese CDMOs for cost-sensitive markets. These sponsors drive specification standards for GMP-plus and biosimilar-grade supply.
- Contract Manufacturing Organizations:CDMOs constitute the fastest-expanding procurement channel as virtual biotech firms outsource integrated development and commercial production. WuXi Biologics and Samsung Biologics anchor regional capacity, serving global innovators seeking alternatives to Western manufacturing. Single-use bioreactor adoption accelerates campaign flexibility for multi-product facilities.
- Biotechnology Firms:Emerging sponsors in Shanghai and Hangzhou unbundle cell line development, drug substance, and fill-finish across specialized vendors to optimize technical fit.
- Research Institutions:Academic and government laboratories procure small-scale biologics for preclinical and early-phase clinical investigation.
Pharmaceutical companies retain the largest procurement volume, though contract manufacturing organizations are expanding share fastest through virtual biotech outsourcing trends.
Application:
Therapeutic area selection dictates clinical trial cost, regulatory pathway complexity, and reimbursement negotiation intensity across Asia-Pacific markets.
- Oncology:Immuno-oncology biologics including checkpoint inhibitors and CAR-T cell therapies command premium pricing and concentrated manufacturing investment. China's National Reimbursement Drug List expansion for PD-1 inhibitors is pulling volume through domestic manufacturing networks. PMDA's stringent comparability standards in Japan preserve originator revenue streams for complex antibody-drug conjugates.
- Autoimmune Disorders:TNF-alpha inhibitors and IL-targeting biologics face biosimilar substitution pressure in price-sensitive markets while maintaining volume leadership. India's CDSCO and China's NMPA have approved multiple adalimumab and etanercept biosimilars, intensifying hospital tender competition. Originators defend position through subcutaneous formulation differentiation and patient support programs.
- Infectious Diseases:Monoclonal antibodies for RSV, HIV, and emerging pathogens represent a growing development focus following pandemic infrastructure buildout.
- Rare Diseases:Enzyme replacement therapies and orphan biologics benefit from expedited regulatory pathways and premium pricing, though patient pool constraints limit absolute revenue scale.
Oncology holds the dominant application share, while autoimmune disorder treatments face the steepest pricing compression from biosimilar competition.
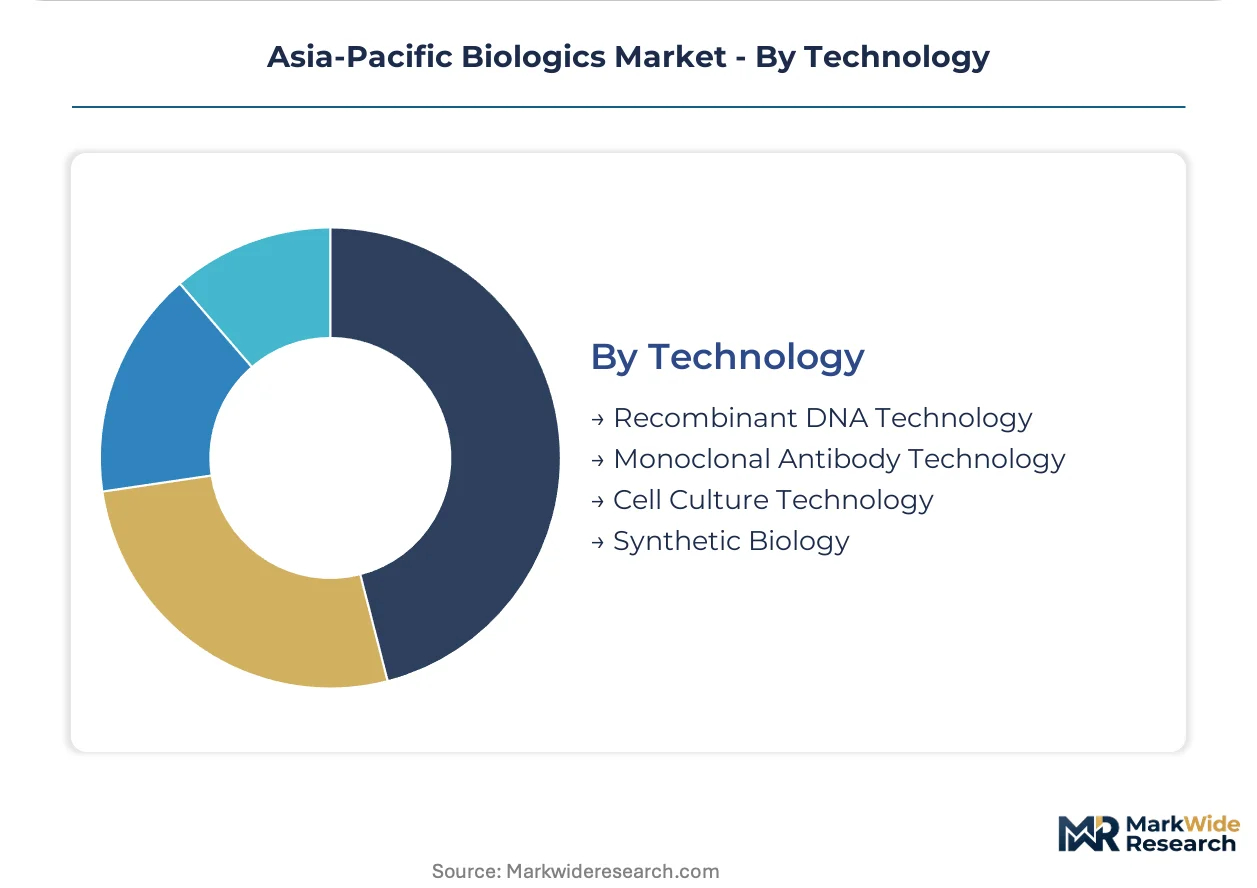
Technology:
Platform selection determines development timeline, capital intensity, and intellectual property positioning for Asia-Pacific biologics manufacturers.
- Recombinant DNA Technology:The foundational platform for therapeutic protein production enables scalable microbial and mammalian expression systems with established regulatory precedents. Chinese and Indian manufacturers leverage decades of insulin and growth hormone production experience to expand into biosimilar monoclonal antibodies. Platform maturity reduces technical risk but intensifies cost competition.
- Cell Culture Technology:Mammalian cell culture anchors complex biologics manufacturing, with perfusion and continuous processing innovations compressing cost-of-goods. Samsung Biologics and WuXi Biologics have invested heavily in single-use and stainless-steel capacity across South Korea and China. Proprietary CHO platform access remains concentrated, forcing emerging sponsors into license negotiations.
- Monoclonal Antibody Technology:Humanization and display library advances enable rapid candidate generation for oncology and autoimmune targets.
- Synthetic Biology:Engineered cell lines and novel expression systems promise improved titers and glycosylation control for next-generation biologics.
Cell culture technology commands the dominant technology share, while synthetic biology platforms are gaining investment traction for next-generation manufacturing efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exhibits the highest demand elasticity as hospital procurement tenders drive aggressive biosimilar pricing, while Japan maintains the most price-inelastic patient access through stringent interchangeability standards that preserve originator premiums. South Korea and India occupy intermediate positions where regulatory acceleration and production incentives reshape competitive dynamics.
China
Domestic PD-1 inhibitor manufacturers and CAR-T cell therapy developers anchor demand growth as the National Reimbursement Drug List expands oncology coverage. NMPA's tightened biosimilar guidance for insulin and growth hormone products redirects investment toward complex monoclonal antibodies. The Yangtze River Delta biotech cluster concentrates contract manufacturing capacity serving both domestic sponsors and export markets.
Japan
Originator biologics command sustained premium pricing for oncology and autoimmune indications where PMDA comparability standards limit pharmacist-level substitution. The regulator's stringent immunogenicity requirements preserve revenue streams for complex antibody-drug conjugates while constraining patient access expansion. Tokyo-Osaka corridor manufacturing maintains captive production for premium therapeutic categories.
India
Adalimumab and etanercept biosimilar volumes surge through CDSCO accelerated approval pathways as hospital tenders intensify price competition. The PLI scheme for biopharmaceuticals subsidizes greenfield facility investment across Hyderabad and Bengaluru. These southern bioclusters anchor mammalian cell culture capacity expansion for export-oriented contract manufacturers.
South Korea
MFDS streamlined review timelines for locally manufactured biologics redirect regional investment toward Songdo and Osong bioclusters. Samsung Biologics anchors massive mammalian cell culture capacity serving global innovators seeking cost-efficient alternatives. Incheon Free Economic Zone tax advantages reinforce the country's position as a biologics export hub.
Singapore
ASEAN market access priorities and limited regional cold-chain biologics production attract greenfield manufacturing investment. Biopolis tax-advantaged zones host multi-national sponsors establishing distribution hubs for Southeast Asian markets. The city-state's regulatory alignment with international standards reduces multi-country dossier complexity for regional launches.
Asia-Pacific Biologics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific biologics landscape. The market structure concentrates around integrated contract manufacturers with captive platform expertise and specialized innovators with protected oncology indications. Three archetypes dominate: full-service CDMOs with discovery-to-commercial platforms, originator biopharmaceuticals with therapeutic specialization, and emerging biosimilar developers with cost-optimized manufacturing. Competitive moves center on capacity expansion in tax-advantaged zones and strategic partnerships for cell line platform access.
Among Asia-Pacific-based contract manufacturers, Samsung Biologics and WuXi Biologics exemplify the full-service CDMO archetype with integrated platform offerings. Roche Holding AG represents the originator specialist position sustained by premium oncology positioning. These three anchors occupy distinct competitive spaces—scale-driven manufacturing efficiency, geographic proximity to biotech clusters, and therapeutic category depth—rather than direct confrontation across all segments.
| Leading Market Players |
|---|
| Roche Holding AG |
| Pfizer Inc. |
| Amgen Inc. |
| Samsung Biologics |
| WuXi Biologics |
| AbbVie Inc. |
| Johnson & Johnson |
| Catalent Inc. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Yangtze River Delta CDMOs and global biopharma innovators lock in mammalian cell culture capacity and provide cost visibility across multi-year development cycles. These arrangements anchor supply security for complex monoclonal antibodies while insulating sponsors from spot-market volatility in plasma-derived feedstocks.
Pricing Analysis
NMPA's tightened biosimilar guidance for insulin and growth hormone products dictates the pricing tier structure across China's hospital procurement networks. Three-tier pricing structure across originator, biosimilar-grade, and GMP-plus certification levels separates premium oncology biologics from commoditized recombinant proteins. Price differentiation hinges on immunogenicity validation depth and cold-chain integrity certification. Margins are tightening for insulin biosimilars as tender aggregation compresses net realized prices. Virtual biotech sponsors exhibit highest price sensitivity, while Japanese originators defending complex antibody-drug conjugates show least elasticity.
Supply Chain Analysis
Port congestion along the Shanghai-Ningbo corridor and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for chromatography resins and single-use bioreactor components. Manufacturing concentration centers on China, South Korea, and India, with the Yangtze River Delta and Incheon Free Economic Zone anchoring mammalian cell culture capacity. Raw material dependencies include US and European plasma collection networks, proprietary CHO cell line platforms, and chromatography media from Western suppliers. Single-source vulnerability in plasma-derived immunoglobulin feedstock exposes fractionators to geopolitical disruption. Distribution runs through cold-chain logistics partnerships serving hospital pharmacy and specialty distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: NMPA, PMDA, and MFDS approval pathways create years-long switching costs for sponsors locked into validated manufacturing relationships.
For Market Incumbents: Fortify cell line platform control through exclusive licensing agreements with CHO expression system providers, blocking emerging sponsors from rapid biosimilar entry. Expand stainless-steel and single-use capacity in Songdo and Hyderabad bioclusters to capture virtual biotech outsourcing volume. Defend against CDMO margin compression by embedding process analytical technology capabilities that mid-scale competitors cannot replicate. For New Entrants and Emerging Players: Service-layer gaps in continuous processing expertise and real-time release testing capability offer white-space entry points where legacy CDMOs under-invest. Southeast Asian markets, particularly Thailand's Eastern Economic Corridor, present the most penetrable geography with limited local biologics manufacturing and growing ASEAN hospital procurement. Pursue partnerships with Singapore-based distribution hubs to establish cold-chain credibility without greenfield facility investment. For Investors and Strategic Acquirers: Specialized CDMOs with validated perfusion bioreactor platforms and existing MFDS or NMPA inspection history represent the priority acquisition archetype. Long-term viability hinges on regulatory relationship depth and platform technology lock-in rather than pure scale. Watch for NMPA guidance revisions on complex antibody biosimilars as the signal for competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands mammalian cell culture capacity in Songdo to serve global innovator demand. |
| Regulatory Approval Pathway | MFDS accelerated review for locally manufactured biologics redirects regional investment flows. |
| Licensing Agreement | Proprietary CHO platform access blocks emerging sponsors from rapid biosimilar entry. |
| Pipeline Diversification | Front-loaded CMC investment in complex monoclonal antibodies evades NMPA insulin guidance friction. |
| Joint Venture | Hyderabad-Bengaluru partnerships leverage India's PLI subsidies for export-oriented biologics capacity. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions for capacity expansion and pricing trajectory. Primary interviews combined with secondary validation against NMPA filings, MFDS submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up facility capacity modeling and top-down reimbursement spend analysis triangulated volume estimates.
Segmentation dimensions modeled span product type, end user, therapeutic application, and technology platform across the analysis window. CAGRs derived from capacity utilization curves, reimbursement list expansion schedules, and biosimilar approval velocity. Forecast inputs include CDMO campaign booking patterns and plasma collection network expansion plans.
Forecasts assume regulatory continuity in NMPA, PMDA, and MFDS approval frameworks; material policy shifts around data exclusivity or local content requirements would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market