
 Air and Naval Countermeasures Market | 2026-2036
Air and Naval Countermeasures Market Size, Share, and Industry Trends Forecast 2026-2036
Air and Naval Countermeasures Market Outlook
Naval procurement priorities are decoupling from legacy air-centric spending patterns as contested littoral zones demand layered survivability across both domains. L3Harris Technologies leverages its cross-domain electronic warfare portfolio to anchor integrated countermeasure architectures for surface combatants. Raytheon Technologies Corporation sustains deep investment in next-generation jamming systems that compete for next-generation fighter and destroyer programs. Thales Group differentiates through European-centric networked decoy deployments that dominate Franco-British naval modernization pathways.
Air and naval countermeasures encompass expendable and reusable systems engineered to detect, deceive, or neutralize hostile targeting sensors through electromagnetic signature manipulation, with chaff dispensers typically deploying aluminum-coated glass fiber clouds at radar wavelengths between 2 and 40 GHz to create false target returns. The platform dimension reveals unmanned aerial vehicles as the fastest-expanding installation base as attritable systems absorb risk previously reserved for manned strike packages, while naval vessels retain the largest absolute spending pool due to per-hull integration complexity and certification cycles. Deployment mode trends favor networked architectures where decoys, jammers, and electronic warfare systems share sensor fusion backbones rather than standalone siloed operation.
The U.S. Department of Defense's Joint Capabilities Integration and Development System shapes platform requirements through mandated interoperability standards, while NATO's Air Command and Control System program drives European convergence in networked countermeasure protocols. France's Direction Générale de l'Armement and the U.K. Defence Equipment and Support impose national security certification gates that filter market access for non-allied suppliers. Stakeholders must monitor how AUKUS technology-sharing commitments redistribute development costs and production responsibilities across the trilateral partnership.
Market Dynamics
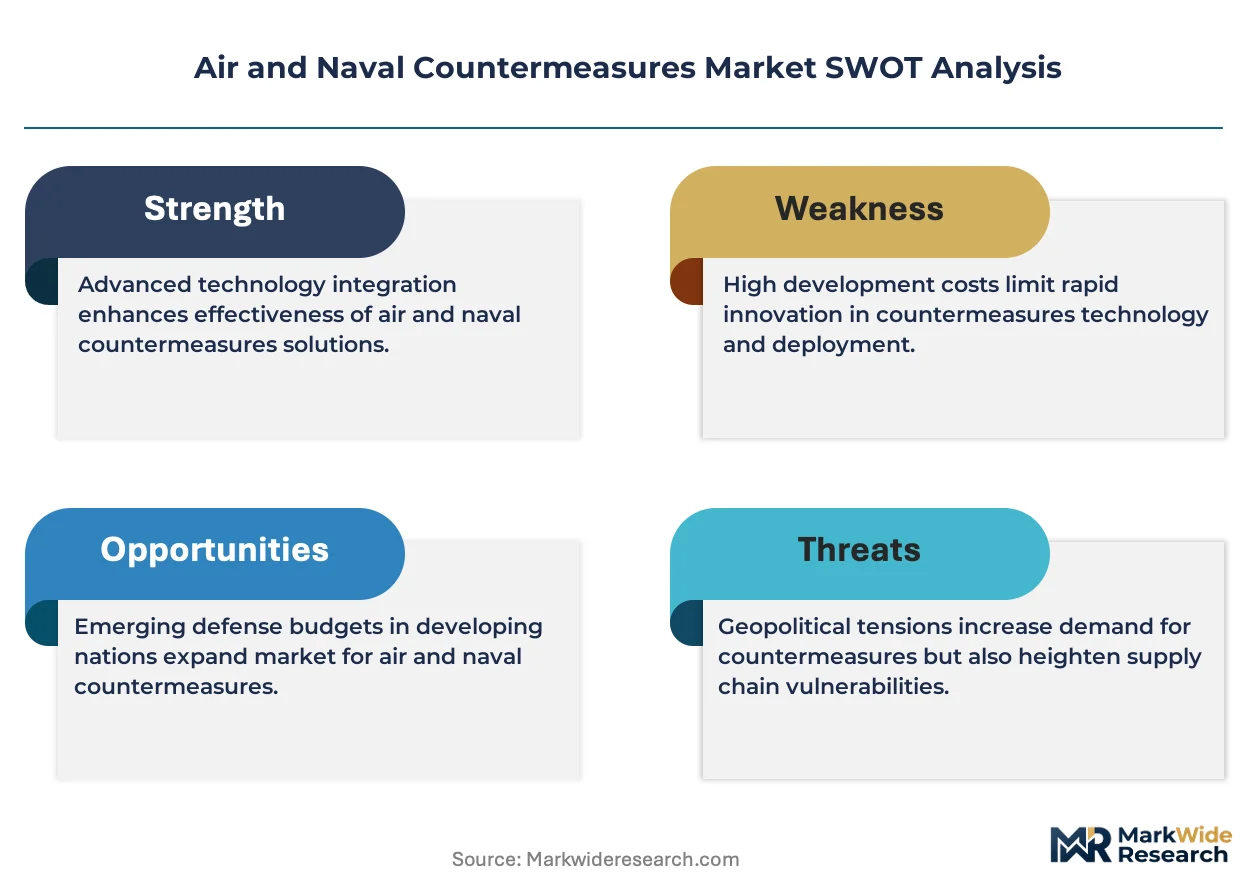
The U.S. Navy's Next Generation Jammer program and NATO's integrated multi-domain survivability mandates are forcing platform manufacturers to redesign electronic warfare architectures around networked rather than standalone countermeasure systems.
Growth Catalysts
- Contested Littoral Operations:Indo-Pacific naval patrol density requirements are driving countermeasure payload expansion per hull across surface combatant classes.
- AUKUS Technology Sharing:The trilateral partnership's submarine and electronic warfare integration protocols are standardizing cross-platform jamming system specifications.
- Direction Générale de l'Armement Modernization:France's naval electronic warfare certification gates are accelerating Franco-British joint procurement for networked decoy architectures.
Market Restraints
- Gallium Nitride Supply Concentration:Foundry capacity for high-power amplifier substrates clusters in East Asian manufacturing zones, creating single-source vulnerability for next-generation jamming transmitters.
- Platform Certification Cycles:Naval combatant integration timelines stretch across multiple fiscal years, compressing supplier cash conversion periods.
- Aluminum-Coated Glass Fiber Input Volatility:Chaff manufacturing depends on specialized metallization processes with limited secondary supply sources.
Strategic Opportunities
- Unmanned Aerial Vehicle Payload Expansion:Attritable systems are absorbing electronic warfare risk previously reserved for manned strike packages, creating new installation bases.
- Joint Capabilities Integration Standards:U.S. Department of Defense interoperability mandates are opening retrofit markets for legacy platform electronic warfare upgrades.
- Sensor Fusion Backbone Convergence:Integration of radar warning receivers with active jamming systems is unifying previously siloed countermeasure procurement budgets.
Industry Challenges
- Cross-Domain Software Certification:Air and naval platform integration requires simultaneous FAA and maritime authority validation, extending development timelines.
- Electromagnetic Spectrum Management Expertise:Shortage of engineers capable of modeling radar cross-section reduction across 2-40 GHz wavelength bands constrains design throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air and Naval Countermeasures Market |
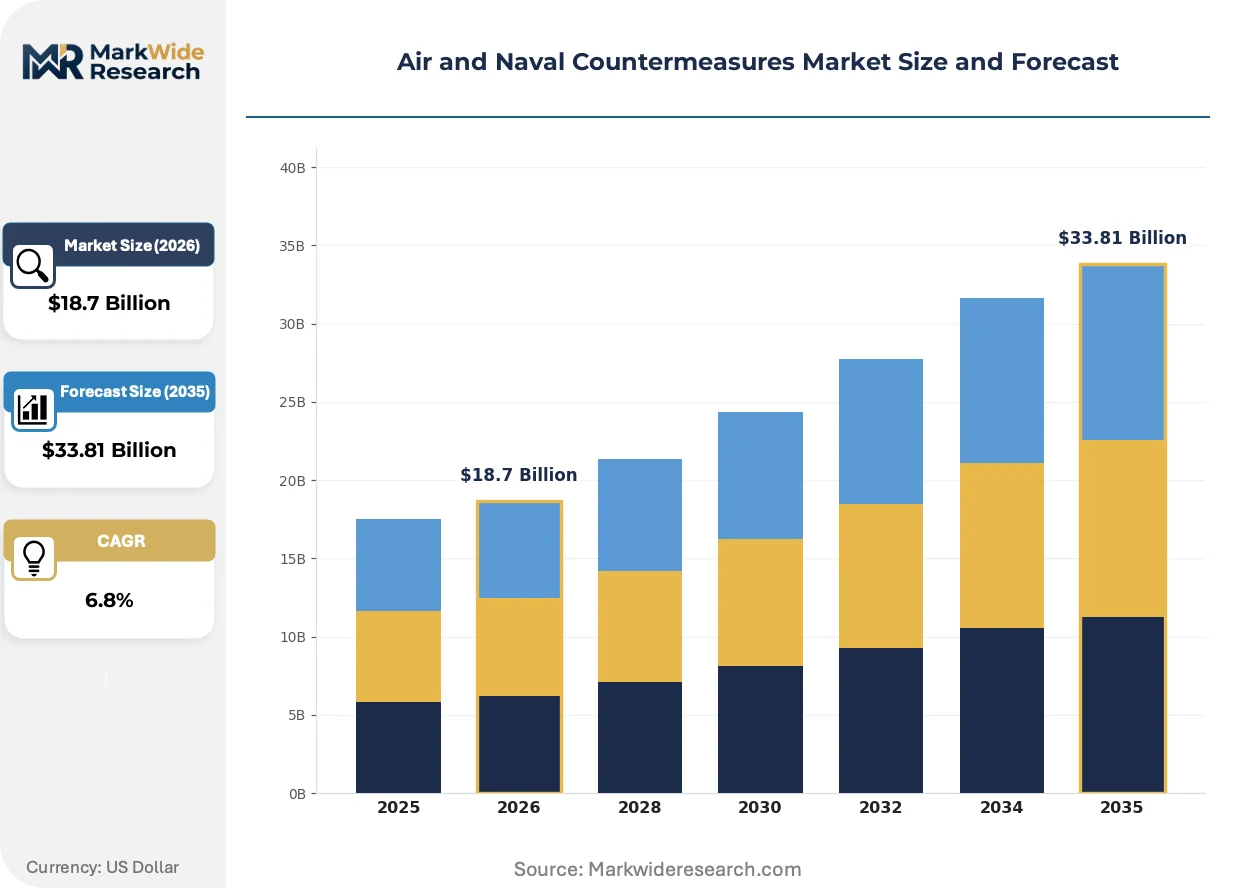
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Decoys, Jammers, Electronic Warfare Systems, Chaff Platform: Aircraft, Naval Vessels, Unmanned Aerial Vehicles, Submarines Deployment Mode: Onboard, Standalone, Networked, Integrated End User: Military, Government Agencies, Private Contractors, Defense Manufacturers |
| Companies Covered | L3Harris Technologies, Israel Aerospace Industries Ltd., Lockheed Martin Corporation, Leonardo SPA, Saab AB, Northrop Grumman Corporation, Raytheon Technologies Corporation, Thales Group, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air and Naval Countermeasures Market Strategic Shifts
Electronic warfare architecture design is abandoning standalone decoy and jammer silos in favor of fused sensor-to-shooter networks that share targeting data across platform types.
Digital radio frequency memory technology is unifying previously separate electronic attack and electronic protect functions into reprogrammable waveform generators. Naval aviation units and surface combatant commands are adopting these systems faster than legacy analog replacement cycles would predict. This convergence is compressing supplier development roadmaps from hardware-centric to software-defined upgrade models.
The EU's Cyber Resilience Act and parallel electromagnetic spectrum allocation reviews are mandating hardened command links for networked countermeasure systems. Manufacturers must now embed post-quantum cryptographic protocols into decoy deployment controllers. European naval modernization programs, particularly Franco-British joint initiatives, are experiencing the steepest compliance cost adjustments.
Defense procurement offices are consolidating electronic warfare specifications under unified multi-domain operating concepts rather than air- or sea-specific requirements. Prime contractors must now bid integrated packages spanning fighter, destroyer, and unmanned platforms simultaneously. This pattern is most visible in AUKUS member states, where trilateral sourcing agreements favor suppliers with cross-domain integration credentials.
Air and Naval Countermeasures Market Segmentation
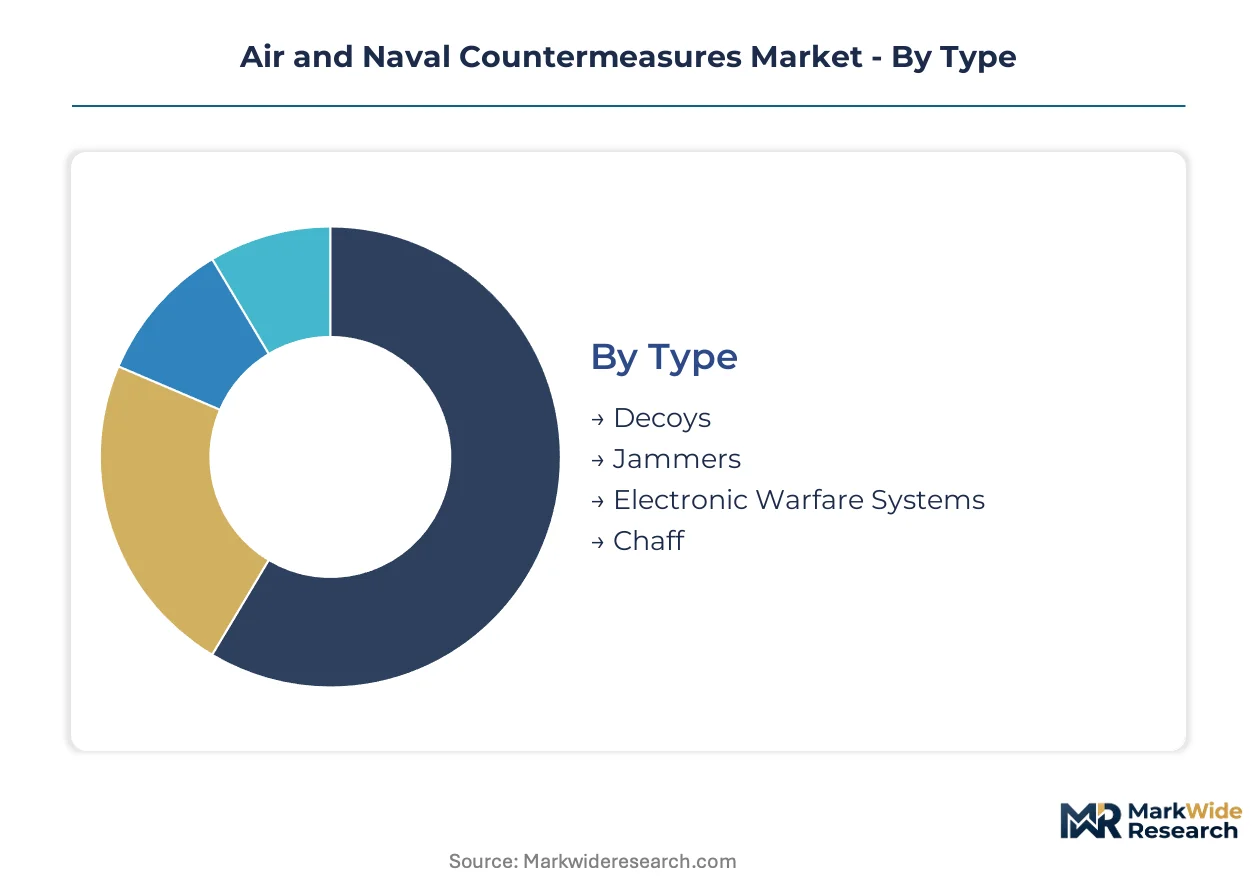
Segmentation in air and naval countermeasures reveals how procurement budgets fragment across technical generations and platform integration complexity. Buyers prioritize either standalone legacy compatibility or networked multi-domain architectures depending on fleet modernization timelines.
Type:
Defense procurement offices differentiate countermeasure types by electromagnetic signature manipulation method and reusability profile.
- Decoys:Expendable or towed systems generate false radar returns through radio frequency emission or infrared signature replication. NATO surface combatant programs in France and the United Kingdom concentrate demand for networked decoy architectures that coordinate with shipboard electronic warfare suites.
- Jammers:Active transmitters disrupt hostile radar and communication links through electromagnetic interference across 2-40 GHz wavelengths. The U.S. Navy's Next Generation Jammer program anchors investment here, with Gallium Nitride amplifier technology driving transmitter power density improvements for fighter and destroyer applications.
- Electronic Warfare Systems:Integrated sensor-to-shooter architectures fuse radar warning, jamming, and decoy control through software-defined waveforms. AUKUS technology-sharing protocols standardize specifications across submarine, surface, and aerial platforms.
- Chaff:Aluminum-coated glass fiber clouds create radar clutter at specific wavelengths. Manufacturing depends on specialized metallization processes with concentrated supply sources.
Electronic warfare systems lead volumes today; decoys are gaining share fastest.
Platform:
Platform selection determines integration certification burden and countermeasure payload density per unit.
- Aircraft:Manned strike packages carry internal and external jamming pods with strict weight and aerodynamic constraints. U.S. Department of Defense Joint Capabilities Integration standards mandate interoperability across fighter generations.
- Naval Vessels:Surface combatants integrate the most complex layered survivability systems due to per-hull space and power availability. Indo-Pacific patrol density requirements drive countermeasure expansion across destroyer and frigate classes.
- Unmanned Aerial Vehicles:Attritable systems absorb electronic warfare risk previously reserved for manned platforms. Payload expansion here climbs the fastest as swarm tactics mature.
- Submarines:Covert operations demand low-probability-of-intercept countermeasures with minimal electromagnetic emissions. AUKUS submarine programs standardize specifications across U.S., U.K., and Australian fleets.
Naval vessels dominate absolute spending; unmanned aerial vehicles show steepest expansion trajectory.
Deployment Mode:
Deployment architecture determines software upgrade pathways and cross-platform interoperability scope.
- Onboard:Systems permanently integrated into host platform power and cooling infrastructure. Legacy aircraft and surface combatants in extended service life programs favor this mode for certification simplicity.
- Standalone:Self-contained countermeasure units operate without external data links. Budget-constrained operators and non-NATO partners prefer standalone procurement for operational independence.
- Networked:Decoys, jammers, and sensors share targeting data across platform types through hardened command links. EU Cyber Resilience Act mandates post-quantum cryptography for these architectures.
- Integrated:Fused sensor-to-shooter networks unify electronic attack and protect functions. France's Direction Générale de l'Armement and U.K. Defence Equipment and Support drive integrated procurement for Franco-British naval modernization.
Onboard systems retain installed base dominance; networked architectures expand most quickly.
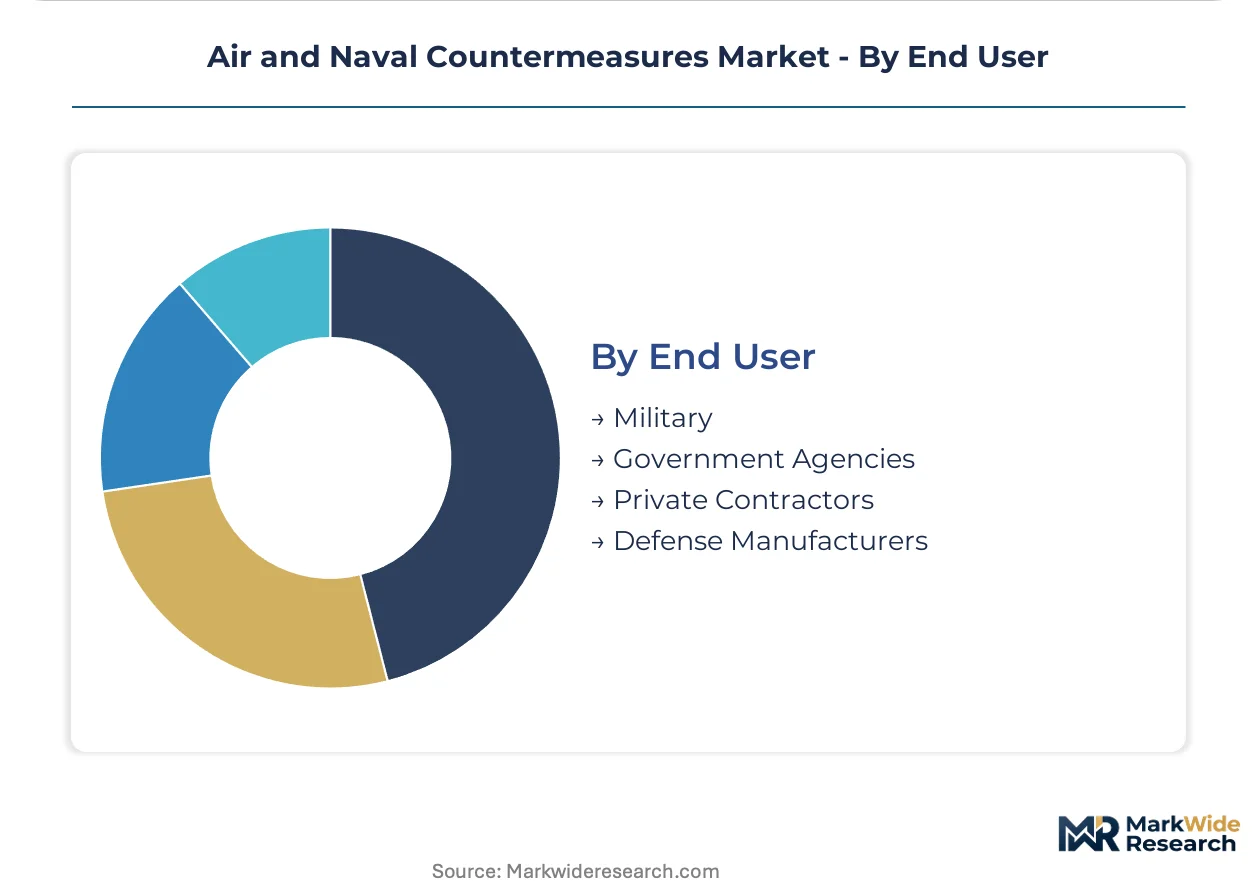
End User:
End user category shapes procurement timeline urgency and security classification thresholds.
- Military:Uniformed services operate the largest countermeasure fleets with multi-decade platform lifecycles. U.S. Navy, Royal Navy, and Marine Nationale programs set technical specifications adopted by allied forces.
- Government Agencies:Coast guards and maritime security organizations procure scaled-down electronic warfare for constabulary missions. These buyers prioritize cost efficiency over full-spectrum capability.
- Private Contractors:Firms providing operational test and evaluation services acquire countermeasure systems for threat replication. Demand concentrates in U.S. and U.K. defense industrial bases.
- Defense Manufacturers:Prime contractors integrate countermeasures into platform production lines under trilateral sourcing agreements. AUKUS member states favor suppliers with cross-domain credentials.
Military organizations command volume leadership; private contractors show fastest budget growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with streamlined defense export controls and established security-cleared manufacturing zones. Suppliers migrate toward countries offering integrated test ranges and sovereign certification authority.
United States
Naval aviation modernization and destroyer electronic warfare retrofits drive procurement volume. The Department of Defense's Joint Capabilities Integration and Development System mandates interoperability standards that shape allied platform specifications. San Diego and Norfolk anchor surface combatant integration clusters where next-generation jamming systems undergo at-sea validation.
France
Franco-British naval modernization programs concentrate demand for networked decoy architectures. Direction Générale de l'Armement certification gates filter market access and accelerate joint procurement pathways. Toulon's naval base and surrounding defense industrial zone host integrated electronic warfare test facilities for surface combatant systems.
United Kingdom
AUKUS submarine and electronic warfare integration protocols standardize cross-platform specifications across trilateral partnerships. Defence Equipment and Support imposes national security certification requirements that favor established suppliers. Portsmouth and Clyde naval bases support submarine countermeasure development and surface fleet electronic warfare upgrades.
Australia
Contested littoral operations in the Indo-Pacific drive countermeasure density requirements for patrol and surface combatant fleets. AUKUS technology-sharing commitments redistribute development costs and production responsibilities across the trilateral partnership. Osborne in South Australia and Henderson in Western Australia concentrate submarine and naval electronic warfare integration capabilities.
Japan
Maritime Self-Defense Force destroyer modernization and air defense fighter upgrades expand countermeasure procurement. METI industrial security guidelines govern foreign supplier access to sensitive electronic warfare programs. Nagasaki and Kure naval districts host surface combatant construction and electronic warfare system integration facilities.
Air and Naval Countermeasures Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system primes capturing naval platform awards while component suppliers serve retrofit and upgrade markets. The vendor landscape organizes around three tiers: cross-domain electronic warfare integrators, platform-specific countermeasure specialists, and expendables manufacturers with metallization expertise. Consolidation pressure intensifies as multi-domain procurement mandates favor suppliers with simultaneous air, surface, and subsurface credentials. Strategic moves center on trilateral sourcing alignment with AUKUS member states and backward integration into Gallium Nitride substrate supply.
Among transatlantic defense primes, L3Harris Technologies, Raytheon Technologies Corporation, and Thales Group occupy positions that exemplify divergent competitive archetypes. L3Harris anchors integrated countermeasure architectures through cross-domain electronic warfare portfolios spanning fighter and destroyer applications. Raytheon sustains deep investment positions in next-generation jamming systems competing for naval aviation and surface combatant programs. Thales differentiates through European-centric networked decoy deployments that dominate Franco-British modernization pathways.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Israel Aerospace Industries Ltd. |
| Lockheed Martin Corporation |
| Leonardo SPA |
| Saab AB |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| Thales Group |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NATO-compliant electronic warfare systems and non-allied alternatives manifests in both pricing premiums and supply chain exclusion patterns. Direction Générale de l'Armement and U.K. Defence Equipment and Security certification gates bifurcate procurement channels, with qualified suppliers commanding sustained margin advantages while excluded competitors face downstream distribution barriers.
Pricing Analysis
Direct-to-OEM channel discounts dominate high-volume naval platform awards, while distributor markups persist in retrofit and upgrade markets for legacy combatants. Three-tier pricing structure across mission-critical, standard military-grade, and commercial-off-the-shelf levels tracks certification depth and electromagnetic spectrum management complexity. Price differentiation stems from Joint Capabilities Integration compliance overhead and Gallium Nitride amplifier integration costs. Cost compression in expendable decoy tiers is intensifying because aluminum-coated glass fiber metallization capacity concentrates in limited foundry zones. Government agencies exhibit highest price sensitivity due to constabulary mission budgets, while prime defense contractors absorb premium pricing for integrated multi-domain architectures.
Supply Chain Analysis
Freight cost volatility for specialized electronic warfare components amplifies total landed cost sensitivity across transatlantic and Indo-Pacific procurement corridors. Manufacturing concentration clusters in the United States, France, and the United Kingdom for NATO-certified systems, with Japan and Australia anchoring AUKUS-aligned production nodes. Raw material dependencies center on Gallium Nitride substrates, aluminum-coated glass fiber, and post-quantum cryptographic chipsets. Single-source vulnerability for high-power amplifier foundries in East Asian manufacturing zones threatens next-generation jamming transmitter availability. Distribution runs through prime contractor integration facilities at San Diego, Toulon, Portsmouth, and Osborne rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-defined waveform upgrades and captive Gallium Nitride supply, as platform certification cycles lock in long-term service revenue streams.
For Market Incumbents: Deploy cross-domain integration credentials as the defensive lever against emerging specialists with single-platform expertise. Backward integration into Gallium Nitride substrate supply secures amplifier cost positions for next-generation jamming programs. Channel control through trilateral AUKUS sourcing agreements filters competitive access to submarine and surface combatant awards. Certification investment in EU Cyber Resilience Act compliance creates switching costs for Franco-British naval modernization pathways. For New Entrants and Emerging Players: Digital-channel routes through operational test and evaluation contractor networks offer lowest barrier entry for threat replication system sales. Private contractor segments serving U.S. and U.K. defense industrial bases present the most penetrable white-space target due to lower security classification thresholds. Geographic expansion into Australian Henderson and Osborne clusters captures AUKUS technology-sharing redistribution opportunities. Direct engagement with maritime security organizations bypasses prime contractor gatekeeping in military procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where cross-domain software certification capabilities overlap with expendable decoy manufacturing scale. Long-term viability favors suppliers with simultaneous air, surface, and subsurface platform credentials across the 2026-2035 modernization window. Acquisition target archetypes include mid-cap electronic warfare specialists with Direction Générale de l'Armement or Defence Equipment and Support pre-qualification status. Monitor AUKUS submarine program milestone announcements as inflection indicators for trilateral sourcing agreement allocations.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Domain Platform Integration | Unifies fighter, destroyer, and unmanned system specifications under Joint Capabilities Integration mandates. |
| Gallium Nitride Supply Security | Captive substrate production insulates next-generation jamming programs from East Asian foundry concentration risk. |
| Networked Decoy Architecture Deployment | Aligns with Franco-British naval modernization and EU Cyber Resilience Act cryptographic compliance requirements. |
| Software-Defined Waveform Transition | Compresses hardware replacement cycles into reprogrammable upgrade revenue models for electronic warfare suites. |
| AUKUS Trilateral Sourcing Alignment | Positions suppliers for submarine and surface combatant awards across U.S., U.K., and Australian procurement offices. |
Study Parameters
Direct dialogue with electronic warfare program managers, naval platform integration engineers, defense procurement officers, and electromagnetic spectrum operations specialists grounded qualitative assessment. Secondary validation drew from U.S. Department of Defense budget justification materials, NATO standardization office publications, AUKUS partnership disclosure documents, and Direction Générale de l'Armement procurement registers. Bottom-up platform deployment projections and top-down defense budget allocation analysis were triangulated against contractor revenue segment disclosures.
Segment-level value outputs across the projection horizon reflect modeled interactions between platform modernization cycles, certification timeline constraints, and technology-sharing agreement implementations. Segmentation dimensions included countermeasure type, platform class, deployment architecture, and end-user category with cross-cutting analysis of NATO versus non-NATO procurement pathway divergence. CAGRs were derived from fitted adoption curves for digital radio frequency memory technology and attritable unmanned system payload expansion rates.
Platform certification delays, Gallium Nitride foundry capacity constraints, and AUKUS partnership restructuring are the dominant revision risks to baseline projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Submarine Combat System Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Combat Management System Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Radar Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Naval Combat Systems Market