
 Military Aerospace and Defense Lifecycle Management Market | 2026-2036
Military Aerospace and Defense Lifecycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aerospace and Defense Lifecycle Management Market Intelligence
Defense contractor fleets is rebalancing toward predictive maintenance and digital twin architectures. Siemens AG leverages its digital thread portfolio to anchor large-scale platform sustainment contracts across NATO-aligned air forces. PTC Inc. sustains technology leadership in augmented reality-enabled maintenance workflows for complex weapons systems. Honeywell International Inc. dominates integrated logistics support for turbine propulsion modules, extending its footprint across multiple service branches.
Military aerospace and defense lifecycle management encompasses the integrated planning, engineering, logistics, and sustainment activities that preserve operational availability of weapon systems across multi-decade service lives, typically spanning 30–50 years for strategic platforms such as heavy transport aircraft and nuclear submarines. Its primary purpose is to minimize total ownership cost while maintaining mission-capable rates above operational readiness thresholds set by military end users. The service type dimension shows maintenance services and engineering services commanding the deepest margin pools, as platform complexity escalates and OEM technical data rights create structural barriers to third-party competition. Product type segmentation reveals aerospace systems sustaining the largest revenue base, while simulation tools represent the fastest-expanding category as synthetic training environments reduce live-flight wear on aging airframes.
The U.S. Department of Defense's CBM+ mandate, the U.K. Ministry of Defence's DE&S safety and airworthiness framework, and NATO's Standardization Agreement 4107 collectively shape procurement specifications, data interoperability requirements, and vendor qualification pathways for lifecycle management solutions. These frameworks compel platform integrators to demonstrate digital engineering maturity and supply chain traceability as prerequisites for contract eligibility. Stakeholders must monitor how emerging AI-enabled fault detection algorithms intersect with existing airworthiness certification processes to determine competitive positioning in next-generation sustainment programs.
Market Dynamics
The U.S. Department of Defense's CBM+ directive is compressing sustainment timelines by mandating real-time sensor integration across tactical aircraft and naval platforms, forcing prime contractors to restructure engineering workflows around predictive analytics rather than scheduled overhaul cycles.
Growth Catalysts
- CBM+ Mandate:The U.S. DoD's Condition-Based Maintenance Plus framework requires digital thread implementation across all major weapons systems, creating compulsory upgrade cycles for legacy platform sustainment contracts.
- Digital Twin Architectures:NATO-aligned air forces are deploying physics-based platform replicas to compress fault isolation timelines and reduce unscheduled maintenance events on aging tactical aircraft fleets.
- Submarine Fleet Modernization:The United Kingdom's nuclear deterrent renewal program and Australia's AUKUS submarine procurement are generating multi-decade engineering services demand for reactor plant lifecycle management.
Market Restraints
- Technical Data Rights Concentration:Original equipment manufacturers retain proprietary control over weapon system design baselines, limiting third-party maintenance provider market entry in the United States and United Kingdom.
- Titanium and Superalloy Supply Constraints:Turbine blade casting feedstock availability is tightening due to Russian-sourced sponge titanium sanctions, elevating propulsion module overhaul costs.
- Airworthiness Certification Friction:The U.K. Military Aviation Authority's safety case requirements for AI-enabled diagnostic tools extend software validation timelines by 18-24 months versus traditional mechanical systems.
Strategic Opportunities
- Underpenetrated Nordic Markets:Norway and Finland's F-35 fleet expansions lack established regional depot infrastructure, creating openings for predictive maintenance platform providers to anchor long-term sustainment partnerships.
- Converging AR and Physics Modeling:Augmented reality maintenance overlays combined with finite element analysis are enabling remote expert guidance for field-level repairs on distributed naval vessels.
- EU Defense Fund Incentives:The European Defence Fund's collaborative procurement mechanisms are subsidizing cross-border lifecycle management consortia for next-generation combat aircraft development.
Industry Challenges
- Model-Based Systems Engineering Talent Scarcity:Defense contractors face acute shortages of engineers proficient in SysML and digital thread architecture, slowing CBM+ implementation timelines.
- Legacy Platform Data Migration Complexity:Paper-based maintenance records from 1970s-era aircraft and vessels resist automated digitization, forcing manual transcription workflows that delay predictive analytics deployment.
- Interoperability Standardization Delays:NATO's STANAG 4107 implementation gaps between member nations' data exchange protocols fragment multi-national fleet sustainment coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aerospace and Defense Lifecycle Management Market |
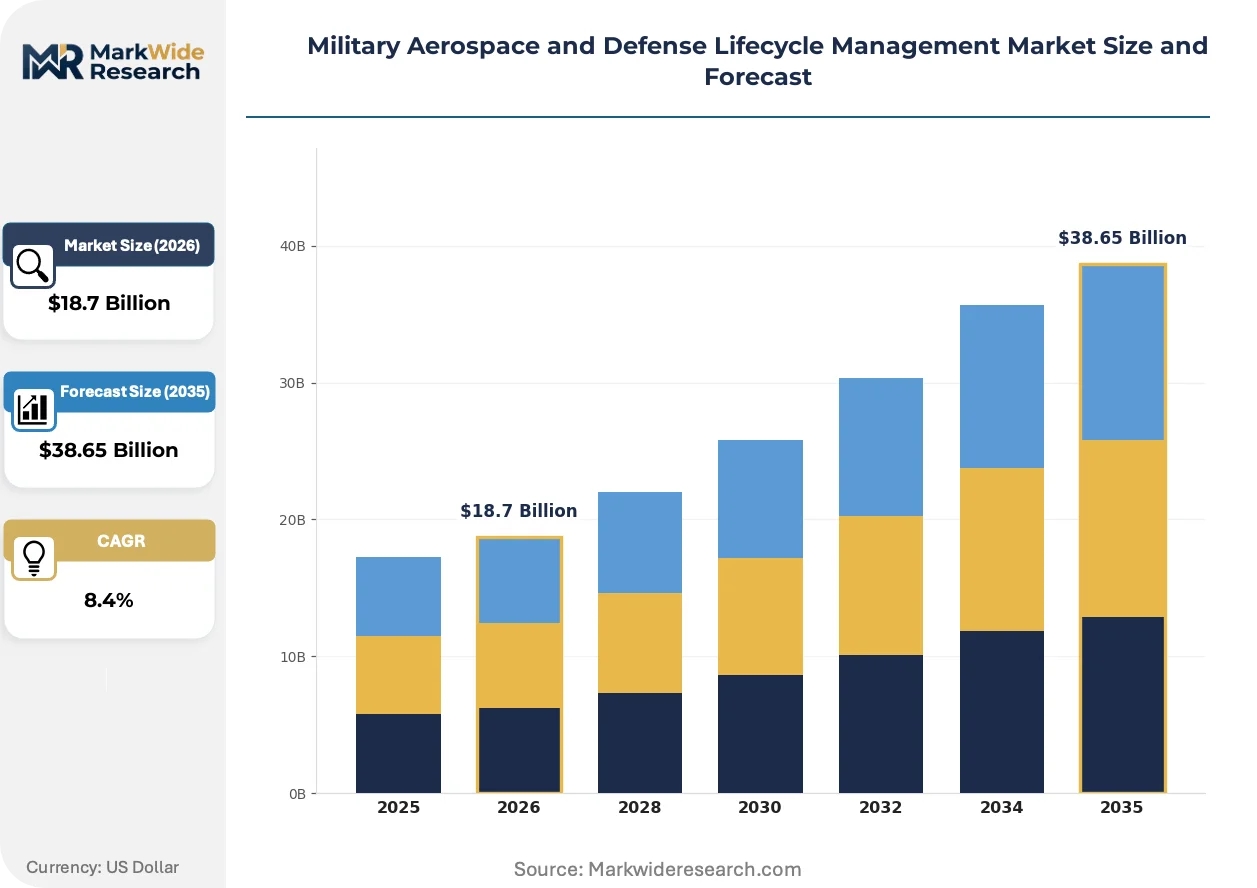
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Logistics Support, Maintenance Services, Engineering Services, Training Solutions Product Type: Aerospace Systems, Defense Equipment, Ground Support Equipment, Simulation Tools End User: Government Agencies, Defense Contractors, OEMs, Third-Party Providers Technology: IoT, Artificial Intelligence, Big Data Analytics, Cloud Computing |
| Companies Covered | Aras Corporation, ATS Global B.V., Dassault Systèmes SE, Honeywell International Inc., Infor, PROLIM, PTC Inc., Cyient Limited, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aerospace and Defense Lifecycle Management Market Strategic Shifts & Innovations
Artificial intelligence is penetrating fault detection workflows at the sensor edge, compressing the interval between anomaly identification and maintenance action across distributed military platforms operating beyond continental supply lines.
Machine learning algorithms deployed on fighter aircraft health monitoring units are automating vibration signature analysis that previously required ground-based specialist interpretation. The U.S. Air Force's F-35 fleet is adopting these edge-computing modules at squadron level, reducing false-positive maintenance flags by eliminating telemetry latency to centralized diagnostic centers. This capability is automating the triage hierarchy that determines which aircraft remain mission-capable versus those requiring immediate depot attention.
The EU AI Act's risk classification framework is imposing mandatory conformity assessments on autonomous diagnostic systems used in European military aviation. France's Direction Générale de l'Armement now requires algorithmic transparency documentation for predictive maintenance software deployed on Rafale fighter sustainment contracts. German and Italian platform integrators are restructuring supplier qualification pathways to satisfy these documentation burdens, prioritizing vendors with pre-certified machine learning development pipelines.
Defense procurement officers are unbundling long-term sustainment contracts from initial platform acquisition, enabling competitive re-competition of engineering services at mid-life upgrade intervals. The U.K. Ministry of Defence's Team Tempest program has separated digital twin development from airframe manufacturing, allowing specialized software houses to bid against traditional aerospace primes. This pattern is most visible in Australia's F/A-18F Super Hornet sustainment transition, where the Royal Australian Air Force migrated from Boeing-locked arrangements to multi-vendor performance-based logistics structures.
Military Aerospace and Defense Lifecycle Management Market Segmentation
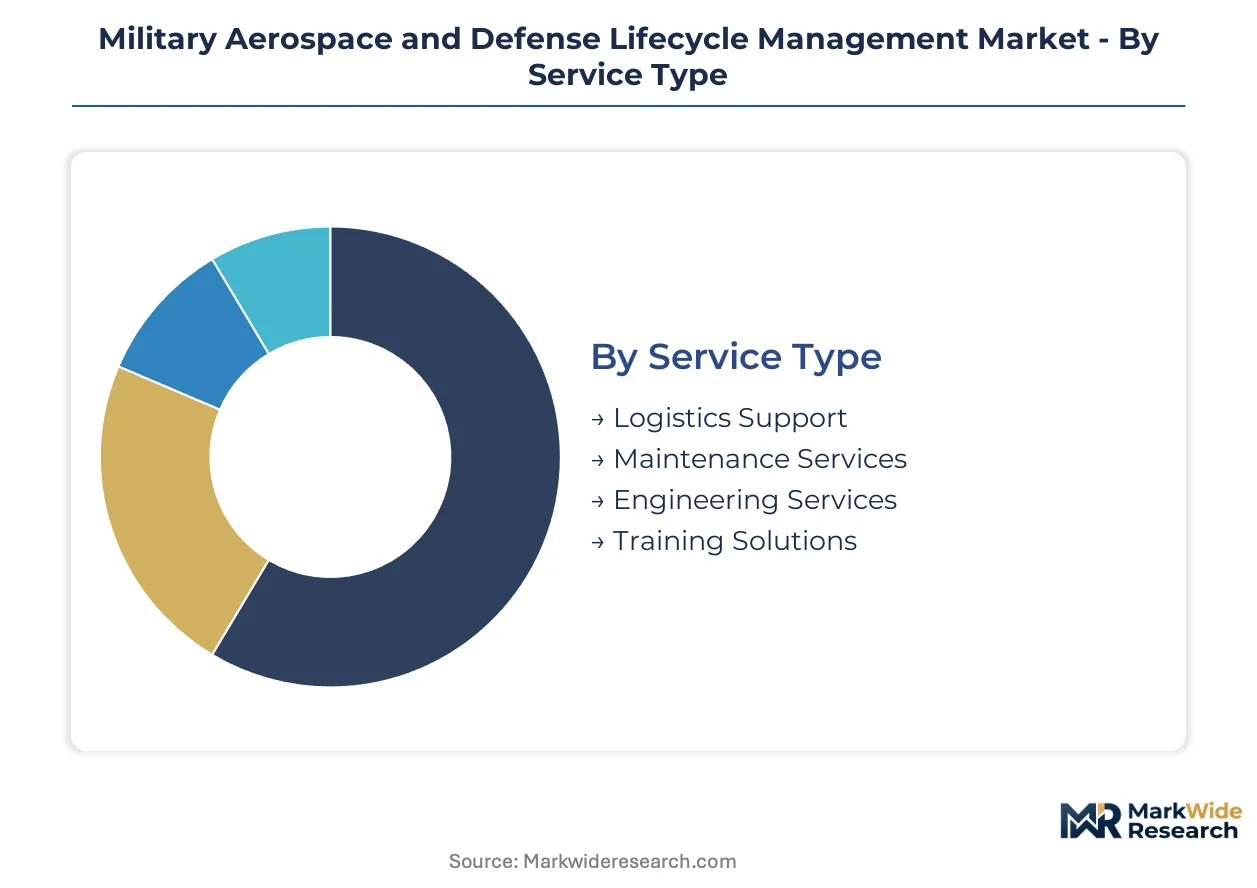
Military aerospace sustainment contracts fragment across service modalities, platform categories, and technology stacks. Each segmentation dimension carries distinct margin profiles and competitive entry barriers shaped by technical data rights and certification requirements.
Service Type:
Customization intensity varies sharply across this dimension, from standardized logistics workflows to bespoke engineering services requiring platform-specific intellectual property access.
- Maintenance Services:Platform overhaul, component repair, and scheduled inspection activities preserve mission-capable rates for aging tactical aircraft and naval vessels. Demand concentrates in the United States, where the U.S. Department of Defense's CBM+ directive forces real-time sensor integration into legacy depot workflows.
- Engineering Services:Structural analysis, fatigue life extension, and airworthiness certification support span multi-decade platform service lives. Australia's AUKUS submarine procurement and the United Kingdom's nuclear deterrent renewal are generating concentrated demand for reactor plant lifecycle engineering.
- Logistics Support:Spare parts provisioning, supply chain management, and inventory optimization sustain distributed military operations.
- Training Solutions:Crew qualification programs and maintenance technician certification reduce operational risk across complex weapons systems.
Most installed capacity flows through Maintenance Services. Expansion is steepest in Engineering Services.
Product Type:
Application criticality drives divergence here, with flight-safety systems commanding regulatory scrutiny that ground support equipment escapes.
- Aerospace Systems:Airframe structures, avionics suites, and propulsion modules sustain the largest revenue base across fighter, transport, and rotary-wing platforms. The U.S. Air Force's F-35 fleet modernization and NATO-aligned tactical aircraft upgrades concentrate demand in North American and European depots.
- Simulation Tools:Synthetic training environments replicate flight dynamics and weapons employment scenarios without airframe wear. France's Direction Générale de l'Armement and the U.K. Ministry of Defence are expanding procurement of these systems to preserve aging airframe fatigue life.
- Defense Equipment:Weapon systems, fire control radars, and electronic warfare modules require specialized test equipment and software load verification.
- Ground Support Equipment:Hydraulic test stands, engine trailers, and munitions handling systems enable flight line operations.
Aerospace Systems anchor current contract value. Simulation Tools are gaining share fastest as live-flight hour reduction becomes a priority.
End User:
Procurement authority concentration shapes competitive dynamics, from sole-source government relationships to fragmented third-party maintenance markets.
- Government Agencies:Military departments and defense ministries hold ultimate platform ownership and sustainment budget authority. The U.S. Department of Defense's performance-based logistics contracts and the U.K. Ministry of Defence's Team Tempest program structure concentrate demand in sovereign procurement frameworks.
- Defense Contractors:Prime integrators and platform OEMs execute long-term sustainment under availability-based contracts. Boeing, Lockheed Martin, and BAE Systems leverage technical data rights to lock in multi-decade service agreements.
- OEMs:Original equipment manufacturers supply proprietary components and engineering support for systems they designed.
- Third-Party Providers:Independent maintenance organizations compete for component-level repair work where technical data is accessible.
Defense Contractors control the deepest contract pipelines. Third-Party Providers face the steepest entry barriers from data rights restrictions.
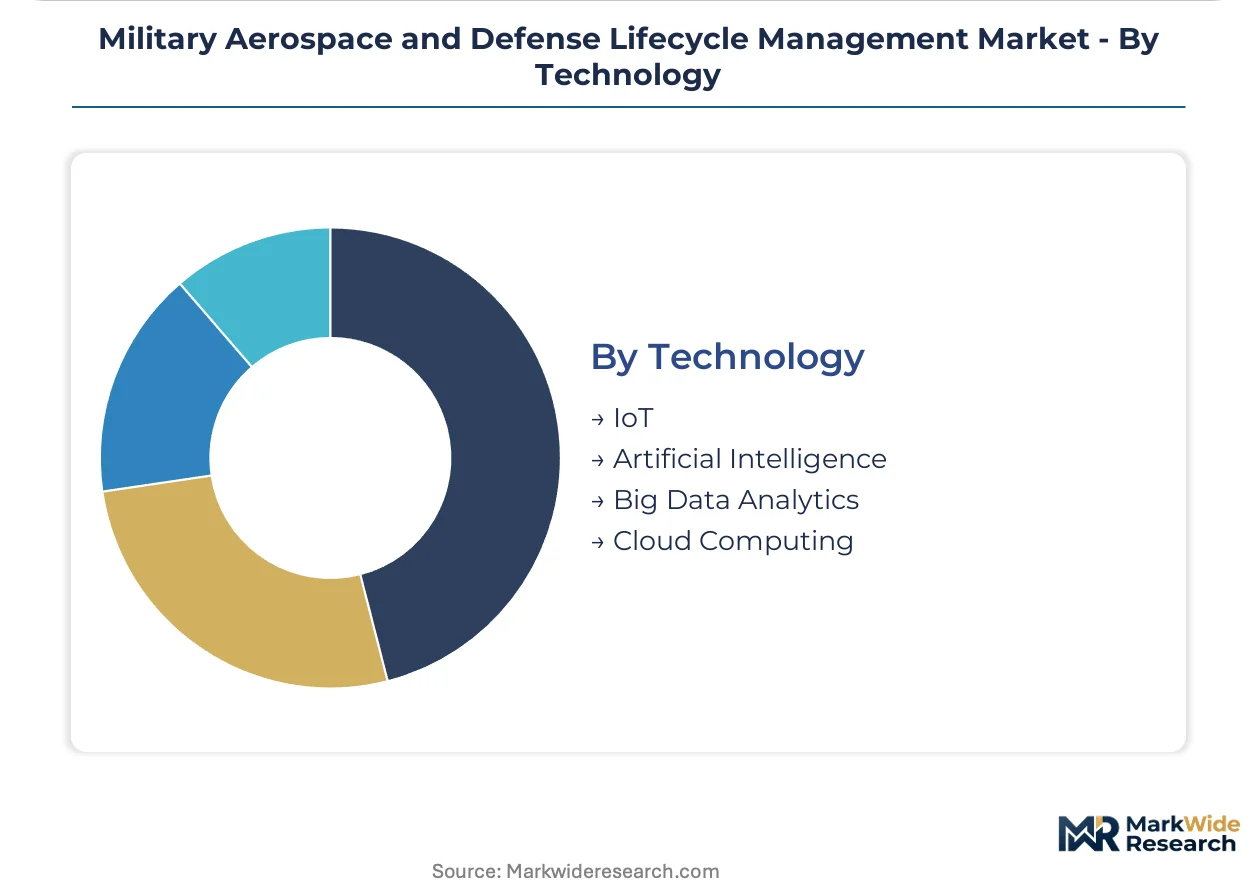
Technology:
Maturity gradients separate established connectivity infrastructure from emerging autonomous diagnostic capabilities.
- Artificial Intelligence:Machine learning algorithms automate fault detection and predictive maintenance triage at the sensor edge. The U.S. Air Force's F-35 health monitoring units and France's Rafale sustainment contracts are deploying these systems under emerging EU AI Act conformity requirements.
- IoT:Sensor networks and telemetry infrastructure capture platform health data for centralized analysis. NATO's STANAG 4107 standardization efforts are driving interoperability investments across member nation fleets.
- Big Data Analytics:Fleet-wide pattern recognition identifies systemic failure modes across dispersed operational environments.
- Cloud Computing:Distributed data storage and processing enable multi-site engineering collaboration and digital twin hosting.
IoT infrastructure underpins current platform connectivity. Artificial Intelligence represents the steepest expansion trajectory as autonomous diagnostics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where defense lifecycle management contracts are executed, with NATO-aligned nations leveraging the EU AI Act's conformity assessment gaps to accelerate autonomous diagnostic deployment faster than U.S. FAA-equivalent timelines permit.
United States
The U.S. Department of Defense's CBM+ directive and F-35 fleet modernization are compressing sustainment timelines across tactical aircraft inventories. The FAA's airworthiness certification framework for AI-enabled systems creates procedural friction that primes are navigating through military exemption pathways. Concentrated demand flows through Lockheed Martin's Fort Worth assembly complex and the Ogden Air Logistics Complex in Utah.
United Kingdom
Team Tempest and nuclear deterrent renewal programs are generating multi-decade engineering services demand for reactor plant lifecycle management. The U.K. Military Aviation Authority's safety case requirements extend software validation timelines for autonomous diagnostics. BAE Systems' Warton facility in Lancashire anchors platform integration and digital twin development for next-generation combat aircraft.
Germany
Rafale and Eurofighter sustainment contracts are expanding as France and Germany deepen defense industrial cooperation. The KBA's absence from military aviation oversight leaves certification to national military authorities, creating faster deployment pathways for predictive maintenance platforms. MTU Aero Engines' Munich headquarters concentrates propulsion module overhaul capacity for NATO-aligned fleets.
Australia
AUKUS submarine procurement and F/A-18F Super Hornet sustainment transitions are driving competitive re-competition of engineering services. The Royal Australian Air Force's migration from Boeing-locked arrangements to multi-vendor performance-based logistics structures is reshaping contractor relationships. RAAF Base Amberley in Queensland serves as the primary concentration for tactical aircraft depot maintenance.
France
Rafale fighter sustainment and Direction Générale de l'Armement procurement are expanding synthetic training environment adoption to preserve aging airframe fatigue life. ANSM and CNIL oversight of the EU AI Act's risk classification framework imposes mandatory algorithmic transparency documentation on predictive maintenance software. Dassault Aviation's Bordeaux-Mérignac facility anchors platform manufacturing and integrated logistics support.
Military Aerospace and Defense Lifecycle Management Market Key Industry Players
Strategic partnerships dominate the current landscape as prime contractors restructure around digital engineering competencies rather than traditional manufacturing scale. The vendor base clusters into three tiers: platform OEMs with technical data rights, specialized software houses with AI/ML development pipelines, and regional maintenance providers competing on component-level repair. Two archetypes are consolidating advantage: digital thread integrators securing NATO-wide sustainment contracts, and predictive analytics specialists penetrating mid-life upgrade intervals. M&A activity and technology licensing agreements represent the dominant competitive vectors, with smaller software targets fetching premiums for pre-certified machine learning development capabilities.
Within the digital engineering tier, Siemens AG and PTC Inc. exemplify contrasting positioning strategies. Siemens leverages its industrial software portfolio to anchor large-scale platform sustainment contracts across NATO-aligned air forces. PTC occupies a specialized position in augmented reality-enabled maintenance workflows for complex weapons systems. Honeywell International Inc. represents the integrated logistics archetype, extending its footprint across multiple service branches through turbine propulsion module expertise. These three companies illustrate how technical data access and pre-existing defense relationships create structural barriers that resist new market entry.
| Leading Market Players |
|---|
| Aras Corporation |
| ATS Global B.V. |
| Dassault Systèmes SE |
| Honeywell International Inc. |
| Infor |
| PROLIM |
| PTC Inc. |
| Cyient Limited |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
The U.S. Department of Defense's CBM+ directive gates qualified supply and premium-tier pricing access by mandating digital thread certification for all major sustainment contractors, forcing primes to absorb compliance costs or cede position to pre-certified competitors.
Pricing Analysis
Direct-to-OEM contracting dominates channel-margin structures, with primes capturing value through long-term availability-based agreements rather than transactional component sales. Three-tier pricing structure across premium, standard, and economy levels reflects technical data rights access, with OEM-locked engineering services commanding premium positioning and third-party component repair competing on cost. Pricing pressure stems from the Royal Australian Air Force's multi-vendor performance-based logistics restructures, which compress margins for incumbents locked into Boeing-style sole-source arrangements. Government agencies exhibit highest price sensitivity due to budget cycle constraints, while defense contractors demonstrate lowest sensitivity where mission-capable rate guarantees justify premium positioning.
Supply Chain Analysis
Regional distribution centers in the United States, United Kingdom, and Germany anchor hub-and-spoke patterns for classified platform components requiring sovereign custody chains. Titanium sponge and nickel-based superalloys for turbine blade casting draw from constrained feedstock pools, with Russian-sourced material sanctions tightening propulsion module overhaul capacity. Single-source vulnerability concentrates in OEM technical data rights, where Boeing, Lockheed Martin, and BAE Systems control design baselines that resist third-party maintenance entry. Distribution runs through military air logistics complexes and naval shipyards rather than commercial freight networks, reflecting security-cleared handling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in military aerospace lifecycle management rests on AI-enabled predictive maintenance platforms that displace scheduled overhaul labor with automated fault detection, compressing cost structures while preserving availability premiums.
For Market Incumbents: Cement technical data rights through digital twin architecture investments that embed proprietary physics models into NATO sustainment contracts. Acquire pre-certified machine learning development pipelines to satisfy the EU AI Act's algorithmic transparency requirements before specialized software houses capture mid-life upgrade intervals. Lockheed Martin's Fort Worth complex and BAE Systems' Warton facility illustrate how sovereign platform integration relationships resist displacement.
For New Entrants and Emerging Players: The EU AI Act's risk classification framework in France and Germany opens a window for algorithmic transparency specialists to penetrate Rafale and Eurofighter sustainment contracts. Target Norway and Finland's F-35 depot infrastructure gaps, where established regional maintenance networks remain underdeveloped. Position through augmented reality-enabled remote expert guidance for distributed naval vessel repairs, converging AR overlays with finite element analysis to bypass capital-intensive depot investments.
For Investors and Strategic Acquirers: Roll-up economics work for predictive analytics specialists because defense procurement officers are unbundling sustainment from platform acquisition, enabling competitive re-competition at mid-life upgrade intervals. The 5-10 year viability window favors targets with pre-certified machine learning pipelines and existing NATO STANAG 4107 interoperability credentials. Monitor the U.K. Military Aviation Authority's safety case approval velocity for AI-enabled diagnostics as the inflection indicator for autonomous maintenance platform adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | BAE Systems' Team Tempest separation of digital twin development from airframe manufacturing enables software house competition against traditional primes. |
| Predictive Maintenance SaaS Deployment | Siemens AG anchors NATO-aligned air force sustainment contracts through industrial software portfolio penetration. |
| Technical Data Rights Acquisition | Honeywell International extends turbine propulsion module dominance through proprietary design baseline control across multiple service branches. |
| AR-Enabled Remote Maintenance | PTC Inc. occupies specialized positioning in augmented reality maintenance workflows for complex weapons systems. |
| EU AI Act Compliance Certification | France's Direction Générale de l'Armement mandates algorithmic transparency documentation that restructuring supplier qualification pathways. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, platform engineering directors, military aviation authority regulators, and sustainment contract managers with secondary validation against U.S. Department of Defense budget justifications, NATO STANAG documentation, EU AI Act regulatory filings, and SEC 10-K disclosures from listed defense primes. Bottom-up service-type and product-type segmentation sizing reconciled against top-down national defense expenditure patterns.
Segment-weighting approaches distributed value across maintenance services, engineering services, logistics support, and training solutions, with aerospace systems, simulation tools, defense equipment, and ground support equipment as product-type dimensions. Technology segmentation captured artificial intelligence, IoT, big data analytics, and cloud computing maturity gradients. CAGRs derived from platform fleet age profiles, modernization cycle timing, and regulatory mandate implementation schedules across the analysis window.
Revisions become necessary when titanium and superalloy supply constraints intensify, when technical data rights frameworks shift toward open-architecture mandates, or when airworthiness certification timelines for autonomous diagnostics compress or extend materially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market