
 Military Vetronics Market | 2026-2036
Military Vetronics Market Size, Share, and Industry Trends Forecast 2026-2036
Military Vetronics Market Analysis
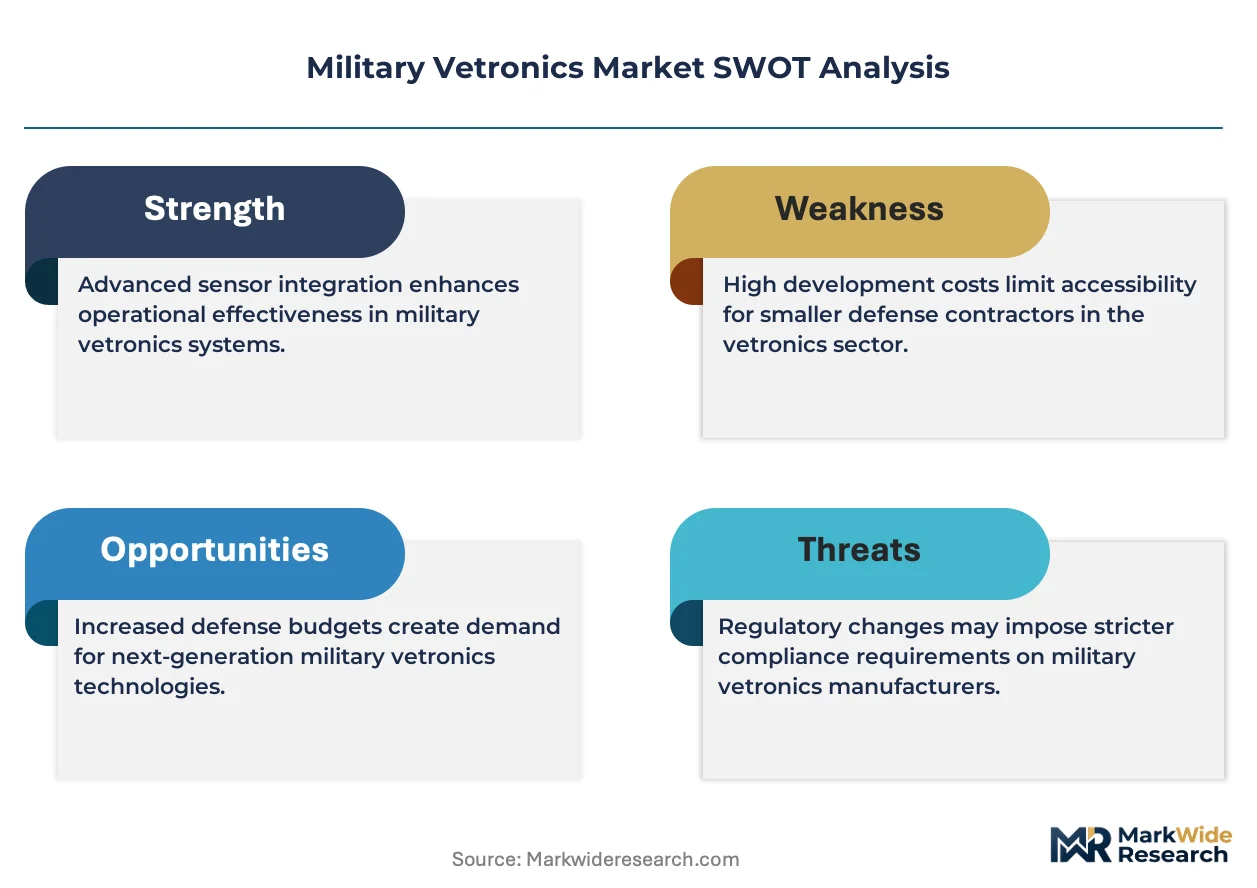
Modular vetronics bundling is rebalancing procurement economics for military vehicle fleets. BAE Systems leverages its UK manufacturing footprint to sustain integrated turret electronics programs across multiple NATO platforms. Rheinmetall AG anchors German land-system vetronics with captive in-house production of command-and-control modules. Curtiss-Wright Corporation specializes in ruggedized computing subsystems that occupy the thermal-management layer of armored vehicle architectures.
Military vetronics encompasses the electronic systems—computing, communications, navigation, and sensor integration—installed in ground combat vehicles, naval craft, and airborne platforms to enable command, control, and situational awareness in contested environments. These systems typically operate across military-specified temperature ranges with shock and vibration hardening per MIL-STD-810, serving the primary purpose of fusing real-time battlefield data into actionable intelligence for vehicle crews. Command Control Systems and Communication Systems represent the mature revenue core where defense contractors compete on program longevity and spare-part contracts, while Autonomous Systems and Surveillance Systems constitute the fastest-expanding technology pockets as unmanned ground vehicle programs accelerate. Software-Defined Radio sits at the center of margin concentration because waveform-upgrade cycles generate recurring engineering revenue without platform replacement.
The US Department of Defense enforces MOSA compliance through the Army's PEO Ground Combat Systems, mandating open-architecture interfaces that prevent vendor lock-in across vehicle electronics suites. NATO's STANAG 4694 for tactical data links shapes interoperability requirements, while Germany's BAAINBw imposes country-specific cybersecurity certifications on vetronics suppliers for Bundeswehr programs. Stakeholders must monitor how the EU Defense Industrial Strategy alters cross-border qualification pathways for vetronics integrators serving multiple European land forces.
Market Dynamics
The US Department of Defense's Modular Open Systems Approach directive is forcing a fundamental restructuring of supplier relationships across military vehicle electronics, as open-architecture mandates dismantle decades of proprietary subsystem lock-in.
Growth Catalysts
- Interoperability Mandates:NATO's STANAG 4694 for tactical data links compels cross-border equipment compatibility, driving replacement cycles in allied armored vehicle fleets.
- Unmanned Platform Proliferation:Autonomous ground vehicle programs in Germany and the United States are expanding demand for sensor fusion computing and edge-processing modules.
- Electromagnetic Spectrum Contention:Software-Defined Radio waveform upgrades generate recurring engineering revenue without requiring full platform replacement.
Market Restraints
- Semiconductor Supply Concentration:Advanced node fabrication for radiation-hardened processors clusters in Taiwan and South Korea, creating single-source vulnerability for mission-critical components.
- Cybersecurity Certification Friction:Germany's BAAINBw imposes country-specific vetronics security protocols that fragment qualification pathways for multinational suppliers.
- Thermal Management Material Costs:Gallium nitride and silicon carbide substrates for power electronics face price volatility from rare earth processing bottlenecks.
Strategic Opportunities
- Poland's Defense Modernization:The Polish military's accelerated armored vehicle procurement creates immediate demand for integrated command-and-control suites from qualified NATO suppliers.
- AI-Enabled Predictive Maintenance:Machine learning algorithms applied to vehicle health monitoring are converging with existing sensor networks to enable condition-based sparing.
- EU Defense Industrial Strategy:Cross-border consortium requirements for major programs open qualification pathways for mid-tier vetronics integrators previously excluded from national tenders.
Industry Challenges
- MOSA Implementation Complexity:Retrofitting open-architecture interfaces into legacy vehicle fleets demands sustained engineering investment without immediate procurement offsets.
- Secure Software Development Workforce Scarcity:Defense-cleared firmware engineers with MIL-STD-882 safety-critical experience command premium compensation that compresses program margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Vetronics Market |
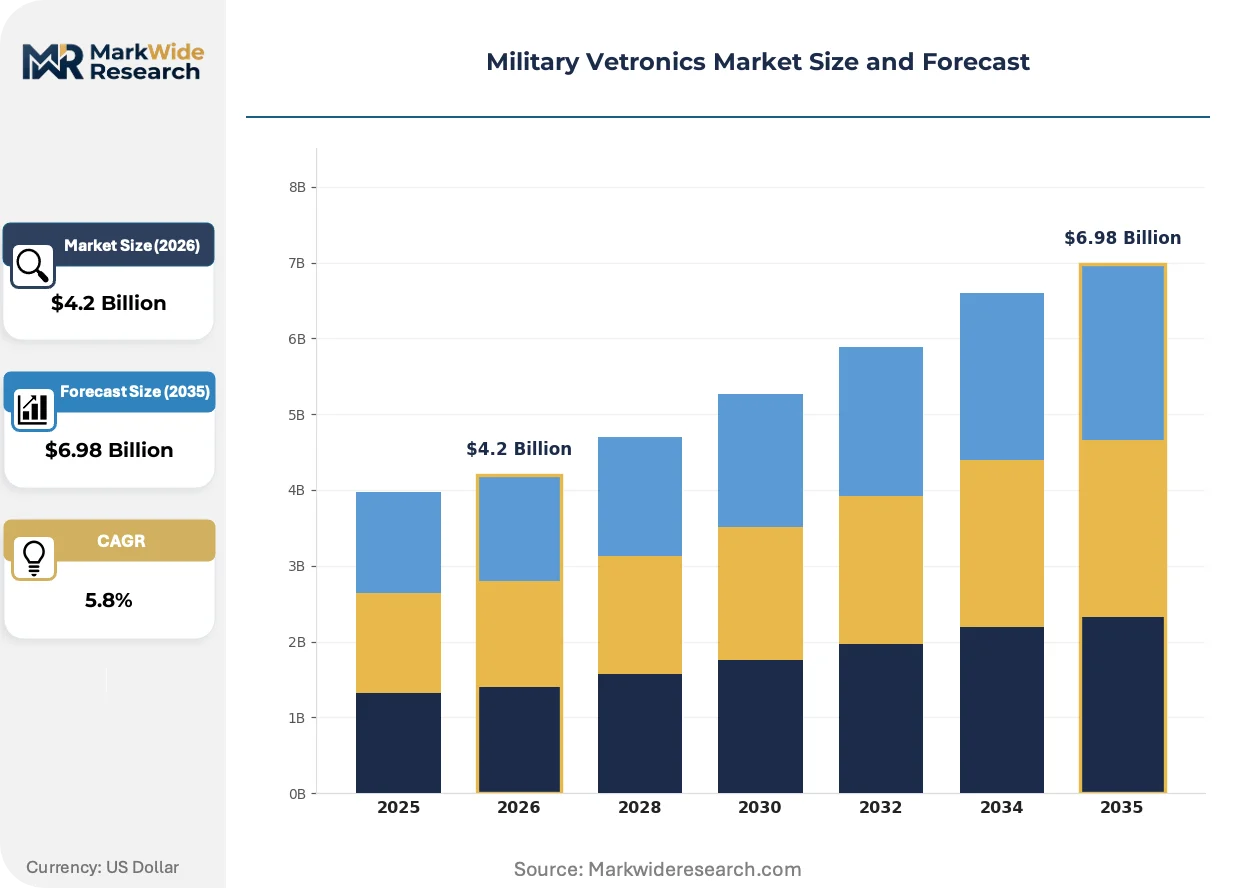
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Command Control Systems, Communication Systems, Navigation Systems, Surveillance Systems Technology: Software-Defined Radio, Advanced Sensor Fusion, Integrated Modular Avionics, Autonomous Systems End User: Naval Forces, Ground Forces, Air Forces, Defense Contractors Application: Combat Operations, Training Simulations, Mobile Warfare, Situational Awareness |
| Companies Covered | General Dynamics Corporation, Rheinmetall AG, BAE Systems, Curtiss-Wright Corporation, Leonardo S.p.A, Lockheed Martin Corporation, Thales Group, Saab AB, Raytheon Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Vetronics Market Emerging Trajectories
Electronics architectures in combat vehicles are transitioning from federated subsystems toward centralized computing fabrics, compressing hardware footprints while expanding software-defined functionality.
Vehicle-mounted edge computing is converging with distributed aperture sensor networks to enable real-time threat detection without reliance on vulnerable datalinks to remote command nodes. Army PEO Ground Combat Systems is accelerating adoption of this architecture across next-generation combat vehicle prototypes. The structural consequence is collapsing traditional boundaries between computing, communications, and sensor processing hardware tiers.
REACH regulation in Europe is restricting hexavalent chromium and cadmium in printed circuit board finishes, forcing suppliers to qualify alternative surface treatments for military-grade reliability. German and French defense procurement agencies are incorporating these material restrictions into technical specifications ahead of broader industrial deadlines. Component manufacturers serving Bundeswehr programs are responding by accelerating tin-bismuth and electroless nickel immersion gold plating line conversions.
Allied defense ministries are consolidating vetronics procurement under platform prime contractors rather than direct subsystem competitions, concentrating supplier selection authority with fewer decision-makers. Tier-two electronics houses accustomed to direct military sales are adapting through exclusive teaming arrangements with tracked and wheeled vehicle manufacturers. This concentration is most visible in Germany's defense industrial corridor, where Rheinmetall and Krauss-Maffei Wegmann now control vetronics integration scope for all major land programs.
Military Vetronics Market Segmentation
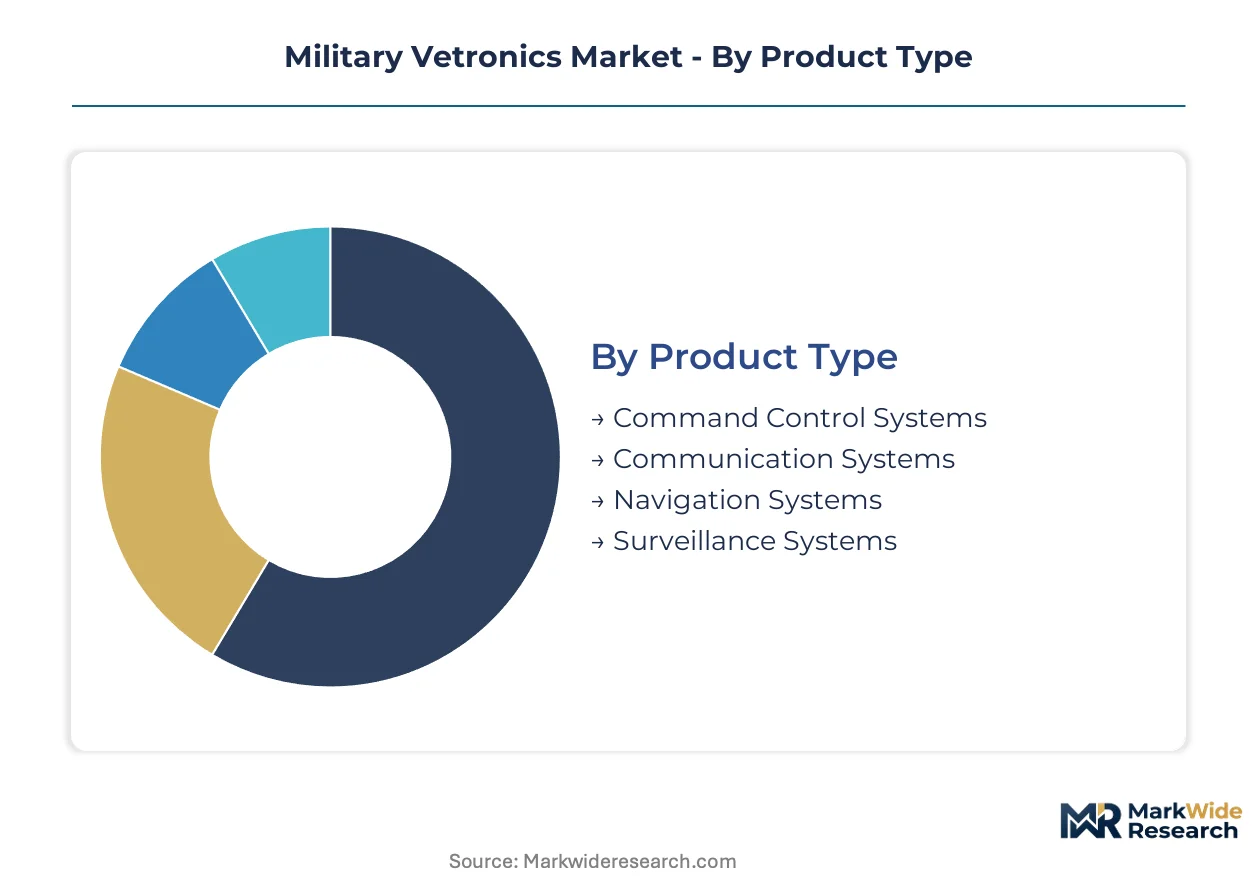
Segmentation in military vetronics reveals how procurement priorities diverge across platform types and operational doctrines. Defense ministries allocate budgets differently for legacy fleet upgrades versus next-generation autonomous platforms, creating distinct competitive arenas for subsystem suppliers.
Product Type:
Standardization dominates at the chassis-integration layer while customization intensifies at the mission-system tier across this category.
- Command Control Systems:These architectures integrate vehicle management computers, crew displays, and fire-control interfaces into unified processing fabrics. Demand concentrates in German and Polish tracked vehicle modernization programs where BAAINBw mandates NATO STANAG 4694 interoperability for cross-border coalition operations.
- Communication Systems:Software-Defined Radio cores with programmable waveforms enable spectrum agility without hardware replacement. US Army PEO Ground Combat Systems procurement is accelerating MOSA-compliant radio suites for armored brigade combat teams, driven by electromagnetic spectrum contention with near-peer adversaries.
- Navigation Systems:GPS-denied positioning using inertial measurement units and celestial references.
- Surveillance Systems:Distributed aperture electro-optical and infrared sensor networks for 360-degree threat detection.
Leading the category by volume: Command Control Systems. Growing fastest: Surveillance Systems.
Technology:
Maturity gradients separate proven battlefield electronics from experimental autonomous architectures in this grouping.
- Software-Defined Radio:Programmable waveform processors enable rapid cryptographic and frequency hopping updates without platform recertification. Recurring engineering revenue from waveform upgrades sustains contractor margins across US and German land force procurement cycles.
- Autonomous Systems:Edge-computing modules for unmanned ground vehicle navigation and threat response without human-in-the-loop latency. German Rheinmetall and US Army RCCTO programs are expanding sensor fusion computing demand for robotic combat vehicle prototypes.
- Advanced Sensor Fusion:Multi-spectral data correlation algorithms for target identification.
- Integrated Modular Avionics:Shared computing resources across historically separate avionics functions.
Highest revenue capture: Software-Defined Radio. Steepest expansion trajectory: Autonomous Systems.
End User:
Procurement authority concentration varies sharply between service branches and prime contractor intermediaries.
- Ground Forces:Armored vehicle fleets generate sustained demand for shock-hardened computing and thermal-managed power electronics. NATO allies' tracked vehicle procurement in Germany, Poland, and the United Kingdom is driving integrated vetronics suite competitions with national industrial participation requirements.
- Defense Contractors:Platform prime contractors increasingly consolidate subsystem selection authority, forcing tier-two electronics houses into exclusive teaming arrangements. This concentration is most visible in Germany's defense industrial corridor where Rheinmetall and Krauss-Maffei Wegmann control vetronics integration scope.
- Naval Forces:Maritime patrol craft and amphibious vehicle electronics with salt-spray hardening.
- Air Forces:Rotary-wing and close air support platform mission computers.
Dominant procurement volume: Ground Forces. Gaining share fastest: Defense Contractors as integration gatekeepers.
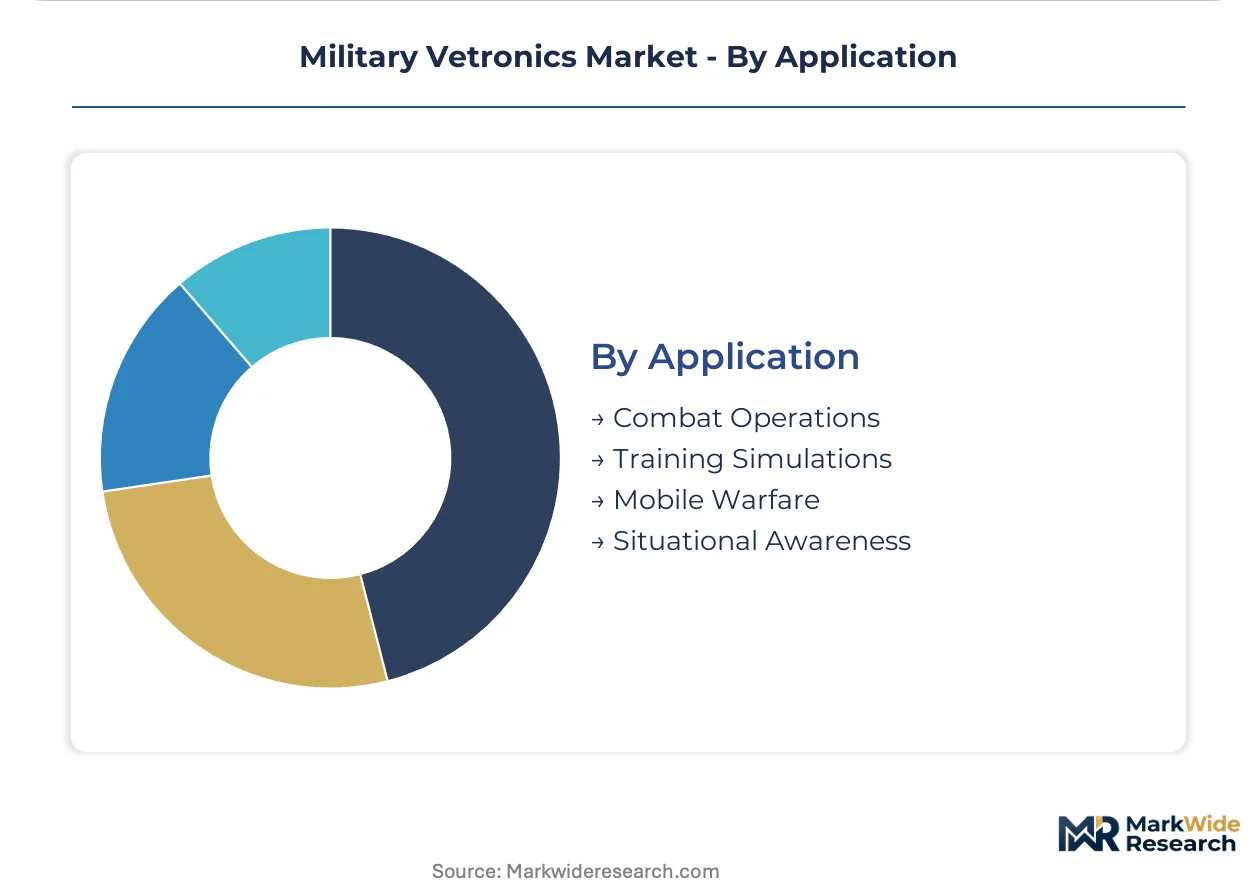
Application:
Operational tempo and safety-criticality differentiate hardware specifications across mission profiles.
- Combat Operations:Full-spectrum hardened electronics meeting MIL-STD-810 shock and MIL-STD-461 electromagnetic compatibility. US Army Abrams and Bradley fleet sustainment programs maintain steady demand for spares and incremental capability inserts.
- Situational Awareness:Real-time battlefield visualization fusing onboard sensors with tactical datalink feeds. Distributed aperture networks and edge-processing architectures are collapsing traditional boundaries between computing and sensor hardware tiers in next-generation vehicle prototypes.
- Training Simulations:High-fidelity crew procedure trainers with identical interface replication.
- Mobile Warfare:Rapidly deployable wheeled vehicle electronics with reduced thermal signatures.
Primary revenue anchor: Combat Operations. Expanding most quickly: Situational Awareness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of military vetronics concentrates in Germany and the United States, while consumption expands across NATO allies modernizing armored vehicle fleets. The United States dominates open-architecture computing development, whereas Germany anchors integrated turret electronics for European land forces. Poland and the United Kingdom represent the fastest-growing procurement markets as defense budgets accelerate tracked vehicle replacement programs.
United States
The US Army's PEO Ground Combat Systems drives MOSA-compliant vetronics procurement for Abrams and Bradley fleet modernization. The Department of Defense mandates open-architecture interfaces through acquisition directives, dismantling proprietary subsystem lock-in. Defense contractors cluster around Michigan's automotive-electronics corridor and Texas defense technology hubs, where ruggedized computing development supports armored brigade combat teams.
Germany
Bundeswehr tracked vehicle programs generate sustained demand for command-and-control modules with NATO STANAG 4694 interoperability. BAAINBw imposes country-specific cybersecurity certifications that fragment qualification pathways for multinational suppliers. Rheinmetall AG and Krauss-Maffei Wegmann anchor production in the defense industrial corridor spanning Düsseldorf and Munich, controlling vetronics integration scope for all major land programs.
Poland
Accelerated armored vehicle procurement creates immediate demand for integrated vetronics suites from qualified NATO suppliers. The Polish Ministry of National Defense prioritizes coalition interoperability standards for regional deterrence posture. Industrial partnerships concentrate in Warsaw and Poznań, where local content requirements shape foreign supplier teaming arrangements for command-and-control system competitions.
United Kingdom
BAE Systems sustains integrated turret electronics programs across multiple NATO platforms from its UK manufacturing footprint. Ministry of Defence procurement emphasizes sovereign capability preservation alongside allied interoperability commitments. Defense electronics activity clusters in Lancashire and Gloucestershire, where platform prime contractors consolidate subsystem selection authority previously held by tier-two houses.
France
SCORPION program modernization drives demand for vetronics architectures supporting network-centric warfare concepts. The Direction Générale de l'Armement enforces European defense industrial participation requirements for major land system acquisitions. Thales Group and Safran Electronics anchor production in the Île-de-France and Provence-Alpes-Côte d'Azur regions, where sensor fusion computing development supports next-generation combat vehicle prototypes.
Military Vetronics Market Vendor Landscape
The competitive structure tilts toward platform prime contractors consolidating subsystem selection authority, forcing tier-two electronics houses into exclusive teaming arrangements. Defense ministries increasingly delegate vetronics procurement decisions to tracked and wheeled vehicle manufacturers rather than holding direct subsystem competitions. Two archetypes dominate: integrated platform primes controlling end-to-end electronics suites, and specialized computing houses occupying thermal-management and edge-processing niches. Competitive moves center on MOSA compliance certification races and exclusive national industrial partnerships securing program access.
Among transatlantic defense contractors, General Dynamics Corporation, Rheinmetall AG, and BAE Systems exemplify the platform prime archetype with captive vetronics integration capabilities. Curtiss-Wright Corporation occupies a specialist position representing the ruggedized computing tier. These entities anchor the supplier landscape through contrasting strategic postures: the primes leverage vehicle manufacturing scale to capture electronics scope, while the computing specialist maintains position through thermal-management and shock-hardening technical differentiation.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Rheinmetall AG |
| BAE Systems |
| Curtiss-Wright Corporation |
| Leonardo S.p.A |
| Lockheed Martin Corporation |
| Thales Group |
| Saab AB |
| Raytheon Company |
| Others |
Supply Flow & Price Mechanics
MOSA compliance mandates from the US Army's PEO Ground Combat Systems are forcing subsystem suppliers to requalify open-architecture interfaces, compressing margins on legacy contracts while rewarding early certification investments with pricing power on new platform competitions.
Pricing Analysis
Margin tightening in ruggedized computing tiers reflects gallium nitride substrate cost volatility and premium compensation demands for defense-cleared firmware engineers. Three-tier pricing structure across MOSA-certified, STANAG-compliant, and legacy proprietary levels separates contractors by interoperability qualification. Cost-down pressure on thermal-management subsystems accelerates because prime contractors consolidate vetronics scope under platform manufacturing contracts. Ground Forces procurement offices exhibit highest price sensitivity on spares and incremental upgrades, while autonomous vehicle programs show lowest sensitivity for sensor fusion computing modules.
Supply Chain Analysis
Dual-sourcing requirements for radiation-hardened processors mandate qualification pathways across Taiwan, South Korea, and the United States, though advanced node fabrication remains concentrated in East Asian foundries. Mission-critical component supply draws from rare earth processing facilities in China and gallium nitride epitaxy houses in Japan and Germany. Single-source vulnerability for semiconductor substrates creates exposure to geopolitical logistics chokepoints. Distribution runs through prime contractor integration facilities in Germany's defense industrial corridor and US defense technology hubs, with tier-two electronics houses adapting through exclusive teaming arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive command-and-control module production is emerging as the decisive competitive lever, with platform primes capturing electronics scope through vehicle manufacturing scale while specialized computing houses defend position through thermal-management technical differentiation.
For Market Incumbents: To counter prime contractor consolidation of subsystem selection authority, BAE Systems and Rheinmetall AG are deepening in-house production of fire-control interfaces and command modules. Incumbents should accelerate MOSA compliance certification races to secure exclusive national industrial partnerships with Bundeswehr and US Army procurement channels. Backward integration into gallium nitride power electronics manufacturing offers margin defense against substrate price volatility. For New Entrants and Emerging Players: AI-enabled predictive maintenance algorithms present a technology-first wedge for mid-tier integrators excluded from national tracked vehicle tenders. Poland's accelerated armored vehicle procurement offers the most penetrable geography for qualified NATO suppliers establishing local content partnerships. A go-to-market angle through exclusive teaming with platform prime contractors in Warsaw and Poznań clusters bypasses direct subsystem competition barriers. For Investors and Strategic Acquirers: The window for entry favors ruggedized computing specialists with thermal-management IP and existing defense security clearances. Long-term viability hinges on positioning within unmanned ground vehicle sensor fusion supply chains as autonomous programs expand. The signal to watch is EU Defense Industrial Strategy cross-border consortium requirements altering qualification pathways for mid-tier integrators.| Strategic Initiative | Industry Significance |
|---|---|
| MOSA Compliance Certification | US Army PEO Ground Combat Systems mandates open-architecture interfaces that prevent vendor lock-in across vehicle electronics suites. |
| Backward Integration into Power Electronics | Gallium nitride substrate supply control insulates margins from rare earth processing bottlenecks in China. |
| Exclusive National Industrial Partnership | BAAINBw cybersecurity certifications fragment qualification pathways, rewarding early German market entrants with program access. |
| AI-Enabled Predictive Maintenance Platform | Machine learning convergence with existing sensor networks enables condition-based sparing contracts with NATO land forces. |
| Cross-Border Consortium Formation | EU Defense Industrial Strategy requirements open pathways for mid-tier integrators previously excluded from national tenders. |
Methodological Framework
Document review covered defense procurement databases, SEC 10-K filings, and Bundeswehr technical specifications, complemented by interviews with program managers at US Army PEO Ground Combat Systems, BAAINBw certification officers, and platform prime contractor procurement directors. Secondary validation drew from NATO STANAG documentation, EU Defense Industrial Strategy publications, and customs trade data on gallium nitride substrate flows. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Market size and growth trajectory outputs across the projection horizon reflect segment-level modeling across product type, technology maturity, end-user procurement authority, and application criticality. CAGRs were derived from procurement cycle analysis, fleet modernization schedules, and unmanned platform program acceleration curves. Industry-specific forecast inputs incorporated electromagnetic spectrum contention intensity and REACH regulation material restriction timelines affecting printed circuit board finishes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or rapid MOSA directive enforcement acceleration. Forecasts reflect assumptions on NATO ally defense budget trajectories and autonomous vehicle program funding continuity. A model refresh is warranted upon material change in EU Defense Industrial Strategy implementation or BAAINBw cybersecurity certification requirement revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Military Load Carriage System Market