
 Military Rifle Market | 2026-2036
Military Rifle Market Size, Share, and Industry Trends Forecast 2026-2036
Military Rifle Market Foresight
Modular weapon architecture is reshaping how military rifles are designed, manufactured, and fielded across defense forces worldwide. Sig Sauer leverages its MCX platform ecosystem to compete across multiple NATO tender categories with interchangeable caliber systems. FN Herstal anchors European supply chains through its SCAR program and sustained production contracts with Belgian and French armed forces. Colt's Manufacturing Company specializes in legacy platform sustainment while navigating competition from more adaptable rivals.
A military rifle is a shoulder-fired, rifled-barrel small arm chambered for intermediate or full-power cartridges, typically operating through gas-piston or direct-impingement cycling systems to deliver semi-automatic or selective-fire capability for individual infantry engagement. Gas-operated systems dominate procurement volumes due to proven reliability in adverse conditions and established maintenance infrastructure across major militaries. The assault rifle segment leads absolute unit demand driven by standard-issue infantry modernization, while designated marksman rifles represent the fastest-growing product category as forces prioritize precision engagement at extended ranges without dedicated sniper assets.
The U.S. Army's Product Manager Individual Weapons, NATO's Standardization Agreement 4694, and the EU's REACH chemicals framework collectively shape material specifications, interoperability mandates, and surface treatment requirements for rifle manufacturers seeking military contracts. These regulatory layers create compliance barriers that favor established suppliers with dedicated certification teams and testing facilities. Stakeholders must monitor how next-generation squad weapon requirements in the United States and allied nations redefine caliber standards and ammunition logistics chains.
Market Dynamics
Modular weapon architecture is compressing replacement cycles across NATO forces, with interchangeable upper receivers and caliber conversion kits allowing single-platform procurement to cover multiple mission profiles previously requiring distinct inventories.
Growth Catalysts
- NATO Standardization Agreement 4694:This interoperability mandate accelerates cross-border tender participation for manufacturers with certified modular systems, consolidating procurement volumes around qualified suppliers.
- Special Operations forces:Elite units across member states are expanding orders for adaptable weapon systems capable of rapid caliber and barrel configuration changes without armorer support.
- Cerium-based surface treatments:REACH regulation compliance is pulling investment into hexavalent chromium alternatives, creating first-mover advantages for suppliers with qualified coating lines.
Market Restraints
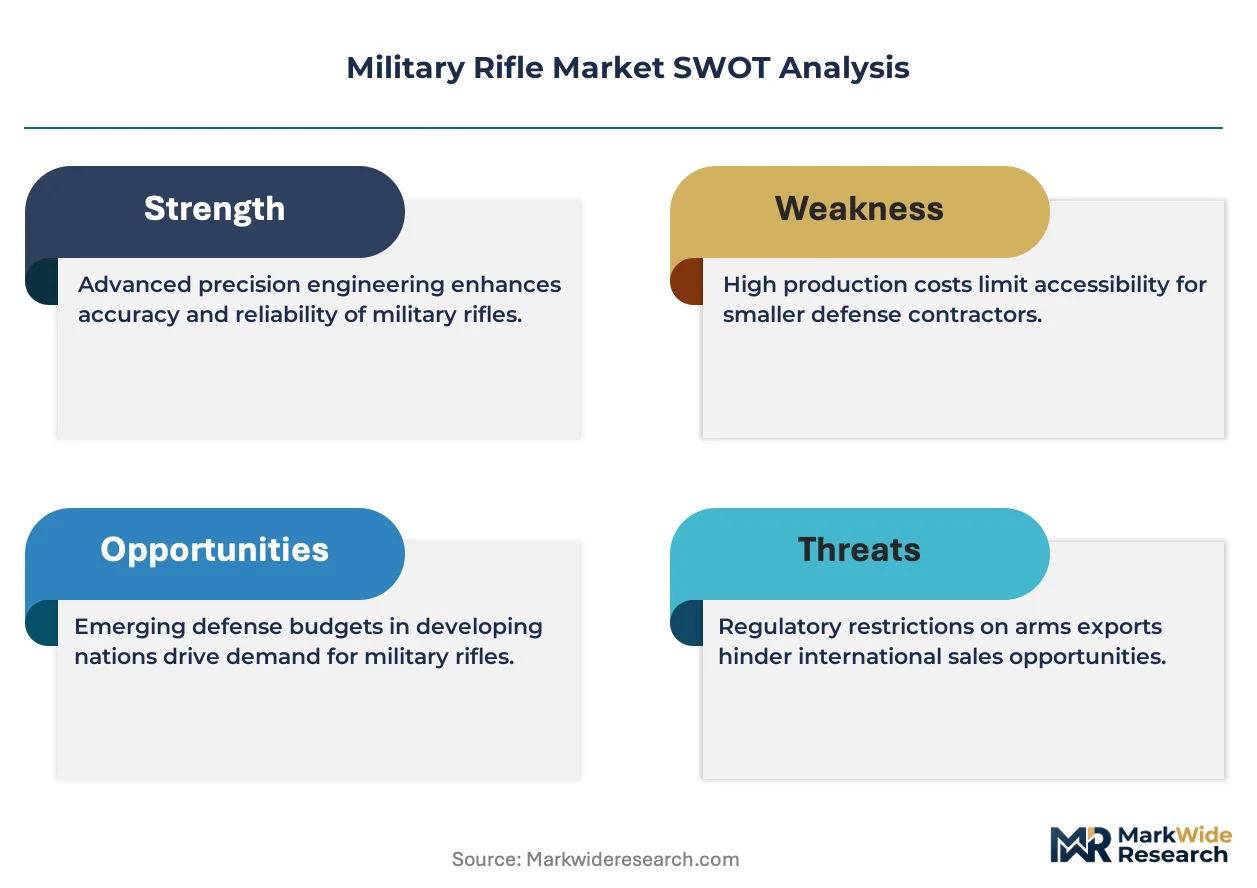
- Tungsten supply concentration:China controls approximately 80% of global tungsten processing capacity, exposing armor-piercing ammunition and penetrator manufacturers to export restriction risk.
- Chromate conversion coating phase-out:EU Green Deal timelines force immediate capital reallocation toward cerium-based alternatives before qualification data matures, compressing margin recovery windows.
- Direct-impingement reliability ceiling:Gas-piston systems demonstrate superior performance in sand and arctic conditions, limiting contract eligibility for manufacturers without piston platform offerings.
Strategic Opportunities
- Designated marksman rifle expansion:Infantry squads are adding precision engagement capability without dedicated sniper assets, opening unit-level procurement channels previously closed to standard-issue suppliers.
- India's defense indigenization:Make-in-India procurement rules and offset requirements create partnership entry points for foreign manufacturers willing to establish local assembly and testing facilities.
- Digital optics integration:Convergence of ballistic computers, thermal modules, and networked target sharing is enabling premium pricing for weapon systems with integrated rail-mounted electronics architectures.
Industry Challenges
- ITAR compliance workforce scarcity:Licensed manufacturing and technical data handling require cleared personnel pools that defense industrial bases struggle to replenish against commercial sector competition.
- Legacy M4 platform sustainment:Decades of accumulated technical data packages, armorer training curricula, and depot-level repair infrastructure create switching friction even where superior alternatives exist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Rifle Market |
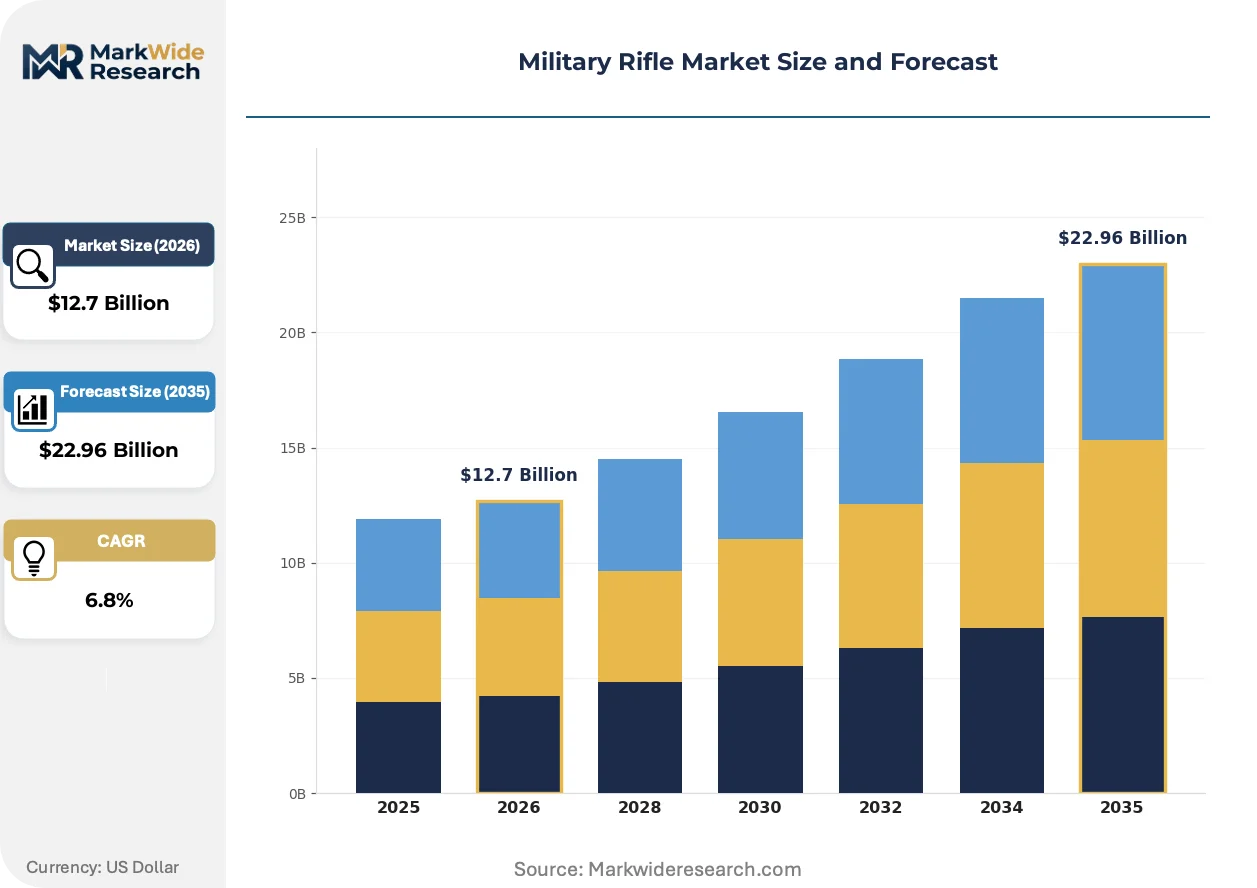
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assault Rifle, Bolt-Action Rifle, Carbine, Designated Marksman Rifle Technology: Gas-Operated, Manual Action, Recoil-Operated, Lever-Action End User: Military Forces, Law Enforcement, Special Operations, Private Security Application: Combat, Training, Paramilitary Operations, Marksmanship Competitions |
| Companies Covered | Colt’s Manufacturing Company, Sig Sauer, FN Herstal, Daniel Defense, Adcor Defense, Arsenal, Bravo Company, Adams Arms, Taurus International Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Rifle Market Shifts & Advancements
Weapon system digitization and environmental compliance are converging to redefine manufacturing processes, procurement evaluation criteria, and field maintenance protocols across military rifle supply chains.
Additive manufacturing of titanium receiver components is rendering obsolete traditional subtractive machining for low-volume special operations variants. Naval Special Warfare and British Special Boat Service units are field-testing printed lower receivers with embedded sensor channels. This distributed production capability is compressing prototype-to-field timelines from years to months for specialized configurations.
REACH regulations and the EU Green Deal are mandating chromate-free surface treatments across all defense equipment categories by 2030. Manufacturers with qualified cerium-based coating lines gain preferential scoring in French and Belgian tender evaluations. German and Dutch procurement offices are accelerating supplier audits to verify hexavalent chromium elimination from supply chains.
Unit-level purchasing authority for precision optics and accessories is fragmenting traditional centralized small arms procurement. U.S. Army and Marine Corps squads now select rail-mounted sights through battalion-level discretionary budgets rather than divisional quartermaster allocation. This decentralization is visible across NATO expeditionary forces, where mission-specific kitting replaces standard table-of-equipment distribution.
Military Rifle Market Segmentation
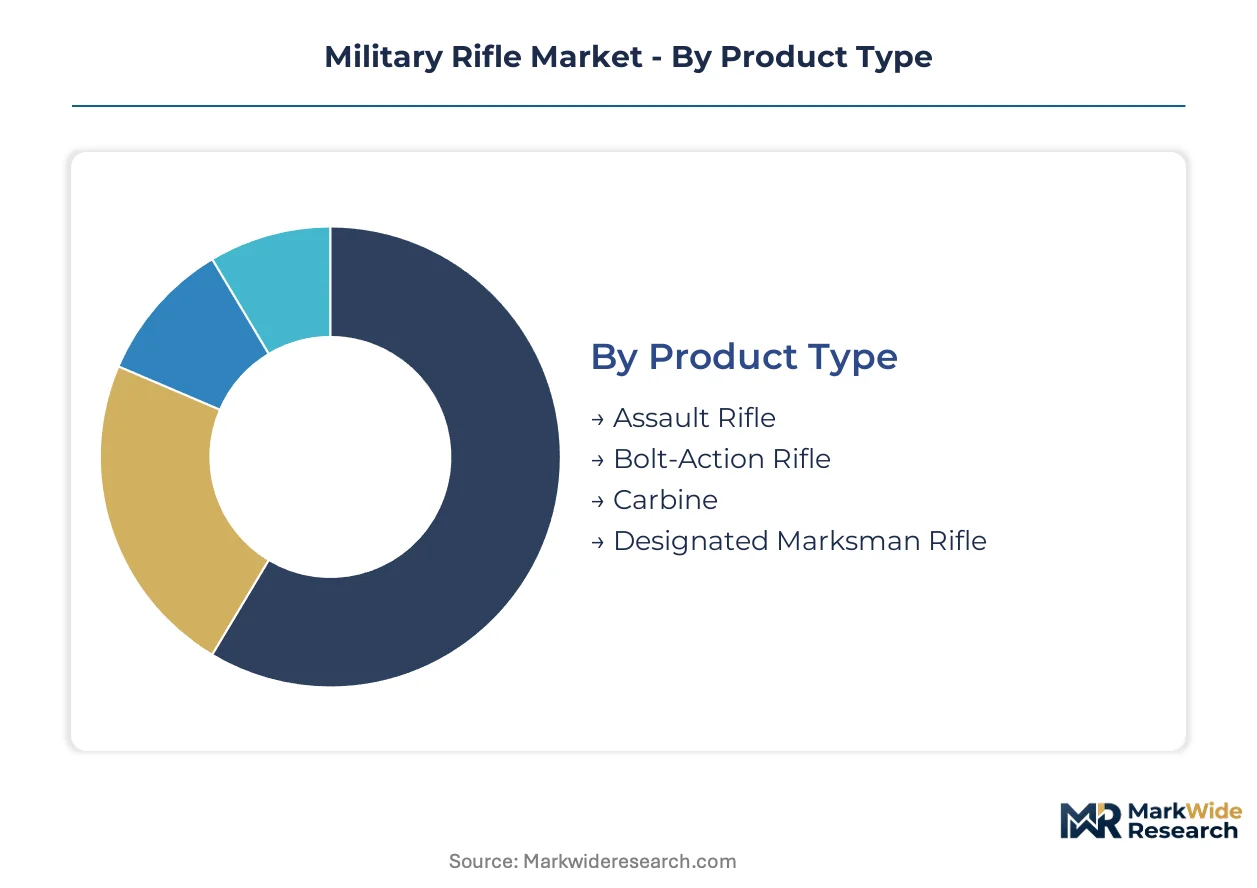
Segmentation in military rifles reflects divergent operational requirements across infantry roles, procurement budgets, and mission profiles. Distinct technology choices and end-user specifications create non-overlapping supply chains with specialized certification barriers.
Product Type:
Mature platforms dominate standard-issue procurement while emerging configurations capture modernization budgets.
- Assault Rifle:Intermediate-cartridge selective-fire weapons form the backbone of infantry small arms procurement. U.S. Army and Marine Corps replacement cycles for legacy M4 platforms concentrate demand volumes here, though modular competitors erode incumbent positions.
- Designated Marksman Rifle:Semi-automatic precision systems bridge the gap between standard rifles and dedicated sniper platforms. NATO expeditionary forces are adding these to squad-level tables of equipment, driving unit procurement outside traditional centralized channels.
- Carbine:Compact variants optimize for vehicle-borne and close-quarters operations.
- Bolt-Action Rifle:Manual-cycle precision systems retain niche roles in specialized sniper applications.
Assault rifles retain volume leadership; designated marksman rifles hold the steepest expansion curve.
Technology:
Cost tiers separate proven military-grade systems from legacy or marginal alternatives.
- Gas-Operated:Gas-piston and direct-impingement cycling systems deliver reliable semi-automatic or selective-fire capability. Sand and arctic testing data favor piston configurations, disqualifying direct-impingement offerings from certain NATO tender categories.
- Manual Action:Bolt-action and break-action systems serve precision applications requiring absolute mechanical simplicity. Special Operations forces accept the rate-of-fire trade-off for enhanced accuracy and reduced maintenance signatures in extended deployments.
- Recoil-Operated:Delayed-blowback and short-recoil mechanisms appear in limited specialized applications.
- Lever-Action:Historical cycling technology persists only in ceremonial or training contexts.
Gas-operated systems retain volume leadership; manual action configurations hold the steepest expansion curve within precision segments.
End User:
Customer type determines specification stringency, certification depth, and contract duration.
- Military Forces:National defense establishments drive standardized platform procurement with decade-long replacement horizons. Army and Marine Corps modernization programs in the United States anchor global demand volumes for next-generation squad weapons.
- Special Operations:Elite units prioritize modularity and rapid reconfiguration over standardization. NATO member state SOF expansion of modular weapon orders creates premium pricing opportunities for qualified suppliers.
- Law Enforcement:Domestic security agencies adopt militarized platforms with reduced selective-fire requirements.
- Private Security:Commercial contractors operate under less restrictive procurement frameworks with shorter evaluation cycles.
Military forces retain volume leadership; special operations holds the steepest expansion curve.
Application:
Application scope ranges from high-intensity combat to non-lethal training environments.
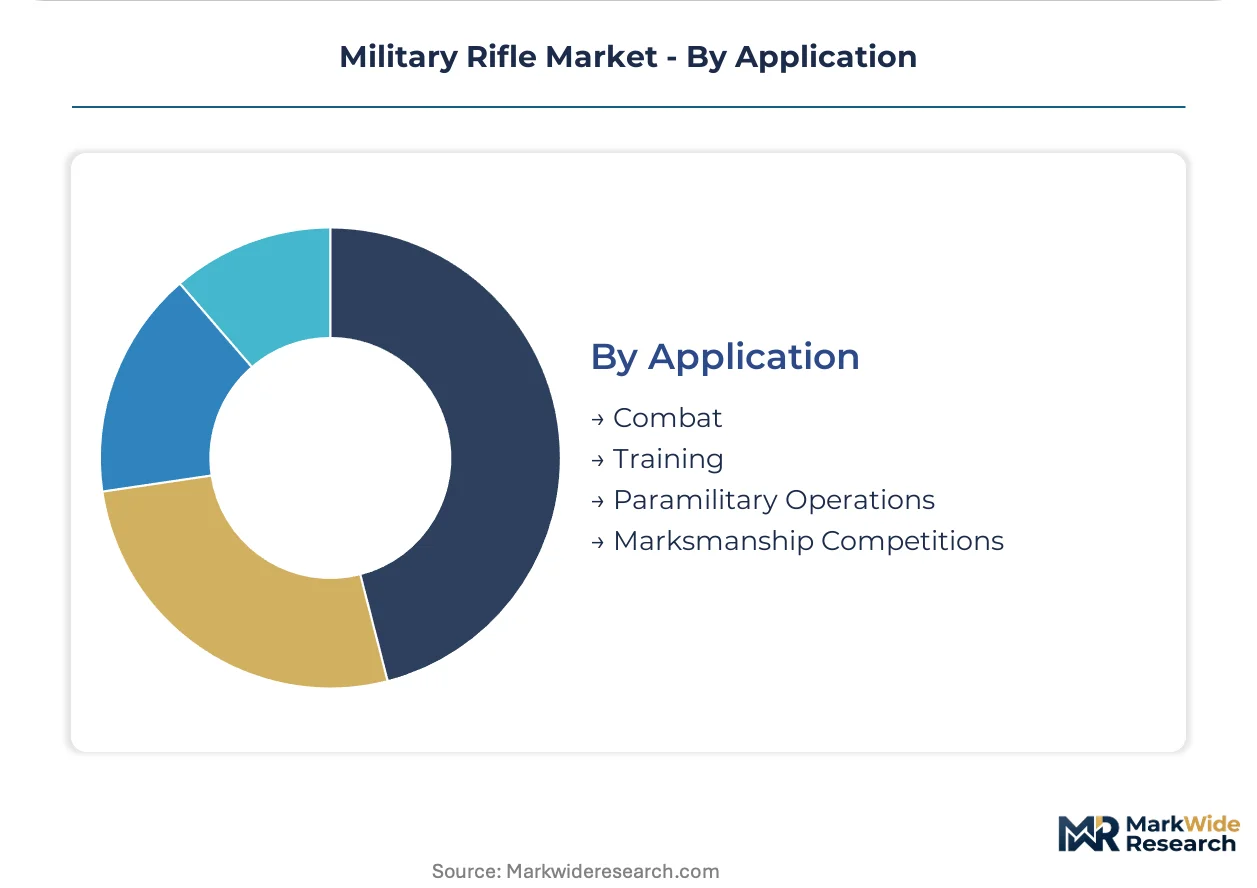
- Combat:Live-fire operational employment demands full-spectrum reliability across environmental extremes. REACH-compliant surface treatments and NATO Standardization Agreement 4694 interoperability mandates shape procurement evaluation criteria.
- Training:Force preparation consumes substantial ammunition volumes and accelerates weapon wear cycles. Simulation-integrated platforms with embedded sensor architectures are gaining procurement priority in advanced militaries.
- Paramilitary Operations:Hybrid security tasks require flexible rules-of-engagement configurations.
- Marksmanship Competitions:Precision shooting sports drive specialized accuracy specifications with limited procurement scale.
Combat applications retain volume leadership; training systems hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National defense modernization programs concentrate procurement authority within defense ministries and special operations commands. Buyers prioritize NATO interoperability certifications and REACH-compliant manufacturing processes when evaluating suppliers.
United States
The Army's Product Manager Individual Weapons and Marine Corps Systems Command drive replacement cycles for legacy M4 platforms. ITAR regulations govern technical data handling and licensed manufacturing arrangements. Connecticut and New Hampshire host established defense industrial clusters where armorer training infrastructure and depot-level repair facilities sustain incumbent platform ecosystems.
Germany
The Bundeswehr's special operations community and conventional infantry modernization programs generate dual demand streams for modular weapon systems. ECHA enforcement of REACH Annex XVII restrictions on hexavalent chromium accelerates supplier qualification audits. Oberndorf and Suhl maintain precision manufacturing traditions with specialized coating line investments for cerium-based surface treatment compliance.
France
The Direction Générale de l'Armement oversees centralized procurement with increasing emphasis on expeditionary force modularity requirements. ANSM and environmental regulators coordinate defense exemptions within broader EU Green Deal chemical phase-out timelines. The Saint-Étienne armament cluster transitions legacy forging capacity toward additive manufacturing qualification for special operations variants.
Belgium
Special Operations Command and conventional force procurement offices operate distinct evaluation frameworks for weapon system tenders. ECHA compliance verification precedes contract award eligibility for surface treatment subcontractors. The Herstal industrial zone concentrates NATO-standard small arms production with integrated ballistic testing and certification facilities.
India
Army and paramilitary force modernization programs create sustained demand volumes under Make-in-India indigenization mandates. BIS certification and DGFT offset requirements structure foreign manufacturer entry pathways. Uttar Pradesh and Madhya Pradesh defense corridors attract joint venture assembly investments with phased technology transfer obligations.
Military Rifle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement categories. Established defense contractors with NATO certification infrastructure and cleared technical data handling capabilities occupy premium contract positions. Three archetypes dominate: legacy platform sustainment specialists, modular ecosystem integrators, and precision manufacturing subcontractors. Competitive moves center on qualification data package accumulation and coating line certification investments.
Within the modular ecosystem tier, Sig Sauer and FN Herstal exemplify platform-architecture strategies with interchangeable caliber systems. Colt's Manufacturing Company anchors legacy sustainment contracting. These three occupy positions spanning NATO tender categories from standard-issue infantry procurement to special operations rapid-reconfiguration requirements.
| Leading Market Players |
|---|
| Colt's Manufacturing Company |
| Sig Sauer |
| FN Herstal |
| Daniel Defense |
| Adcor Defense |
| Arsenal |
| Bravo Company |
| Adams Arms |
| Taurus International Manufacturing |
| Others |
Supply & Pricing Matrix
Tungsten supply concentration in China determines both margin compression in armor-piercing ammunition tiers and the geographic diversification imperatives now reshaping NATO procurement sourcing. REACH-mandated coating transitions add qualification cost layers that widen pricing spreads between cerium-certified suppliers and legacy chrome-plated alternatives.
Pricing Analysis
Cost-plus contracts with steel and rare-earth indexation dominate military rifle procurement, insulating prime contractors from raw material volatility while passing through qualified coating line investments. Price differentiation rests on NATO Standardization Agreement 4694 certification grade and after-sales depot support bundling. Cost compression in standard-issue assault rifle tiers is intensifying because modular platform competitors erode incumbent M4 sustainment margins. Law enforcement agencies exhibit highest price sensitivity due to constrained municipal budgets, while special operations commands prioritize rapid-reconfiguration capability over unit cost.
Supply Chain Analysis
Supplier-financing facilities with 180-day payment terms have become standard for barrel forging and precision optics subcontractors serving defense primes. Manufacturing concentrates in the United States, Belgium, and Germany, with raw material dependencies spanning tungsten for penetrators, chromium alternatives for REACH compliance, and titanium for additive-manufactured receivers. Single-source vulnerability in Chinese tungsten processing exposes armor-piercing ammunition supply chains to export restriction risk. Distribution runs through national armament directorates and special operations command procurement offices with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military rifle market sits in a cyclical recovery phase driven by NATO-wide legacy platform replacement programs. Defense modernization budgets across member states are accelerating procurement velocity after procurement freezes.
For Market Incumbents: Pre-empt modular platform displacement by accelerating cerium-based coating line certification before ECHA enforcement windows tighten. Anchor positions through backward integration into barrel forging capacity in Oberndorf and Suhl industrial clusters. Defend against Sig Sauer ecosystem expansion by locking multi-year special operations framework agreements with embedded caliber-conversion kit provisioning.
For New Entrants and Emerging Players: Pursue India's Make-in-India joint venture pathways in Uttar Pradesh and Madhya Pradesh defense corridors, where BIS certification and DGFT offset requirements create partnership entry points. Target designated marksman rifle procurement channels as the most penetrable segment, where unit-level purchasing authority fragments traditional centralized tender barriers. Lead with simulation-integrated platforms featuring embedded sensor architectures for training system tenders.
For Investors and Strategic Acquirers: The market sits at a modernization-investment phase that favors modular-ecosystem integrators with NATO qualification data packages. Long-term viability over the next decade rests on REACH-compliant manufacturing capabilities and additive manufacturing qualification for special operations variants. Watch ECHA enforcement acceleration on hexavalent chromium as the signal indicating which coating-line investments will capture preferential tender scoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Cerium-Based Coating Line Qualification | ECHA REACH Annex XVII compliance secures preferential scoring in French and Belgian tender evaluations. |
| Modular Platform Ecosystem Expansion | Interchangeable caliber systems capture multiple NATO tender categories with single-platform procurement. |
| Additive Manufacturing Qualification | Titanium receiver printing compresses special operations prototype-to-field timelines from years to months. |
| India Joint Venture Establishment | Make-in-India assembly investments satisfy BIS certification and DGFT offset requirements for army modernization. |
| Digital Optics Integration | Rail-mounted ballistic computers and thermal modules enable premium pricing for networked target-sharing architectures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, armament directorate technical leads, special operations weapons program managers, and coating line engineering specialists. Secondary validation drew from NATO Standardization Agreement documentation, ECHA REACH regulatory filings, U.S. Army Product Manager Individual Weapons program disclosures, and EU Green Deal implementation timelines. Bottom-up platform shipment estimates triangulated against top-down defense budget allocation analysis across the analysis window.
Calibration against historical replacement cycle patterns and procurement award announcements anchored the analytical framework. Segmentation modeling spanned product type, technology configuration, end-user category, and application scope throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to platform adoption trajectories, with inputs including special operations force expansion rates and REACH compliance investment schedules.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriations or rare-earth export policy would shift the trajectory. Forecasts reflect documented assumptions on NATO interoperability mandates and coating qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Parachute Market