
 India Palm Oil Market | 2026-2036
India Palm Oil Market Size, Share, and Industry Trends Forecast 2026-2036
India Palm Oil Market Insights
Wholesale distributor networks across India are reshaping as bulk buyers consolidate procurement through direct mill relationships. Adani Wilmar Limited leverages its integrated crushing-refining footprint to control inland logistics costs. Godrej Agrovet anchors its position through specialty fat formulations for bakery and dairy substitutes. Ruchi Soya Industries Limited dominates the institutional channel, supplying HoReCa and packaged food manufacturers at scale.
Palm oil comprises the mesocarp extract of Elaeis guineensis, yielding a semi-solid fat with roughly 50% saturated palmitic acid and natural beta-carotene content that imparts distinctive color and oxidative stability. The oil serves primarily as a cost-effective frying medium, shortening base, and oleochemical feedstock across food and non-food industries. Refined palm oil leads volume flows due to its neutral flavor profile and extended fry-life in commercial kitchens, while palm oil derivatives command margin premiums in surfactant and cosmetic applications. The biofuels segment expands fastest as state oil marketing companies advance blending mandates, though food industry absorption still absorbs the dominant share of domestic supply.
The Food Safety and Standards Authority of India enforces maximum permissible limits for contaminants and labeling disclosures that refiners must meet before interstate shipment. Bureau of Indian Standards specifications for edible palm oil grades create entry barriers for unorganized processors lacking laboratory certification infrastructure. Stakeholders must monitor how state-level renewable energy obligations and import duty adjustments on crude versus refined palm oil reshape margin economics across the value chain.
Market Dynamics
FSSAI's tightened trans-fat limits are forcing packaged food manufacturers across Maharashtra and Gujarat to reformulate toward palm olein blends, restructuring procurement relationships between refiners and bulk buyers.
Growth Catalysts
- Blending Mandates:State oil marketing companies are advancing biofuel obligations that expand offtake for palm oil methyl ester, creating dedicated demand channels outside traditional food applications.
- FSSAI Reformulation Pressure:The regulator's reduced trans-fat thresholds in processed foods are accelerating palm olein adoption by bakery and confectionery manufacturers seeking stable frying media.
- Port-Adjacent Refining Clusters:Bulk edible oil refining capacity concentrated near western Indian port infrastructure minimizes inland logistics costs for imported crude palm oil.
Market Restraints
- Import Duty Asymmetry:India's differential tariff structure between crude and refined palm oil creates margin compression for domestic refiners when CPO prices spike.
- Supply Concentration Risk:Overreliance on Indonesian and Malaysian suppliers exposes buyers to export levy volatility and seasonal production fluctuations.
- Technical Substitution Limits:Bakery applications requiring specific crystallization profiles cannot fully replace palm stearin with liquid oils without reformulating entire product lines.
Strategic Opportunities
- Specialty Fat Formulations:Dairy substitute and vegan bakery segments present underdeveloped demand for tailored palm fractions with customized melting characteristics.
- Direct Mill Procurement:Large HoReCa chains and packaged food manufacturers are bypassing traditional distributors to negotiate volume contracts with refiners.
- PLI Scheme Alignment:India's production-linked incentive framework for food processing infrastructure supports capital investment in integrated crushing-refining assets.
Industry Challenges
- BIS Certification Timelines:Bureau of Indian Standards laboratory accreditation requirements create bottlenecks for unorganized processors seeking interstate shipment authorization.
- Reformulation Expertise Gap:Shortage of lipid chemists capable of optimizing palm olein blends for specific fry-life and texture targets delays product relaunches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Palm Oil Market |
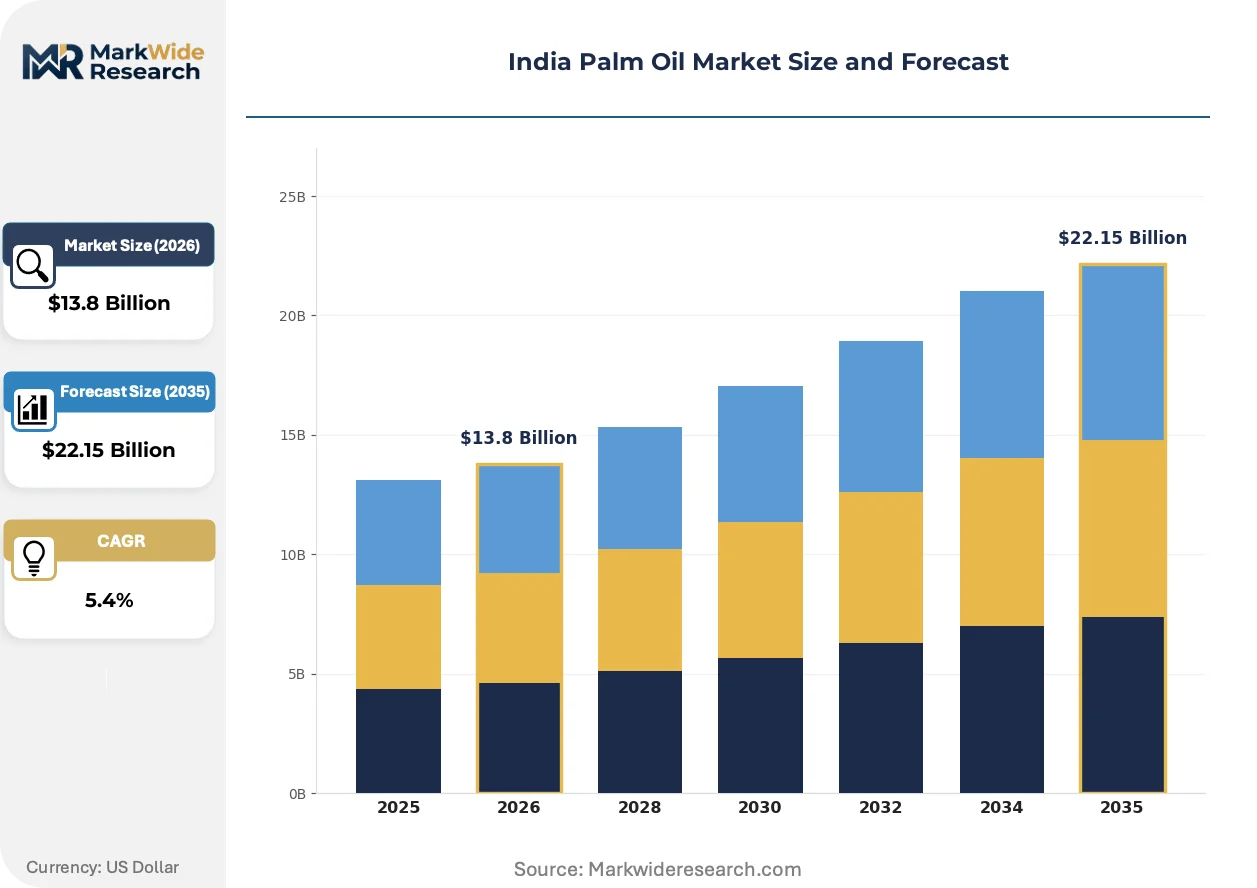
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Palm Oil, Refined Palm Oil, Palm Kernel Oil, Palm Oil Derivatives Application: Food Industry, Personal Care, Biofuels, Industrial Use End User: Food Manufacturers, Cosmetic Companies, Energy Sector, Exporters Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Godrej Agrovet, Mother Dairy Fruit & Vegetable, Adani Wilmar Limited, Oil Palm India Limited, Cofco Agri Ltd., Ruchi Soya Industries Limited, Bunge India, Marico Limited, Cargill India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Palm Oil Market Trends and Innovations
Physical refining technology and fractionation control systems are reshaping how Indian processors extract value from imported crude palm oil, enabling tighter specification matching for end-use buyers.
Membrane filtration for degumming and bleaching is migrating from European specialty refiners to mid-scale Indian processors seeking to reduce chemical usage and improve oxidative stability metrics. Packaged food manufacturers in Gujarat are piloting these systems to meet FSSAI contaminant thresholds without thermal degradation. The technology is compressing the quality gap between domestically refined and imported refined palm oil, altering procurement calculus for premium applications.
FSSAI's mandatory labeling disclosures for saturated fat content and origin traceability are compelling refiners to invest in laboratory certification infrastructure before interstate shipment authorization. The regulation's industrial consequence is accelerated consolidation among organized processors with in-house testing capabilities. Western Indian refining clusters near Mumbai and Kandla are responding fastest, leveraging existing port laboratories to shorten compliance timelines.
Consolidation among wholesale distributors is concentrating procurement leverage in the hands of bulk buyers negotiating directly with refiners. Traditional distributor networks in Maharashtra are losing volume to institutional channels serving HoReCa and packaged food manufacturers at scale. This channel disintermediation is most visible in Gujarat, where integrated food parks house co-located refining and manufacturing operations eliminating intermediate handling steps.
India Palm Oil Market Segmentation
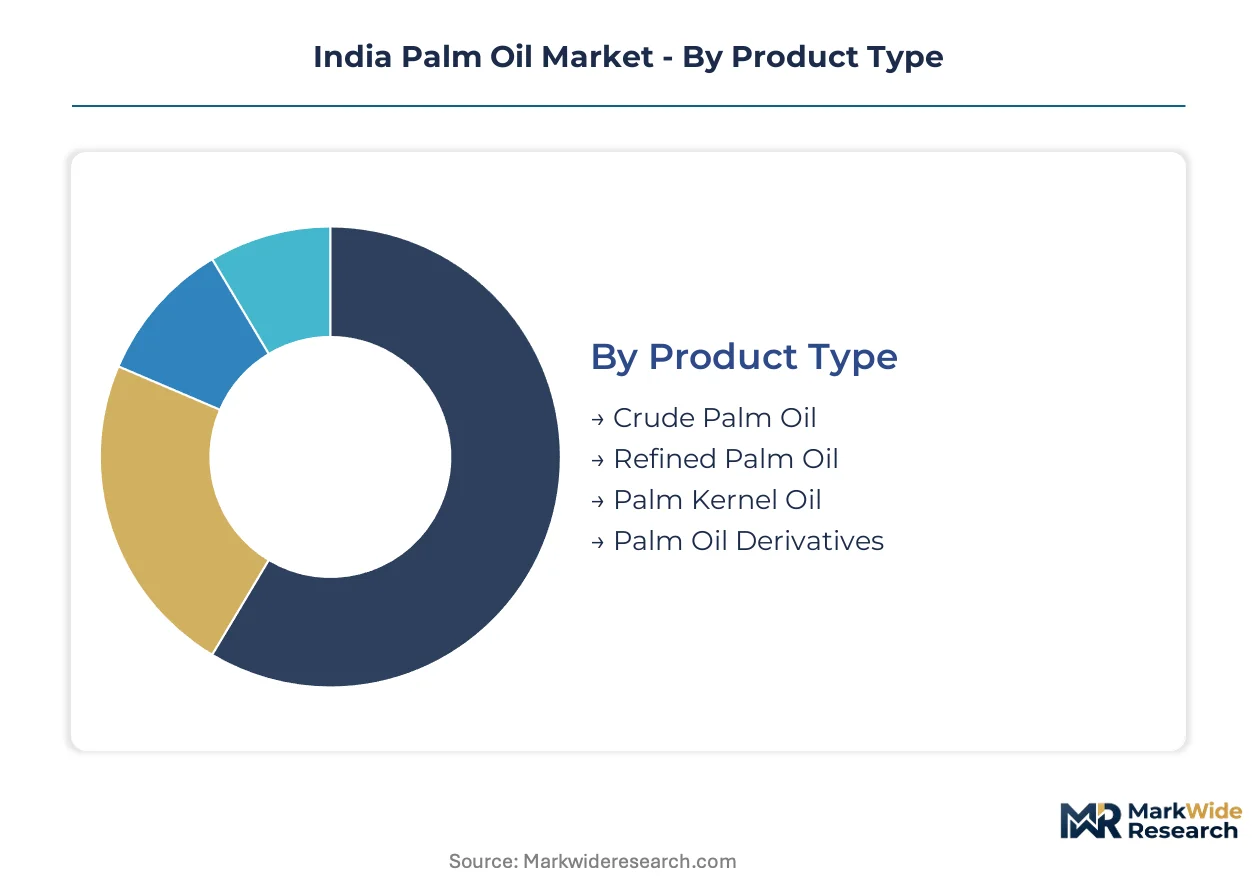
Segmentation in India's palm oil market reveals distinct procurement patterns across product grades and end-use applications. Each category carries specific technical requirements, regulatory obligations, and margin structures that shape supplier relationships and distribution economics.
Product Type:
After-sales service intensity varies sharply across product categories, with refined grades demanding technical support for specification compliance while crude volumes flow on commodity terms.
- Crude Palm Oil:Unrefined mesocarp extract with high beta-carotene content and free fatty acid levels above 5%. Bulk procurement concentrates at Kandla and Mumbai port refineries where Adani Wilmar and Ruchi Soya operate integrated crushing assets; FSSAI contaminant thresholds and BIS grade specifications drive laboratory investment requirements for interstate shipment authorization.
- Refined Palm Oil:Neutral-flavor, bleached, and deodorized product with extended fry-life characteristics. Maharashtra and Gujarat packaged food manufacturers source directly from western refining clusters to minimize inland logistics costs; FSSAI's tightened trans-fat limits accelerate reformulation demand for stable frying media.
- Palm Kernel Oil:Endosperm extract yielding high-lauric fat for oleochemical feedstock applications.
- Palm Oil Derivatives:Fractionated and chemically modified products including palm olein, stearin, and methyl esters.
Refined Palm Oil holds the largest share; momentum sits with Palm Oil Derivatives as biofuel blending mandates expand dedicated offtake channels.
Application:
Cost tier differentiation separates commodity frying applications from premium cosmetic and specialty industrial formulations requiring certified supply chains.
- Food Industry:Dominant absorption channel spanning frying media, shortening bases, and confectionery fats. Western Indian states concentrate demand where bulk refining clusters serve Maharashtra and Gujarat bakery and packaged food manufacturers; FSSAI reformulation pressure on trans-fat limits accelerates palm olein blend adoption.
- Biofuels:Fastest-expanding segment driven by state oil marketing company blending mandates for palm oil methyl ester. Dedicated demand channels outside traditional food applications concentrate procurement leverage with integrated refiners capable of fractionation control; renewable energy obligations at state level reshape margin economics.
- Personal Care:Surfactant and cosmetic applications commanding margin premiums for refined fractions.
- Industrial Use:Oleochemical feedstock for lubricants, coatings, and polymer additives.
Food Industry retains volume dominance; Biofuels gains share fastest as blending infrastructure scales.
End User:
Customer type determines contract structure, with institutional buyers consolidating procurement leverage against fragmented cosmetic and export channels.
- Food Manufacturers:Packaged food producers and HoReCa chains across Maharashtra and Gujarat. Direct mill procurement relationships are displacing traditional wholesale distributors; Godrej Agrovet anchors specialty fat supply for bakery and dairy substitute segments.
- Energy Sector:State oil marketing companies and private blenders advancing biofuel obligations. Procurement concentrates with refiners possessing integrated crushing-fractionation assets near port infrastructure; PLI scheme alignment supports capital investment in dedicated methyl ester production.
- Cosmetic Companies:Formulators requiring customized melting characteristics and oxidative stability metrics.
- Exporters:Traders serving South Asian and Middle Eastern markets with BIS-certified grades.
Food Manufacturers command the largest procurement volumes; Energy Sector expansion trajectory is steepest.
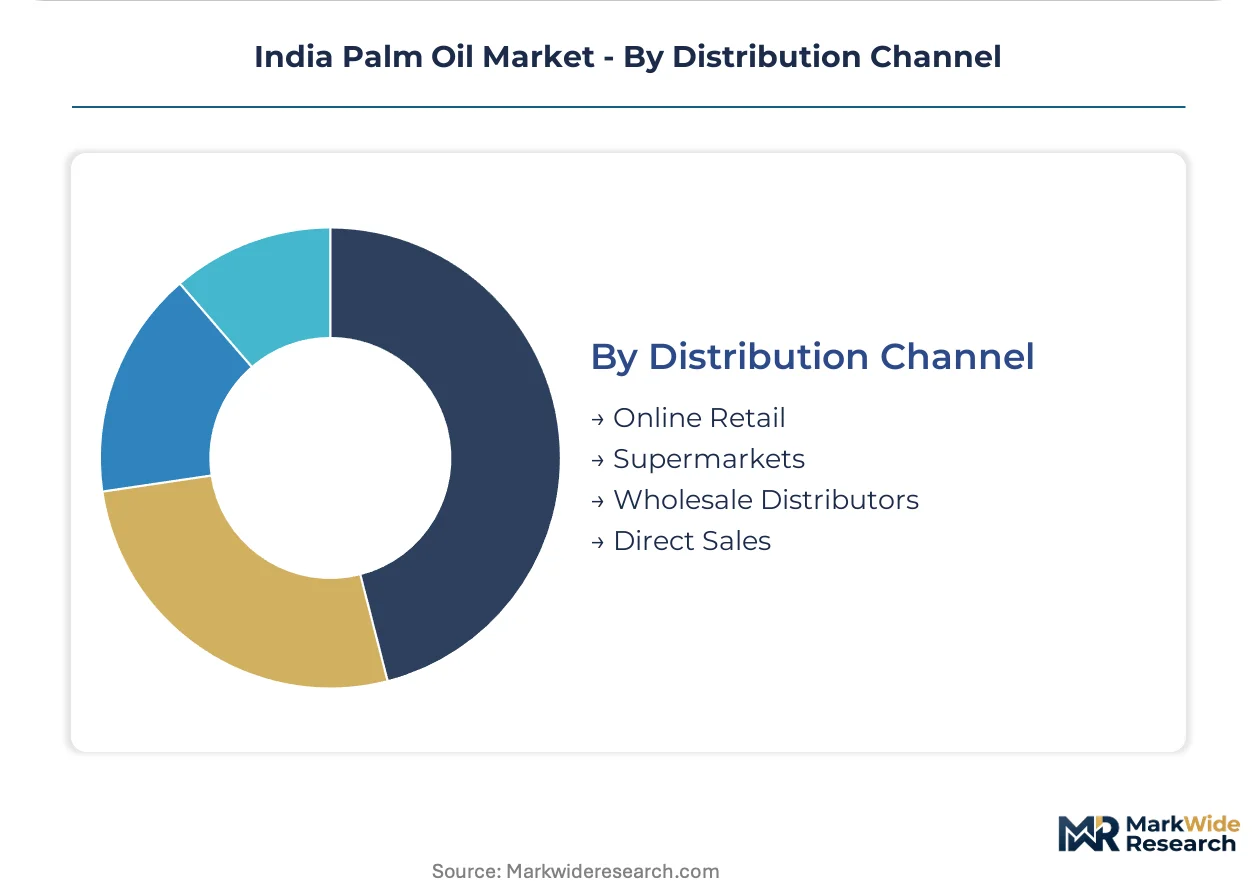
Distribution Channel:
Supply concentration near western port infrastructure favors direct and wholesale channels over retail fragmentation.
- Wholesale Distributors:Traditional network under consolidation pressure as bulk buyers bypass intermediaries. Volume concentration in Maharashtra distributor networks is shifting to institutional channels; Ruchi Soya's HoReCa scale exemplifies channel disintermediation.
- Direct Sales:Volume contracts between refiners and large food manufacturers or energy sector buyers. Gujarat integrated food parks house co-located refining and manufacturing operations eliminating intermediate handling; membrane filtration technology adoption shortens quality compliance timelines for premium applications.
- Supermarkets:Branded packaged oils for household consumers in urban centers.
- Online Retail:Emerging channel for specialty and organic-certified product tiers.
Wholesale Distributors retain residual volume; Direct Sales captures momentum as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in western Indian refining clusters near Kandla and Mumbai ports, while inland buyers in northern and eastern states absorb higher logistics costs. This asymmetry structures procurement consolidation patterns across state boundaries. FSSAI's interstate shipment rules further reinforce concentration advantages for port-adjacent processors.
Maharashtra
Packaged food manufacturers in Mumbai and Pune metropolitan zones drive refined palm oil demand for frying and confectionery applications. FSSAI's tightened trans-fat limits force reformulation toward palm olein blends, accelerating direct procurement relationships with western refiners. Bulk edible oil refining clusters along the Jawaharlal Nehru Port Trust corridor minimize inland distribution costs for HoReCa and institutional buyers.
Gujarat
Kandla port infrastructure anchors India's largest crude palm oil import and processing capacity, with integrated food parks housing co-located refining and manufacturing operations. DGFT's import duty differential between crude and refined grades shapes margin economics for domestic processors. Gandhidham and Mundra industrial zones concentrate fractionation assets serving biofuel blending mandates advanced by state oil marketing companies.
Karnataka
Bengaluru's bakery and dairy substitute manufacturers generate specialty fat demand requiring customized palm fraction crystallization profiles. BIS laboratory certification requirements create compliance bottlenecks for smaller processors seeking interstate shipment authorization. The state's refining capacity remains limited relative to western clusters, forcing buyers to absorb higher logistics costs from Mumbai-Kandla supply lines.
Tamil Nadu
Chennai port receives direct palm oil shipments serving southeastern food manufacturing and oleochemical feedstock applications. State-level renewable energy obligations reshape procurement calculus for palm oil methyl ester destined for biofuel blending. Coimbatore's industrial belt concentrates surfactant and cosmetic formulators commanding margin premiums for refined fractions.
Delhi-NCR
Northern India's institutional food service and packaged goods distribution channels consolidate procurement leverage against fragmented wholesale distributor networks. FSSAI labeling disclosure mandates for saturated fat content and origin traceability compel laboratory investment before interstate authorization. The region lacks indigenous refining capacity, making it structurally dependent on western Indian supply lines with embedded logistics premiums.
India Palm Oil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The India palm oil market structures around three tiers: integrated crushing-refining conglomerates controlling port infrastructure and inland logistics; specialty fat formulators serving bakery and dairy substitute niches; and institutional channel operators supplying HoReCa and packaged food manufacturers at scale. Consolidation accelerates through direct mill procurement relationships displacing traditional wholesale distributors, while membrane filtration technology adoption compresses quality gaps between domestic and imported refined grades.
Among integrated conglomerates, Adani Wilmar Limited and Ruchi Soya Industries Limited exemplify the port-adjacent refining archetype with captive logistics networks. Godrej Agrovet occupies a position within the specialty formulation tier, anchoring supply relationships for customized melting characteristic requirements. These three entities represent distinct competitive vectors: scale-driven infrastructure control, institutional channel dominance, and technical differentiation through fractionation expertise.
| Leading Market Players |
|---|
| Godrej Agrovet |
| Mother Dairy Fruit & Vegetable |
| Adani Wilmar Limited |
| Oil Palm India Limited |
| Cofco Agri Ltd. |
| Ruchi Soya Industries Limited |
| Bunge India |
| Marico Limited |
| Cargill India |
| Others |
Pricing and Supply Chain Analysis
Kandla-Mundra refining clusters concentrate India's palm oil processing capacity, translating port-adjacent logistics advantages into pricing leverage over inland buyers. FSSAI's interstate shipment rules compound this asymmetry by forcing distant processors to absorb compliance delays and laboratory certification costs that western refiners already amortize.
Pricing Analysis
The customization-premium spread separates commodity crude palm oil spot contracts from refined grades configured to specific fry-life and contaminant thresholds. Pricing stratifies across BIS-certified premium grades, standard refined volumes, and economy crude lots with higher free fatty acid baselines. Cost compression in standard refined tiers is intensifying because membrane filtration technology adoption narrows quality gaps with imported refined oil. Institutional HoReCa chains exhibit lowest price sensitivity due to reformulation lock-in costs, while unorganized bakery processors in Karnataka and Tamil Nadu face acute margin pressure from logistics premiums.
Supply Chain Analysis
Supplier-financing facilities from Indonesian and Malaysian trading houses extend 90-120 day payment terms to large Indian refiners, compressing working capital cycles for port-adjacent processors. Raw material flows draw from Indonesian estates, Malaysian mills, and limited Indian domestic cultivation in Andhra Pradesh and Telangana. Supply chain risk centers on DGFT import duty volatility between crude and refined grades, which erodes refiner margins unpredictably. Distribution runs through direct mill contracts displacing Maharashtra wholesale networks, with integrated food parks in Gujarat eliminating intermediate handling steps entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as biofuel blending mandates create dedicated offtake channels outside food applications, absorbing surplus refining capacity that accumulated during prior import duty shocks.
For Market Incumbents: Entrench port-adjacent refining dominance by accelerating membrane filtration deployment to shorten FSSAI compliance timelines for premium applications. Deepen backward integration into Indonesian and Malaysian mill relationships through long-term offtake contracts that lock in supply security against export levy volatility. Channel control represents the critical lever as distributor disintermediation threatens residual wholesale volumes. For New Entrants and Emerging Players: Karnataka's specialty fat segment offers underpenetrated white-space for customized palm fraction formulations serving Bengaluru's vegan bakery and dairy substitute manufacturers. Direct procurement relationships with mid-scale food manufacturers bypassing traditional distributors provide the most penetrable entry vector. A go-to-market angle anchored in lipid chemistry consulting services addresses the reformulation expertise gap delaying competitor product relaunches. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates seeking to monetize non-core palm oil refining assets stranded by import duty asymmetry. Long-term viability hinges on fractionation technology depth and biofuel channel positioning rather than commodity scale alone. The inflection signal to monitor is state-level renewable energy obligation acceleration that would revalue methyl ester production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indonesian Mill Assets | Long-term offtake contracts with Sumatran suppliers neutralize export levy volatility exposure. |
| Membrane Filtration Technology Deployment | Gujarat processors adopting European degumming systems compress quality gaps with imported refined grades. |
| Biofuel Methyl Ester Capacity Expansion | PLI scheme alignment supports capital investment in dedicated fractionation assets near Kandla port infrastructure. |
| Specialty Fat Formulation R&D Investment | Customized crystallization profiles for Bengaluru vegan bakery segment command margin premiums over commodity volumes. |
| Direct Mill Procurement Channel Development | Volume contracts with Maharashtra HoReCa chains displace traditional wholesale distributor networks. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, FSSAI compliance officers at western Indian processors, HoReCa procurement heads, and specialty fat formulators in Karnataka, then refined through secondary validation. Trade data from DGFT customs records, BIS certification registries, FSSAI contaminant disclosure filings, and state renewable energy obligation notifications anchored quantitative baselines. Bottom-up volume builds from individual refinery capacity and top-down demand calibration from end-use consumption surveys were triangulated to resolve estimation variance.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling segmentation dimensions spanning product grade tiers, application channels, end-user contract structures, and regional refining clusters. CAGRs were derived from regression-weighted historical trend extrapolation adjusted for policy inflection points including biofuel mandate acceleration and trans-fat limit enforcement. Forecast inputs incorporated palm oil methyl ester blending infrastructure deployment timelines and membrane filtration technology adoption curves among mid-scale processors.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, Indonesian export levy regimes, or crude petroleum price trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory continuity and technology diffusion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
United Kingdom Animal Protein Market