
 Microfluidics Market | 2026-2036
Microfluidics Market Size, Share, and Industry Trends Forecast 2026-2036
Microfluidics Market Intelligence
A shift in buyer focus from academic centers to commercial diagnostics laboratories is reorganizing the competitive landscape. This transition prioritizes scalable, high-throughput systems over bespoke research instruments. Thermo Fisher Scientific leverages its extensive portfolio to serve both research and clinical end-users. Illumina, in parallel, specializes in microfluidic applications for next-generation sequencing, dominating a critical niche.
Microfluidics involves the precise manipulation of fluids within channels possessing dimensions of tens to hundreds of micrometers. These devices, often fabricated from polymers or glass, enable the miniaturization of complex laboratory procedures into a single chip. The diagnostics application segment, particularly for point-of-care testing, constitutes the largest share of the market. Within product types, integrated sensors are experiencing rapid development to improve real-time data acquisition and device automation.
Regulatory requirements from bodies like the US FDA and China's NMPA heavily influence device design and material selection for clinical applications. In Europe, CE marking under the Medical Devices Regulation (MDR) establishes stringent performance and safety standards for market access. Navigating these varied international compliance pathways remains a critical competency for manufacturers seeking to commercialize new diagnostic platforms.
Market Dynamics
The transition from bespoke academic research instruments to scalable, high-throughput systems for commercial diagnostics is the central force shaping the microfluidics market. This shift elevates the importance of regulatory compliance with bodies like the FDA and NMPA for market access.
Growth Catalysts
- Lab-on-a-Chip Miniaturization:Advanced Lab-on-a-Chip (LOC) technologies enable the integration of complex laboratory procedures onto a single device, accelerating adoption in point-of-care diagnostics and personalized medicine.
- Genomics Sample Preparation:Demand for automated and low-volume sample preparation for next-generation sequencing (NGS) workflows provides a significant pull for microfluidic systems in both research and clinical genomics.
- Favorable Chinese Policy:China's strategic investment in its life sciences sector, combined with NMPA initiatives to fast-track innovative medical devices, creates a concentrated demand center for diagnostic and research platforms.
Market Restraints
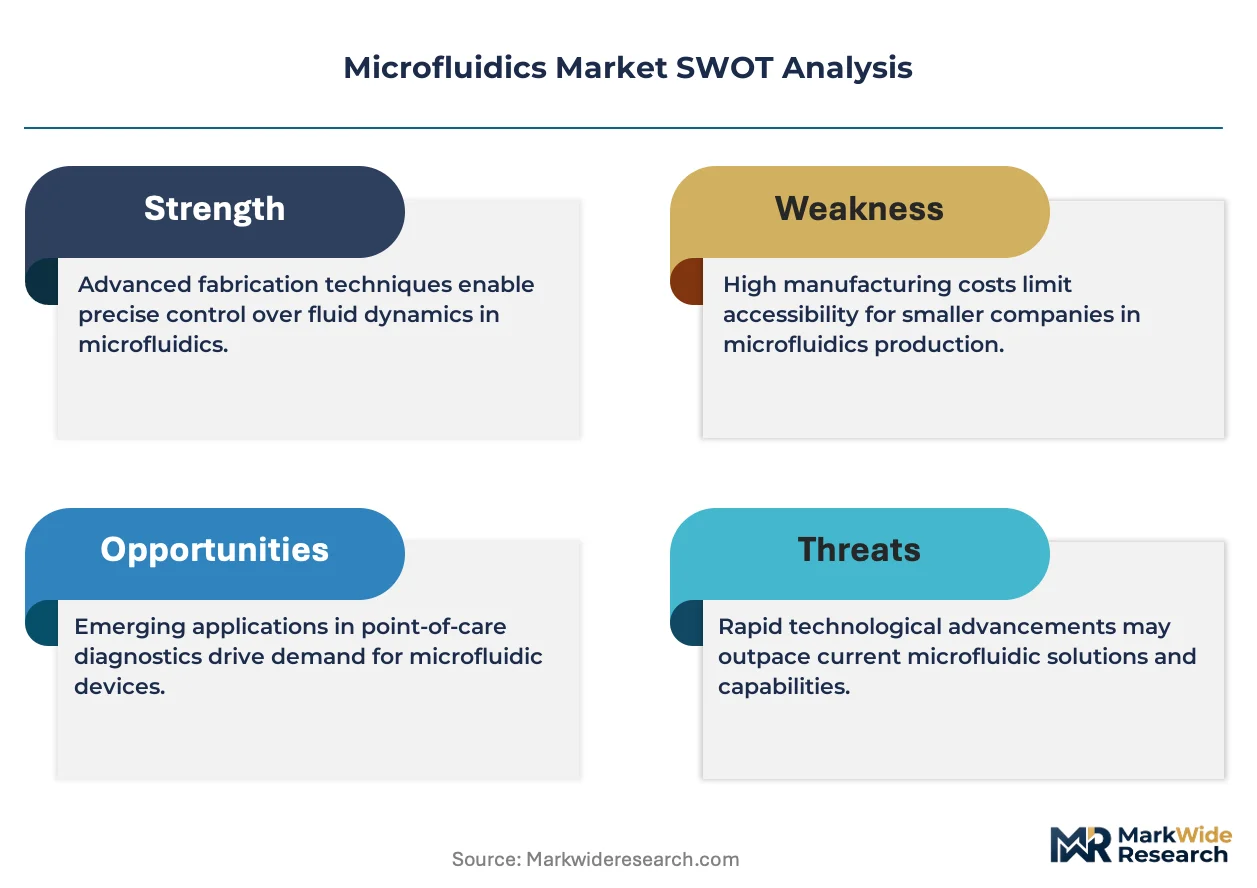
- High Fabrication Costs:The initial investment for fabricating precise glass or silicon-based microfluidic devices remains a barrier for smaller research laboratories and startups, limiting broader experimentation and use.
- Standardization Deficits:A lack of industry-wide standards for device interconnects and fluidic ports complicates integration with existing laboratory automation equipment, hindering seamless workflow adoption.
- EU Regulatory Hurdles:The EU's Medical Devices Regulation (MDR) imposes stringent clinical evidence and post-market surveillance requirements, extending development timelines and increasing compliance costs for diagnostic manufacturers.
Strategic Opportunities
- Organ-on-a-Chip Platforms:Developing microfluidic-based organ-on-a-chip models for preclinical drug toxicology and efficacy testing presents a major opportunity to reduce reliance on traditional animal studies.
- AI-Integrated Sensors:The convergence of integrated sensors with AI algorithms allows for real-time process control and predictive analytics in bioprocessing and continuous monitoring applications.
- Polymer-Based Diagnostics for Emerging Markets:Manufacturing low-cost, polymer-based microfluidic cartridges for infectious disease testing can unlock significant volume in underserved healthcare markets across Latin America and Africa.
Industry Challenges
- Intellectual Property Complexity:A dense patent landscape surrounding fundamental microfluidic principles, such as flow control and droplet generation, creates significant risk of litigation and licensing complexities for new market entrants.
- Manufacturing Scalability:Transitioning device designs from low-volume prototyping to high-volume, cost-effective manufacturing while maintaining stringent quality control for clinical applications remains a significant operational hurdle.
- Interdisciplinary Talent Gaps:A persistent shortage of engineers and scientists with combined expertise in microfabrication, fluid dynamics, and molecular biology impedes rapid innovation and product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfluidics Market |
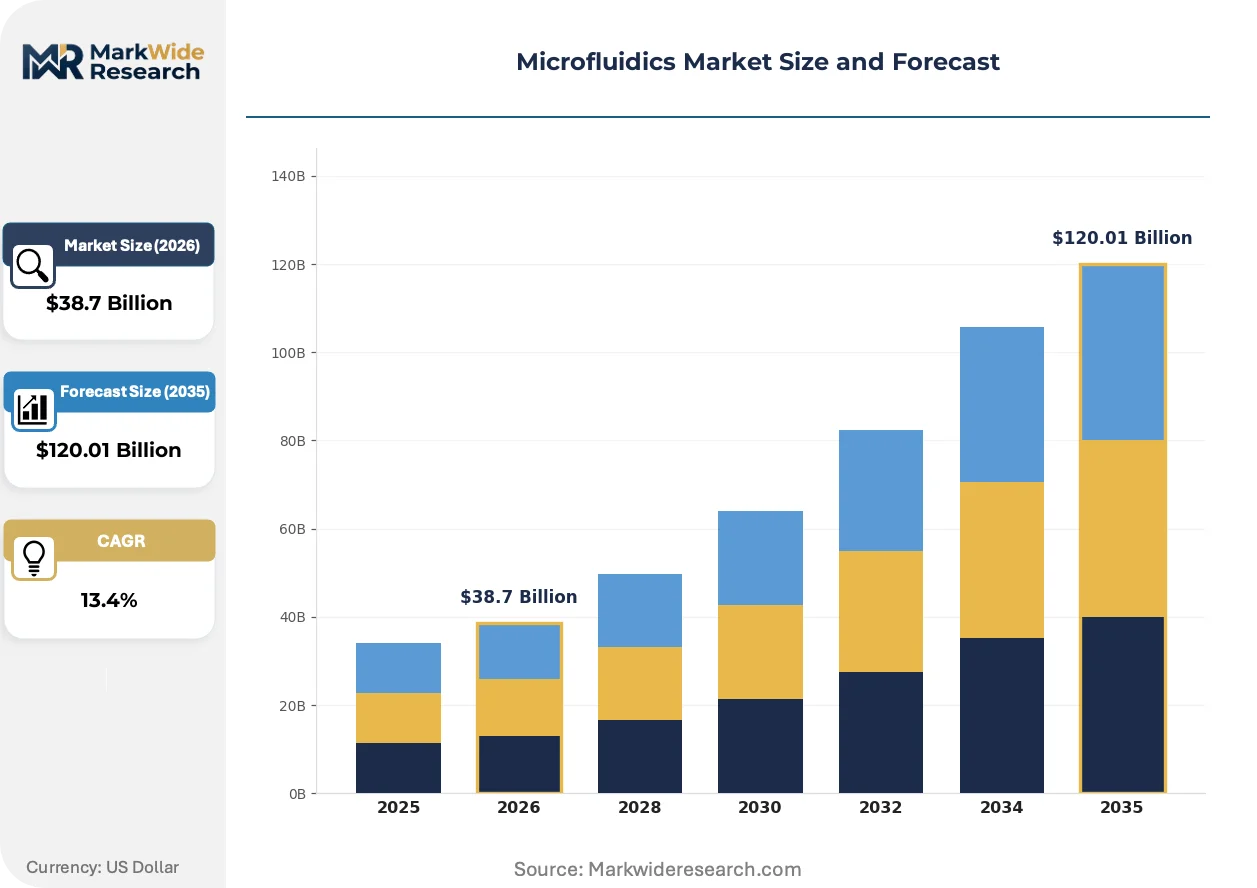
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $120.01 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Pumps, Microvalves, Sensors, Droplet Generators Application: Diagnostics, Drug Delivery, Environmental Testing, Lab-on-a-Chip End User: Pharmaceuticals, Diagnostics Laboratories, Research Institutes, Academic Centers Technology: Electrowetting, Pressure-driven, Capillary-driven, Magnetic |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Illumina, Agilent Technologies, Bio-Rad Laboratories, F. Hoffmann-La Roche, Abbott Laboratories, PerkinElmer, Standard BioTools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfluidics Market Strategic Shifts & Innovations
The convergence of advanced materials science with data analytics is transforming microfluidic devices from static components into dynamic, intelligent systems. This evolution enables more sophisticated automation and control over complex biological and chemical processes, expanding the technology's application scope.
Digital microfluidics (DMF) technology offers programmable fluid handling by manipulating discrete droplets on an electrode array using electrowetting. Pharmaceutical and biotechnology laboratories are adopting DMF for its flexibility in high-throughput screening and automated synthesis protocols. This droplet-based manipulation is supplanting traditional channel-based microfluidics in applications requiring complex, multi-step liquid handling sequences without physical valves.
The US FDA’s growing acceptance of data from organ-on-a-chip systems as supplementary evidence in Investigational New Drug (IND) filings marks a critical regulatory evolution. This policy shift incentivizes pharmaceutical firms to integrate microfluidic-based tissue models into preclinical toxicology and efficacy testing. Consequently, the drug discovery segment is reallocating resources to these advanced in-vitro platforms to better predict clinical outcomes and reduce late-stage failures.
A notable behavioral shift is occurring as customers move from outright capital equipment purchases toward consumption-based procurement models. This approach, where instrument access is linked to recurring purchases of proprietary reagents and consumables, is replacing one-time system sales. This trend is most prominent in the North American and European clinical diagnostics sectors, where labs prioritize operational expenditure models over large upfront capital outlays.
Microfluidics Market Segmentation
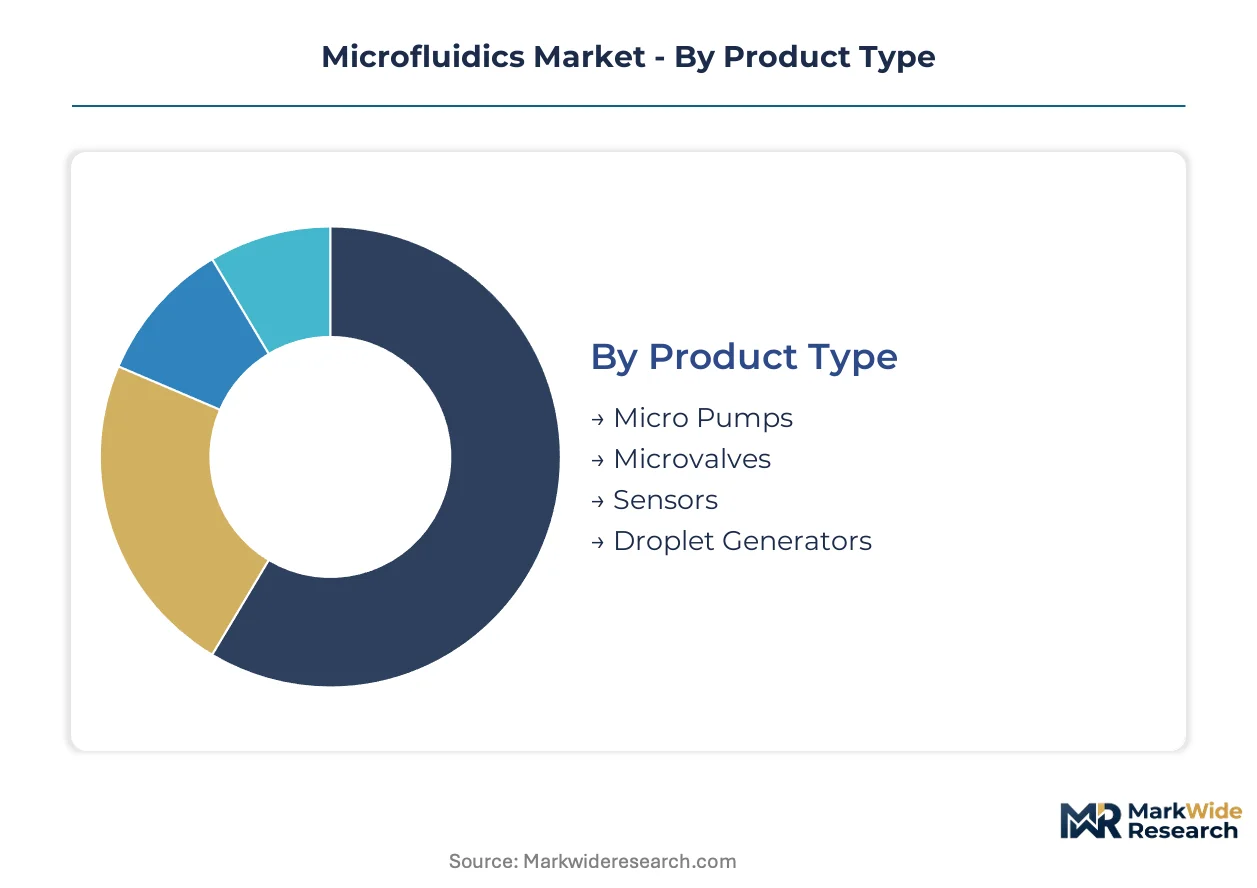
The microfluidics market segmentation reveals how diverse product types, applications, end-users, and technologies converge to meet specific industry needs. Understanding these distinctions is critical for manufacturers to tailor product development and market entry strategies effectively. Each segment presents unique challenges and opportunities for growth.
Product Type:
The distribution channels for microfluidic products vary, reflecting the diverse technical requirements and end-user procurement models.
- Sensors:Integrated sensors enable real-time data acquisition and device automation, crucial for advanced analytical systems. Clinical diagnostics sectors in North America prioritize these components for continuous patient monitoring and rapid assay development.
- Droplet Generators:These devices precisely control and manipulate discrete fluid volumes, facilitating complex biochemical reactions. Pharmaceutical and biotechnology laboratories widely adopt them for high-throughput screening and automated synthesis protocols.
- Micro Pumps:These components facilitate precise fluid movement within microfluidic channels, ensuring accurate reagent delivery.
- Microvalves:These control fluid flow and direction within miniaturized systems, enabling complex fluidic pathways.
By volume, Micro Pumps see widespread deployment. By growth pace, Sensors are expanding most quickly.
Application:
The application segments reflect varying levels of investment and complexity, influencing the overall cost structure of microfluidic solutions.
- Diagnostics:Microfluidic devices miniaturize complex assays for rapid analysis, reducing sample volume and processing time. Point-of-care testing in healthcare sectors, especially in China, drives significant adoption for infectious disease detection.
- Lab-on-a-Chip:These integrated systems combine multiple laboratory functions onto a single chip, enhancing automation and throughput. Personalized medicine and advanced research institutes leverage these for complex biological workflows and drug screening.
- Drug Delivery:Microfluidics enables precise and controlled release mechanisms for therapeutic agents, improving treatment efficacy.
- Environmental Testing:These applications involve rapid detection of contaminants in water and air samples for public health.
Diagnostics applications currently hold the largest market share, while Lab-on-a-Chip integration shows substantial future potential.
End User:
Customer types vary significantly in their procurement cycles and technical support requirements for microfluidic technologies.
- Diagnostics Laboratories:These facilities utilize microfluidic systems for high-throughput sample processing and analysis in clinical settings. Commercial diagnostic labs in North America are shifting towards scalable, automated systems for efficiency.
- Pharmaceuticals:Microfluidic platforms support drug discovery, toxicology screening, and process development, accelerating research timelines. Pharmaceutical companies are integrating organ-on-a-chip models for preclinical testing to reduce reliance on traditional animal studies.
- Research Institutes:These entities employ microfluidic devices for fundamental scientific investigations and proof-of-concept studies.
- Academic Centers:Universities use microfluidics for educational purposes and early-stage research, fostering innovation.
Commercial diagnostics laboratories represent the primary revenue stream, with pharmaceutical companies driving innovation in advanced applications.
Technology:
The underlying technologies dictate the precision and scalability achievable, influencing the concentration of specialized manufacturing expertise.
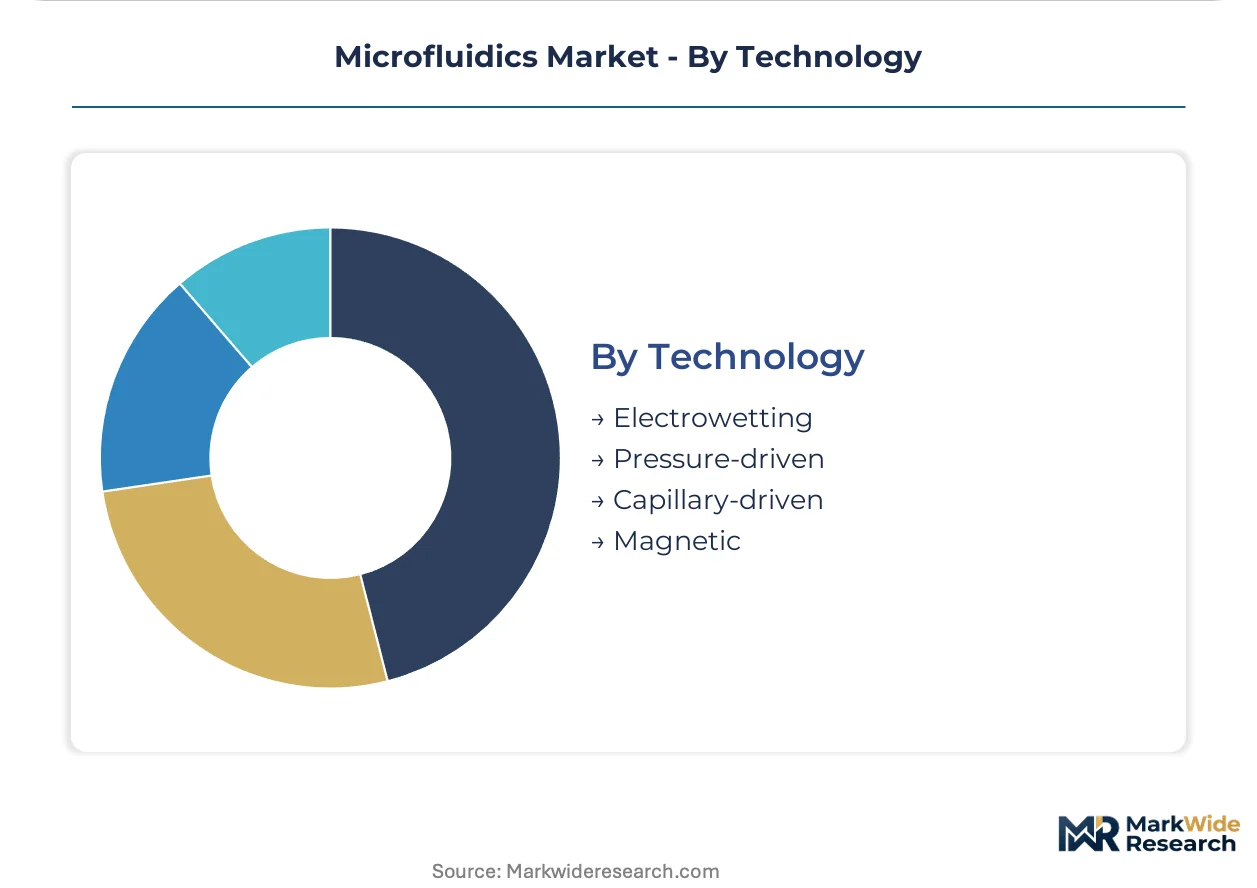
- Electrowetting:This digital microfluidics technology manipulates discrete droplets on electrode arrays using electrical fields. Biotechnology labs widely adopt it for high-throughput screening and automated synthesis protocols, offering flexible liquid handling.
- Pressure-driven:External pumps or pneumatic systems control fluid movement through microchannels, providing robust and continuous flow. Established laboratory automation systems frequently integrate pressure-driven microfluidics for reliable and precise liquid transport.
- Capillary-driven:Surface tension and wetting properties drive fluid flow in passive microfluidic devices, often used in low-cost, disposable platforms.
- Magnetic:Magnetic fields manipulate magnetic beads or ferrofluids within microfluidic systems for separation, mixing, or cell sorting applications.
Pressure-driven systems maintain a broad installed base, while electrowetting-based solutions are gaining traction for advanced applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global supply chains, underpinned by extensive air freight networks, facilitate the rapid distribution of microfluidic devices and reagents worldwide. These logistical capabilities are crucial for delivering sensitive diagnostic components to diverse markets. Efficient transportation infrastructure supports the global reach of specialized microfluidic manufacturing and research.
United States
Demand for advanced point-of-care diagnostics and genomics sample preparation drives microfluidics adoption in the United States. The US FDA's regulatory framework influences device design for clinical applications. Research clusters in Boston and San Francisco actively develop next-generation microfluidic platforms.
China
China's rapidly advancing life sciences and diagnostics industries create a concentrated demand center for microfluidic platforms. The NMPA's initiatives to fast-track innovative medical devices support market entry. Major diagnostic manufacturing hubs like Suzhou and Shanghai are scaling up production capabilities.
Germany
German pharmaceutical and biotechnology sectors exhibit strong demand for high-throughput screening and automated synthesis protocols. CE marking under the Medical Devices Regulation (MDR) establishes stringent performance standards for market access. Bio-clusters in Munich and Heidelberg focus on microfluidic-based drug discovery and personalized medicine.
Japan
Japanese research institutes and medical device manufacturers prioritize precision engineering for microfluidic device fabrication. PMDA regulations ensure device quality and safety for clinical use. Tokyo and Osaka serve as key centers for microfluidic innovation in integrated sensors and Lab-on-a-Chip technologies.
United Kingdom
The United Kingdom's robust academic research base and growing biotech sector drive innovation in microfluidic applications for genomics and drug development. The MHRA oversees medical device approvals for market access. Cambridge and Oxford host numerous startups specializing in advanced microfluidic solutions.
Microfluidics Market Key Industry Players
Concentration sits with established life science tool providers offering broad portfolios across research and clinical applications. The market structure is tiered, featuring large diversified corporations alongside specialized technology developers and emerging startups. Strategic archetypes include integrated solution providers, niche technology innovators focusing on specific applications like next-generation sequencing, and regional manufacturing specialists. Portfolio diversification into complementary technologies and strategic partnerships for market access represent dominant competitive moves.
Within the integrated solution provider tier, Thermo Fisher Scientific and Danaher Corporation exemplify companies leveraging extensive product ranges to serve both research and clinical end-users globally. These entities anchor significant market segments through their established distribution channels and technological expertise. Illumina, in parallel, occupies a position as a specialized innovator, dominating the microfluidic applications for next-generation sequencing workflows. These firms represent archetypes of market leadership, combining comprehensive offerings with focused technological advancements to drive adoption across various end-user segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Illumina |
| Agilent Technologies |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| PerkinElmer |
| Standard BioTools |
| Others |
Cost & Logistics Intelligence
CE marking under the Medical Devices Regulation (MDR) gates microfluidic device qualification, simultaneously influencing market access and price differentiation for clinical applications in Europe. This stringent regulatory environment impacts both manufacturing costs and commercialization strategies for diagnostic platforms.
Pricing Analysis
Tiered pricing structures across premium, standard, and economy levels characterize the microfluidics market, often bundled with consumption-based procurement for recurring reagents. Price differentiation stems from device precision engineering, regulatory certification (such as US FDA or CE marking), and the inclusion of comprehensive after-sales support. Pricing pressure intensifies on high-volume, polymer-based diagnostics due to emerging market demand for cost-effective solutions. Commercial diagnostics laboratories prioritize operational expenditure models, exhibiting sensitivity to total cost of ownership rather than initial capital outlay.
Supply Chain Analysis
Manufacturing scalability for microfluidic devices presents a critical chokepoint, particularly in transitioning from low-volume prototyping to high-volume clinical production. Geographic supply draws from specialized manufacturing hubs in China and precision engineering centers in Japan. Key component dependencies include specialized polymers, high-purity glass, and integrated sensors. Intellectual property complexity across the dense patent landscape introduces a structural risk for new market entrants. Global air freight networks facilitate downstream distribution of sensitive diagnostic components worldwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microfluidics market stands at a platform-economics inflection point, driven by the convergence of integrated sensors with AI algorithms. This shift towards intelligent, dynamic systems enables advanced automation and control across complex biological processes.
For Market Incumbents: Secure intellectual property portfolios through strategic acquisitions of specialized technology developers to mitigate litigation risks. Invest in advanced manufacturing capacity within key regions like China to address scalability hurdles for high-volume production. Diversify product offerings beyond traditional research instruments into clinical diagnostics to counter competitive pressure from niche innovators. Focus R&D on AI-integrated sensors to maintain a technological edge against emerging players.
For New Entrants and Emerging Players: Lead with innovative polymer-based diagnostic solutions tailored for emerging markets in Latin America and Africa to address underserved healthcare needs. Target the organ-on-a-chip segment, offering novel platforms for preclinical drug toxicology and efficacy testing. Leverage digital microfluidics for automated synthesis protocols, providing flexible liquid handling for biotechnology labs. Focus on developing cost-effective, standardized interconnects to ease integration into existing laboratory workflows.
For Investors and Strategic Acquirers: US FDA’s growing acceptance of organ-on-a-chip data reshapes the acquisition landscape for advanced in-vitro platforms over the next decade. Prioritize investments in specialized technology developers offering integrated sensors or digital microfluidics solutions. Seek firms with robust intellectual property portfolios and established manufacturing scalability for clinical applications. The signal to watch is expanding regulatory clarity for novel microfluidic diagnostic platforms in major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Connects diverse microfluidic components into unified diagnostic or research systems. |
| Advanced Materials R&D | Develops novel polymers and glass for enhanced device performance and cost reduction. |
| Regulatory Pathway Acceleration | Streamlines device approval processes for faster market entry in key geographies. |
| Organ-on-a-Chip Development | Reduces reliance on animal testing, improving drug discovery efficiency and ethics. |
| Consumables-Based Business Models | Shifts revenue to recurring purchases, aligning with customer operational expenditure preferences. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, clinical lab managers, and regulatory affairs specialists, then refined through iterative analysis. This involved extensive interviews with pharmaceutical procurement leads and microfluidics engineers to gather qualitative insights. Secondary validation drew from FDA filings, CE marking documentation, NMPA guidelines, and academic research papers. Bottom-up data aggregation and top-down market sizing provided robust triangulation for market estimates.
Variance decomposition across product types, applications, and end-users informed the market projection framework over the analysis window. Segmentation included technology types like electrowetting and regional regulatory clusters influencing market access. Compound annual growth rates derived from historical trends, projected technology adoption, and evolving policy impacts. Key forecast inputs included R&D investment in microfluidic miniaturization and regulatory approval rates for novel diagnostic platforms.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen regulatory changes would require recalibration. Forecasts reflect assumptions regarding technological development pace and sustained R&D investment. Practitioners should keep alternative scenarios live as global supply chain stability and material science innovations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Elemental Analyzer Market