
 Life Science and Analytical Instruments Market | 2026-2036
Life Science and Analytical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Life Science and Analytical Instruments Market Foresight
Direct instrument sales to pharmaceutical companies is fragmenting as procurement teams adopt multi-vendor strategies to reduce dependency risk. Thermo Fisher Scientific leverages its integrated service network to sustain recurring revenue streams across installed chromatography and mass spectrometry bases. Danaher Corporation anchors its position through vertical integration into consumables that lock in platform-specific demand. Bruker Corporation differentiates via specialized magnetic resonance and mass spectrometry technologies for academic and industrial research segments.
Life science and analytical instruments comprise precision measurement systems operating at detection thresholds of parts-per-billion or lower, utilizing separation science, optical spectroscopy, and ion-mobility techniques to characterize molecular structure, purity, and concentration. These systems serve as the foundational infrastructure for pharmaceutical development, environmental compliance verification, and food safety assurance. Chromatography systems and mass spectrometers command the largest share of capital expenditure among product categories, driven by biopharmaceutical pipeline expansion into complex modalities. Sequencing technology within the technology dimension exhibits the steepest growth trajectory as clinical adoption of next-generation diagnostics accelerates.
FDA bioanalytical method validation guidelines, EMA Good Manufacturing Practice Annex 15, and ISO 17025 accreditation requirements collectively elevate instrument qualification burdens and extend replacement cycles for non-compliant legacy equipment. REACH chemical registration protocols in Europe additionally mandate analytical traceability that drives demand for high-resolution mass spectrometry in contract testing laboratories. Stakeholders must evaluate how evolving regulatory data integrity standards will reshape vendor selection criteria and total cost-of-ownership calculations across their instrument portfolios.
Market Dynamics
Pharmaceutical procurement teams are fragmenting vendor relationships across multiple suppliers to mitigate concentration risk, forcing instrument manufacturers to defend installed bases through service contracts and consumables lock-in rather than new system sales alone.
Growth Catalysts
- FDA Bioanalytical Method Validation:Updated guidance tightens instrument performance thresholds, compelling pharmaceutical quality control departments to upgrade legacy chromatography platforms.
- Biologics Pipeline Expansion:Complex therapeutic modalities require mass spectrometry and separation science infrastructure at every development stage from cell line characterization to release testing.
- China Contract Research Clusters:Concentrated investment in Shanghai and Suzhou biotech corridors generates sustained capital expenditure on analytical instrumentation for both domestic and outsourced pharmaceutical development.
Market Restraints
- Critical Component Concentration:High-precision ion sources and detector arrays rely on single-source suppliers in Germany and Japan, exposing lead times to geopolitical friction.
- Helium Supply Volatility:Gas chromatography systems face input cost pressure from constrained helium extraction, particularly affecting laboratories dependent on carrier gas stability.
- Legacy System Interoperability:Decades-old data formats and communication protocols create technical debt that slows cloud-enabled laboratory informatics adoption.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO quality mandate expansion and PLI scheme incentives position the country for analytical instrument penetration in generic API and biosimilar production.
- Artificial Intelligence-Assisted Spectral Interpretation:Machine learning convergence with optical spectroscopy enables real-time impurity detection without specialist operator intervention.
- Remote Service Telemetry:Predictive maintenance channels using instrument-embedded sensors reduce downtime and displace traditional break-fix service contracts.
Industry Challenges
- Mass Spectrometry Specialist Scarcity:Universities produce insufficient operators capable of method development and troubleshooting for high-resolution platforms.
- ISO 17025 Accreditation Timelines:Contract laboratories face 12-18 month validation cycles that delay revenue generation on new instrument deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Science and Analytical Instruments Market |
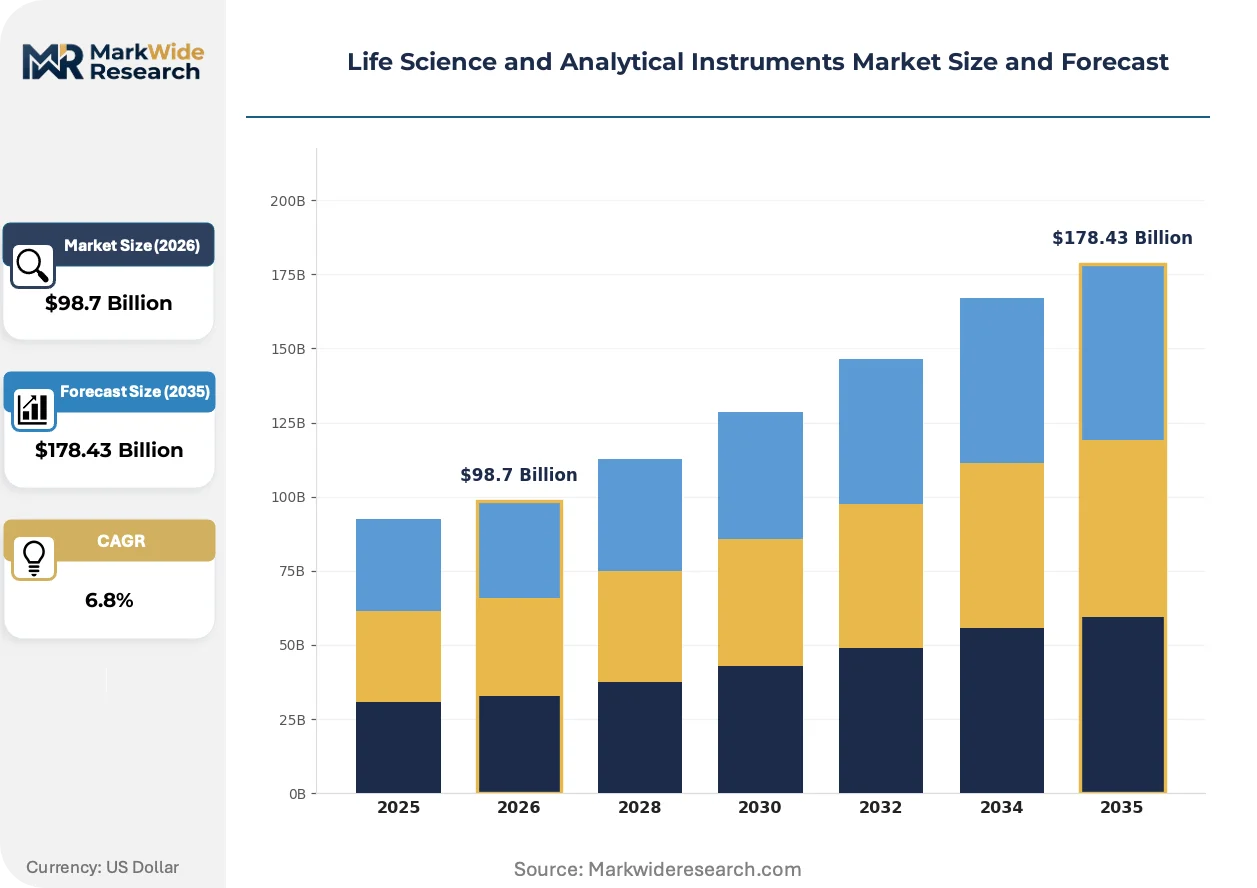
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Spectroscopy Equipment, Mass Spectrometers, Microplate Readers Technology: RFID, PCR, Electrophoresis, Sequencing Application: Drug Discovery, Clinical Diagnostics, Environmental Testing, Food Safety End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Academic Institutions |
| Companies Covered | Waters Corporation, Shimadzu Corporation, Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., PerkinElmer Inc., Danaher Corporation, Bruker Corporation, Merck KGaA, Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Science and Analytical Instruments Market Shifts & Advancements
Miniaturization and computational integration are compressing the physical footprint and skill requirements of analytical workflows, while regulatory data integrity mandates accelerate replacement of paper-based laboratory systems.
Microfluidic sample preparation is rendering obsolete traditional liquid-liquid extraction protocols in pharmaceutical quality control laboratories. Mid-tier generic manufacturers in Eastern Europe and Southeast Asia are adopting these cartridge-based systems at twice the pace of five years prior. The shift is compressing method development timelines from weeks to days while reducing solvent consumption and hazardous waste generation.
EMA Annex 15 revision on computerized systems validation imposes audit trail and electronic signature requirements that extend qualification burdens to software updates and configuration changes. Contract manufacturing organizations in Ireland and the Netherlands are absorbing the largest compliance costs as they serve multiple sponsor quality systems. Instrument vendors are responding with pre-validated software builds and change control documentation packages.
Academic core facilities and mid-size biotechnology companies are unbundling maintenance contracts from initial capital purchases, negotiating separate multi-vendor service agreements through third-party aggregators. The disintermediation is most pronounced in the Boston and San Diego research corridors where shared instrumentation cooperatives pool service spend across institutional boundaries. This procurement pattern pressures manufacturer margins on attach rates while elevating independent service provider influence in replacement decisions.
Life Science and Analytical Instruments Market Segmentation
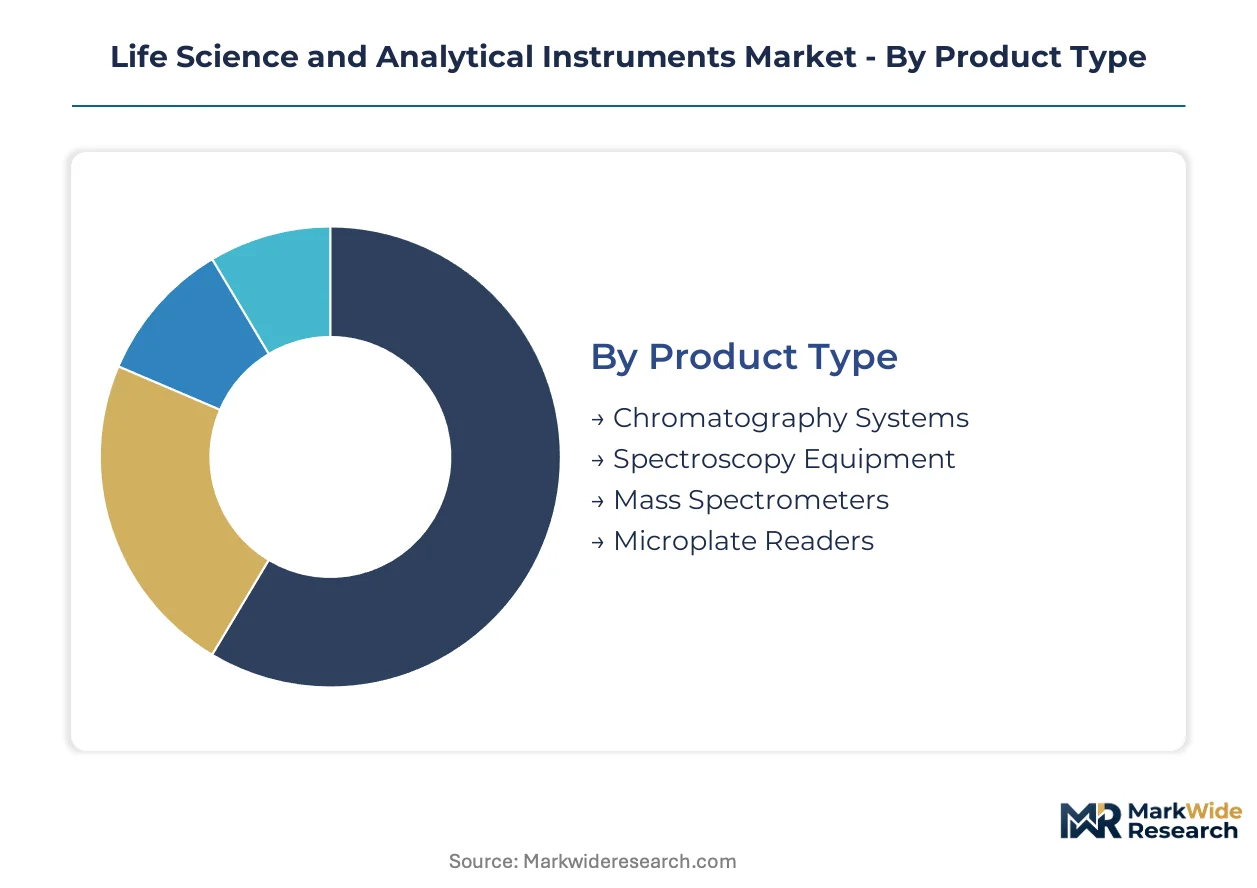
Segmentation in this market reveals divergent replacement rhythms: capital-intensive platforms operate on decade-long depreciation schedules while consumables-linked technologies refresh annually. Procurement strategies differ fundamentally across these cycles, shaping vendor engagement models and service contract structures.
Product Type:
Replacement velocity separates these categories sharply—mass spectrometers and chromatography systems anchor decade-long capital planning, while microplate readers turn over in three-to-five year windows.
- Mass Spectrometers:High-resolution ion detection platforms utilizing quadrupole, time-of-flight, and Orbitrap architectures for molecular weight determination at sub-parts-per-million accuracy. Pharmaceutical quality control departments in the United States and Germany deploy these for biologics impurity profiling under tightened FDA bioanalytical validation standards.
- Chromatography Systems:Separation science platforms combining liquid or gas mobile phases with stationary phase columns to resolve complex mixtures into constituent analytes. Contract research clusters in China—particularly Shanghai and Suzhou biotech corridors—drive capital expenditure as domestic biopharmaceutical pipelines mature.
- Spectroscopy Equipment:Optical and magnetic resonance systems measuring molecular absorption, emission, or magnetic properties for structural elucidation. Academic core facilities represent the primary demand concentration for specialized nuclear magnetic resonance installations.
- Microplate Readers:High-throughput absorbance, fluorescence, and luminescence detection instruments for screening applications. Drug discovery units in Boston and San Diego research corridors favor rapid refresh cycles to capture advancing detection sensitivity specifications.
Chromatography systems dominate installed base. Mass spectrometers are where expansion concentrates.
Technology:
Cost tiering structures vendor positioning—sequencing commands premium pricing at population-scale deployment while electrophoresis occupies the economy tier for routine analytical separations.
- Sequencing:Next-generation and third-generation platforms enabling massively parallel nucleic acid readout for clinical diagnostics and research applications. Clinical laboratories in the United States and China are expanding procurement as reimbursement pathways for genetic testing solidify.
- PCR:Thermal cycling amplification technology for nucleic acid quantification and detection in diagnostic and research settings. Hospital laboratories across Germany and the United States sustained elevated demand through infectious disease surveillance protocols.
- Electrophoresis:Gel and capillary-based separation methods resolving biomolecules by size and charge. Academic institutions maintain steady replacement demand for teaching and routine analytical workflows.
- RFID:Radio-frequency identification systems for sample tracking, chain-of-custody documentation, and laboratory inventory management. Contract manufacturing organizations in Ireland and the Netherlands adopt these for EMA Annex 15 compliance on data integrity and audit trails.
PCR commands the largest installed footprint. Sequencing is climbing the fastest.
Application:
Volume concentration varies by regulatory intensity—drug discovery and clinical diagnostics absorb multi-million-dollar platform deployments while environmental and food safety applications favor distributed, mid-tier instrumentation.
- Drug Discovery:Target identification, lead optimization, and preclinical characterization workflows requiring high-content screening and analytical confirmation. Biotechnology companies in the United States concentrate spending on integrated mass spectrometry and chromatography platforms for complex biologics modalities.
- Clinical Diagnostics:Patient sample analysis for disease detection, monitoring, and treatment selection in certified laboratory environments. China's hospital laboratory expansion and the United States' precision medicine initiatives sustain instrument procurement.
- Environmental Testing:Water, soil, and air quality monitoring for contaminant detection and regulatory compliance. REACH chemical registration protocols in Europe mandate high-resolution mass spectrometry in contract testing laboratories.
- Food Safety:Pathogen detection, allergen screening, and authenticity verification across production and distribution chains. FSSAI mandate expansion in India drives instrumentation penetration in domestic and export-oriented food processing facilities.
Clinical diagnostics dominates installed base. Drug discovery is where expansion concentrates.
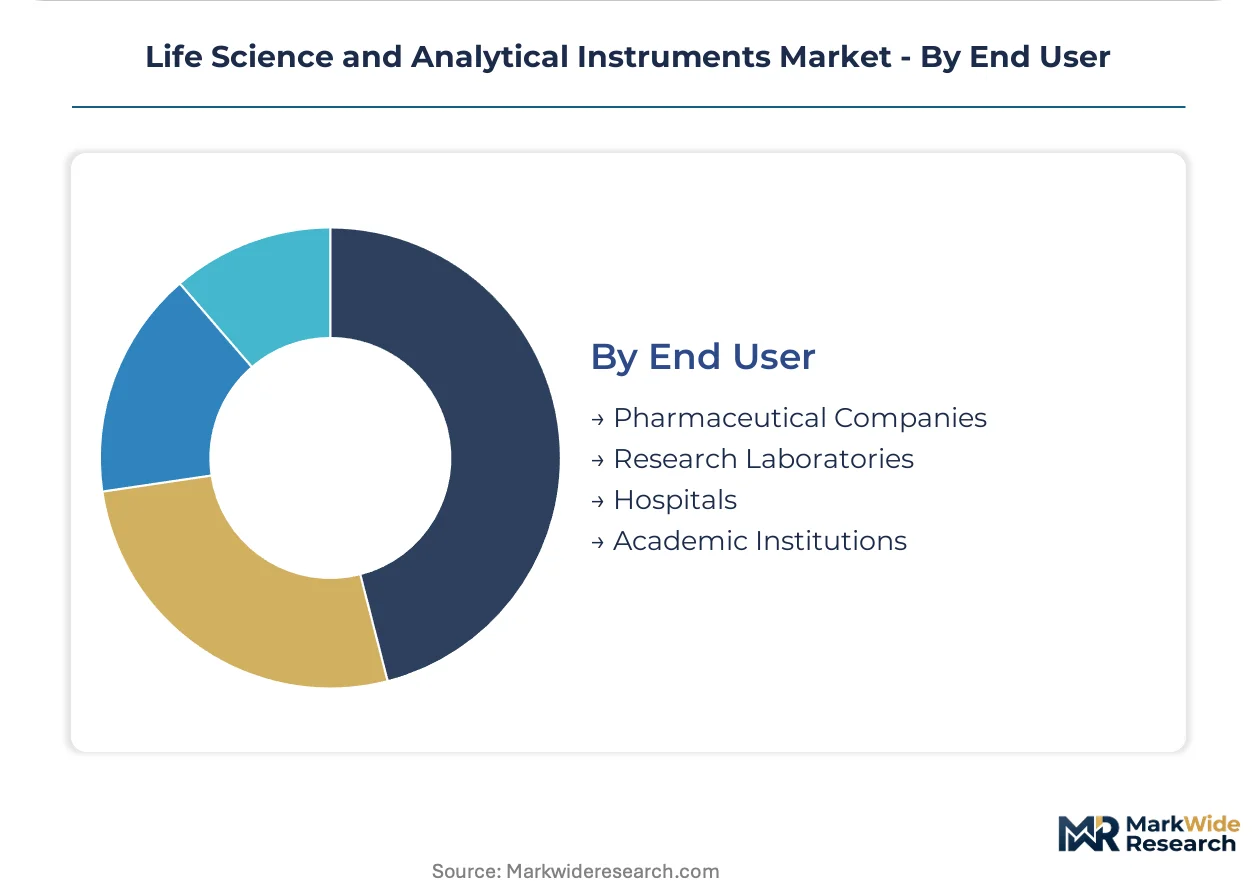
End User:
Customer type determines procurement authority—pharmaceutical companies centralize capital decisions through specialized procurement teams while academic institutions fragment purchasing across departmental budgets.
- Pharmaceutical Companies:Integrated drug development and manufacturing organizations operating quality control, process analytical technology, and release testing functions. Multi-vendor sourcing strategies predominate in the United States and Germany to mitigate supplier concentration risk.
- Research Laboratories:Biotechnology firms, government research institutes, and independent testing facilities conducting applied and basic science. CDSCO quality mandate expansion and PLI scheme incentives in India position this segment for analytical instrument penetration in generic API and biosimilar production.
- Academic Institutions:Universities and research consortia operating core facilities and departmental instrumentation pools. Shared instrumentation cooperatives in Boston and San Diego corridors pool service spend across institutional boundaries.
- Hospitals:Clinical laboratories within integrated health systems performing diagnostic testing and patient monitoring. China's tertiary hospital expansion and laboratory accreditation requirements sustain capital expenditure on automated analytical platforms.
Pharmaceutical companies dominate installed base. Research laboratories are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument pricing power tilts toward Germany and the United States, where regulatory stringency and biopharmaceutical concentration justify premium positioning, while Chinese manufacturers compete on procurement scale and localization mandates.
United States
FDA bioanalytical method validation updates tighten performance thresholds for chromatography and mass spectrometry platforms. The agency's 2023 guidance on bioanalytical method validation compels quality control departments to retire legacy systems. Boston and San Diego research corridors host shared instrumentation cooperatives that pool service spend across institutional boundaries.
Germany
EMA Annex 15 revisions on computerized systems validation impose audit trail and electronic signature requirements extending to software updates. REACH chemical registration protocols mandate analytical traceability that drives high-resolution mass spectrometry demand in contract testing laboratories. Heidelberg and Munich academic core facilities maintain specialized nuclear magnetic resonance installations for structural elucidation workflows.
China
NMPA quality mandate expansion and dual carbon goals accelerate domestic instrument procurement for biopharmaceutical development. Concentrated investment in Shanghai and Suzhou biotech corridors generates sustained capital expenditure on analytical infrastructure for both domestic and outsourced pharmaceutical production. Tertiary hospital laboratory expansion sustains automated platform deployment for clinical diagnostics.
India
CDSCO quality mandate expansion and PLI scheme incentives position analytical instrument penetration in generic API and biosimilar production. FSSAI mandate expansion drives instrumentation adoption in domestic and export-oriented food processing facilities. Hyderabad and Bengaluru pharmaceutical manufacturing clusters absorb multi-vendor sourcing strategies to mitigate supplier concentration risk.
United Kingdom
MHRA alignment with EMA post-Brexit maintains equivalent instrument qualification burdens for pharmaceutical exporters. Academic core facilities in Cambridge and Oxford operate departmental instrumentation pools with fragmented procurement across research budgets. London-based contract research organizations serve sponsor quality systems requiring ISO 17025 accreditation timelines of 12-18 months.
Life Science and Analytical Instruments Market Competitive Landscape
Integrated conglomerates and specialized technology developers split the market along capability depth versus portfolio breadth lines. The vendor base concentrates around three strategic archetypes: full-service platform providers bundling hardware with consumables lock-in, precision technology specialists commanding premium positioning in narrow detection domains, and regional challengers leveraging localization requirements and cost-advantaged manufacturing. Dominant competitive moves include backward integration into consumables supply and predictive maintenance service models displacing traditional break-fix contracts.
Within the full-service platform tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated conglomerate archetype through captive supply of consumables and service network density. Bruker Corporation occupies a position among precision technology specialists, differentiating through specialized magnetic resonance and mass spectrometry platforms. Shimadzu Corporation represents the regional challenger archetype with established positioning in Asian pharmaceutical manufacturing corridors.
| Leading Market Players |
|---|
| Waters Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| PerkinElmer Inc. |
| Danaher Corporation |
| Bruker Corporation |
| Merck KGaA |
| Agilent Technologies Inc. |
| Others |
Supply & Pricing Matrix
German and Japanese precision optics suppliers command 60-70% of high-resolution ion source and detector array manufacturing, anchoring margin capture at the component tier while system integrators compete on service attach rates and consumables lock-in downstream.
Pricing Analysis
Configured-to-order mass spectrometry platforms command 40-60% premiums over standard liquid chromatography configurations, with pricing stratifying across premium, standard, and economy tiers based on detection sensitivity specifications and software validation documentation depth. Price differentiation hinges on ISO 17025 pre-certification status and captive consumables bundling. Cost compression in mid-tier chromatography systems is intensifying because Chinese manufacturers are expanding localized production for domestic biopharmaceutical procurement. Academic core facilities exhibit highest price sensitivity due to fragmented departmental budgets, while pharmaceutical quality control departments prioritize total cost-of-ownership over upfront capital expenditure.
Supply Chain Analysis
Upstream feedstock concentration in helium extraction from Qatar, the United States, and Algeria exposes gas chromatography operators to carrier gas cost volatility and allocation rationing during supply disruptions. High-precision ion sources draw from single-source suppliers in Germany and Japan, while rare earth magnets for nuclear magnetic resonance systems rest on Chinese processing dominance. Single-source vulnerability in detector array manufacturing creates procurement risk for lead times extending 12-18 months. Distribution runs through authorized service networks and third-party aggregators competing on multi-vendor maintenance contract consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as FDA bioanalytical method validation updates force replacement of decade-old chromatography platforms in pharmaceutical quality control departments.
For Market Incumbents: Insulate installed base revenue through predictive maintenance telemetry and consumables subscription models that displace break-fix service contracts. Threats from third-party service aggregators in Boston and San Diego research corridors are eroding attach rates; counter by deepening backward integration into high-margin consumables supply and pre-validated software builds that accelerate ISO 17025 accreditation timelines for contract laboratories. For New Entrants and Emerging Players: Build out specialized magnetic resonance and mass spectrometry platforms for academic core facilities in Germany and India where incumbent coverage is thin. The most penetrable segment lies in mid-tier generic API manufacturers in Eastern Europe and Southeast Asia adopting microfluidic sample preparation systems at twice prior rates. A service-first go-to-market angle—unbundling maintenance from capital purchase—aligns with procurement pattern shifts in shared instrumentation cooperatives. For Investors and Strategic Acquirers: Capital is best deployed toward precision technology specialists with captive detection IP and established positioning in high-resolution mass spectrometry rather than full-service platform conglomerates facing margin compression from multi-vendor sourcing strategies. Long-term viability over a 5-10 year window favors vendors controlling consumables chemistry and software validation documentation. The signal to watch is NMPA quality mandate expansion in China accelerating domestic instrument procurement versus import substitution trends.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Subscription Model | Recurring revenue streams from chromatography column and solvent supply lock in platform-specific demand across pharmaceutical quality control departments. |
| Predictive Maintenance Telemetry | Instrument-embedded sensors reduce downtime and displace traditional break-fix service contracts in Boston and San Diego research corridors. |
| Pre-Validated Software Builds | Change control documentation packages accelerate EMA Annex 15 compliance timelines for contract manufacturing organizations in Ireland and the Netherlands. |
| Microfluidic Sample Preparation Systems | Cartridge-based workflows compress method development timelines from weeks to days while reducing hazardous waste generation in pharmaceutical laboratories. |
| Multi-Vendor Service Aggregation | Third-party providers pool maintenance spend across institutional boundaries, pressuring manufacturer margins on attach rates in academic core facilities. |
Research Methodology
Operator-level perspectives from pharmaceutical quality control directors, academic core facility managers, contract laboratory procurement leads, and instrument service technicians anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FDA bioanalytical method validation guidance documents, EMA Annex 15 revision texts, ISO 17025 accreditation records, and SEC 10-K filings from listed instrument manufacturers. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing around regulatory implementation timelines and biopharmaceutical pipeline maturation rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application workflow, and end-user procurement authority. CAGRs were derived from replacement cycle analysis and capital expenditure survey data. Industry-specific forecast inputs incorporated helium supply volatility indices and NMPA quality mandate expansion schedules.
Sensitivities concentrate around FDA guidance implementation pacing, China import substitution policy shifts, and academic research funding fluctuations in the United States and Germany. Forecasts reflect assumptions on regulatory data integrity standard adoption curves and biologics pipeline complexity trajectories. Cross-checking against EMA and NMPA instrument qualification filing volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Thermogravimetric Analyzer Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Microchip Electrophoresis Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
Laser-Based Gas Analyzers Market