
 Metal Analyzers Market | 2026-2036
Metal Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Analyzers Market Outlook
Software-defined calibration services is recalibrating how vendors monetize metal analyzer deployments, shifting revenue from hardware transactions to recurring instrumentation intelligence contracts. Thermo Fisher Scientific leverages its embedded software ecosystem to sustain long-term client relationships across North American foundries. Bruker Corporation anchors European demand through specialized optical emission systems for alloy verification. HORIBA Ltd. competes aggressively in Asian environmental compliance segments with portable X-ray fluorescence configurations.
Metal analyzers are precision instruments that determine elemental composition, alloy grade, and material purity through spectroscopic, electrochemical, or thermal methods, typically operating at detection thresholds measured in parts per million to prevent structural failures in critical components. Their primary purpose is to enforce material specifications across manufacturing, recycling, and regulatory inspection workflows. Portable analyzers are capturing expanding share in scrapyard and field inspection environments where mobility outweighs laboratory precision. Spectroscopy technologies dominate R&D and high-throughput quality control settings due to superior multi-element detection speed. Mass spectrometry segments are gaining traction in environmental testing agencies pursuing trace-level contaminant identification.
The EPA enforces hazardous waste characterization rules that mandate certified metal content screening before industrial discharge or landfill disposal, directly stimulating analyzer procurement across American manufacturing facilities. REACH compliance in Europe requires comprehensive substance identification throughout supply chains, compelling metal manufacturers to deploy benchtop systems with expanded elemental libraries. ISO 17025 accreditation standards for testing laboratories are tightening calibration traceability requirements, elevating demand for vendor-backed service contracts. Stakeholders must weigh the trade-off between capital-intensive optical emission investments and the operational flexibility of portable X-ray fluorescence platforms as compliance timelines compress.
Market Dynamics
Software-defined calibration is compressing hardware replacement cycles across metal analyzer deployments, converting one-time instrument sales into recurring instrumentation intelligence contracts that extend vendor-client relationships over multi-year horizons.
Growth Catalysts
- REACH compliance mandates:European manufacturers must maintain comprehensive substance identification records throughout supply chains, compelling investment in benchtop systems with expanded elemental libraries for alloy verification.
- Scrapyard mobility requirements:Portable X-ray fluorescence configurations are displacing laboratory-bound workflows as secondary metal processors prioritize rapid field-based sorting over centralized testing protocols.
- NMPA alloy verification enforcement:China's stricter certification standards for structural metals are accelerating replacement demand for outdated benchtop analyzers in domestic foundries and fabrication facilities.
Market Restraints
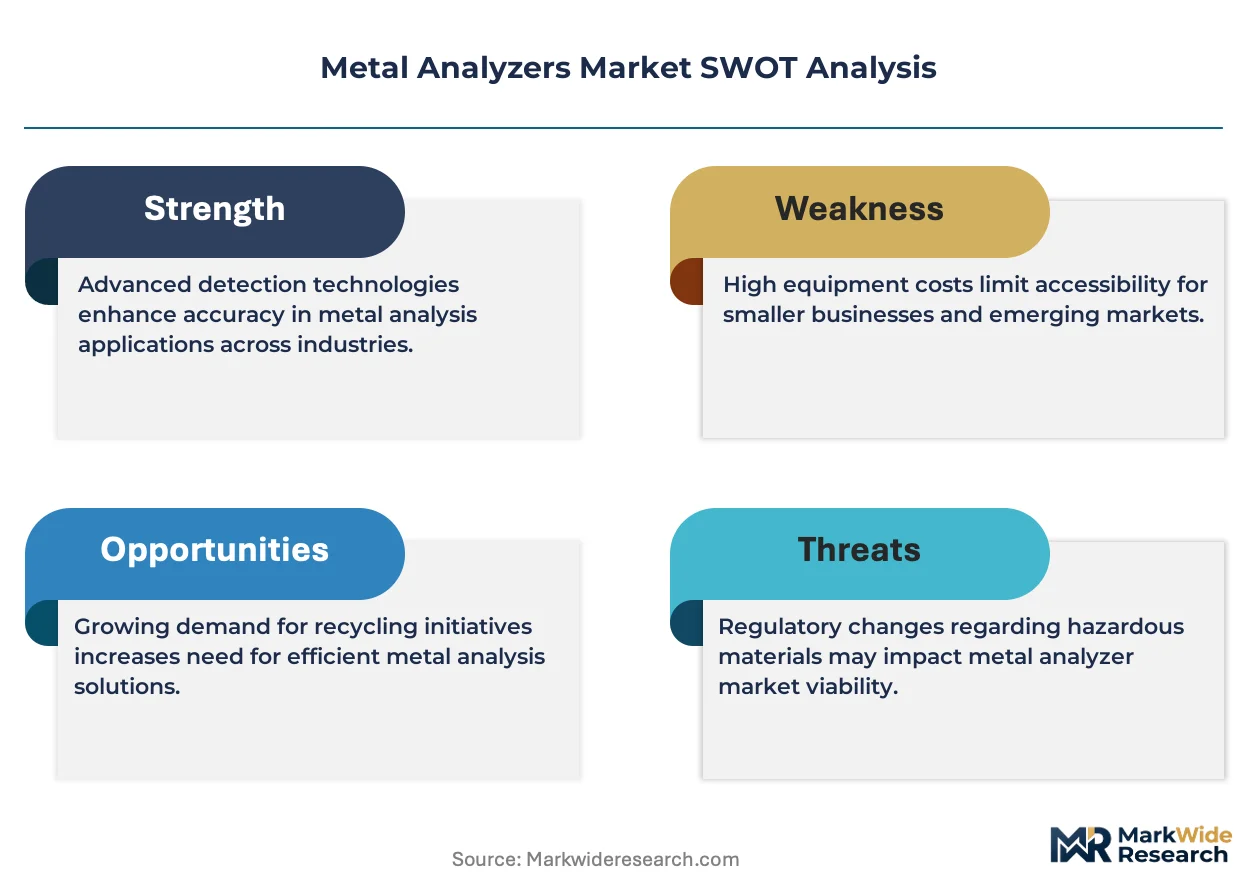
- Optical emission spectrometer capital intensity:High-precision laboratory systems require substantial upfront investment in argon gas infrastructure and climate-controlled housing, limiting penetration among mid-tier metal fabricators.
- Detector component concentration:Specialized silicon drift detectors and X-ray tubes concentrate production among a narrow supplier base in East Asian manufacturing corridors, creating vulnerability to supply disruptions.
- ISO 17025 calibration traceability:Accreditation requirements mandate documented calibration chains with certified reference materials, elevating ongoing compliance costs beyond initial instrument acquisition.
Strategic Opportunities
- Indian industrial corridor expansion:Metal fabricators around Pune and Chennai are modernizing quality assurance protocols, creating first-mover advantage for vendors establishing localized service infrastructure.
- Environmental testing agency demand:Mass spectrometry configurations are gaining traction for trace-level contaminant identification in soil and wastewater analysis, opening adjacent revenue streams beyond traditional manufacturing applications.
- Cloud-connected instrument ecosystems:Integration of spectroscopic hardware with remote diagnostic platforms enables predictive maintenance contracts and real-time calibration adjustment, shifting revenue toward subscription-based instrumentation intelligence.
Industry Challenges
- Spectroscopy technician scarcity:Foundries and testing laboratories face acute shortages of personnel trained in optical emission system operation, sample preparation protocols, and interference correction algorithms.
- Legacy LIMS integration complexity:New analyzer deployments frequently encounter data format incompatibilities with established laboratory information management systems, extending commissioning timelines and requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Analyzers Market |
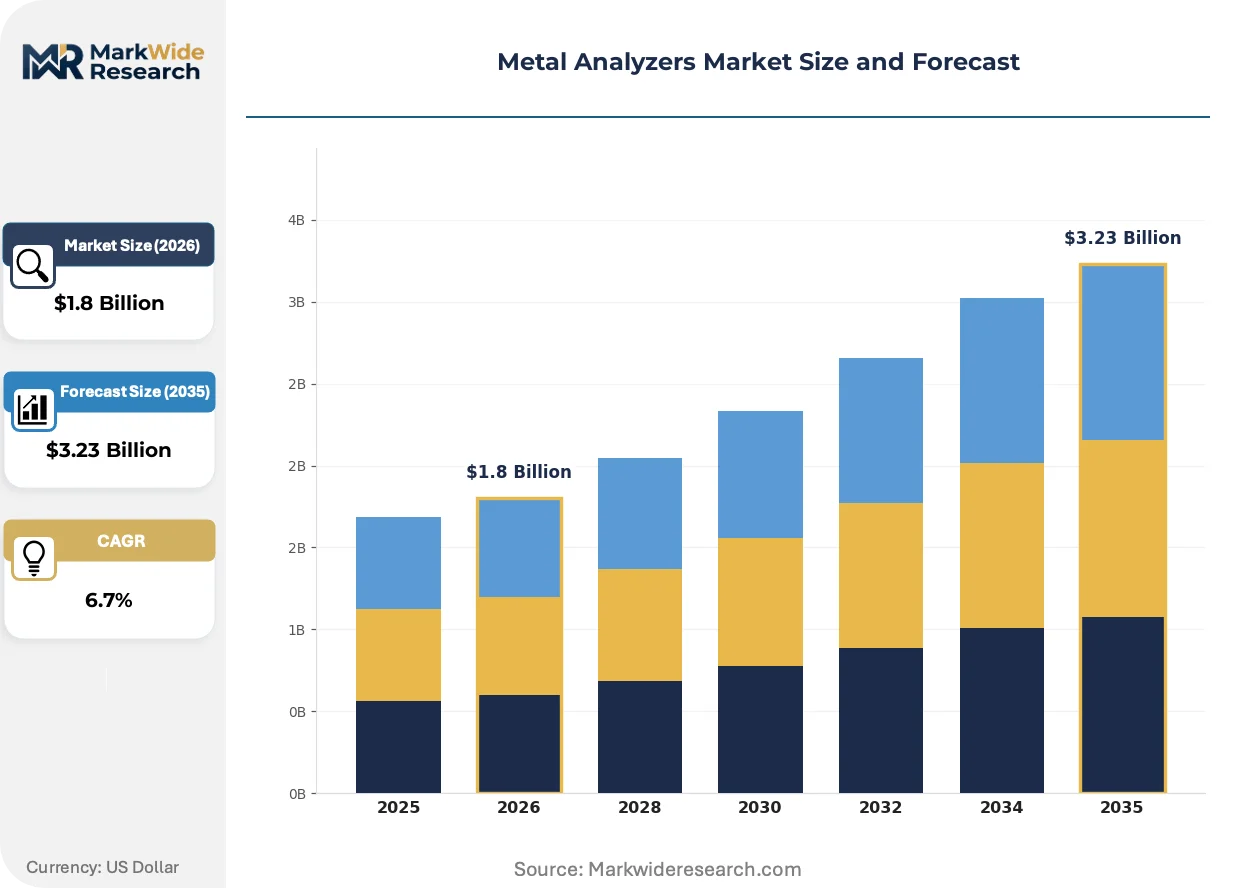
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Benchtop Analyzers, Optical Emission Spectrometers, X-Ray Fluorescence Analyzers Technology: Thermal Analysis, Spectroscopy, Electrochemical, Mass Spectrometry End User: Metal Manufacturers, Research Laboratories, Quality Control Units, Environmental Testing Agencies Application: Quality Assurance, Material Identification, Process Control, Compliance Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., PerkinElmer Inc., Bruker Corporation, Shimadzu Corporation, SPECTRO Analytical Instruments GmbH, HORIBA Ltd., Analytik Jena AG, Malvern Panalytical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Analyzers Market Strategic Shifts
Artificial intelligence is embedding directly into spectroscopic signal processing, enabling real-time alloy identification without cloud dependency while compressing the skill threshold required for accurate field-based analysis.
Handheld laser-induced breakdown spectroscopy is decentralizing elemental analysis from centralized laboratories to production floor environments. Automotive tier-one suppliers in Germany and Japan are deploying these units for incoming raw material verification. The technology is compressing quality control cycle times from hours to minutes while reducing dependency on specialized laboratory personnel.
EPA hazardous waste characterization rules are mandating certified metal content screening before industrial discharge or landfill disposal. American manufacturing facilities must deploy analyzers capable of detecting regulated heavy metals at parts-per-million thresholds. Scrap metal processors and electroplating operations face the most acute compliance pressure, driving procurement of portable X-ray fluorescence units with expanded elemental libraries.
Service contract unbundling is fragmenting traditional vendor relationships. Large foundry operators are separating hardware acquisition from calibration and maintenance services, negotiating directly with third-party metrology laboratories for ISO 17025-accredited support. This pattern is most pronounced in North American aerospace supply chains, where prime contractors impose stringent vendor qualification requirements that favor specialized service providers over generalist instrument manufacturers.
Metal Analyzers Market Segmentation
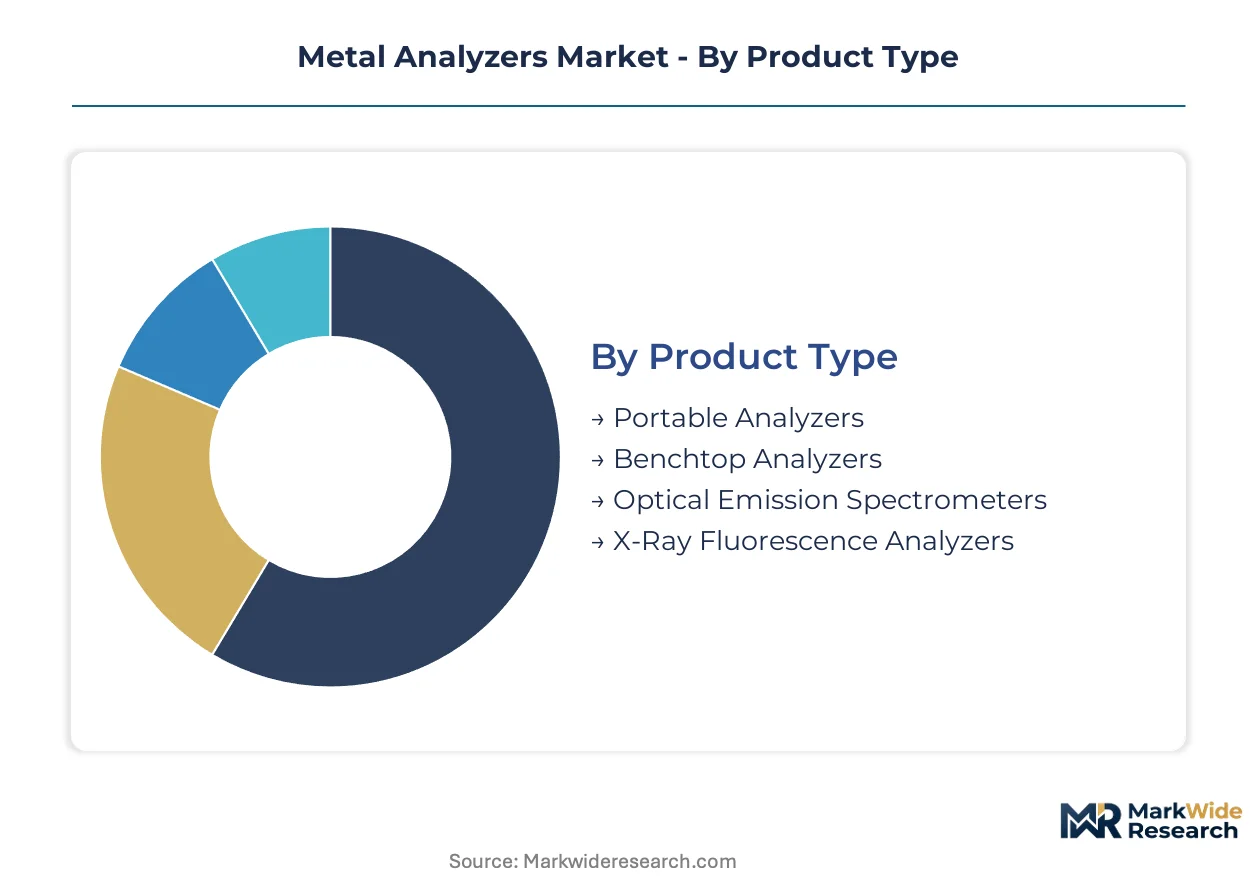
Metal analyzer procurement decisions pivot on mobility requirements, detection precision thresholds, and integration complexity with existing laboratory infrastructure. Segmentation reveals how portable configurations are displacing centralized testing workflows while spectroscopy technologies dominate high-throughput manufacturing environments.
Product Type:
Capital intensity versus operational flexibility shapes buyer selection across deployment environments.
- Portable Analyzers:Battery-powered X-ray fluorescence and laser-induced breakdown spectroscopy units enable rapid field-based alloy verification without sample transport logistics. Scrapyards in India's Pune industrial corridor are deploying these for real-time incoming material sorting, compressing quality control cycles from hours to minutes while eliminating laboratory bottlenecks.
- Benchtop Analyzers:Compact systems balance laboratory-grade precision with reduced footprint requirements, typically housing energy-dispersive X-ray fluorescence or basic optical emission modules. China's NMPA enforcement of stricter structural metal certification standards is accelerating replacement demand for outdated benchtop units in domestic foundries.
- Optical Emission Spectrometers:High-precision laboratory systems utilizing argon plasma excitation deliver parts-per-million detection thresholds for critical aerospace and automotive components.
- X-Ray Fluorescence Analyzers:Non-destructive elemental screening dominates environmental compliance applications where sample preservation matters.
Benchtop analyzers lead on scale; portable analyzers lead on momentum.
Technology:
Detection methodology determines throughput speed, elemental range coverage, and operator skill requirements.
- Spectroscopy:Optical emission and atomic absorption methods deliver multi-element simultaneous detection with superior speed for high-volume manufacturing quality control. Aerospace manufacturers in Germany and Japan are expanding spectroscopy-based assurance programs for incoming raw material verification.
- Mass Spectrometry:Inductively coupled plasma configurations achieve ultra-trace detection thresholds for environmental contaminant identification. Testing agencies pursuing soil and wastewater analysis are adopting these systems for regulatory compliance documentation.
- Thermal Analysis:Differential scanning calorimetry and thermogravimetric methods characterize material phase transitions and thermal stability.
- Electrochemical:Potentiometric and voltammetric techniques offer cost-effective screening for specific ionic species in aqueous samples.
Spectroscopy dominates manufacturing penetration; mass spectrometry is climbing fastest in adjacent environmental applications.
End User:
Operational scale and regulatory exposure intensity differentiate procurement patterns across buyer categories.
- Metal Manufacturers:Foundries, fabricators, and secondary processors require continuous alloy verification to prevent specification failures in structural components. EPA hazardous waste characterization rules mandate certified metal content screening before industrial discharge, directly stimulating analyzer procurement across American manufacturing facilities.
- Environmental Testing Agencies:Regulatory laboratories pursue trace-level contaminant identification in soil, water, and air matrices. These agencies are expanding mass spectrometry deployments for parts-per-billion detection of regulated heavy metals under discharge monitoring requirements.
- Research Laboratories:Academic and industrial R&D facilities prioritize analytical flexibility and publication-grade precision.
- Quality Control Units:Embedded manufacturing laboratories focus on throughput optimization and operator training minimization.
Metal manufacturers lead on installed base volume; environmental testing agencies lead on specification intensity.
Application:
Workflow integration depth determines instrument configuration complexity and service contract structure.
- Quality Assurance:Incoming material verification and finished product certification require documented traceability chains. ISO 17025 accreditation standards are tightening calibration requirements, elevating demand for vendor-backed service contracts in testing laboratories.
- Compliance Testing:Regulatory-mandated screening for hazardous substance content drives procurement with expanded elemental libraries. REACH compliance in Europe requires comprehensive substance identification throughout metal supply chains, compelling manufacturers to deploy benchtop systems with broad detection capabilities.
- Material Identification:Rapid alloy grade confirmation supports scrap sorting and reverse logistics operations.
- Process Control:Real-time monitoring of molten metal chemistry enables immediate furnace adjustment.
Quality assurance leads on contract value; compliance testing is gaining share fastest under tightening regulatory timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping metal analyzer procurement as manufacturers relocate quality assurance operations to jurisdictions with streamlined certification pathways and lower compliance overhead.
United States
EPA hazardous waste characterization rules mandate certified metal content screening before industrial discharge, driving analyzer deployment across electroplating and scrap processing facilities. American aerospace suppliers face stringent prime contractor qualification requirements that elevate demand for ISO 17025-accredited calibration services. Foundry operators in the Ohio River Valley industrial corridor are unbundling hardware acquisition from third-party metrology support to reduce total cost of ownership.
Germany
Automotive tier-one suppliers are deploying handheld laser-induced breakdown spectroscopy units for incoming raw material verification, compressing quality control cycles from hours to minutes. REACH compliance mandates comprehensive substance identification records throughout metal supply chains, compelling investment in benchtop systems with expanded elemental libraries. Aerospace manufacturers in the Bavarian industrial cluster are expanding spectroscopy-based quality assurance programs for critical component certification.
China
NMPA enforcement of stricter alloy verification standards for structural metals is accelerating replacement demand for outdated benchtop analyzers in domestic foundries. The country's national environmental regulator has tightened discharge monitoring requirements for heavy metals in industrial wastewater. Fabrication facilities in the Yangtze River Delta are modernizing testing protocols to meet dual carbon goals and export certification requirements.
India
Metal fabricators around Pune and Chennai are modernizing quality assurance protocols, creating first-mover advantage for vendors establishing localized service infrastructure. BIS certification requirements for structural steel grades are elevating demand for portable X-ray fluorescence configurations in secondary metal processing. The country's industrial corridor expansion is concentrating procurement decisions among mid-tier fabricators seeking operational flexibility over laboratory-grade precision.
Japan
METI industrial standards for material traceability are elevating demand for cloud-connected instrument ecosystems with predictive maintenance capabilities. Aerospace and automotive manufacturers in the Nagoya industrial zone are deploying spectroscopic hardware with embedded artificial intelligence for real-time alloy identification. JIS standards compliance is tightening calibration traceability requirements, extending vendor-client relationships through multi-year instrumentation intelligence contracts.
Metal Analyzers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in laboratory-grade optical emission systems and fragmented competition in portable field-deployable units. The vendor base organizes around three strategic archetypes: diversified analytical instrumentation conglomerates, specialized spectroscopy houses, and regional system integrators. Competitive dynamics center on technology licensing agreements for detector components and strategic partnerships to secure ISO 17025-accredited service networks.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. occupy positions anchored by embedded software ecosystems and recurring service contract revenue models. Bruker Corporation exemplifies the specialized spectroscopy archetype through its European-market focus on optical emission systems. HORIBA Ltd. represents the Asia-Pacific environmental compliance specialization vector with portable X-ray fluorescence configurations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Bruker Corporation |
| Shimadzu Corporation |
| SPECTRO Analytical Instruments GmbH |
| HORIBA Ltd. |
| Analytik Jena AG |
| Malvern Panalytical Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silicon drift detector spot prices and argon gas futures cascade through metal analyzer manufacturing tiers, compressing margins on laboratory-grade optical emission systems while sustaining premium pricing on portable X-ray fluorescence configurations with integrated calibration intelligence.
Pricing Analysis
Distributor margins absorb 15-25 points on benchtop systems sold through regional system integrators, whereas direct-to-OEM contracts for aerospace qualification programs command volume discounts tied to multi-year service bundling. Pricing stratifies across premium optical emission spectrometers with argon infrastructure, standard energy-dispersive X-ray fluorescence units for environmental compliance, and economy handheld laser-induced breakdown spectroscopy devices for scrapyard mobility. Cost compression in the economy tier is intensifying because Chinese foundries are consolidating procurement through domestic integrators. Mid-tier metal fabricators in India's industrial corridors exhibit acute price sensitivity, while German automotive tier-one suppliers prioritize certification-grade precision over unit economics.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing corridors to European qualification laboratories is elevating landed costs for silicon drift detectors and microfocus X-ray tubes by double-digit percentages. Component fabrication concentrates in Japan, South Korea, and Taiwan, with final assembly distributed across Germany, China, and the United States. Specialized detector production rests on single-source dependencies for high-purity germanium crystal growth and ceramic substrate metallization. Tariff exposure on semiconductor-grade materials creates vulnerability for vendors without captive supply arrangements. Distribution runs through authorized service networks with ISO 17025-accredited calibration capabilities rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal analyzers function as a regulatory compounder where REACH substance identification mandates and EPA hazardous waste characterization rules create durable replacement demand regardless of industrial production cycles.
For Market Incumbents: Anchor recurring revenue through cloud-connected calibration ecosystems that extend instrumentation intelligence contracts beyond hardware replacement cycles. Deepen backward integration into silicon drift detector supply to mitigate single-source vulnerability from East Asian component concentration. Defend against portable X-ray fluorescence commoditization by embedding artificial intelligence signal processing that elevates operator skill thresholds for competitive alternatives. For New Entrants and Emerging Players: Mid-tier fabricators in India's Pune and Chennai corridors represent an underserved buyer archetype seeking operational flexibility without laboratory-grade capital intensity. Penetrate this segment through handheld laser-induced breakdown spectroscopy configurations with localized Hindi and Tamil language interfaces. Pursue environmental testing agencies in secondary Chinese municipalities where MEE discharge monitoring expansion outpaces incumbent service infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized spectroscopy houses possessing ISO 17025-accredited service networks in jurisdictions with tightening calibration traceability requirements. Long-term viability hinges on recurring instrumentation intelligence revenue exceeding 40 percent of total mix. Monitor NMPA enforcement intensity in China as the inflection indicator for benchtop replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Instrument Ecosystem | Enables predictive maintenance contracts with real-time calibration adjustment for Japanese METI traceability standards. |
| Backward Integration into Detector Components | Reduces vulnerability to silicon drift detector supply disruptions from concentrated East Asian manufacturing corridors. |
| Localized Service Infrastructure Expansion | Captures first-mover advantage in India's Pune and Chennai industrial corridors modernizing quality assurance protocols. |
| Artificial Intelligence Signal Processing | Compresses skill thresholds for accurate field-based analysis while differentiating against commodity portable alternatives. |
| ISO 17025 Accreditation Investment | Secures vendor qualification requirements from North American aerospace prime contractors unbundling hardware from services. |
Study Parameters
Bottom-up metal fabricator and environmental testing agency modeling reconciled against top-down spectroscopy and mass spectrometry equipment production tracking forms the analytical core of this analysis. Primary interviews with foundry quality control managers, environmental laboratory directors, OEM procurement specialists, and aftermarket service heads were validated against secondary sources including EPA enforcement databases, ECHA REACH registration filings, NMPA structural metal certification records, and customs trade data for detector component flows. Triangulation across these inputs ensures segmentation integrity across portable, benchtop, and laboratory-grade system categories.
Input-output matrices map instrument shipments by technology type and end-use application against regulatory compliance timelines and replacement cycle assumptions across the projection horizon. Segmentation dimensions include product mobility tier, detection methodology, end-user operational scale, and application workflow depth. CAGRs were derived from regression analysis of historical procurement patterns against regulatory milestone schedules, with specific weighting for NMPA enforcement intensity and REACH substance identification expansion rates.
Underlying measurement precision varies by segment; optical emission spectrometers and mass spectrometry configurations carry tighter precision than portable X-ray fluorescence economy tiers due to established installation base visibility. Forecasts reflect assumptions regarding regulatory enforcement continuity, component supply stability, and technician training pipeline adequacy. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
HERG Screening Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Spectrum Analyzer Market