
 Automatic Labeling Machine Market | 2026-2036
Automatic Labeling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Labeling Machine Market Analysis
Pharmaceutical packaging is repositioning automatic labeling equipment toward serialization-ready configurations. Krones AG leverages its beverage systems heritage to compete in high-speed pharma lines. Syntegon Technology GmbH specializes in containment-compatible labeling for sterile injectables. Herma GmbH anchors its position through precision self-adhesive applicator technology.
An automatic labeling machine applies pre-printed or print-on-demand labels to products, containers, or packaging using mechanical, pneumatic, or servo-driven dispensing systems with positioning accuracy typically measured in millimeters. The equipment serves primary functions across batch coding, regulatory compliance marking, brand decoration, and supply chain traceability in continuous production environments. Pressure sensitive technology dominates installed capacity due to its material flexibility and changeover speed, while shrink sleeve systems capture premium positioning in cosmetics and beverage segments where full-body decoration commands higher margins. Flat bottle configurations lead unit shipments given their prevalence in food and personal care, though pouch formats are gaining traction in single-serve pharmaceutical and nutraceutical applications.
FDA DSCSA requirements for pharmaceutical distribution traceability and EU MDR device labeling standards are forcing equipment upgrades toward vision-verified, database-integrated systems. CE marking and ISO 9001 compliance remain baseline requirements for market access across European and North American procurement channels. Stakeholders must evaluate retrofit compatibility against greenfield specifications as regulatory deadlines compress investment cycles.
Market Dynamics
Pharmaceutical serialization mandates are compressing equipment replacement cycles as manufacturers race to install vision-verified, database-integrated labeling systems before regulatory deadlines.
Growth Catalysts
- FDA DSCSA Traceability Mandates:US pharmaceutical distributors must achieve unit-level traceability, forcing wholesale adoption of serialization-ready automatic labeling equipment across packaging lines.
- EU MDR Device Labeling Standards:European medical device manufacturers face expanded UDI requirements, accelerating investment in high-precision applicators with integrated verification cameras.
- Shrink Sleeve Technology:Cosmetics and beverage producers in South Korea and Germany are expanding full-body decoration capacity to capture premium positioning through 360-degree brand presentation.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 stainless steel price swings directly impact equipment manufacturing costs, squeezing margins for mid-tier machinery producers.
- Precision Component Supply Concentration:Servo motors and machine vision sensors concentrate among Japanese and German suppliers, creating vulnerability for equipment assemblers elsewhere.
- Technical Limitation in Curved Surface Application:Complex container geometries in personal care and nutraceuticals continue to challenge standard pressure-sensitive systems, requiring costly custom engineering.
Strategic Opportunities
- Contract Packaging Services:Third-party logistics providers in Germany and the Netherlands are expanding dedicated labeling capacity to serve fragmented pharmaceutical and food brands.
- Convergence of Print-on-Demand and Vision Verification:Integrated systems combining thermal transfer printing with real-time OCR inspection are opening retrofit markets among legacy bottling operations.
- India's PLI Scheme for Pharmaceuticals:Production-linked incentives for domestic drug manufacturing are stimulating greenfield packaging line investments with integrated track-and-trace capability.
Industry Challenges
- Mechatronics Skill Scarcity:Servo tuning, vision system calibration, and pneumatic integration expertise remain concentrated among aging technician populations in Germany and Japan.
- Legacy System Integration Complexity:Brownfield pharmaceutical facilities struggle to synchronize new serialization equipment with existing SCADA and MES architectures without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Labeling Machine Market |
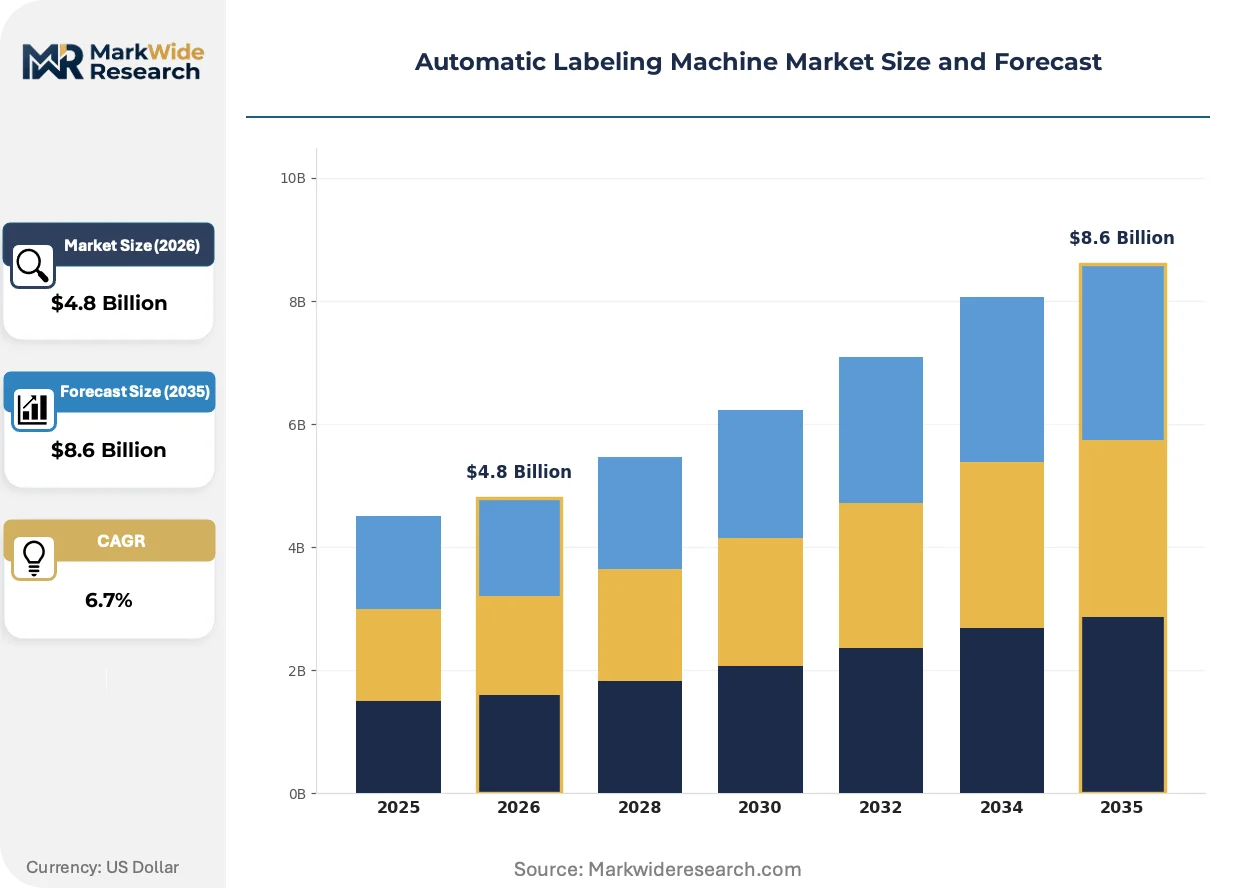
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bottle, Round Bottle, Jar, Pouch Technology: Pressure Sensitive, Shrink Sleeve, Hot Melt, Glue End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Installation: Standalone, Integrated, Semi-Automatic, Fully Automatic |
| Companies Covered | Krones AG, Sacmi, Sidel, KHS GmbH, Herma GmbH, ProMach, Accutek Packaging Equipment Companies, Marchesini Group, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Labeling Machine Market Emerging Trajectories
Equipment architecture is pivoting from standalone mechanical systems toward modular, data-connected platforms that synchronize with enterprise traceability databases and quality management systems.
Print-on-demand labeling technology is decentralizing quality control from centralized pre-print operations to individual packaging lines. Pharmaceutical manufacturers in Switzerland and the United States are adopting inline thermal transfer systems that generate variable data at the point of application, eliminating pre-print label inventory and reducing changeover downtime. This shift is decentralizing supply chain risk by removing dependency on external label converters and enabling lot-specific customization without material waste.
EU MDR and FDA DSCSA alignment is forcing harmonization of data carrier formats across Atlantic pharmaceutical trade. Dual-compliance equipment configurations now dominate procurement specifications for exporters serving both jurisdictions, compressing the viable supplier base to vendors with transatlantic certification support. Sterile injectable manufacturers face the steepest compliance burden, as containment-compatible labeling must simultaneously satisfy EMA and FDA validation protocols.
Contract packagers are unbundling equipment ownership from operational service, shifting toward equipment-as-a-service arrangements with performance-based uptime guarantees. This procurement evolution concentrates among mid-sized pharmaceutical and nutraceutical brands in the Netherlands and Belgium that lack capital for dedicated line investment. Food and personal care verticals in these markets are following suit, prioritizing operational flexibility over asset control.
Automatic Labeling Machine Market Segmentation
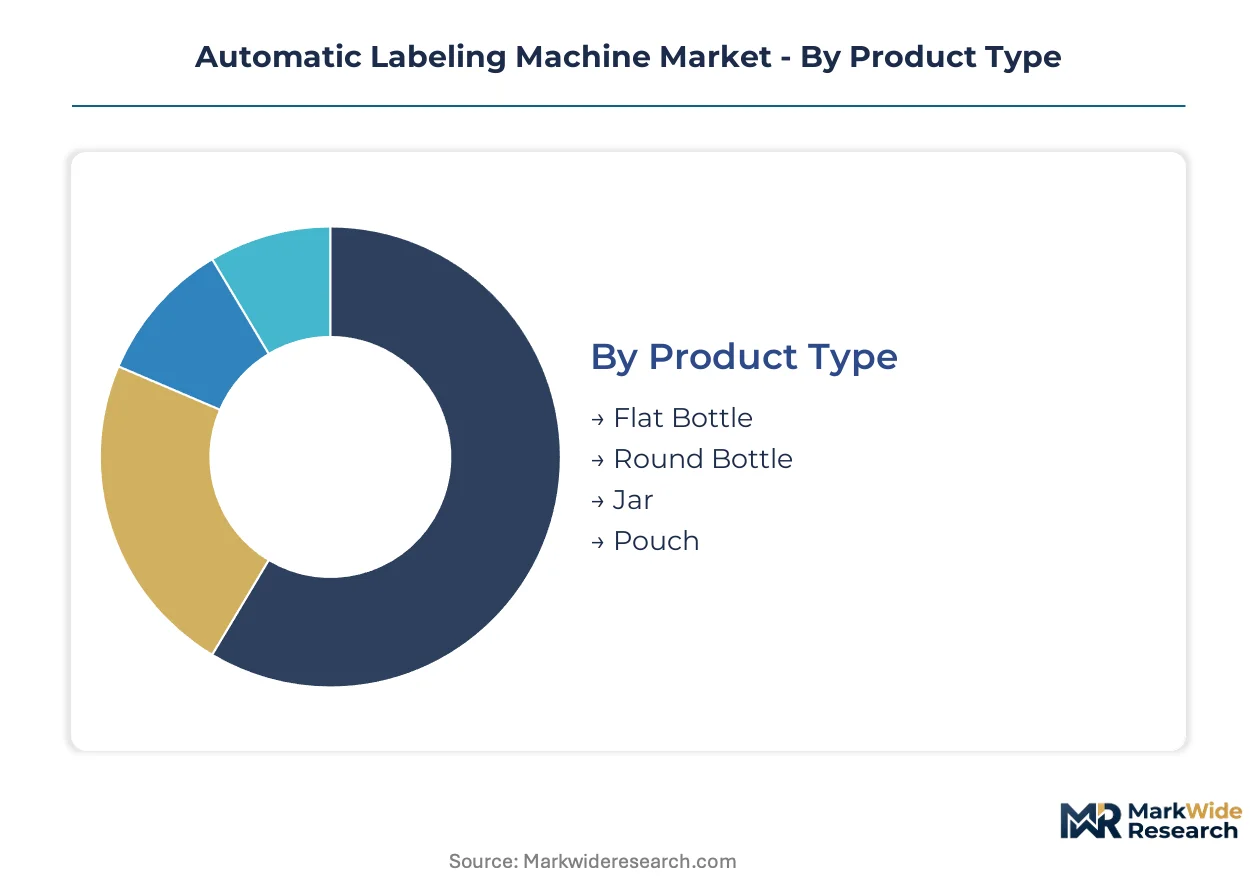
Equipment specification varies sharply across container geometry, adhesive chemistry, and line integration depth. Procurement patterns in automatic labeling machinery track end-use regulatory intensity rather than unit volume alone.
Product Type:
Upgrade cycles diverge sharply by container stability and label registration complexity.
- Flat Bottle:Rectangular or square cross-section containers with stable label landing surfaces dominate food and personal care packaging. Pharmaceutical contract manufacturers in Germany specify flat bottle systems for their compatibility with vision-verified serialization at line speeds exceeding 400 units per minute.
- Round Bottle:Cylindrical containers require rotary handling modules and skew correction algorithms. Beverage producers in South Korea deploy round bottle equipment for premium spirits where 360-degree label alignment demands servo-driven orientation.
- Jar:Wide-mouth containers with pronounced shoulder geometry challenge standard applicator reach. Nutaceutical brands in Switzerland favor jar configurations for protein powders and supplement stacks.
- Pouch:Flexible film formats with irregular sealing seams require specialized tension control. Single-serve pharmaceutical packaging in the United States is climbing fastest as unit-dose compliance packaging expands.
Volume placements concentrate in flat bottle configurations; the faster expansion belongs to pouch formats.
Technology:
Cost tiers separate by material waste rates and changeover labor intensity.
- Pressure Sensitive:Self-adhesive labels applied through pneumatic or servo-driven dispensing heads with peel plate precision. This technology anchors installed capacity across food and personal care due to substrate flexibility and 90-second format changeovers.
- Shrink Sleeve:Full-body polymer sleeves heat-shrunk to container contours command premium positioning. Cosmetics manufacturers in Germany and South Korea specify shrink sleeve systems where 360-degree brand presentation justifies 40% higher equipment investment.
- Hot Melt:Thermoplastic adhesive applied through heated nozzles enables high-speed paper labeling. Beverage bottlers in Belgium favor hot melt for returnable glass where wash-off requirements conflict with permanent adhesives.
- Glue:Water-based or synthetic cold adhesives applied through roller or spray systems. Emerging market beverage producers in India select glue technology for lowest material cost per thousand labels.
Pressure sensitive systems dominate unit placements; shrink sleeve configurations are gaining share fastest in premium positioning segments.
End User:
Customer type determines compliance burden and therefore equipment specification tier.
- Food & Beverage:High-volume, low-SKU-complexity operations prioritize throughput over traceability. German dairy cooperatives specify mid-tier systems with batch coding but omit serialization modules.
- Pharmaceuticals:Regulatory mandates under FDA DSCSA and EU MDR force vision-verified, database-integrated configurations. Swiss injectable manufacturers demand containment-compatible labeling with EMA and FDA dual validation.
- Cosmetics:Aesthetic precision and decoration flexibility outweigh speed requirements. South Korean skincare brands specify shrink sleeve and pressure sensitive hybrid lines for seasonal limited editions.
- Electronics:Small-format, high-accuracy labeling for components and retail packaging. Contract manufacturers in South Korea deploy compact rotary systems for smartphone accessory labeling.
Food and beverage operations anchor volume demand; pharmaceutical compliance investments are climbing the fastest.
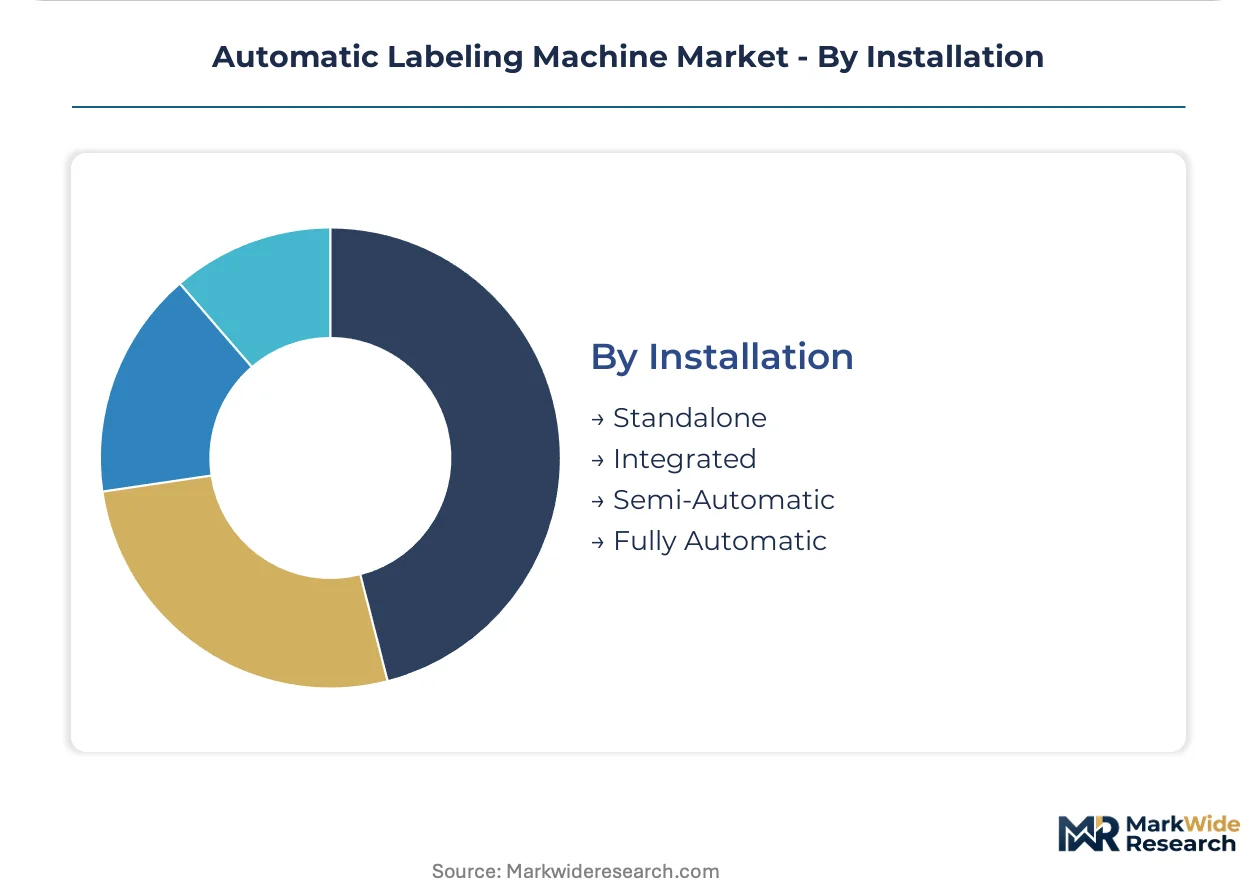
Installation:
Maturity curves separate brownfield retrofit from greenfield integrated line design.
- Standalone:Self-contained units with independent controls and manual feed or discharge. Small-batch nutraceutical producers in Belgium favor standalone configurations for operational flexibility.
- Integrated:Synchronized with upstream filling and downstream case packing through line control architecture. Pharmaceutical greenfield facilities in India specify integrated installations under PLI scheme incentives.
- Semi-Automatic:Operator-assisted loading with automated label application and discharge. Mid-tier cosmetics contract packagers in the Netherlands deploy semi-automatic systems for SKU proliferation management.
- Fully Automatic:Unattended operation with automatic feeding, application, inspection, and rejection. High-volume beverage bottlers in Germany specify fully automatic configurations for 24/7 production schedules.
Integrated installations lead capital commitment value; semi-automatic systems are expanding most quickly among contract packaging entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea and India's pharmaceutical corridors are concentrating automatic labeling equipment investment through tax-advantaged manufacturing incentives. FDA DSCSA and EU MDR deadlines are compressing procurement cycles across export-oriented production clusters.
Germany
Contract packaging services in the Netherlands-Belgium-Germany corridor are expanding dedicated labeling capacity for fragmented pharmaceutical brands. CE marking and ISO 9001 compliance remain baseline procurement requirements across European channels. The Baden-Württemberg precision engineering cluster hosts concentrated equipment R&D for containment-compatible sterile injectable systems.
United States
Pharmaceutical distributors must achieve unit-level traceability under FDA DSCSA mandates, forcing wholesale adoption of serialization-ready equipment. Single-serve pharmaceutical and nutraceutical packaging in New Jersey and Pennsylvania is climbing fastest as unit-dose compliance expands. The Boston-Cambridge biotech corridor demands vision-verified, database-integrated labeling configurations for clinical trial materials.
South Korea
Electronics manufacturing and premium beverage production are driving investment in high-accuracy rotary systems and full-body decoration equipment. MFDS pharmaceutical serialization requirements are accelerating track-and-trace system adoption alongside FDA export compliance. The Gyeonggi-do manufacturing belt concentrates both smartphone accessory labeling and cosmetics shrink sleeve capacity for 360-degree brand presentation.
India
Production-linked incentives under the PLI scheme for domestic drug manufacturing are stimulating greenfield packaging line investments with integrated track-and-trace capability. CDSCO alignment with international serialization standards is forcing equipment upgrades toward vision-verified configurations. The Maharashtra-Gujarat pharmaceutical corridor anchors capital commitment for serialization-ready automatic labeling systems.
Switzerland
Swissmedic validation protocols for sterile injectable manufacturers impose the steepest compliance burden for containment-compatible labeling equipment. Dual EMA-FDA validation capability concentrates procurement specifications among vendors with transatlantic certification support. The Basel-Lucerne pharmaceutical manufacturing cluster demands precision applicator technology for high-value biologic packaging.
Automatic Labeling Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical compliance requirements favoring established precision engineering houses over emerging fabricators. The vendor landscape organizes into three tiers: beverage-system heritage players with pharma line extensions, dedicated pharmaceutical containment specialists, and precision self-adhesive technology anchors. Consolidation pressure concentrates among mid-tier machinery producers squeezed by stainless steel input volatility and Japanese-German component supply concentration. Strategic moves center on retrofit compatibility engineering and equipment-as-a-service arrangements for contract packaging entrants.
Within the beverage-to-pharma extension tier, Krones AG and KHS GmbH represent archetypal transitions from high-speed bottling heritage into serialization-ready pharmaceutical configurations. Syntegon Technology GmbH exemplifies the containment-specialist archetype, occupying a position shaped by sterile injectable validation requirements. Herma GmbH anchors the precision-applicator technology segment, sitting within a competitive set defined by self-adhesive dispensing accuracy and changeover speed. These three company structures—AG, GmbH, and GmbH respectively—reflect the German engineering concentration that dominates transatlantic certification-capable equipment supply.
| Leading Market Players |
|---|
| Krones AG |
| Sacmi |
| Sidel |
| KHS GmbH |
| Herma GmbH |
| ProMach |
| Accutek Packaging Equipment Companies |
| Marchesini Group |
| Syntegon Technology GmbH |
| Others |
Supply Flow & Price Mechanics
Mechatronics expertise concentration in Baden-Württemberg and Nagoya feeds labor-cost differentials that widen pricing-tier spreads between precision-engineered pharmaceutical systems and standard food-grade configurations. Servo tuning and vision calibration skill scarcity in these clusters commands premium compensation that equipment manufacturers pass through to serialization-ready product lines.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to vision-verified pharmaceutical systems against standard delivery schedules, while spot inventory of mid-tier food-grade equipment trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels separates EMA-FDA dual-validated containment systems from CE-marked standard configurations and basic pressure-sensitive units without verification modules. Cost compression in mid-tier machinery is intensifying because stainless steel input volatility squeezes assemblers lacking backward integration into precision component supply. Contract packaging services in the Netherlands exhibit highest price sensitivity due to equipment-as-a-service procurement models, while Swiss sterile injectable manufacturers show least sensitivity given validation protocol requirements.
Supply Chain Analysis
Dual-sourcing qualification mandates from pharmaceutical OEMs force equipment assemblers to maintain approved supplier lists across Japanese and German servo motor producers. Component supply concentrates in Germany, Japan, and South Korea for machine vision sensors, precision peel plates, and rotary handling modules. Grade 304 and 316 stainless steel feedstock draws from European and Asian mill networks with price volatility transmitted directly to equipment manufacturing costs. Single-source vulnerability concentrates in high-resolution optical encoders and containment-grade pneumatic seals. Distribution runs through direct sales engineering teams for pharmaceutical compliance systems and regional distributor networks for standard food and beverage configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Precision component supply concentration is forcing equipment manufacturers toward in-house production of servo drives and vision systems to defend margin position.
For Market Incumbents: Acquire machine vision sensor calibration capabilities to reduce dependency on Japanese component suppliers facing allocation constraints. Consolidate regional service engineering footprints in the Germany-Netherlands-Belgium corridor where contract packaging density supports preventive maintenance revenue streams. Backward integration into stainless steel fabrication mitigates raw material margin compression from commodity price swings. For New Entrants and Emerging Players: Begin with semi-automatic pouch labeling configurations for single-serve pharmaceutical packaging in India where PLI scheme incentives reduce greenfield capital barriers. Target India's Maharashtra-Gujarat pharmaceutical corridor for initial equipment placement given CDSCO alignment pressures forcing vision-verified upgrades. Pursue equipment-as-a-service arrangements with mid-sized nutraceutical brands lacking internal mechatronics maintenance capability. For Investors and Strategic Acquirers: Re-rating potential sits with containment-compatible labeling specialists given EU MDR and FDA DSCSA deadline convergence accelerating replacement cycles. Long-term viability centers on vendors with transatlantic certification support and sterile injectable validation experience. Watch MFDS serialization mandate implementation timing as inflection indicator for South Korean export equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Production | Captive supply of precision motion components reduces allocation risk from Japanese suppliers. |
| Equipment-as-a-Service Launch | Performance-based uptime guarantees attract Netherlands contract packagers with capital constraints. |
| Dual EMA-FDA Validation Investment | Transatlantic certification capability opens Swiss sterile injectable and US biotech procurement channels. |
| Regional Service Engineering Expansion | Localized mechatronics expertise addresses skill scarcity in Germany's precision engineering clusters. |
| Inline Thermal Transfer Integration | Print-on-demand capability eliminates pre-print label inventory for Swiss pharmaceutical manufacturers. |
Methodological Framework
Independent corroboration across equipment manufacturer sales engineering teams, pharmaceutical packaging line operators, and contract packaging procurement directors underwrites the qualitative findings. Primary fieldwork encompassed interviews with maintenance directors at beverage bottlers, plant engineers at sterile injectable facilities, OEM procurement teams at electronics contract manufacturers, and aftermarket service heads at labeling equipment distributors. Secondary validation drew from FDA DSCSA guidance documents, EMA MDR technical specifications, MFDS serialization notices, CDSCO pharmaceutical packaging circulars, and trade customs data for labeling machinery imports. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections from pharmaceutical and food manufacturing sectors.
Rate-of-change decomposition across the analysis window separates volume growth from mix shift toward higher-value serialization-ready configurations. Segmentation dimensions modeled include container geometry stability, adhesive chemistry type, end-use regulatory intensity, line integration depth, and regional compliance cluster. CAGRs were derived from equipment replacement cycle compression analysis and greenfield investment flow tracking. Industry-specific forecast inputs encompassed pharmaceutical serialization deadline schedules and production-linked incentive scheme disbursement patterns.
Underlying measurement precision varies by segment; pharmaceutical compliance configurations carry tighter precision than standard food-grade equipment given transparent regulatory filing requirements. Forecasts reflect assumptions regarding stainless steel price stability, servo motor supplier allocation continuity, and regulatory deadline enforcement rigor. Deviation in EU MDR audit intensity or FDA DSCSA waiver extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Automated Tray Fill and Seal Machines Market