
 Brazil Food Ingredient Market | 2026-2036
Brazil Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Ingredient Market Analysis
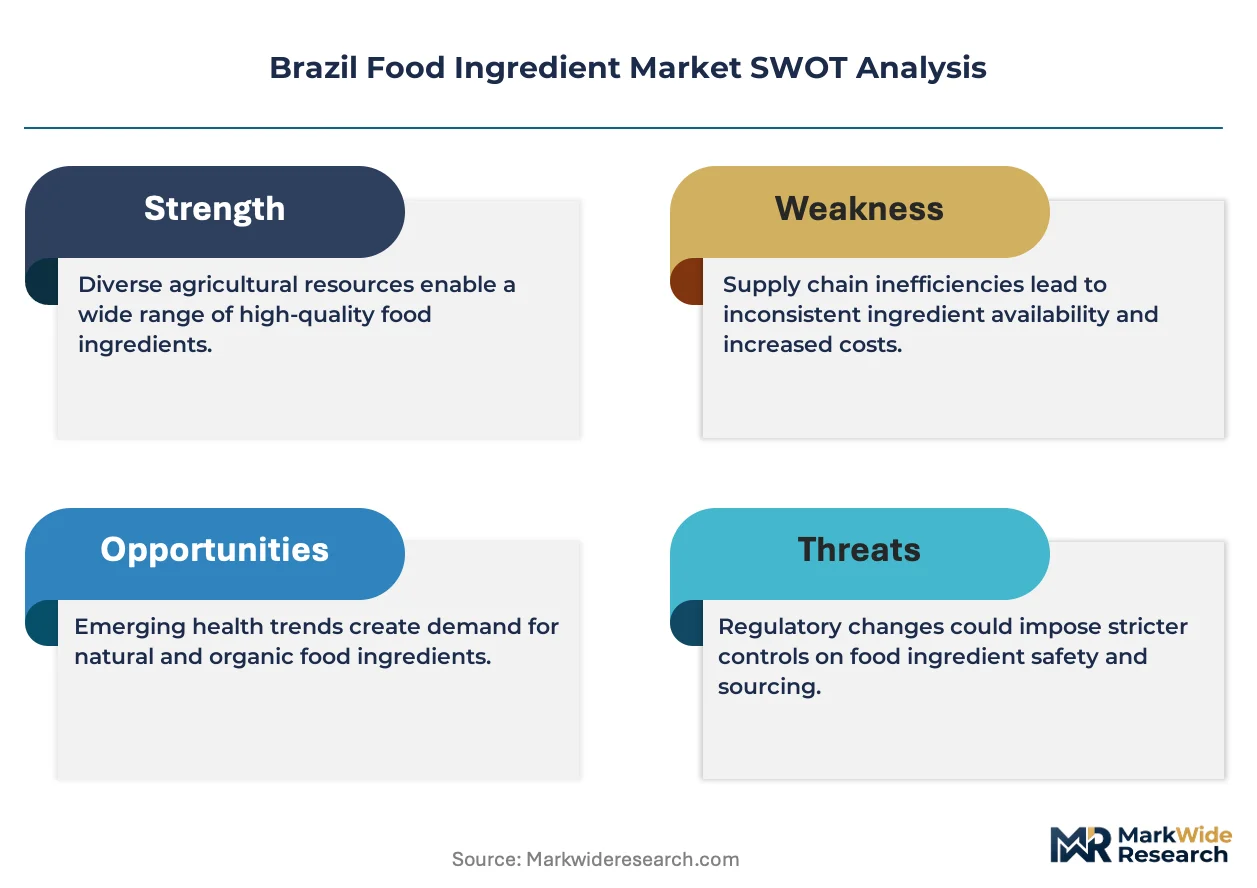
A shortage of food technologists trained in clean-label formulation is redrawing competitive boundaries across Brazil's ingredient sector. Cargill Incorporated leverages its integrated oilseed processing network to secure cost positions in emulsifier supply. Kerry Group anchors its position through specialized taste and nutrition solutions tailored to Brazilian palates. Bunge Limited competes on soybean-derived ingredient scale, while Givaudan SA differentiates through flavor creation capabilities developed at its regional innovation center.
Brazil food ingredients encompass functional additives, flavor systems, colorants, and texturizers formulated to enhance sensory properties, shelf stability, and processing performance in manufactured foods. These inputs typically undergo enzymatic modification, extraction, or fermentation processes to achieve precise viscosity, pH tolerance, or heat stability specifications required by industrial food production. Flavoring agents command the deepest margin pools as beverage and snack manufacturers prioritize taste differentiation in saturated categories. Stabilizers and emulsifiers are gaining share as dairy processors reformulate for extended shelf life under tropical distribution conditions. Colorants face structural pressure from natural source transitions, with annatto and turmeric extracts displacing synthetic alternatives in bakery and snack applications.
ANVISA governs food additive approvals and maximum usage limits, while the Ministry of Agriculture's MAPA oversees ingredient quality standards for animal and plant-derived inputs. The PLI scheme for food processing incentivizes domestic manufacturing of specialized ingredients previously imported. Stakeholders must monitor how ANVISA's accelerated review pathways for novel ingredients reshape first-mover advantages against established supplier relationships.
Market Dynamics
ANVISA's accelerated review pathways for novel ingredients are compressing time-to-market windows and forcing incumbent suppliers to defend formulation relationships against agile domestic entrants.
Growth Catalysts
- Clean-label reformulation mandates:Processed meat and poultry manufacturers are expanding procurement of natural stabilizers and colorants to meet retail chain requirements.
- PLI scheme for food processing infrastructure:Federal incentives are attracting capital investment into domestic manufacturing of specialized emulsifiers previously imported.
- São Paulo industrial corridor concentration:Proximity between multinational ingredient suppliers and major food manufacturers is reducing logistics costs and enabling just-in-time formulation support.
Market Restraints
- Soybean price volatility:Bunge and Cargill's cost positions in oilseed-derived emulsifiers remain exposed to commodity futures swings.
- Technical talent scarcity:Brazilian universities produce insufficient food technologists trained in clean-label enzymatic modification techniques.
- ANVISA approval bottlenecks:Novel fermentation-derived texturizers face extended safety review timelines that advantage established additive portfolios.
Strategic Opportunities
- Northeast Brazil dairy expansion:Bahia and Pernambuco processors are retrofitting plants for extended shelf-life formulations requiring tropical-stabilized emulsifiers.
- Natural colorant substitution wave:Annatto and turmeric extract demand is accelerating as bakery and snack manufacturers purge synthetic dyes.
- Enzyme-texturizer convergence:Cross-functional ingredients combining viscosity control with protein modification are opening premium positioning in plant-based meat analogs.
Industry Challenges
- Clean-label formulation expertise gap:Food manufacturers struggle to source technologists capable of replacing synthetic additives without compromising shelf stability.
- Legacy equipment retrofit costs:Dairy processors in Minas Gerais face capital outlays to handle heat-stable natural emulsifiers in existing UHT lines.
- ANVISA-MAPA jurisdictional overlap:Dual agency oversight of plant-derived inputs creates compliance timeline uncertainty for new ingredient launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Ingredient Market |
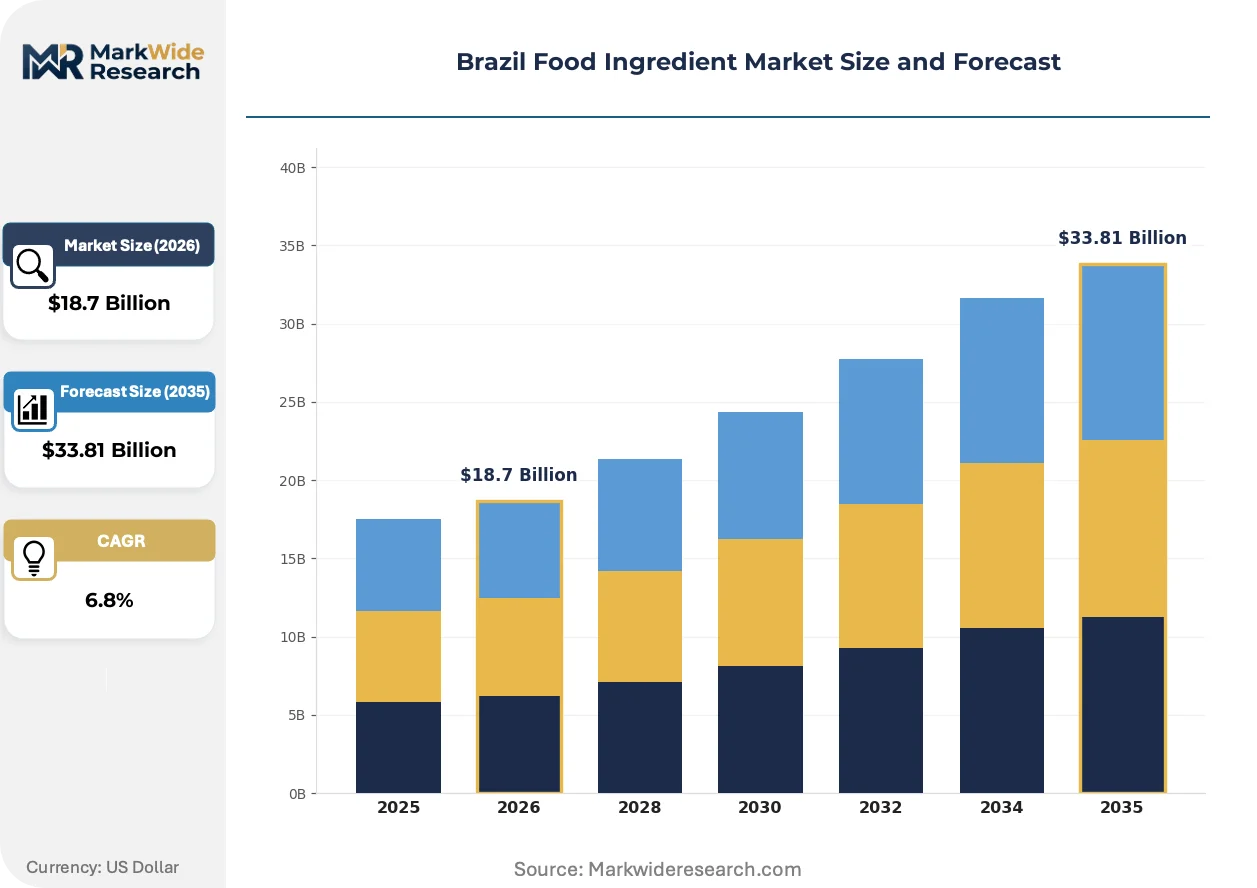
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Colorants, Stabilizers, Emulsifiers Application: Beverages, Dairy Products, Bakery, Snacks End User: Food Manufacturers, Restaurants, Retailers, Catering Services Distribution Channel: Online Sales, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, International Flavors & Fragrances Inc, Bunge Limited, Cargill Incorporated, Givaudan SA, Sensient Technologies, Kerry Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Ingredient Market Emerging Trajectories
Microencapsulation and fermentation-derived texturizers are redrawing technical specifications across Brazil's ingredient procurement patterns. Suppliers are racing to align R&D pipelines with regulatory acceleration and tropical distribution requirements.
Precision fermentation for customized protein hydrocolloids is miniaturizing production economics for regional suppliers. Mid-tier Brazilian ingredient houses are adopting modular bioreactor systems previously accessible only to multinational scale operations. This technology compression is enabling domestic entrants to challenge Kerry and Givaudan in specialized taste and texture solutions for regional snack brands.
ANVISA's updated food additive regulations are mandating expanded safety documentation for enzymatically modified starches. The agency's maximum usage limit revisions are forcing reformulation of legacy dairy and bakery applications. Processors in São Paulo state's industrial corridor are front-loading compliance investments to secure first-mover positioning in approved novel ingredient categories.
Direct technical service contracts are displacing traditional distributor relationships for complex stabilizer systems. Large meat and dairy processors are embedding supplier technologists within their formulation teams to accelerate clean-label transitions. This pattern concentrates in São Paulo and Rio Grande do Sul, where buyer consolidation enables unbundled procurement of technical support from commodity supply.
Brazil Food Ingredient Market Segmentation
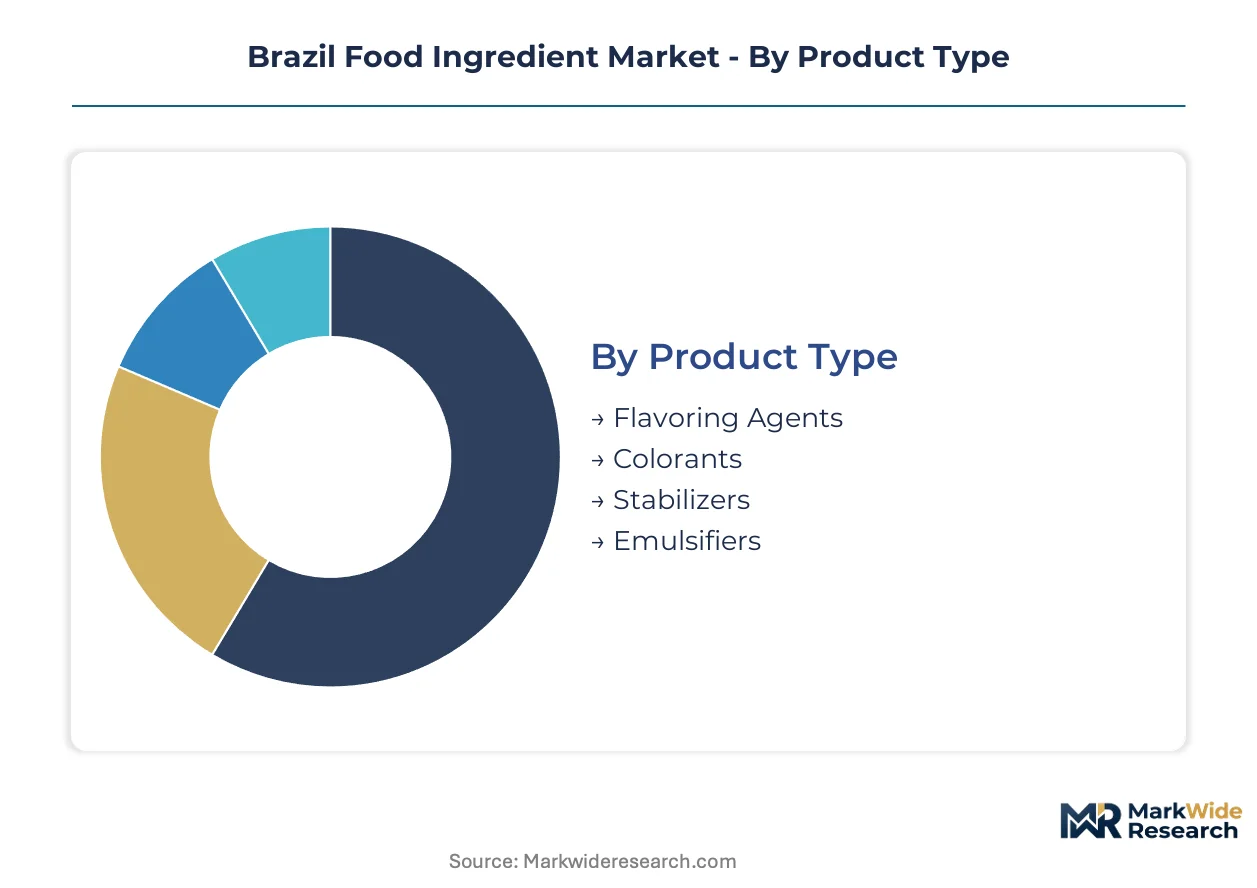
Ingredient procurement patterns across Brazil diverge sharply by functional role and customer scale. Manufacturers prioritize technical service depth while foodservice operators optimize for logistics flexibility and minimum order quantities.
Product Type:
Flavoring agents command the deepest margin pools within this category, driven by beverage and snack manufacturers seeking taste differentiation in saturated categories.
- Flavoring Agents:These comprise natural extracts, reaction flavors, and encapsulated volatile compounds formulated for heat stability and controlled release. São Paulo's industrial corridor concentrates demand from carbonated soft drink and savory snack producers reformulating for reduced sodium and sugar without taste compromise.
- Stabilizers:Hydrocolloids, modified starches, and protein-based texturizers manage viscosity and prevent syneresis in tropical distribution conditions. Dairy processors in Minas Gerais and Bahia are expanding procurement of heat-stable natural stabilizers as they retrofit UHT lines for extended shelf-life formulations.
- Colorants:Annatto, turmeric, and beet-derived pigments displace synthetic alternatives in bakery and meat applications. ANVISA's updated additive regulations are accelerating natural source transitions.
- Emulsifiers:Lecithin, mono- and diglycerides, and polysorbates enable fat-water dispersion in processed foods. Soybean price volatility constrains cost positions for oilseed-derived variants supplied by integrated processors.
Flavoring agents hold installed capacity. Stabilizers are rotating up the share rankings as dairy reformulation accelerates.
Application:
Volume concentration tracks Brazil's processed food production geography, with São Paulo state anchoring multisite procurement contracts.
- Beverages:Flavor systems, acidulants, and clouding agents for carbonated drinks, juices, and functional beverages. Multinational concentrate manufacturers in São Paulo's industrial corridor drive specification standards for tropical-stabilized emulsions.
- Dairy Products:Stabilizers, cultures, and enzymes for yogurt, cheese, and UHT milk. Northeast Brazil expansion in Bahia and Pernambuco is creating demand for heat-stable texturizers in extended shelf-life formulations.
- Bakery:Emulsifiers, enzymes, and natural colorants for bread, cakes, and biscuits. Clean-label mandates from retail chains are forcing rapid substitution of synthetic preservatives and azo dyes.
- Snacks:Seasonings, coatings, and moisture-control agents for chips, extruded products, and nuts. Regional Brazilian flavor preferences drive localized procurement of spice extracts and umami enhancers.
Beverages anchor volume commitments. Dairy is climbing the fastest as processors retrofit for tropical distribution.
End User:
Customer scale determines service model economics, with large manufacturers unbundling technical support from commodity supply.
- Food Manufacturers:Industrial-scale processors of meat, dairy, bakery, and beverage products. Direct technical service contracts are displacing distributor relationships for complex stabilizer systems in São Paulo and Rio Grande do Sul.
- Restaurants:Chain and independent foodservice operators sourcing prepared sauces, bases, and finishing ingredients. Procurement prioritizes consistent flavor profiles and simplified inventory management.
- Retailers:Private-label product developers and central kitchens for supermarket chains. Clean-label requirements are cascading down supplier qualification criteria.
- Catering Services:Institutional feeding operations and event service providers. Volume concentration is lower, with procurement fragmented across regional distributors.
Food manufacturers hold technical service relationships. Retailers are rotating up the share rankings as private-label development accelerates.
Distribution Channel:
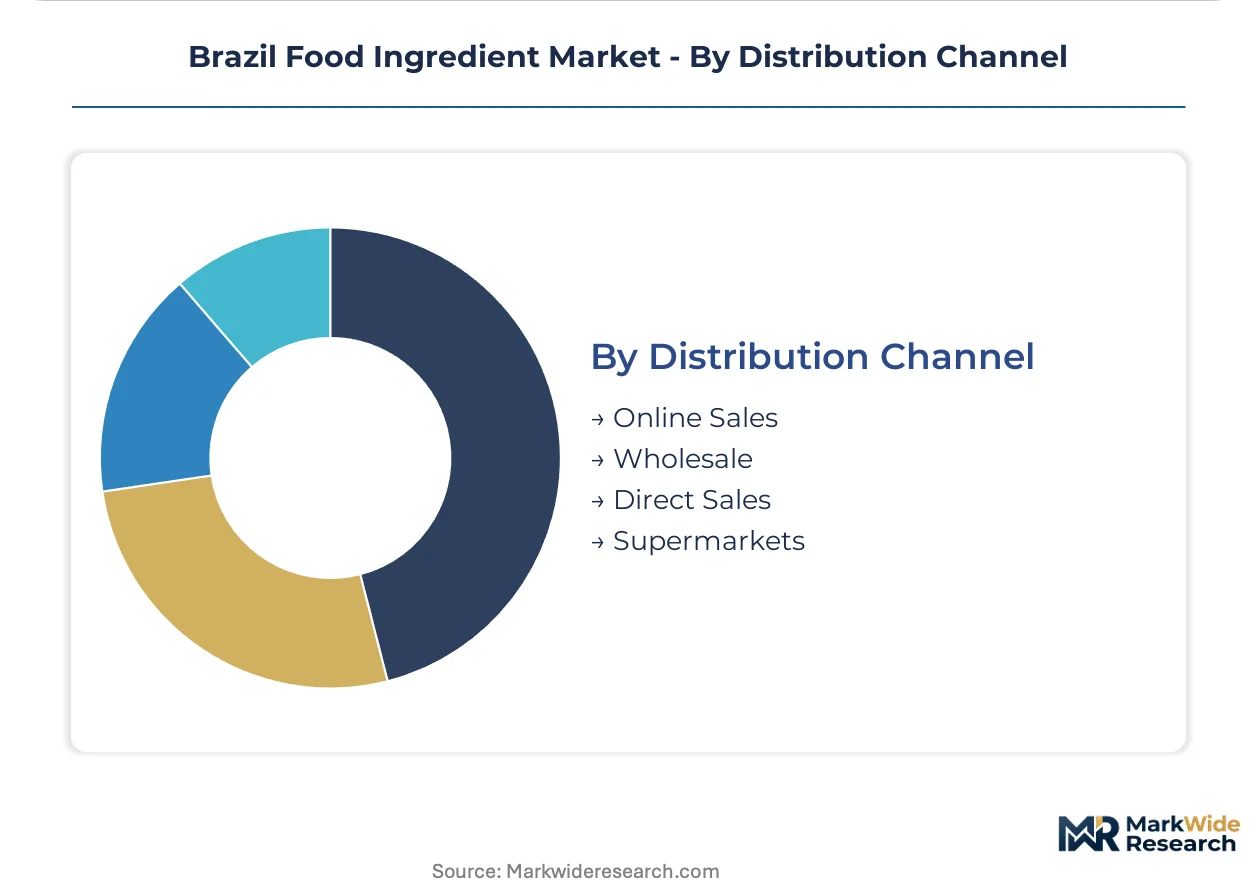
Channel selection reflects ingredient complexity and customer technical capability requirements.
- Direct Sales:Supplier-managed relationships for large manufacturers requiring formulation support and just-in-time delivery. São Paulo's industrial corridor enables embedded technologist models.
- Wholesale:Regional distributors serving mid-tier processors with consolidated ingredient portfolios. Logistics cost optimization drives channel selection for standard additives.
- Online Sales:Digital platforms for small manufacturers and foodservice operators with predictable specification requirements. Growth is constrained by technical service needs for complex formulations.
- Supermarkets:Limited ingredient sales through retail-packaged formats for consumer baking and cooking. Channel share is marginal for industrial-grade inputs.
Direct sales hold relationship density. Wholesale is rotating up the share rankings as distributor networks consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA governs food additive approvals across Brazil's federal structure, with state-level agricultural departments enforcing ingredient quality standards. The PLI scheme for food processing infrastructure is redirecting capital toward domestic manufacturing clusters.
São Paulo
Multinational concentrate manufacturers and savory snack producers drive specification standards for tropical-stabilized emulsions. The state's industrial corridor concentrates procurement contracts for carbonated soft drink flavor systems. Direct technical service relationships dominate as large processors embed supplier technologists within formulation teams.
Minas Gerais
Dairy processors retrofit UHT lines for extended shelf-life formulations requiring heat-stable natural stabilizers. MAPA oversees quality standards for milk-derived inputs and cultures. Belo Horizonte anchors a cluster of yogurt and cheese manufacturers sourcing enzymatic texturizers.
Bahia
Northeast Brazil's dairy expansion creates demand for tropical-stabilized emulsifiers in ambient distribution conditions. Federal incentives under the PLI scheme attract capital into domestic manufacturing of specialized ingredients. Salvador-based processors are front-loading compliance investments to secure ANVISA approval for novel fermentation-derived additives.
Rio Grande do Sul
Meat and poultry processors expand procurement of clean-label stabilizers and natural colorants to meet retail chain requirements. Buyer consolidation enables unbundled procurement of technical support from commodity supply. Porto Alegre's industrial zone concentrates processed meat formulation expertise.
Rio de Janeiro
Beverage manufacturers prioritize taste differentiation in saturated categories, deepening margin pools for flavoring agents. ANVISA's accelerated review pathways compress time-to-market windows for novel ingredients. The state's food technologist shortage forces processors to source formulation expertise from São Paulo-based suppliers.
Brazil Food Ingredient Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Brazil's ingredient sector. The market structures around integrated oilseed processors, specialized taste solution providers, and regional fermentation houses. Three archetypes dominate: multinational scale players with captive raw material access, mid-tier specialists in enzymatic modification, and domestic entrants leveraging modular bioreactor systems. Competitive moves concentrate on direct technical service contracts and embedded formulation partnerships.
Among the integrated processor tier, Cargill Incorporated and Bunge Limited anchor positions through upstream control over oilseed-derived emulsifier supply. Kerry Group and Givaudan SA occupy the specialized solutions vector, with the former representing taste and nutrition tailoring and the latter exemplifying regional flavor creation capabilities. These four names illustrate how competitive boundaries redraw around clean-label formulation expertise rather than commodity scale alone.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc |
| Bunge Limited |
| Cargill Incorporated |
| Givaudan SA |
| Sensient Technologies |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty days of inventory coverage for fermentation-derived texturizers concentrates pricing power among São Paulo-based suppliers with embedded technologist teams, while ANVISA approval timelines force buyers to absorb carrying costs for safety documentation.
Pricing Analysis
São Paulo industrial corridor pricing runs fifteen to twenty percent above Northeast Brazil for equivalent heat-stable emulsifiers, reflecting logistics premiums and direct technical service bundling. Three-tier pricing structure across premium, standard, and economy levels separates formulation-supported specialty ingredients from commodity hydrocolloids and unbranded natural extracts. Cost compression in standard-tier lecithin supply is intensifying because soybean futures volatility constrains integrated processors' margin buffers. Mid-tier dairy processors in Minas Gerais exhibit highest price sensitivity, while multinational beverage manufacturers in São Paulo prioritize specification compliance over unit cost.
Supply Chain Analysis
Brazil and Argentina anchor South American oilseed crushing capacity for lecithin and mono-diglyceride feedstocks, while India and China supply turmeric and annatto extracts for natural colorant transitions. Domestic supply draws from soybean oilseed networks, imported spice extraction inputs, and modular bioreactor systems for precision fermentation. Single-source vulnerability concentrates in fermentation-derived hydrocolloids where ANVISA approval bottlenecks limit qualified suppliers. Distribution runs through direct sales relationships for large manufacturers requiring just-in-time formulation support, with wholesale distributors consolidating mid-tier processor portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded technical service contracts are functioning as platform lock-in mechanisms, with supplier technologists becoming de facto extensions of buyer R&D teams and interoperability standards emerging around clean-label formulation protocols.
For Market Incumbents: Consolidate formulation relationship density by embedding technologists within São Paulo and Rio Grande do Sul processor R&D teams, and secure backward integration into annatto and turmeric extraction to defend margin position against commodity price swings. Modular bioreactor entrants threaten specialty hydrocolloid positioning; counter through exclusive direct service contracts with dairy retrofit programs in Bahia and Pernambuco. For New Entrants and Emerging Players: Technical service gaps in Northeast Brazil dairy expansion create entry points for regional fermentation houses with tropical-stabilization expertise. Target Bahia processors retrofitting UHT lines for extended shelf-life formulations, where incumbent response times lag due to São Paulo-centric resource allocation. Lead with enzyme-texturizer convergence products for plant-based meat analogs, leveraging ANVISA accelerated review pathways to compress first-mover windows. For Investors and Strategic Acquirers: Long-term, this sits as a capability-accumulation play because clean-label formulation expertise is accumulating faster than Brazilian universities can replenish technical talent pipelines. Target mid-tier enzymatic modification specialists with established ANVISA dossier libraries and embedded relationships with Minas Gerais dairy processors. Watch for inflection when PLI scheme incentives redirect toward domestic precision fermentation capacity versus imported specialty ingredient substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Extraction | Cargill and Bunge are securing annatto and turmeric supply chains to stabilize colorant margins against import volatility. |
| Embedded Technologist Deployment | Kerry Group positions taste specialists within São Paulo beverage R&D teams to accelerate clean-label reformulation cycles. |
| Modular Bioreactor Scale-Up | Domestic fermentation houses are challenging multinational hydrocolloid suppliers through precision protein texturizer production. |
| Direct Service Contract Unbundling | Large meat processors in Rio Grande do Sul are separating technical support procurement from commodity ingredient supply. |
| PLI-Aligned Domestic Manufacturing | Federal incentives are attracting capital into specialized emulsifier production previously imported from Asian suppliers. |
Methodological Framework
A standing panel of food technologists, procurement directors at São Paulo-based multinationals, ANVISA regulatory affairs specialists, and dairy plant managers in Minas Gerais provided ongoing calibration across primary interview rounds. Secondary validation drew from ANVISA additive approval databases, MAPA quality standard filings, Brazilian customs trade records for ingredient imports, and PLI scheme infrastructure disbursement reports. Bottom-up segment sizing triangulated against top-down macroeconomic consumption projections.
Consistency checks validated volume and value outputs against external benchmarks including industrial food production indices, regional dairy processing capacity utilization rates, and beverage manufacturer formulation spend patterns. Segmentation modeling incorporated product type, application, end-user scale, and distribution channel complexity dimensions across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory acceleration effects and PLI incentive uptake curves.
Forecasts assume regulatory continuity in ANVISA additive approval regimes and MAPA quality enforcement frameworks; material policy shifts would require re-modeling. Specific risks include ANVISA-MAPA jurisdictional clarification, soybean commodity price dislocation, and technical talent pipeline constraints. Recalibration cycles align with material shifts in PLI scheme implementation, ANVISA review pathway modifications, and regional dairy capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
Phytogenic Feed Additives Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market