
 Military Fixed-Wing Aircraft Market | 2026-2036
Military Fixed-Wing Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Fixed-Wing Aircraft Market Analysis
Capital-intensity divergence between full-spectrum primes and specialized subsystem houses is redrawing competitive boundaries in military fixed-wing aircraft. Lockheed Martin leverages its captive stealth fabrication complex to dominate fifth-generation fighter production. Boeing sustains strategic airlift and tanker franchises through integrated military-civilian manufacturing infrastructure.
Military fixed-wing aircraft encompass crewed, powered, heavier-than-air platforms designed for sustained atmospheric flight exceeding 300 knots, incorporating aluminum-lithium alloy airframes, fly-by-wire control architectures, and radar-absorbent material treatments for signature management. Fighter jets command the largest value pool due to unit costs exceeding 80 million dollars per airframe and embedded sensor-fusion electronics. Surveillance aircraft represent the fastest-expanding capability segment as sovereign nations prioritize long-endurance intelligence collection over manned penetration missions.
FAA airworthiness certification for military derivative platforms, ITAR export controls administered by the US State Department, and EASA military type certificate processes collectively govern market access and foreign military sale eligibility. Procurement officers and defense acquisition executives must monitor evolving electromagnetic spectrum warfare requirements and sovereign content mandates that will determine supplier qualification criteria.
Market Dynamics
Adaptive cycle propulsion systems are compressing engine development timelines while stealth composite fabrication concentrates production among three qualified suppliers, fundamentally restructuring prime contractor relationships and tier-one sourcing obligations.
Growth Catalysts
- ITAR Export Framework Modernization:The US State Department's streamlined foreign military sale licensing protocols are accelerating platform delivery schedules to NATO allies and Indo-Pacific partners.
- Multi-Domain Interoperability Mandates:Air forces in Japan, the United Kingdom, and Australia are prioritizing sensor-fusion architectures that integrate space, cyber, and electronic warfare capabilities.
- Aluminum-Lithium Alloy Diffusion:Advanced airframe materials are reducing structural weight by fifteen percent while extending fatigue life, enabling extended-range missions without aerial refueling dependency.
Market Restraints
- Titanium Sponge Supply Concentration:Russian and Chinese smelters control seventy percent of aerospace-grade titanium feedstock, exposing Western primes to geopolitical supply disruption.
- FAA-EASA Certification Divergence:Inconsistent military type certificate requirements between US and European regulators are fragmenting platform development roadmaps and inflating compliance costs.
- Unmanned Platform Substitution:Long-endurance surveillance drones are absorbing mission profiles previously assigned to crewed reconnaissance aircraft, compressing demand for manned penetrator variants.
Strategic Opportunities
- Poland's Accelerated Fighter Procurement:Warsaw's defense modernization program is creating immediate demand for fourth-plus-generation interim platforms pending fifth-generation delivery.
- India's Indigenous Content Mandates:The country's PLI scheme for defense manufacturing is incentivizing joint ventures with foreign primes for local airframe assembly and subsystem integration.
- Digital Twin Convergence:Integration of physics-based modeling with operational flight data is enabling predictive maintenance contracts that extend platform service life beyond original design specifications.
Industry Challenges
- Electromagnetic Spectrum Warfare Talent Scarcity:Prime contractors face acute shortages of engineers proficient in radar cross-section optimization and low-observable antenna integration.
- Legacy System Interface Complexity:New platforms must maintain backward compatibility with NATO Link 16 and proprietary national datalink architectures, inflating software integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Fixed-Wing Aircraft Market |
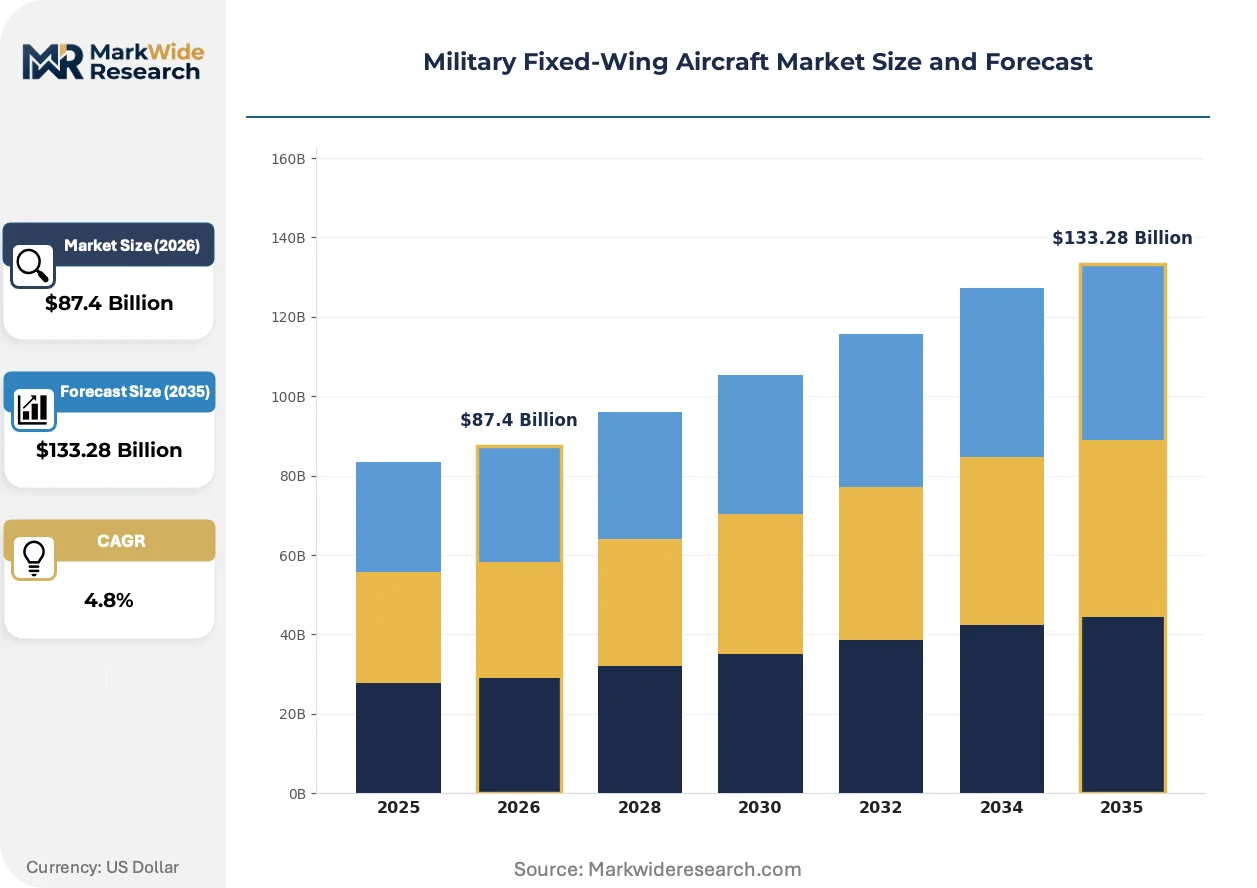
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Fighter Jets, Surveillance Aircraft, Transport Aircraft, Trainer Aircraft End User: Air Force, Naval Aviation, Government Agencies, Defense Contractors Technology: Avionics, Propulsion Systems, Navigation Systems, Communications Equipment Capability: Reconnaissance, Air Mobility, Combat Support, Aerial Refueling |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Airbus Defence and Space, Northrop Grumman Corporation, BAE Systems plc, Dassault Aviation, Leonardo S.p.A., Saab AB, Hindustan Aeronautics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Fixed-Wing Aircraft Market Emerging Trajectories
Stealth fabrication techniques and sovereign content requirements are actively restructuring supplier qualification criteria, compressing the qualified vendor base while elevating technical performance thresholds for new market entrants.
Directed energy weapon hardening is displacing conventional electromagnetic interference shielding across next-generation fighter programs. The US Air Force and Royal Air Force are mandating integrated laser-resistant coatings and power-distribution architectures on all Block 4+ procurement contracts. This capability shift is displacing legacy arc-jet testing protocols and forcing primes to retool thermal protection qualification facilities.
REACH chemical restrictions in Europe are banning hexavalent chromium surface treatments and specific composite resin formulations previously standard in military airframe production. EASA's military type certificate division is enforcing alternative compliance pathways for corrosion protection and radar-absorbent material bonding. Fighter and trainer platforms destined for European operators are most affected, with primes accelerating plasma electrolytic oxidation process qualification.
Performance-based logistics contracts are supplanting traditional spares-and-repair procurement across Anglo-American defense acquisition. The UK Ministry of Defence and US Defense Logistics Agency are consolidating vendor-managed inventory responsibility with prime contractors, transferring obsolescence risk upstream. This contractual evolution is most visible in F-35 sustainment operations, where Lockheed Martin assumes full availability accountability across eight international partner nations.
Military Fixed-Wing Aircraft Market Segmentation
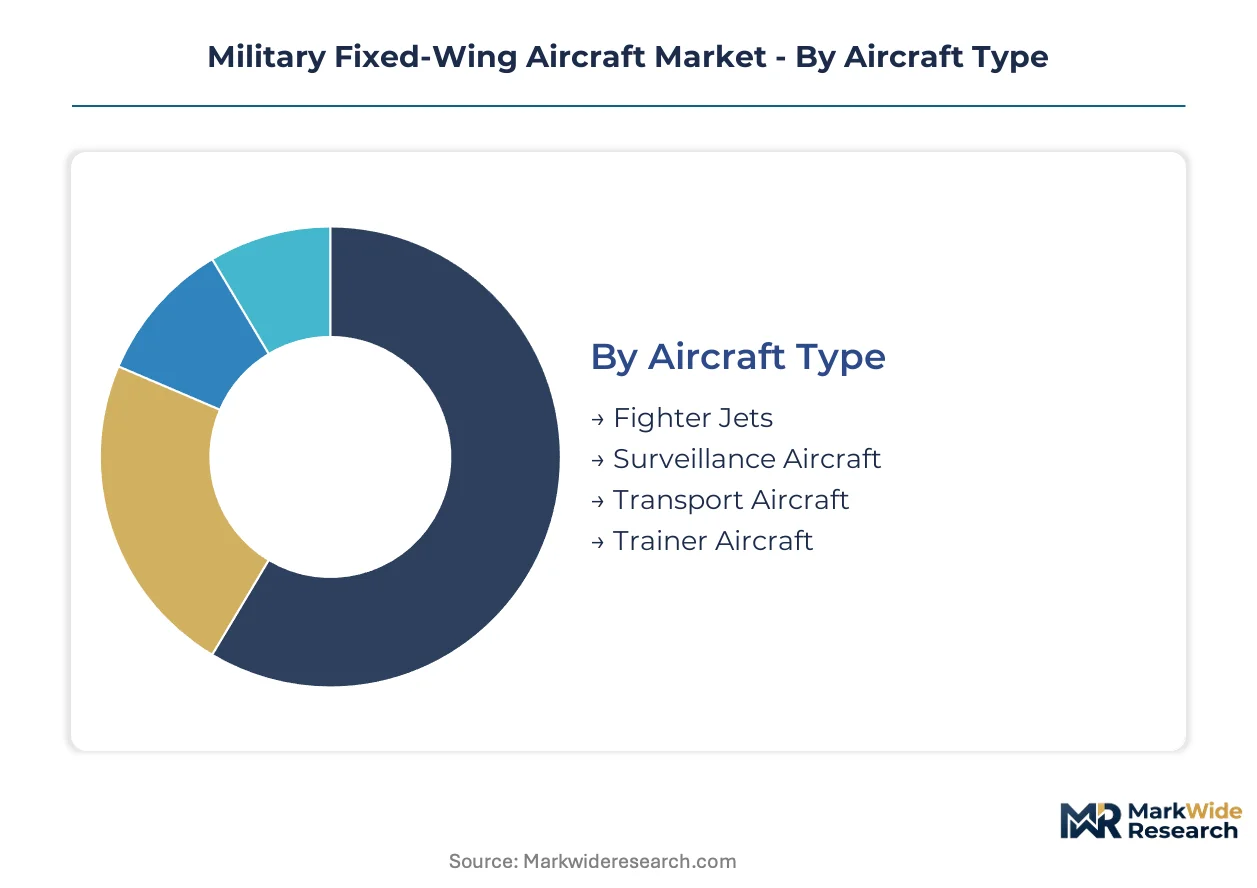
Segmentation in military fixed-wing aircraft reveals how procurement priorities diverge across mission profiles and funding authorities. Understanding these divides exposes where unmanned substitution pressures concentrate and where crewed platforms retain irreplaceable strategic value.
Aircraft Type:
Surveillance aircraft face the most acute substitution pressure from long-endurance unmanned platforms, while fighter and transport categories maintain crewed-platform dominance due to mission complexity and payload requirements.
- Fighter Jets:Crewed combat platforms incorporating stealth airframes, adaptive cycle engines, and integrated electronic warfare suites. Demand concentrates in Japan, the United Kingdom, and Poland as NATO and Indo-Pacific allies accelerate fifth-generation procurement timelines.
- Surveillance Aircraft:Long-endurance crewed platforms equipped with synthetic aperture radar and signals intelligence arrays. Mission profiles in the United States and Australia increasingly shift toward unmanned alternatives, compressing procurement volumes for manned penetrator variants.
- Transport Aircraft:Strategic and tactical airlifters with aluminum-lithium alloy structures and defensive countermeasure suites. Boeing sustains production dominance through integrated military-civilian manufacturing infrastructure.
- Trainer Aircraft:Intermediate and advanced pilot instruction platforms with embedded virtual reality mission systems. Poland's accelerated fighter procurement generates immediate demand for fourth-plus-generation interim training capacity.
Fighter jets anchor the volume base while surveillance aircraft gains share at the steepest rate despite unmanned substitution headwinds.
End User:
Cost-tier stratification separates sovereign air forces with full-spectrum procurement authority from defense contractors operating under foreign military sale constraints.
- Air Force:Primary service branch operating fighter, transport, and surveillance fleets with organic maintenance infrastructure. The US Air Force and Royal Air Force mandate directed energy weapon hardening on all Block 4+ procurement contracts.
- Naval Aviation:Carrier-based and maritime patrol units requiring corrosion-resistant coatings and arrested-recovery structural reinforcements. FAA-EASA certification divergence fragments platform development roadmaps for carrier-compatible variants.
- Government Agencies:Intelligence community operators prioritizing specialized mission equipment over standard combat configurations. ITAR export controls administered by the US State Department govern foreign military sale eligibility for signals intelligence platforms.
- Defense Contractors:Private military service providers and foreign prime subcontractors operating leased or second-hand platforms. India's PLI scheme for defense manufacturing incentivizes joint ventures for local airframe assembly within this channel.
Air Force commands the revenue concentration while Government Agencies expand procurement most quickly through classified intelligence program budgets.
Technology:
Supply concentration in stealth composite fabrication and adaptive cycle propulsion creates bottleneck dependencies that reshape tier-one sourcing obligations.
- Avionics:Integrated sensor-fusion architectures combining radar, electronic warfare, and communications arrays. Japan and Australia prioritize multi-domain interoperability mandates that integrate space and cyber capabilities.
- Propulsion Systems:Adaptive cycle engines compressing development timelines while reducing fuel consumption across mission profiles. Russian and Chinese titanium sponge smelters control seventy percent of aerospace-grade feedstock, exposing Western primes to geopolitical disruption.
- Navigation Systems:GPS-denied positioning architectures incorporating inertial reference and celestial backup modes. REACH chemical restrictions in Europe are banning hexavalent chromium surface treatments previously standard in military airframe production.
- Communications Equipment:Low-probability-of-intercept datalinks and satellite communications terminals. Legacy system interface complexity inflates software integration timelines as new platforms must maintain backward compatibility with NATO Link 16.
Avionics captures the margin concentration while Propulsion Systems faces the steepest supplier qualification compression.
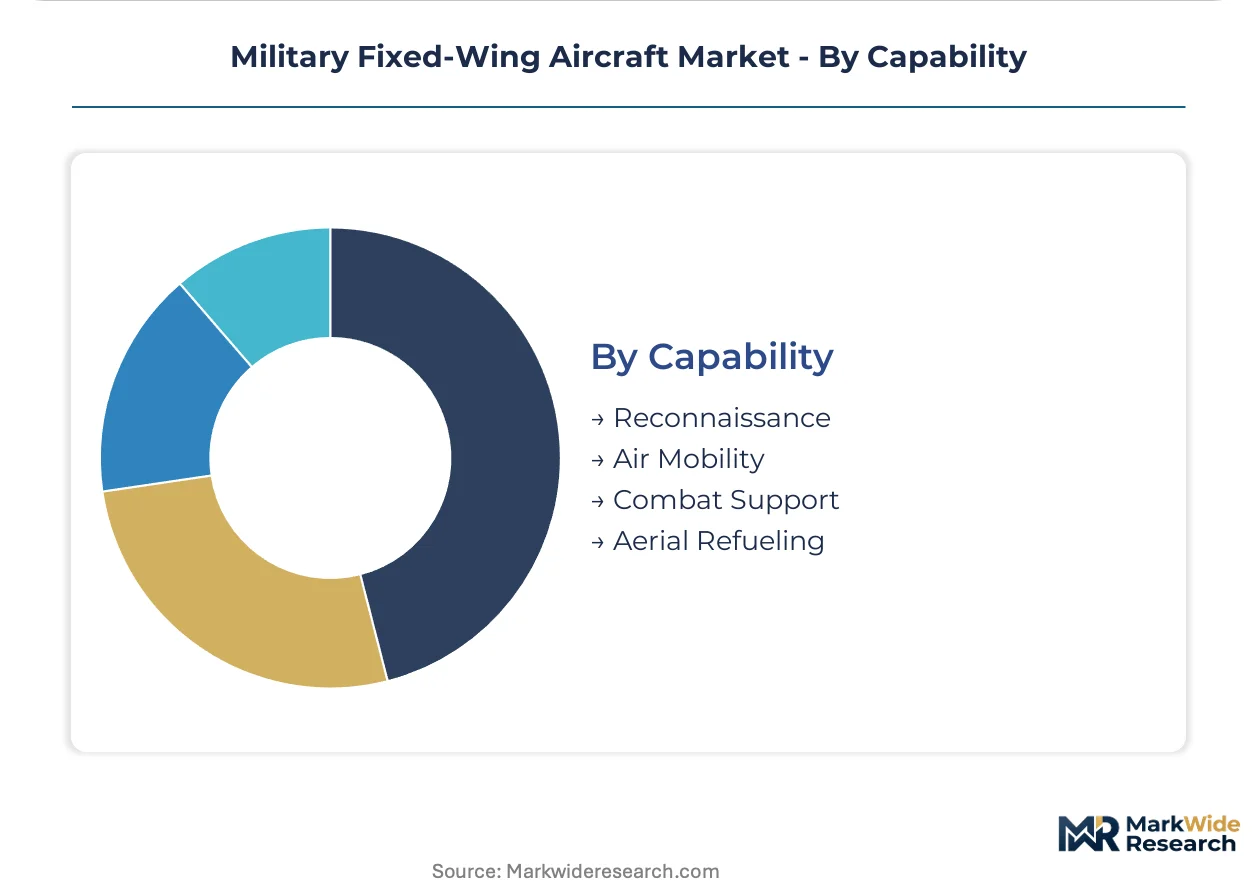
Capability:
Application maturity separates established mission categories with defined doctrine from emerging capability areas requiring operational concept development.
- Reconnaissance:Intelligence collection missions spanning visual, electronic, and signals disciplines. Long-endurance surveillance drones are absorbing profiles previously assigned to crewed reconnaissance aircraft.
- Air Mobility:Personnel and cargo transport across strategic distances with or without aerial refueling. Aluminum-lithium alloy diffusion is reducing structural weight by fifteen percent while extending fatigue life for extended-range missions.
- Combat Support:Close air support, interdiction, and suppression of enemy air defenses. Electromagnetic spectrum warfare talent scarcity constrains radar cross-section optimization for next-generation programs.
- Aerial Refueling:Tanker operations extending fighter and surveillance platform endurance. Performance-based logistics contracts are supplanting traditional spares-and-repair procurement across Anglo-American defense acquisition.
Air Mobility anchors the fleet size base while Reconnaissance climbs the fastest despite unmanned platform substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Washington procurement corridors while Tokyo and London absorb technology premiums through foreign military sale frameworks. Sovereign air forces in Warsaw and New Delhi negotiate offset arrangements that compress margins for Western primes. Regulatory divergence between FAA and EASA fragments platform certification costs across Atlantic supply chains.
United States
The US Air Force drives fifth-generation fighter procurement through Block 4+ upgrade contracts mandating directed energy weapon hardening. FAA military type certificate processes govern platform airworthiness for export derivatives sold to NATO allies. Lockheed Martin's Fort Worth fabrication complex anchors stealth composite production for F-35 international partner nations.
United Kingdom
Royal Air Force Tempest program spending prioritizes sensor-fusion architectures integrating space and cyber domains. The UK Ministry of Defence consolidates vendor-managed inventory responsibility through performance-based logistics contracts transferring obsolescence risk upstream. BAE Systems' Lancashire engineering centers coordinate pan-European subsystem development for sixth-generation prototypes.
Japan
Japan Air Self-Defense Force procurement accelerates F-X indigenous fighter development alongside F-35B carrier-compatible variants. METI defense production committee reviews govern technology transfer agreements with US primes for local assembly partnerships. Mitsubishi Heavy Industries' Nagoya aerospace division integrates domestic content into airframe fabrication for Pacific deterrence postures.
Poland
Warsaw's defense modernization program generates immediate demand for fourth-plus-generation interim fighters pending F-35 delivery schedules. EU Green Deal REACH chemical restrictions accelerate plasma electrolytic oxidation qualification for corrosion protection on European-operated platforms. Polish Aviation Group's Mielec facility negotiates offset arrangements for subsystem integration into regional trainer procurement.
India
Indian Air Force procurement operates under PLI scheme incentives requiring foreign primes to establish joint ventures for local airframe assembly. DGFT import substitution mandates compress timelines for indigenous content achievement in fighter and trainer categories. Hindustan Aeronautics Limited's Bangalore complex manages licensed production agreements while developing Tejas Mk2 platforms for domestic squadron deployment.
Military Fixed-Wing Aircraft Market Vendor Landscape
Concentration sits with full-spectrum primes controlling captive stealth fabrication and adaptive cycle propulsion integration. Three qualified suppliers dominate radar-absorbent material bonding, compressing tier-one sourcing obligations for new market entrants. Strategic archetypes separate integrated platform houses from specialized subsystem fabricators and sovereign-content joint ventures. Competitive moves cluster around performance-based logistics contracting and backward integration into titanium sponge alternative supply chains.
Among US-based platform integrators, Lockheed Martin Corporation and The Boeing Company exemplify divergent specialization vectors within military fixed-wing aircraft. Lockheed Martin occupies a position representing fifth-generation stealth production concentration through captive fabrication infrastructure. The Boeing Company anchors strategic airlift and tanker franchises leveraging integrated military-civilian manufacturing footprints. European primes including Airbus Defence and Space and BAE Systems plc sit within transatlantic partnership structures balancing NATO interoperability mandates with sovereign content requirements. Dassault Aviation represents independent fighter platform development outside US foreign military sale frameworks.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Airbus Defence and Space |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Dassault Aviation |
| Leonardo S.p.A. |
| Saab AB |
| Hindustan Aeronautics Limited |
| Others |
Supply Flow & Price Mechanics
Plasma electrolytic oxidation process adoption replacing hexavalent chromium surface treatments under EU REACH restrictions is redrawing corrosion protection supply geography while elevating European platform pricing premiums relative to US-sourced alternatives. Western primes absorbing qualification costs for alternative bonding chemistry pass through elevated unit economics to NATO operators, compressing margin elasticity for tier-two subsystem houses.
Pricing Analysis
Configured-to-order fighter platforms command substantial premiums over Foreign Military Sale standard configurations, with customization depth spanning sensor-fusion architecture, sovereign datalink integration, and directed energy weapon hardening. Price differentiation rests on ITAR licensing tier and local content achievement thresholds, with Indian and Polish procurement officers exhibiting acute sensitivity to offset ratios while Japanese and Australian buyers prioritize interoperability over unit cost. Pricing pressure stems from performance-based logistics contract proliferation transferring availability risk to primes, tightening margins on long-tail sustainment revenue. Government Agencies and intelligence community operators demonstrate lowest price sensitivity, absorbing mission equipment premiums that Air Force procurement officers resist.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade titanium sponge dominates inventory strategy as Russian and Chinese smelter concentration exposes Western primes to geopolitical disruption, with Japanese and US defense contractors maintaining eighteen-month forward cover against supply interruption. Feedstock draws from Kazakhstan, Japan, and Saudi Arabia as alternative sponge sources, while radar-absorbent material bonding rests on three qualified US suppliers compressing tier-one sourcing obligations. Single-source vulnerability in stealth composite fabrication constitutes primary structural risk, with distribution running through prime contractor captive facilities rather than open merchant markets. Long-term offtake agreements with Japanese titanium processors are displacing spot procurement across F-35 partner nation supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among sovereign air forces with multi-domain interoperability mandates, fragmenting pricing leverage previously held by full-spectrum primes as Poland, India, and Japan negotiate offset-heavy procurement frameworks.
For Market Incumbents: Consolidate backward integration into titanium sponge alternative supply chains through offtake agreements with Japanese and Saudi processors, mitigating Russian and Chinese smelter concentration risk. Lockheed Martin and Boeing should deepen captive stealth fabrication capacity to defend against emerging subsystem houses challenging radar-absorbent material bonding qualifications. Performance-based logistics contract expansion transfers obsolescence risk upstream but demands predictive maintenance infrastructure investment. For New Entrants and Emerging Players: Lead with directed energy weapon hardening subsystem specialization targeting Royal Air Force and US Air Force Block 4+ upgrade timelines, where electromagnetic spectrum warfare talent scarcity creates penetrable white space. Poland's accelerated fighter procurement generates immediate demand for fourth-plus-generation interim platforms, offering lower qualification barriers than fifth-generation prime contracting. Joint venture structures with Hindustan Aeronautics Limited under India's PLI scheme provide go-to-market access without full foreign military sale certification burden. For Investors and Strategic Acquirers: The market sits at a modernization-cycle acceleration phase that favors adaptive cycle propulsion specialists and stealth composite fabricators with qualified supplier status. Long-term viability over the next decade rests on sovereign content mandate compliance capabilities across NATO and Indo-Pacific procurement frameworks. Acquisition targets should demonstrate EASA military type certificate pathway progress or FAA certification reciprocity. The signal to watch is ITAR export framework modernization velocity, where streamlined licensing protocols would re-rate foreign military sale eligibility premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Stealth Fabrication Expansion | Lockheed Martin's Fort Worth complex anchors F-35 production for eight partner nations. |
| Performance-Based Logistics Contracting | UK Ministry of Defence transfers vendor-managed inventory responsibility to prime contractors. |
| Joint Venture Under India's PLI Scheme | Foreign primes establish local airframe assembly partnerships with Hindustan Aeronautics Limited. |
| Alternative Titanium Sponge Offtake | Japanese and Saudi processors displace Russian and Chinese smelter dependency. |
| Plasma Electrolytic Oxidation Qualification | REACH chemical restrictions mandate hexavalent chromium replacement for European operators. |
Methodological Framework
A spread of perspectives from program executive officers at sovereign air forces, defense acquisition executives, prime contractor platform directors, and subsystem engineering leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with procurement officers in Washington, London, Tokyo, Warsaw, and New Delhi alongside secondary validation through FAA military type certificate filings, EASA regulatory notices, US State Department foreign military sale disclosures, and defense ministry budget appropriations documentation. Bottom-up build-ups across fighter, surveillance, transport, and trainer categories were triangulated against top-down macroeconomic and threat-environment scenarios.
Segmentation dimensions modeled span aircraft type, end user service branch, technology subsystem, and capability mission profile across the projection horizon. Fighter jet, surveillance, transport, and trainer volumes were projected through platform retirement timelines and replacement procurement schedules, with CAGRs derived from budget trajectory analysis and foreign military sale pipeline visibility. Adaptive cycle propulsion adoption curves, stealth composite fabrication capacity constraints, and sovereign content mandate compliance timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FAA-EASA certification reciprocity and ITAR export licensing protocols; material policy shifts would require re-modeling platform delivery schedules and international partner eligibility. Titanium sponge supply disruption, electromagnetic spectrum warfare talent scarcity, or unmanned platform substitution acceleration constitute specific risk factors warranting forecast revision. Revision becomes warranted when sovereign content thresholds cross eighty percent indigenous achievement or when REACH chemical restriction scope expands beyond hexavalent chromium treatments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Helicopter Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Electric Aircraft Market
Aircraft
Commercial Aerospace Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Global Helicopter Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Aerospace Turbojet Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market