
 Aircraft Pushback Tugs Market | 2026-2036
Aircraft Pushback Tugs Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Pushback Tugs Market Analysis
Airline fleet consolidation among low-cost carriers is decoupling procurement decisions from traditional airport authorities, fragmenting buyer power across independent ground handlers. TLD Group leverages its manufacturing scale to supply towbarless systems to major European hubs. JBT Corporation sustains channel control through long-term service contracts with North American cargo operators. Mototok International GmbH differentiates via compact remote-controlled units designed for narrow-body aircraft in constrained gate positions.
Aircraft pushback tugs are motorized vehicles engineered to move aircraft between gate positions and taxiways without engine power, typically generating drawbar pull forces from 20 to 70 metric tons depending on target aircraft weight class; their primary purpose is eliminating jet fuel consumption during ground maneuvering while preventing foreign object damage from engine thrust. Towbarless tugs dominate revenue pools due to faster coupling times and reduced manpower needs at high-frequency gates. Electric power source variants represent the fastest-growing structural category as airports phase out diesel equipment under local air quality mandates. Conventional tugs with diesel engines retain volume leadership in emerging markets where charging infrastructure remains underdeveloped.
The FAA mandates operational compliance under 14 CFR Part 139 for airport rescue and firefighting equipment compatibility, while the EU Green Deal imposes binding fleet decarbonization timelines that directly shape ground support equipment procurement specifications. EASA certification requirements for motorized tow vehicles enforce braking performance and visibility standards that filter market access for non-compliant manufacturers. Stakeholders must monitor evolving battery energy density thresholds and automated driver-assist validation protocols as these technical benchmarks increasingly determine contract eligibility at tier-one airports.
Market Dynamics
Europe's F-Gas Regulation and the EU Green Deal are compressing diesel equipment replacement cycles, forcing ground handlers to accelerate capital deployment toward electric traction systems before infrastructure readiness catches up.
Growth Catalysts
- Battery energy density thresholds:Lithium-ion pack improvements now enable 70-ton drawbar pull ratings previously exclusive to diesel platforms, expanding electric applicability to wide-body handling.
- EU Green Deal fleet decarbonization timelines:Binding mandates require major European airports to eliminate fossil-fuel ground support equipment by specified deadlines, creating procurement urgency.
- Germany manufacturing clusters:Concentrated production capabilities around Munich and Augsburg shorten lead times for towbarless system delivery across Central European hubs.
Market Restraints
- Lithium and copper input volatility:Battery pack raw material cost swings compress electric tug margins and extend payback calculations for fleet operators.
- Charging infrastructure underdevelopment:Emerging market airports in Southeast Asia and Sub-Saharan Africa lack grid capacity for high-amperage fast-charging installations.
- EASA braking performance certification:Extended validation timelines for new electric traction systems delay market entry by 12-18 months versus conventional platforms.
Strategic Opportunities
- India airport privatization wave:Greenfield terminals at Navi Mumbai and Jewar lack legacy diesel fleets, enabling pure-electric infrastructure design from commissioning.
- Autonomous driver-assist validation:Convergence of LiDAR positioning and teleoperation protocols creates remote-controlled tug categories for ultra-narrow gate positions.
- US Inflation Reduction Act clean vehicle credits:Section 45W commercial vehicle incentives offset 30% of electric tug acquisition costs for ground handlers serving domestic carriers.
Industry Challenges
- High-voltage technician scarcity:Maintenance crews trained in 800V battery management systems remain concentrated at OEM service centers, constraining independent ground handler autonomy.
- Legacy towbar coupling standardization:Mixed fleets of conventional and towbarless tugs require redundant training protocols and spare inventory, complicating workforce deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Pushback Tugs Market |
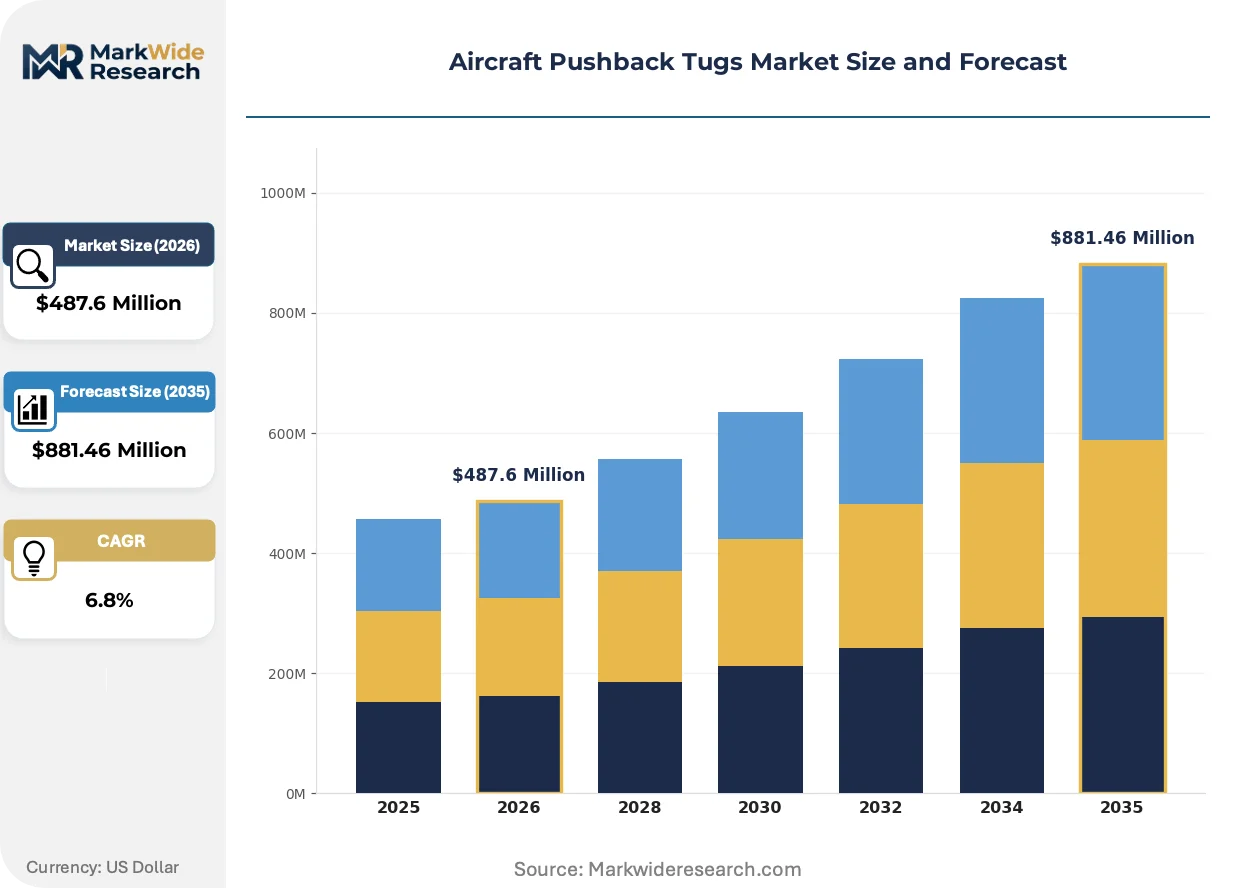
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Tugs, Towbarless Tugs, Electric Tugs, Hybrid Tugs Power Source: Diesel, Electric, Hybrid, Gasoline Driver Type: Manual, Automated, Semi-Automated, Remote-Controlled End User: Airports, Ground Handling Companies, Freight Carriers, Airlines |
| Companies Covered | MULAG Fahrzeugwerk Heinz Wössner GmbH u. Co. KG, TREPEL Airport Equipment GmbH, TLD Group, Mototok International GmbH, Tronair Inc., JBT Corporation, Goldhofer AG, Oshkosh AeroTech, Textron GSE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Pushback Tugs Market Emerging Trajectories
Electrification is converging with automation protocols to redefine ground handling economics, while regulatory pressure compresses equipment lifecycles and buyer fragmentation reshapes channel structures.
Teleoperation architecture is converging with 5G low-latency networks to enable remote-controlled pushback from centralized command centers. Low-cost carriers operating high-frequency narrow-body schedules at constrained European gates are piloting these systems to reduce headcount per turn. The technology is converging with existing fleet management software to compress gate utilization times by eliminating operator transit delays.
The EU F-Gas Regulation phases down hydrofluorocarbon use in cooling systems, indirectly accelerating electric traction adoption by raising total cost of ownership for diesel-powered auxiliary equipment. Ground handlers must now certify entire GSE fleets against carbon intensity benchmarks to maintain preferred supplier status at tier-one airports. Electric variants capture disproportionate contract share at Amsterdam Schiphol and Frankfurt, where municipal air quality ordinances precede broader EU enforcement.
Airline fleet consolidation among low-cost carriers fragments procurement authority away from traditional airport authorities toward independent ground handling companies. These operators now negotiate directly with OEMs, bypassing incumbent lessors and service aggregators. The shift concentrates most visibly in Spain and Italy, where Ryanair and Wizz Air volume growth outpaces legacy carrier networks.
Aircraft Pushback Tugs Market Segmentation
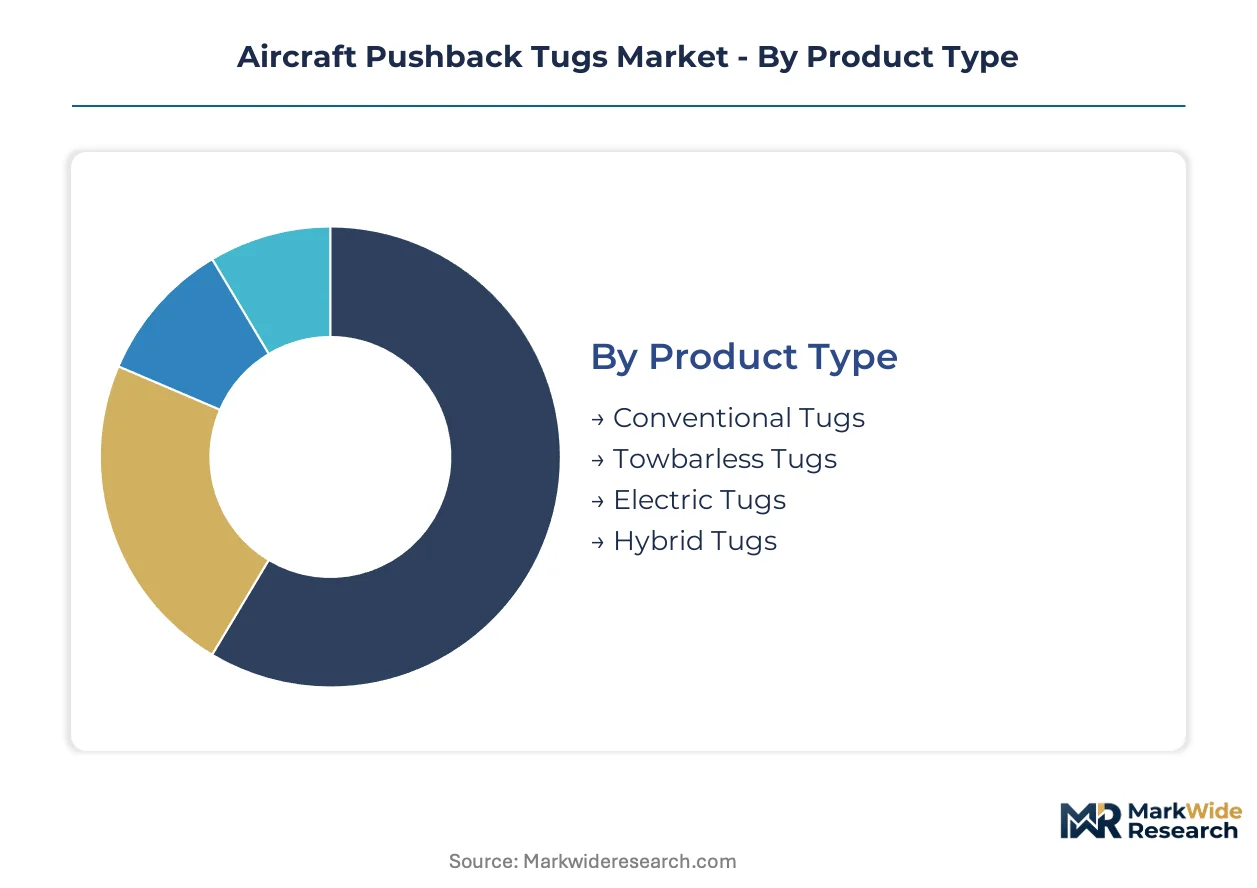
Pushback tug procurement patterns diverge sharply across operational contexts. Equipment specifications track aircraft weight classes, gate constraints, and ground handler fleet modernization cycles. Segmentation reveals where capital deployment concentrates and which technology transitions command premium pricing.
Product Type:
Supply concentration tilts toward towbarless architectures as high-frequency gates demand faster coupling cycles.
- Conventional Tugs:Diesel-powered platforms with towbar coupling dominate installed bases at emerging market airports. Indian ground handlers at Delhi and Mumbai rely on these units where charging infrastructure remains underdeveloped and acquisition budgets constrain fleet turnover.
- Towbarless Tugs:Clamp-based lifting mechanisms eliminate towbar inventory and reduce manpower per pushback. Frankfurt and Amsterdam Schiphol specify these systems exclusively for narrow-body gates handling 15+ daily turns per stand.
- Electric Tugs:Battery traction systems with 70-ton drawbar pull ratings now match diesel performance for wide-body handling. Munich manufacturing clusters shorten lead times for Central European hub deliveries.
- Hybrid Tugs:Dual-power architectures bridge infrastructure gaps at airports with intermittent grid reliability. Southeast Asian operators pilot these units to maintain operational continuity during peak demand periods.
Towbarless systems absorb the bulk of installed capacity at tier-one European hubs; electric variants are expanding most quickly as fleet decarbonization deadlines approach.
Power Source:
Cost tier stratification separates mature diesel platforms from emerging electric alternatives with divergent total ownership economics.
- Diesel:Compression-ignition engines retain volume leadership in Sub-Saharan Africa and parts of Southeast Asia. Extended equipment lifecycles and established maintenance networks sustain procurement despite rising fuel costs.
- Electric:Lithium-ion battery packs with 800V architectures enable high-amperage fast-charging during turnaround windows. German airports under EU Green Deal mandates drive concentrated demand as F-Gas Regulation phases raise diesel auxiliary costs.
- Hybrid:Series-hybrid configurations deploy smaller diesel generators as range extenders. Italian ground handlers at Rome Fiumicino use these for wide-body remote stands beyond charging cable reach.
- Gasoline:Spark-ignition units occupy niche applications for light aircraft and general aviation terminals. Limited commercial relevance outside North American regional airports with specific emissions exemptions.
Diesel retains the widest installed base across developing regions; electric powertrains are climbing the fastest as regulatory deadlines compress replacement cycles.
Driver Type:
Application context determines automation investment—high-frequency narrow-body gates justify advanced systems while remote stands favor simpler architectures.
- Manual:Operator-controlled tugs with conventional steering and throttle interfaces remain standard at low-utilization general aviation facilities. Training requirements and labor availability constrain adoption at major commercial hubs.
- Automated:LiDAR-guided autonomous systems with predefined gate-to-taxiway routing operate without onboard personnel. Pilot deployments at constrained European gates target headcount reduction per aircraft turn.
- Semi-Automated:Driver-assist features including collision avoidance and precision docking aids reduce operator cognitive load. Spanish low-cost carrier ground handlers favor these for high-frequency schedules with mixed fleet types.
- Remote-Controlled:Teleoperation via 5G low-latency networks enables centralized command center control. Mototok International GmbH specializes in compact units for ultra-narrow gate positions where operator visibility is limited.
Manual systems still dominate total fleet numbers; remote-controlled configurations are gaining share fastest where 5G infrastructure and labor costs converge.
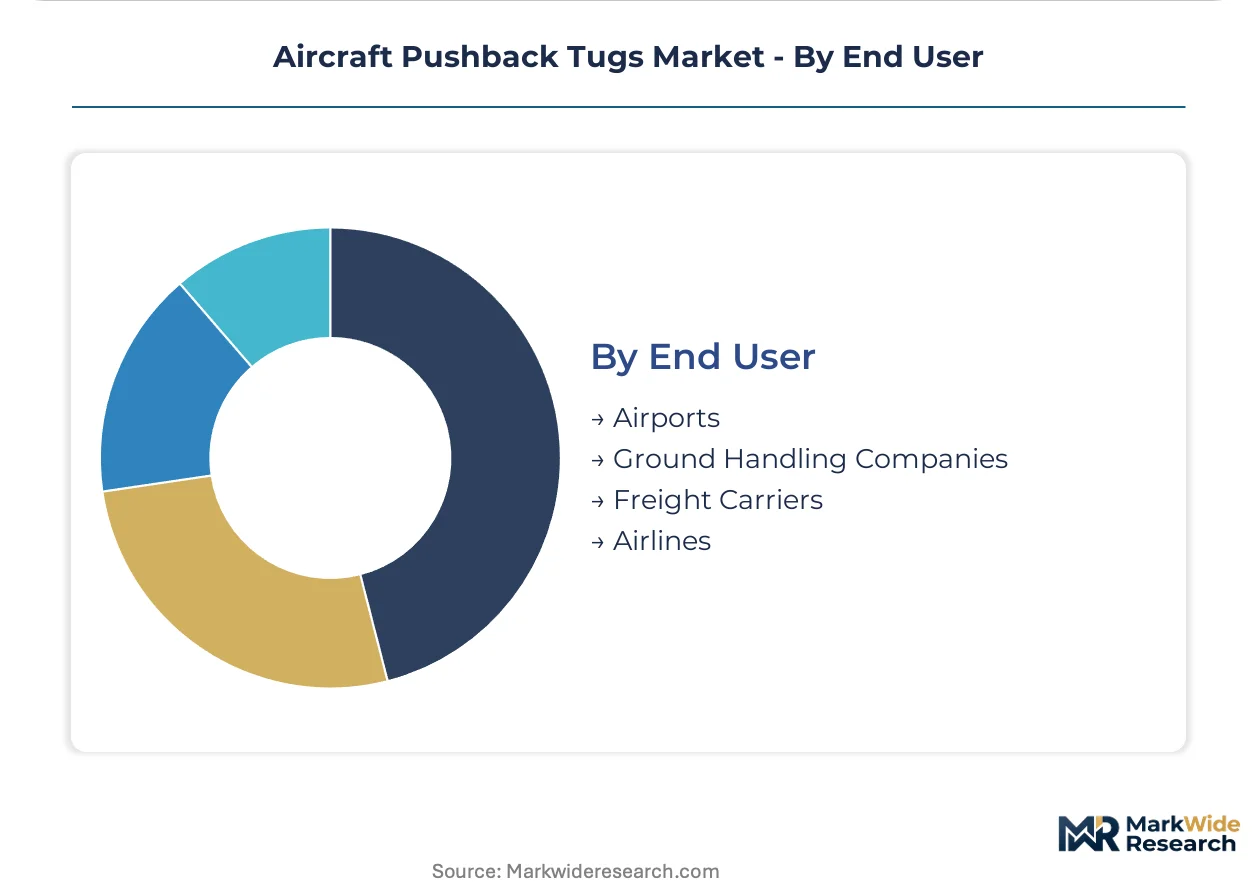
End User:
Customer type fragmentation reshapes procurement authority as airline consolidation displaces traditional airport authority decision-making.
- Airports:Municipal and regional airport authorities specify fleet standards for common-use gate infrastructure. German hub operators under binding decarbonization timelines enforce electric-only procurement for new equipment.
- Ground Handling Companies:Independent operators like those serving Ryanair and Wizz Air at Spanish and Italian bases negotiate directly with OEMs. These entities now bypass incumbent lessors to secure volume pricing on towbarless systems.
- Freight Carriers:Cargo-dedicated operators prioritize drawbar pull reliability for heavy wide-body freighters. JBT Corporation maintains long-term service contracts with North American cargo operators to sustain channel control.
- Airlines:Legacy carriers with proprietary ground handling capabilities specify integrated fleet management systems. Fleet standardization across hub networks drives集中采购 decisions for electric traction platforms.
Ground handling companies absorb the bulk of new capacity investment as procurement authority fragments; freight carrier specifications are expanding most quickly with dedicated cargo terminal growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ground handling procurement concentrates at German manufacturing clusters and US cargo hubs, with regulatory pressure from the EU Green Deal and FAA mandates shaping fleet replacement timelines across distinct national markets.
Germany
Munich and Augsburg anchor towbarless system production for Central European hub demand. The EU F-Gas Regulation phases down hydrofluorocarbon use, indirectly raising diesel auxiliary costs and accelerating electric traction adoption. Goldhofer AG and TREPEL Airport Equipment GmbH manufacture 70-ton drawbar pull electric units for Frankfurt and Amsterdam Schiphol.
United States
Cargo-dedicated operators at Memphis and Louisville anchor heavy wide-body freighter handling demand. The FAA mandates operational compliance under 14 CFR Part 139 for airport rescue and firefighting equipment compatibility. JBT Corporation sustains channel control through long-term service contracts with North American cargo operators.
India
Greenfield terminals at Navi Mumbai and Jewar lack legacy diesel fleets, enabling pure-electric infrastructure design from commissioning. The country's national airport regulator enforces ground support equipment standards under privatization frameworks. Ground handlers at Delhi and Mumbai rely on conventional diesel units where charging infrastructure remains underdeveloped.
Spain
Ryanair and Wizz Air volume growth at Barcelona and Madrid outpaces legacy carrier networks, fragmenting procurement authority toward independent ground handlers. EU Green Deal fleet decarbonization timelines create procurement urgency at tier-one airports. Low-cost carrier ground handlers pilot semi-automated driver-assist systems for high-frequency narrow-body schedules.
Italy
Rome Fiumicino deploys series-hybrid configurations for wide-body remote stands beyond charging cable reach. The EU Green Deal imposes binding fleet decarbonization timelines that directly shape ground support equipment procurement specifications. Italian ground handlers negotiate directly with OEMs, bypassing incumbent lessors to secure volume pricing on towbarless systems.
Aircraft Pushback Tugs Market Vendor Landscape
German producers anchor one tier; North American specialists hold cargo-dedicated service contract positions. Market structure tilts toward consolidated supply around Munich-Augsburg manufacturing clusters, with independent ground handlers fragmenting procurement authority away from traditional airport authorities. Three archetypes dominate: scale-driven towbarless system manufacturers, compact remote-controlled unit specialists, and cargo-focused service contract holders. Competitive moves concentrate on geographic expansion toward Indian greenfield terminals and portfolio diversification into autonomous driver-assist validation.
Within the scale-driven tier, TLD Group supplies towbarless systems to major European hubs, while JBT Corporation exemplifies the cargo-dedicated service contract archetype through its North American channel control. Mototok International GmbH occupies a distinct position as a compact remote-controlled unit specialist for narrow-body aircraft in constrained gate positions. These three entities represent the primary competitive anchors shaping procurement patterns across fragmented buyer landscapes.
| Leading Market Players |
|---|
| MULAG Fahrzeugwerk Heinz Wössner GmbH u. Co. KG |
| TREPEL Airport Equipment GmbH |
| TLD Group |
| Mototok International GmbH |
| Tronair Inc. |
| JBT Corporation |
| Goldhofer AG |
| Oshkosh AeroTech |
| Textron GSE |
| Others |
Supply Flow & Price Mechanics
EU Green Deal fleet decarbonization timelines are forcing ground handlers to accelerate electric tug procurement before charging infrastructure maturity catches up, compressing supplier lead times and elevating contract premiums for 70-ton drawbar pull battery systems from Munich-Augsburg manufacturing clusters.
Pricing Analysis
Volume leadership sits with diesel-powered conventional tugs in emerging markets where acquisition budgets constrain fleet turnover, while margin concentration flows to towbarless electric variants at tier-one European hubs. Price differentiation hinges on EASA braking performance certification status and after-sales service bundling. Cost compression in the diesel tier is intensifying because lithium and copper input volatility compresses electric tug margins and extends payback calculations. Independent ground handling companies serving low-cost carriers exhibit highest price sensitivity; cargo-dedicated operators at North American freighter hubs show lowest sensitivity due to long-term service contract structures.
Supply Chain Analysis
Freight cost premiums on lithium-ion battery packs from South Korean and Chinese cell manufacturers elevate landed costs for electric traction system assemblers in Germany. Manufacturing concentration centers on Munich and Augsburg for towbarless system final assembly, while steel chassis components draw from Czech and Polish fabrication networks. Single-source vulnerability around 800V battery management system controllers creates procurement risk for independent ground handlers lacking OEM service center proximity. Distribution runs through direct OEM relationships with fragmented independent ground handling companies, bypassing incumbent equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with captive battery supply agreements and EASA pre-certified platforms, as EU F-Gas Regulation enforcement eliminates non-compliant diesel auxiliary equipment from preferred supplier lists at tier-one airports.
For Market Incumbents: Deepen backward integration into lithium-ion pack assembly to offset raw material cost swings and compress electric tug lead times for Central European hub deliveries. Anchor channel control through multi-year service contracts with cargo-dedicated operators at Memphis and Louisville, defending against emerging remote-controlled unit specialists targeting narrow-body gate positions. For New Entrants and Emerging Players: Launch via direct sales to greenfield terminals at Navi Mumbai and Jewar, where absence of legacy diesel fleets enables pure-electric infrastructure specification from commissioning. Target hybrid tug demand at Southeast Asian airports with intermittent grid reliability, using series-hybrid configurations as bridge technology while fast-charging infrastructure matures. For Investors and Strategic Acquirers: The window for entry favors compact remote-controlled unit specialists with validated 5G teleoperation protocols and LiDAR positioning integration. Mid-cap German manufacturers with EASA pre-certified electric platforms and established relationships with Frankfurt and Amsterdam Schiphol procurement committees represent prime acquisition archetypes. Monitor battery energy density threshold announcements as inflection indicator for wide-body electric tug contract eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Munich manufacturers securing lithium cell supply agreements compress electric tug cost structures against South Korean competitors. |
| EASA Pre-Certification Investment | Early braking performance validation eliminates 12-18 month market entry delays versus conventional platform approvals. |
| Remote-Controlled Unit Development | 5G teleoperation convergence with LiDAR positioning creates headcount reduction value for constrained European gates. |
| Greenfield Terminal Partnership | Direct OEM relationships at Navi Mumbai and Jewar bypass legacy equipment lessor intermediaries. |
| Long-Term Service Contract Expansion | Cargo-dedicated operator lock-in at Memphis and Louisville sustains JBT Corporation channel control against emerging entrants. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ground handling fleet managers, airport procurement officers, OEM product directors, and aftermarket service heads. EASA certification databases, FAA Part 139 compliance records, EU Green Deal implementation timelines, and ground support equipment customs classifications provided secondary validation. Bottom-up equipment shipment tracking and top-down airport capital expenditure analysis were triangulated to reconcile volume estimates.
Data-stream reconciliation across manufacturer production schedules, airport fleet modernization announcements, and ground handler contract awards shaped the analytical framework. Segmentation dimensions modeled include product architecture, power source, automation level, and end-user procurement authority across the projection horizon. CAGRs were derived from equipment replacement cycle compression under regulatory deadlines and battery energy density improvement curves. Industry-specific inputs incorporated EU F-Gas Regulation phase-down schedules and lithium-ion pack cost trajectory assumptions.
Regulatory enforcement delays, battery raw material price spikes, and charging infrastructure deployment shortfalls are the dominant revision risks for electric tug adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Supersonic Jet Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Docking System Market
Aircraft
Aircraft Leasing Market
Aircraft
Aircraft Wheels Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Europe Military Helicopters Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Aircraft Window Frame Market