
 Global Healthcare Software As a Service Market | 2026-2036
Global Healthcare Software As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Software As a Service Market Foresight
A shortage of health informatics specialists is collapsing implementation timelines for enterprise SaaS deployments. Oracle Corporation leverages its Cerner acquisition to anchor hospital system migrations, while Epic Systems Corporation dominates academic medical center contracts with its integrated care network architecture. Microsoft Corporation extends cloud infrastructure dominance through Azure Health Data Services, competing directly with specialized clinical platform vendors.
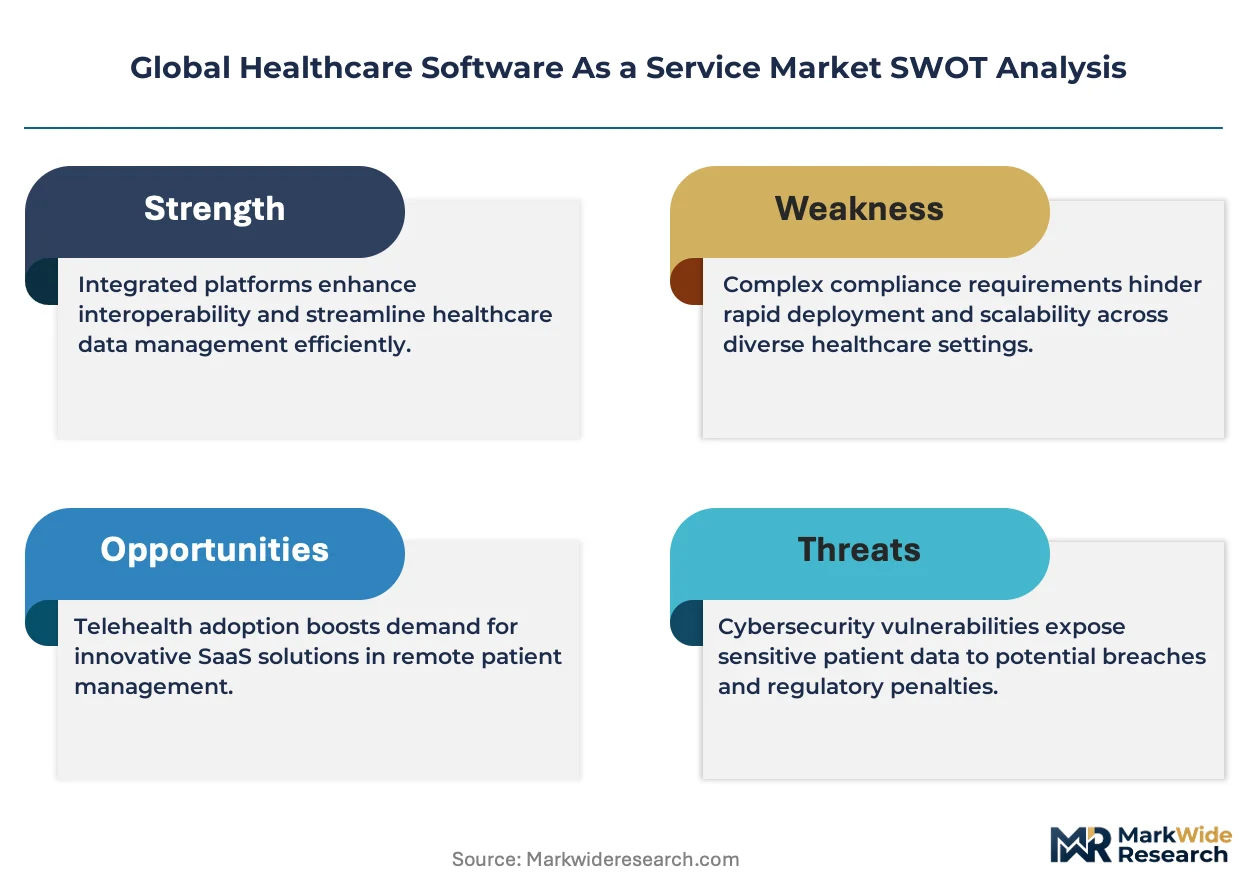
Healthcare Software As a Service denotes cloud-hosted applications delivering clinical, operational, and financial functions to medical organizations via subscription licensing, typically operating on multi-tenant architectures with API-driven interoperability standards. These systems process protected health information under encryption protocols and serve primarily to replace capital-intensive on-premise installations with scalable operational expenditure models. Electronic health records and telemedicine platforms command the largest revenue pools, while patient engagement solutions and clinical decision support tools represent the fastest-expanding segments as providers seek measurable outcome improvements. Revenue cycle management applications concentrate margin capture among mid-sized clinic chains facing reimbursement complexity.
FDA software-as-a-medical-device oversight, HIPAA security rule enforcement, and EU MDR clinical evidence requirements collectively elevate compliance costs for cross-border platform deployment. GDPR data residency constraints in Europe and India's Digital Information Security in Healthcare Act further fragment cloud architecture strategies, forcing vendors to maintain region-specific infrastructure. Stakeholders must evaluate regulatory divergence between jurisdictions before committing to single-tenant versus multi-tenant deployment architectures.
Market Dynamics
Multi-tenant cloud architectures are displacing on-premise hospital data centers as HIPAA interoperability mandates force API-driven data exchange between previously siloed systems.
Growth Catalysts
- FDA Software-as-a-Medical-Device Guidance:The 2022 enforcement discretion policy accelerates clinical decision support tool commercialization by reducing premarket review burdens for lower-risk algorithms.
- India's Digital Information Security in Healthcare Act:Data localization requirements stimulate domestic cloud infrastructure investment and create captive demand for indigenous SaaS platforms.
- Telemedicine platform integration:Remote patient monitoring reimbursement parity in Germany and the United States expands addressable patient populations beyond traditional facility-based care.
Market Restraints
- GDPR data residency constraints:European cloud sovereignty rules fragment vendor architectures and inflate operational expenditure through redundant regional data center footprints.
- Health informatics specialist shortage:Implementation timelines for enterprise EHR migrations extend 40-60% beyond contracted durations due to certified workforce scarcity.
- Legacy system technical debt:Proprietary on-premise databases from the 1990s lack standardized APIs, forcing expensive middleware development for interoperability compliance.
Strategic Opportunities
- Rural hospital network consolidation:Federally qualified health centers in the United States seek unified SaaS platforms to replace fragmented point solutions across distributed sites.
- Revenue cycle management automation:Mid-sized clinic chains facing Medicare Advantage reimbursement complexity represent underpenetrated demand for AI-enhanced claims processing.
- EU MDR clinical evidence requirements:Streamlined digital health technology assessment pathways in Germany create first-mover advantages for predictive analytics vendors.
Industry Challenges
- API standardization delays:HL7 FHIR implementation inconsistency between Epic Systems and Oracle Cerner deployments forces redundant integration engineering.
- Cross-border data governance complexity:India's DISHA Act, EU GDPR, and US state-level privacy laws create conflicting encryption and access control obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Software As a Service Market |
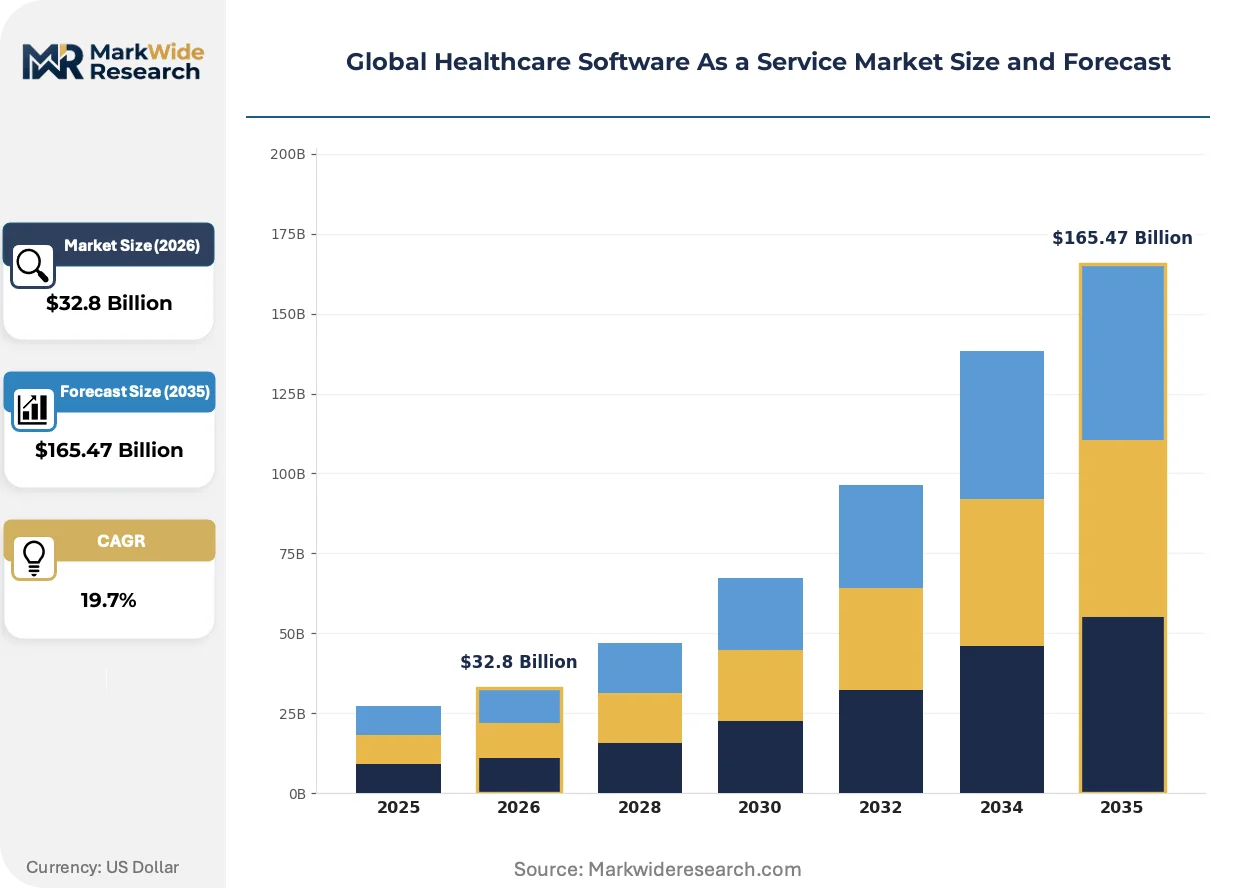
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $165.47 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Medical Billing Software, Telemedicine Platforms, Patient Engagement Solutions, Clinical Decision Support Application: Remote Patient Monitoring, Appointment Scheduling, Revenue Cycle Management, Prescription Management, Health Analytics End User: Hospitals, Clinics, Diagnostic Centers, Rehabilitation Facilities, Home Care Providers Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise |
| Companies Covered | Epic Systems Corporation, Oracle Corporation, Cerner Corporation, Athenahealth Inc., Allscripts Healthcare Solutions Inc., Microsoft Corporation, SAP SE, Optum Inc., CareCloud Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Software As a Service Market Shifts & Advancements
Generative AI integration is compressing clinical documentation workflows while regulatory pressure on algorithmic transparency reshapes vendor development priorities.
Large language model deployment for clinical note generation is bifurcating EHR vendor strategies between proprietary AI stacks and third-party API partnerships. Academic medical centers with dedicated informatics teams favor in-house model fine-tuning, while community hospitals outsource to Azure Health Data Services or Google Cloud Healthcare API. This divergence is compressing mid-tier vendors unable to fund either pathway into acquisition targets or niche specialty players.
EU AI Act risk classification for medical decision support systems imposes conformity assessment obligations on software previously operating under lighter medical device frameworks. High-risk algorithmic diagnostic tools must now demonstrate clinical validation through notified body review. German university hospitals and French public health networks are front-loading compliance investments ahead of 2026 enforcement deadlines.
Subscription pricing for clinical modules is displacing perpetual licensing in procurement negotiations with integrated delivery networks. United States health systems facing capital expenditure constraints favor operational expenditure models that align vendor payments with activated user counts. This shift pressures traditional on-premise incumbents to accelerate cloud-native platform development or cede mid-market share to pure-play SaaS competitors.
Global Healthcare Software As a Service Market Segmentation
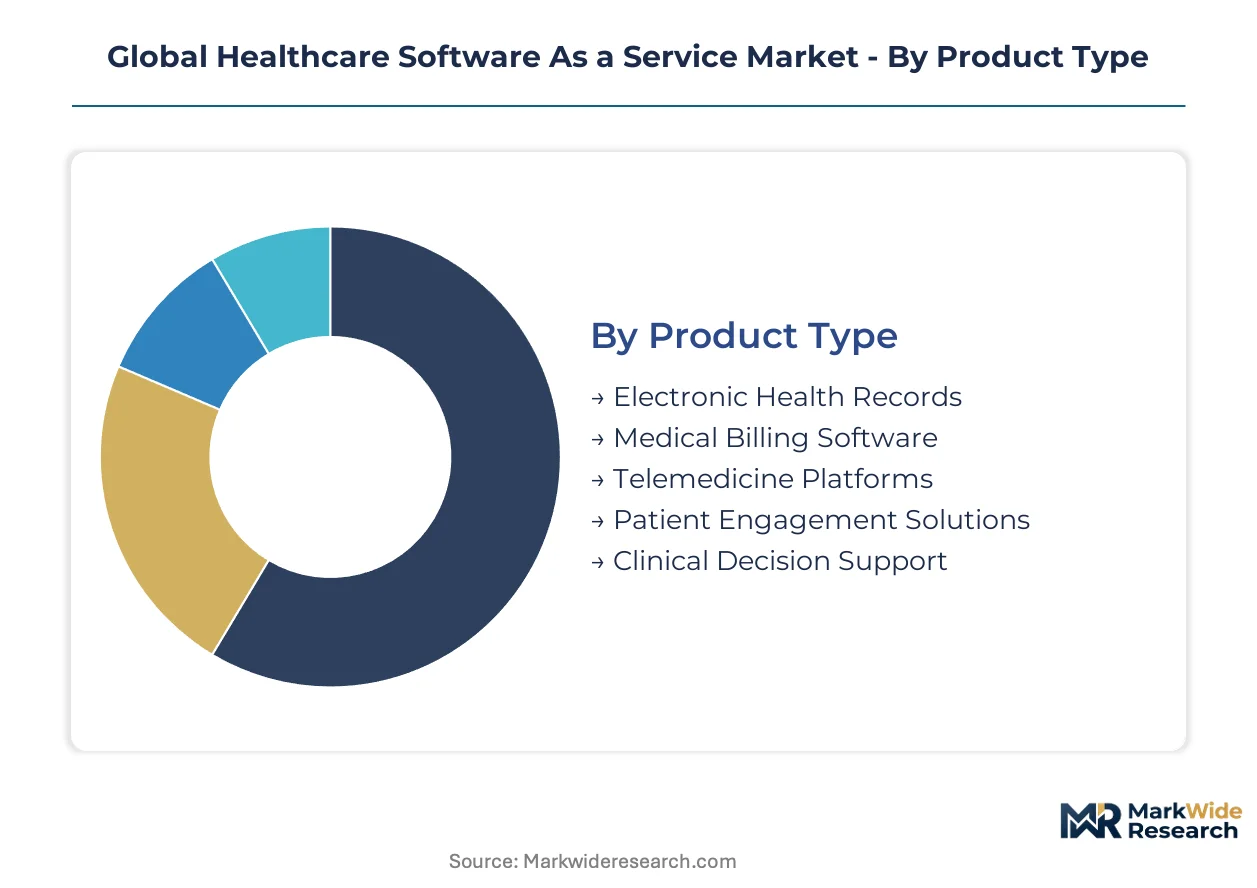
Regulatory divergence across HIPAA, GDPR, and India's DISHA Act fragments deployment architectures and forces vendors to architect product lines around jurisdictional compliance requirements. Cloud-hosted clinical applications must navigate encryption standards, data residency mandates, and algorithmic transparency obligations that vary by segment and geography. Understanding how these constraints map to product categories reveals where margin pools concentrate and where technical debt accumulates.
Product Type:
FDA software-as-a-medical-device guidance and EU AI Act risk classification create divergent certification burdens across clinical versus operational modules.
- Electronic Health Records:Multi-tenant cloud architectures with HL7 FHIR APIs process protected health information under HIPAA encryption protocols. Academic medical centers in the United States drive demand for integrated care network architectures that Oracle Cerner and Epic Systems deploy across hospital system migrations.
- Telemedicine Platforms:Real-time video infrastructure with remote patient monitoring integration enables reimbursement parity expansion in Germany and the United States. Federally qualified health centers seek unified platforms to replace fragmented point solutions across distributed rural sites.
- Medical Billing Software:AI-enhanced claims processing addresses Medicare Advantage complexity for mid-sized clinic chains facing margin pressure.
- Patient Engagement Solutions:Mobile-first portals with automated outreach compress readmission rates for value-based care contracts.
- Clinical Decision Support:Algorithmic diagnostic tools face EU AI Act conformity assessment obligations requiring clinical validation through notified body review.
Electronic Health Records handles the majority of throughput; Patient Engagement Solutions is gaining share fastest as providers seek measurable outcome improvements.
Application:
Operational expenditure models favor applications with activated user count pricing over capital-intensive perpetual licensing.
- Revenue Cycle Management:Automated claims scrubbing and denial prediction capture margin for clinic chains navigating reimbursement complexity. Mid-sized United States providers represent underpenetrated demand as Medicare Advantage enrollment expands.
- Remote Patient Monitoring:Continuous vital sign streaming with automated escalation protocols extends care beyond facility walls. German university hospitals front-load compliance investments ahead of EU AI Act enforcement deadlines for predictive analytics.
- Health Analytics:Population health dashboards aggregate multi-source data for risk stratification.
- Appointment Scheduling:Self-service booking with automated reminders reduces no-show rates.
- Prescription Management:E-prescribing with formulary checking integrates pharmacy benefit data.
Revenue Cycle Management captures the dominant share of procurement budgets; Remote Patient Monitoring shows the steepest expansion trajectory as reimbursement parity spreads.
End User:
Scale and informatics capability determine whether organizations favor in-house AI fine-tuning or outsourced cloud API partnerships.
- Hospitals:Enterprise EHR migrations extend 40-60% beyond contracted timelines due to certified health informatics specialist scarcity. Oracle leverages its Cerner acquisition to anchor system consolidations while Epic dominates academic medical center contracts.
- Clinics:Federally qualified health centers and mid-sized chains seek unified SaaS platforms to replace fragmented point solutions. Operational expenditure constraints drive preference for subscription pricing aligned with activated user counts.
- Diagnostic Centers:Imaging workflow integration with PACS connectivity dominates procurement priorities.
- Rehabilitation Facilities:Outcome measurement tools support value-based reimbursement reporting.
- Home Care Providers:Mobile documentation and remote supervision tools address workforce dispersion.
Hospitals account for the largest deployment volume; Clinics are expanding most quickly as rural network consolidation accelerates.
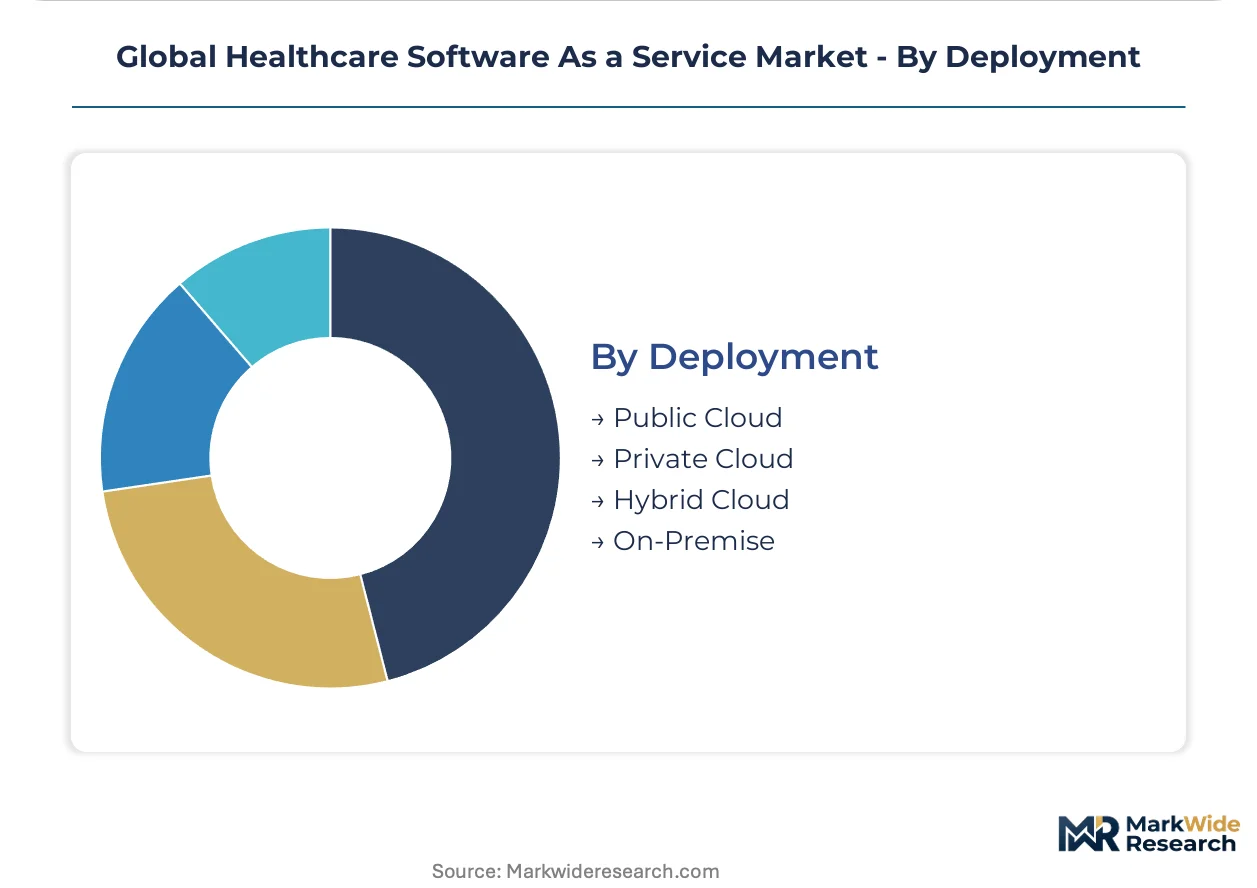
Deployment:
Data residency constraints fragment architecture strategies between single-tenant and multi-tenant models.
- Public Cloud:Microsoft Azure Health Data Services and Google Cloud Healthcare API compete for community hospital contracts lacking in-house informatics teams. GDPR European cloud sovereignty rules inflate operational expenditure through redundant regional data center footprints.
- Hybrid Cloud:Sensitive workload isolation with burst capacity to public infrastructure addresses India's DISHA Act localization requirements. Domestic cloud infrastructure investment stimulates captive demand for indigenous SaaS platforms.
- Private Cloud:Dedicated tenant environments satisfy HIPAA security rule enforcement for high-risk algorithmic diagnostic tools.
- On-Premise:Legacy 1990s proprietary databases force expensive middleware development for interoperability compliance.
Public Cloud carries the dominant workload volume; Hybrid Cloud is climbing the fastest as cross-border data governance complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where reimbursement parity for telemedicine creates premium capture opportunities, while India's data localization mandates compress margins through infrastructure duplication requirements.
United States
Federally qualified health centers and rural hospital networks drive SaaS consolidation demand as Medicare Advantage enrollment expands reimbursement complexity. HIPAA interoperability mandates and FDA software-as-a-medical-device guidance reshape vendor certification requirements. The Boston-Cambridge corridor anchors academic medical center procurement where Epic Systems dominates integrated care network contracts.
Germany
Telemedicine reimbursement parity and EU MDR clinical evidence requirements stimulate predictive analytics adoption among university hospitals. The EU AI Act imposes conformity assessment obligations on algorithmic diagnostic tools through notified body review. Berlin and Munich cluster health technology assessment activity ahead of 2026 enforcement deadlines.
India
Data localization requirements under the Digital Information Security in Healthcare Act create captive demand for indigenous cloud platforms. National health digitization programs scale across state-level hospital networks. Bangalore and Hyderabad concentrate domestic SaaS development as vendors architect region-specific infrastructure for DISHA compliance.
United Kingdom
NHS England's cloud-first policies accelerate electronic health record migrations among integrated care systems. GDPR data residency constraints intersect with post-Brexit data adequacy negotiations fragmenting cross-border architecture decisions. London's health tech corridor hosts specialized clinical platform vendors competing with Microsoft Azure Health Data Services deployments.
Japan
Ministry of Economy Trade and Industry digitization incentives target aging population care coordination through remote patient monitoring platforms. PMDA guidance on software-as-a-medical-device creates regulatory clarity for clinical decision support commercialization. Tokyo and Osaka metropolitan areas concentrate hospital system procurement for cloud-native EHR replacements.
Global Healthcare Software As a Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform vendors commanding academic medical centers while modular specialists capture mid-sized clinic chains. The market exhibits tiered consolidation around electronic health record dominance and cloud infrastructure scale. Three archetypes prevail: enterprise EHR consolidators, hyperscale cloud providers, and vertical-specific workflow specialists. Competitive dynamics center on hospital system migration anchoring and API ecosystem partnership formation.
Among enterprise platform consolidators, Oracle Corporation and Epic Systems Corporation occupy positions at opposite ends of the integration spectrum. Oracle leverages its Cerner acquisition to anchor hospital system migrations toward unified cloud architectures, while Epic dominates academic medical center contracts with integrated care network deployments. Microsoft Corporation sits within the hyperscale infrastructure tier, extending Azure Health Data Services to community hospitals lacking dedicated informatics teams.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Corporation |
| Cerner Corporation |
| Athenahealth Inc. |
| Allscripts Healthcare Solutions Inc. |
| Microsoft Corporation |
| SAP SE |
| Optum Inc. |
| CareCloud Corporation |
| Others |
Supply & Pricing Matrix
FDA software-as-a-medical-device guidance and EU AI Act risk classification gate both vendor qualification and price differentiation across clinical modules. These regulatory frameworks simultaneously elevate compliance costs for cross-border deployment and stratify pricing tiers by certification burden and jurisdictional coverage.
Pricing Analysis
United States health systems command 40-60% subscription premiums over Indian domestic platforms due to HIPAA interoperability mandates and FDA oversight requirements. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity: academic medical centers pay for Epic's integrated care network architecture while community hospitals select Azure Health Data Services or Google Cloud Healthcare API partnerships. Cost compression in mid-tier EHR modules is intensifying because Oracle Cerner and Epic Systems are anchoring hospital system migrations with bundled migration services. Federally qualified health centers exhibit highest price sensitivity due to capital expenditure constraints, whereas German university hospitals show lowest sensitivity as EU MDR clinical evidence requirements prioritize compliance over procurement cost.
Supply Chain Analysis
The United States and Germany concentrate cloud infrastructure investment for healthcare SaaS, with India scaling domestic data center capacity under DISHA Act localization mandates. Software development draws from Bangalore and Hyderabad engineering clusters, while hyperscale infrastructure feeds from Microsoft Azure, Amazon Web Services, and Google Cloud regional deployments. Single-source vulnerability concentrates in HL7 FHIR API standardization, where Epic Systems and Oracle Cerner implementation inconsistency forces redundant integration engineering. Distribution runs through direct enterprise sales to hospital systems, with channel partners serving mid-sized clinic chains lacking dedicated procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated delivery networks in the United States and hospital system consolidations in Germany, fragmenting procurement leverage across thousands of independent rural clinics and federally qualified health centers.
For Market Incumbents: Consolidate API ecosystem partnerships to defend against hyperscale cloud providers encroaching on community hospital contracts. Oracle Cerner and Epic Systems should deepen vertical integration into clinical decision support modules before EU AI Act enforcement elevates notified body review requirements for algorithmic diagnostic tools. Certification investment in Germany's streamlined digital health technology assessment pathways creates first-mover advantages for predictive analytics vendors ahead of conformity assessment deadlines. For New Entrants and Emerging Players: Revenue cycle management automation for mid-sized United States clinic chains represents a service-layer gap where incumbents under-serve Medicare Advantage reimbursement complexity. Federally qualified health centers seeking unified SaaS platforms across distributed rural sites offer penetrable demand with lower competitive intensity than academic medical center contracts. A channel partnership strategy with GPO contracts managers bypasses direct enterprise sales barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across generative AI integration for clinical documentation workflows, compressing mid-tier vendors unable to fund proprietary model development or third-party API partnerships into acquisition targets. Target acquisition profile: vertical-specific workflow specialists with established HL7 FHIR integrations and activated user count pricing models. Watch for EU AI Act enforcement timeline acceleration as the inflection signal indicating regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic Systems dominates academic medical center procurement through integrated care network architecture anchoring. |
| Platform Integration | Microsoft Azure Health Data Services competes for community hospitals lacking dedicated informatics teams. |
| Geographic Expansion | Domestic cloud infrastructure investment in Bangalore and Hyderabad addresses India's DISHA Act localization requirements. |
| Acquisition of Specialist Firm | Oracle Corporation leverages Cerner acquisition to consolidate hospital system migrations toward unified cloud architectures. |
| Reimbursement Strategy | Telemedicine platform vendors capture premium pricing in Germany through remote patient monitoring reimbursement parity. |
Research Methodology
Operator-level perspectives from hospital CIOs, health informatics specialists, GPO contracts managers, and biomedical engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and hyperscaler cloud capex disclosures. Bottom-up deployment counts across electronic health record, telemedicine, and revenue cycle management modules triangulated with top-down market sizing from subscription revenue disclosures.
Sensitivity analysis tested forecast robustness across HIPAA interoperability mandate acceleration scenarios and EU AI Act enforcement timeline variations. Segmentation dimensions modeled include deployment architecture, organization scale, clinical versus operational application, integration complexity tier, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and average revenue per user trajectories across the analysis window. Forecast inputs incorporated health informatics specialist shortage impacts on implementation timeline extension and cloud infrastructure investment cycles in India and Germany.
Underlying assumptions cover sustained Medicare Advantage enrollment expansion, DISHA Act enforcement without relaxation, and HL7 FHIR API standardization convergence, with deviation risk concentrated in EU AI Act risk classification reinterpretation and GDPR data adequacy negotiation outcomes. Recalibration cycles align with material shifts in FDA software-as-a-medical-device guidance enforcement discretion and national health digitization program funding allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
OBGYN EHR Market