
 North America Silica Sand Market | 2026-2036
North America Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
North America Silica Sand Market Intelligence
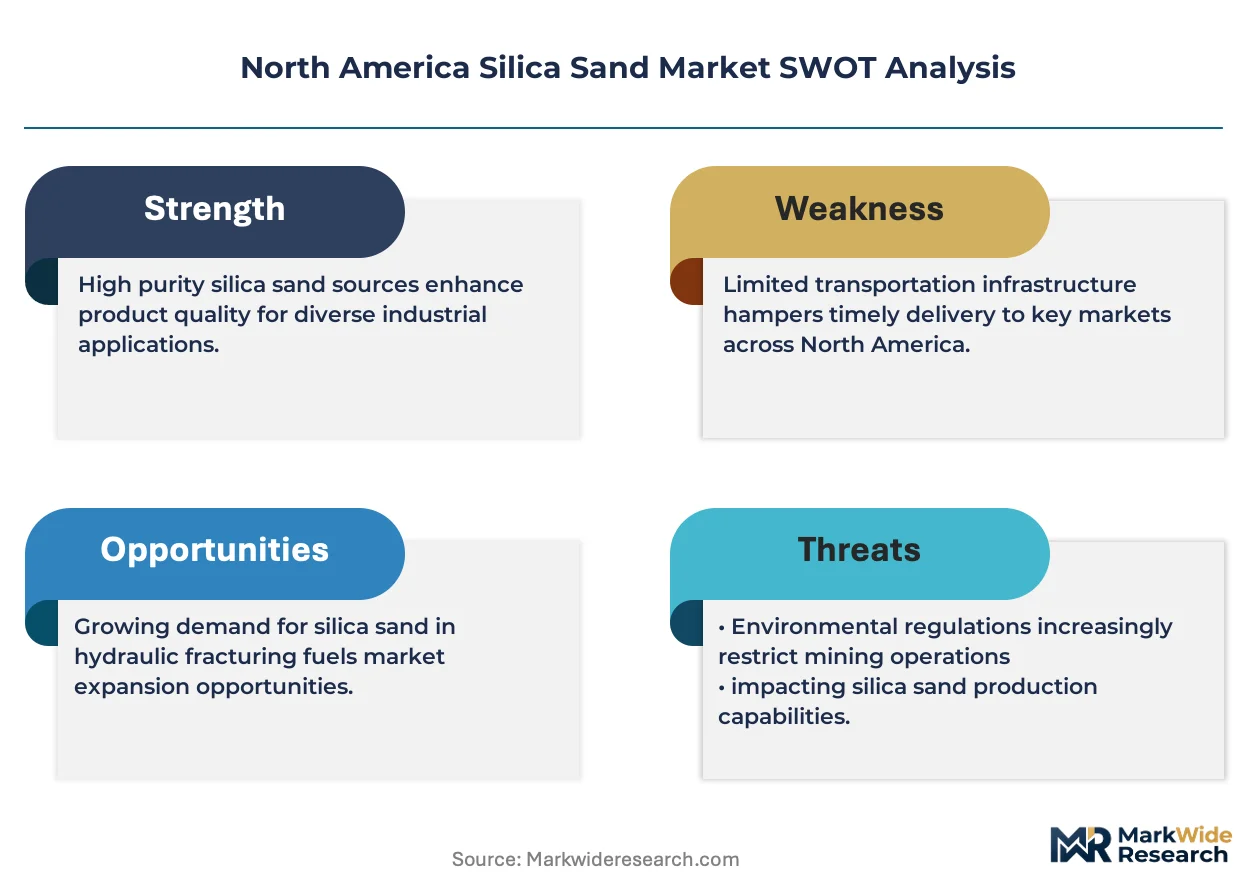
Hydraulic fracturing is realigning the North America silica sand market as energy-sector offtake climbs relative to traditional glass and foundry buyers. U.S. Silica leverages its transload network across the Permian and Eagle Ford to sustain last-mile delivery advantages. Covia Holdings anchors volume through integrated mine-to-wellhead logistics, while Badger Mining Corporation specializes in Northern White Sand purity grades for premium proppant applications.
Silica sand consists primarily of alpha quartz with SiO₂ content typically exceeding 95%, formed through weathering and erosion of quartz-bearing rocks before beneficiation via washing, classification, and attrition scrubbing to meet industrial specifications. The material serves as an essential feedstock for glass melting, metal casting molds, and oilfield proppant beds where sphericity and crush resistance determine performance. Alpha quartz dominates product type volumes across glass manufacturing and foundry casting, where high thermal stability commands consistent offtake. Hydraulic fracturing application growth outpaces legacy segments as well completion intensity rises, while high purity grade silica flour captures widening margins in specialty electronics and solar substrate markets.
OSHA enforces permissible exposure limits for respirable crystalline silica under its revised construction and general industry standards, forcing mine operators and downstream processors to invest in dust suppression and worker protection systems. EPA oversight of mining runoff and NHTSA-linked transportation safety rules for bulk haulage add compliance layers across the supply chain. Stakeholders must weigh capital deployment toward regional mesh-size flexibility against longer-term exposure to renewable energy substitution for frack-sand demand.
Market Dynamics
Permian Basin well completion intensity is compressing proppant logistics cycles and forcing mesh-size flexibility investments across Texas and New Mexico transload networks.
Growth Catalysts
- OSHA respirable crystalline silica enforcement:Tighter exposure limits are accelerating dust suppression system deployments at mine sites and processing facilities across the United States.
- Eagle Ford shale reactivation:Drilling activity resurgence in South Texas is pulling Northern White Sand volumes southward through reconfigured rail-to-truck transload corridors.
- High-purity silica flour specification:Solar substrate and semiconductor foundry buyers are capturing premium margins for 99.9% SiO₂ grades in Arizona and Nevada processing hubs.
Market Restraints
- Diesel and railcar input volatility:Bulk haulage costs swing with Class I railroad fuel surcharges and spot truck pricing across the Bakken and Permian freight corridors.
- Mine-to-wellhead supply concentration:Three integrated operators control roughly two-thirds of Permian proppant logistics infrastructure, creating bottleneck vulnerability.
- Ceramic proppant substitution:High-pressure deep-well operators in the Delaware sub-basin are displacing sand with bauxite-based alternatives above 10,000 psi closure stress.
Strategic Opportunities
- Mexico energy reform offtake:Burgos Basin shale development is drawing Texas mine output across the Rio Grande through newly permitted cross-border rail spurs.
- EPA mining runoff credit trading:Beneficiation facilities investing in closed-loop water systems can monetize compliance surplus in watershed-constrained jurisdictions.
- PropTech convergence:Real-time frac sand inventory tracking via IoT sensors is unifying mine scheduling with last-mile blender operations in the Midland-Odessa hub.
Industry Challenges
- Respirable silica competency gaps:Industrial hygienists certified in OSHA's 2016 construction standard remain scarce across rural Wisconsin and Minnesota mine counties.
- Legacy ERP integration friction:Mine operators adopting automated load-out systems face data migration complexity with decades-old batch scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Silica Sand Market |
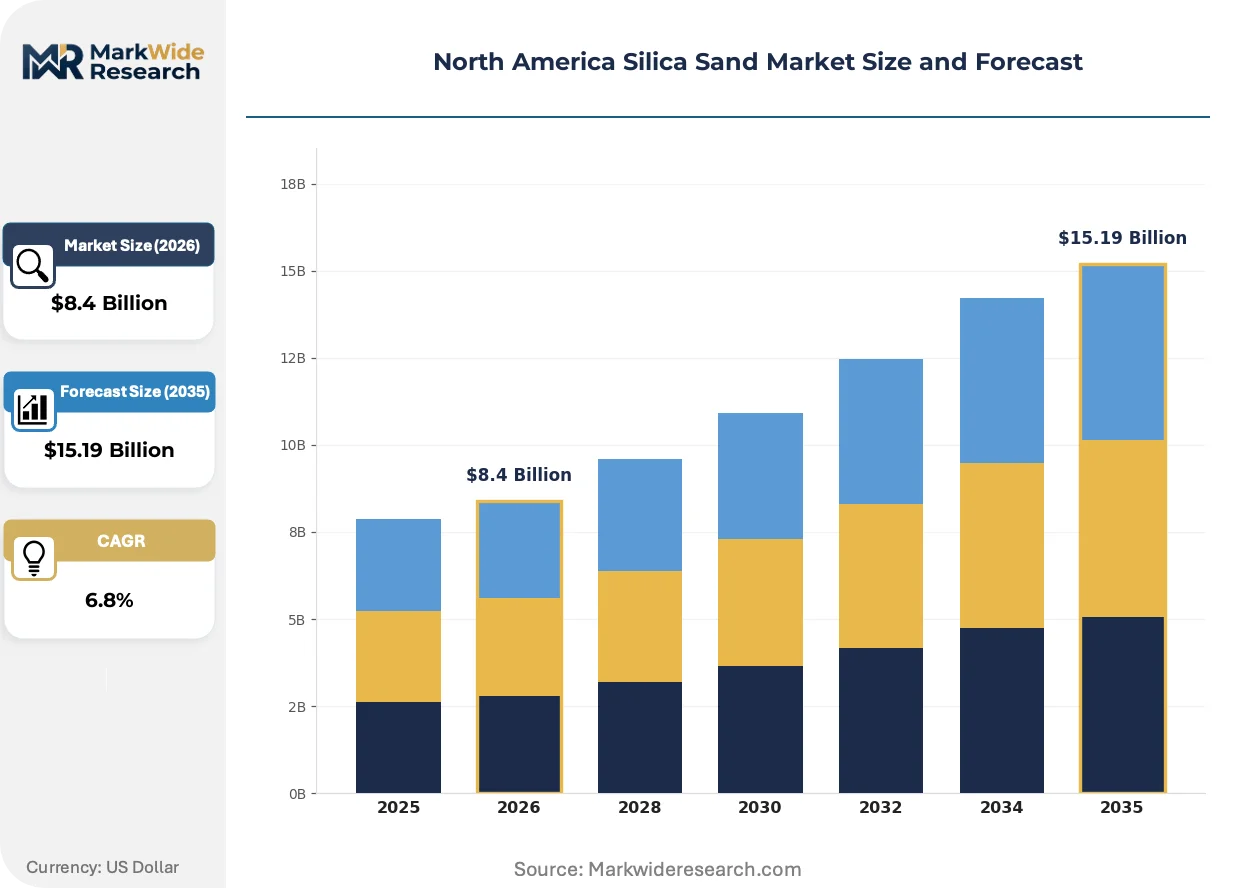
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha Quartz, Cristobalite, Tridymite, Silica Flour Application: Glass Manufacturing, Foundry Casting, Hydraulic Fracturing, Construction Grade: Industrial Grade, High Purity Grade, Low Iron Grade, Volcanic Grade Packaging Type: Bulk Bags, Paper Bags, Plastic Bags, Big Bags |
| Companies Covered | U.S. Silica, Covia Holdings LLC, Badger Mining Corporation, Atlas Energy Solutions, SmartSand, Inc., Hi-Crush Inc., Source Energy Services, Sil Industrial Minerals, Superior Silica Sands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Silica Sand Market Strategic Shifts & Innovations
Digital logistics platforms and beneficiation automation are compressing proppant delivery windows while regulatory pressure on respirable dust forces capital redeployment toward worker protection and environmental containment systems.
Automated attrition scrubbing circuits with real-time particle size analyzers are unifying washing and classification stages into continuous-flow operations. Proppant processors in Wisconsin and Texas are adopting these systems to cut mesh-size changeover downtime. The technology is unifying quality control with production scheduling, collapsing the gap between mine output and wellhead specification windows.
EPA's 2024 updates to National Pollutant Discharge Elimination System permits for industrial sand mining are tightening total suspended solids limits at outfall points. Facilities in Chippewa County, Wisconsin and McCulloch County, Texas face retrofit deadlines for settling pond and filtration infrastructure. The rule is compressing capital deployment timelines for mine expansions in water-stressed jurisdictions.
Direct mine-to-blender procurement contracts are displacing traditional proppant distributor intermediaries in the Permian and Eagle Ford. E&P operators with captive logistics teams now negotiate volume commitments directly with Wisconsin and Illinois mine gates, stripping margin from regional sand yards. The pattern is most visible among Delaware Basin independents with integrated supply chain functions based in Midland.
North America Silica Sand Market Segmentation
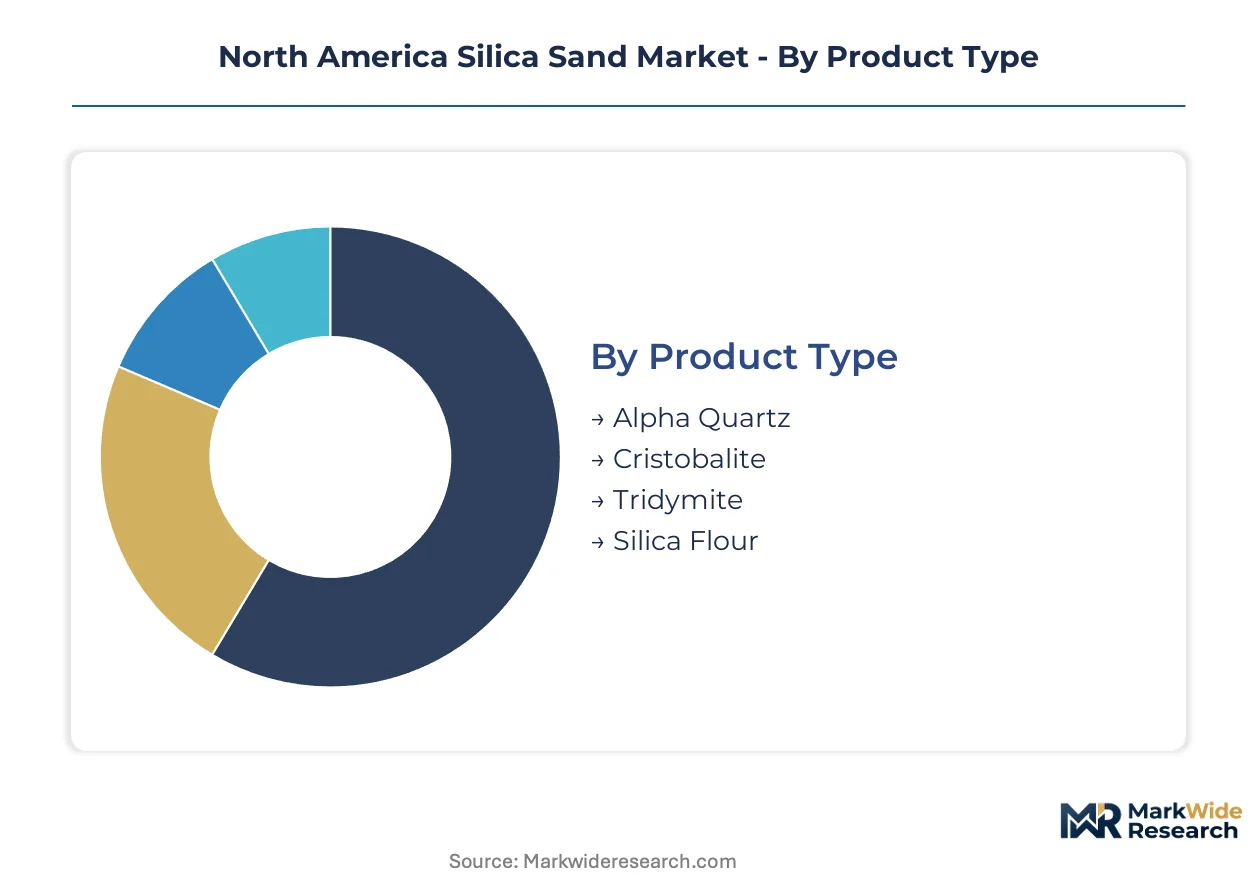
Silica sand buyers across North America prioritize particle geometry, chemical purity, and logistics compatibility when selecting product specifications. Segment boundaries in this market reflect divergent technical requirements between oilfield proppant operators and glass or foundry manufacturers. Understanding these splits reveals where margin compression and pricing power concentrate.
Product Type:
Buyers choose mineral phases based on thermal stability demands and end-use temperature thresholds.
- Alpha Quartz:The trigonal crystalline form of SiO₂ dominates industrial volumes through exceptional hardness and thermal resistance above 1,000°C. Permian Basin proppant specifications favor alpha quartz for crush resistance under formation closure stress. Demand concentrates in Texas and Wisconsin mining districts where sphericity standards exceed 0.6 Krumbein roundness.
- Silica Flour:Ground to sub-75 micron particle sizes, this high-surface-area material serves semiconductor substrate polishing and solar panel glass manufacturing. Arizona processing hubs near Phoenix and Tucson capture premium offtake from electronics foundries requiring 99.9% SiO₂ purity with controlled iron content below 100 ppm.
- Cristobalite:The high-temperature tetragonal polymorph commands specialized refractory applications where thermal shock resistance exceeds alpha quartz capabilities.
- Tridymite:The orthorhombic phase appears in limited ceramic and investment casting niches requiring specific thermal expansion profiles.
Volume sits with Alpha Quartz; growth tilts toward Silica Flour.
Application:
End-use selection follows capital intensity cycles in energy extraction and construction activity.
- Hydraulic Fracturing:Proppant sand specifications demand 20/40 and 40/70 mesh sizes with turbidity below 250 FTU and acid solubility under 1%. Permian and Eagle Ford well completion intensity pulls volumes through Texas transload networks. OSHA respirable silica enforcement is forcing wet-sand handling retrofits at blender sites.
- Glass Manufacturing:Container and flat glass furnaces require 99.5% SiO₂ with tight alumina and iron oxide limits. Pennsylvania and Ohio float glass plants anchor steady offtake through long-term mine contracts.
- Foundry Casting:Metal casting molds use rounded grain sands with AFS grain fineness numbers between 50 and 60. Wisconsin and Illinois mine output supplies automotive and heavy equipment casting operations.
- Construction:Concrete additives, mortar sand, and specialty cement applications consume lower-purity regional deposits with less stringent beneficiation requirements.
Revenue concentrates in Hydraulic Fracturing; expansion accelerates fastest in Glass Manufacturing as solar substrate demand climbs.
Grade:
Purity thresholds determine addressable market tiers and margin capture potential.
- High Purity Grade:Exceeding 99.9% SiO₂ with controlled trace metals, this grade commands premium positioning in semiconductor and photovoltaic supply chains. Nevada and Arizona processing facilities specialize in acid-washing and magnetic separation circuits to achieve these specifications.
- Industrial Grade:Standard 95-99% SiO₂ material serves bulk glass, foundry, and construction applications where cost efficiency outweighs extreme purity requirements. Wisconsin's Wonewoc and Ottawa deposits anchor North American supply.
- Low Iron Grade:Ferric oxide content below 0.02% enables optical glass and specialty container applications where color neutrality matters.
- Volcanic Grade:Naturally occurring volcanic glass sands serve niche filtration and specialty abrasive markets with minimal processing.
Shipments cluster in Industrial Grade; value expansion favors High Purity Grade.
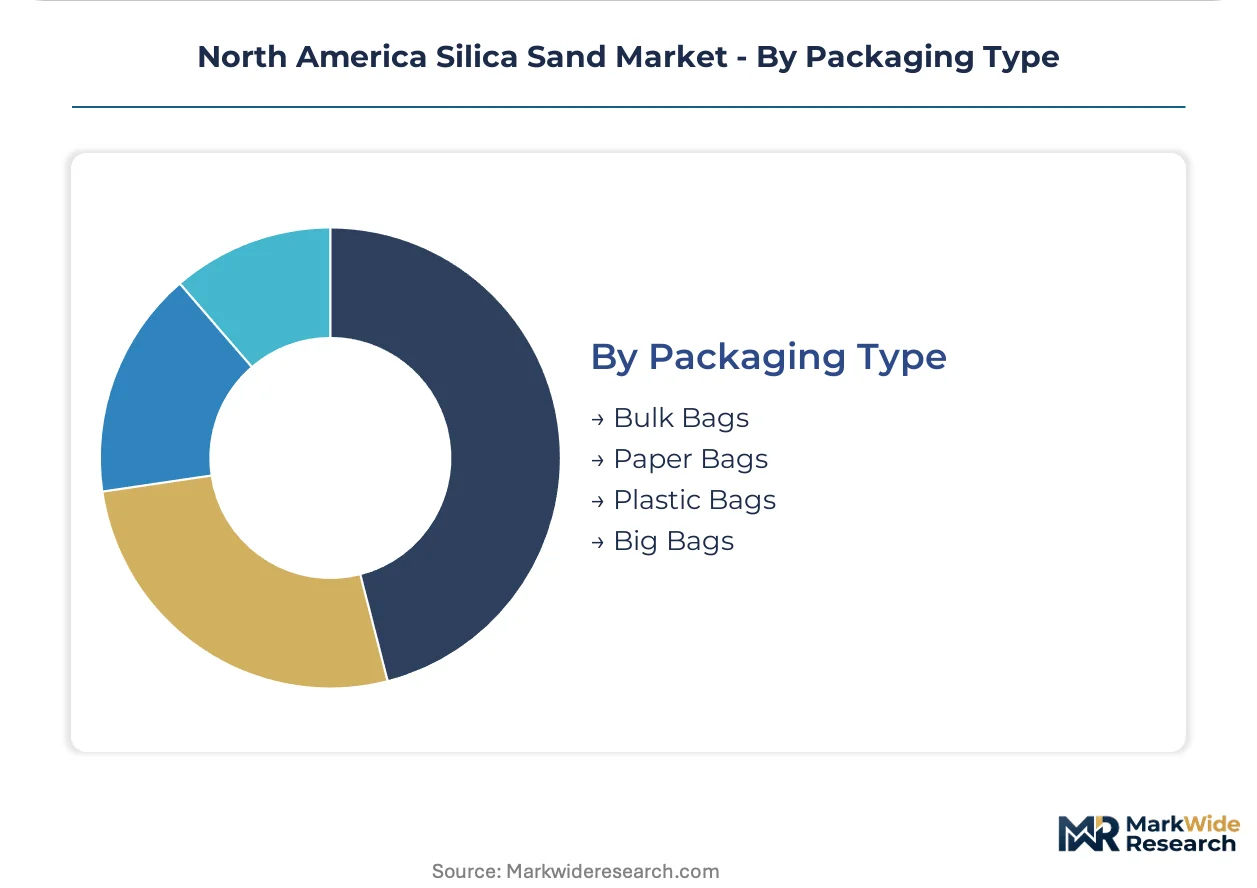
Packaging Type:
Logistics economics and handling automation drive format selection across the supply chain.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate oilfield proppant delivery through pneumatic discharge compatibility at wellsite blenders. Texas and New Mexico transload facilities maintain bulk bag inventory buffers.
- Big Bags:Larger multi-ton formats serve integrated glass plants with automated handling systems and covered storage.
- Paper Bags:50-pound multi-wall sacks persist in foundry and specialty construction channels where batch-scale handling remains manual.
- Plastic Bags:Polypropylene woven bags with polyethylene liners protect moisture-sensitive high-purity grades during extended storage.
Tonnage flows through Bulk Bags; format innovation targets Big Bags for automated plant integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin Opportunity Zone designations in Texas and New Mexico concentrate silica sand logistics infrastructure near hydraulic fracturing demand centers. Tax-advantaged development incentives pull processing capacity toward shale formation proximity.
United States
Permian Basin well completion intensity drives proppant consumption through Texas transload networks. OSHA respirable crystalline silica enforcement under 29 CFR 1926.1153 mandates wet-sand handling retrofits at mine sites and blender operations. Wisconsin's Chippewa and Barron counties anchor Northern White Sand production for premium oilfield specifications.
Canada
Alberta oil sands operators and Saskatchewan potash mines consume industrial-grade silica for construction and processing applications. Health Canada guidelines on occupational exposure to crystalline silica align with provincial worker safety mandates across Ontario and Quebec processing hubs. Manitoba's Winnipeg corridor hosts distribution infrastructure serving Prairie Province foundry demand.
Mexico
Burgos Basin shale development draws Texas mine output across newly permitted cross-border rail spurs. Mexico's energy reform offtake agreements under CNH permitting frameworks enable direct mine-to-wellhead contracts. Nuevo León and Tamaulipas border zones concentrate transload facilities for northern Mexico drilling programs.
North America Silica Sand Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated mine-to-wellhead operators commanding Permian logistics corridors while regional processors serve glass and foundry niches. Three archetypes dominate: vertically integrated proppant suppliers with captive rail networks, purity-grade specialists leveraging Wisconsin deposits, and basin-focused last-mile logistics providers. Competitive moves concentrate on mesh-size flexibility investments and direct procurement contract displacement of distributor intermediaries.
Among North American integrated operators, U.S. Silica exemplifies the transload-network archetype with Permian and Eagle Ford corridor positioning. Covia Holdings occupies the scale-driven tier through mine-to-wellhead logistics integration. Badger Mining Corporation represents purity-grade specialization anchored in Wisconsin Northern White Sand deposits.
| Leading Market Players |
|---|
| U.S. Silica |
| Covia Holdings LLC |
| Badger Mining Corporation |
| Atlas Energy Solutions |
| SmartSand, Inc. |
| Hi-Crush Inc. |
| Source Energy Services |
| Sil Industrial Minerals |
| Superior Silica Sands |
| Others |
Cost & Logistics Intelligence
Permian Basin E&P operators with captive procurement teams concentrate demand power and anchor contract-based long-term offtake structures that reward volume scale and logistics reliability over spot-market flexibility.
Pricing Analysis
Short lead-time premiums compress margins for proppant processors serving Delaware Basin independents with urgent well completion schedules. Pricing stratifies across Northern White Sand premium grades, regional brown sand standard tiers, and economy mesh-size alternatives with relaxed turbidity specifications. Cost compression in standard-grade material intensifies as direct mine-to-blender contracts strip distributor markup. Glass manufacturers in Pennsylvania and Ohio exhibit lowest price sensitivity due to long-term mine contracts and furnace switching costs.
Supply Chain Analysis
Single-source vulnerability sits with Wisconsin's Chippewa and Barron counties for premium Northern White Sand sphericity grades. The supply chain draws from Wisconsin mining districts, Texas Permian Basin transload hubs, and Illinois regional deposits. Raw material dependencies include diesel fuel for bulk haulage, Class I railroad capacity, and pneumatic discharge equipment for wellsite blender integration. Tariff exposure on Canadian railcar imports creates bottleneck risk. Distribution runs through mine-to-wellhead direct contracts displacing traditional proppant yard intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American silica sand has become a vertical-integration race where captive rail networks and transload infrastructure determine pricing power and delivery reliability.
For Market Incumbents: Extend mesh-size flexibility investments across Texas and New Mexico transload corridors to defend against ceramic proppant substitution in high-pressure Delaware sub-basin formations. Deepen backward integration into Wisconsin mine gates through direct procurement contracts that lock in Northern White Sand purity grades and strip margin from regional distributors serving Eagle Ford reactivation programs. For New Entrants and Emerging Players: Begin with Mexico Burgos Basin shale development where cross-border rail spur permits enable first-mover positioning before integrated operators consolidate Nuevo León transload infrastructure. Target high-purity silica flour specifications for Arizona solar substrate and semiconductor foundry buyers where 99.9% SiO₂ grades command premium positioning absent from commoditized proppant markets. For Investors and Strategic Acquirers: The window for entry favors vertically integrated proppant suppliers with captive Permian logistics networks and EPA-compliant closed-loop water systems. Long-term viability hinges on exposure to renewable energy substitution risk versus solar substrate demand expansion. Watch ceramic proppant adoption rates above 10,000 psi closure stress as the inflection signal for sand displacement vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Transload Network Expansion | Captive rail-to-truck infrastructure in Midland-Odessa compresses last-mile delivery windows for Permian operators. |
| Closed-Loop Water Retrofit | EPA NPDES compliance investments in Chippewa County facilities monetize credit trading in watershed-constrained jurisdictions. |
| Mesh-Size Flexibility Automation | Real-time particle size analyzers at Wisconsin processing plants collapse changeover downtime between 20/40 and 40/70 specifications. |
| Direct Mine Procurement Contracting | Bypassing proppant distributors strips margin and locks volume commitments from Delaware Basin independents. |
| High-Purity Grade Acid Washing | Arizona processing hubs capture semiconductor and solar substrate premiums through magnetic separation and iron content control. |
Research Approach
Independent corroboration across mine operations executives, E&P procurement leads, Class I railroad commercial managers, and industrial hygiene consultants underwrites the qualitative findings. Primary fieldwork combined with secondary validation from OSHA enforcement databases, EPA NPDES permit filings, EIA drilling activity reports, and FERC rail rate case documents. Bottom-up mine capacity estimates triangulate against top-down proppant consumption models derived from well completion intensity data.
Historical reference periods spanning pre-pandemic baseline, supply chain disruption peak, and post-reform normalization anchor the forecast window. Segmentation dimensions include product mineral phase, end-use application, purity grade tier, and regional logistics corridor. CAGRs derive from elasticity-adjusted demand curves incorporating well completion intensity, solar substrate expansion, and foundry casting cycles. Forecast inputs integrate OSHA respirable silica compliance cost pass-through and diesel fuel surcharge volatility.
Underlying measurement precision varies by segment; hydraulic fracturing proppant volumes carry tighter precision than specialty silica flour given standardized API specifications and transparent well completion reporting. Forecasts reflect documented assumptions on shale formation productivity, regulatory enforcement intensity, and ceramic proppant substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Slate Market
Industrial Minerals
Pyrites Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Industrial Salts Market