
 Global Drug Discovery Informatics Market | 2026-2036
Global Drug Discovery Informatics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drug Discovery Informatics Market Foresight
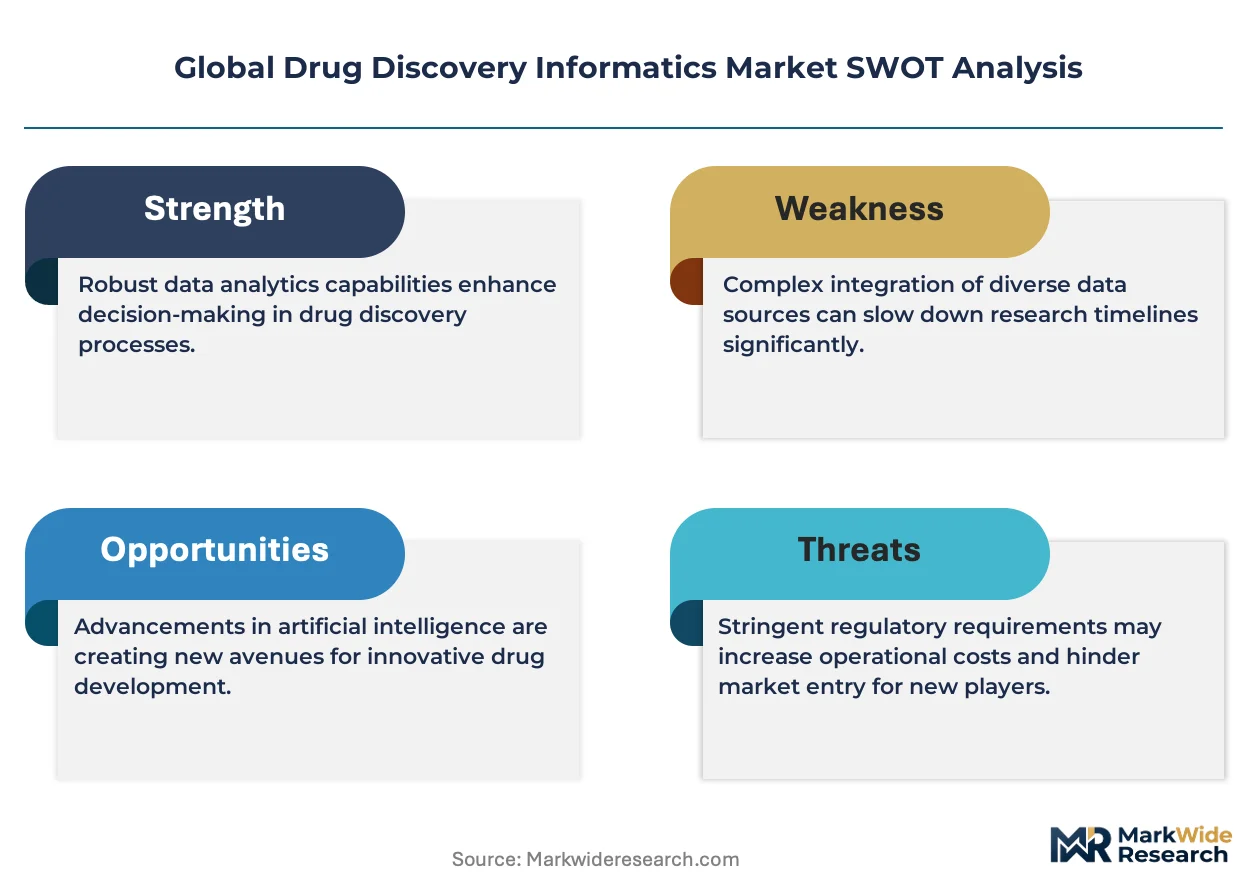
Biotech firm demand is rebalancing the end-user mix away from traditional pharmaceutical dominance. Schrödinger leverages physics-based molecular simulation to anchor its position in lead optimization workflows. Certara sustains competitive differentiation through its extensive regulatory science consulting paired with software platforms. Charles River Laboratories competes by extending laboratory services into integrated informatics offerings for contract research clients.
Drug discovery informatics comprises computational platforms, data architectures, and analytical workflows that process biological, chemical, and clinical datasets to identify and optimize therapeutic candidates. These systems integrate molecular docking algorithms, pharmacokinetic prediction models, and multi-omics data pipelines to reduce attrition rates in preclinical development. Artificial intelligence and machine learning segments attract the majority of new capital deployment as sponsors seek to replace heuristic screening with predictive target identification. Cloud computing infrastructure supports the fastest deployment velocity among technology categories by enabling elastic compute for high-throughput virtual screening campaigns.
The FDA's model-informed drug development framework and EMA's qualification opinion pathway for novel methodologies shape validation requirements for simulation-based submissions. ISO 14155 and ICH E6(R2) standards govern how informatics outputs integrate into clinical trial documentation and regulatory filings. Stakeholders must monitor evolving evidentiary standards for AI-derived predictions as health authorities formalize acceptance criteria for algorithm-supported regulatory packages.
Market Dynamics
Physics-based molecular simulation is displacing empirical screening as the dominant paradigm in lead optimization, compressing preclinical timelines from years to months and forcing platform vendors to integrate quantum mechanical engines with machine learning inference layers.
Growth Catalysts
- FDA Model-Informed Drug Development:The FDA's MIDD framework creates formal pathways for simulation-based submissions, accelerating vendor investment in predictive pharmacokinetic and pharmacodynamic tools.
- NIH funding concentration:United States federal grant flows into AI-native drug discovery startups expand the addressable base of informatics platform subscribers beyond traditional pharmaceutical incumbents.
- Cloud elastic compute:Amazon Web Services and Microsoft Azure infrastructure enables high-throughput virtual screening campaigns without capital-intensive on-premise supercomputing clusters.
Market Restraints
- Specialized talent scarcity:Computational chemists with dual expertise in quantum mechanics and machine learning command premium compensation, constraining platform scaling for mid-tier vendors.
- Validation burden:EMA qualification opinion pathway for novel methodologies demands extensive evidentiary packages, extending time-to-revenue for simulation-based offerings.
- Data silo fragmentation:Proprietary chemical libraries and patient cohort records remain locked within pharmaceutical incumbents, limiting training data access for independent platform developers.
Strategic Opportunities
- India contract research expansion:Indian CROs building integrated informatics-laboratory hybrids capture sponsor demand for compressed discovery-to-IND timelines at reduced cost structures.
- Multi-omics convergence:Integration of genomics, proteomics, and metabolomics data pipelines with small-molecule design workflows opens white space in target identification and biomarker discovery.
- EU AI Act alignment:Early certification of explainable AI modules for regulatory submission packages creates differentiation as European health authorities formalize algorithmic transparency requirements.
Industry Challenges
- Legacy system integration:Pharmaceutical data architectures built on decade-old relational databases resist seamless API connectivity with modern cloud-native informatics platforms.
- Cross-functional workflow alignment:Computational chemists, biologists, and regulatory scientists operate in disconnected silos, impeding end-to-end platform adoption.
- ISO 14155 evidentiary standards:Evolving documentation requirements for informatics-derived clinical trial inputs create compliance uncertainty and extended legal review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drug Discovery Informatics Market |
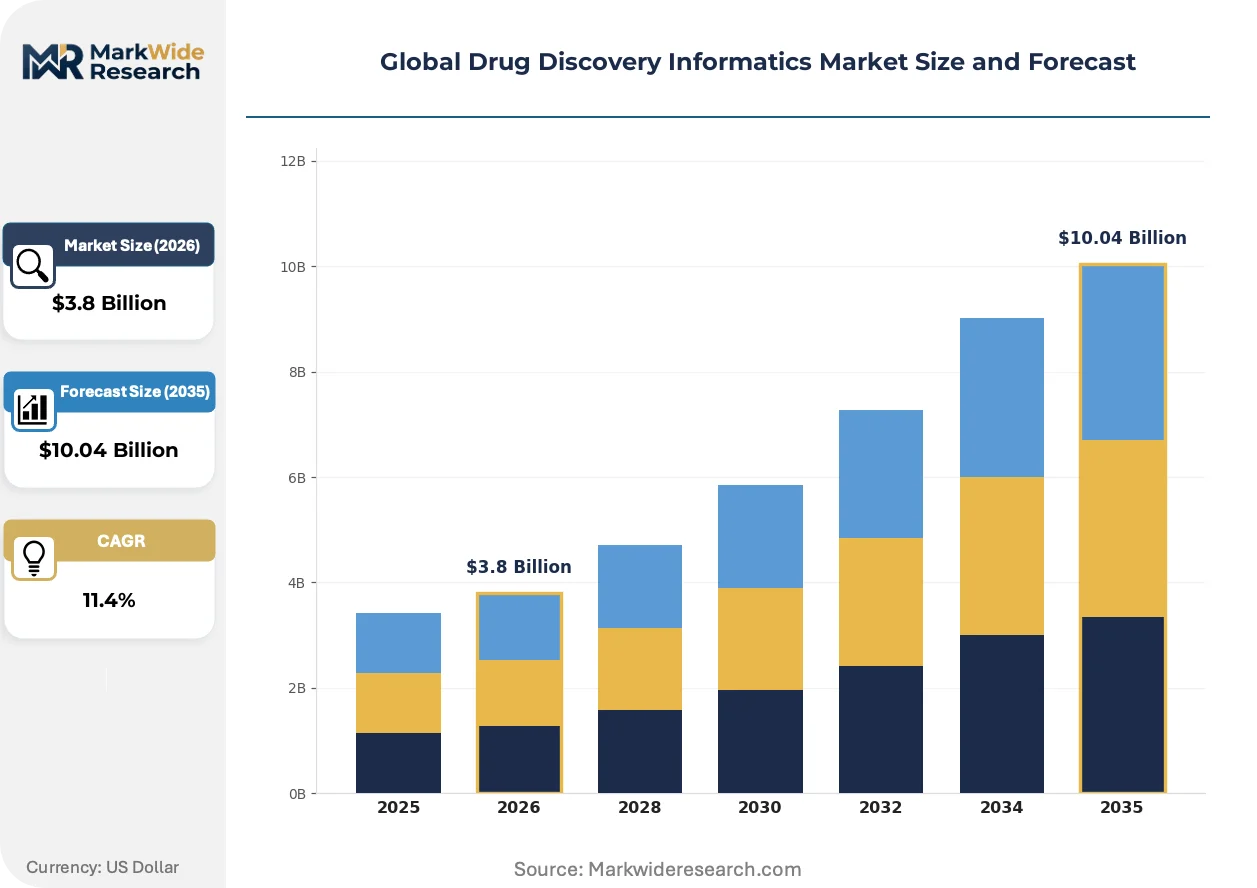
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Management, Molecular Modeling, Target Identification, High-Throughput Screening, Lead Optimization Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Bioinformatics, Laboratory Information Management Systems Application: Preclinical Research, Biomarker Discovery, Toxicology Analysis, Pharmacokinetics, Compound Profiling End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Academic Institutions, Regulatory Agencies |
| Companies Covered | Certara, Schrödinger, Charles River Laboratories, PerkinElmer, Evotec, Chemaxon Ltd, Infosys Ltd, Boehringer Ingelheim International GmbH, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drug Discovery Informatics Market Shifts & Advancements
Artificial intelligence architectures are converging with physics-based simulation engines to reshape how therapeutic candidates emerge from computational workflows, with regulatory acceptance frameworks racing to catch up with technical capabilities.
Generative chemistry models are converging with molecular dynamics simulation to propose and validate novel scaffolds in silico. Mid-cap biotechnology firms deploy these hybrid systems to replace high-throughput screening facilities entirely. The structural consequence is collapsing the traditional medicinal chemistry iteration cycle from twelve to eighteen months down to four to six weeks.
EMA's qualification opinion pathway for novel methodologies is formalizing acceptance criteria for model-informed drug development submissions. Pharmaceutical sponsors now commission extensive validation studies to secure regulatory buy-in prior to pivotal trial design. Small-molecule oncology programs face the steepest compliance burden as survival endpoints demand higher predictive confidence.
Biotechnology procurement departments are consolidating vendor relationships around integrated platform ecosystems rather than point solutions. Standalone docking or ADMET prediction tools lose share to suites offering seamless workflow orchestration. This concentration is most visible in the United States, where venture-backed startups prioritize rapid deployment over best-of-breed component assembly.
Global Drug Discovery Informatics Market Segmentation
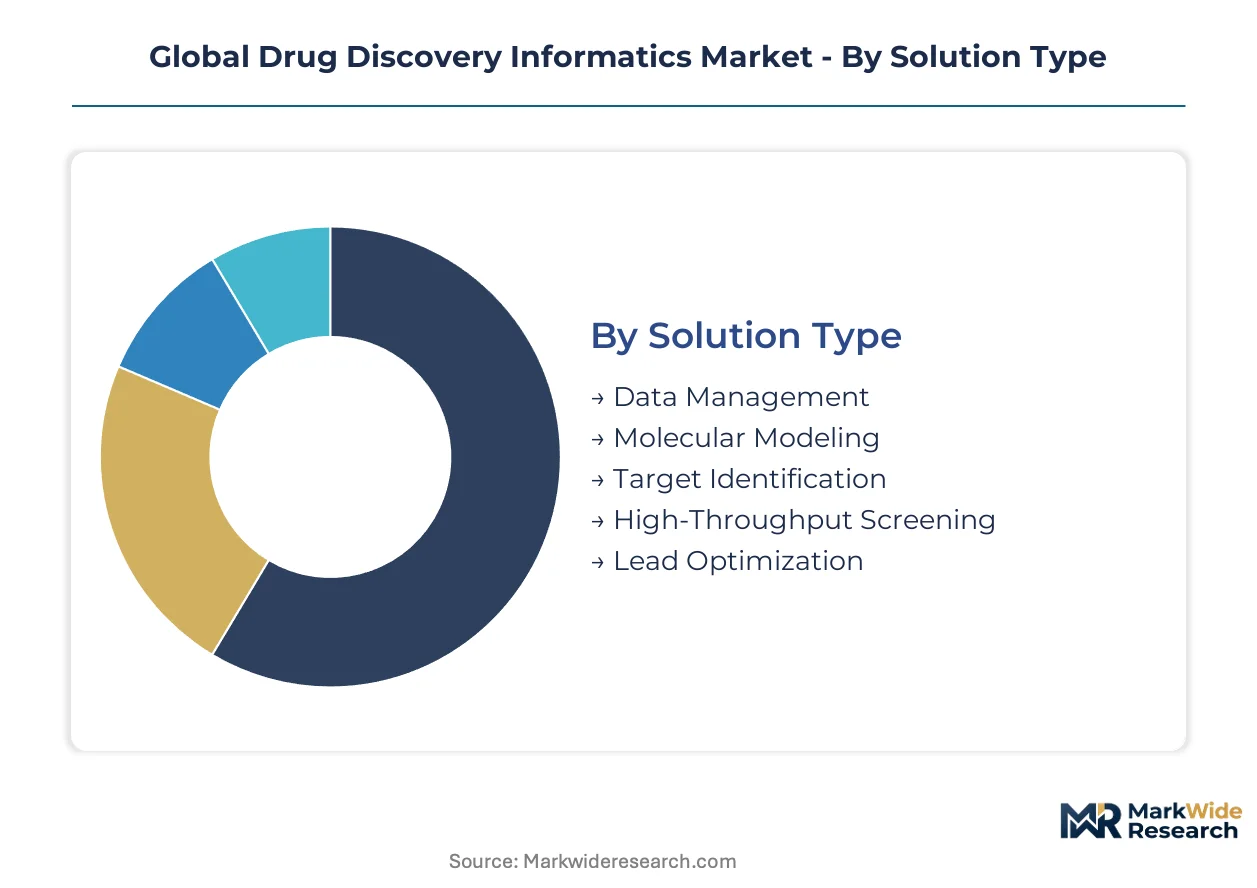
Segmentation in drug discovery informatics reveals how computational workloads distribute across discovery phases and organizational types. Vendors configure pricing and deployment models around whether platforms serve standalone research functions or embed within broader laboratory ecosystems.
Solution Type:
Standalone modules dominate early adoption cycles, while integrated suites capture enterprise renewals through workflow compression.
- Data Management:Centralized repositories harmonize chemical, biological, and clinical datasets across distributed research sites. Pharmaceutical incumbents in the United States deploy these systems to consolidate decades of proprietary assay records. Demand concentrates among organizations with multi-site discovery operations where data silos previously impeded cross-functional collaboration.
- Molecular Modeling:Physics-based simulation engines predict protein-ligand binding affinities and conformational dynamics. Schrödinger anchors its platform position here, serving biotechnology firms seeking to replace crystallography bottlenecks. The fastest expansion belongs to hybrid quantum-classical methods that compress optimization timelines.
- Target Identification:Multi-omics integration platforms prioritize druggable genomic loci through network pharmacology analysis.
- High-Throughput Screening:Virtual screening workflows replace physical compound libraries with in silico enumeration.
- Lead Optimization:ADMET prediction modules guide medicinal chemists through property refinement cycles.
Volume placements concentrate in Data Management; the faster expansion belongs to Molecular Modeling.
Technology:
Technology selection tracks computational intensity requirements and regulatory acceptance maturity for each methodology.
- Artificial Intelligence:Deep learning architectures predict molecular properties from structural fingerprints without explicit physical modeling. Venture-backed startups in the United States attract NIH funding to develop explainable AI modules that satisfy emerging FDA guidance on algorithmic transparency. Deployment concentrates in target identification and generative chemistry applications.
- Machine Learning:Random forests and gradient-boosted models optimize pharmacokinetic parameter prediction with lower computational overhead than neural approaches. Mid-tier biotechnology firms favor these methods for rapid deployment without specialized hardware investments. The steepest expansion trajectory appears in ADMET prediction where training data abundance supports robust model performance.
- Cloud Computing:Elastic infrastructure from Amazon Web Services and Microsoft Azure enables burst capacity for virtual screening campaigns.
- Bioinformatics:Sequence analysis pipelines process genomic and transcriptomic data for target prioritization.
- Laboratory Information Management Systems:Sample tracking and protocol execution platforms integrate wet-lab operations with computational workflows.
Cloud Computing commands the largest installed base; Artificial Intelligence gains share fastest among new procurement decisions.
Application:
Application segmentation follows the discovery pipeline from target validation through IND-enabling studies.
- Preclinical Research:Integrated platforms coordinate in vitro and in silico validation studies to support regulatory submission packages. Contract research organizations in India build informatics-laboratory hybrids to compress discovery-to-IND timelines for sponsor cost reduction. FDA's model-informed drug development framework accelerates validation investment in predictive simulation tools.
- Biomarker Discovery:Multi-omics data pipelines identify predictive signatures for patient stratification and companion diagnostic development. Oncology programs drive demand concentration as survival endpoints require higher predictive confidence under EMA qualification opinion pathways. The fastest growth appears in proteomics-metabolomics convergence applications.
- Toxicology Analysis:Computational models predict off-target effects and safety liabilities before animal study initiation.
- Pharmacokinetics:PBPK simulation platforms forecast human dose projections from preclinical data.
- Compound Profiling:Polypharmacology assessment tools characterize off-target activities across therapeutic classes.
Preclinical Research absorbs the greatest platform investment; Biomarker Discovery climbs fastest as precision medicine requirements tighten.
End User:
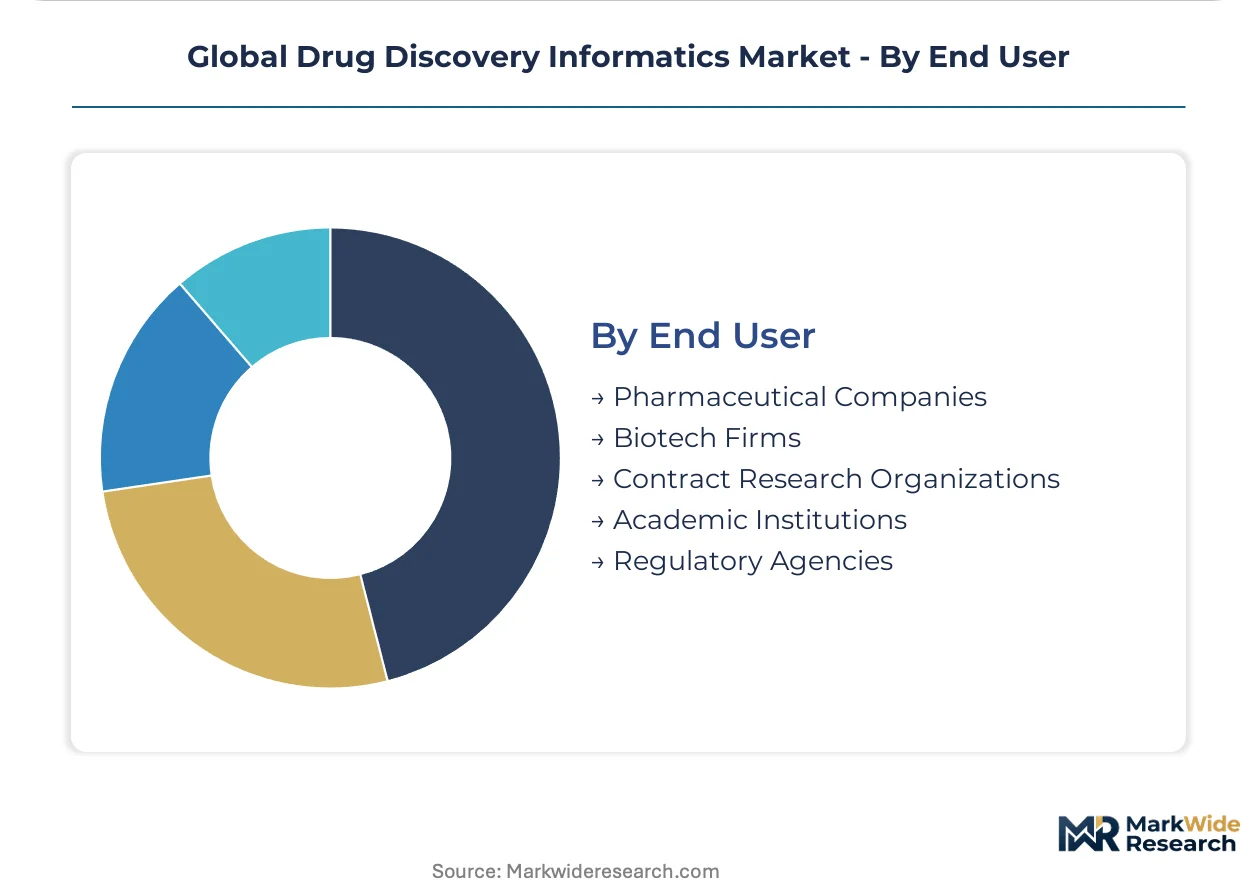
End-user mix reflects shifting R&D outsourcing patterns and public-private funding flows.
- Pharmaceutical Companies:Integrated platform deployments span discovery through clinical pharmacology with mandatory regulatory compliance modules. Legacy data architecture constraints impede cloud-native platform adoption at major incumbents. Procurement concentrates in lead optimization and clinical candidate selection workflows.
- Biotech Firms:AI-native startups prioritize rapid deployment over best-of-breed assembly, consolidating vendor relationships around integrated suites. NIH funding expansion in the United States broadens the subscriber base beyond traditional pharmaceutical dominance. The steepest expansion trajectory belongs to venture-backed organizations with asset-light operating models.
- Contract Research Organizations:Integrated informatics-laboratory offerings capture sponsor demand for compressed timelines.
- Academic Institutions:Federally funded research centers develop open-source tools that migrate to commercial platforms.
- Regulatory Agencies:Internal simulation capabilities support model-informed drug development framework implementation.
Pharmaceutical Companies maintain the largest committed spend; Biotech Firms expand their procurement share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates in the United States and Western Europe, while consumption spreads across biotech clusters in Asia-Pacific and contract research networks in India. NIH funding flows and venture capital availability determine where informatics vendors establish primary engineering centers.
United States
NIH grant expansion and venture capital concentration in Boston and San Francisco drive AI-native startup formation. FDA's model-informed drug development framework creates formal pathways for simulation-based submissions, accelerating vendor investment in predictive tools. The Greater Boston corridor hosts the densest cluster of physics-based molecular simulation firms serving biotechnology procurement departments.
Germany
Industrial pharmaceutical research from Heidelberg to Munich sustains demand for integrated informatics-laboratory platforms. EMA qualification opinion pathways for novel methodologies shape validation requirements for German-sponsored submissions. The Rhine-Main biotech corridor attracts contract research organizations building informatics-laboratory hybrids for European sponsor access.
India
Cost-compressed discovery-to-IND timelines attract multinational sponsor contracts to Indian CROs building informatics capabilities. CDSCO regulatory alignment with ICH standards enables integrated platform outputs to support international submission packages. The Hyderabad-Bengaluru corridor concentrates contract research informatics development for oncology and infectious disease programs.
United Kingdom
Academic research commercialization from Cambridge and Oxford feeds platform spin-outs targeting target identification workflows. MHRA engagement with FDA on model-informed drug development creates dual-validation opportunities for simulation vendors. The Cambridge cluster anchors European headquarters for several molecular modeling platform providers.
Japan
PMDA acceptance of AI-derived pharmacokinetic predictions expands addressable market for machine learning platform vendors. METI funding for pharmaceutical digitalization supports domestic biotech adoption of cloud-native informatics suites. The Kanto region concentrates pharmaceutical R&D spending on integrated data management and molecular modeling platforms.
Global Drug Discovery Informatics Market Competitive Landscape
Top-tier vendors anchor enterprise platform suites, while mid-tier specialists compete on workflow-specific modules. Physics-based simulation providers and AI-native startups occupy distinct strategic positions with limited direct overlap. Three archetypes dominate: integrated platform ecosystems, standalone molecular modeling engines, and laboratory-informatics hybrids. Consolidation pressure favors acquisition of specialized algorithm shops by full-service platform vendors, while strategic partnerships between cloud infrastructure providers and simulation software houses accelerate deployment velocity.
Within the integrated platform tier, Certara and Schrödinger occupy positions representing regulatory science consulting and physics-based molecular simulation respectively. Charles River Laboratories exemplifies the laboratory-informatics hybrid archetype, extending contract research services into computational workflows. These three anchors demonstrate how vendor strategy diverges across platform depth, scientific specialization, and service integration vectors.
| Leading Market Players |
|---|
| Certara |
| Schrödinger |
| Charles River Laboratories |
| PerkinElmer |
| Evotec |
| Chemaxon Ltd |
| Infosys Ltd |
| Boehringer Ingelheim International GmbH |
| IBM |
| Others |
Supply & Pricing Matrix
ISO 14155 and ICH E6(R2) compliance mandates gate qualified supply access for informatics platforms serving FDA submission workflows, with only vendors bearing validated regulatory science modules commanding premium-tier SaaS pricing from pharmaceutical incumbents. This certification barrier compresses the addressable vendor base while amplifying pricing power for compliant platform providers.
Pricing Analysis
Margin tightening in mid-tier molecular modeling reflects intensifying competition from AI-native startups undercutting physics-based simulation suites on annual contract value. Pricing stratifies across enterprise subscription tiers anchored by regulatory consulting bundles, usage-based burst compute for virtual screening, and entry-level SaaS modules for academic users. Pharmaceutical procurement departments exhibit highest price sensitivity, while venture-backed biotech firms prioritize rapid deployment velocity over cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA GPU allocation for quantum mechanical simulation workloads, constraining platform scaling for vendors lacking long-term silicon supply agreements. Engineering talent concentrates in the United States, Germany, and the United Kingdom, while cloud infrastructure feeds from Amazon Web Services and Microsoft Azure data centers across North America and Western Europe. Tariff exposure on specialized hardware imports threatens margin stability for simulation-intensive platform providers. Distribution runs through direct enterprise sales teams and strategic partnerships with contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physics-based molecular simulation is displacing empirical high-throughput screening as the dominant paradigm, compressing discovery timelines and forcing legacy platform vendors to rearchitect around hybrid AI-simulation engines or face displacement.
For Market Incumbents: To counter AI-native startup encroachment on lead optimization workflows, Certara and Schrödinger should deepen regulatory science consulting integration with platform subscriptions while securing exclusive cloud compute partnerships to lock in burst capacity pricing advantages. Backward integration into specialized GPU supply chains would defend margin position against silicon allocation constraints. For New Entrants and Emerging Players: Explainable AI modules for FDA model-informed drug development submissions represent the most penetrable white space, as regulatory transparency requirements outpace incumbent platform capabilities. Target Indian contract research organizations building informatics-laboratory hybrids with modular API-first architectures that compress discovery-to-IND timelines at reduced cost structures. Go-to-market should emphasize rapid deployment guarantees over feature depth. For Investors and Strategic Acquirers: EMA qualification opinion pathway approvals for novel simulation methodologies are the leading indicator that platform vendors have achieved regulatory defensibility worth premium valuation multiples. Long-term viability favors acquisition targets combining proprietary molecular dynamics engines with established FDA submission track records. Watch for NIH grant concentration shifts toward quantum-classical hybrid methods as the inflection signal for next-generation platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Science Consulting Integration | Certara's FDA submission expertise anchors enterprise pricing power against pure-play software competitors. |
| Quantum-Classical Simulation Engine Development | Schrödinger's hybrid methods compress lead optimization timelines from months to weeks for biotechnology clients. |
| Cloud-Native Platform Architecture Migration | Elastic AWS and Azure deployment enables high-throughput virtual screening without capital-intensive on-premise infrastructure. |
| Indian CRO Informatics-Laboratory Hybrid Buildout | Charles River Laboratories extends contract research services into computational workflows for cost-compressed sponsor timelines. |
| Explainable AI Module Certification | EU AI Act alignment creates differentiation as European health authorities formalize algorithmic transparency requirements for submissions. |
Research Methodology
Document review covered FDA model-informed drug development guidance documents, EMA qualification opinion pathway submissions, and NIH funding allocation records, complemented by interviews with drug development executives, regulatory affairs leads, computational chemistry directors, and platform procurement officers at biotechnology firms. Secondary validation drew from ClinicalTrials.gov simulation study registrations, SEC 10-K software revenue disclosures, and cloud infrastructure provider capex reports. Bottom-up and top-down triangulation reconciled vendor platform deployment estimates with sponsor R&D spending patterns.
Historical growth trajectories were cross-referenced against panel input from industry stakeholders to inform analytical framework construction across the projection horizon. Segmentation dimensions modeled include solution type, technology architecture, discovery phase application, and end-user organization scale. CAGRs were derived from fitted trend analysis incorporating NIH funding velocity, venture capital deployment into AI-native startups, and FDA regulatory acceptance rate assumptions for simulation-based submissions.
Several conditions sit outside the modeled scope, including unforeseen shifts in FDA evidentiary standards for AI-derived predictions, geopolitical disruptions to cloud infrastructure access, and abrupt consolidation among mid-tier biotechnology firms. Forecasts reflect documented assumptions about regulatory pathway maturation and cloud compute cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Software Synthesizers Market
Others
Wind and Solar Hybrid Street Light Market
Others
Coriolis Meters Market
Others
France 3D Printing Construction Market
Others
Global Recruitment and Staffing Market
Others
Diamond Mining Market
Others
Reinforcement Geosynthetics Market
Others
Global Active Speaker Market
Others
Buchner Funnels Market
Others
Japan 3D Printing Construction Market
Others
Bird Food Market
Others
Couscous Market
Others
Android STB and TV Market
Others
Cremation Furnace Market
Others
South America Halal Food and Beverages Market
Others
Hypersensitivity Market