
 Decanol Market | 2026-2036
Decanol Market Size, Share, and Industry Trends Forecast 2026-2036
Decanol Market Analysis
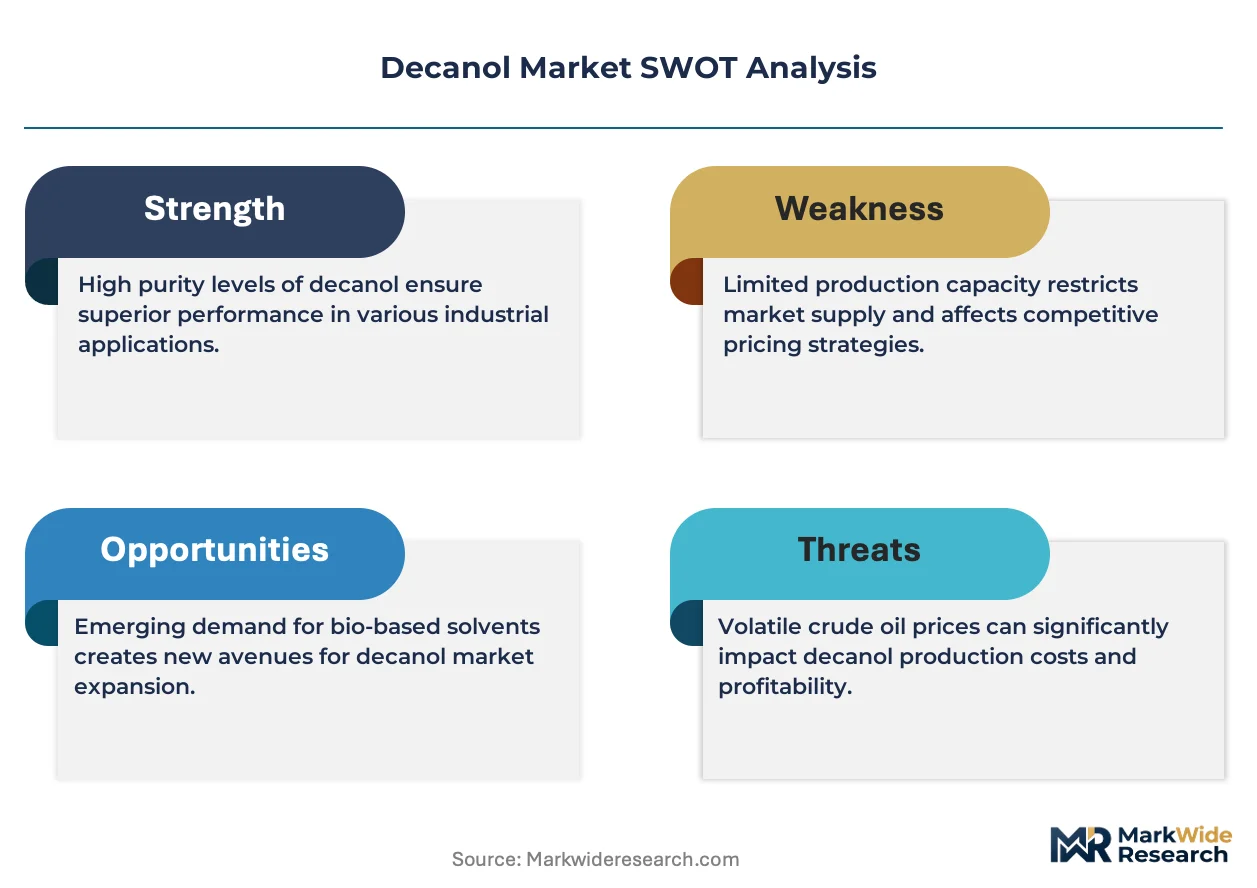
The gap between pharmaceutical-grade purified decanol and industrial blends is recalibrating procurement patterns across downstream sectors. BASF SE leverages its integrated oleochemicals platform to sustain supply security for high-purity grades. Emery Oleochemicals anchors its position through backward integration into tropical oil feedstocks. Kao Corporation competes on specialized cosmetic-grade specifications for Asian personal care markets.
Decanol refers to a ten-carbon primary alcohol existing as multiple isomers, with 1-decanol being the most commercially significant form; it is produced via ethylene oligomerization or natural oil hydrogenolysis and functions primarily as a chemical intermediate, solvent, and formulation ingredient across surfactant, lubricant, and personal care applications. Purified decanol commands the strongest margin pool due to pharmaceutical and cosmetic certification requirements, while decanol blends serve volume-driven industrial cleaning and plasticizer markets where specification tolerance is wider. The surfactants application category leads current offtake, though emollient demand in premium personal care is expanding fastest.
EPA chemical safety evaluations under TSCA and REACH registration requirements in Europe shape product standards and market access for decanol suppliers serving regulated end uses. FDA oversight of cosmetic ingredient safety and pharmaceutical excipient qualification further stratifies the competitive landscape between certified and uncertified supply tiers. Stakeholders must monitor evolving biobased content mandates and feedstock traceability rules as these criteria increasingly determine contract eligibility across European and North American buyer networks.
Market Dynamics
The decanol market is bifurcating sharply between certified pharmaceutical-cosmetic grades and industrial commodity streams, with REACH purity mandates and EPA TSCA safety reviews compressing supply options for regulated end uses while surfactant and plasticizer demand concentrates in Asian manufacturing clusters.
Growth Catalysts
- REACH Registration:European chemical safety requirements are forcing cosmetic and pharmaceutical formulators toward certified high-purity decanol, eliminating uncertified suppliers from contract eligibility pools.
- Surfactant Manufacturing:China's domestic output of anionic and non-ionic surfactants is absorbing decanol volumes at scale, particularly for household and industrial cleaning applications.
- Ethylene Oligomerization:Synthetic production routes are achieving tighter carbon-chain distribution control, enabling more consistent feedstock quality for premium-grade alcohol derivatives.
Market Restraints
- Palm Kernel Oil Volatility:Natural oil hydrogenolysis feedstock costs fluctuate with Malaysian and Indonesian crude palm oil pricing, compressing margin predictability for oleochemical producers.
- Specialty Grade Concentration:Pharmaceutical and cosmetic certification capabilities cluster among integrated oleochemical majors, limiting qualified supplier pools for regulated buyers.
- Linear Alcohol Substitution:C12-C14 alcohol blends compete in surfactant applications where chain-length specificity is less critical, pressuring decanol volume in commodity detergent markets.
Strategic Opportunities
- Indian Personal Care:BIS standards evolution and domestic formulator expansion create openings for certified decanol supply as multinational brands localize production.
- Biobased Content Mandates:EU Green Deal sustainable carbon targets and corporate Scope 3 reduction commitments favor natural-origin decanol in European cosmetic and lubricant formulations.
- Direct Contracting:Large surfactant and plasticizer manufacturers are bypassing distributors to secure dedicated offtake agreements with oleochemical producers, reshaping channel economics.
Industry Challenges
- Pharmaceutical Excipient Qualification:FDA Drug Master File submission timelines and ICH Q3C residual solvent compliance extend certification cycles to 18-24 months for new decanol supply sources.
- Analytical Capability Investment:Gas chromatography and mass spectrometry infrastructure for isomeric purity verification requires substantial capital outlay, disadvantaging smaller regional blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decanol Market |
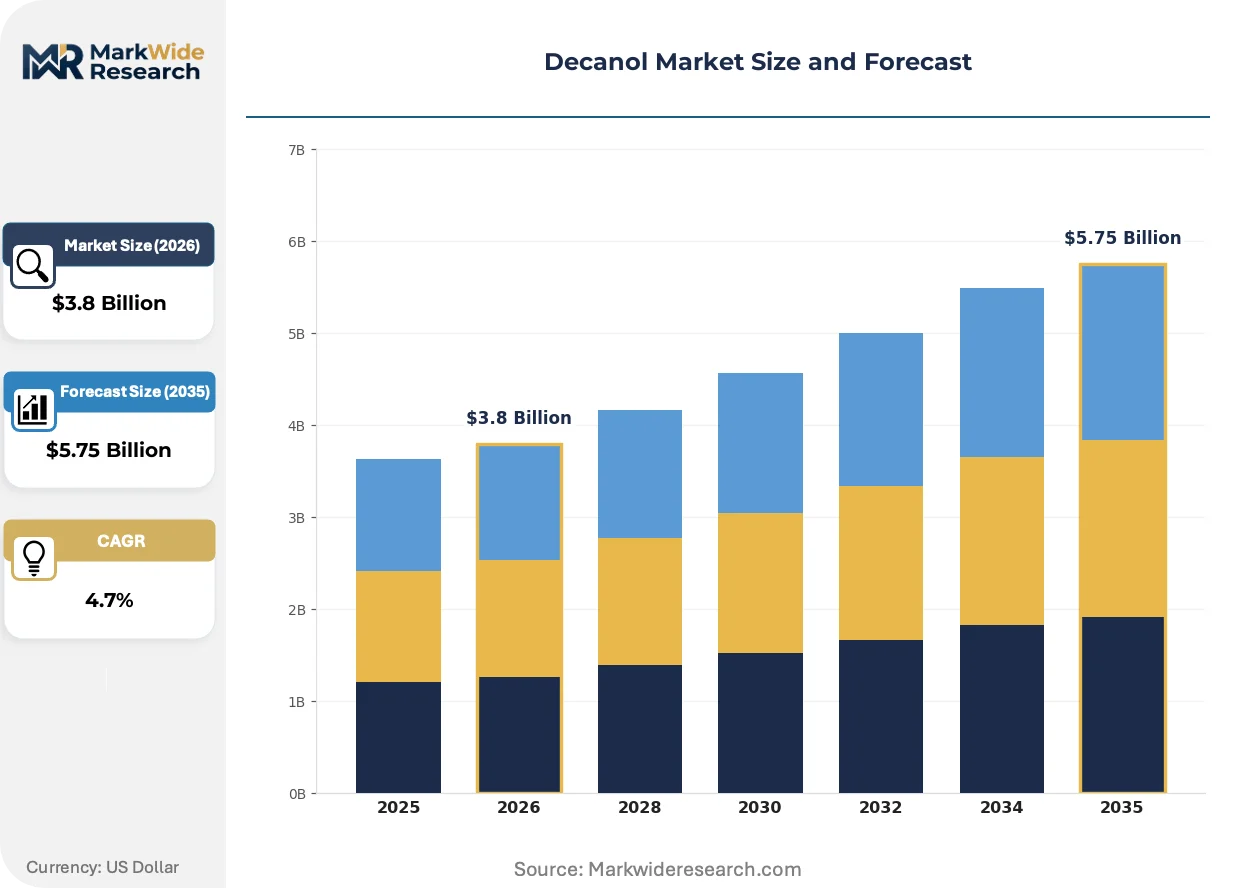
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Decanol, Decanol Blends, Industrial Decanol, Cosmetic Grade Decanol End Use: Personal Care, Pharmaceuticals, Industrial Cleaning, Plasticizers Application: Solvents, Emollients, Surfactants, Coatings Supply Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | Emery Oleochemicals, ExxonMobil Chemical Company, BASF SE, Kao Corporation, Evonik Industries AG, Sasol Limited, Musim Mas Group, Oxiteno, Kuala Lumpur Kepong Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decanol Market Emerging Trajectories
Process intensification and digital traceability systems are reconfiguring how decanol purity is verified and certified across supply chains, while feedstock provenance becomes a competitive differentiator in regulated end uses.
Membrane filtration technology is integrating into downstream decanol purification trains, enabling producers to achieve pharmaceutical-grade specifications without energy-intensive fractional distillation. Cosmetic and excipient manufacturers in Germany and Switzerland are adopting membrane-polished supply streams for carbon-footprint reduction targets. This integration is compressing the capital-cost gap between synthetic and natural-origin high-purity production routes.
ECHA's SCIP database requirements under the Waste Framework Directive are mandating article-level substance of very high concern disclosure throughout European supply chains. Decanol-containing formulations in consumer products must now demonstrate full upstream transparency to maintain market access. Personal care brands with complex multi-tier supplier networks face the steepest compliance reconfiguration.
Formulator consolidation among multinational personal care groups is concentrating purchasing power and extending qualification timelines for new raw material suppliers. Tier-1 manufacturers now demand combined ISO 9001, ISO 14001, and RSPO mass-balance certification as baseline contract conditions. This behavioral shift is most pronounced in Nordic and Benelux markets where retailer sustainability scorecards drive ingredient selection.
Decanol Market Segmentation
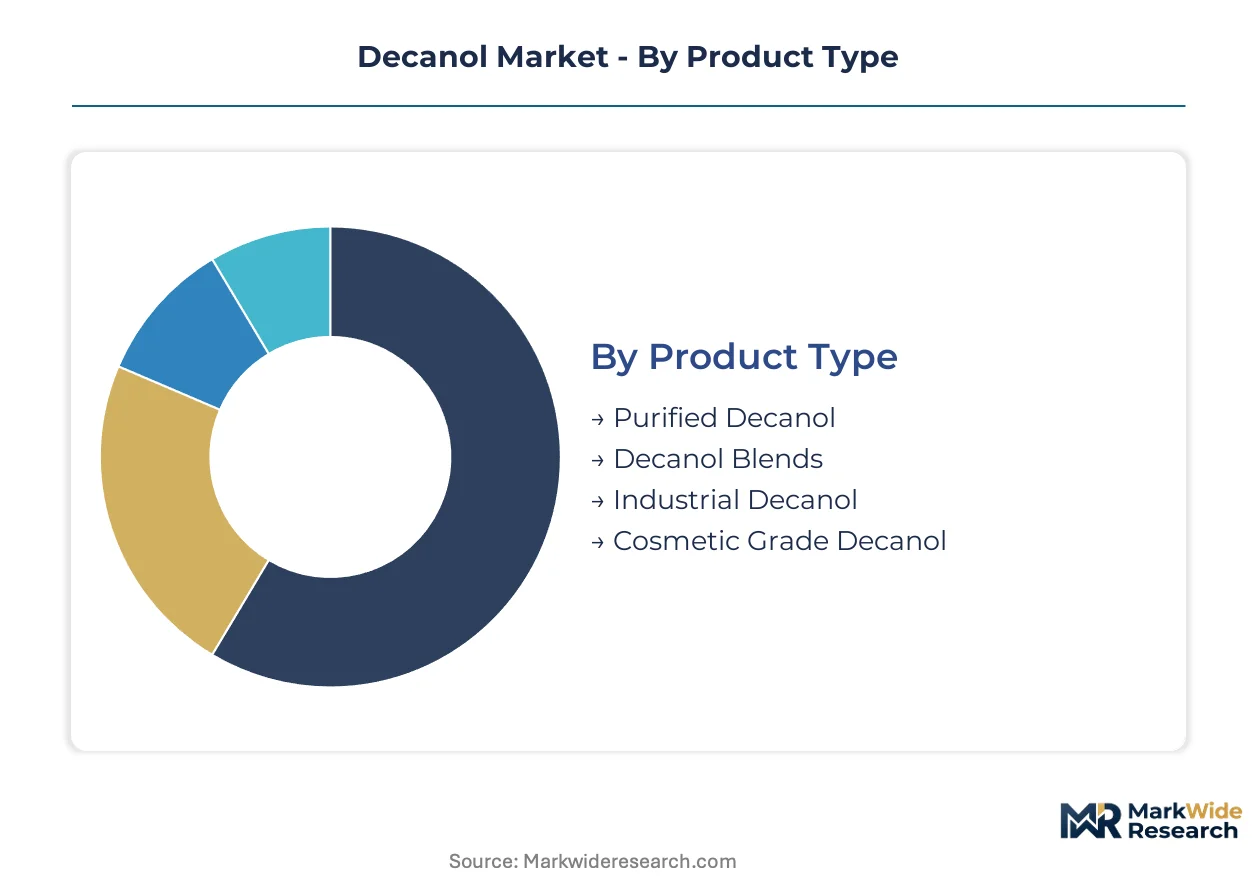
Decanol procurement patterns diverge sharply across purity grades and end-use certifications, with pharmaceutical and cosmetic formulators demanding analytical documentation that industrial buyers rarely require. Understanding these segment boundaries clarifies why supplier capabilities cluster unevenly despite apparent commodity characteristics.
Product Type:
Formulators upgrade from industrial to cosmetic-grade specifications when REACH registration or FDA excipient qualification becomes mandatory, triggering replacement cycles that favor integrated oleochemical producers with captive analytical infrastructure.
- Purified Decanol:Pharmaceutical-grade material meeting ICH Q3C residual solvent limits and USP-NF monograph requirements. FDA Drug Master File submissions from German and Swiss excipient manufacturers concentrate demand for documented chain-of-custody material with isomeric purity verification.
- Decanol Blends:Mixed C8-C12 alcohol streams optimized for surfactant feedstock economics. Chinese anionic detergent producers absorb volumes through direct contracting arrangements that bypass traditional distribution layers.
- Industrial Decanol:Technical-grade material for lubricant and metalworking fluid applications where odor and color specifications tolerate wider variance.
- Cosmetic Grade Decanol:RSPO mass-balance certified material with heavy metals and peroxide specifications tailored to premium personal care formulators in Nordic markets.
Purified decanol sits at the top of the volume ranking, with cosmetic grade decanol climbing the fastest as multinational brands localize production in India and Southeast Asia.
End Use:
Cost tier differentiation separates excipient-qualified supply from commodity streams, with certification overhead creating margin pools that only integrated producers can capture.
- Personal Care:Emollient and surfactant applications in skin and hair care formulations. EU Green Deal biobased content mandates and retailer sustainability scorecards in Benelux markets favor natural-origin decanol with documented feedstock provenance.
- Pharmaceuticals:Excipient and synthesis intermediate uses subject to FDA oversight and EMA quality guidelines. Swiss and German generic drug manufacturers maintain qualified supplier lists with 18-24 month onboarding timelines.
- Industrial Cleaning:Hard surface and equipment degreasing formulations where C12-C14 alcohol substitution pressures decanol volume.
- Plasticizers:Polymer additive applications in flexible PVC and synthetic rubber, concentrated in Chinese manufacturing clusters.
Personal care commands the largest absolute volume, while pharmaceutical applications deliver the steepest margin expansion trajectory.
Application:
Customer type segmentation distinguishes specification-intensive buyers from price-sensitive commodity offtakers, with surfactant manufacturers representing the volume anchor and emollient formulators the value upside.
- Surfactants:Anionic and non-ionic detergent feedstocks requiring consistent carbon-chain distribution. Chinese household cleaning product manufacturers drive offtake through backward-integrated oleochemical complexes.
- Emollients:Skin-feel and spreadability modifiers in premium cosmetic formulations. Korean and Japanese personal care brands specify low-odor, low-color material with tropical oil traceability documentation.
- Solvents:Carrier and extraction applications in pharmaceutical and agrochemical processing.
- Coatings:Flow-control additives in industrial paint and varnish systems.
Surfactants dominate current offtake, with emollients gaining share fastest as Asian middle-class consumption shifts toward premium personal care.
Supply Channel:
Geography-driven channel restructuring is concentrating procurement power among large surfactant and plasticizer manufacturers capable of direct producer engagement.
- Direct Sales:Dedicated offtake agreements between oleochemical majors and multinational formulators. BASF and Kao Corporation anchor this channel with integrated supply security guarantees.
- Distributors:Regional stocking and technical service networks serving mid-tier formulators without qualification resources.
- Online Retail:Small-volume specialty chemical portals for research and pilot-scale procurement.
- Exporters:Trading houses bridging Malaysian and Indonesian production to Indian and Middle Eastern markets.
Direct sales channels capture the largest volume flows, with distributor relationships expanding most quickly among Indian domestic formulators building technical capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in Germany's Ruhr Valley and China's Yangtze Delta anchor the highest-value decanol production capabilities worldwide. These workforce concentrations sustain the analytical infrastructure and process control expertise that pharmaceutical-grade certification demands.
China
Surfactant manufacturing expansion in Jiangsu and Zhejiang provinces absorbs decanol volumes at industrial scale. The Ministry of Ecology and Environment enforces dual carbon goals that favor process efficiency investments in oleochemical complexes. Nantong and Taizhou chemical parks concentrate backward-integrated production serving domestic detergent and plasticizer markets.
Germany
Excipient-qualified supply chains in North Rhine-Westphalia serve Swiss and German generic drug manufacturers with documented isomeric purity. ECHA REACH registration requirements eliminate uncertified suppliers from pharmaceutical contract pools. Ludwigshafen and Marl industrial clusters integrate membrane filtration technology to reduce carbon intensity in high-purity alcohol production.
United States
EPA TSCA safety reviews compress supply options for cosmetic and pharmaceutical formulators seeking compliant feedstock. The Gulf Coast petrochemical corridor sustains synthetic decanol output through ethylene oligomerization infrastructure. Houston-area producers leverage integrated oleochemical platforms to serve multinational personal care brands with certified material.
India
Domestic formulator expansion in Maharashtra and Gujarat creates demand for BIS-standard cosmetic-grade decanol as multinational brands localize production. CDSCO pharmaceutical oversight extends excipient qualification timelines for imported supply sources. Mumbai-Pune industrial belt distributors are building technical service capabilities to bridge qualified producer networks and mid-tier buyers.
Malaysia
Tropical oil feedstock availability in Peninsular Malaysia sustains natural-origin decanol production with RSPO mass-balance certification for European cosmetic markets. The Malaysian Palm Oil Board enforces sustainability traceability requirements that determine contract eligibility with Nordic retailers. Klang Valley processing clusters export to Indian and Middle Eastern markets through regional trading houses.
Decanol Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-cosmetic certification, while regional blenders and commodity distributors occupy price-sensitive industrial segments. The market structure concentrates qualified supply among integrated oleochemical majors with captive analytical infrastructure. Three archetypes dominate: backward-integrated tropical oil processors, synthetic petrochemical producers with carbon-chain control, and specialty chemical houses serving Asian personal care markets. Competitive moves center on direct contracting arrangements that bypass distribution layers and membrane technology licensing for energy-efficient purification.
Within the integrated oleochemical tier, BASF SE and Emery Oleochemicals exemplify the capability concentration that REACH and FDA qualification demands. Kao Corporation occupies a position representing specialized cosmetic-grade specifications for Asian markets. These three anchors illustrate how certification infrastructure and feedstock control separate contract-eligible supply from commodity streams.
| Leading Market Players |
|---|
| Emery Oleochemicals |
| ExxonMobil Chemical Company |
| BASF SE |
| Kao Corporation |
| Evonik Industries AG |
| Sasol Limited |
| Musim Mas Group |
| Oxiteno |
| Kuala Lumpur Kepong Berhad |
| Others |
Supply Flow & Price Mechanics
REACH registration mandates for pharmaceutical-grade decanol are compressing supplier pools and forcing procurement toward integrated oleochemical majors with captive analytical infrastructure, concentrating pricing power among certified producers while uncertified blenders face margin erosion.
Pricing Analysis
Bundled certification-plus-analytics services command substantial premiums over unbundled commodity supply. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates contract-eligible supply from volume-driven streams. Price differentiation rests on isomeric purity verification and RSPO mass-balance documentation. Cost compression in industrial blends is intensifying because C12-C14 alcohol substitution pressures decanol volume in commodity detergent markets. Personal care formulators show least price sensitivity due to excipient qualification barriers, while Chinese surfactant manufacturers absorb volumes through direct contracting at tight margins.
Supply Chain Analysis
EU Green Deal biobased content mandates are reshaping sourcing toward Malaysian and Indonesian tropical oil feedstocks with documented provenance. Geographic supply concentration centers on Germany, China, and Malaysia as the dominant production clusters. Raw material dependencies draw from palm kernel oil, ethylene feedstocks, and hydrogenation catalysts. Single-source vulnerability runs through Malaysian crude palm oil pricing volatility. Distribution runs through direct offtake agreements between oleochemical majors and multinational formulators, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decanol procurement has shifted toward late-cycle quality specifications as pharmaceutical and cosmetic formulators extend qualification timelines and consolidate supplier lists around certified integrated producers.
For Market Incumbents: Acquire membrane filtration technology assets to reduce carbon intensity in high-purity production without energy-intensive fractional distillation. BASF and Emery Oleochemicals should deepen backward integration into RSPO-certified tropical oil estates to secure feedstock provenance documentation for European cosmetic markets. C12-C14 alcohol substitution in commodity surfactants represents the primary volume threat requiring defensive positioning in emollient-grade specifications. For New Entrants and Emerging Players: Capture Indian personal care localization as multinational brands build domestic formulation capabilities under evolving BIS standards. Mid-tier surfactant manufacturers in Maharashtra and Gujarat offer penetrable entry points for certified cosmetic-grade supply. Partner with Mumbai-Pune industrial belt distributors building technical service capabilities to bridge qualified producer networks and price-sensitive domestic formulators. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated oleochemical specialists possessing pharmaceutical excipient qualification infrastructure and tropical oil estate control. Long-term viability favors producers with combined ISO 9001, ISO 14001, and RSPO mass-balance certification as baseline contract conditions across European buyer networks. Monitor ECHA SCIP database compliance timelines as the critical inflection signal for supply chain transparency investments.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Enables pharmaceutical-grade purification without energy-intensive fractional distillation for German and Swiss cosmetic manufacturers. |
| RSPO Mass-Balance Certification | Determines contract eligibility with Nordic retailers enforcing EU Green Deal sustainable carbon targets. |
| Direct Contracting Arrangements | Reshapes channel economics as Chinese surfactant manufacturers bypass distributors for dedicated offtake agreements. |
| Indian Market Localization | Captures demand from multinational personal care brands building domestic formulation capabilities under BIS standards. |
| Pharmaceutical Excipient Qualification | Extends competitive moats through FDA Drug Master File submissions and ICH Q3C residual solvent compliance. |
Methodological Framework
Multiple input streams — primary interviews with oleochemical plant managers and personal care procurement leads, secondary validation through customs data and SEC filings from listed chemical producers, and technical literature on membrane filtration advances — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included surfactant manufacturing executives in Jiangsu and Zhejiang provinces, pharmaceutical excipient qualification specialists in North Rhine-Westphalia, and RSPO certification officers in Peninsular Malaysia. Secondary sources comprised trade data from Malaysian Palm Oil Board disclosures, ECHA REACH registration databases, and BASF and Kao Corporation sustainability reports.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor projections across the analysis window. Segmentation modeling incorporated grade tier distinctions, end-use industry classifications, and regional production hub dynamics. CAGRs were derived through iterative reconciliation of supply-side capacity announcements and demand-side offtake patterns. Industry-specific forecast inputs included ethylene oligomerization capacity expansion timelines and palm kernel oil price volatility indices.
Feedstock price shocks, regulatory timeline extensions for pharmaceutical qualification, and substitution acceleration in commodity surfactants are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Fluorinated Solvents Market
Solvents
Asia-Pacific Ethane Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Diethanolamine (DEA) Market
Solvents
Benzylamine Market
Solvents
Global Ink Solvents Market
Solvents
Ortho-Xylene Market
Solvents
Global Solvent Dyes Market
Solvents
High Purity Solvents Market
Solvents
Trifluoroethanol Market
Solvents
Phenylacetonitrile Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Hexylene Glycol Market
Solvents
Solvent Cement Market
Solvents
Europe Acetonitrile Market