
 Consumer Floriculture Market | 2026-2036
Consumer Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Floriculture Market Insights
Dutch breeder-producer capacity is hardening around proprietary genetics and climate-controlled propagation infrastructure. Syngenta Flowers leverages molecular breeding platforms to compress cultivar development cycles. Ball Horticultural anchors North American supply through its distribution network of licensed propagators. Dümmen Orange differentiates via global rooting stations that reduce transit stress on unrooted cuttings.
Consumer floriculture encompasses the cultivation, processing, and distribution of ornamental plants and flowers for non-industrial end use, with products classified by perishability metrics such as vase life duration, chilling sensitivity measured in degree-hours, and post-harvest ethylene exposure thresholds. The primary commercial purpose centers on aesthetic enhancement of residential, ceremonial, and retail environments through living or preserved plant material. Cut flowers command the largest revenue pool within product type segments due to high turnover velocity in event and gifting channels, while potted plants capture margin concentration through extended retail shelf life and lower logistics spoilage rates. Online stores represent the fastest-expanding sales channel, driven by subscription bouquet models and direct-to-consumer fulfillment networks that bypass traditional wholesale auction layers.
The EU Green Deal and REACH frameworks govern chemical inputs across European cultivation zones, while the USDA and EPA regulate pesticide residues and invasive pest pathways for imports entering United States territory. These standards reshape competitive access by elevating compliance costs for non-certified producers and redirecting procurement toward verified sustainable supply chains. Stakeholders must monitor evolving phytosanitary protocols and carbon border adjustments that will determine which origin countries retain shelf space in premium retail channels.
Market Dynamics
The EU Green Deal is compressing competitive access for non-certified producers while Dutch auction infrastructure concentrates supply-side power around Aalsmeer's cold-chain density.
Growth Catalysts
- REACH chemical frameworks:European regulators are redirecting procurement toward verified sustainable supply chains, elevating certified producers above commodity competitors.
- Subscription bouquet models:Direct-to-consumer fulfillment networks are bypassing traditional wholesale auction layers entirely.
- Aalsmeer cluster density:Netherlands-based cold-chain logistics infrastructure enables same-day distribution velocity unmatched by peripheral origins.
Market Restraints
- Phytosanitary compliance costs:EU Green Deal tightening on imported floral products elevates entry barriers for non-European cultivation zones.
- Input energy volatility:Climate-controlled propagation infrastructure exposes Dutch producers to natural gas price swings.
- Perishability physics:Vase life duration and chilling sensitivity measured in degree-hours cap geographic sourcing radius regardless of labor arbitrage.
Strategic Opportunities
- Corporate event vertical:Event planners are expanding procurement of sustainably certified cut flowers for corporate gatherings.
- Online store channel innovation:Digital platforms are capturing margin previously absorbed by wholesale auction intermediaries.
- Carbon border adjustment preparation:Early compliance with emerging EU carbon accounting standards positions certified producers for preferential shelf access.
Industry Challenges
- Molecular breeding talent scarcity:Compression of cultivar development cycles demands specialized genomics expertise concentrated at Syngenta-level platforms.
- Rooting station integration complexity:Global propagation networks require synchronization of unrooted cutting transit stress protocols across multiple climatic zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Floriculture Market |
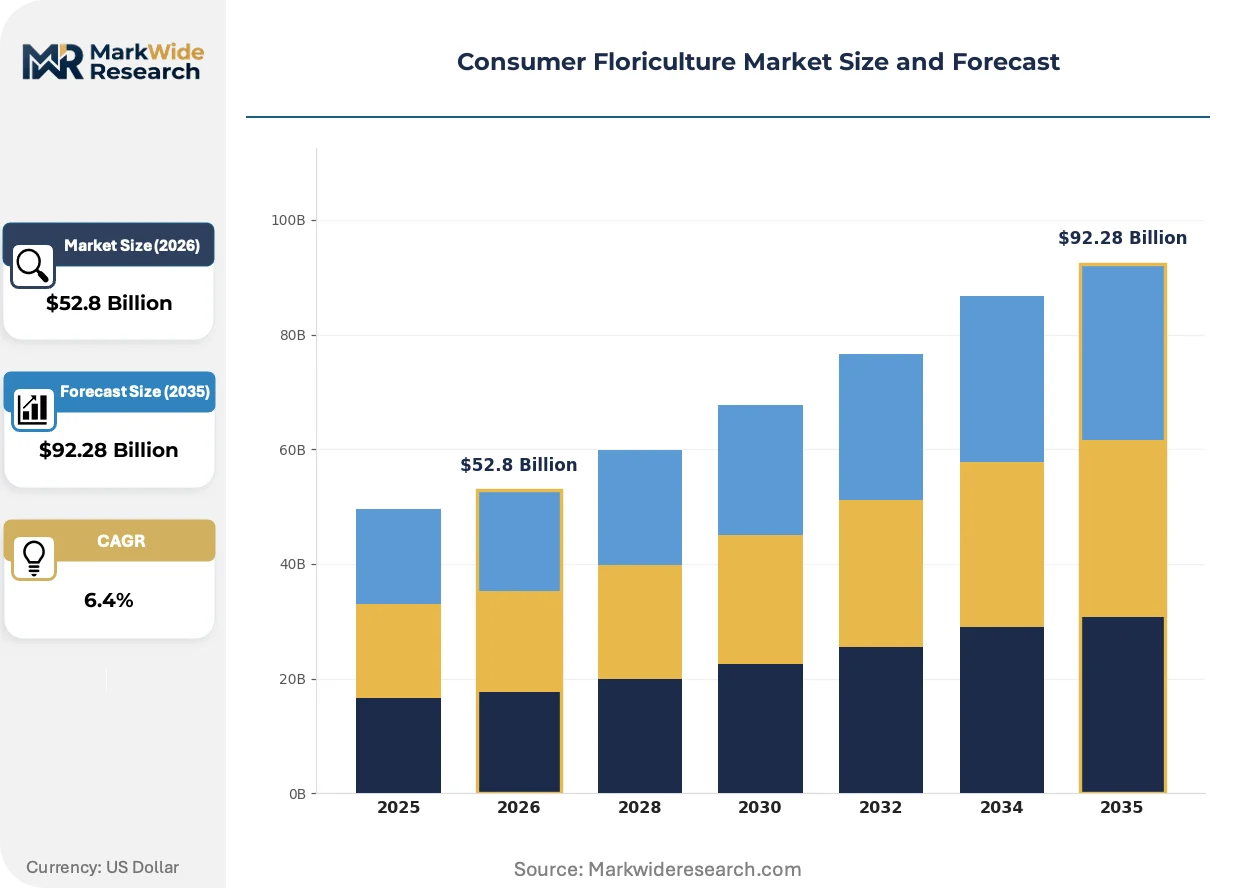
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flowering Plants, Foliage Plants, Cut Flowers, Potted Plants End User: Individuals, Retailers, Wholesale Distributors, Event Planners Sales Channel: Online Stores, Garden Centers, Supermarkets, Farmers' Markets Distribution Channel: Direct Sales, E-commerce, Wholesale, Franchise |
| Companies Covered | Dümmen Orange, Syngenta Flowers, Finlays, Beekenkamp, Karuturi, Oserian, Selecta One, Washington Bulb, Ball Horticultural, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Floriculture Market Trends and Innovations
Molecular breeding platforms are compressing product development timelines while regulatory frameworks accelerate supply chain verification requirements.
Genomic selection technology is consolidating cultivar development cycles from traditional decade-long timelines into multi-year windows. Breeder-producers adopting these platforms are capturing proprietary genetics faster than conventional hybridization programs permit. This acceleration is consolidating competitive advantage around firms with captive molecular biology infrastructure.
REACH and EU Green Deal frameworks are tightening chemical input restrictions across European cultivation zones. Industrial consequence includes elevated compliance documentation burdens and third-party certification requirements for market access. Cut flower imports entering Netherlands auctions face intensified residue testing protocols that smaller origin-country exporters struggle to satisfy.
Corporate procurement departments are embedding sustainability verification into supplier scorecards ahead of regulatory mandates. Traditional wholesale auction layers are losing volume to direct contracts between certified farms and event planning agencies. Germany and Netherlands corporate headquarters are driving this preference shift through centralized procurement policy.
Consumer Floriculture Market Segmentation
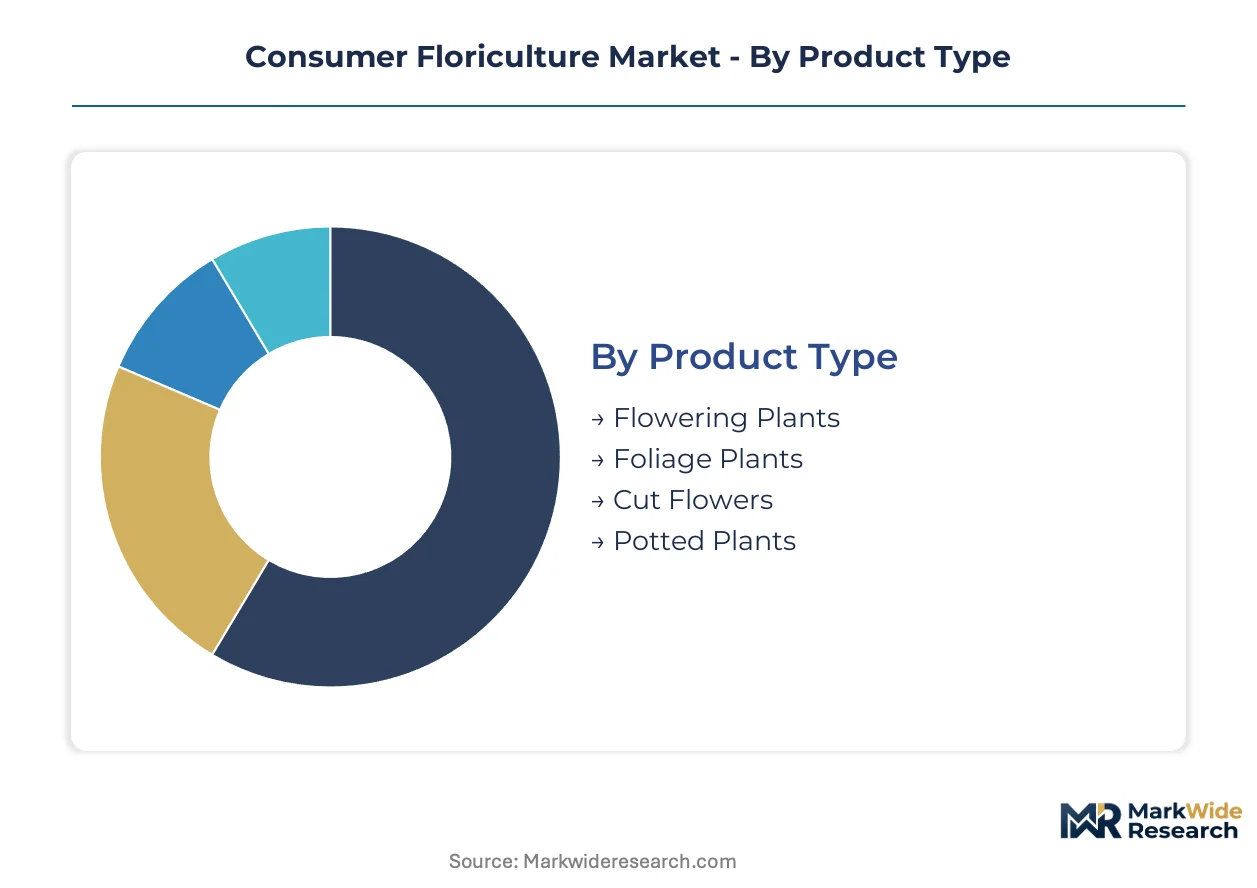
Segmentation in consumer floriculture reveals how perishability constraints and procurement channel evolution reshape margin capture. Product type determines logistics infrastructure requirements, while sales channel selection increasingly separates premium-certified supply from commodity auction flows.
Product Type:
Volume concentrates in high-turnover categories with established cold-chain infrastructure, while premium margin pools form around extended shelf-life segments that reduce spoilage risk.
- Cut Flowers:Harvested blooms with vase life duration measured in days and chilling sensitivity tracked in degree-hours. Demand concentrates in corporate event procurement across Germany and Netherlands, driven by REACH-compliant certification requirements that exclude non-verified origins.
- Potted Plants:Living specimens in soil media with extended retail shelf life and lower ethylene exposure vulnerability. Margin concentration is highest in this segment due to reduced logistics spoilage rates and subscription model compatibility through direct-to-consumer fulfillment networks.
- Flowering Plants:Ornamental species cultivated for bloom display, requiring controlled photoperiod management and temperature regimes.
- Foliage Plants:Non-flowering specimens valued for architectural form and air-quality properties, capturing interior design specification demand.
Today's leader: Cut Flowers. Tomorrow's challenger: Potted Plants.
End User:
Procurement authority is fragmenting across customer types, with institutional buyers embedding sustainability verification into supplier scorecards ahead of individual consumer preferences.
- Event Planners:Professional coordinators of ceremonial and corporate gatherings with centralized procurement policies. Sustainability certification requirements from EU Green Deal frameworks are redirecting their sourcing toward verified Dutch auction supply chains.
- Retailers:Brick-and-mortar and digital storefront operators managing inventory turnover velocity. Cold-chain logistics density around Aalsmeer enables same-day distribution velocity that peripheral origins cannot match.
- Individuals:Direct consumers purchasing for residential aesthetic enhancement or gifting occasions.
- Wholesale Distributors:Intermediary aggregators managing volume consolidation from multiple cultivation origins.
Event Planners are gaining procurement sophistication fastest. Individuals remain the volume foundation.
Sales Channel:
Channel selection now determines whether producers capture margin previously absorbed by wholesale auction intermediaries or remain trapped in commodity pricing dynamics.
- Online Stores:Digital platforms enabling subscription bouquet models and direct farm-to-consumer fulfillment. This channel is expanding most quickly as it bypasses traditional auction layers entirely and captures customer data for repeat purchase optimization.
- Garden Centers:Specialized retail environments with trained staff and controlled climate display infrastructure. Demand concentrates in Netherlands and Germany where consumer education on cultivar care supports premium pricing.
- Supermarkets:Mass-market retail with high foot traffic and impulse purchase placement.
- Farmers' Markets:Local producer-direct venues with freshness claims and regional provenance storytelling.
Online Stores are climbing the fastest. Garden Centers defend the premium position.
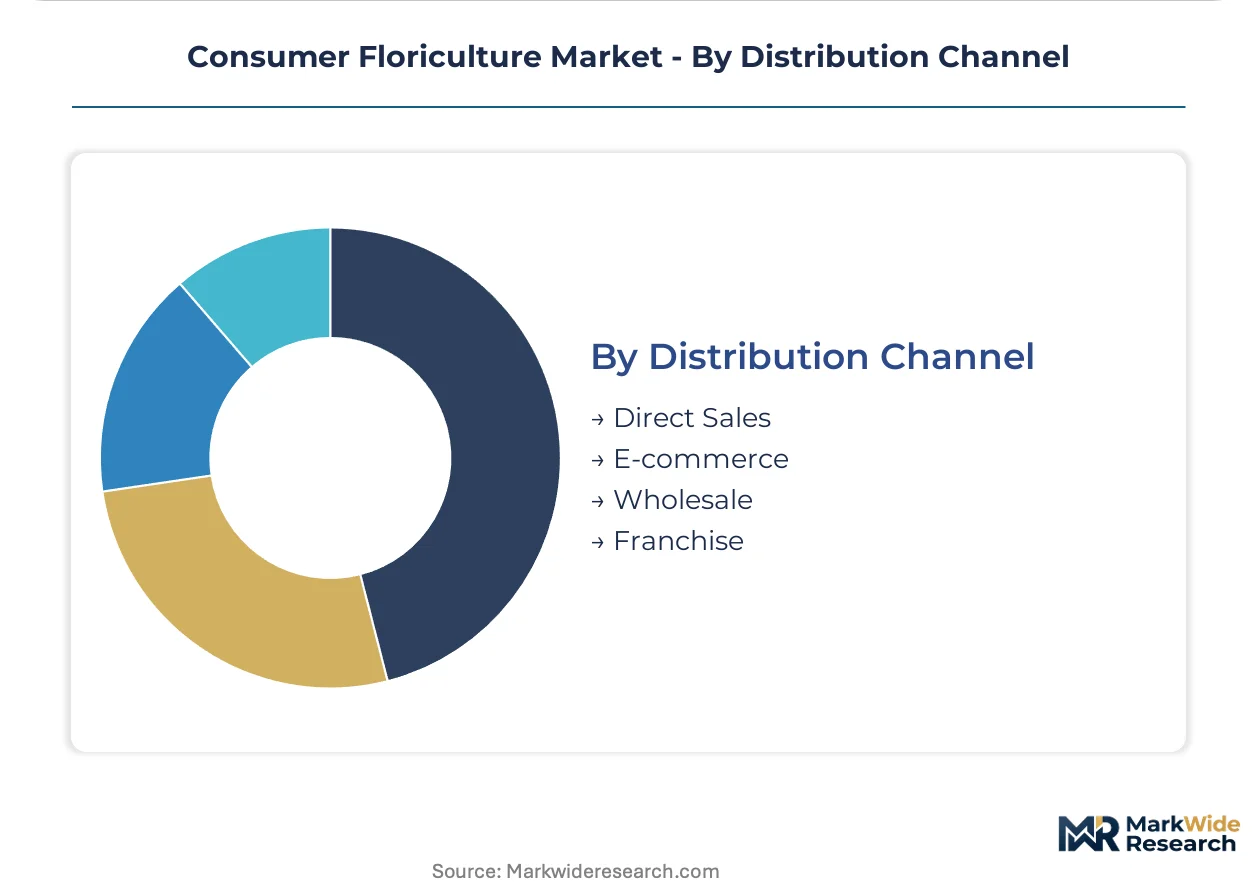
Distribution Channel:
Supply chain configuration determines exposure to phytosanitary compliance costs and carbon border adjustment risks under emerging EU frameworks.
- E-commerce:Digitally enabled fulfillment networks with integrated cold-chain tracking and last-mile temperature control. REACH documentation requirements and residue testing protocols favor certified producers with established compliance infrastructure.
- Direct Sales:Producer-to-buyer contracts eliminating intermediary margin extraction. Corporate procurement departments in Netherlands and Germany are expanding these arrangements for sustainably certified cut flowers.
- Wholesale:Auction-based volume aggregation centered on Aalsmeer infrastructure.
- Franchise:Licensed retail networks with standardized merchandising and supply protocols.
E-commerce holds the steepest expansion trajectory. Direct Sales offers the cleanest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands concentrates auction infrastructure and cold-chain density unmatched by Kenya's field-grown volume, while Germany's corporate procurement policies redirect regional sourcing patterns toward certified supply chains.
Netherlands
Aalsmeer's auction infrastructure processes daily volumes that peripheral origins cannot replicate, while corporate event planners in Amsterdam and Rotterdam expand certified cut flower procurement. REACH chemical frameworks govern cultivation inputs across Dutch greenhouse zones. The Randstad cluster integrates climate-controlled propagation with same-day distribution velocity to Germany and Belgium.
Germany
Corporate headquarters in Berlin and Frankfurt embed sustainability verification into supplier scorecards ahead of regulatory mandates, compressing competitive access for non-certified producers. EU Green Deal phytosanitary requirements reshape import pathways for floral products entering German retail channels. Bavaria's garden center density supports premium potted plant pricing through trained staff and controlled climate displays.
United States
Subscription bouquet models from California and Pacific Northwest fulfillment networks bypass traditional wholesale auction layers entirely. USDA and EPA pesticide residue regulations govern imports entering through Miami and Los Angeles cold-chain entry points. Washington Bulb anchors domestic lily supply through licensed propagator networks across the Pacific Northwest.
Kenya
Field-grown rose and summer flower volumes from Naivasha and Thika supply European auction demand, though EU Green Deal tightening elevates compliance documentation burdens. The country's national agricultural regulator coordinates with ECHA residue testing protocols that smaller exporters struggle to satisfy. Lake Naivasha's floriculture cluster faces water stewardship scrutiny under emerging carbon border adjustment frameworks.
Colombia
Bogotá's savanna plateau produces carnation and chrysanthemum volumes for North American event and gifting channels, leveraging equatorial photoperiod consistency. US EPA phytosanitary requirements for imports entering Miami International Airport intensify pathway compliance costs. Cundinamarca's greenhouse concentration integrates post-harvest ethylene management with direct-to-retailer contracts bypassing auction intermediaries.
Consumer Floriculture Market Competitive Landscape
Dutch breeder-producers anchor the premium genetics tier; Kenyan and Colombian field-grown specialists hold volume positions in auction supply chains. The market structures around three tiers: molecular breeding platforms with compressed cultivar development cycles, global propagation networks with distributed rooting stations, and regional greenhouse operators serving proximate retail channels. Competitive moves concentrate on proprietary genetics acquisition and direct-to-corporate procurement contracts that bypass wholesale auction layers.
Within the integrated breeding and propagation tier, Syngenta Flowers and Ball Horticultural exemplify contrasting geographic anchoring strategies. Syngenta Flowers occupies a position emphasizing molecular biology infrastructure for cultivar acceleration. Ball Horticultural sits within the North American distribution archetype, leveraging licensed propagator networks for regional supply security. Dümmen Orange represents the global rooting station model, reducing transit stress on unrooted cuttings through distributed propagation infrastructure.
| Leading Market Players |
|---|
| Dümmen Orange |
| Syngenta Flowers |
| Finlays |
| Beekenkamp |
| Karuturi |
| Oserian |
| Selecta One |
| Washington Bulb |
| Ball Horticultural |
| Others |
Pricing and Supply Chain Analysis
Molecular breeding specialists concentrated in the Netherlands and North America command wage premiums that compress margin spreads between premium-certified and standard-grade floral products. REACH compliance documentation burdens and cold-chain logistics density around Aalsmeer amplify cost differentials between verified sustainable supply chains and commodity auction flows.
Pricing Analysis
Capacity additions in Kenya and Colombia are reshaping price floors for standard-grade cut flowers entering European auction channels. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade levels separates Dutch greenhouse-origin products with full REACH traceability from field-grown African and South American volumes. Pricing pressure stems from EU Green Deal phytosanitary tightening that elevates residue testing costs for non-certified origins. Corporate event planners exhibit lowest price sensitivity due to sustainability scorecard mandates, while supermarket procurement teams drive hardest bargain on per-stem economics.
Supply Chain Analysis
Skilled propagator workforce availability in the Netherlands, Kenya, and Colombia determines rooting station placement and unrooted cutting transit protocols. Propagation draws from Dutch greenhouse clusters, Naivasha field-grown zones, and Bogotá savanna plateau concentrations. Input dependencies center on peat substrate, climate-controlled energy, and phytosanitary certification documentation. Single-source vulnerability concentrates in Aalsmeer auction infrastructure that processes daily volumes unmatched by peripheral alternatives. Distribution runs through direct-to-corporate contracts, e-commerce fulfillment networks, and traditional wholesale auction layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer floriculture market functions as a regulatory compounder where EU Green Deal phytosanitary milestones redirect procurement toward verified supply chains ahead of carbon border adjustment implementation.
For Market Incumbents: Hedge against REACH documentation burden escalation by deepening captive propagation infrastructure in Kenya and Colombia. Secure molecular breeding talent pools through acquisition of specialized genomics platforms before development cycle compression becomes table stakes. Prioritize direct-to-corporate procurement contracts that bypass Aalsmeer auction margin extraction. For New Entrants and Emerging Players: Launch via subscription bouquet models targeting German corporate headquarters with centralized sustainability procurement policies. Exploit white-space in potted plant direct-to-consumer fulfillment where extended shelf life reduces logistics spoilage risk. Penetrate through digital-native customer acquisition that captures repeat purchase data for cultivar optimization. For Investors and Strategic Acquirers: Breeder-producers with proprietary genetics and climate-controlled propagation infrastructure are the most active acquirer targets in this space. Long-term viability hinges on carbon border adjustment readiness and molecular breeding platform ownership. Watch for EU Green Deal enforcement intensity as inflection indicator for certified supply chain premium persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Genetics Acquisition | Molecular breeding platforms compress cultivar development cycles faster than conventional hybridization permits. |
| Direct-to-Corporate Contracting | Bypassing Aalsmeer auction layers captures margin previously absorbed by wholesale intermediaries. |
| Carbon Border Adjustment Preparation | Early REACH compliance documentation positions certified producers for preferential EU retail shelf access. |
| Global Rooting Station Expansion | Distributed propagation infrastructure reduces transit stress on unrooted cuttings across climatic zones. |
| Subscription Model Launch | Direct-to-consumer fulfillment networks capture customer data for repeat purchase optimization. |
Research Methodology
Direct dialogue with breeder-producer executives, auction house operations managers, corporate procurement officers, and cold-chain logistics specialists grounded qualitative findings in operational reality. Secondary validation drew from EU Green Deal regulatory filings, ECHA residue testing protocols, Dutch customs trade data, and SEC disclosures from listed horticultural firms. Bottom-up cultivar volume estimates and top-down auction throughput data were triangulated for segment sizing.
Segment-level value projections were generated across product type, end user, sales channel, and geographic origin dimensions throughout the forecast period. CAGRs were derived from historical auction volume trajectories and modeled penetration curves for subscription bouquet models. Key inputs included phytosanitary compliance cost escalation rates and corporate sustainability procurement policy adoption timelines.
Several conditions sit outside the modeled scope, including abrupt EU regulatory enforcement suspensions, natural gas price volatility impacts on Dutch greenhouse operations, and pandemic-scale logistics disruptions. Forecasts reflect assumptions about REACH framework stability and carbon border adjustment implementation sequencing. Material deviation in EU Green Deal phytosanitary tightening velocity or molecular breeding platform accessibility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Organic Feed Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Faba Beans Flour Market