
 Aerospace 3D Printing Consumables Market | 2026-2036
Aerospace 3D Printing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace 3D Printing Consumables Market Insights
Germany is reconfiguring European supply chain architecture for aerospace-grade metal powders through dedicated atomization facilities and research consortia. EOS GmbH leverages its Munich-centered laser sintering ecosystem to anchor premium powder qualification programs. Stratasys Ltd. competes across polymer extrusion platforms for cabin interior components, while Norsk Titanium AS specializes in plasma-deposition titanium wire for structural aeroframe elements.
Aerospace 3D printing consumables encompass feedstock materials engineered to precise chemical and morphological specifications for layer-by-layer fabrication of flight-critical components. Metal powders demand spherical particle morphology with tight size distribution, typically 15-45 microns for selective laser melting, to achieve fully dense microstructures in turbine blades and structural brackets. Photopolymers dominate prototyping workflows where dimensional accuracy and surface finish take priority over mechanical load-bearing capacity. Thermoplastic filaments, particularly PEI and PEEK grades, occupy aerospace interiors where flame-smoke-toxicity certification governs cabin material selection.
FAA airworthiness directives and EASA certification memoranda establish the regulatory perimeter for additively manufactured parts in commercial aviation, with both agencies expanding acceptable means of compliance for powder bed fusion processes. China's CAAC has issued parallel technical standards for domestic narrowbody programs, while ISO/ASTM 52900 series definitions harmonize terminology across jurisdictional boundaries. Stakeholders must track evolving qualification protocols for recycled powder reuse ratios, as regulatory acceptance of blended virgin-reclaimed feedstock will reshape unit economics and supplier competitive position.
Market Dynamics
FAA qualification protocols for powder bed fusion are compressing certification timelines for flight-critical titanium components, while aircraft engine OEMs accelerate substitution of subtractive machining with directed energy deposition for turbine blade repair.
Growth Catalysts
- Engine OEM Material Substitution:Pratt & Whitney and Rolls-Royce expand plasma-deposition titanium wire programs for blade restoration, displacing conventional forging and machining workflows.
- EASA Certification Memoranda:The European regulator's expanded acceptable means of compliance for laser powder bed fusion reduces qualification burden for structural brackets and pylon mounts.
- German Atomization Infrastructure:Dedicated gas atomization facilities in Bavaria and North Rhine-Westphalia concentrate premium nickel superalloy powder supply for regional aerospace clusters.
Market Restraints
- Virgin Powder Cost Volatility:Spherical titanium and nickel superalloy powders command 8-12x conventional billet pricing due to argon atomization energy intensity and yield losses.
- Chinese Supply Concentration:Over 60% of global plasma rotating electrode atomization capacity resides in Jiangsu and Shaanxi provinces, creating single-source vulnerability for aerospace-grade feedstock.
- Recertification Friction:FAA airworthiness directives require full requalification of blended virgin-reclaimed powder lots, blocking circular economy economics for high-value metal powders.
Strategic Opportunities
- Indian Narrowbody Programs:Hindustan Aeronautics and Tata Advanced Systems lack domestic qualified powder suppliers for regional jet engine components, creating first-mover entry for certified foreign feedstock vendors.
- Photopolymer Tooling Convergence:Digital light processing resins combined with ceramic investment casting enable rapid turbine blade core production without hard tooling lead times.
- CAAC Technical Standards:China's aviation regulator has issued parallel certification pathways for C919 and ARJ21 additively manufactured parts, opening qualified supplier access to state-owned airframe programs.
Industry Challenges
- Metallurgical Talent Scarcity:Powder characterization, process parameter development, and non-destructive evaluation for additively manufactured aerospace parts require specialized skill sets concentrated at German Fraunhofer institutes and US national laboratories.
- Multi-OEM Certification Burden:Each airframer and engine manufacturer maintains proprietary material specifications and build parameter sets, forcing feedstock suppliers to duplicate qualification campaigns for Boeing, Airbus, and COMAC supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace 3D Printing Consumables Market |
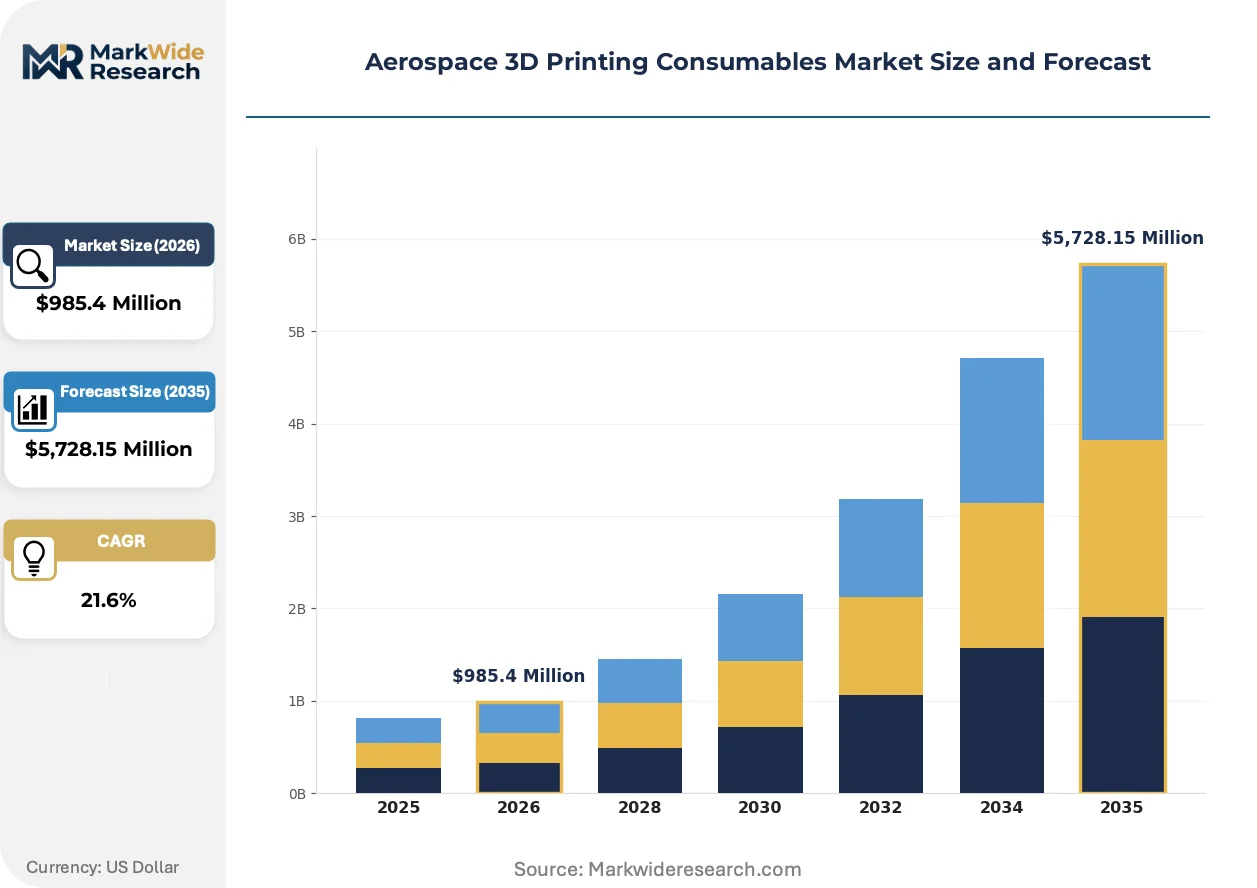
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $5,728.15 Million |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal Powders, Thermoplastic Filaments, Photopolymers, Ceramic Powders, Composite Filaments Printer Technology: Selective Laser Melting, Fused Deposition Modeling, Stereolithography, Electron Beam Melting, Binder Jetting Application: Prototype Manufacturing, Tooling Production, Structural Components, Engine Parts, Aerospace Interiors End User: Aircraft Manufacturers, Tier-1 Suppliers, Maintenance Providers, Research Institutes, Airlines |
| Companies Covered | Stratasys Ltd., 3D Systems Corporation, EOS GmbH, Höganäs AB, ExOne, EnvisionTec GmbH, Ultimaker B.V., Norsk Titanium AS, Materialise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace 3D Printing Consumables Market Trends and Innovations
Digital thread integration across powder production, build monitoring, and post-processing verification is collapsing quality assurance cycles for flight-critical components. Three developments are compressing the path from feedstock qualification to serial production.
Electron beam powder bed fusion is virtualizing the economics of titanium structural components for satellite and launch vehicle applications. SpaceX and Relativity Space deploy the technology for propellant tank domes and thrust chamber bodies where traditional machining waste ratios exceed 90%. The process is virtualizing supplier relationships by enabling direct digital transfer of build files without hard tooling intermediaries.
ISO/ASTM 52900 series harmonization is streamlining cross-border qualification of aerospace feedstock materials. The terminology standardization reduces friction for German powder suppliers seeking FAA approval and US vendors pursuing EASA certification. Asian aerospace programs in Japan and South Korea are adopting the framework verbatim, collapsing duplicate documentation requirements for multi-jurisdictional suppliers.
Airline maintenance divisions are consolidating powder procurement under airframe OEM managed service agreements. Lufthansa Technik and Delta TechOps now source titanium wire and nickel superalloy powder through Boeing and Airbus approved vendor lists rather than direct mill relationships. This channel compression is most advanced in European long-haul fleet operations where MRO providers lack metallurgical laboratories for independent feedstock verification.
Aerospace 3D Printing Consumables Market Segmentation
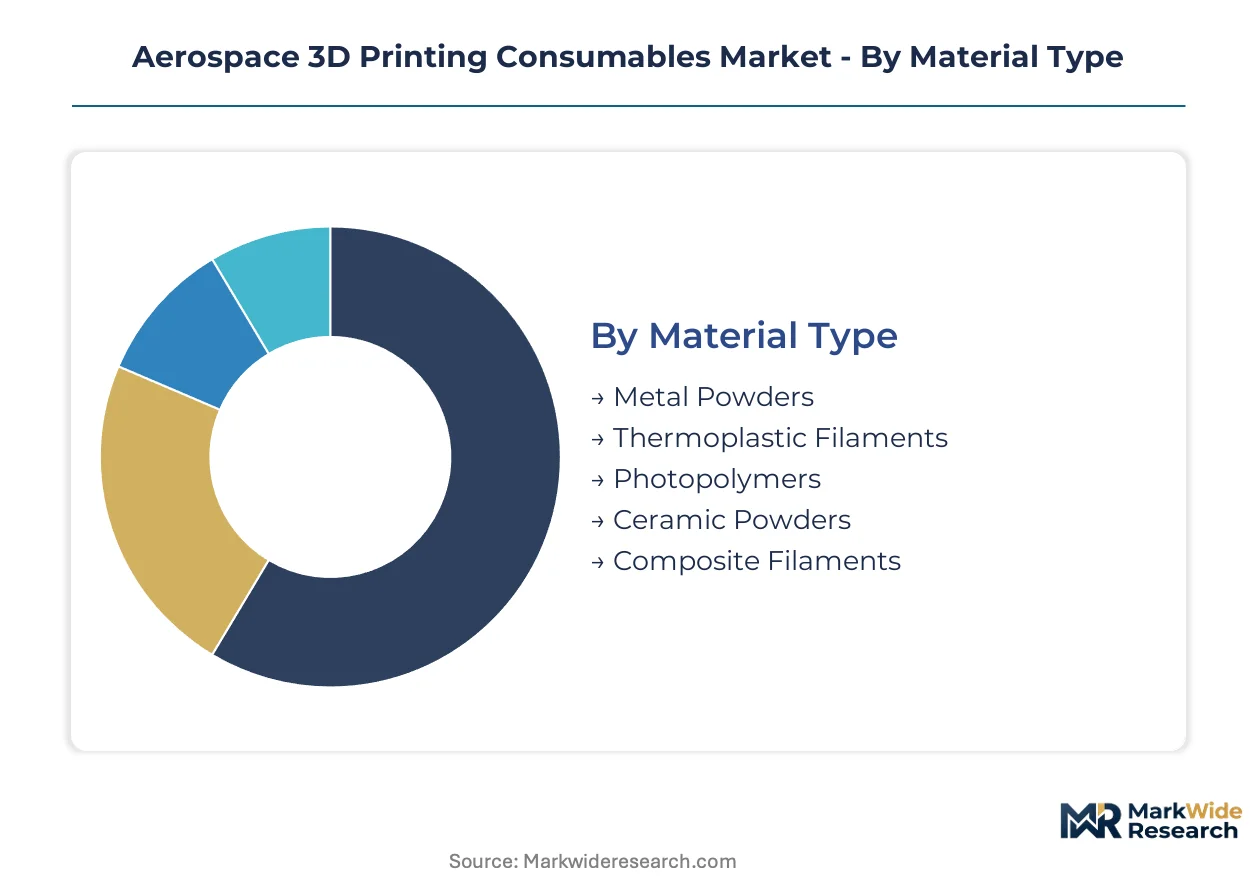
Feedstock differentiation in aerospace additive manufacturing follows certification boundaries rather than commodity chemistry. Each segment carries distinct qualification burdens and margin structures that determine supplier viability.
Material Type:
Cost tier stratification separates qualified aerospace feedstock from industrial-grade alternatives, with certification premiums widening the price spread.
- Metal Powders:Spherical titanium, nickel superalloy, and aluminum powders produced via argon or plasma rotating electrode atomization. Demand concentrates at Pratt & Whitney and Rolls-Royce repair facilities for turbine blade restoration, though FAA recertification requirements for reclaimed powder blending constrain circular economy adoption.
- Thermoplastic Filaments:PEI and PEEK grades certified to flame-smoke-toxicity standards for cabin interior components. Airbus and Boeing approved supplier lists dominate procurement, with Stratasys Ltd. and EOS GmbH anchoring filament qualification programs in Germany and the United States.
- Photopolymers:UV-curable resins for prototyping workflows where dimensional accuracy exceeds mechanical load requirements.
- Ceramic Powders:Oxide and non-oxide ceramics for investment casting cores and thermal barrier applications.
- Composite Filaments:Continuous fiber-reinforced polymers for non-structural brackets and ducting.
Metal powders hold installed capacity. Thermoplastic filaments are rotating up the share rankings.
Printer Technology:
Application requirements dictate technology selection, with flight-critical parts demanding energy-intensive fusion processes over deposition methods.
- Selective Laser Melting:Fiber laser-based powder bed fusion achieving fully dense microstructures in titanium and nickel superalloys. EOS GmbH and SLM Solutions anchor installed base in Germany, while GE Additive concentrates qualification expertise for turbine bracket serial production.
- Electron Beam Melting:Vacuum-based powder bed fusion utilizing electron beam energy input. SpaceX and Relativity Space deploy the technology for propellant tank domes where machining waste ratios exceed 90%, collapsing traditional supplier relationships through direct digital file transfer.
- Fused Deposition Modeling:Thermoplastic extrusion for non-flight-critical cabin components and prototyping.
- Stereolithography:Vat photopolymerization for high-resolution turbine blade core patterns.
- Binder Jetting:Powder bed process using liquid binding agents for sand cores and metal infiltration.
Selective laser melting commands qualification depth. Electron beam melting is climbing the fastest.
Application:
Volume concentration shifts from prototyping toward serial production as certification pathways mature for structural and propulsion applications.
- Engine Parts:Turbine blades, vanes, and combustion components produced via directed energy deposition and powder bed fusion. Pratt & Whitney's plasma-deposition titanium wire programs for blade restoration displace conventional forging in the United States, while Rolls-Royce expands laser powder bed fusion for fuel nozzles.
- Structural Components:Titanium brackets, pylon mounts, and aeroframe elements. Norsk Titanium AS specializes in plasma-deposition titanium wire for Boeing 787 structural parts, with FAA qualification protocols compressing certification timelines.
- Prototype Manufacturing:Form and fit validation models without flight certification requirements.
- Tooling Production:Conformal cooling channels and sacrificial patterns for investment casting.
- Aerospace Interiors:Seat frames, ducting, and galley components governed by flame-smoke-toxicity certification.
Engine parts dominate qualified volume. Structural components are gaining share fastest.
End User:
Procurement authority is consolidating under airframe OEM managed service agreements, compressing direct mill relationships.
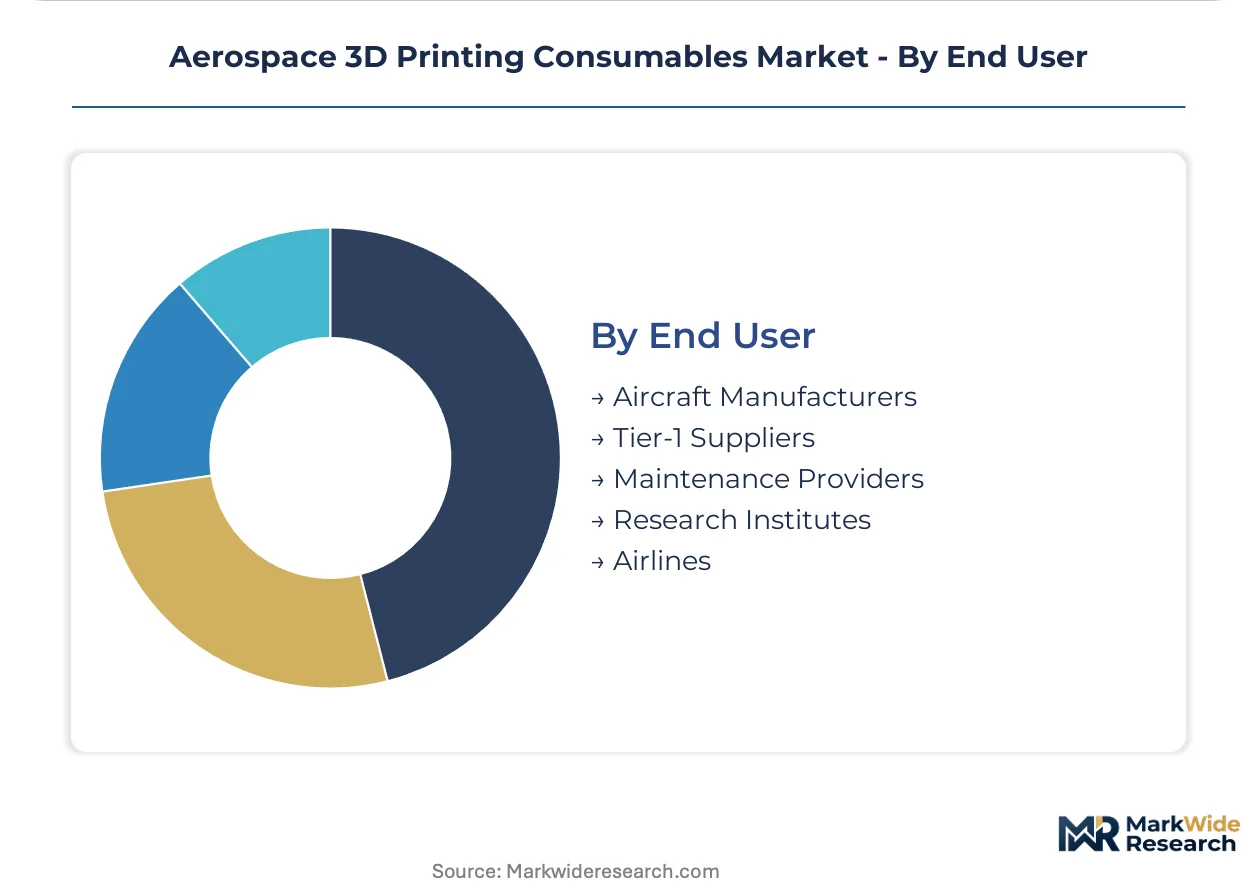
- Aircraft Manufacturers:Boeing, Airbus, and COMAC direct procurement for flight-critical structural and propulsion components. Boeing's approved vendor lists now govern titanium wire and nickel superalloy powder sourcing for supplier tiers, centralizing metallurgical qualification burden.
- Maintenance Providers:Lufthansa Technik and Delta TechOps source feedstock through OEM channels rather than direct powder mill relationships, lacking independent laboratory capacity for feedstock verification.
- Tier-1 Suppliers:Subcontracted component fabrication under OEM material specifications.
- Research Institutes:Fraunhofer institutes and US national laboratories anchor process parameter development.
- Airlines:Direct procurement limited to non-critical interior retrofits.
Aircraft manufacturers control specification authority. Maintenance providers are rotating up the procurement volume rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German atomization infrastructure and Chinese plasma rotating electrode capacity concentrate aerospace-grade metal powder supply, while FAA and EASA certification pathways determine market access in North America and Europe.
United States
Pratt & Whitney and GE Aviation drive titanium wire demand for turbine blade restoration and structural bracket serial production. FAA airworthiness directives compress qualification timelines for powder bed fusion components, expanding acceptable means of compliance. Texas and Connecticut aerospace clusters anchor plasma-deposition programs for directed energy deposition repair workflows.
Germany
EOS GmbH and SLM Solutions anchor selective laser melting installed base, while Bavarian gas atomization facilities concentrate nickel superalloy powder supply. EASA certification memoranda reduce qualification burden for laser powder bed fusion structural parts. Munich-centered research consortia coordinate premium powder qualification programs across regional aerospace tiers.
China
COMAC's C919 and ARJ21 programs generate qualified feedstock demand for additively manufactured airframe components. CAAC technical standards establish parallel certification pathways mirroring FAA and EASA frameworks. Jiangsu and Shaanxi provinces concentrate over sixty percent of global plasma rotating electrode atomization capacity, creating supply vulnerability.
United Kingdom
Rolls-Royce expands laser powder bed fusion for fuel nozzles and combustion components across Derby and Bristol engineering centers. UK national laboratories anchor process parameter development for nickel superalloy microstructures. Midlands aerospace cluster coordinates with German powder suppliers under ISO/ASTM 52900 harmonized terminology standards.
India
Hindustan Aeronautics and Tata Advanced Systems lack domestic qualified powder suppliers for regional jet engine programs. The country's national aviation regulator has not issued comprehensive additive manufacturing standards for flight-critical parts. Bangalore and Hyderabad defense-aerospace clusters currently import certified titanium and nickel superalloy feedstock from German and US vendors.
Aerospace 3D Printing Consumables Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and process development. The vendor base stratifies across laser sintering system providers, powder metallurgy suppliers, and directed energy deposition specialists. Three archetypes dominate: Munich-centered laser sintering ecosystems, Scandinavian plasma-deposition wire specialists, and US-based polymer extrusion platforms. Competitive moves concentrate on powder atomization capacity expansion and multi-OEM qualification campaign duplication.
Among German limited liability companies, EOS GmbH and EnvisionTec GmbH exemplify the precision system integration archetype, anchoring premium powder qualification programs within European aerospace clusters. Höganäs AB represents the powder metallurgy specialist tier, occupying a position upstream of build system vendors. Norsk Titanium AS exemplifies the directed energy deposition specialist model, with its corporate structure indicating Norwegian origin and focused positioning on titanium wire feedstock for structural aeroframe elements.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems Corporation |
| EOS GmbH |
| Höganäs AB |
| ExOne |
| EnvisionTec GmbH |
| Ultimaker B.V. |
| Norsk Titanium AS |
| Materialise |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in German gas atomization facilities drives supplier prioritization of long-term offtake contracts over spot market sales, compressing availability for smaller buyers while elevating pricing power for qualified powder producers serving FAA-certified airframe programs.
Pricing Analysis
FAA airworthiness directives dictate the pricing tier structure for aerospace-grade metal powders, separating qualified feedstock for flight-critical components from industrial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with virgin nickel superalloy powders commanding maximum premiums due to argon atomization energy intensity. Cost compression in standard-tier titanium wire is intensifying because Chinese plasma rotating electrode capacity expansion outpaces Western qualification timelines. Tier-1 engine OEMs exhibit lowest price sensitivity given captive supplier relationships, while Indian maintenance providers face acute cost pressure sourcing through Boeing and Airbus approved vendor lists.
Supply Chain Analysis
Export control regimes limiting plasma rotating electrode technology transfer constrain Western access to Chinese atomization capacity despite its concentration in Jiangsu and Shaanxi provinces. Aerospace-grade spherical titanium and nickel superalloy powders draw from argon feedstock, high-purity metal billets, and precision classification equipment. Single-source vulnerability pervades the supply architecture, as over sixty percent of global PREP capacity resides within Chinese provincial borders. Distribution runs through airframe OEM managed service agreements, with Lufthansa Technik and Delta TechOps sourcing exclusively via Boeing and Airbus approved vendor lists rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace 3D printing consumables represent a service-attach opportunity where powder lifecycle management and build-parameter optimization subscriptions expand faster than hardware sales, as airline maintenance divisions lack independent metallurgical laboratories for feedstock verification.
For Market Incumbents: Entrench position through backward integration into captive atomization capacity in Bavaria and North Rhine-Westphalia, securing premium nickel superalloy powder supply for regional aerospace clusters. Accelerate multi-OEM qualification campaign duplication to block emerging entrants from achieving Boeing, Airbus, and COMAC supplier status simultaneously. Certification investment in CAAC parallel pathways for C919 programs anchors long-term access to Chinese narrowbody demand. For New Entrants and Emerging Players: Indian domestic qualified powder supply gaps create immediate white-space opportunity for certified foreign feedstock vendors targeting Hindustan Aeronautics and Tata Advanced Systems. Photopolymer tooling convergence for turbine blade core production offers penetrable entry point without competing against entrenched metal powder qualifications. Go-to-market execution should emphasize digital light processing resin partnerships with regional investment casting foundries lacking hard tooling capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among powder lifecycle management providers serving maintenance provider networks under OEM managed service agreements. Long-term viability over the coming decade hinges on regulatory acceptance of recycled powder reuse ratios, which would collapse unit economics for virgin-only suppliers. Acquisition target archetype: German limited liability companies with Munich-centered laser sintering ecosystems and established EASA certification memoranda relationships. The signal to watch is FAA guidance on blended virgin-reclaimed powder lot qualification, which would unlock circular economy economics and reshape competitive position.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-OEM Qualification Campaign Duplication | Secures supplier status across Boeing, Airbus, and COMAC approved vendor lists simultaneously. |
| Backward Integration into Atomization Capacity | EOS GmbH and SLM Solutions anchor premium powder supply through Bavarian gas atomization facilities. |
| Digital Thread Integration Investment | Collapses quality assurance cycles for Pratt & Whitney and Rolls-Royce turbine blade serial production. |
| CAAC Certification Pathway Development | Opens qualified supplier access to COMAC C919 and ARJ21 state-owned airframe programs. |
| Powder Lifecycle Management Subscription Launch | Captures recurring revenue from Lufthansa Technik and Delta TechOps lacking independent laboratory capacity. |
Research Methodology
Cross-validation between primary interviews with powder metallurgy executives, FAA certification specialists, airline procurement managers, and MRO operations directors and secondary validation through EASA certification memoranda, CAAC technical standards, ISO/ASTM 52900 series documentation, and SEC filings from publicly traded additive manufacturing equipment vendors anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down aerospace production forecasts from airframe OEM disclosure patterns.
Calibration against historical qualification timeline compression and certification pathway expansion patterns shapes the analytical framework across the analysis window. Segmentation dimensions include material type certification tier, printer technology energy input method, application flight-criticality level, and end-user procurement authority concentration. CAGRs derive from installed base expansion rates, powder consumption per qualified part, and regulatory acceptance velocity for recycled feedstock reuse.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-sponsored atomization capacity builders or sudden FAA relaxation of reclaimed powder blending requirements would shift outcomes. Material shifts in EASA or CAAC regulatory alignment with FAA airworthiness directive frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Beryllium Aluminum Alloy Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market