
 Automotive Blind Spot Detection (BSD) System Market | 2026-2036
Automotive Blind Spot Detection (BSD) System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Blind Spot Detection (BSD) System Market Intelligence
The European Union's Vision Zero initiative, aimed at eliminating road fatalities, is realigning OEM priorities toward standardizing advanced safety features. Robert Bosch GmbH leverages its extensive portfolio in sensor technology and software to serve this demand. Continental AG competes through its expertise in sensor fusion for complex ADAS applications. Valeo SA specializes in ultrasonic and camera-based systems, targeting cost-sensitive vehicle segments across multiple geographies.
Automotive Blind Spot Detection systems are a type of Advanced Driver-Assistance System (ADAS) that warns drivers of vehicles in their adjacent blind spots. These systems typically utilize 24 GHz or 77 GHz radar sensors to monitor areas not visible in mirrors. Radar-based systems dominate the product landscape due to their performance reliability in adverse weather and lighting conditions. The passenger vehicles application segment constitutes the largest area of deployment, with rapid expansion now occurring in commercial vehicles.
Regulatory frameworks from the U.S. National Highway Traffic Safety Administration (NHTSA) and the United Nations Economic Commission for Europe (UNECE) are key demand catalysts. In China, Ministry of Industry and Information Technology (MIIT) standards for intelligent vehicles also drive adoption. These regulations accelerate the transition of BSD from an optional feature to a standard safety requirement. The critical decision for suppliers involves balancing system performance with cost to meet mandates across diverse vehicle classes.
Market Dynamics
The primary force shaping the market is the regulatory transition of ADAS features from luxury options to standard equipment. Mandates from bodies like the UNECE and NHTSA compel automakers to integrate systems like BSD across all vehicle segments, making it a foundational safety technology.
Growth Catalysts
- Regulatory Mandates:UNECE vehicle safety provisions and similar frameworks in China are making ADAS features, including BSD, standard fitment, accelerating market penetration beyond premium vehicles.
- Commercial Vehicle Safety:Demand for BSD systems is expanding rapidly in the heavy commercial vehicle segment to reduce accidents involving large trucks and vulnerable road users.
- Sensor Technology Advancement:The maturation of 77 GHz radar provides superior range, resolution, and performance in adverse weather, driving its adoption over older 24 GHz systems.
Market Restraints
- System Cost:The bill-of-materials for high-performance radar and camera sensors remains a significant cost factor, challenging implementation in budget-conscious, entry-level vehicle models.
- False Alert Potential:In dense urban environments with complex traffic patterns, BSD systems can generate false positives, which can erode driver trust and lead to system deactivation.
- Integration Complexity:Harmonizing BSD sensor hardware and software with the diverse electronic architectures and CAN bus protocols of different automotive OEMs presents a significant engineering hurdle.
Strategic Opportunities
- Motorcycle Applications:The two-wheeler segment remains a largely untapped market where compact, low-power BSD systems can dramatically improve rider safety and prevent common lane-change accidents.
- Sensor Fusion with V2X:Integrating BSD radar data with Vehicle-to-Everything (V2X) communication allows for predictive warnings about non-line-of-sight threats, creating a new performance tier.
- Emerging Market Adoption:Safety-conscious consumers and nascent regulatory initiatives in markets like India and Brazil create new growth avenues for cost-optimized BSD solutions.
Industry Challenges
- Software Validation Burden:Verifying and validating the millions of lines of code in ADAS software to ensure functional safety and prevent system failures is a time-consuming and expensive process.
- Cybersecurity Vulnerabilities:As vehicles become more connected, securing BSD systems and their communication channels from remote hacking and data manipulation is a critical operational concern for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Blind Spot Detection (BSD) System Market |
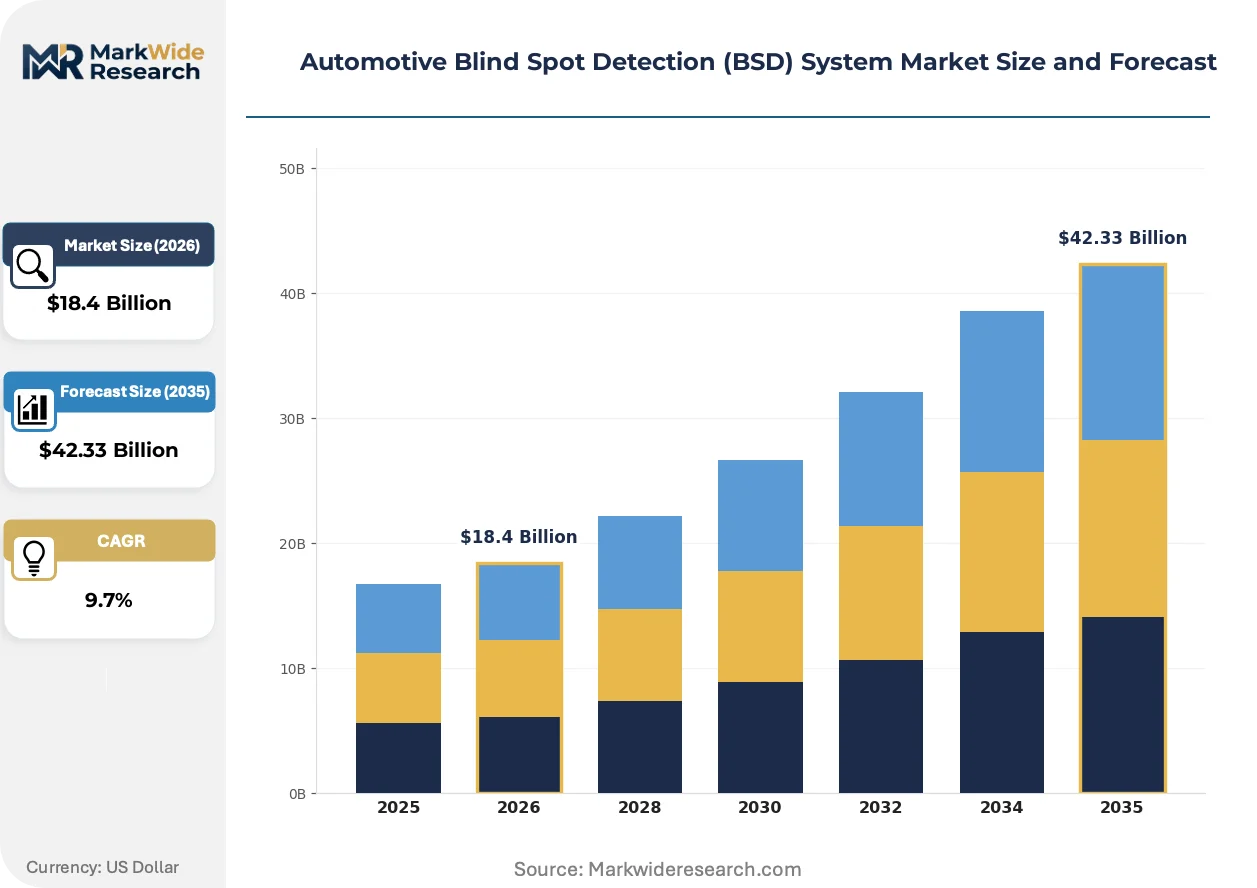
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $42.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar-Based, Camera-Based, Ultrasonic-Based, Infrared-Based, Lidar-Based Technology: Machine Learning, Sensor Fusion, Signal Processing, Adaptive Algorithms, Real-Time Detection Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles, Heavy Equipment End User: OEMs, Tier-1 Suppliers, Automotive Dealerships, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Valeo SA, Infineon Technologies AG, Continental AG, Aptiv, Autoliv Inc., Robert Bosch GmbH, NXP Semiconductors, ZF Friedrichshafen AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Blind Spot Detection (BSD) System Market Strategic Shifts & Innovations
The evolution of blind spot detection is defined by its integration into a vehicle's broader sensorium. Systems are moving beyond simple alerts toward becoming integral components of a centralized driver-assist computational domain, enhancing overall vehicle intelligence and situational awareness.
In-cabin driver monitoring systems use radar or cameras to track driver alertness and head position. This technology is seeing rapid uptake in new premium and mid-range passenger car models. This driver-state data is converging with external BSD sensor inputs to enable more context-aware alerts, reducing alarm fatigue and improving response effectiveness.
New UNECE regulations for cybersecurity (UN R155) and software updates (UN R156) establish a new baseline for vehicle type approval. These rules compel manufacturers to implement and document comprehensive cybersecurity management systems across the entire supply chain. The ADAS software stack, including BSD algorithms, is directly impacted, necessitating secure-by-design development processes.
A transition toward software-defined vehicles is altering the monetization of safety features. Instead of being a fixed hardware option at purchase, automakers are starting to offer BSD functionality through over-the-air (OTA) updates or as part of subscription packages. This model is most prominent within the premium electric vehicle segment in Europe and North America.
Automotive Blind Spot Detection (BSD) System Market Segmentation
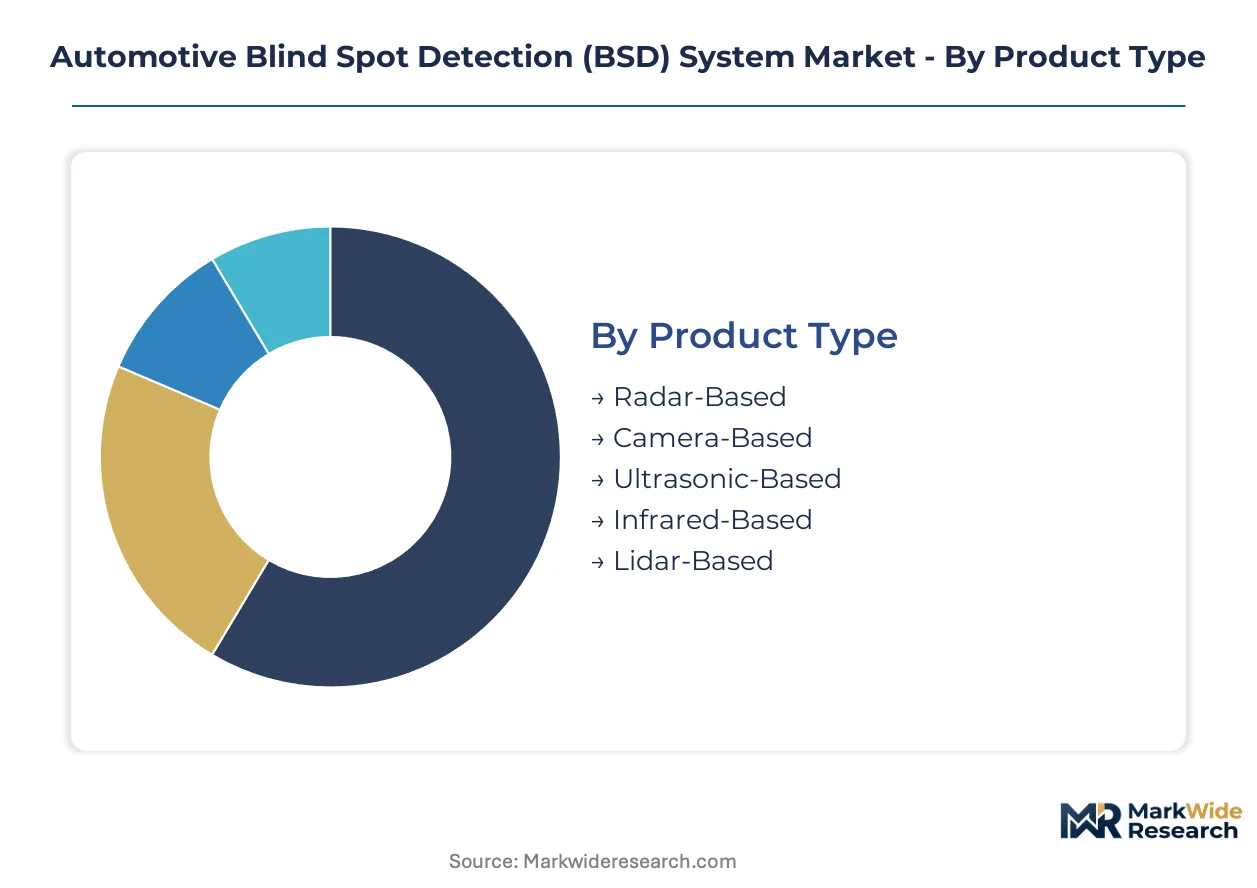
The Automotive Blind Spot Detection (BSD) System Market segmentation provides a granular view of how technology, product types, applications, and end-users influence market dynamics. Understanding these distinct segments reveals specific adoption patterns, strategic opportunities, and areas of concentrated growth for BSD system providers.
Product Type:
The product type segmentation differentiates between high-volume, cost-effective solutions and premium, performance-driven systems, reflecting varied OEM requirements.
- Radar-Based:Utilizes 24 GHz or 77 GHz electromagnetic waves to detect objects and measure their speed and distance, offering high reliability in adverse weather. Demand concentrates in passenger vehicles, driven by regulatory mandates from UNECE for standard safety features.
- Lidar-Based:Employs pulsed laser light to measure distances to objects, creating highly detailed 3D maps of the vehicle's surroundings for precise environmental perception. Adoption is gaining traction in premium electric vehicles, where its superior capabilities support advanced ADAS functions.
- Camera-Based:Relies on visual data processing to identify vehicles and objects in blind spots, often integrated with other vision systems.
- Ultrasonic-Based:Uses sound waves for short-range detection, typically integrated into parking assist systems due to its limited range.
- Infrared-Based:Detects thermal signatures of objects, offering capabilities in low-light conditions but with resolution limitations.
Today's leader: Radar-Based. Tomorrow's challenger: Lidar-Based.
Technology:
Technology advancements enable higher accuracy and lower latency, directly impacting system reliability and driver trust.
- Sensor Fusion:Integrates inputs from diverse sensors (e.g., radar, camera, lidar) to overcome individual sensor limitations, enhancing object detection and tracking. Critical for advanced ADAS systems in commercial vehicles, where robust performance across varied conditions is paramount.
- Machine Learning:Employs neural networks and other AI techniques to process sensor data, identifying objects and predicting their trajectories with high precision. Primarily used in next-generation BSD systems for passenger vehicles, aiming to enhance contextual awareness and reduce driver distraction.
- Signal Processing:Refines raw sensor data to filter noise and extract relevant information for object identification and classification.
- Adaptive Algorithms:Adjust system parameters dynamically based on driving conditions and environmental factors, improving system responsiveness.
- Real-Time Detection:Ensures immediate processing of sensor data and warning generation, crucial for preventing accidents.
The fastest-growing trajectory resides within Sensor Fusion, driven by the increasing complexity of ADAS requirements.
Application:
The application segments delineate the diverse vehicle types benefiting from enhanced blind spot awareness, each with unique integration challenges.
- Passenger Vehicles:BSD systems are embedded during vehicle manufacturing, often communicating with other ADAS components via CAN bus. Growth is concentrated in China and Europe, propelled by government initiatives and stringent safety regulations.
- Commercial Vehicles:Systems are designed to cover larger blind zones and withstand harsher operating environments compared to passenger car systems. Expanding rapidly in Europe due to new UNECE regulations requiring advanced safety features for heavy goods vehicles.
- Two-Wheelers:Includes motorcycles and scooters, where compact BSD solutions enhance rider safety during lane changes.
- Off-Road Vehicles:Integrates BSD for improved situational awareness in demanding terrains and low-visibility conditions.
- Heavy Equipment:Applies BSD to construction and mining machinery, preventing collisions in complex work sites.
Market expansion is primarily driven by Passenger Vehicles, with Commercial Vehicles showing significant latent potential.
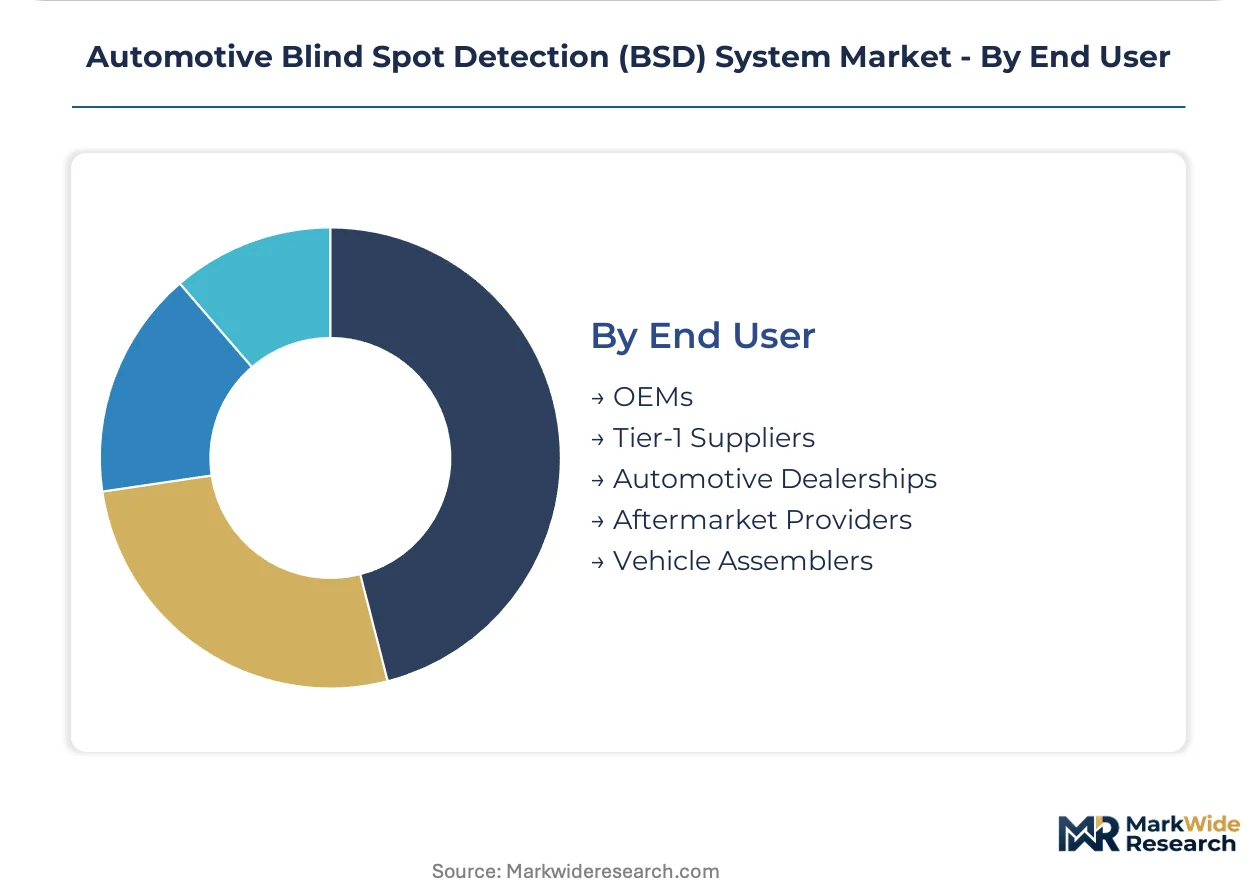
End User:
End-user segments reflect the value chain for BSD systems, from initial integration to consumer access.
- OEMs (Original Equipment Manufacturers):OEMs specify sensor types, software algorithms, and integration points, ensuring seamless operation with other vehicle electronics. Driven by regulatory compliance and consumer safety expectations, particularly in established markets like Germany and Japan.
- Tier-1 Suppliers:These suppliers focus on sensor development, ECU design, and software integration, often managing complex supply chains. Concentrated in regions with strong automotive manufacturing bases, such as Germany and China, supplying major global automakers.
- Automotive Dealerships:Offer optional BSD installations or upgrades for new and used vehicles as a value-added service.
- Aftermarket Providers:Supply standalone or integrated BSD solutions for installation post-purchase, catering to existing vehicle owners.
- Vehicle Assemblers:Install pre-fabricated BSD modules as part of the final vehicle assembly process under OEM direction.
The dominant channel for volume is OEMs, while Aftermarket Providers capture specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive industry's foundational engineering, particularly in Germany and Japan, established early frameworks for advanced vehicle systems. These regions initially drove the development of sophisticated components now integral to blind spot detection. Global regulatory bodies subsequently expanded the adoption of these safety technologies worldwide.
China
China's rapid embrace of intelligent connected vehicles fuels demand for BSD systems in passenger vehicles. MIIT standards for advanced driver-assistance features accelerate their integration into domestic automotive production. The Yangtze River Delta region, including Shanghai, drives significant manufacturing and innovation for these integrated vehicle safety solutions.
Germany
German OEMs prioritize advanced safety features, standardizing BSD systems across their vehicle lineups. UNECE vehicle safety provisions compel manufacturers to integrate these technologies into all new models. Bavaria, a hub for automotive engineering, concentrates R&D efforts on next-generation ADAS and sensor fusion technologies.
United States
The United States market experiences demand for BSD systems driven by NHTSA safety mandates and consumer preferences for advanced vehicle protection. NHTSA's safety ratings heavily influence automakers' decisions to include these features as standard. Detroit, the heart of the American automotive industry, continues to develop and integrate ADAS solutions into mass-market vehicles.
Japan
Japanese automakers consistently integrate advanced safety technologies, enhancing vehicle intelligence and driver assistance. JIS standards for automotive components and safety systems guide the development and deployment of robust BSD solutions. The Tokyo metropolitan area, a center for automotive R&D, leads innovation in compact and high-performance sensor technologies.
India
India represents a growing market for BSD systems, with increasing consumer awareness of vehicle safety features. BIS automotive standards are gradually incorporating advanced safety requirements for new vehicle models. Chennai, a prominent automotive manufacturing hub, attracts investment in localizing ADAS production and supply chains.
Automotive Blind Spot Detection (BSD) System Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the Automotive Blind Spot Detection market. Established automotive suppliers, often vertically integrated, face challenges from specialized software and sensor developers. The market structure exhibits a tiered consolidation, with a few dominant players providing comprehensive ADAS platforms. Strategic partnerships and technology licensing are prevalent competitive moves, alongside continuous portfolio diversification to cover various vehicle segments.
On the premium-tier vector, Robert Bosch GmbH, a German-based GmbH, exemplifies a vertically integrated automotive supplier leveraging extensive sensor technology and software. Continental AG, another German AG, occupies a similar position, specializing in sensor fusion for complex ADAS applications and broader vehicle safety systems. Valeo SA, a French SA, sits within the established supplier archetype, focusing on cost-sensitive ultrasonic and camera-based systems to meet diverse vehicle segment requirements across multiple geographies. These entities anchor the market by providing comprehensive solutions to global OEMs.
| Leading Market Players |
|---|
| Valeo SA |
| Infineon Technologies AG |
| Continental AG |
| Aptiv |
| Autoliv Inc. |
| Robert Bosch GmbH |
| NXP Semiconductors |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
The maturation of 77 GHz radar technology is reshaping both cost economics and the supply concentration for high-performance BSD systems. This transition drives demand for specialized semiconductor components and advanced manufacturing processes.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model for OEM-integrated BSD systems. Pricing stratifies across premium, standard, and economy tiers based on sensor performance and certification levels, such as UNECE compliance. Pricing pressure stems from OEM demands for cost optimization as BSD becomes standard equipment. Entry-level passenger vehicle segments exhibit the highest price sensitivity, while premium electric vehicles and commercial vehicle applications prioritize performance over absolute cost.
Supply Chain Analysis
Regional distribution centers support a hub-and-spoke model for delivering BSD components to automotive assembly plants worldwide. Supply concentration for critical components, like 77 GHz radar chips and specialized ASICs, centers in Germany, China, and Japan. The market relies on a few key semiconductor manufacturers, creating a single-source vulnerability for advanced radar sensors. Downstream distribution primarily involves direct integration into OEM vehicle production lines, complemented by aftermarket channels for system upgrades and older vehicle fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BSD market represents a late-cycle quality narrative, shifting from optional features to mandated safety systems. Regulatory pressure from UNECE frameworks drives a demand-shift toward premium specifications and robust performance across all vehicle segments.
For Market Incumbents: Hedge against margin pressure by deepening vertical integration into proprietary sensor manufacturing and ASIC design. Consolidate software validation efforts to meet stringent functional safety standards for ADAS, countering the threat from agile software-defined vehicle architectures. Invest in advanced sensor fusion R&D to maintain performance leadership against emerging entrants. Secure long-term supply agreements for critical semiconductor components.
For New Entrants and Emerging Players: Online marketplaces for aftermarket solutions provide a direct digital-channel route to safety-conscious consumers. Target the underpenetrated two-wheeler segment with compact, low-power BSD systems designed for motorcycle applications. Develop cost-optimized solutions for nascent regulatory initiatives in emerging markets like India and Brazil. Form strategic partnerships with ride-sharing platforms to integrate safety features into their fleets, offering a new go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light software developers specializing in ADAS algorithms and cybersecurity for connected vehicles. The market demonstrates strong long-term viability over a five-to-ten-year window, driven by persistent regulatory tailwinds and safety mandates. Target specialized software developers with proven expertise in sensor fusion and machine learning for next-generation BSD systems. The signal to watch is the increasing adoption rate of V2X integration with BSD data, indicating a new performance tier.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces OEM integration complexity and accelerates market penetration across diverse vehicle models. |
| Software-Defined Vehicle Investment | Enables over-the-air updates for BSD functionality, creating new monetization streams for automakers. |
| Sensor Fusion Algorithm Development | Enhances detection accuracy and reduces false positives, improving driver trust in ADAS systems. |
| Cybersecurity Framework Implementation | Protects BSD systems from remote hacking, ensuring functional safety and regulatory compliance. |
| Compact Radar Module Miniaturization | Opens new application segments, particularly for two-wheelers and space-constrained vehicle designs. |
Research Approach
Bottom-up passenger vehicle modeling reconciled against top-down sensor component tracking forms the analytical core for this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, ADAS software developers, and automotive safety regulators provided qualitative insights. Secondary validation drew from NHTSA safety ratings, UNECE vehicle safety provisions, MIIT intelligent vehicle standards, and IHS Markit registration data. This approach ensures robust triangulation of market dynamics.
An input-output matrix frames the quantitative forecast across the analysis window, integrating various market forces. Segmentation dimensions modeled include product type, technology, application (vehicle class), end-user, and regional regulatory cluster. Compound Annual Growth Rates were derived via regression analysis of historical trends and projected adoption rates. Key industry-specific forecast inputs included vehicle production volumes and ADAS feature penetration rates.
The model assumes a particular technology adoption path; alternative pathways for lidar integration or V2X communication would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer acceptance, but unforeseen geopolitical shifts or rapid advancements in alternative sensor technologies represent risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market