
 Ocean Freight Software Market | 2026-2036
Ocean Freight Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ocean Freight Software Market Insights
The EU Green Deal's maritime emissions targets is expanding compliance requirements for ocean carriers operating into European ports. WiseTech leverages extensive customs and compliance functionality to anchor its position across Asia-Pacific trade lanes. Descartes Systems Group sustains its network effect through multimodal connectivity and customs brokerage integration. CargoWise competes aggressively on single-platform architecture for large forwarders managing complex origin-destination pairs.
Ocean freight software encompasses digital platforms that automate rate management, booking execution, vessel tracking, and documentation workflows across containerized shipping operations. These systems typically integrate EDI messaging, AIS vessel feeds, and customs filing protocols to synchronize cargo movement across port authorities, carriers, and customs agencies. Freight Management solutions dominate current revenue as shipping lines consolidate fragmented point solutions into unified operating platforms. Booking Systems represent the fastest-expanding category as real-time capacity allocation replaces manual space commitments and email-based confirmations. Cloud-based deployment captures the majority of new implementations, though hybrid architectures persist among carriers with legacy terminal operating system dependencies.
The International Maritime Organization enforces carbon intensity indicators that compel carriers to document and optimize voyage efficiency, directly stimulating demand for analytics-enabled freight software. The EU's F-Gas Regulation and CSRD reporting requirements extend compliance obligations to refrigerated container operations and supply chain emissions disclosure, tightening software specification standards. Stakeholders must evaluate whether their current platforms can ingest emerging regulatory data streams without custom integration overhead.
Market Dynamics
Carbon intensity tracking mandates from the International Maritime Organization are forcing container carriers to replace fragmented operational tools with unified analytics platforms that capture voyage efficiency data across fleet networks.
Growth Catalysts
- IMO 2023 Carbon Intensity Regulations:Container shipping lines must document fuel consumption and voyage optimization metrics, creating mandatory procurement of emissions-tracking modules within freight management suites.
- Freight Forwarder Consolidation:Large logistics providers operating Asia-Europe trade lanes are retiring point solutions in favor of single-platform architectures that unify booking, documentation, and customs workflows.
- Port Authority Digitalization:Rotterdam, Singapore, and Shanghai port authorities are mandating API-first data exchange protocols, accelerating cloud platform adoption among terminal operators and carriers.
Market Restraints
- Legacy System Interdependence:Major carriers maintain hybrid architectures due to captive terminal operating systems at owned port facilities, slowing full-cloud migration timelines.
- Data Standardization Fragmentation:Competing EDI formats between ocean carriers, freight forwarders, and customs agencies impose persistent integration costs on platform vendors and users.
- Cybersecurity Compliance Burden:EU NIS2 Directive and national maritime security frameworks impose escalating certification requirements for software handling vessel routing and cargo manifest data.
Strategic Opportunities
- Reefer Container Analytics:EU F-Gas Regulation compliance creates white space for platforms integrating refrigerated container monitoring with emissions reporting and predictive maintenance algorithms.
- India Trade Lane Expansion:DGFT digitization initiatives and port automation at JNPT and Mundra are opening procurement windows for cloud-based freight management among mid-tier forwarders.
- Blockchain-EDI Convergence:Distributed ledger verification of bill-of-lading documents is creating partnership opportunities between established software vendors and maritime blockchain consortia.
Industry Challenges
- Maritime-AI Talent Scarcity:Shortage of data engineers with combined vessel operations and machine learning expertise is constraining predictive analytics deployment at mid-size carriers.
- Multi-Modal Integration Complexity:Forwarders require seamless handoffs between ocean, rail, and truck segments, but rail operators in North America and Europe maintain proprietary data protocols that resist standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocean Freight Software Market |
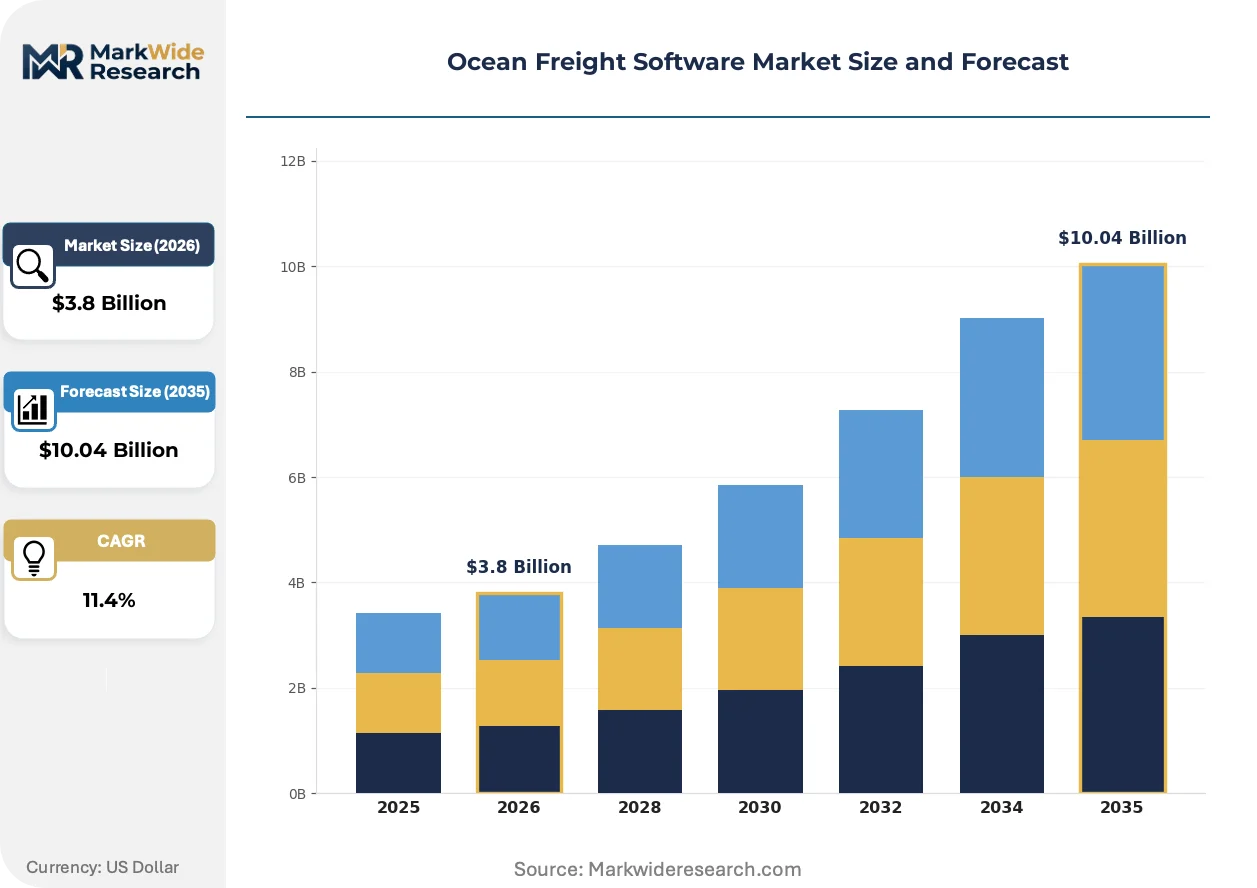
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Freight Management, Booking Systems, Tracking Solutions, Analytics Tools End User: Shipping Companies, Freight Forwarders, Importers, Exporters Deployment Model: Cloud-based, On-premises, Hybrid, SaaS Functionality: Inventory Management, Document Management, Cost Calculation, Compliance Management |
| Companies Covered | WiseTech, Descartes Systems Group, Magaya Corporation, Oracle, Riege Software, Mercurygate, Aljex Software, Navis, CargoWise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocean Freight Software Market Trends and Innovations
Real-time capacity visibility tools are compressing booking cycle times from days to hours, while regulatory disclosure requirements are embedding compliance functionality deeper into core platform architectures.
Artificial intelligence-driven voyage optimization is consolidating carrier procurement around predictive routing engines that integrate weather data, fuel pricing, and port congestion signals. Large container lines operating trans-Pacific strings are deploying these tools to automate slow-steaming decisions and berth window negotiations. The technology is consolidating competitive advantage around carriers with sufficient data infrastructure to train proprietary models.
EU CSRD reporting obligations are extending supply chain emissions disclosure to beneficial cargo owners, forcing freight software platforms to capture and format Scope 3 maritime transport data for corporate sustainability filings. Container lines serving European importers are prioritizing software vendors with pre-built CSRD reporting templates. The regulation is reshaping procurement criteria among forwarders managing retail and automotive supply chains into Rotterdam and Hamburg.
Subscription-based platform pricing is displacing perpetual license models among mid-market freight forwarders seeking to align software costs with shipment volume volatility. Buyers in Southeast Asia and Latin America are prioritizing vendors offering usage-based tiers over upfront capital commitments. The shift is most visible among forwarders operating emerging market trade lanes where cargo volumes fluctuate seasonally.
Ocean Freight Software Market Segmentation
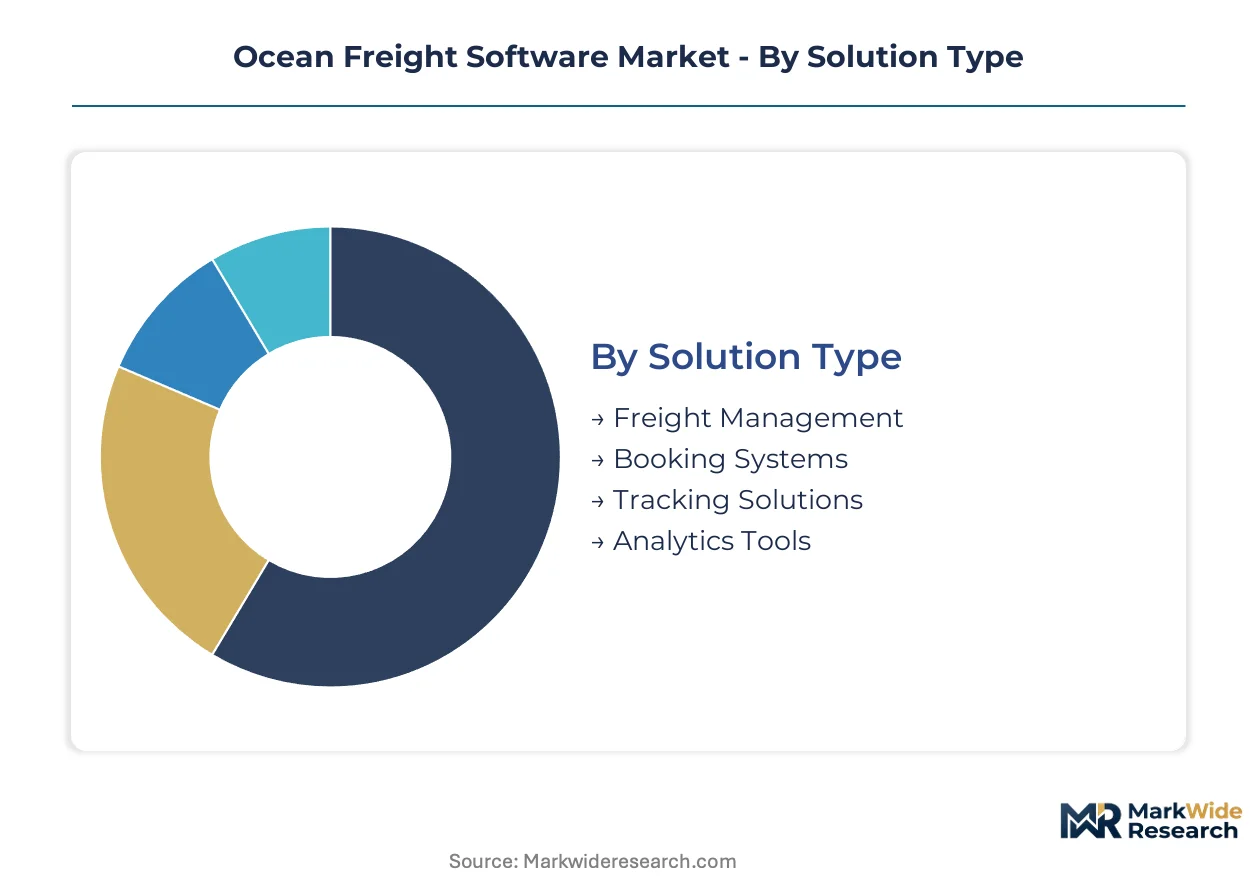
Segmentation in ocean freight software reveals how procurement priorities diverge between integrated carriers seeking unified platforms and specialized forwarders demanding modular capabilities. Understanding these divides clarifies where vendors must embed compliance functionality versus where standalone tools retain viability.
Solution Type:
Standalone booking modules serve fragmented forwarder networks, while freight management suites embed deeply into carrier ERP architectures through API-first integration layers.
- Freight Management:Unified platforms consolidate rate management, documentation workflows, and customs filing into single operating environments. Demand concentrates among Asia-Europe trade lane operators facing IMO 2023 carbon intensity documentation mandates. Large forwarders in Rotterdam and Hamburg prioritize vendors with pre-built CSRD reporting templates.
- Booking Systems:Real-time capacity allocation tools replace email-based space commitments with automated confirmations against carrier APIs. Mid-tier forwarders across India trade lanes drive procurement as DGFT digitization accelerates port automation at JNPT and Mundra. Subscription pricing models displace perpetual licenses in this segment.
- Tracking Solutions:AIS vessel feed integration and milestone automation for cargo visibility.
- Analytics Tools:Predictive routing engines combining weather data, fuel pricing, and port congestion signals.
Volume placements concentrate in Freight Management; the faster expansion belongs to Booking Systems.
End User:
Procurement scale and integration complexity vary sharply across user types, with carriers demanding fleet-wide standardization while traders prioritize trade-lane-specific flexibility.
- Shipping Companies:Container lines require voyage optimization modules that capture fuel consumption metrics across fleet networks for IMO compliance. These buyers favor vendors with proprietary machine learning infrastructure to train slow-steaming decision models. Trans-Pacific string operators anchor demand for predictive routing capabilities.
- Freight Forwarders:Logistics providers managing multi-modal handoffs need seamless ocean-rail-truck data synchronization. European forwarders face EU CSRD Scope 3 disclosure obligations extending to beneficial cargo owners. Consolidation among large Asia-Europe operators drives single-platform procurement.
- Importers:Retail and automotive supply chain managers prioritizing emissions data capture for sustainability filings.
- Exporters:Manufacturing shippers seeking API connectivity to port authorities and customs agencies.
Revenue concentration sits with Shipping Companies; Freight Forwarders are climbing the fastest as consolidation accelerates platform standardization.
Deployment Model:
Cost structures and migration timelines diverge based on captive infrastructure dependencies and regulatory certification burdens.
- Cloud-based:Majority of new implementations among forwarders seeking usage-based pricing alignment with shipment volatility. Southeast Asian and Latin American buyers prioritize vendors offering tiered subscriptions over upfront capital commitments. Rotterdam, Singapore, and Shanghai port authority API mandates accelerate adoption.
- On-premises:Persist among carriers with legacy terminal operating system dependencies at owned port facilities. Cybersecurity certification under EU NIS2 Directive and national maritime security frameworks imposes heavy compliance overhead for this model.
- Hybrid:Architectures bridging cloud analytics with captive terminal systems at major carrier-owned facilities.
- SaaS:Subscription platforms displacing perpetual licenses among mid-market forwarders with seasonal volume fluctuations.
New procurement flows predominantly to Cloud-based; SaaS is gaining share fastest among emerging market forwarders.
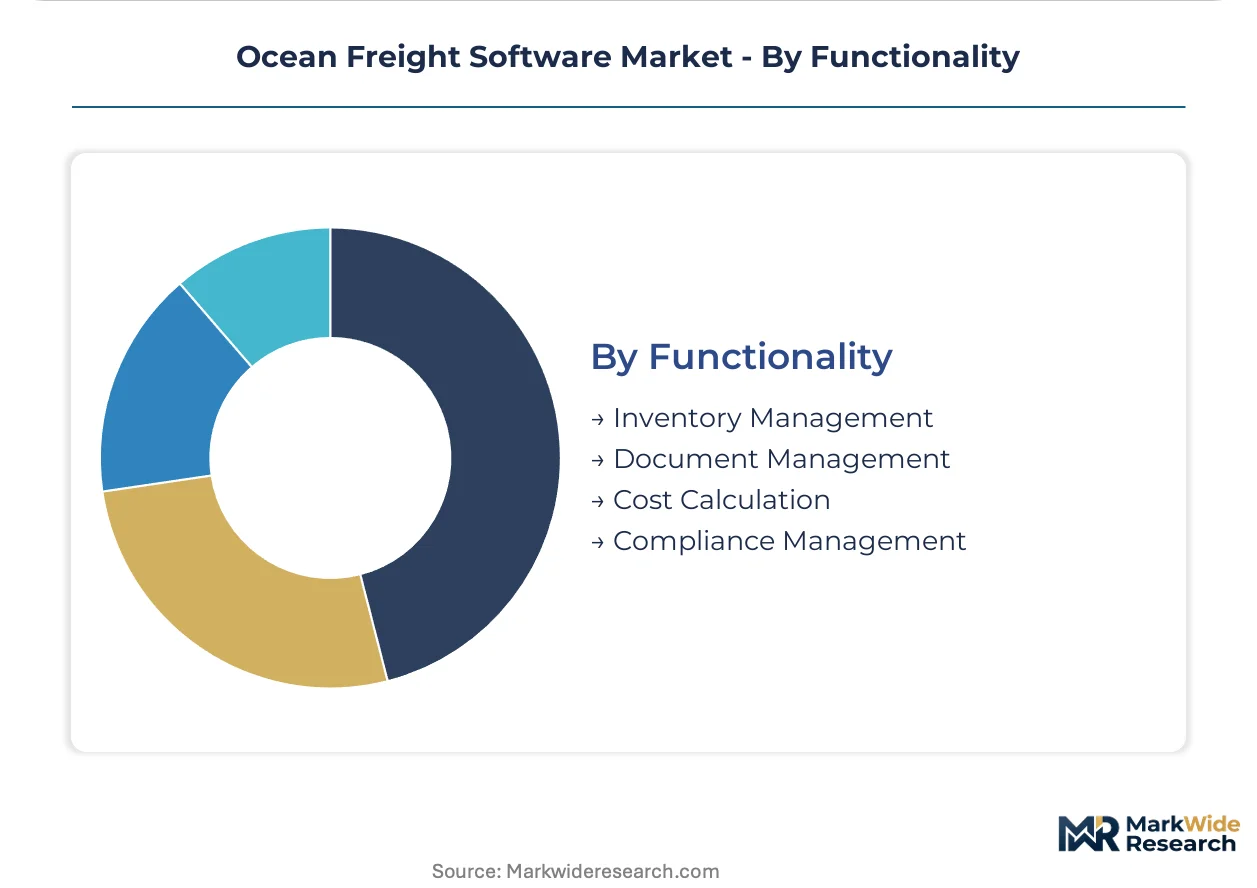
Functionality:
Regulatory embedding depth determines whether capabilities remain standalone modules or become core platform infrastructure.
- Inventory Management:Reefer container monitoring integrated with EU F-Gas Regulation compliance and predictive maintenance algorithms. Demand concentrates among European cold chain operators facing tightened emissions reporting for refrigerated units. Platforms capturing temperature, humidity, and refrigerant leakage data command procurement priority.
- Document Management:Bill-of-lading digitization and blockchain-EDI convergence for distributed ledger verification. Maritime blockchain consortia are partnering with established vendors to automate document workflows. Shippers into European ports prioritize vendors with CSRD-ready data formatting.
- Cost Calculation:Automated rate management and landed cost estimation across multi-modal segments.
- Compliance Management:Embedded customs brokerage integration and regulatory filing protocols.
Procurement volume clusters in Inventory Management; Document Management is expanding most quickly through blockchain partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates among North American and European vendors, while procurement demand clusters around Asia-Pacific trade lanes and European compliance corridors. Consumption patterns diverge sharply between carrier headquarters in developed markets and forwarder operations in emerging logistics hubs.
United States
Trans-Pacific string operators anchor demand for predictive voyage optimization and fuel analytics modules. The Federal Maritime Commission enforces detention and demurrage billing transparency rules that accelerate API-first platform adoption. Los Angeles-Long Beach port complex drives concentrated procurement among forwarders managing Asia-U.S. west coast volumes.
Germany
Hamburg and Bremerhaven logistics clusters generate sustained demand for CSRD-compliant emissions reporting functionality. The EU Green Deal's maritime emissions targets tighten software specification standards for carriers serving European importers. Bavaria-based industrial shippers prioritize platforms with embedded Scope 3 data capture for automotive supply chains.
China
Shanghai port authority's API-first data exchange mandates accelerate cloud platform adoption among terminal operators and state-owned carriers. The Ministry of Transport's dual carbon goals compel domestic shipping lines to document voyage efficiency metrics. Yangtze River Delta forwarders consolidate fragmented point solutions into unified operating environments.
Singapore
The Maritime and Port Authority's digitalization initiatives drive concentrated procurement among Southeast Asian forwarders seeking usage-based pricing alignment. PSA International's terminal operating systems create hybrid architecture dependencies for regional carriers. Singapore-based shipping lines prioritize vendors with proprietary machine learning infrastructure for slow-steaming decision models.
India
DGFT digitization initiatives and port automation at JNPT and Mundra open procurement windows for cloud-based freight management among mid-tier forwarders. The Bureau of Indian Standards frames data security protocols for maritime software handling cargo manifest information. Maharashtra-based logistics providers retire email-based booking systems in favor of real-time capacity allocation tools.
Ocean Freight Software Market Competitive Landscape
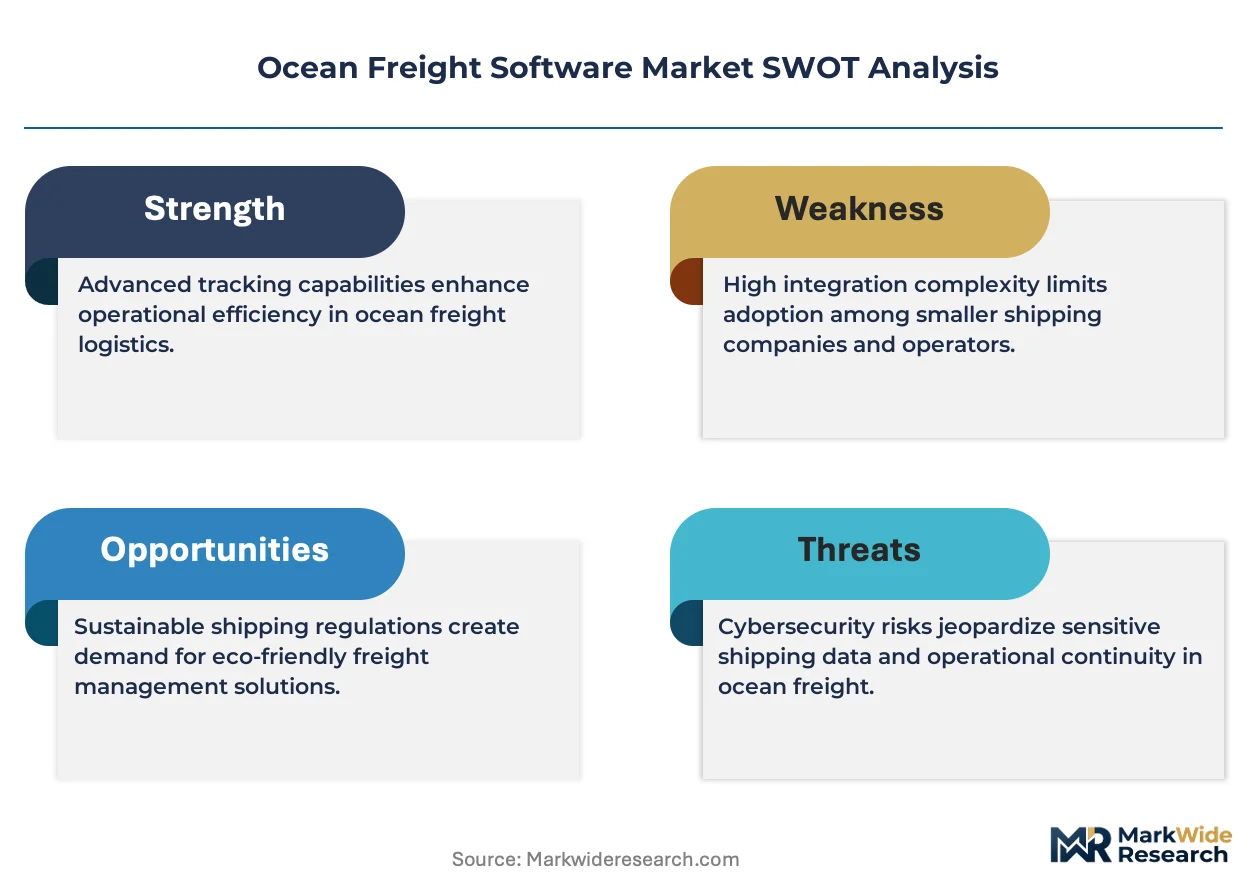
The competitive structure tilts toward integrated platform vendors with customs and compliance depth. Large forwarders operating complex origin-destination pairs consolidate procurement around single-architecture vendors, while specialized booking modules retain viability among fragmented regional networks. Two strategic archetypes dominate: compliance-anchored suite providers and API-native capacity allocation specialists. M&A activity concentrates on acquiring customs brokerage data assets; strategic partnerships focus on maritime blockchain consortia integration.
Within the integrated suite tier, WiseTech and Descartes Systems Group exemplify vendors anchoring position through extensive customs functionality and multimodal network effects. CargoWise occupies a position representing aggressive single-platform competition for large forwarder consolidation waves. These three companies illustrate how compliance depth and trade lane coverage determine procurement priority among Asia-Europe operators facing IMO 2023 carbon intensity mandates.
| Leading Market Players |
|---|
| WiseTech |
| Descartes Systems Group |
| Magaya Corporation |
| Oracle |
| Riege Software |
| Mercurygate |
| Aljex Software |
| Navis |
| CargoWise |
| Others |
Pricing and Supply Chain Analysis
Compliance-grade platform divergence separates IMO-certified freight management suites from basic booking modules, concentrating pricing power with vendors embedding carbon intensity tracking and CSRD reporting while commodity tools compete on subscription tiers alone. This bifurcation reshapes supply chain configurations as premium vendors backward-integrate into customs data assets and API infrastructure, whereas price-competitive players outsource vessel feed integrations to third-party AIS providers.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects subscription pricing displacement of perpetual licenses among Southeast Asian forwarders with seasonal volume volatility. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth—premium bundles embed predictive routing engines and EU F-Gas Regulation compliance, while economy tiers offer standalone booking modules with limited API connectivity. Price differentiation hinges on customs brokerage integration density and machine learning infrastructure for voyage optimization. Small forwarders in India trade lanes exhibit highest price sensitivity; trans-Pacific carriers demonstrate lowest, prioritizing fleet-wide standardization over unit cost.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data centers concentrated in the United States, Ireland, and Singapore, with backup dependencies in Frankfurt and Mumbai for regional latency compliance. Core platform development draws from software engineering talent pools in India and Poland, while maritime domain expertise feeds from retired carrier operations staff in Rotterdam and Hamburg. Single-source vulnerability concentrates in AIS vessel feed providers and terminal operating system vendors at major port authorities. Distribution runs through direct enterprise sales for carrier accounts and channel partners for mid-tier forwarder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ocean freight software market operates as a cost-of-compliance story where IMO 2023 carbon intensity regulations erect barrier-to-entry moats favoring vendors with pre-built emissions documentation and CSRD reporting templates.
For Market Incumbents: Extend customs data asset coverage through targeted acquisitions of regional brokerage operators in India and Southeast Asia to anchor network effects against API-native challengers. Deepen vertical integration into terminal operating system partnerships at Rotterdam and Singapore to capture hybrid architecture procurement from state-owned carriers. Prioritize machine learning infrastructure investment for proprietary slow-steaming models that lock in trans-Pacific string operators. For New Entrants and Emerging Players: Capture white space in reefer container analytics by building EU F-Gas Regulation compliance modules that incumbent suites have deprioritized. Target mid-tier forwarders at JNPT and Mundra where DGFT digitization creates procurement windows before established vendors localize. Lead with usage-based pricing and rapid API onboarding to outmaneuver legacy contract structures. For Investors and Strategic Acquirers: Re-rating potential sits with customs brokerage data specialists given IMO and CSRD compliance tailwinds extending through the analysis window. Long-term viability favors vendors with multimodal network density across Asia-Europe corridors. Watch maritime-AI talent scarcity as inflection signal—carriers unable to hire combined vessel operations and machine learning expertise will accelerate outsourced platform procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage Acquisition | Secures regulatory data moats against API-native competitors in Asia-Pacific trade lanes. |
| Reefer Analytics Module Launch | Captures EU F-Gas Regulation compliance demand that incumbent suites underweight. |
| Terminal OS Partnership | Enables hybrid cloud deployments for carriers with captive port infrastructure dependencies. |
| Machine Learning Infrastructure Buildout | Supports proprietary voyage optimization models that differentiate trans-Pacific carrier offerings. |
| Blockchain-EDI Integration | Automates bill-of-lading verification through maritime blockchain consortia partnerships. |
Research Methodology
Independent corroboration across carrier IT procurement officers, freight forwarder operations directors, and port authority digitalization leads underwrites the qualitative findings. Primary fieldwork encompassed CTOs at container lines, platform integration specialists at logistics providers, and channel partners serving Southeast Asian markets. Secondary validation drew from IMO regulatory filings, EU CSRD implementation guidance, port authority API documentation, and customs automation directives. Bottom-up shipment volume modeling triangulated against top-down software spend estimates from enterprise procurement databases.
Comparable-period anchoring to pre-IMO 2023 implementation baselines established trajectory parameters across the projection horizon. Segmentation dimensions modeled deployment model, forwarder size tier, trade lane complexity, and regulatory jurisdiction cluster. CAGRs derived from shipment volume elasticity to software pricing and compliance mandate phase-in schedules. Forecast inputs incorporated AIS feed proliferation rates and cloud infrastructure cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to maritime-AI talent availability and blockchain-EDI standardization adoption. Assumptions reflect current regulatory trajectories without anticipating IMO protocol amendments or EU Green Deal acceleration. Watch for NIS2 Directive enforcement variance across member states and India DGFT digitization timeline shifts as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Outbound Logistics Market