
 CLV and Churn Prediction AI Market | 2026-2036
CLV and Churn Prediction AI Market Size, Share, and Industry Trends Forecast 2026-2036
CLV and Churn Prediction AI Market Insights
Aftermarket service revenue is rewriting how enterprise software vendors monetize customer relationships. Salesforce leverages its Einstein analytics layer to embed churn scoring directly into CRM workflows. Optimove sustains differentiation through specialized behavioral modeling engines for subscription businesses. Zendesk anchors its positioning by integrating predictive signals into support ticket routing, reducing escalation costs.
CLV and Churn Prediction AI encompasses machine learning systems that process transactional histories, engagement telemetry, and demographic attributes to forecast customer lifetime value and propensity to cancel. These platforms typically operate on feature pipelines refreshed daily, scoring millions of accounts against gradient-boosted or neural architectures to trigger retention interventions before cancellation events materialize. Cloud-Based deployment leads solution delivery due to elastic compute requirements for real-time inference across seasonal demand spikes. Predictive Analytics occupies the core margin pool as enterprises prioritize algorithmic explainability for revenue-impacting decisions. Behavioral Modeling grows fastest among solution types as digital-native firms demand granular interaction-level signals rather than coarse segment averages.
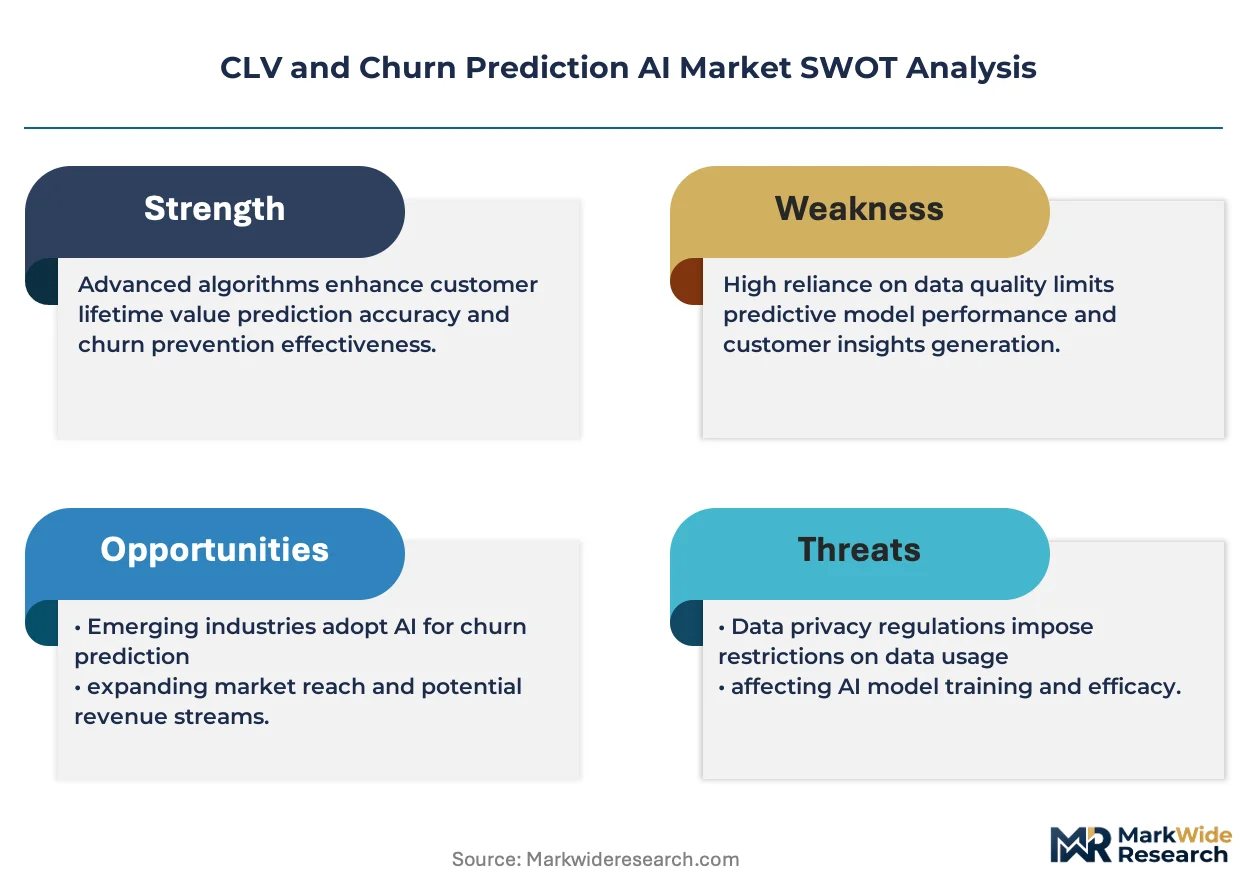
The EU AI Act classifies automated customer scoring as high-risk, mandating human oversight and algorithmic transparency for systems affecting economic access. The US Federal Trade Commission scrutinizes dark-pattern retention tactics and opaque subscription cancellation flows, pressuring vendors to document prediction fairness. HIPAA constrains how healthcare-adjacent financial services firms deploy churn models against patient-derived data. Stakeholders must decide whether to build explainability architectures that satisfy divergent regulatory expectations or fragment product variants by jurisdiction.
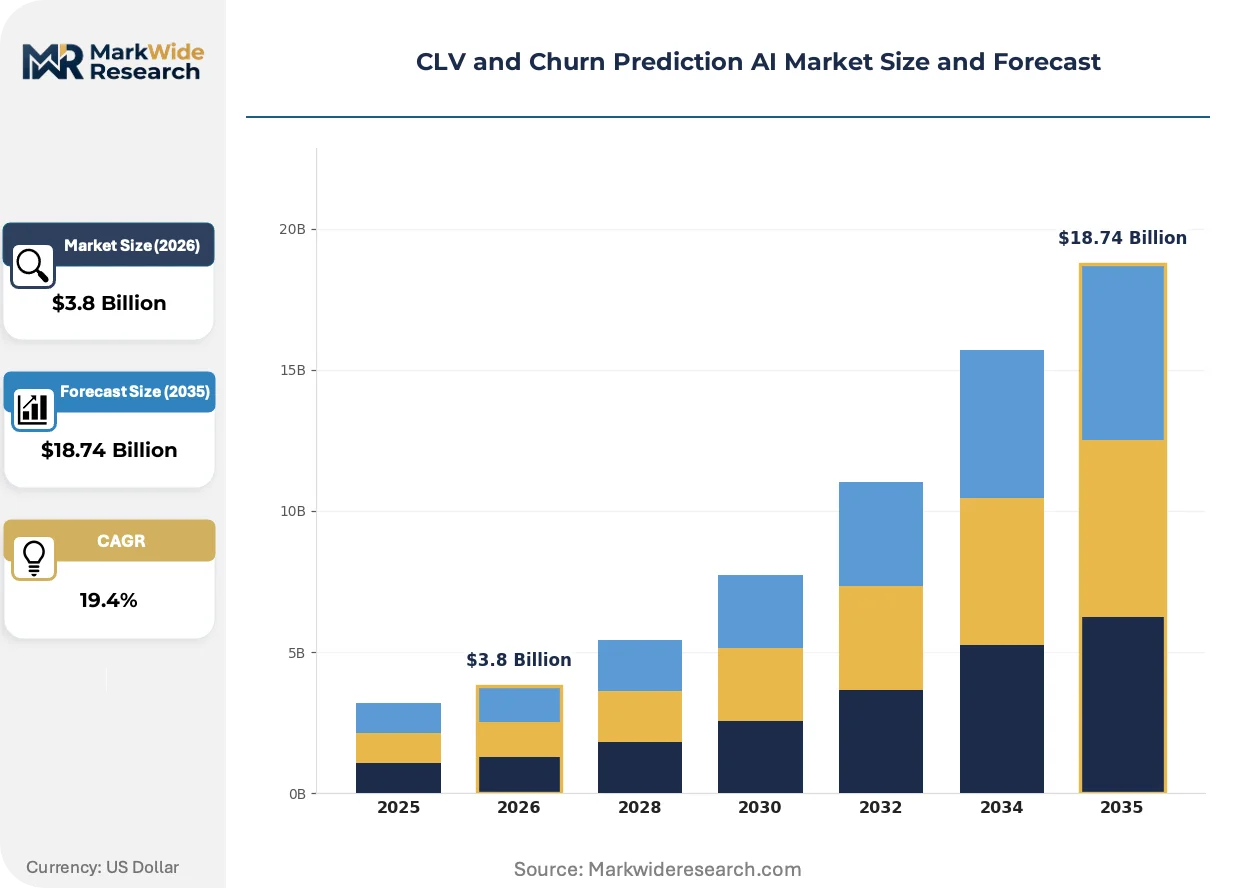
Market Dynamics
The EU AI Act's high-risk classification of automated customer scoring systems is forcing vendors to rebuild algorithmic explainability architectures, diverting engineering resources from predictive accuracy toward audit-ready transparency pipelines.
Growth Catalysts
- Telecommunications subscriber defection prevention:Mobile network operators in the United States deploy real-time churn signals to preempt cancellation before contract renewal windows close.
- GDPR-compliant behavioral telemetry pipelines:European subscription businesses invest in consent-managed data collection to fuel gradient-boosted retention models without regulatory exposure.
- Cloud-based elastic inference infrastructure:Seasonal demand spikes in retail and travel verticals require auto-scaling compute clusters for same-day model retraining.
Market Restraints
- GPU compute cost volatility:Training neural architectures for CLV prediction requires sustained access to NVIDIA H100 clusters, squeezing margins for mid-market SaaS vendors.
- Algorithmic audit liability concentration:The EU AI Act mandates human oversight for high-risk scoring systems, creating compliance cost asymmetry favoring incumbents with dedicated risk teams.
- Feature engineering talent scarcity:Behavioral sequence modeling for churn prediction demands specialized machine learning operations expertise concentrated in San Francisco and London.
Strategic Opportunities
- India's digital payments surge:UPI transaction volumes generate granular behavioral signals for fintech churn models previously impossible with cash-dominated economies.
- Healthcare-adjacent financial services:HIPAA-constrained insurers seek federated learning architectures to predict policy lapse without centralizing patient-derived data.
- Real-time streaming inference convergence:Apache Kafka and Redis integration enables sub-second churn scoring during live customer service interactions.
Industry Challenges
- Legacy CRM integration friction:Enterprises running decade-old Salesforce or SAP instances face 12-18 month timelines to embed predictive signals into existing workflow automation.
- Explainability-versus-accuracy tradeoffs:Regulatory pressure for interpretable models limits deployment of black-box neural architectures with superior predictive performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CLV and Churn Prediction AI Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Predictive Analytics, Customer Segmentation, Sentiment Analysis, Behavioral Modeling, Risk Assessment Application: Subscription Services, Telecom Operators, Ecommerce Platforms, Digital Media, Financial Services Customer Type: Enterprises, Small and Medium Businesses, Startups, Nonprofit Organizations |
| Companies Covered | Salesforce, Twilio Segment, Optimove, Gainsight, HubSpot, Qualtrics, Zendesk, Amplitude, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CLV and Churn Prediction AI Market Trends and Innovations
Automated machine learning pipelines are compressing model deployment cycles from quarters to weeks, reshaping how enterprises operationalize churn prediction without dedicated data science teams.
Transformer-based sequence models trained on clickstream telemetry are rendering obsolete traditional RFM segmentation for subscription businesses. Direct-to-consumer brands in the United States adopt these architectures within six-month implementation windows. The shift compresses feature engineering timelines while demanding specialized MLOps talent scarce outside coastal technology clusters.
The EU AI Act's high-risk system designation triggers mandatory conformity assessments for CLV scoring platforms deployed across member states. Vendors must document training data provenance and algorithmic fairness metrics before commercial deployment. Healthcare and financial services segments in Germany and France face the steepest compliance timelines, with some operators fragmenting product variants by jurisdiction.
Buyers increasingly demand outcome-based retention contracts where vendors bear financial risk for failed churn interventions. This displaces traditional per-seat SaaS pricing in enterprise telecommunications and streaming media verticals. The model concentrates fastest in the United Kingdom, where CFOs prioritize guaranteed return on AI investment over speculative pilot programs.
CLV and Churn Prediction AI Market Segmentation
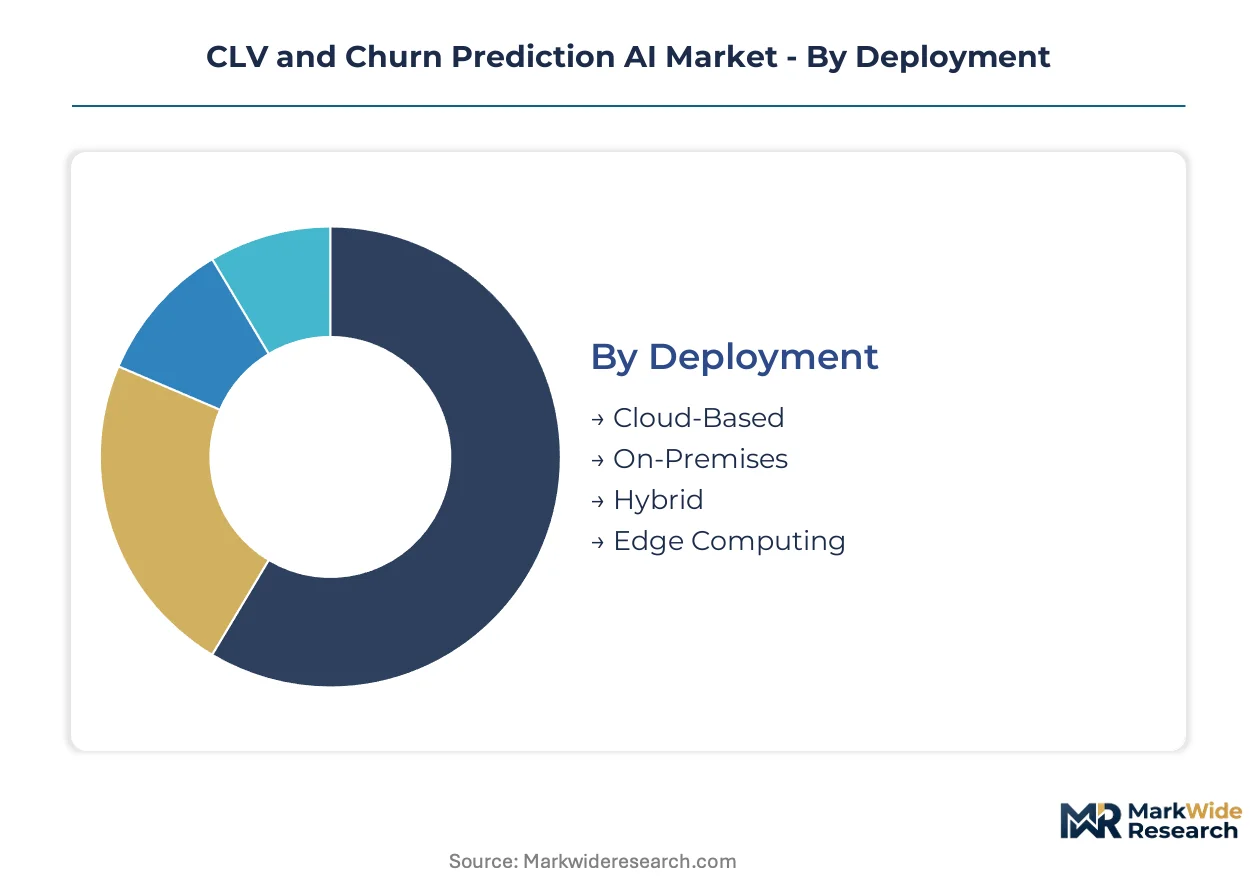
CLV and churn prediction AI vendors architect their offerings around four intersecting dimensions. Deployment modality determines infrastructure economics. Solution type shapes algorithmic sophistication. Application vertical dictates feature engineering priorities. Customer type governs pricing architecture and implementation complexity.
Deployment:
Cloud-based architectures dominate telecommunications and retail verticals demanding elastic inference capacity during renewal cycles and holiday peaks.
- Cloud-Based:Multi-tenant SaaS platforms provision auto-scaling GPU clusters for real-time scoring across millions of subscriber accounts. US mobile operators and streaming services concentrate procurement here due to seasonal demand volatility and zero capital expenditure requirements.
- On-Premises:Air-gapped installations serve HIPAA-constrained health insurers and Tier-1 banks in Germany and Switzerland requiring sovereign data control. Compliance teams mandate these deployments despite 40-60% higher total cost of ownership.
- Hybrid:Split architectures train models in cloud environments while executing inference within client data centers. European subscription businesses adopt this pattern to satisfy GDPR data residency requirements without sacrificing algorithmic iteration speed.
- Edge Computing:Embedded scoring engines deploy directly at point-of-sale terminals and mobile base stations. Retailers in India and Brazil leverage these for sub-100 millisecond latency during live customer interactions.
The dominant share belongs to Cloud-Based deployments, while Edge Computing is closing the gap fastest.
Solution Type:
Margin concentration follows algorithmic explainability requirements imposed by financial services regulators.
- Behavioral Modeling:Transformer architectures process clickstream sequences and engagement telemetry to predict defection before explicit cancellation signals emerge. Direct-to-consumer brands in the United States and United Kingdom prioritize these capabilities for granular intervention targeting.
- Predictive Analytics:Gradient-boosted frameworks generate interpretable CLV scores with documented feature importance for audit trails. German and French insurers mandate these transparent pipelines under EU AI Act high-risk system obligations.
- Customer Segmentation:Clustering algorithms group accounts by behavioral similarity to optimize retention campaign economics. Mid-market SaaS vendors embed these modules as entry-level offerings.
- Sentiment Analysis:Natural language processing of support tickets and social media extracts churn precursors from unstructured text. Telecommunications operators in India deploy these for multilingual customer bases.
- Risk Assessment:Composite scoring integrates credit, behavioral, and macroeconomic signals for policy lapse prediction. HIPAA-constrained US health insurers federate these models without centralizing patient data.
Predictive Analytics commands the largest revenue pool, though Behavioral Modeling is expanding most quickly as digital-native firms displace legacy RFM segmentation.
Application:
Vertical-specific feature engineering separates vendors with durable competitive positions from horizontal platform providers.
- Telecom Operators:Real-time scoring of usage patterns, network quality complaints, and competitive switching signals preempts subscriber defection during contract renewal windows. US and Indian carriers represent concentrated demand.
- Subscription Services:Recurring revenue models require continuous engagement monitoring across onboarding, expansion, and contraction phases. Streaming platforms and software vendors in the United Kingdom and Germany drive implementation.
- Financial Services:Policy lapse and credit card attrition models must satisfy stringent regulatory documentation requirements. German insurers and US health plans dominate procurement.
- Ecommerce Platforms:Cart abandonment and repeat purchase prediction leverage browsing telemetry and logistics satisfaction signals. Indian digital marketplaces generate fastest-growing demand.
- Digital Media:Content consumption patterns and ad load sensitivity inform retention for publisher and advertising-supported platforms. US and Brazilian operators concentrate here.
Telecom Operators capture the dominant deployment share, while Financial Services is climbing the fastest on regulatory compliance spending.
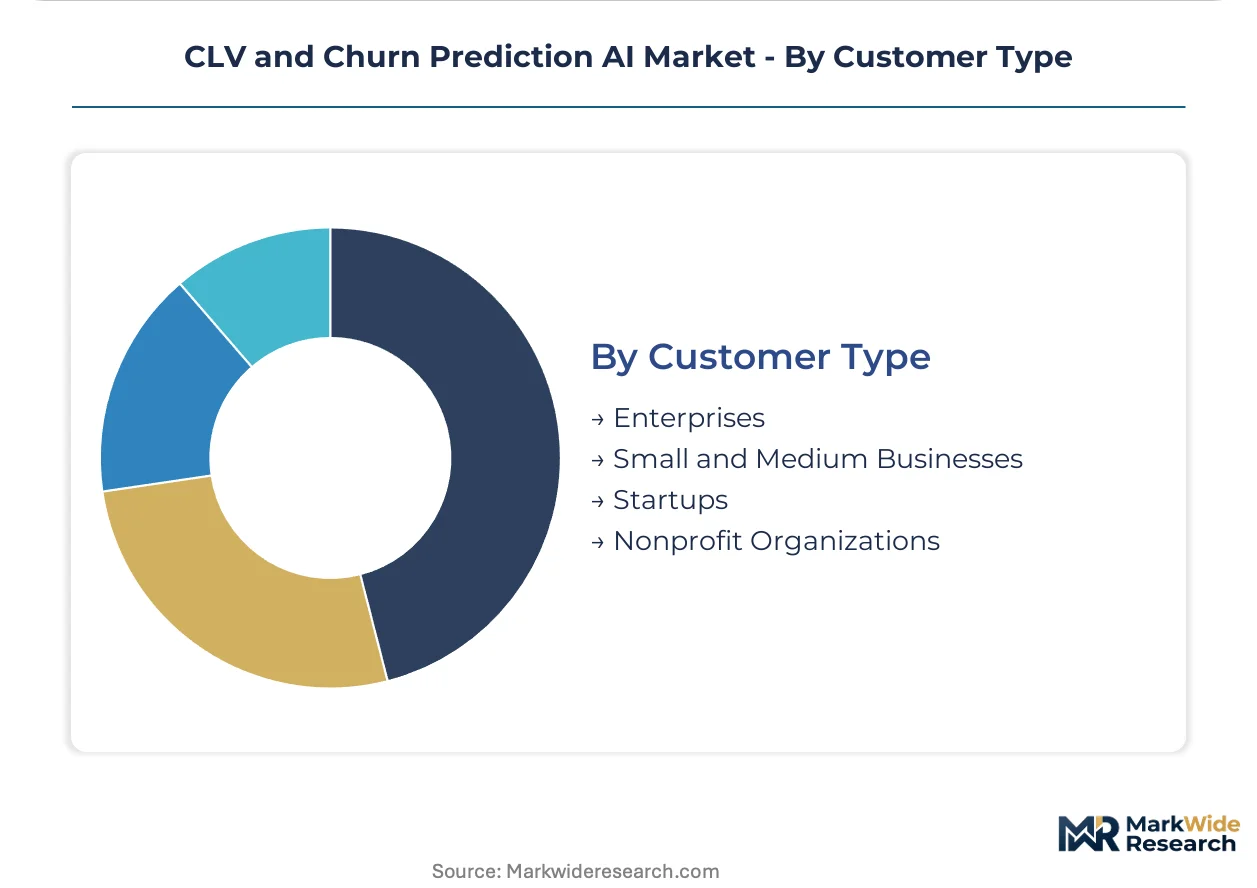
Customer Type:
Pricing architecture fragments across implementation complexity and data infrastructure maturity.
- Enterprises:Custom model development with dedicated MLOps engineering and SLA-guaranteed inference latency. Fortune 500 telecommunications and insurance groups in the United States, Germany, and United Kingdom anchor this tier.
- Small and Medium Businesses:Pre-configured templates with limited customization and shared infrastructure economics. UK and US mid-market SaaS vendors represent fastest-growing adoption.
- Startups:API-first consumption with per-prediction pricing and minimal implementation support. Indian fintech and Brazilian proptech ventures concentrate demand.
- Nonprofit Organizations:Donor retention and volunteer engagement scoring with subsidized or grant-funded procurement. US healthcare nonprofits and UK charitable foundations dominate this niche.
Enterprises retain the dominant revenue contribution, while Small and Medium Businesses is gaining share fastest as automated machine learning compresses deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States enterprises embed churn signals directly into CRM workflows, while European operators prioritize GDPR-compliant behavioral telemetry pipelines, and Indian fintechs exploit UPI transaction volumes for granular defection modeling.
United States
Mobile network operators and streaming services drive concentrated demand for real-time churn scoring during contract renewal windows. The FTC scrutinizes dark-pattern retention tactics and opaque subscription cancellation flows, pressuring vendors toward documented prediction fairness. San Francisco and Seattle clusters host specialized MLOps talent pools that sustain gradient-boosted model development for Fortune 500 telecommunications groups.
Germany
Health insurers and Tier-1 banks mandate air-gapped, on-premises deployments for sovereign data control despite elevated total cost of ownership. The EU AI Act imposes high-risk system classification on automated customer scoring, triggering mandatory conformity assessments with algorithmic fairness documentation. Berlin and Munich engineering centers fragment product variants to satisfy divergent regulatory expectations across member states.
United Kingdom
CFOs at enterprise SaaS vendors and streaming media platforms prioritize outcome-based retention contracts where vendors bear financial risk for failed interventions. GDPR consent-managed data collection frameworks govern behavioral telemetry pipelines for subscription businesses. London's financial services corridor concentrates procurement of interpretable CLV scoring systems with audit-ready transparency pipelines.
India
UPI transaction volumes generate behavioral signals for fintech churn models previously impossible with cash-dominated economies. The RBI oversees data localization requirements for payment system operators deploying predictive analytics. Bangalore and Mumbai clusters anchor API-first consumption models among proptech and fintech ventures seeking per-prediction pricing with minimal implementation support.
Brazil
Digital marketplaces and advertising-supported media platforms adopt edge computing architectures for sub-100 millisecond latency during live customer interactions. ANVISA and central bank guidelines constrain how healthcare-adjacent financial services deploy patient-derived data in retention models. São Paulo's retail technology corridor concentrates demand for embedded scoring engines at point-of-sale terminals.
CLV and Churn Prediction AI Market Competitive Landscape
Capability concentration sits with specialized behavioral modeling engines; scale advantage sits with horizontal CRM platforms embedding churn signals into existing workflow automation. The vendor base stratifies across three tiers: enterprise SaaS incumbents with dedicated risk teams, mid-market automated machine learning providers compressing deployment timelines, and API-first specialists serving venture-backed startups. Dominant competitive moves include outcome-based pricing contracts displacing per-seat SaaS models and explainability architecture investments satisfying EU AI Act high-risk system obligations.
Within the enterprise SaaS tier, Salesforce and Zendesk anchor positions through workflow integration advantages, while Optimove exemplifies the specialized behavioral modeling archetype for subscription businesses. Gainsight and HubSpot occupy positions across the customer success automation spectrum. Twilio Segment and Amplitude represent the product analytics-to-churn-prediction convergence pattern among digital-native firms. Qualtrics and SAP sit within the experience management and enterprise resource planning extension vectors respectively.
| Leading Market Players |
|---|
| Salesforce |
| Twilio Segment |
| Optimove |
| Gainsight |
| HubSpot |
| Qualtrics |
| Zendesk |
| Amplitude |
| SAP |
| Others |
Pricing and Supply Chain Analysis
GPU cluster undercapacity in North American cloud regions is forcing mid-market SaaS vendors toward reserved instance commitments, compressing margins while locking in pricing predictability for enterprise buyers. This utilization squeeze simultaneously accelerates vendor consolidation and intensifies cost pass-through negotiations for behavioral modeling workloads.
Pricing Analysis
Long-term outcome-based contracts are displacing per-seat SaaS subscriptions in enterprise telecommunications and streaming media verticals, particularly in the United Kingdom where CFOs demand guaranteed return on AI investment. Price differentiation rests on algorithmic explainability tiering and dedicated MLOps engineering support. Pricing pressure stems from GPU compute cost volatility squeezing margins for neural architecture training. Small and medium businesses exhibit highest price sensitivity due to limited data infrastructure budgets, while Fortune 500 insurance groups absorb premium pricing for audit-ready transparency pipelines.
Supply Chain Analysis
Upstream feedstock concentration in NVIDIA H100 and A100 GPU fabrication centers on Taiwan and South Korea, with advanced packaging capacity concentrated in Malaysia and Vietnam. Raw material dependencies include high-bandwidth memory from SK Hynix and Micron, specialized substrates from Japanese suppliers, and rare earth elements for magnetics in cooling systems. Single-source vulnerability around TSMC's leading-edge nodes creates supply chain risk for training cluster procurement. Distribution runs through hyperscaler marketplaces and direct OEM channels, with air-gapped on-premises installations bypassing cloud intermediaries for German and Swiss compliance mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket model retraining and explainability audit services are expanding faster than initial platform licensing, creating a service-attach opportunity that vendors must architect into recurring revenue streams.
For Market Incumbents: Entrench workflow integration advantages by embedding churn signals deeper into Salesforce and SAP automation layers, defending against API-first specialists. Acquire automated machine learning providers in Bangalore and London to compress deployment timelines for mid-market expansion. Prioritize EU AI Act conformity assessment pre-certification to create compliance cost asymmetry against emerging entrants lacking dedicated risk teams.
For New Entrants and Emerging Players: Mid-market SaaS vendors in the United Kingdom and United States with limited data science teams represent the most penetrable entry point, as automated machine learning pipelines reduce implementation friction. India's UPI-enabled fintech ventures offer white-space opportunity for per-prediction pricing models with minimal implementation support. Target outcome-based retention contracts in streaming media verticals where CFOs prioritize guaranteed ROI over speculative pilots.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud-based inference infrastructure as seasonal demand spikes require auto-scaling GPU commitments. Long-term viability over the coming decade favors specialized behavioral modeling engines with transformer-based sequence architectures over horizontal platform extensions. Target acquisition profiles should emphasize vendors with documented algorithmic fairness metrics and GDPR-compliant consent management frameworks. The signal to watch is regulatory fragmentation forcing product variant multiplication across jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainability Architecture Investment | EU AI Act high-risk system obligations mandate human oversight pipelines for automated customer scoring platforms. |
| Outcome-Based Contract Expansion | UK CFOs in telecommunications and streaming media prioritize guaranteed ROI over traditional per-seat SaaS pricing. |
| Automated Machine Learning Acquisition | Compresses deployment timelines from quarters to weeks for mid-market SaaS vendors lacking dedicated data science teams. |
| GDPR-Compliant Telemetry Pipeline Development | European subscription businesses require consent-managed data collection to fuel retention models without regulatory exposure. |
| Real-Time Streaming Inference Convergence | Apache Kafka and Redis integration enables sub-second churn scoring during live customer service interactions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief technology officers at telecommunications operators, customer success executives at subscription SaaS vendors, data science leads at health insurers, and MLOps engineers at digital-native firms. Secondary validation drew from SEC filings of publicly traded CRM platforms, EU AI Act implementation guidance documents, FTC enforcement actions on dark-pattern retention tactics, and hyperscaler capex disclosures for GPU cluster deployment. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association revenue aggregates.
Calibration against historical deployment timelines and regulatory compliance spending patterns anchored projections across the analysis window. Segmentation dimensions modeled include deployment modality, solution type, application vertical, and customer type, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from slope analysis of technology adoption curves and compliance cost trajectories. Forecast inputs incorporated GPU compute cost volatility assumptions and MLOps talent availability indices for San Francisco, London, and Bangalore clusters.
Macroeconomic conditions sit as an overlay; deviation in enterprise software spending cycles or cloud infrastructure investment would shift the trajectory. Forecasts reflect assumptions around EU AI Act enforcement intensity and HIPAA constraint evolution in healthcare-adjacent financial services. Cross-checking against hyperscaler earnings call commentary on AI workload growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market