
 AI Demand Forecasting Software Market | 2026-2036
AI Demand Forecasting Software Market Size, Share, and Industry Trends Forecast 2026-2036
AI Demand Forecasting Software Market Insights
North American cloud infrastructure expansion is fragmenting competitive dynamics across the AI demand forecasting landscape. SAP leverages deep ERP integration to anchor enterprise accounts across manufacturing verticals. Blue Yonder competes through specialized supply chain planning modules that extend its footprint in retail and consumer goods. o9 Solutions differentiates via AI-native architecture built for real-time decisioning rather than retrofitted legacy stacks.
AI demand forecasting software applies machine learning algorithms to historical transaction data, external signals, and operational variables to generate probabilistic demand projections with quantified confidence intervals. Cloud-based deployment dominates current uptake due to elastic compute requirements for model retraining and inference at scale. Predictive analytics solutions sustain the largest revenue pool today, though prescriptive analytics is gaining fastest as buyers seek automated decision recommendations rather than standalone forecasts. Inventory optimization applications occupy the deepest margin pools within manufacturing end-user industries where stockout costs exceed software investment multiples.
The EU AI Act imposes risk classification and conformity requirements on automated forecasting systems used in critical supply chains, shaping vendor product roadmaps and go-to-market timing. FDA oversight of AI-enabled demand prediction for pharmaceutical distribution adds compliance layers in the US healthcare supply chain. Enterprises must monitor evolving algorithmic accountability standards across jurisdictions to avoid retrofit costs and market access barriers.
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing vendors to re-architect legacy forecasting platforms for real-time elasticity, compressing deployment timelines and raising certification barriers simultaneously.
Growth Catalysts
- EU AI Act cloud mandates:Risk classification requirements for automated supply chain systems are accelerating vendor certification investments and enterprise procurement cycles.
- Fortune 500 manufacturers:Post-disruption supply chain resilience programs are expanding procurement of probabilistic demand projection tools with quantified confidence intervals.
- Inventory optimization:Retail chains facing elevated carrying costs are deploying machine learning algorithms to reduce safety stock levels without elevating stockout risk.
Market Restraints
- Elastic compute costs:Model retraining and inference at scale require sustained cloud infrastructure expenditure that mid-market buyers struggle to amortize.
- Algorithmic accountability standards:Divergent regulatory frameworks across jurisdictions create compliance fragmentation and retrofit cost exposure.
- Legacy ERP integration friction:Retrofitted forecasting stacks face data pipeline complexity when interfacing with decades-old manufacturing execution systems.
Strategic Opportunities
- Prescriptive analytics convergence:Automated decision recommendations are displacing standalone forecasts as buyers seek closed-loop planning systems.
- Healthcare supply chain AI:FDA oversight of pharmaceutical distribution forecasting creates specialized compliance layers for qualified vendors.
- Real-time decisioning architecture:AI-native platforms built for streaming data ingestion are capturing share from batch-processed legacy alternatives.
Industry Challenges
- Machine learning operations talent:Scarce MLOps expertise constrains model deployment velocity and ongoing performance monitoring at enterprise scale.
- Cross-functional data harmonization:Demand signal integration across sales, operations, and finance functions requires organizational redesign beyond software implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Demand Forecasting Software Market |
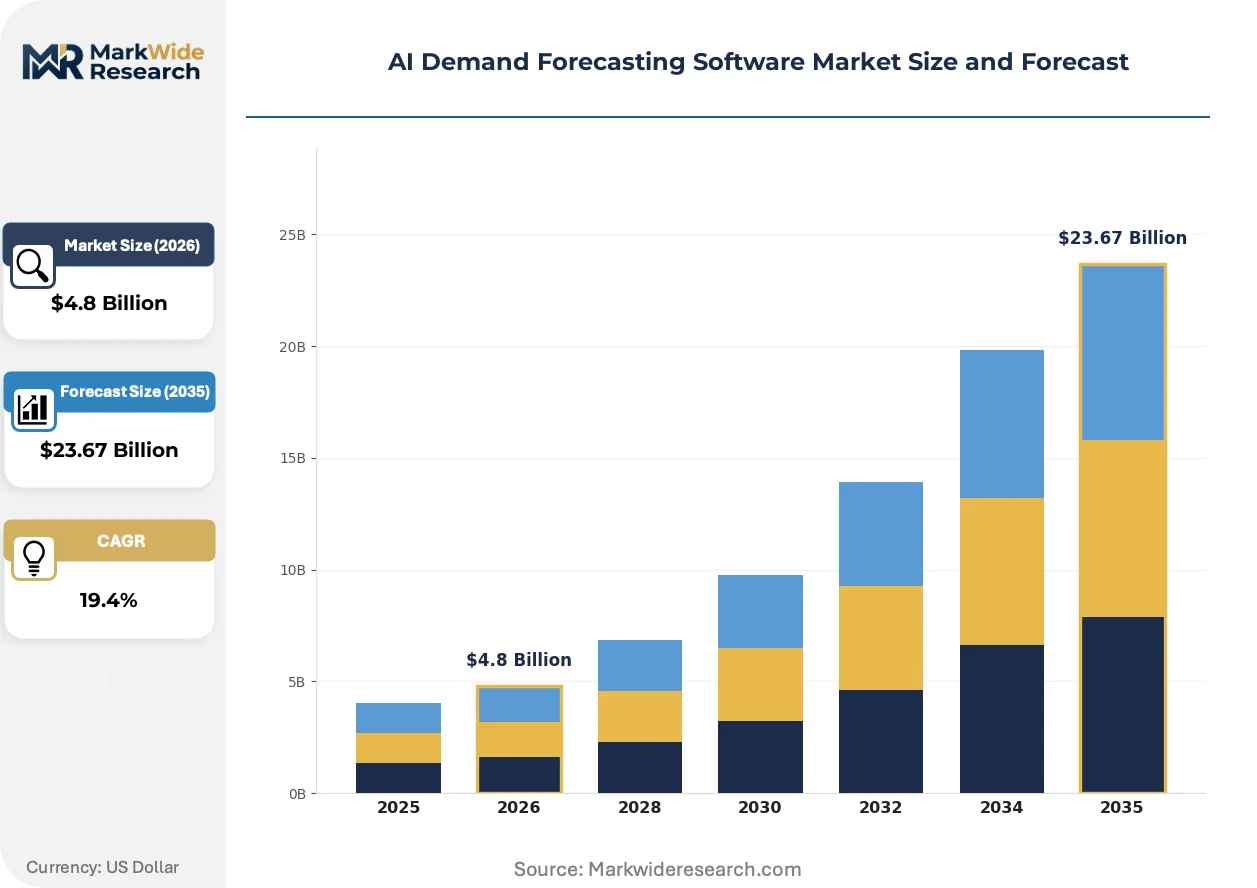
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $23.67 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Solution Type: Predictive Analytics, Prescriptive Analytics, Visual Analytics, Real-Time Analytics Application: Inventory Optimization, Sales Forecasting, Supply Chain Planning, Market Trend Analysis End User Industry: Consumer Electronics, Fashion & Apparel, FMCG, Telecommunications, Manufacturing |
| Companies Covered | SAP, Oracle, Blue Yonder, Kinaxis, o9 Solutions, Infor, Anaplan, GMDH Streamline, Netstock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Demand Forecasting Software Market Trends and Innovations
Probabilistic forecasting methods are displacing deterministic models across supply chain planning, compressing the gap between prediction accuracy and automated response execution.
Transformer-based neural architectures are migrating from natural language processing into demand forecasting applications, enabling multi-horizon prediction with external signal integration. Automotive and consumer electronics manufacturers are piloting these models for component procurement planning. The technology is migrating from experimental deployments toward production-grade supply chain orchestration platforms.
The EU AI Act's risk classification framework imposes conformity assessment requirements on high-stakes automated forecasting systems used in critical infrastructure supply chains. Vendors must document algorithmic transparency and human oversight protocols to maintain market access. Pharmaceutical distribution networks across Germany, France, and the Netherlands are restructuring procurement criteria to prioritize certified providers.
Subscription-based platform economics are displacing perpetual license structures as dominant commercial models. Enterprise buyers prefer consumption-aligned pricing tied to forecast volume or SKU complexity rather than upfront capital commitment. This shift is most visible among United States-based Fortune 500 manufacturers rebuilding procurement flexibility post-pandemic.
AI Demand Forecasting Software Market Segmentation
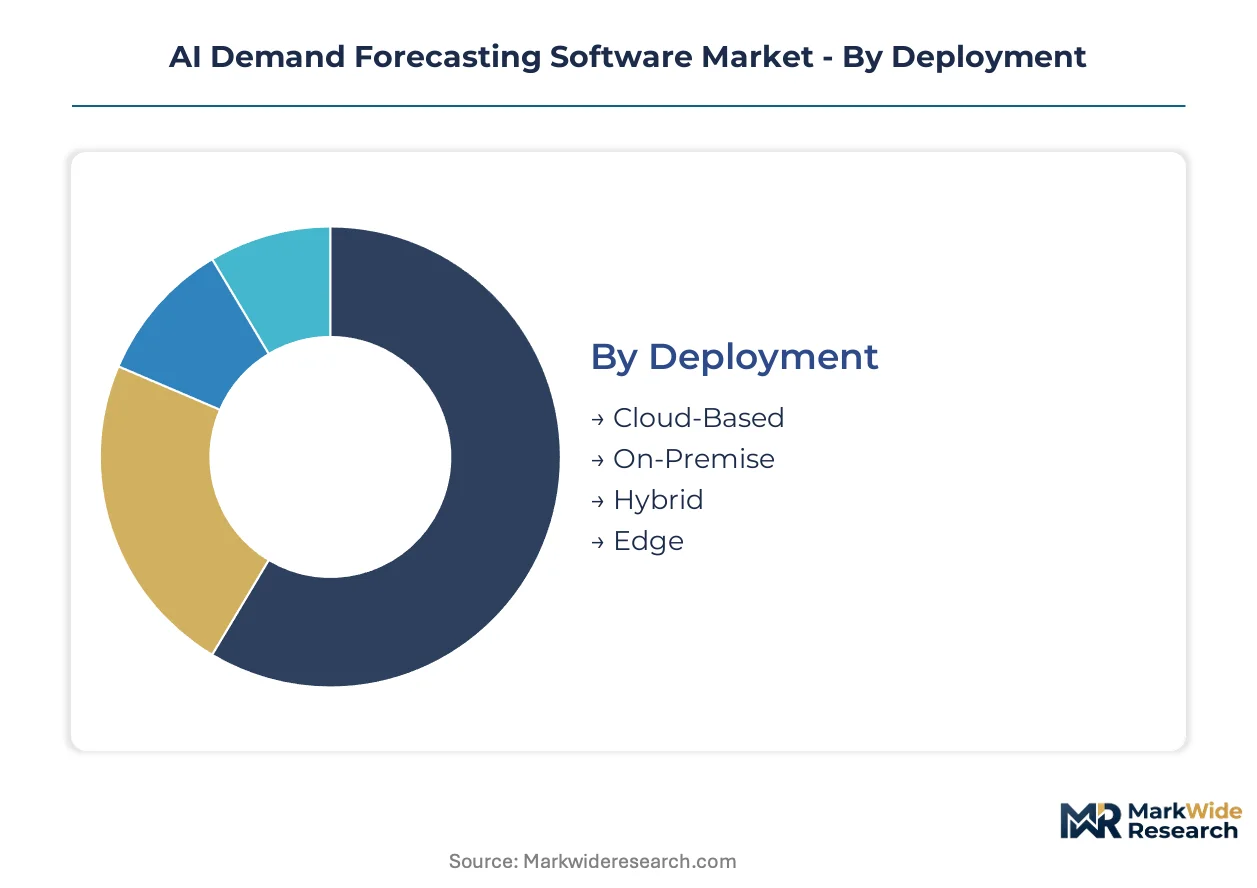
Segmentation in AI demand forecasting software reveals distinct procurement patterns across infrastructure maturity, analytical sophistication, and industry-specific compliance requirements. Buyers prioritize deployment flexibility and solution architecture based on data sovereignty constraints, computational intensity, and integration complexity with legacy operational systems.
Deployment:
Mature cloud architectures dominate procurement volumes, while emerging edge deployments capture specialized latency-sensitive applications.
- Cloud-Based:Elastic compute infrastructure supports model retraining and inference at scale without capital-intensive hardware procurement. United States-based Fortune 500 manufacturers favor this deployment for supply chain resilience programs requiring rapid elasticity.
- On-Premise:Air-gapped installations serve pharmaceutical distribution networks subject to FDA oversight and EU AI Act data residency mandates. German and French healthcare supply chains prioritize these deployments for algorithmic accountability documentation.
- Hybrid:Split architectures process sensitive demand signals locally while leveraging cloud resources for non-critical workloads.
- Edge:Distributed inference nodes enable real-time decisioning in manufacturing execution systems with sub-second latency requirements.
Cloud-based deployments retain volume leadership; edge infrastructure holds the steepest expansion curve.
Solution Type:
Cost tier differentiation separates established predictive modules from premium prescriptive capabilities commanding implementation premiums.
- Predictive Analytics:Probabilistic demand projection with quantified confidence intervals sustains the largest revenue pool across retail and consumer goods. Inventory carrying cost reduction drives procurement among United States retail chains.
- Prescriptive Analytics:Automated decision recommendations displace standalone forecasts as buyers seek closed-loop planning systems. Automotive manufacturers pilot these modules for component procurement optimization.
- Visual Analytics:Dashboard-centric interfaces facilitate cross-functional demand signal interpretation across sales and operations planning workflows.
- Real-Time Analytics:Streaming data ingestion architectures support continuous model updating for volatile demand environments.
Predictive analytics commands the deepest installed base; prescriptive solutions are expanding most quickly.
Application:
Application focus correlates with margin sensitivity — stockout cost exposure determines software investment thresholds.
- Inventory Optimization:Machine learning algorithms reduce safety stock levels without elevating stockout risk in manufacturing verticals where carrying costs exceed software investment multiples. United States manufacturers rebuilding supply chain resilience post-disruption prioritize this application.
- Supply Chain Planning:Multi-echelon coordination modules integrate procurement, production, and distribution forecasting across complex network topologies.
- Sales Forecasting:Historical transaction pattern analysis supports revenue planning and resource allocation in seasonal demand environments.
- Market Trend Analysis:External signal integration captures demand shifts from macroeconomic indicators, competitor actions, and consumer sentiment.
Inventory optimization captures the highest margin pools; supply chain planning demonstrates the broadest cross-industry penetration.
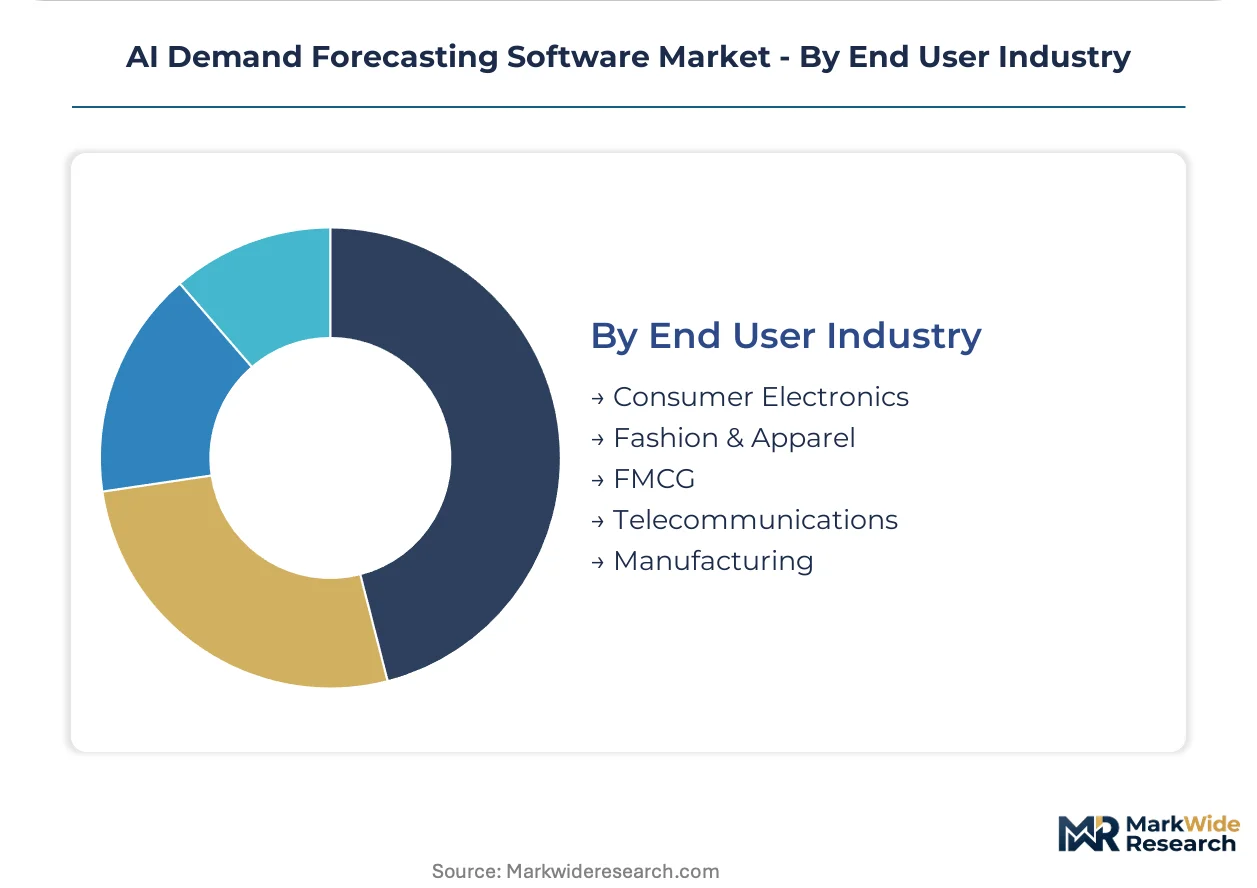
End User Industry:
Customer type stratification reflects divergent data maturity and regulatory exposure across verticals.
- Manufacturing:Discrete and process manufacturers deploy demand forecasting for raw material procurement and production scheduling synchronization. EU AI Act cloud migration mandates accelerate vendor certification investments in German and French industrial clusters.
- Consumer Electronics:Short product lifecycles and component obsolescence risk demand high-velocity forecast updating with supplier collaboration integration.
- Fashion & Apparel:Seasonal demand volatility and trend-driven purchasing patterns require rapid style-level demand sensing.
- FMCG:High-frequency replenishment cycles and promotion-driven demand spikes necessitate granular store-level forecasting.
- Telecommunications:Infrastructure capacity planning and device demand projection support network investment timing decisions.
Manufacturing retains the deepest software investment intensity; consumer electronics shows the most rapid adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize real-time elasticity and supply chain resilience, while European procurement emphasizes regulatory certification and algorithmic accountability under emerging AI governance frameworks.
United States
Fortune 500 manufacturers dominate procurement, deploying cloud-native forecasting for inventory optimization and post-disruption resilience rebuilding. FDA oversight of pharmaceutical distribution AI adds compliance layers for healthcare supply chains. The Chicago industrial corridor and Texas manufacturing belt concentrate deployment of probabilistic demand projection tools with quantified confidence intervals.
Germany
Automotive and discrete manufacturers drive demand for prescriptive analytics modules that automate component procurement decisions. EU AI Act cloud migration mandates accelerate vendor certification investments and compress deployment timelines. The Baden-Württemberg automotive cluster and Bavarian industrial corridor prioritize real-time decisioning architectures for supplier collaboration integration.
France
Luxury goods and pharmaceutical distributors procure certified forecasting systems to meet EU AI Act conformity requirements for high-risk automated supply chains. ANSM oversight of healthcare AI creates specialized procurement criteria for pharmaceutical networks. The Île-de-France logistics hub and Lyon pharmaceutical corridor restructure vendor selection around algorithmic transparency documentation.
China
Consumer electronics manufacturers pilot transformer-based neural architectures for multi-horizon component procurement planning amid volatile demand cycles. MIIT standards for industrial AI systems shape vendor qualification requirements. The Yangtze River Delta electronics manufacturing belt and Pearl River Delta supply chain clusters accelerate adoption of streaming data ingestion architectures.
United Kingdom
Retail chains and FMCG distributors deploy machine learning algorithms to reduce safety stock levels without elevating stockout risk in high-frequency replenishment environments. GDPR data residency requirements influence hybrid deployment preferences. The London financial and logistics corridor and Midlands manufacturing belt concentrate procurement of subscription-based platform economics over perpetual licenses.
AI Demand Forecasting Software Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around ERP-anchored incumbents with deep manufacturing integration, AI-native specialists built for real-time decisioning, and supply chain planning modularists extending retail footprints. Strategic moves concentrate on cloud re-architecture for EU AI Act compliance and prescriptive analytics convergence toward closed-loop planning systems.
Within the ERP-anchored tier, SAP and Oracle represent scale-driven incumbents leveraging decades of manufacturing system integration. Blue Yonder and o9 Solutions exemplify contrasting architectural approaches—one extending specialized supply chain modules, the other built AI-native for streaming data ingestion. Kinaxis occupies a position bridging modular planning and real-time orchestration for complex network topologies.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| Blue Yonder |
| Kinaxis |
| o9 Solutions |
| Infor |
| Anaplan |
| GMDH Streamline |
| Netstock |
| Others |
Pricing and Supply Chain Analysis
Elastic compute undercapacity across Western European cloud regions is compressing vendor margins while amplifying pricing power for hyperscale infrastructure providers serving AI demand forecasting workloads.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, displacing perpetual licenses as Fortune 500 manufacturers seek consumption-aligned pricing tied to forecast volume or SKU complexity. Price differentiation separates certified EU AI Act-compliant tiers from standard cloud deployments, with algorithmic transparency documentation commanding implementation premiums. Pricing pressure stems from mid-market buyers struggling to amortize sustained cloud infrastructure expenditure for model retraining at scale. Retail chains exhibit highest price sensitivity due to inventory carrying cost pressures, while pharmaceutical distributors under FDA oversight demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Export-control restrictions on advanced GPU clusters and specialized AI accelerators are constraining vendor capacity expansion across United States, Taiwan, and South Korea manufacturing nodes. Cloud infrastructure supply draws from hyperscale data center buildouts in Virginia, Frankfurt, and Singapore, with transformer-based neural architecture development resting on restricted semiconductor foundry access. Single-source vulnerability concentrates in NVIDIA GPU supply chains for model training workloads. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations for cloud-native deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive dynamics as ERP-anchored incumbents face displacement pressure from AI-native architectures built for real-time interoperability with streaming data ecosystems.
For Market Incumbents: Insulate enterprise accounts by deepening ERP integration investments and accelerating EU AI Act certification timelines before cloud-native competitors achieve compliance. SAP and Oracle must defend manufacturing verticals against o9 Solutions' real-time decisioning architecture by embedding prescriptive analytics modules directly into production scheduling workflows. Priority lever sits in backward integration into MLOps tooling to reduce third-party dependency for model deployment velocity. For New Entrants and Emerging Players: Pursue white-space opportunities in pharmaceutical distribution networks across Germany, France, and the Netherlands where ANSM and EU AI Act compliance requirements have restructured vendor selection criteria around algorithmic transparency documentation. The most penetrable segment comprises mid-market manufacturers in the Texas industrial corridor seeking inventory optimization without full-scale ERP replacement. Go-to-market angle should emphasize subscription-based platform economics with consumption-aligned pricing to mirror buyer preference shifts among United States Fortune 500 procurement teams. For Investors and Strategic Acquirers: Long-term, this sits as a vertical-SaaS consolidation play because AI-native demand forecasting platforms with real-time streaming architectures will capture share from retrofitted legacy stacks as prescriptive analytics convergence accelerates. Acquisition target archetype centers on specialized MLOps tooling providers with healthcare supply chain credentials under FDA oversight frameworks. Signal to watch is certification velocity under EU AI Act risk classification timelines as inflection indicator for vendor market access positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-anchored vendors embed prescriptive analytics to close the loop between forecasting and automated procurement execution. |
| Acquisition of Specialist Firm | Real-time streaming architecture targets capture MLOps capabilities to accelerate model deployment velocity at enterprise scale. |
| Geographic Expansion | Certified cloud deployments in Baden-Württemberg and Bavaria secure EU AI Act compliance for automotive supply chains. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure provide elastic compute infrastructure for transformer-based neural model retraining. |
| Product Launch | AI-native platforms displace batch-processed legacy alternatives with streaming data ingestion for volatile demand environments. |
Research Methodology
A standing panel of supply chain planning directors, MLOps engineering leads, enterprise software procurement officers, and regulatory compliance specialists provided ongoing calibration across primary interview programs. Secondary validation drew from SEC 10-K filings of publicly traded ERP vendors, hyperscaler capex disclosures from AWS and Azure, EU AI Act implementation guidance documents, and FDA AI-enabled medical device enforcement correspondence. Bottom-up segment sizing triangulated against top-down market aggregation from cloud infrastructure expenditure tracking.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling deployment model transitions, organization size tiering, vertical adoption intensity, integration complexity strata, and regional regulatory cluster divergence. CAGRs derived from segment-level build-ups incorporating cloud migration mandate compliance timelines, inventory optimization software investment multiples, and prescriptive analytics module attach rates. Industry-specific inputs included transformer-based neural architecture pilot deployment counts across automotive manufacturers and EU AI Act certification pipeline status for vendor qualification tracking.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, cloud infrastructure capital expenditure cycles, or semiconductor foundry capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and enterprise cloud migration velocity. Material shifts in EU AI Act risk classification implementation timelines or FDA AI oversight scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
AI Watermarking Market