
 Middle East and Africa Virtual Reality (VR) Health Market | 2026-2036
Middle East and Africa Virtual Reality (VR) Health Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Virtual Reality (VR) Health Market Foresight
Standalone VR headsets with integrated spatial computing is narrowing the gap between consumer-grade hardware and clinical-grade deployment requirements. Koninklijke Philips N.V. leverages its diagnostic imaging heritage to anchor VR visualization in surgical planning workflows. Samsung Electronics Co. Ltd. sustains hardware supply advantages through its Galaxy VR ecosystem and display panel manufacturing scale. Siemens Healthineers AG differentiates by embedding VR modules directly into its existing radiology and angiography suites.
Middle East and Africa Virtual Reality (VR) Health comprises immersive digital systems combining head-mounted displays, real-time motion tracking, and haptic feedback interfaces to simulate medical procedures, therapeutic environments, or anatomical structures for clinical training and patient intervention. These systems typically operate at sub-20 millisecond motion-to-photon latency to prevent simulator sickness during extended therapeutic sessions. The application dimension shows training and pain management segments attracting disproportionate investment as Gulf health systems address anesthesia alternatives and workforce competency gaps. Product type dynamics favor software over headsets as margins concentrate in proprietary clinical content libraries and procedure-specific simulation engines rather than commoditized display hardware.
South Africa's Health Products Regulatory Authority, the UAE's Ministry of Health and Prevention, and Saudi Food and Drug Authority collectively govern medical software classification, data localization requirements, and clinical evidence standards for VR therapeutic claims across the region. These frameworks shape market access timelines and compel vendors to maintain separate compliance documentation for each national jurisdiction. Stakeholders must monitor evolving medical device software guidance from Gulf regulators as classification determinations will dictate whether VR health platforms require full pre-market approval or qualify for expedited digital health pathways.
Market Dynamics
Standalone VR headsets with integrated spatial computing are collapsing the cost barrier between consumer hardware and clinical deployment, forcing Gulf health systems to reevaluate procurement strategies around disposable versus capital equipment models.
Growth Catalysts
- SFDA medical device software guidance:Saudi Arabia's streamlined digital health approval pathways compress market entry timelines for VR therapeutic platforms, accelerating vendor commercialization cycles.
- Anesthesia alternatives in surgical protocols:Dubai Health Authority-backed pain management initiatives embed immersive therapeutics into pre-operative and post-operative care standards, creating institutional demand pull.
- Workforce competency gaps:Gulf Cooperation Council hospital systems deploy VR surgical simulation to address specialist shortages in interventional cardiology and orthopedic procedures.
Market Restraints
- Data localization mandates:UAE and Saudi patient data sovereignty requirements fragment cloud infrastructure strategies, compelling vendors to maintain separate regional server deployments.
- Display panel supply concentration:Dependence on East Asian micro-OLED manufacturers exposes procurement timelines to semiconductor foundry allocation cycles.
- Simulator sickness thresholds:Sub-20 millisecond motion-to-photon latency requirements constrain hardware vendor selection and elevate minimum viable specifications.
Strategic Opportunities
- Sub-Saharan expansion corridors:Nigeria and Kenya present underpenetrated demand for VR-enabled medical education as university hospital networks digitize curricula.
- Haptic-VR convergence:Integration of force-feedback interfaces with immersive visualization creates procedure-specific training modules for laparoscopic and endovascular interventions.
- MOHAP digital health incentives:UAE Ministry of Health and Prevention reimbursement pilots for chronic pain VR therapy establish precedent for insurance coverage expansion.
Industry Challenges
- Clinical evidence generation timelines:Randomized controlled trials for VR therapeutic claims require 18-36 month study windows, delaying regulatory submissions to South Africa's Health Products Regulatory Authority.
- Interoperability with PACS infrastructure:Integration of VR visualization modules with existing radiology archiving systems demands custom DICOM gateway development.
- Specialized simulation engineer scarcity:Shortage of personnel capable of translating anatomical imaging into real-time procedural environments constrains content library expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Virtual Reality (VR) Health Market |
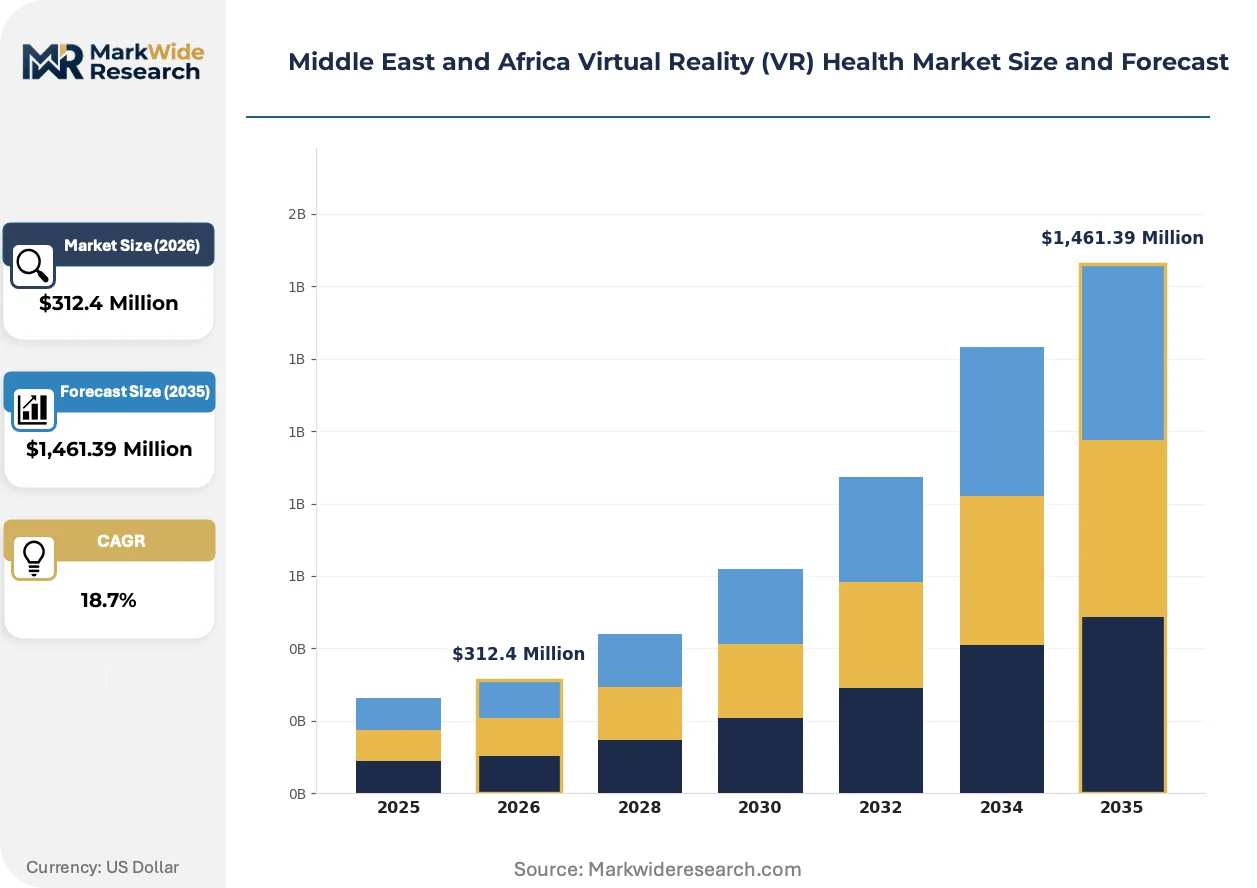
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Accessories, Simulators Application: Therapeutic, Training, Rehabilitation, Pain Management End User: Hospitals, Clinics, Rehabilitative Centers, Research Institutions Technology: Motion Tracking, Haptic Feedback, 3D Visualization, Immersive Environments |
| Companies Covered | Koninklijke Philips N.V., Samsung Electronics Co. Ltd., HTC Corporation, Siemens Healthineers AG, Sony Group Corp., Osso VR, XRHealth, CAE Inc., EON Reality, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Virtual Reality (VR) Health Market Shifts & Advancements
Spatial computing architectures are redefining the boundary between diagnostic visualization and therapeutic intervention, compressing the hardware refresh cycles that previously separated training systems from patient-facing deployments.
Cloud-rendered VR streaming is rendering obsolete the tethered workstation configurations that dominated early clinical pilot programs. Saudi hospital procurement committees now evaluate browser-based immersive platforms that offload compute to regional edge nodes, slashing per-deployment capital requirements by two-thirds. This architecture shift enables same-day activation across multiple surgical departments without dedicated IT infrastructure builds.
South Africa's Health Products Regulatory Authority has issued updated software-as-a-medical-device classification guidance that distinguishes wellness applications from therapeutic claims. The framework requires clinical evidence packages for pain management and psychiatric intervention modules while exempting pure training simulators from pre-market approval. Vendors are restructuring product portfolios to bifurcate regulatory pathways, with UAE and Saudi submissions following parallel but distinct documentation standards.
Gulf health system procurement committees are consolidating vendor relationships around integrated platform providers rather than point solutions. Saudi Arabia's Ministry of Health and Prevention now mandates enterprise licensing agreements that span surgical training, patient education, and therapeutic intervention modules under single contracting vehicles. This concentration rewards vendors with proprietary content libraries across multiple clinical domains while marginalizing hardware-only suppliers.
Middle East and Africa Virtual Reality (VR) Health Market Segmentation
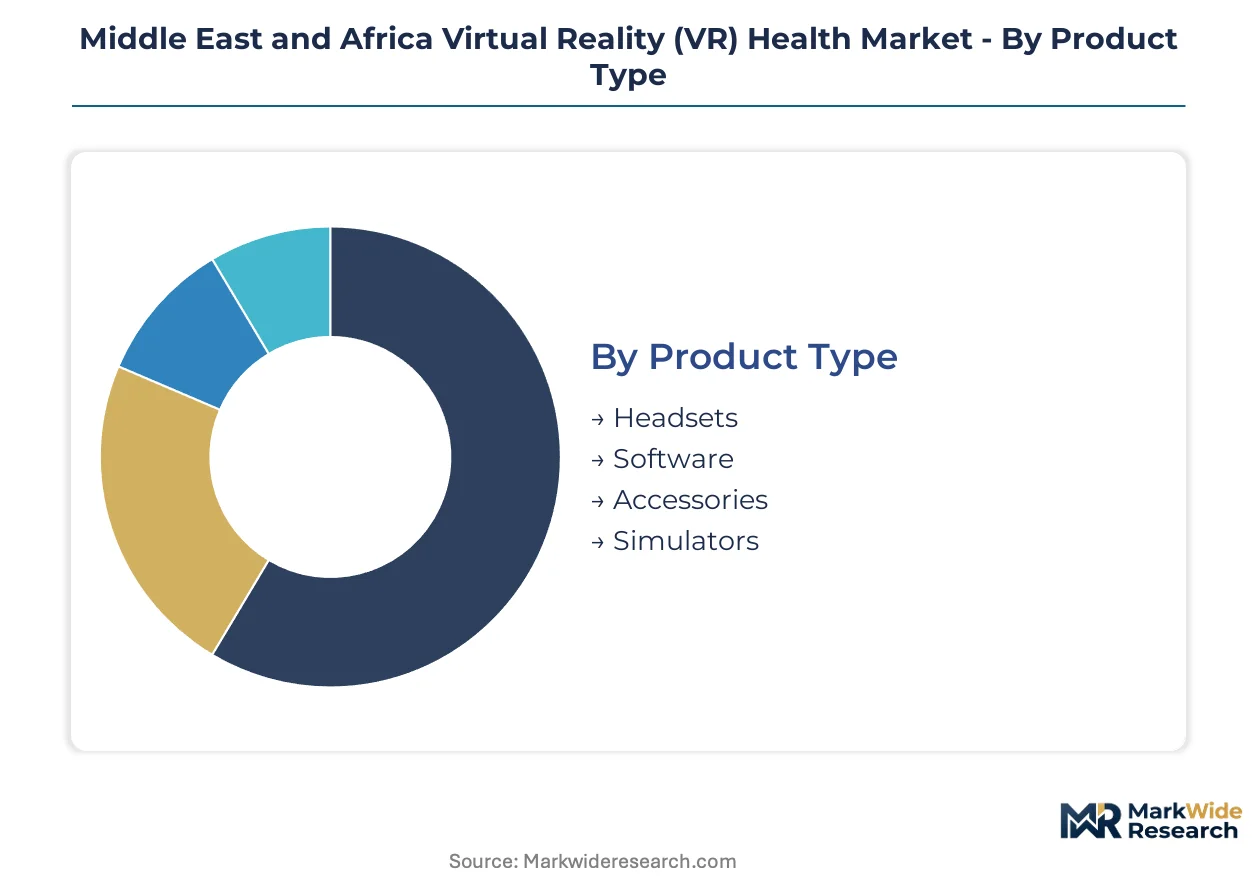
Segmentation in the Middle East and Africa VR Health Market reveals where procurement budgets concentrate and which clinical workflows drive hardware specifications. Gulf health systems prioritize software content libraries over headset commoditization, while South African regulators differentiate approval pathways by therapeutic claim intensity.
Product Type:
Cost tier dynamics separate capital-intensive hardware from recurring software licensing models across Gulf hospital procurement committees.
- Software:Proprietary clinical content libraries and procedure-specific simulation engines generate recurring licensing revenue. Dubai Health Authority-backed pain management protocols embed immersive therapeutics requiring continuous content updates, pulling institutional subscriptions.
- Headsets:Standalone VR headsets with integrated spatial computing operate at sub-20 millisecond motion-to-photon latency. Procurement committees evaluate disposable versus capital equipment models as consumer-grade hardware narrows clinical deployment gaps.
- Accessories:Controller peripherals, hygiene covers, and mounting systems address infection control protocols.
- Simulators:Full-body procedural training rigs combine haptic feedback with anatomical visualization for surgical credentialing.
Software commands the established base. The steepest expansion runs through Headsets as standalone spatial computing collapses deployment cost barriers.
Application:
Clinical use case maturity determines whether VR platforms require full pre-market approval from Saudi Food and Drug Authority or qualify for expedited digital health pathways.
- Training:Surgical simulation addresses workforce competency gaps in interventional cardiology and orthopedic procedures across Gulf Cooperation Council hospital systems. South Africa's Health Products Regulatory Authority exempts pure training simulators from pre-market approval, accelerating vendor commercialization.
- Pain Management:Immersive therapeutics embedded in pre-operative and post-operative care standards create institutional demand pull. UAE Ministry of Health and Prevention reimbursement pilots establish precedent for insurance coverage expansion.
- Therapeutic:Psychiatric intervention modules require clinical evidence packages under updated software-as-a-medical-device classification guidance.
- Rehabilitation:Motor skill recovery protocols leverage real-time motion tracking for stroke and trauma patient populations.
Training anchors current procurement volumes. Pain Management is gaining share fastest as anesthesia alternatives reshape surgical protocols.
End User:
Customer type scale dictates whether deployments follow enterprise licensing agreements or point-solution procurement models.
- Hospitals:Saudi Arabia's Ministry of Health and Prevention mandates enterprise licensing spanning surgical training, patient education, and therapeutic intervention under single contracting vehicles. This concentration rewards integrated platform providers with proprietary content libraries.
- Clinics:Outpatient facilities prioritize browser-based immersive platforms offloading compute to regional edge nodes, slashing capital requirements.
- Rehabilitative Centers:Specialized facilities deploy haptic-VR convergence for motor recovery and chronic pain protocols.
- Research Institutions:University hospital networks in Nigeria and Kenya digitize curricula, presenting underpenetrated demand for VR-enabled medical education.
Hospitals dominate contract value. Research Institutions show the steepest expansion trajectory as Sub-Saharan university networks accelerate curriculum digitization.
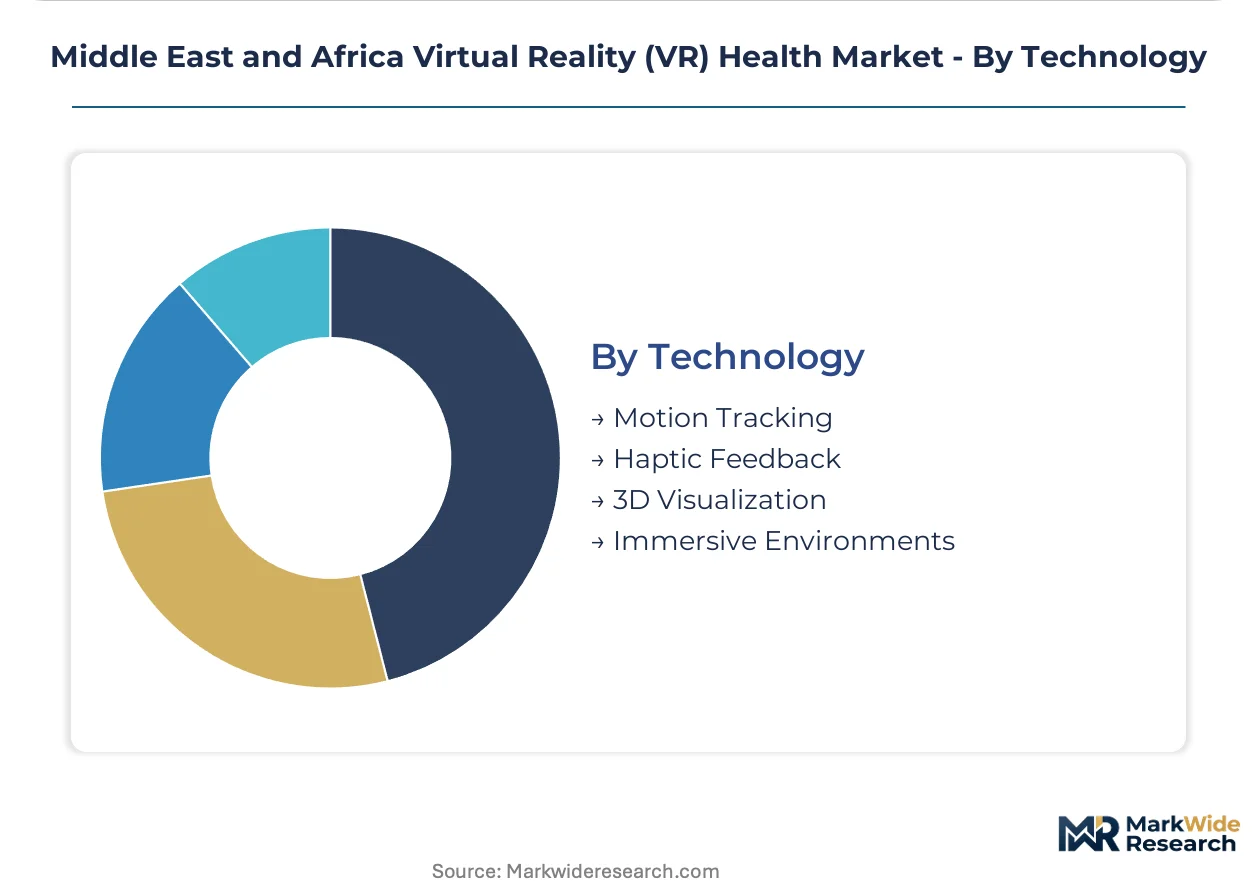
Technology:
Technical specification thresholds constrain vendor selection and elevate minimum viable procurement standards across the region.
- Haptic Feedback:Force-feedback interfaces integrated with immersive visualization create procedure-specific training modules for laparoscopic and endovascular interventions. Gulf surgical departments prioritize tactile fidelity for credentialing programs.
- Motion Tracking:Real-time positional systems operating at sub-20 millisecond latency prevent simulator sickness during extended therapeutic sessions. Hardware selection depends on semiconductor foundry allocation cycles from East Asian manufacturers.
- 3D Visualization:DICOM-compliant rendering engines demand custom gateway development for PACS infrastructure integration.
- Immersive Environments:Cloud-rendered VR streaming enables same-day activation across multiple departments without dedicated IT infrastructure builds.
Motion Tracking underpins baseline system performance. Haptic Feedback is climbing the fastest as procedural fidelity requirements intensify for surgical credentialing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based VR health platforms export immersive surgical training modules to Saudi hospital networks, while South African regulatory expertise diffuses northward through SADC trade corridors. This regional trade architecture concentrates procurement budgets in Gulf health systems while channeling technical compliance standards from Pretoria.
United Arab Emirates
Dubai Health Authority embeds immersive therapeutics into pre-operative pain management protocols, generating institutional subscription demand for proprietary clinical content libraries. MOHAP reimbursement pilots for chronic pain VR therapy establish precedent for insurance coverage expansion across the emirates. Abu Dhabi's Cleveland Clinic outpost deploys standalone spatial computing headsets for interventional cardiology credentialing programs.
Saudi Arabia
SFDA streamlined digital health approval pathways compress market entry timelines for VR therapeutic platforms targeting anesthesia alternatives in surgical protocols. Ministry of Health and Prevention mandates enterprise licensing agreements spanning training, patient education, and therapeutic modules under single contracting vehicles. Riyadh's King Faisal Specialist Hospital anchors regional procurement volume for haptic-integrated surgical simulators.
South Africa
Health Products Regulatory Authority software-as-a-medical-device classification distinguishes wellness applications from therapeutic claims, exempting pure training simulators from pre-market approval. University hospital networks in Johannesburg and Cape Town digitize medical curricula, presenting demand for VR-enabled education platforms. Cape Town's Groote Schuur Hospital pilots cloud-rendered VR streaming for same-day multi-department activation.
Israel
Specialist shortages in interventional procedures drive hospital system deployment of VR surgical simulation for workforce competency development. National digital health infrastructure supports integration of immersive visualization with existing PACS radiology archiving systems. Tel Aviv's Sheba Medical Center hosts regional training hubs exporting procedural simulation expertise to Gulf Cooperation Council partners.
Egypt
University hospital networks in Cairo and Alexandria accelerate curriculum digitization, generating underpenetrated demand for browser-based immersive platforms offloading compute to regional edge nodes. National medical device regulatory frameworks evolve toward alignment with Gulf digital health standards. Cairo's Kasr Al Ainy Medical School anchors North African VR medical education procurement.
Middle East and Africa Virtual Reality (VR) Health Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers rather than point-solution hardware vendors. Procurement committees favor vendors spanning surgical training, patient education, and therapeutic intervention under unified enterprise agreements. Three archetypes dominate: diagnostic imaging heritage players extending into VR visualization, consumer electronics manufacturers leveraging display panel scale, and specialized simulation content developers. Competitive positioning hardens through proprietary clinical content libraries and procedure-specific simulation engines rather than commoditized headset specifications.
Within the diagnostic imaging tier, Koninklijke Philips N.V. and Siemens Healthineers AG occupy positions anchored by radiology suite integration capabilities. Samsung Electronics Co. Ltd. exemplifies the hardware-scale archetype through Galaxy VR ecosystem manufacturing. These three represent the dominant competitive anchors as Gulf health systems consolidate vendor relationships around enterprise licensing models.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Samsung Electronics Co. Ltd. |
| HTC Corporation |
| Siemens Healthineers AG |
| Sony Group Corp. |
| Osso VR |
| XRHealth |
| CAE Inc. |
| EON Reality |
| Others |
Supply & Pricing Matrix
Jebel Ali port freight corridors into the Gulf Cooperation Council carry consumer-grade VR headset volumes at rates that compress clinical hardware premiums, while South African data localization mandates force parallel cloud infrastructure builds that bifurcate subscription pricing across the region. This logistics-cost asymmetry between hardware import lanes and software delivery networks concentrates margin pressure on headset vendors while insulating proprietary content libraries from price erosion.
Pricing Analysis
Next-generation spatial computing headsets command three-to-fourfold premiums over prior-generation tethered configurations, while current-generation standalone units occupy a contracting mid-tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under SFDA and MOHAP software-as-a-medical-device pathways, with premium tiers bundling enterprise licensing across training and therapeutic modules. Cost compression in standard-tier hardware intensifies because East Asian micro-OLED foundry allocation cycles constrain supply elasticity. Hospital procurement committees exhibit lowest price sensitivity due to enterprise mandate consolidation, while outpatient clinics face acute budget constraints driving browser-based platform adoption.
Supply Chain Analysis
Extended payment terms from Gulf health system procurement committees now stretch to 180 days, forcing VR hardware vendors to secure supply-chain finance facilities against receivables. Manufacturing concentration rests on China, South Korea, and Taiwan for micro-OLED display panels, semiconductor foundry services, and precision motion tracking sensors. Single-source vulnerability runs through East Asian micro-OLED manufacturers given limited alternative qualified suppliers for sub-20 millisecond latency specifications. Distribution runs through authorized medical device distributors holding SFDA and MOHAP import licenses, with direct-to-hospital contracting emerging for enterprise platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in the Middle East and Africa VR Health Market as Saudi Arabia's Ministry of Health and Prevention enterprise licensing mandates consolidate procurement around integrated platform providers, marginalizing point-solution vendors.
For Market Incumbents: Pre-empt content library commoditization by acquiring specialized simulation engineering teams capable of translating DICOM imaging into real-time procedural environments. Anchor defensive positioning through backward integration into haptic feedback hardware manufacturing, securing supply chain control over force-feedback interfaces as Gulf surgical credentialing programs intensify tactile fidelity requirements. Counter emerging browser-based platform threats by embedding cloud-rendered VR modules directly into existing PACS infrastructure, raising switching costs for hospital IT departments. For New Entrants and Emerging Players: Establish a beachhead in Sub-Saharan medical education by deploying lightweight browser-based immersive platforms to university hospital networks in Nigeria and Kenya, where curriculum digitization accelerates without legacy infrastructure constraints. Target pure training simulator segments exempt from South Africa's Health Products Regulatory Authority pre-market approval, compressing commercialization timelines relative to therapeutic claim pathways. Pursue channel partnerships with established medical device distributors holding multi-jurisdiction import licenses rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diagnostic imaging heritage conglomerates seeking to divest non-core VR visualization units lacking enterprise platform scale. Long-term viability hinges on proprietary clinical content library depth across multiple procedural domains rather than hardware manufacturing assets. Monitor SFDA classification determinations for VR therapeutic claims as the inflection signal—expanded pre-market approval requirements would accelerate consolidation toward integrated platform providers with regulatory affairs infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Enterprise Licensing Consolidation | Saudi MOHAP mandates span training, education, and therapeutic modules under single contracting vehicles. |
| Cloud-Rendered VR Streaming | Browser-based platforms offload compute to regional edge nodes, slashing capital requirements for multi-department activation. |
| Haptic-VR Convergence Development | Force-feedback integration creates procedure-specific modules for laparoscopic and endovascular credentialing programs. |
| Sub-Saharan Curriculum Digitization | University hospital networks in Nigeria and Kenya present underpenetrated demand for medical education platforms. |
| Regulatory Pathway Bifurcation | South Africa's SAHPRA distinguishes wellness applications from therapeutic claims, restructuring product portfolio strategies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement committee members, biomedical engineering directors, surgical simulation program leads, and medical device regulatory affairs specialists across the United Arab Emirates, Saudi Arabia, and South Africa. Secondary validation drew from SFDA software guidance documents, MOHAP reimbursement pilot disclosures, SAHPRA classification frameworks, hospital procurement database extracts, and GPO contract filings. Bottom-up and top-down triangulation reconciled vendor shipment estimates with institutional deployment records.
Calibration against historical adoption curves for digital health technologies informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, clinical application intensity, end-user scale, and technology specification threshold. CAGRs were derived from logistic diffusion curves fitted to early-adopter deployment trajectories. Forecast inputs incorporated semiconductor foundry allocation cycles and Gulf health system capital budget planning cycles.
Stress conditions across micro-OLED supply constraints, data localization compliance costs, and simulator sickness latency thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory pathway stability and health system procurement consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Global Patient Engagement Solution Market