
 Natural Language Processing in BFSI Market | 2026-2036
Natural Language Processing in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Language Processing in BFSI Market Foresight
The shift from rules-based chatbots to large language model architectures is tilting procurement priorities across financial institutions. Microsoft Corporation leverages its Azure OpenAI partnerships to anchor enterprise banking contracts. IBM Corporation sustains differentiation through Watson's specialized compliance modules for regulatory document parsing. NVIDIA Corporation dominates the infrastructure layer, controlling GPU supply chains that underpin training pipelines for sector-specific models.
Natural Language Processing in BFSI encompasses computational techniques for parsing, interpreting, and generating human language within banking, financial services, and insurance workflows, typically operating across unstructured text corpora with sub-second latency requirements for real-time fraud alerts. Its primary commercial purpose centers on automating document-intensive processes while extracting actionable intelligence from customer communications, market commentary, and regulatory filings. Sentiment analysis applications command mature margin pools in trading desks, whereas chatbot deployments are expanding fastest among retail banking end users. Cloud-based delivery models are displacing on-premises installations as banks pursue elastic scaling for seasonal query volumes.
The SEC enforces disclosure standards for AI-driven investment advice, compelling vendors to document model provenance and bias testing protocols. The EU AI Act imposes conformity requirements on credit-scoring algorithms, restricting black-box NLP deployments in consumer-facing decisions. HIPAA-aligned safeguards govern voice-to-text pipelines handling insurance claimant data. Stakeholders must weigh jurisdictional compliance fragmentation against the cost of maintaining region-specific model variants.
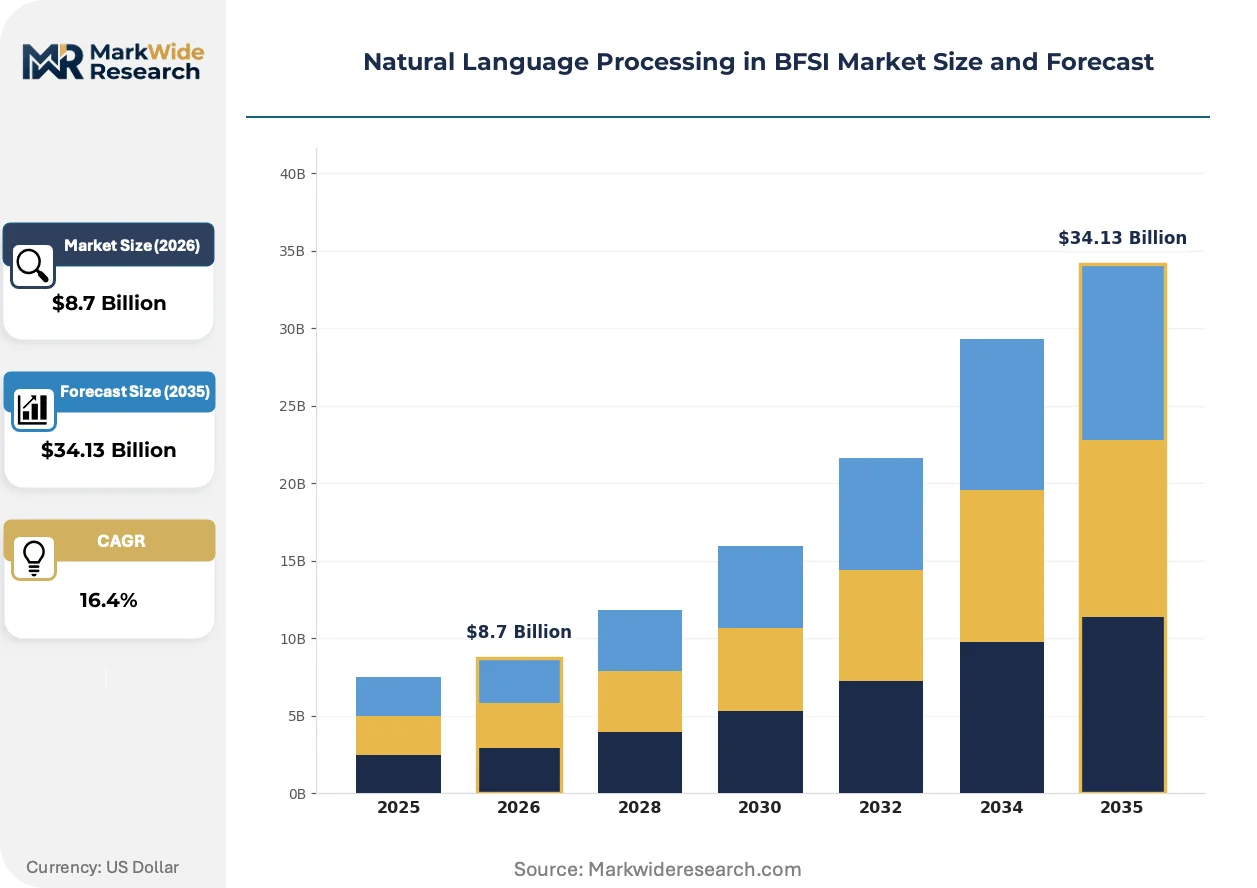
Market Dynamics
The transition from rules-based chatbots to transformer-based architectures is compressing vendor margins while elevating infrastructure requirements for financial institutions. This technology shift concentrates procurement power among cloud hyperscalers and specialized GPU suppliers.
Growth Catalysts
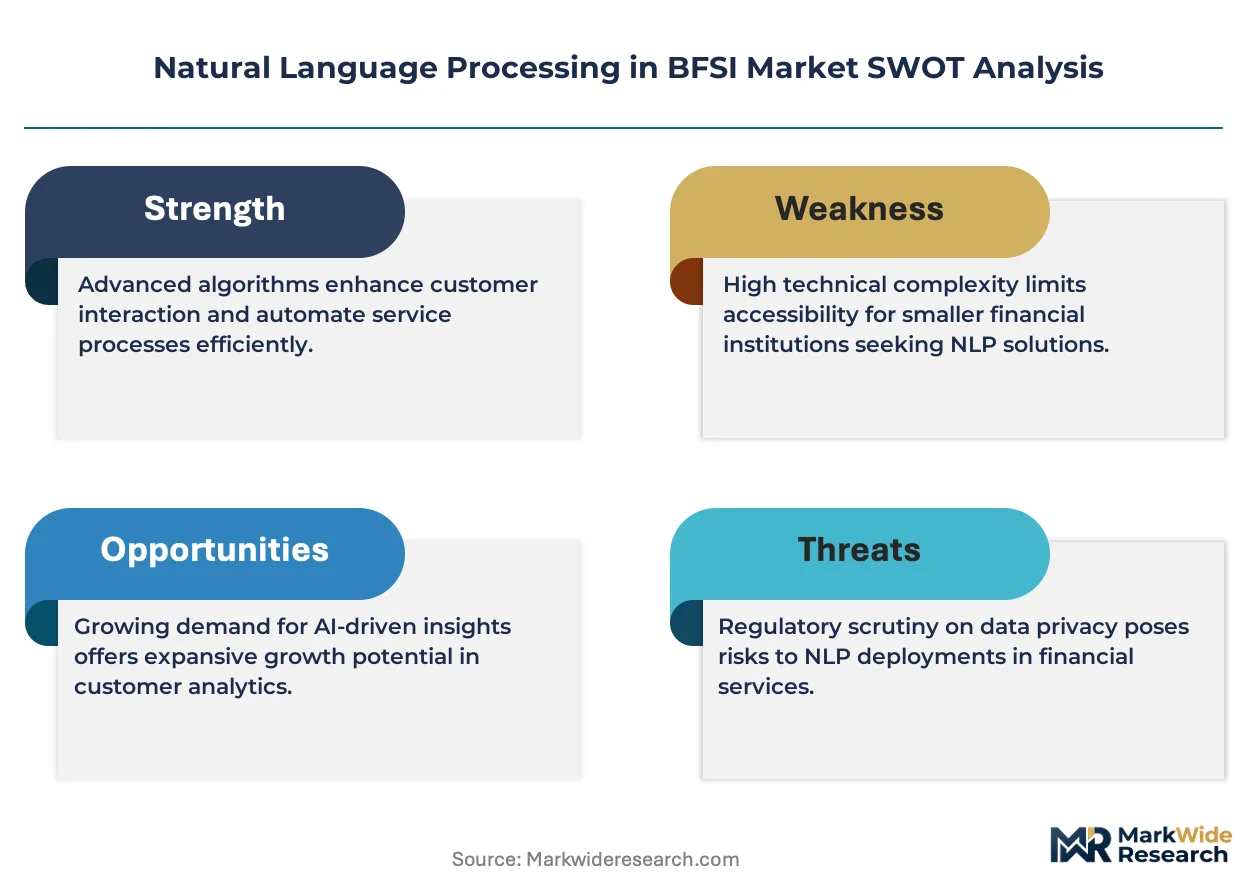
- EU AI Act compliance mandates:Credit-scoring transparency requirements are forcing banks to replace black-box NLP with interpretable transformer variants, creating replacement demand across retail lending divisions.
- Real-time fraud detection:Sub-second latency requirements for transaction monitoring are expanding deployment of edge-optimized language models in payment processing networks.
- United States institutional investment:Major financial institutions are establishing proprietary NLP centers of excellence, driving captive development of sector-specific training datasets and evaluation benchmarks.
Market Restraints
- GPU supply concentration:Training pipeline capacity depends on NVIDIA's foundry allocations, creating procurement bottlenecks for mid-tier financial institutions without cloud-scale purchasing power.
- Regulatory fragmentation:Jurisdictional divergence between SEC disclosure standards and EU AI Act conformity requirements forces maintenance of region-specific model variants, elevating compliance costs.
- Legacy system integration:Core banking infrastructure built on COBOL and mainframe architectures resists API-native NLP deployment, extending implementation timelines.
Strategic Opportunities
- Insurance claims processing automation:HIPAA-aligned voice-to-text pipelines for claimant interviews remain underpenetrated relative to banking applications, offering expansion vectors for specialized vendors.
- Regulatory document parsing:The EU AI Act's documentation requirements for algorithmic decision-making are creating demand for automated compliance report generation tools.
- Conversational AI for wealth management:High-net-worth advisory segments show latent demand for multilingual, context-aware client interaction platforms beyond current retail banking deployments.
Industry Challenges
- Specialized talent scarcity:Financial NLP engineering requires hybrid expertise in quantitative finance, computational linguistics, and regulatory compliance, with acute shortages in model interpretability and bias auditing functions.
- Training data access restrictions:Proprietary customer communication datasets are siloed across institutions, limiting fine-tuning quality for sector-specific language models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Language Processing in BFSI Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Sentiment Analysis, Chatbots, Fraud Detection, Risk Management End User: Banks, Insurance Companies, Investment Firms, Credit Unions Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services Solution: Text Analytics, Speech Recognition, Machine Translation, Semantic Analysis |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC, Amazon Web Services, Intel Corporation, NVIDIA Corporation, Accenture PLC, Salesforce Inc., Nuance Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Language Processing in BFSI Market Shifts & Advancements
Transformer architectures are displacing earlier neural approaches across document-intensive BFSI workflows. This shift reconfigures competitive positioning toward infrastructure control and specialized compliance tooling.
Retrieval-augmented generation is migrating from experimental deployments to production document analysis pipelines. Commercial banking divisions handling trade finance documentation are adopting RAG architectures to ground LLM outputs in verified regulatory texts. This migration is compressing error rates in sanctions screening and letter-of-credit verification while elevating compute requirements for real-time retrieval indexing.
The EU AI Act imposes conformity assessment requirements on credit-scoring algorithms deployed in consumer-facing decisions. Financial institutions must document model provenance, bias testing protocols, and human oversight mechanisms before deployment. Retail banking units across Germany, France, and Italy are restructuring NLP procurement to prioritize vendors with pre-certified compliance modules.
Enterprise buyers are consolidating vendor relationships around integrated platform providers rather than point solutions. Procurement committees at major financial institutions now evaluate NLP capabilities within broader cloud service contracts, displacing standalone chatbot vendors. This pattern is most visible in the United States, where Azure OpenAI and comparable offerings anchor multi-year enterprise agreements spanning infrastructure, model access, and compliance tooling.
Natural Language Processing in BFSI Market Segmentation
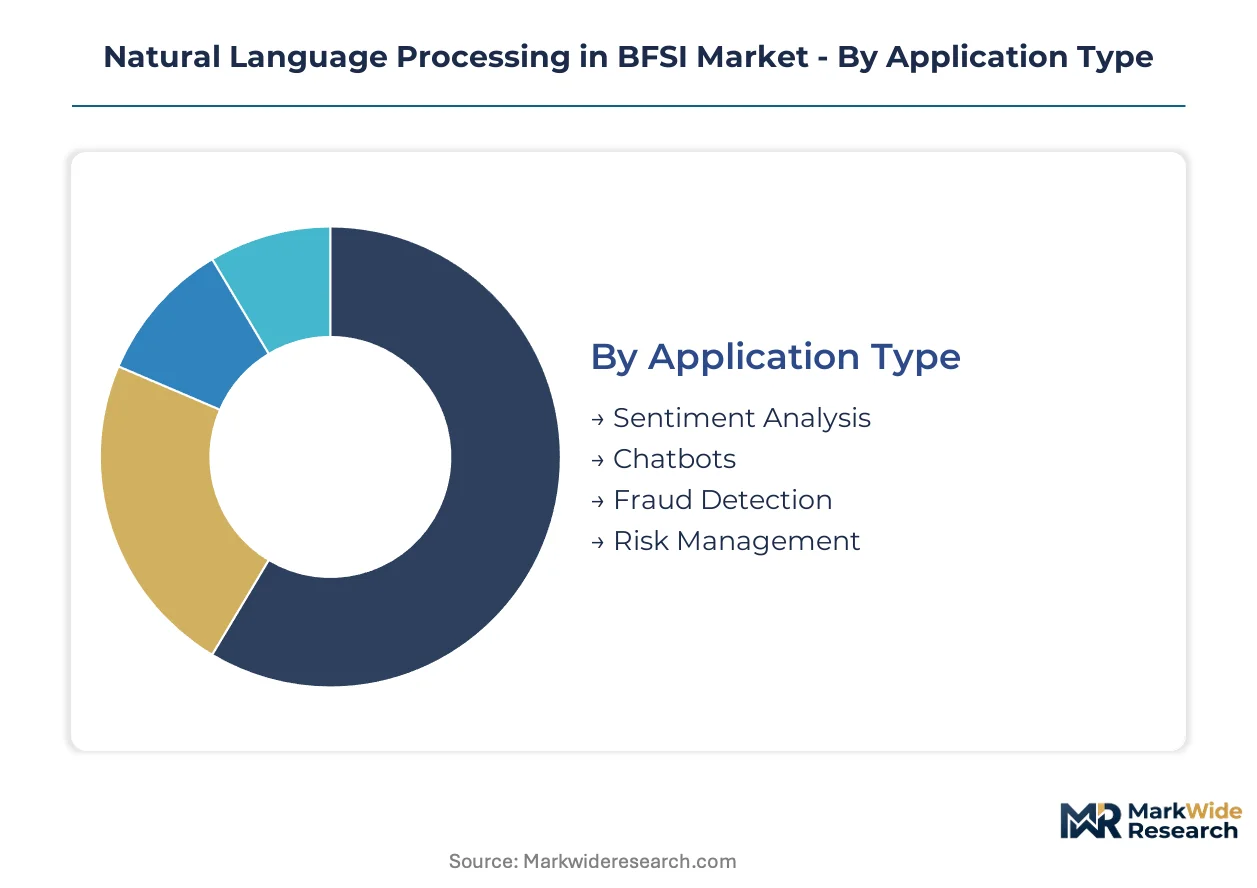
Segmentation in the Natural Language Processing in BFSI Market reveals divergent procurement patterns across application maturity tiers and infrastructure requirements. Financial institutions prioritize interpretable architectures for regulated decisions while deploying black-box variants in low-risk automation workflows.
Application Type:
Application type captures functional purpose within banking, insurance, and investment workflows, distinguishing mature margin pools from emerging deployment categories.
- Sentiment Analysis:Algorithms parse market commentary, earnings transcripts, and social media feeds to quantify investor mood and price movement signals. Trading desks at investment firms in the United States deploy these tools for real-time positioning, constrained by SEC disclosure requirements for AI-driven investment advice.
- Chatbots:Conversational AI platforms automate customer service interactions across retail banking channels. German and French retail banking divisions are accelerating procurement of transformer-based variants to meet EU AI Act transparency mandates for consumer-facing decisions.
- Fraud Detection:Sub-second latency models flag anomalous transaction patterns in payment networks.
- Risk Management:Document parsing for credit underwriting and portfolio stress testing.
Sentiment analysis holds installed capacity. Chatbots are rotating up the share rankings.
End User:
End user segmentation tracks organizational type and regulatory exposure, with procurement authority concentrating among institutions with captive infrastructure budgets.
- Banks:Universal and retail banking divisions deploy NLP across customer service automation, compliance documentation, and real-time fraud monitoring. United States-based institutions are establishing proprietary NLP centers of excellence, driving demand for specialized talent in model interpretability and bias auditing.
- Insurance Companies:Claims processing automation and voice-to-text pipelines for claimant interviews dominate deployment. HIPAA-aligned safeguards govern these workflows, creating procurement friction for vendors lacking healthcare-adjacent compliance certifications.
- Investment Firms:Sentiment analysis for trading desks and automated research report generation.
- Credit Unions:Cost-constrained deployments favoring managed service models over captive infrastructure.
Banks command procurement volume. Insurance companies are climbing the fastest as claims automation accelerates.
Deployment Model:
Deployment model reflects infrastructure control versus operational flexibility trade-offs, with elasticity requirements driving cloud migration.
- Cloud-Based:Elastic scaling supports seasonal query volume spikes in retail banking customer service operations. Major United States financial institutions are consolidating procurement around Azure OpenAI and comparable hyperscaler offerings, displacing standalone chatbot vendors.
- Hybrid:Sensitive data remains on-premises while compute-intensive training leverages cloud resources. German retail banking units favor this architecture to satisfy EU AI Act data localization preferences while accessing GPU supply for model fine-tuning.
- On-Premises:Legacy core banking integration for COBOL-resistant institutions.
- Managed Services:Outsourced operations for mid-tier institutions lacking specialized NLP engineering talent.
Cloud-based deployments hold installed capacity. Hybrid architectures are gaining share fastest among EU-regulated institutions.
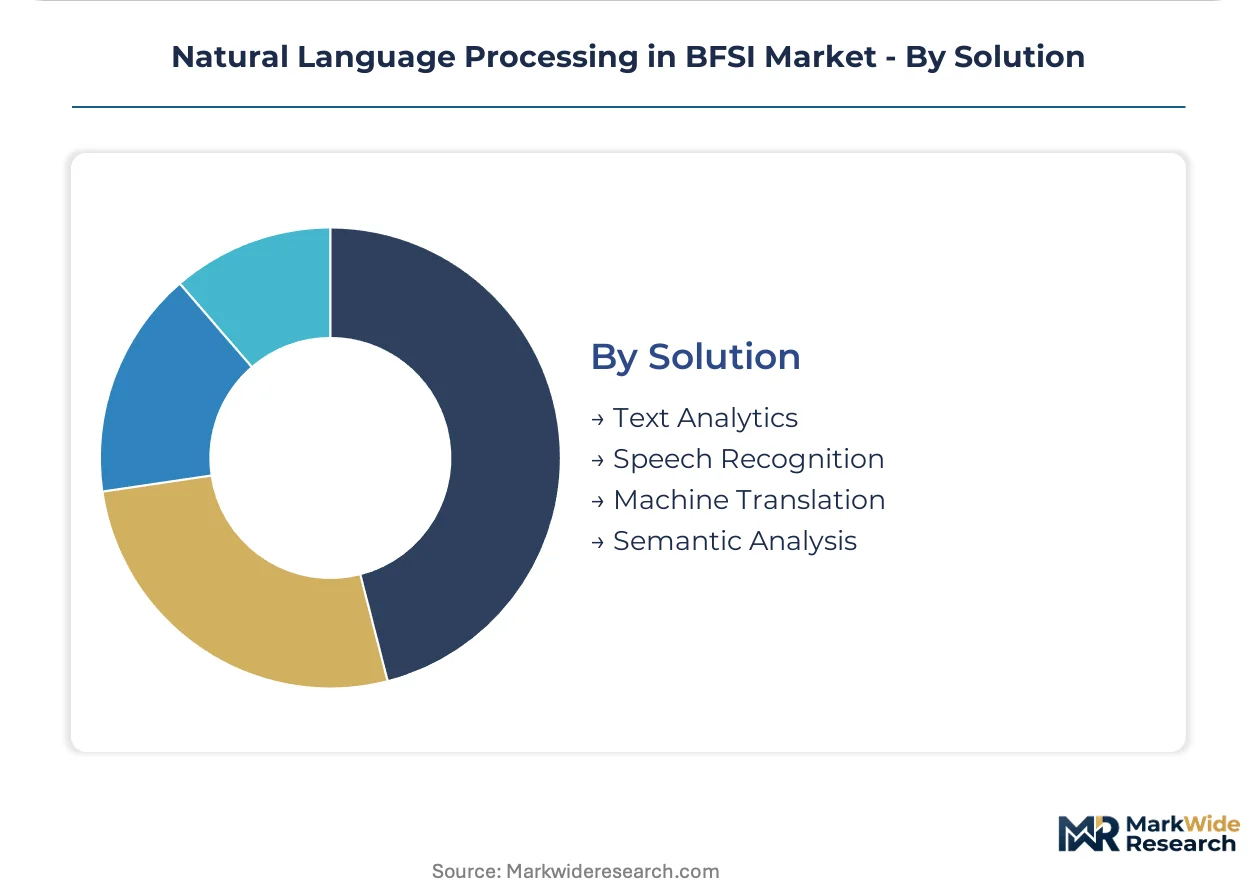
Solution:
Solution type distinguishes input modalities and analytical depth, with procurement committees evaluating capabilities within broader platform contracts.
- Text Analytics:Unstructured document processing for regulatory filings, contracts, and customer communications. Commercial banking divisions handling trade finance documentation are adopting retrieval-augmented generation architectures to ground outputs in verified regulatory texts.
- Speech Recognition:Voice-to-text pipelines for insurance claimant interviews and wealth management client interactions. HIPAA-aligned deployments remain underpenetrated relative to banking applications.
- Machine Translation:Multilingual client communication platforms for cross-border banking.
- Semantic Analysis:Deep meaning extraction for legal document interpretation and compliance verification.
Text analytics holds installed capacity. Speech recognition is rotating up the share rankings as voice channel automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based financial institutions export NLP-enabled fraud detection and compliance automation solutions to banking partners across Canada and Mexico, establishing a North American corridor for real-time transaction monitoring technology.
United States
Major banks including JPMorgan Chase and Bank of America operate proprietary NLP centers of excellence in New York and Charlotte, driving captive development of sector-specific training datasets. SEC disclosure standards for AI-driven investment advice compel vendors to document model provenance and bias testing protocols. The San Francisco Bay Area concentrates venture-backed fintechs deploying transformer architectures for wealth management client interactions.
Germany
Retail banking divisions at Deutsche Bank and Commerzbank accelerate procurement of interpretable transformer variants to satisfy EU AI Act transparency mandates for credit-scoring decisions. The Federal Financial Supervisory Authority enforces conformity assessment requirements on algorithmic consumer-facing decisions. Frankfurt's financial district hosts specialized compliance vendors developing automated documentation tools for model provenance tracking.
United Kingdom
HSBC and Barclays deploy sentiment analysis platforms for trading desk operations, constrained by Financial Conduct Authority guidelines on AI-generated investment research. The Prudential Regulation Authority coordinates with the Bank of England on systemic risk monitoring using natural language processing of regulatory filings. London's Square Mile clusters hedge funds and asset managers purchasing real-time market commentary parsing tools.
India
State Bank of India and HDFC Bank expand conversational AI deployments for vernacular-language customer service across tier-2 and tier-3 cities. The Reserve Bank of India issues guidance on algorithmic transparency for digital lending platforms. Mumbai's Bandra-Kurla Complex concentrates fintech startups developing low-latency fraud detection models for payment network integration.
Singapore
DBS Bank and OCBC deploy multilingual NLP platforms for cross-border trade finance documentation processing. The Monetary Authority of Singapore mandates fairness and explainability standards for AI-driven credit decisions under its FEAT principles. The Marina Bay financial district hosts regional headquarters of global technology vendors serving ASEAN banking clients.
Natural Language Processing in BFSI Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers that bundle infrastructure, model access, and compliance tooling into multi-year enterprise contracts. Hyperscale cloud operators and specialized GPU suppliers capture disproportionate procurement power as financial institutions abandon standalone chatbot vendors. Three archetypes dominate: infrastructure-anchored hyperscalers, compliance-specialized legacy vendors, and GPU supply chain controllers. Competitive moves concentrate on strategic partnerships between cloud platforms and financial institutions, alongside vertical integration into sector-specific training data assets.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services exemplify platform consolidation strategies that embed NLP capabilities within broader cloud service agreements. IBM Corporation occupies a position representing legacy vendors pivoting toward specialized compliance modules for regulatory document parsing. NVIDIA Corporation anchors the GPU supply chain archetype, controlling foundry allocations that determine training pipeline capacity for sector-specific model development across the industry.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC |
| Amazon Web Services |
| Intel Corporation |
| NVIDIA Corporation |
| Accenture PLC |
| Salesforce Inc. |
| Nuance Communications |
| Others |
Supply & Pricing Matrix
GPU foundry undercapacity across Taiwan and South Korea is squeezing training pipeline availability for financial institutions, forcing buyers into long-term reservation contracts while elevating compute costs for real-time NLP deployments. This utilization dynamic concentrates pricing power with NVIDIA and TSMC, compelling mid-tier banks to accept managed service premiums or cede infrastructure control to hyperscaler platforms.
Pricing Analysis
Transformer-generation pricing gaps separate legacy rules-based chatbot contracts from retrieval-augmented generation deployments and emerging multimodal architectures. SaaS-tiered subscription models dominate, with premium tiers commanding differentiation through EU AI Act pre-certification and sub-second latency guarantees. Price differentiation rests on compliance automation depth and GPU allocation priority. Cost compression in standard-tier offerings is intensifying as Microsoft and Amazon bundle NLP capabilities into enterprise cloud agreements. Credit unions and regional banks exhibit acute price sensitivity, whereas universal banks prioritize compliance-grade SLAs over unit economics.
Supply Chain Analysis
Contract manufacturing concentration at TSMC and Samsung Foundry anchors GPU supply for NLP training clusters, with NVIDIA controlling allocation priority through direct foundry partnerships. Geographic supply concentration centers on Taiwan, South Korea, and the United States for advanced node production. Raw material dependencies include high-bandwidth memory from SK Hynix and Micron, specialized substrates from Ibiden and Shinko, and rare earth elements for magnetic components in data center infrastructure. Single-source vulnerability in CoWoS packaging capacity presents acute disruption risk for financial institutions scaling transformer deployments. Distribution runs through direct hyperscaler partnerships and tier-one systems integrators serving regulated banking clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source foundation models threaten incumbent NLP vendors with commoditization pressure, forcing proprietary platform providers to defend through compliance integration and sector-specific fine-tuning assets.
For Market Incumbents: Entrench market position through captive development of EU AI Act-certified model variants and exclusive data partnerships with tier-one banks. Acquire specialized talent in bias auditing and model interpretability to differentiate from hyperscaler commodity offerings. Defensive consolidation around compliance tooling creates moats against open-source substitution. For New Entrants and Emerging Players: Mid-tier insurance carriers in Germany and France represent the most penetrable entry point, with HIPAA-aligned voice-to-text pipelines for claims automation remaining underpenetrated relative to banking saturation. Regulatory document parsing for EU AI Act compliance reporting offers a second white-space vector. Go-to-market execution should anchor on pre-certified compliance modules that accelerate procurement cycles at EU-regulated institutions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GPU-dependent infrastructure layers, favoring asset-light compliance software vendors over hardware-heavy training operations. Long-term viability concentrates in firms controlling sector-specific evaluation benchmarks and proprietary fine-tuning datasets. Acquisition target archetype: specialized vendors with EU AI Act pre-certification and existing deployments at Deutsche Bank, Commerzbank, or BNP Paribas. Monitor NVIDIA foundry allocation announcements as the critical inflection signal for training pipeline capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certified modules accelerate procurement at Deutsche Bank and Commerzbank. |
| Retrieval-Augmented Generation Deployment | RAG architectures compress error rates in sanctions screening at HSBC trade finance. |
| GPU Supply Reservation Agreements | Long-term NVIDIA allocations secure training capacity for JPMorgan's NLP center of excellence. |
| Proprietary Dataset Development | Captive sector-specific corpora differentiate from open-source foundation model commoditization. |
| Hybrid Cloud Architecture Expansion | German retail banks favor on-premise data localization with cloud burst capacity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with NLP engineering directors, compliance officers at EU-regulated banks, GPU procurement leads, and cloud platform specialists; and secondary validation against SEC AI disclosure filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and RBI algorithmic transparency circulars. Bottom-up deployment estimates across application types triangulated with top-down infrastructure spending analysis from major financial institutions.
Forecast inputs incorporated transformer architecture migration timelines, EU AI Act enforcement phase-ins, and GPU foundry capacity expansion schedules across the analysis window. Segmentation dimensions modeled include application maturity tier, deployment model elasticity requirements, end-user regulatory exposure, and solution modality. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure constraint boundaries. Industry-specific inputs included sub-second latency requirements for fraud detection and HIPAA-aligned safeguard implementation costs for insurance voice pipelines.
Stress conditions across GPU supply disruption severity, EU AI Act enforcement acceleration, and open-source model capability advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscaler pricing discipline and regulatory fragmentation persistence. Quarterly review of NVIDIA foundry allocation announcements and EU AI Act conformity assessment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Computer Vision Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
Enterprise LLM Market