
 Artificial Intelligence (AI) in Social Media Market | 2026-2036
Artificial Intelligence (AI) in Social Media Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Social Media Market Analysis
Platform bundling of generative AI with analytics dashboards is pivoting how marketing agencies evaluate vendor contracts. Google LLC leverages its search-integrated advertising stack to anchor enterprise clients seeking unified campaign intelligence. Meta Platforms Inc. competes through native AI tools embedded across Instagram, Facebook, and Threads, sustaining high engagement monetization. Salesforce Inc. differentiates by weaving Einstein GPT into its social studio, extending CRM data directly into content scheduling workflows.
Artificial Intelligence in Social Media encompasses machine learning models, natural language processing engines, and computer vision systems trained on user-generated content to automate creation, moderation, and targeting decisions across digital platforms. These systems process behavioral signals, visual metadata, and conversational patterns in real time to serve personalized feeds and advertisements. Cloud-based deployment leads adoption among social media platforms requiring elastic compute for viral traffic spikes, while sentiment analysis applications capture concentrated margin pools from reputation-sensitive corporations. Predictive modeling functionality is growing fastest as brands demand forecasted engagement metrics prior to campaign commitment.
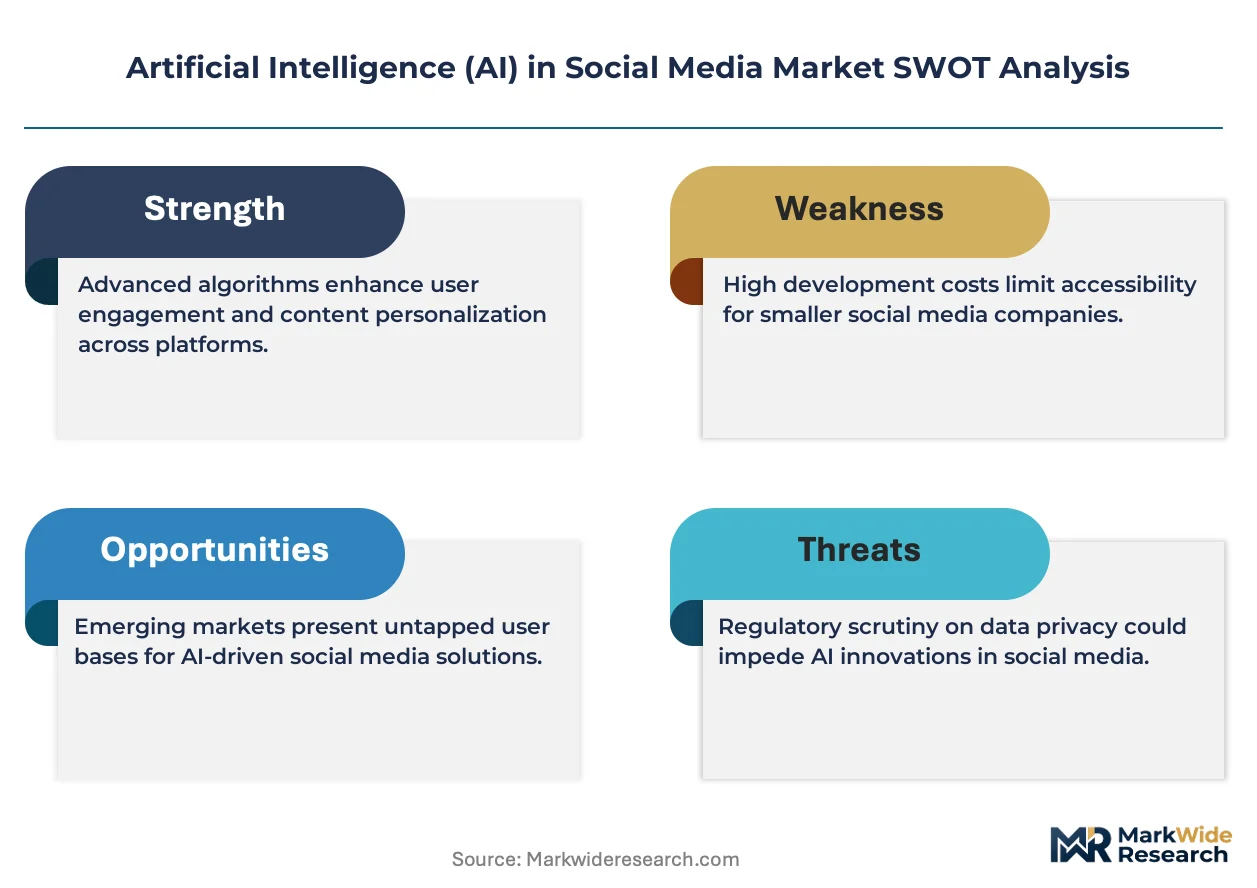
The EU AI Act mandates risk classification for algorithmic content recommendation systems, forcing platform operators to document training data provenance and human oversight protocols. The US Federal Trade Commission scrutinizes AI-enabled ad targeting for discriminatory exclusion practices, tightening consent frameworks. China's SAMR enforces algorithmic registration for domestic platforms, fragmenting compliance architectures. Stakeholders must monitor which regulatory jurisdiction's transparency standards become the de facto benchmark for cross-border tool deployment.
Market Dynamics
Enterprise marketing teams now demand predictive engagement metrics before committing campaign budgets, compressing vendor evaluation cycles and forcing platform operators to expose algorithmic performance data previously treated as proprietary.
Growth Catalysts
- EU AI Act compliance mandates:Risk classification requirements for algorithmic content recommendation systems create documented demand for transparency tools and audit-ready infrastructure among platform operators.
- Cloud-native architecture:Elastic compute provisioning enables social media platforms to absorb viral traffic spikes without service degradation, removing infrastructure barriers to AI deployment at scale.
- Sentiment analysis procurement:Reputation-sensitive corporations in financial services and consumer goods are purchasing specialized moderation and brand safety modules as standalone software categories.
Market Restraints
- GPU supply concentration:Training and inference workloads for large language models depend on semiconductor fabrication capacity concentrated in Taiwan and South Korea, creating input cost volatility and allocation uncertainty.
- Cross-border data friction:China's SAMR algorithmic registration requirements fragment compliance architectures, forcing multinational platforms to maintain separate technical stacks for domestic operations.
- Human-in-the-loop costs:EU AI Act documentation of training data provenance and oversight protocols requires persistent staffing layers that resist full automation.
Strategic Opportunities
- Small and medium enterprise penetration:Mid-market brand advertisers in India and Brazil remain underserved by current predictive modeling offerings priced for Fortune 500 procurement thresholds.
- Multimodal content generation:Convergence of computer vision and natural language processing enables automated video scripting and visual asset production from text briefs.
- CRM-social integration:Distribution through existing customer data platforms allows AI content tools to bypass standalone procurement cycles and embed within established enterprise workflows.
Industry Challenges
- MLOps talent scarcity:Platform operators and vendor engineering teams face acute shortages of practitioners capable of maintaining production-grade recommendation systems at billion-user scale.
- Legacy stack integration:Enterprise marketing departments struggle to connect modern AI content tools with decades-old campaign management databases and approval workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Social Media Market |
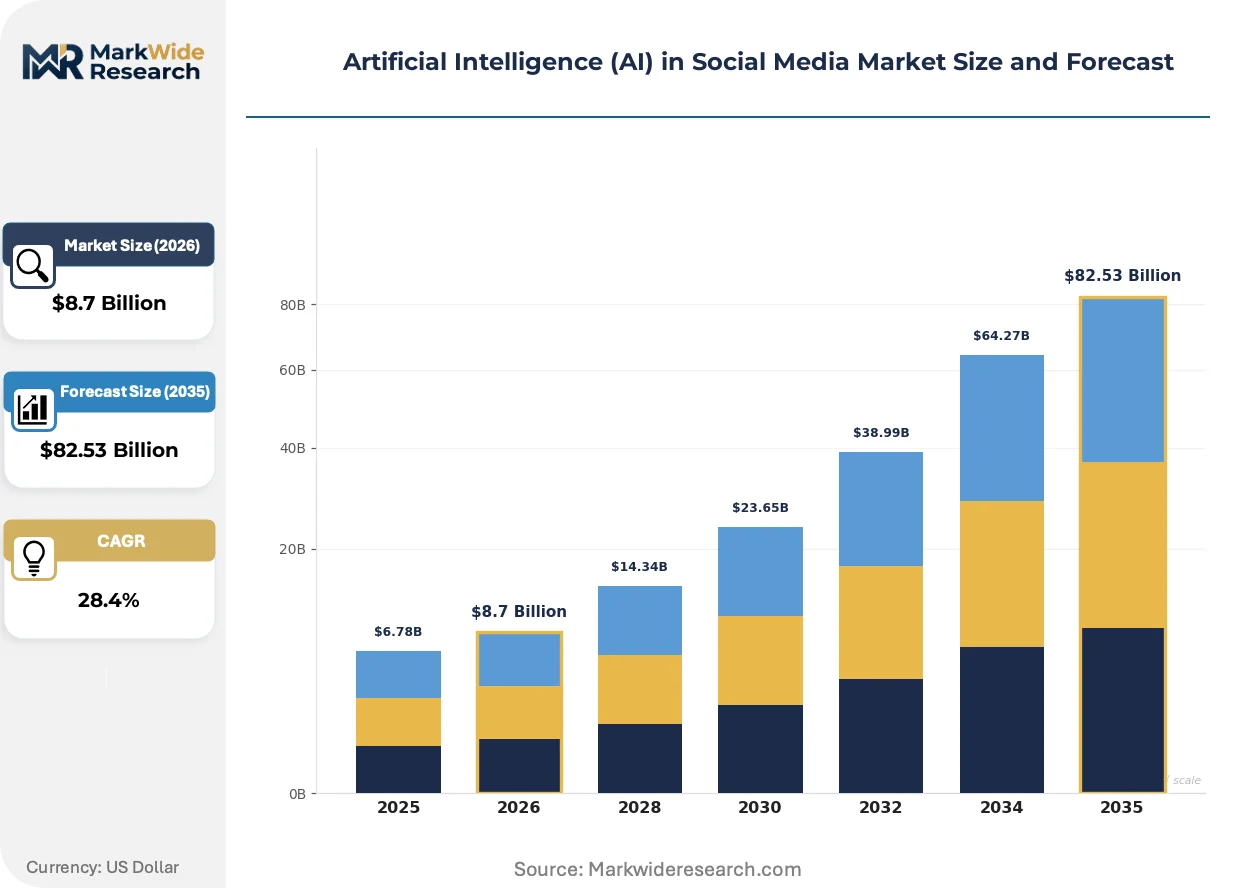
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Content Creation, Sentiment Analysis, Ad Targeting, User Engagement End User: Small Businesses, Corporations, Marketing Agencies, Social Media Platforms Functionality: Chatbots, Image Recognition, Data Analytics, Predictive Modeling Deployment: Cloud-based, On-premise, Hybrid Solutions, Managed Services |
| Companies Covered | Google LLC, Meta Platforms Inc., Microsoft Corporation, Amazon Web Services Inc., IBM Corporation, Adobe Systems Incorporated, Salesforce Inc., Sprinklr Inc., Sprout Social Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Social Media Market Emerging Trajectories
Generative AI capabilities are migrating from standalone products into embedded platform features, altering how marketing technology budgets are allocated and which vendor relationships survive consolidation.
Multimodal foundation models trained on combined text, image, and video corpora are consolidating creative production workflows previously fragmented across specialized tools. Brand creative teams at consumer packaged goods and entertainment studios are adopting these systems for rapid asset variation and localization. This consolidation is compressing the addressable market for point-solution design software vendors while expanding the strategic importance of training data licensing.
The EU AI Act's risk-tier classification system is forcing documented accountability for algorithmic amplification decisions. Platform operators must now maintain technical documentation and human oversight protocols for content recommendation engines above defined scale thresholds. Social media publishers with EU user bases exceeding 45 million are responding by establishing dedicated algorithmic transparency divisions and pre-emptive audit relationships with notified bodies.
Marketing procurement departments are unbundling creative agency retainers to source AI-generated content directly through platform-native tools. Mid-sized brand advertisers in the United States and United Kingdom are replacing traditional production contracts with self-service generation interfaces and spot-purchased human refinement. This pattern is most visible in retail and direct-to-consumer verticals where campaign velocity exceeds agency turnaround capacity.
Artificial Intelligence (AI) in Social Media Market Segmentation
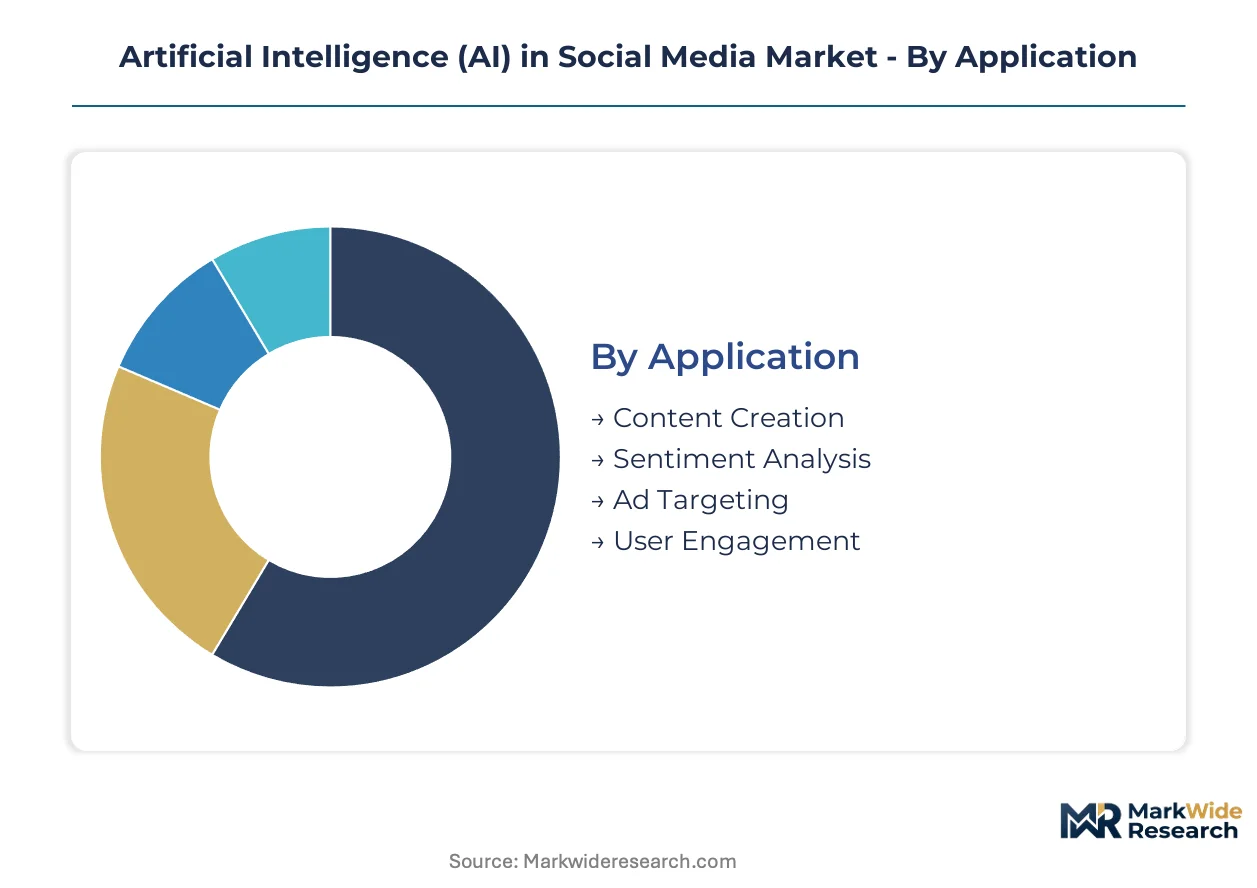
AI in social media fragments across four critical dimensions: how tools are applied, who deploys them, what functions they perform, and where infrastructure resides. Each axis reveals divergent margin profiles and vendor competitive intensity.
Application:
Volume concentrates in automation-heavy workflows, while premium pricing attaches to predictive and analytical use cases requiring specialized model training.
- Content Creation:Generative systems produce text, image, and video assets from natural language prompts. Marketing agencies in the United States purchase these tools to compress production cycles for high-velocity retail campaigns.
- Sentiment Analysis:Natural language processing engines classify emotional valence across user-generated posts and comments. Financial services firms in London and Singapore deploy these systems for real-time reputation monitoring during earnings windows.
- Ad Targeting:Behavioral prediction models segment audiences for programmatic placement.
- User Engagement:Recommendation algorithms personalize feed ranking and notification timing.
Today's leader: Content Creation. Tomorrow's challenger: Sentiment Analysis.
End User:
Procurement scale separates enterprise platforms with billion-user inference loads from mid-market advertisers seeking turnkey solutions.
- Social Media Platforms:Native operators run custom model training at massive scale, maintaining proprietary data moats and direct hardware procurement relationships with cloud hyperscalers.
- Corporations:Brand advertisers integrate AI tools through existing martech stacks, prioritizing CRM connectivity and compliance documentation for EU AI Act adherence.
- Marketing Agencies:Service firms license white-label generation tools to maintain margin on creative retainers.
- Small Businesses:Self-service interfaces with per-credit pricing dominate this tier.
Platform operators command the largest absolute spend. Corporate in-house teams are climbing the fastest.
Functionality:
Technical maturity varies sharply: computer vision and statistical forecasting carry decades of production heritage, while large language interfaces remain deployment-intensive.
- Predictive Modeling:Statistical and neural forecasting engines project engagement, churn, and conversion probabilities from historical behavioral sequences. Enterprise advertisers in Germany and Japan demand these capabilities for budget allocation decisions.
- Image Recognition:Convolutional and transformer-based vision systems classify visual content for moderation and search indexing.
- Data Analytics:Aggregation and visualization layers transform raw platform signals into campaign performance dashboards.
- Chatbots:Conversational interfaces handle customer service and lead qualification workflows.
Predictive Modeling captures premium pricing. Chatbots face commoditization pressure from open-source alternatives.
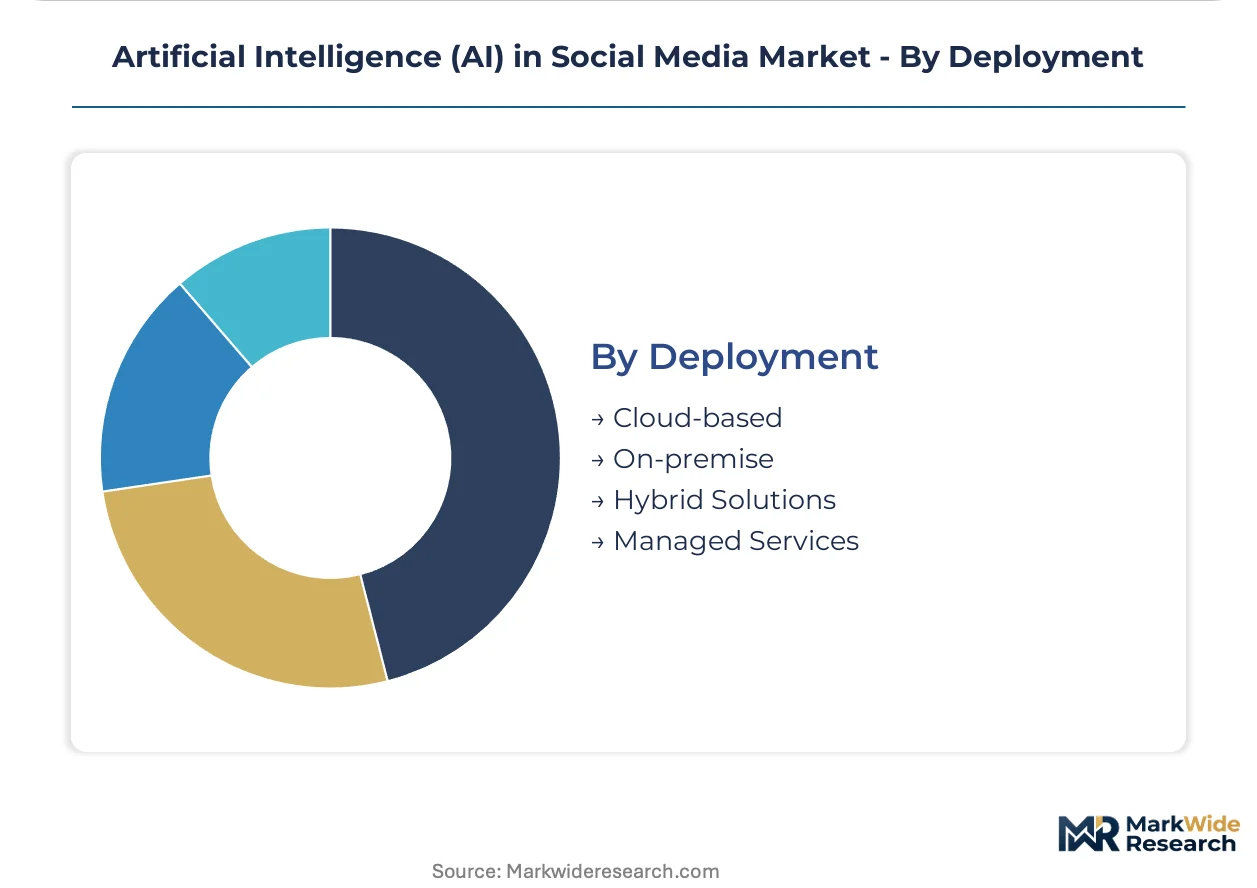
Deployment:
Infrastructure location determines latency, compliance jurisdiction, and capital intensity for model training versus inference.
- Cloud-based:Elastic compute provisioning enables viral traffic absorption without capacity planning. Social media publishers across Brazil and India default to this model for cost flexibility.
- Hybrid Solutions:Split architectures run sensitive inference locally while tapping cloud resources for training workloads. Regulated industries in Switzerland and Australia prefer this pattern for data residency compliance.
- On-premise:Captive hardware installations serve classified or latency-critical applications.
- Managed Services:Third-party operators handle model maintenance and infrastructure operations.
Cloud-based deployment holds dominant share. Hybrid Solutions show steepest expansion trajectory as data localization requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The artificial intelligence in social media industry traces its commercial origins to Silicon Valley, where platform-native recommendation engines first demonstrated scalable monetization of behavioral prediction. From this foundation, development radiated through three distinct regulatory jurisdictions, each now imposing divergent compliance architectures on algorithmic systems.
United States
Enterprise marketing teams in New York and Los Angeles drive procurement of predictive engagement tools, with brand advertisers demanding forecasted metrics before budget commitment. The FTC scrutinizes AI-enabled ad targeting for discriminatory exclusion practices, tightening consent frameworks for behavioral data collection. San Francisco Bay Area clusters anchor hyperscaler development of foundation models serving billion-user inference loads.
Germany
Automotive and industrial conglomerates in Stuttgart and Munich purchase sentiment analysis modules for reputation monitoring during product launch windows. The EU AI Act mandates risk classification for algorithmic content recommendation systems, forcing documentation of training data provenance and human oversight protocols. Berlin hosts emerging transparency tool vendors serving publishers with EU user bases exceeding 45 million.
China
Domestic platform operators in Beijing and Shenzhen maintain separate technical stacks to satisfy SAMR algorithmic registration requirements, fragmenting compliance architectures for multinational publishers. Shanghai clusters concentrate computer vision development for moderation systems processing user-generated video at scale. The dual carbon goals pressure data center operators to optimize inference workload energy efficiency.
United Kingdom
Financial services firms in London deploy natural language processing engines for real-time reputation monitoring during earnings windows. The Information Commissioner's Office enforces GDPR-aligned transparency requirements for automated decision-making in content ranking. Manchester and Edinburgh emerging as secondary hubs for AI marketing technology implementation serving mid-market brand advertisers.
India
Mid-market brand advertisers in Mumbai and Bangalore remain underserved by predictive modeling offerings priced for Fortune 500 procurement thresholds. The Digital Personal Data Protection Act establishes consent frameworks for behavioral targeting, though enforcement mechanisms remain nascent. Hyderabad clusters concentrate engineering talent for cloud-native AI tool development serving Southeast Asian platform operators.
Artificial Intelligence (AI) in Social Media Market Vendor Landscape
Premium-margin players sit above commodity-margin players across data moat depth and inference scale, with hyperscaler-affiliated platforms commanding proprietary behavioral datasets that resist replication. The vendor base stratifies into three tiers: native platform operators with captive infrastructure, enterprise software vendors integrating AI into existing martech stacks, and point-solution specialists facing consolidation pressure. Dominant competitive moves include strategic partnerships with cloud hyperscalers for elastic compute provisioning and portfolio diversification into multimodal content generation capabilities.
Within the hyperscaler-affiliated tier, Google LLC and Meta Platforms Inc. occupy positions defined by search-integrated advertising stacks and native AI tools embedded across social properties respectively. Salesforce Inc. represents the enterprise software archetype, weaving generative capabilities into CRM-connected workflows. Microsoft Corporation anchors the cloud infrastructure vector, supplying foundation model access and compute provisioning to downstream application vendors. These three exemplify divergent strategic postures: platform-native monetization, enterprise workflow integration, and infrastructure layer capture.
| Leading Market Players |
|---|
| Google LLC |
| Meta Platforms Inc. |
| Microsoft Corporation |
| Amazon Web Services Inc. |
| IBM Corporation |
| Adobe Systems Incorporated |
| Salesforce Inc. |
| Sprinklr Inc. |
| Sprout Social Inc. |
| Others |
Supply Flow & Price Mechanics
MLOps talent scarcity in the San Francisco Bay Area and Bangalore widens pricing spreads between premium-tier predictive modeling suites and economy-grade content automation tools, compressing margins for mid-market vendors unable to command specialized labor premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates vendor offerings, with enterprise-grade predictive engagement tools commanding substantial premiums over self-service generation interfaces. Price differentiation hinges on model training data exclusivity and EU AI Act compliance documentation depth. Pricing pressure stems from open-source foundation model commoditization eroding standalone tool value. Small businesses exhibit highest price sensitivity, while Fortune 500 procurement thresholds absorb premium tiers without volume negotiation.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea constrain GPU fabrication capacity, creating allocation bottlenecks for training and inference hardware. Semiconductor supply draws from TSMC foundries in Hsinchu and Samsung facilities in Pyeongtaek, with NVIDIA holding dominant accelerator design share. Single-source vulnerability in advanced node fabrication exposes cost volatility. Distribution runs through cloud hyperscaler procurement channels rather than direct hardware resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as enterprise procurement shifts toward audit-ready transparency infrastructure over raw generation capability.
For Market Incumbents: Anticipate regulatory fragmentation forcing redundant compliance architectures across EU AI Act, SAMR, and FTC jurisdictions. Defend position by deepening proprietary data moats through exclusive platform behavioral signals. Prioritize certification investment for algorithmic transparency tooling to capture premium procurement from reputation-sensitive financial services buyers. For New Entrants and Emerging Players: Mid-market brand advertisers in India and Brazil remain underserved by predictive modeling offerings priced for Fortune 500 thresholds. Capture share through localized deployment partnerships with domestic cloud providers. Pursue white-label licensing to marketing agencies seeking margin preservation on creative retainers. For Investors and Strategic Acquirers: Valuations sit cheapest among point-solution sentiment analysis vendors facing consolidation pressure from multimodal platform bundling. Long-term viability favors CRM-integrated workflow tools over standalone generation interfaces. Monitor hyperscaler capex allocation shifts as inflection indicator for downstream application vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Infrastructure | Documentation tooling captures premium procurement from publishers with 45 million-plus EU user bases. |
| Multimodal Foundation Model Integration | Converged text-image-video systems consolidate fragmented creative production workflows for CPG brands. |
| CRM-Social Workflow Embedding | Einstein GPT-style integration bypasses standalone procurement cycles through existing enterprise data platforms. |
| Hybrid Cloud Deployment Architecture | Split local-cloud configurations satisfy Swiss and Australian data residency requirements for regulated industries. |
| Algorithmic Transparency Division Formation | Dedicated audit readiness units preempt regulatory enforcement from EU notified bodies. |
Methodological Framework
Bottom-up corporate procurement modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs at social media platforms, martech procurement officers at Fortune 500 advertisers, MLOps engineering leads, and regulatory compliance directors informed demand-side assumptions. Secondary validation drew from SEC hyperscaler filings, EU AI Act implementation guidance, SAMR algorithmic registration disclosures, and cloud provider capex reports. Triangulation across these sources anchored segmentation-specific volume estimates.
Input-output matrices mapped inference workload growth against elastic compute provisioning capacity across deployment models. Segmentation dimensions modeled include application type, end-user category, functionality tier, and infrastructure location. CAGRs were derived from regression analysis of historical procurement patterns projected through the forecast horizon. Industry-specific inputs incorporated EU AI Act compliance cost premiums and GPU supply allocation constraints.
Underlying measurement precision varies by segment; cloud-based deployment and content creation applications carry tighter precision than emerging hybrid configurations. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and semiconductor fabrication expansion. Material deviation in hyperscaler capex allocation or EU AI Act audit intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
US Voice Recognition Market
Artificial Intelligence (AI)
Chatbot Market