
 Smart Personal Assistance Devices Market | 2026-2036
Smart Personal Assistance Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Personal Assistance Devices Market Analytics
Enterprise procurement of smart personal assistance devices is consolidating around large technology departments and facility-management buyers seeking unified voice platforms. Amazon leverages its Alexa for Business infrastructure to anchor commercial deployments across hospitality and healthcare settings. Google competes through deep integration with Workspace productivity suites and Android enterprise mobility. Apple differentiates via on-device processing architecture that limits data transmission to cloud servers.
Smart personal assistance devices encompass hardware-software systems that process natural-language commands through microphone arrays, edge or cloud-based NLP engines, and actuator networks to execute tasks ranging from environmental control to information retrieval. Smart speakers currently occupy the largest installed base, while wearable assistants represent the fastest-expanding category as biometric sensors merge with voice interfaces. The technology stack segments reveal that voice recognition capabilities now serve as the baseline competitive requirement, whereas machine learning personalization layers command premium positioning.
The EU AI Act, GDPR, and the US FDA's evolving guidance on software as a medical device collectively determine which voice-interaction features reach regulated environments such as clinical settings and educational institutions. China's MIIT certification framework for intelligent speech products adds another compliance gateway for manufacturers seeking access to that installed base. Stakeholders must monitor how divergent privacy-by-design mandates affect cross-border feature parity and localization costs.
Market Dynamics
Enterprise procurement of smart personal assistance devices is consolidating around unified voice platforms that integrate facility management, IT service desks, and employee productivity workflows into single-vendor ecosystems.
Growth Catalysts
- EU AI Act compliance pathways:Manufacturers achieving conformity assessment for high-risk AI systems gain preferential access to healthcare and educational procurement channels across Germany, France, and the Netherlands.
- Edge AI chip architectures:On-device natural language processing reduces latency for voice commands in manufacturing floor environments where cloud connectivity remains intermittent.
- China's MIIT intelligent speech certification:Domestic manufacturers with GB standards compliance capture government and state-owned enterprise contracts in smart city deployments.
Market Restraints
- GDPR data localization mandates:Voice biometric storage requirements force redundant infrastructure deployment, raising operational costs for cross-border service delivery.
- Semiconductor supply concentration:Advanced microphone array DSPs depend on Taiwan-based foundry capacity, creating vulnerability to geopolitical disruption.
- Acoustic interference limitations:Far-field voice recognition accuracy degrades significantly in industrial settings above 85 decibels, restricting deployment in heavy manufacturing.
Strategic Opportunities
- Rural healthcare in India:Low-literate patient populations create demand for voice-first diagnostic interfaces that bypass smartphone dependency.
- Wearable-biometric convergence:Integration of continuous glucose monitoring with voice assistants opens chronic disease management applications.
- US IRA healthcare IT incentives:Medicare reimbursement adjustments for remote patient monitoring accelerate clinical voice assistant procurement.
Industry Challenges
- Multilingual NLP engineering scarcity:Fluent low-resource language model development requires specialized linguist-technologist hybrid talent concentrated in Bangalore and Tallinn.
- FDA software-as-medical-device timelines:Clinical voice triage applications face 18-24 month premarket review cycles that compress competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Personal Assistance Devices Market |
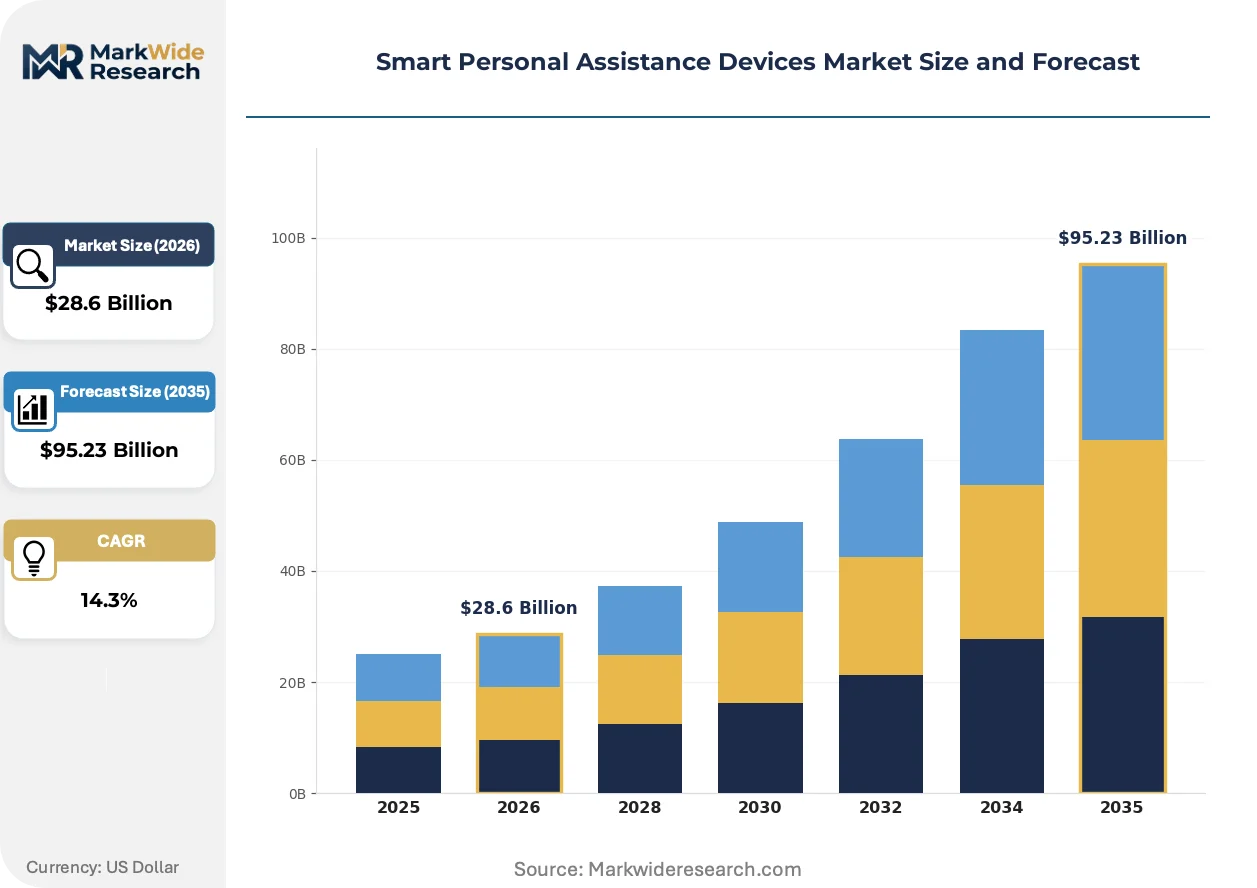
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $95.23 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Wearable Assistants, Home Automation Hubs, Virtual Assistants Technology: Natural Language Processing, Voice Recognition, Artificial Intelligence, Machine Learning End User: Households, Enterprises, Educational Institutions, Healthcare Providers Distribution Channel: Online Retail, Offline Retail, Direct Sales, E-commerce Platforms |
| Companies Covered | Amazon, Google, Apple, Microsoft, Samsung, IBM, Sonos, Baidu, Nuance Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Personal Assistance Devices Market Evolving Landscape
Voice interface architecture is consolidating around multimodal systems that fuse acoustic, visual, and haptic inputs into contextual command interpretation layers.
Multimodal sensor fusion is consolidating disparate input streams—microphone arrays, ambient light sensors, and gesture recognition—into unified inference engines. Automotive OEMs in Germany and Japan are adopting these stacks for cabin control systems. The technology is consolidating previously separate hardware categories into single-module designs that reduce bill-of-materials complexity.
REACH substance restrictions on persistent organic pollutants are forcing redesign of flexible printed circuit boards in microphone assemblies. Manufacturers must reformulate adhesives and substrates to maintain acoustic performance while eliminating restricted flame retardants. Medical device suppliers in Switzerland and the Netherlands are responding fastest, leveraging existing MDR documentation systems to accelerate material requalification.
Facility management buyers are bundling voice assistant procurement with HVAC and security system upgrades rather than acquiring standalone devices. System integrators in the United States are displacing traditional AV resellers as primary channels. This concentration is most visible in Class A commercial real estate in New York and Chicago, where landlords standardize on single-vendor smart building platforms to reduce tenant onboarding friction.
Smart Personal Assistance Devices Market Segmentation
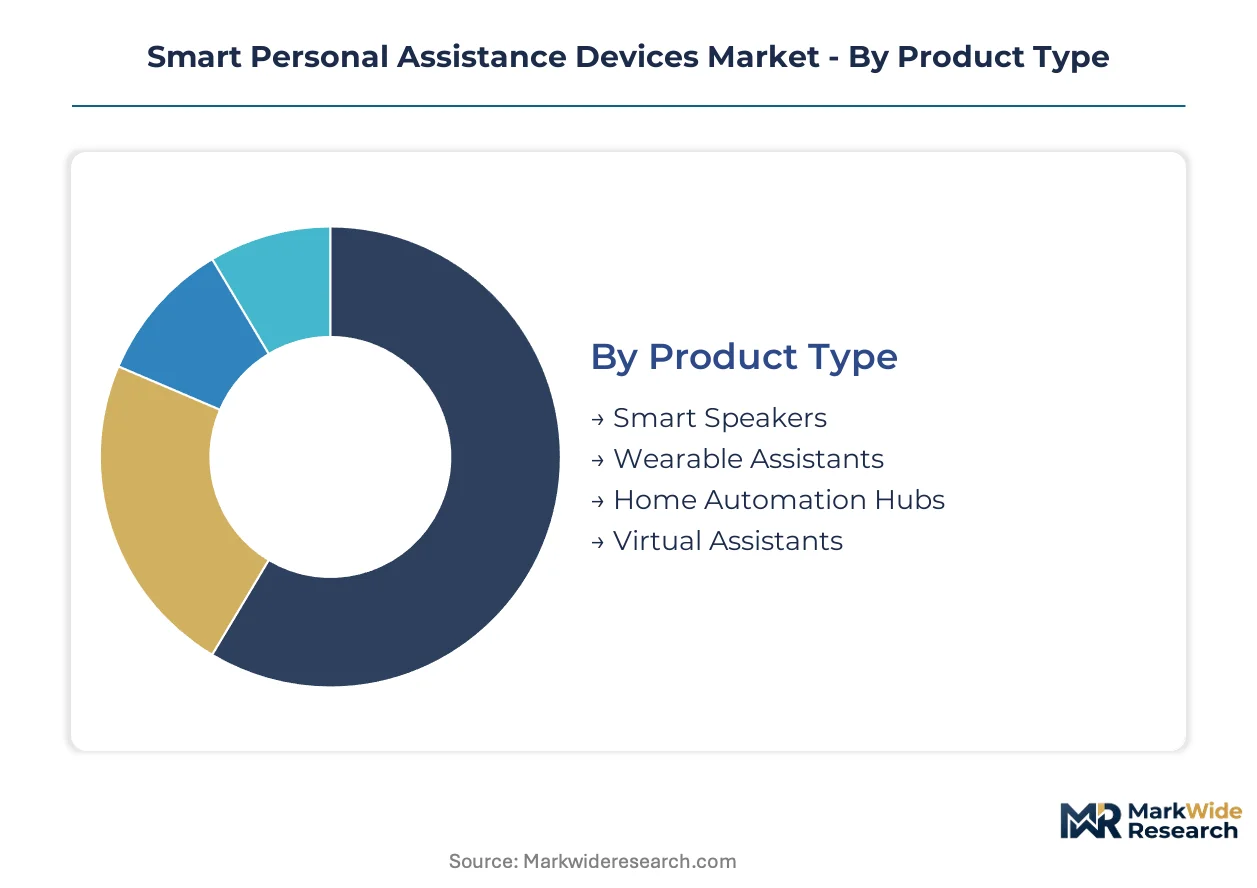
Segmentation in smart personal assistance devices reveals how hardware form factors, processing architectures, and procurement channels create distinct competitive arenas with divergent margin profiles and compliance requirements.
Product Type:
Supply concentration in microphone array manufacturing and edge AI chip fabrication favors scaled producers with direct foundry relationships.
- Smart Speakers:Cylindrical or spherical enclosures housing far-field microphone arrays, DSPs, and Wi-Fi/Bluetooth connectivity modules. Amazon Echo and Google Nest deployments dominate hospitality lobbies and hospital patient rooms in the United States and Germany, driven by facility management standardization on single-vendor building platforms.
- Wearable Assistants:Wrist-worn or clip-on devices integrating biometric sensors with voice interfaces for hands-free operation. Demand concentrates in chronic disease management applications across Switzerland and the Netherlands, where continuous glucose monitoring integration commands premium positioning.
- Home Automation Hubs:Centralized controllers bridging multiple IoT protocols for unified environmental control.
- Virtual Assistants:Software-only implementations deployed through existing screens and speakers without dedicated hardware.
Smart Speakers absorb the bulk of installed capacity; Wearable Assistants are expanding most quickly.
Technology:
Cost tier stratification separates baseline voice recognition from premium personalization engines requiring specialized machine learning infrastructure.
- Natural Language Processing:Cloud-based transformer architectures parsing semantic intent from conversational queries. Enterprise IT departments in Chicago and New York prioritize NLP accuracy for service desk automation, where misinterpretation rates directly affect operational expenditure.
- Voice Recognition:Acoustic pattern matching for speaker identification and command authentication. GDPR biometric storage mandates in France and Germany force redundant EU-localized infrastructure, raising deployment costs for cross-border service delivery.
- Artificial Intelligence:Inference engines enabling contextual task completion beyond scripted responses.
- Machine Learning:Personalization layers adapting to individual user patterns through behavioral data accumulation.
Voice Recognition underpins baseline competitive requirements; Machine Learning commands the steepest expansion trajectory as differentiation shifts to predictive assistance.
End User:
Application maturity varies sharply across settings, with regulated environments imposing certification barriers that filter vendor participation.
- Households:Residential deployments for media control, shopping, and environmental management. Smart home spending acceleration in the United States and China sustains volume demand despite replacement cycle elongation.
- Enterprises:Workplace implementations integrating with productivity suites and facility systems. Healthcare providers in India and Germany are expanding fastest, driven by voice-first diagnostic interfaces for low-literate patient populations and EU AI Act compliance pathways for clinical procurement.
- Educational Institutions:Classroom and administrative deployments requiring COPPA and GDPR student data protections.
- Healthcare Providers:Clinical settings subject to FDA software-as-medical-device and HIPAA constraints.
Households retain the largest installed base; Healthcare Providers are gaining share fastest as reimbursement incentives align with remote monitoring expansion.
Distribution Channel:
Customer type fragmentation between consumer self-service and enterprise procurement teams reshapes channel economics and sales cycle duration.
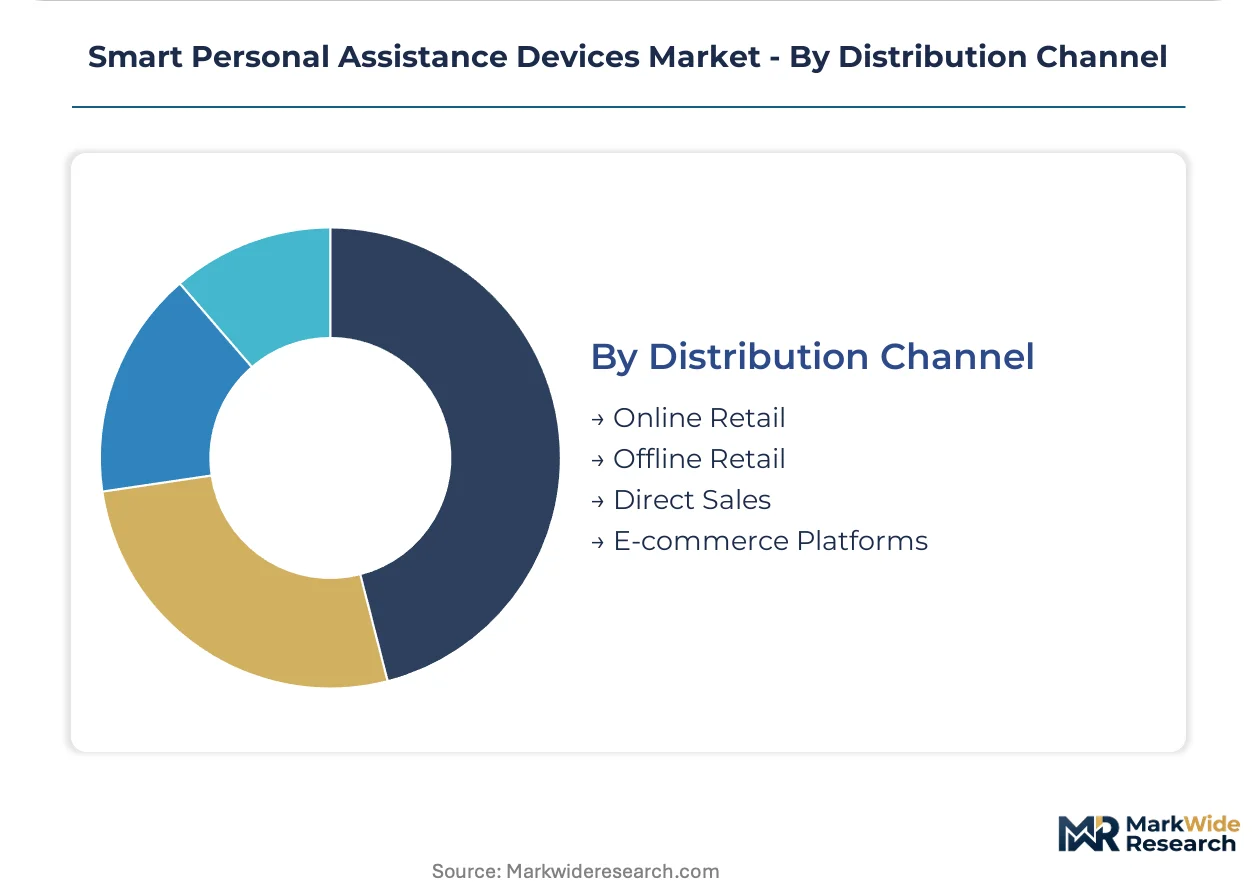
- Online Retail:Direct-to-consumer platforms with algorithmic recommendation engines. Amazon and specialized electronics marketplaces dominate household purchases in the United States and Germany, where comparison shopping behavior concentrates price sensitivity.
- Offline Retail:Big-box electronics and telecommunications storefronts with physical demonstration capabilities. China's MIIT certification requirements favor domestic manufacturers with established retail relationships in tier-one cities.
- Direct Sales:Enterprise account teams managing complex procurement workflows for unified building platform deployments.
- E-commerce Platforms:Third-party marketplaces aggregating multiple vendor offerings with standardized fulfillment.
Online Retail captures the majority of household volume; Direct Sales are climbing the fastest as facility management procurement consolidates around single-vendor ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, China, and Germany as smart home and enterprise IT spending accelerates. Facility management buyers in these markets drive consolidation around unified voice platforms for hospitality and healthcare deployments.
United States
Healthcare providers and hospitality chains anchor procurement volume for voice-enabled workflow automation. The FDA's evolving guidance on software as a medical device shapes clinical voice assistant certification pathways. Hospital systems in Chicago and New York standardize on single-vendor building platforms to reduce tenant onboarding friction.
China
MIIT certification requirements for intelligent speech products filter market access for domestic and foreign manufacturers. State-owned enterprises and smart city deployments in tier-one cities favor GB standards-compliant suppliers. Beijing and Shanghai clusters concentrate government contract awards for integrated voice platforms.
Germany
EU AI Act compliance pathways for high-risk AI systems unlock preferential procurement in healthcare and educational channels. GDPR biometric storage mandates force redundant EU-localized infrastructure deployment. Industrial automation hubs in Bavaria and Baden-Württemberg adopt edge AI architectures for manufacturing floor voice control.
India
Low-literate patient populations in rural districts create demand for voice-first diagnostic interfaces bypassing smartphone dependency. The country's national electronics regulator enforces localization requirements for biometric data processing. Healthcare IT clusters in Karnataka and Telangana develop multilingual NLP engines for regional language support.
Switzerland
Medical device suppliers leverage existing MDR documentation systems to accelerate material requalification under REACH substance restrictions. Swissmedic oversight shapes clinical voice assistant deployment in chronic disease management. Zurich and Basel clusters concentrate wearable-biometric convergence development for continuous glucose monitoring integration.
Smart Personal Assistance Devices Market Competitive Landscape
United States producers anchor one tier; Chinese specialists hold government contract channels through MIIT certification compliance. The market structures around three to five dominant platform ecosystems with deep enterprise integration capabilities. Strategic archetypes include cloud-first infrastructure deployers, on-device privacy architects, and vertical healthcare specialists. Competitive moves concentrate on strategic partnerships with facility management integrators and portfolio diversification into wearable form factors.
Within the cloud-first infrastructure tier, Amazon and Google represent scaled platform deployers with hospitality and healthcare penetration. Apple occupies a position exemplifying on-device processing architecture that limits data transmission to cloud servers. Baidu anchors the Chinese domestic market through MIIT-certified intelligent speech products for smart city and government deployments.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Microsoft |
| Samsung |
| IBM |
| Sonos |
| Baidu |
| Nuance Communications |
| Others |
Value Network & Pricing Analysis
Captive edge AI chip fabrication anchors supply positioning and pricing power for scaled producers with direct Taiwan-based foundry relationships, while outsourced microphone array assembly compresses margins for second-tier hardware vendors competing on device cost.
Pricing Analysis
Volume concentration in smart speakers absorbs the bulk of installed base at compressed margins, while wearable assistants with biometric sensor fusion command premium positioning. Three-tier pricing structure across premium on-device processing, standard cloud-dependent, and economy white-label tiers separates vendors by GDPR compliance certification and EU AI Act conformity assessment. Cost compression in the economy tier intensifies because Chinese domestic manufacturers leverage MIIT certification pathways to capture government contract volume. Enterprise facility management buyers in the United States and Germany exhibit the lowest price sensitivity due to bundled procurement with HVAC and security system upgrades, whereas household consumers in online retail channels concentrate price sensitivity through algorithmic comparison shopping.
Supply Chain Analysis
Reverse-logistics flows for voice-enabled hardware remain underdeveloped, with refurbishment channels concentrated in Shenzhen and limited remanufacturing of microphone array assemblies due to REACH substance restrictions on adhesives and substrates. Geographic supply concentration centers on Taiwan for advanced DSP foundry capacity, China for final device assembly, and Germany for automotive-grade cabin control modules. Raw material dependencies span rare-earth magnets for speaker drivers, gallium nitride substrates for edge AI chips, and specialized acoustic fabrics for far-field microphone enclosures. Single-source vulnerability in Taiwan-based foundry capacity creates exposure to geopolitical disruption. Distribution runs through system integrators displacing traditional AV resellers in Class A commercial real estate, with Amazon and Google direct sales channels capturing enterprise procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
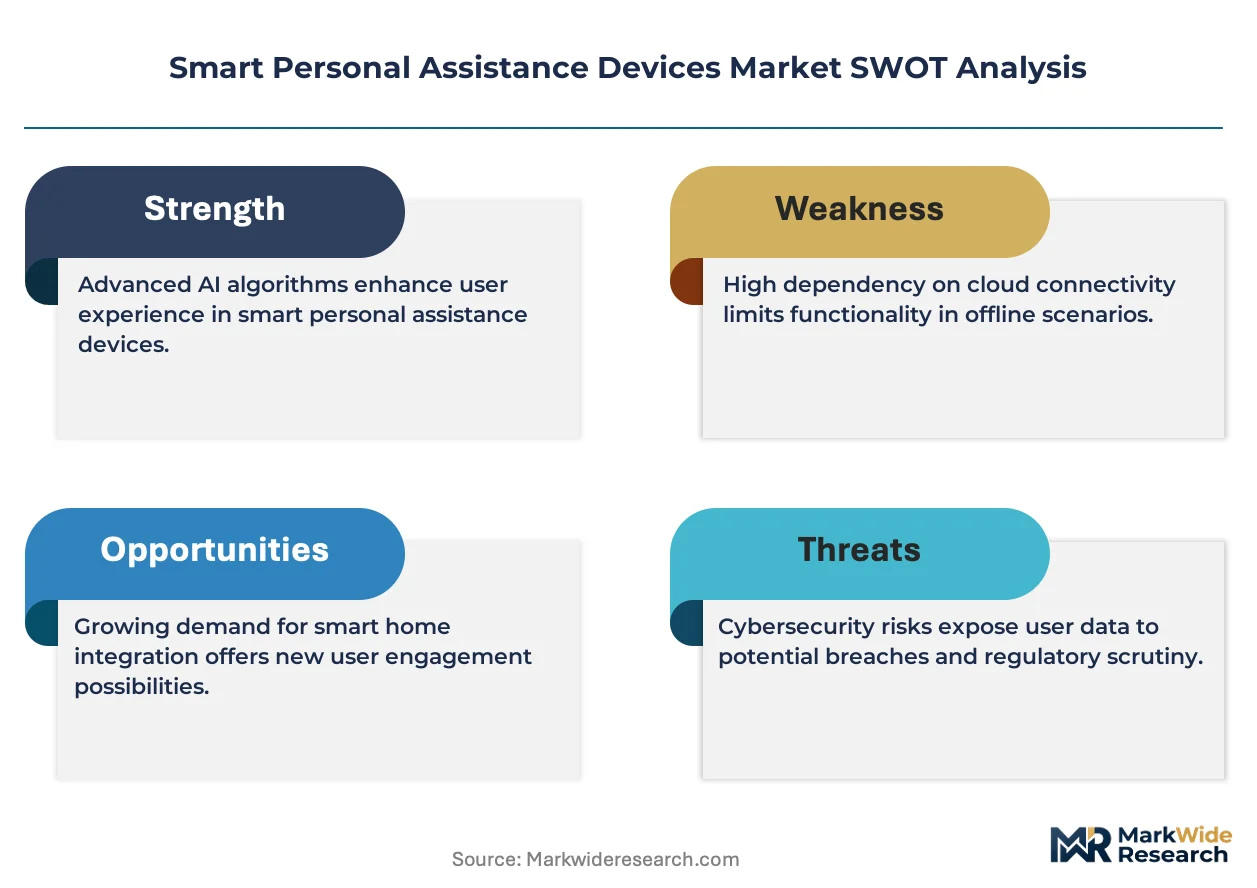
This market reads as a cost-of-compliance story where EU AI Act high-risk AI system certification creates a barrier-to-entry moat for manufacturers with documented conformity assessment pathways, filtering participation in healthcare and educational procurement channels.
For Market Incumbents: Acquire multilingual NLP engineering talent concentrated in Bangalore and Tallinn to defend against emerging entrants exploiting low-resource language gaps. Anchor defensive positioning through backward integration into edge AI chip design, reducing dependency on Taiwan-based foundry capacity. Accelerate FDA software-as-medical-device premarket submission timelines to compress competitive windows for clinical voice triage applications.
For New Entrants and Emerging Players: US IRA healthcare IT incentives open a window for voice-first remote patient monitoring solutions targeting Medicare reimbursement adjustments. Rural healthcare districts in India present the most penetrable geography, where low-literate patient populations demand diagnostic interfaces bypassing smartphone dependency. Pursue partnership-based go-to-market with Swiss and Dutch medical device suppliers leveraging existing MDR documentation systems for accelerated material requalification.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertical healthcare specialists with FDA-cleared clinical voice applications and wearable-biometric convergence capabilities. Long-term viability over the projection horizon hinges on predictive personalization engine differentiation rather than baseline voice recognition commoditization. Monitor FDA software-as-medical-device premarket review cycle compression as an inflection indicator for competitive window dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | Unlocks preferential procurement in German and French healthcare channels requiring high-risk AI certification. |
| Edge AI Chip Architecture Development | Reduces latency for manufacturing floor voice control in Bavaria where cloud connectivity remains intermittent. |
| Multilingual NLP Engine Expansion | Captures rural India healthcare demand through regional language support bypassing smartphone dependency. |
| Continuous Glucose Monitoring Integration | Opens chronic disease management premium positioning in Swiss and Dutch wearable-biometric convergence markets. |
| Facility Management System Integration | Consolidates procurement with HVAC and security upgrades in Chicago and New York Class A commercial real estate. |
Research Methodology
SEC filings from Amazon, Google, Apple, and Microsoft, EU AI Act implementation guidance documents, and FDA software-as-medical-device guidance updates formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with enterprise IT procurement officers, facility management directors, biomedical engineers at hospital systems, and regulatory affairs specialists at medical device manufacturers combined with secondary validation through customs records and hyperscaler capex disclosures. Bottom-up device shipment estimates and top-down enterprise IT spending analysis enabled triangulation across independent analytical paths.
Historical trendline analysis of smart speaker and wearable assistant adoption patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include hardware form factor, processing architecture, end-user setting, and procurement channel. CAGRs derived from fitted growth curves adjusted for regulatory compliance timeline impacts and reimbursement incentive phase-ins. Industry-specific forecast inputs encompassed EU AI Act implementation schedules and US IRA healthcare IT incentive disbursement patterns.
The model assumes a particular technology adoption path; alternative pathways for on-device versus cloud-based natural language processing would alter the outlook for vendor competitive positioning and infrastructure investment requirements. Forecasts reflect documented assumptions regarding regulatory compliance timelines and foundry capacity expansion. Practitioners should monitor FDA premarket review cycle durations, Taiwan semiconductor foundry utilization rates, and EU AI Act delegated act publications for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Gantry (Cartesian) Robot Market